
 Workplace Safety Market | 2026-2036
Workplace Safety Market Size, Share, and Industry Trends Forecast 2026-2036
Workplace Safety Market Analysis
Buyer concentration among large construction and energy contractors is realigning procurement leverage toward integrated safety platforms. Honeywell International Inc. leverages its sensor hardware portfolio to anchor long-term service contracts with infrastructure operators. 3M Company sustains dominance in disposable respiratory protection through captive manufacturing scale and brand recognition among industrial distributors. MSA Safety Incorporated specializes in fixed gas detection systems, competing on calibration reliability and channel density across North American utility networks.
Workplace safety encompasses engineered systems, administrative protocols, and personal protective technologies designed to eliminate or mitigate occupational hazards including chemical exposure, mechanical impact, and atmospheric contamination. Functional parameters span detection thresholds measured in parts per million for toxic gases, fall arrest force limits, and arc flash thermal ratings measured in calories per square centimeter. Personal Protective Equipment commands the largest revenue pool due to replacement cycles and regulatory minimums, while Safety Management Software captures expanding margins as enterprises digitize incident reporting and compliance documentation. Hazard Detection Systems are gaining share fastest where IoT Solutions enable real-time environmental monitoring tied to automated shutdown protocols.
OSHA enforces permissible exposure limits and recordkeeping standards that directly shape product certification requirements for US manufacturers. The EU Machinery Directive and CE marking obligations create parallel compliance pathways for equipment sold across European member states. Japan's METI and Industrial Safety and Health Act mandate specific inspection intervals for pressure vessels and crane systems, sustaining aftermarket service demand. Stakeholders must monitor divergence between regional IoT data governance standards and safety device connectivity mandates as connected platforms proliferate.
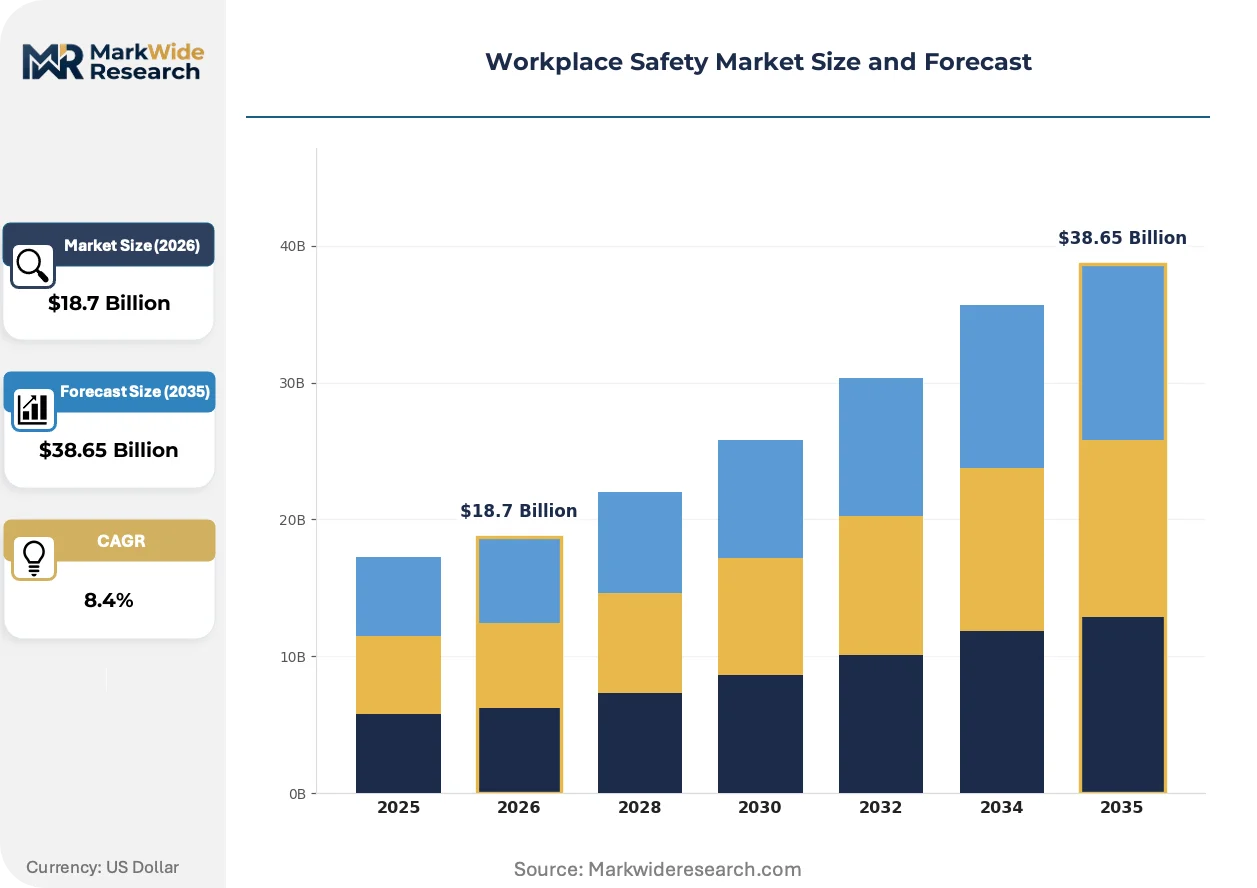
Market Dynamics
Connected protective systems are compressing replacement cycles and forcing legacy equipment suppliers to reconfigure service architectures around real-time data streams rather than periodic hardware sales.
Growth Catalysts
- OSHA Recordkeeping Modernization:Revised electronic submission mandates for injury and illness data are compelling mid-sized manufacturers to adopt integrated safety management platforms that automate compliance documentation.
- Industrial IoT sensor networks:Fall detection wearables and connected gas monitors are generating recurring software revenue streams that offset declining hardware margins across utility and petrochemical end-uses.
- German industrial automation density:Automotive and chemical producers in Baden-Württemberg and North Rhine-Westphalia are procuring synchronized PPE-to-PLC systems that trigger automated equipment lockouts.
Market Restraints
- Semiconductor component volatility:MEMS sensors and wireless communication modules face allocation constraints that extend lead times for connected respiratory and detection equipment.
- Calibration infrastructure concentration:Certified service networks for fixed gas detection remain concentrated along the US Gulf Coast and Rhine-Ruhr corridor, limiting deployment flexibility.
- CE marking complexity:Divergent notified body interpretations of the EU Machinery Directive's Annex I essential requirements create certification friction for multi-country equipment launches.
Strategic Opportunities
- Japanese construction robotics integration:METI's Society 5.0 roadmap is creating demand for collaborative safety systems that protect human workers alongside autonomous heavy equipment.
- India's manufacturing scale-up:The PLI scheme for specialty chemicals and textiles is attracting safety equipment investment as foreign operators impose corporate HSE standards on local contract labor.
- AI-enabled predictive hazard modeling:Convergence of computer vision and environmental sensor fusion is opening white space in proactive intervention systems that anticipate incidents before threshold breaches.
Industry Challenges
- Functional safety engineer scarcity:IEC 61508 and ISO 13849 certification requirements exceed the available talent pool for programmable safety system design and validation.
- Legacy SCADA integration friction:Brownfield facilities running proprietary protocols require costly gateway development to connect modern safety devices to centralized monitoring architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Workplace Safety Market |
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $38.65 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Personal Protective Equipment, Safety Training Programs, Hazard Detection Systems, Safety Management Software End User: Construction, Manufacturing, Oil & Gas, Chemical Processing Application: Fire Safety, Fall Protection, Electrical Safety, Ergonomics Technology: Wearable Safety Devices, IoT Solutions, AI Safety Analytics, Virtual Reality Training |
| Companies Covered | Hexagon AB, Microsoft Corporation, Honeywell International Inc., DuPont, Appian Corporation, 3M Company, MSA Safety Incorporated, Drägerwerk AG & Co. KGaA, IBM Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Workplace Safety Market Emerging Trajectories
Real-time environmental monitoring is displacing scheduled inspection regimes, compressing the interval between hazard detection and corrective action from days to milliseconds in critical process industries.
Wearable biometric sensors are converging with edge computing architectures to enable localized decision-making without cloud dependency. Oil and gas operators in Alberta and Texas are deploying these systems in explosive atmospheres where wireless infrastructure remains restricted. This convergence is compressing the traditional separation between personal protection and process safety management into unified risk control platforms.
Japan's METI has mandated specific inspection intervals for pressure vessels and crane systems under the Industrial Safety and Health Act amendments. These requirements are sustaining aftermarket service demand for original equipment manufacturers with certified technician networks. Fixed equipment segments are responding by bundling predictive maintenance software with mandatory inspection contracts.
Buyer concentration among mega-contractors is consolidating procurement authority and disintermediating traditional industrial distributors. Large construction and energy firms are establishing direct supplier relationships that bypass channel intermediaries for high-volume PPE categories. This pattern is most visible in North American infrastructure projects where joint venture structures aggregate purchasing across multiple operating companies.
Workplace Safety Market Segmentation
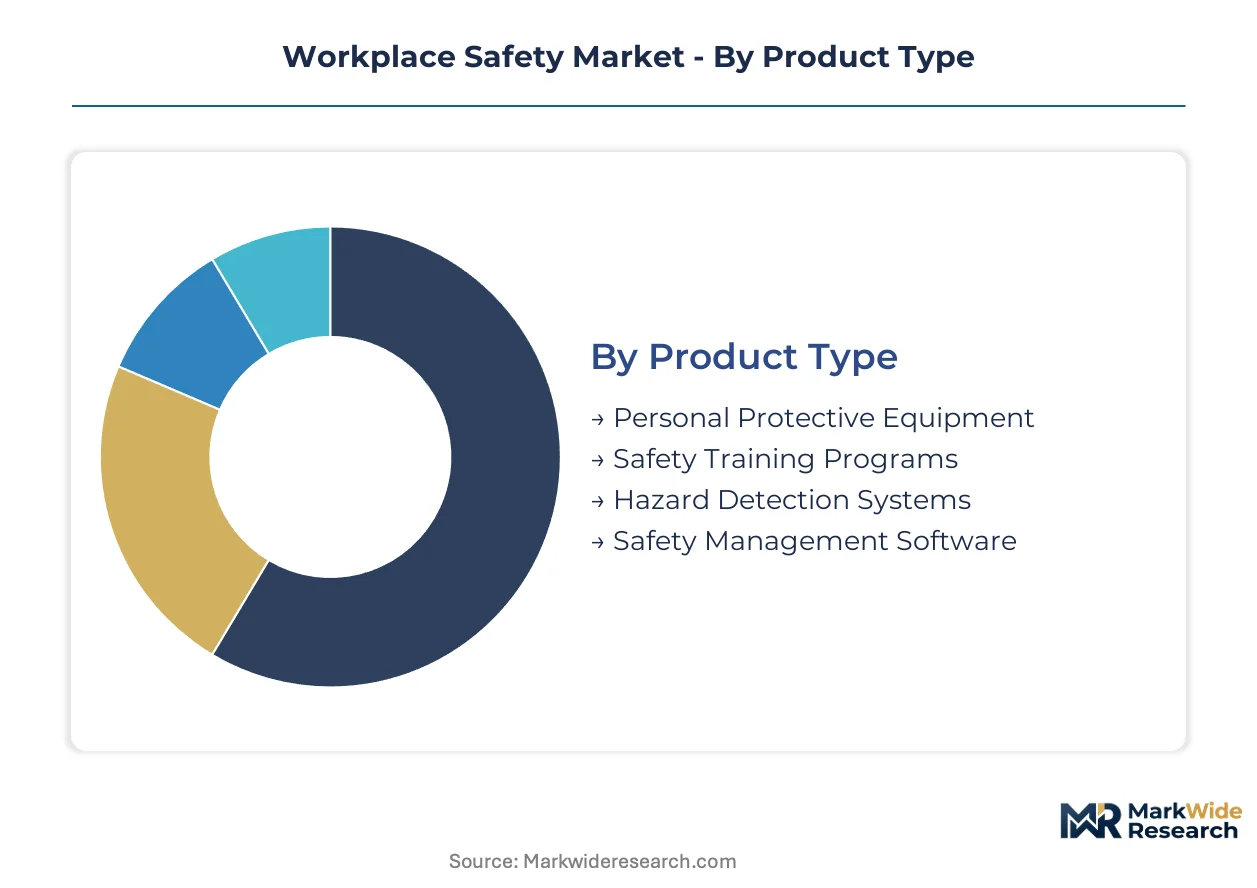
Workplace safety procurement splits between standalone consumables and integrated systems that embed protection into operational technology. Understanding this layering clarifies where hardware margins compress against software recurring revenue.
Product Type:
Personal Protective Equipment operates as standalone procurement with replacement-driven demand, while software and detection systems embed deeper into facility infrastructure and enterprise IT.
- Personal Protective Equipment:Disposable respirators, hard hats, and protective garments dominate procurement volumes through mandated minimums and wear-cycle replacement. Construction contractors in Germany and the United States consolidate purchasing through direct supplier relationships that bypass traditional distribution. PPE leads volumes today; Safety Management Software is gaining share fastest.
- Safety Training Programs:Classroom and field instruction modules cover hazard recognition, lockout/tagout procedures, and emergency response protocols. Energy sector operators in the US Gulf Coast sustain demand for specialized certification programs tied to OSHA compliance audits.
- Hazard Detection Systems:Fixed gas monitors, flame detectors, and particulate sensors integrate with building management and process control systems. Petrochemical facilities in Texas and Louisiana deploy these for real-time atmospheric monitoring with automated shutdown triggers.
- Safety Management Software:Cloud platforms digitize incident reporting, compliance documentation, and corrective action tracking. Mid-sized manufacturers adopt these systems to satisfy OSHA electronic recordkeeping mandates without expanding administrative headcount.
PPE absorbs the largest procurement budgets through sheer unit volume; software captures expanding margins as digitization penetrates compliance workflows.
End User:
End-use concentration varies by hazard intensity and regulatory scrutiny, with process industries driving premium system adoption.
- Construction:Fall protection, struck-by hazards, and respiratory exposure dominate safety spend. Mega-contractors across North America consolidate procurement authority through joint venture structures that aggregate volume across operating companies.
- Manufacturing:Robotics integration and repetitive motion injuries shape protective system design. Automotive producers in Baden-Württemberg deploy synchronized PPE-to-PLC systems that trigger equipment lockouts when worker proximity breaches thresholds.
- Oil & Gas:Explosive atmospheres and confined space entry mandate specialized detection and communication equipment. Alberta operators deploy wearable biometric sensors with edge computing to enable localized decision-making where wireless infrastructure remains restricted.
- Chemical Processing:Toxic exposure limits and pressure vessel integrity sustain demand for fixed detection and predictive maintenance contracts. Rhine-Ruhr corridor facilities bundle inspection services with sensor calibration to satisfy regulatory intervals.
Construction generates the highest unit volumes; chemical processing commands the steepest expansion trajectory through predictive system adoption.
Application:
Application segments align with specific regulatory mandates and injury cost profiles that justify differentiated technology investment.
- Fire Safety:Suppression systems, detection networks, and emergency egress infrastructure protect against thermal and smoke hazards. Commercial and industrial facilities in Japan integrate these with METI-mandated inspection protocols for pressure vessels and crane systems.
- Fall Protection:Harnesses, anchor points, and guardrail systems address leading causes of construction fatalities. Connected wearables with fall detection algorithms are compressing response intervals from minutes to seconds in North American infrastructure projects.
- Electrical Safety:Arc flash protection, lockout/tagout equipment, and insulated tools mitigate shock and thermal hazards. Utility networks prioritize calibration reliability for fixed detection systems across geographically dispersed substations.
- Ergonomics:Adjustable workstations, exoskeletons, and motion-tracking systems reduce musculoskeletal injury rates. Manufacturing scale-up in India's PLI-supported sectors is attracting investment as foreign operators impose corporate HSE standards on local contract labor.
Fall protection leads procurement spend today; ergonomics is climbing the fastest as automation extends worker career longevity.
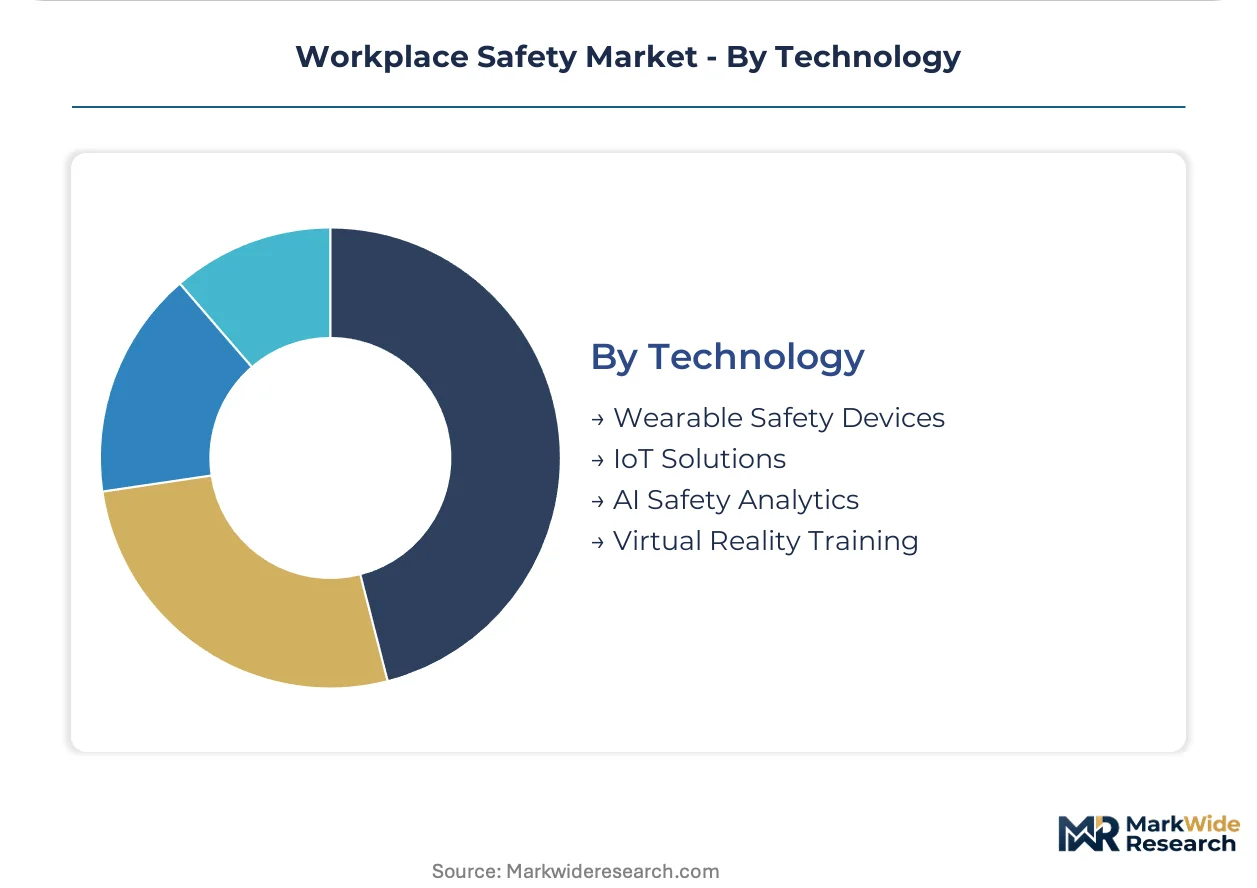
Technology:
Technology segments stratify by connectivity architecture, from passive protection to predictive intervention systems.
- Wearable Safety Devices:Biometric monitors, location tags, and environmental sensors attach to worker garments or equipment. Oil and gas operators deploy these in explosive atmospheres where wireless infrastructure faces regulatory restrictions.
- IoT Solutions:Sensor networks transmit environmental and equipment status data to centralized monitoring platforms. German chemical producers synchronize these with programmable logic controllers for automated hazard response.
- AI Safety Analytics:Computer vision and sensor fusion enable predictive hazard modeling before threshold breaches. This convergence opens white space in proactive intervention systems that anticipate incidents rather than reacting to alarms.
- Virtual Reality Training:Immersive simulations replicate hazardous scenarios without physical exposure risk. Construction and energy firms deploy these for high-consequence procedure rehearsal where live training carries unacceptable injury potential.
Wearable devices dominate installed base; AI Safety Analytics shows the steepest adoption curve as sensor fusion matures.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German chemical producers deploy synchronized PPE-to-PLC systems at automation densities the United States has yet to match, while Japanese regulators enforce inspection intervals that sustain aftermarket service demand for original equipment manufacturers.
United States
OSHA's electronic recordkeeping mandates compel mid-sized manufacturers to adopt integrated safety management platforms. The agency's revised injury and illness data submission rules automate compliance documentation across construction and energy sectors. Texas and Louisiana petrochemical facilities deploy fixed gas monitors with automated shutdown triggers for real-time atmospheric monitoring.
Germany
Automotive and chemical producers in Baden-Württemberg and North Rhine-Westphalia procure synchronized protective systems that trigger equipment lockouts. The EU Machinery Directive's CE marking obligations shape certification requirements for equipment sold across member states. Rhine-Ruhr corridor facilities bundle predictive maintenance software with mandatory sensor calibration contracts.
Japan
METI's Society 5.0 roadmap generates demand for collaborative safety systems protecting workers alongside autonomous heavy equipment. The Industrial Safety and Health Act mandates specific inspection intervals for pressure vessels and crane systems. Original equipment manufacturers with certified technician networks capture sustained aftermarket service revenue from these regulatory requirements.
India
The PLI scheme for specialty chemicals and textiles attracts safety equipment investment as foreign operators impose corporate HSE standards on local contract labor. The country's national industrial regulator enforces evolving workplace safety protocols across manufacturing scale-up zones. Maharashtra and Gujarat industrial corridors see concentrated procurement of respiratory protection and hazard detection systems.
Canada
Alberta oil and gas operators deploy wearable biometric sensors with edge computing architectures in explosive atmospheres where wireless infrastructure faces restrictions. Health Canada and provincial regulators align with OSHA-equivalent exposure limits for toxic gases and confined space entry. Western Canadian energy infrastructure sustains demand for specialized detection and communication equipment.
Workplace Safety Market Vendor Landscape
United States producers anchor one tier; German specialists hold certification-intensive positions in fixed detection and respiratory systems. The vendor base stratifies across integrated industrial conglomerates, pure-play safety equipment manufacturers, and enterprise software platforms entering through compliance digitization. Three archetypes dominate: sensor-hardware-anchored service contractors, disposable protection scale manufacturers, and cloud-based safety management platforms. Competitive moves concentrate on M&A for IoT sensor capabilities and strategic partnerships bridging operational technology with enterprise IT systems.
Within the integrated industrial tier, Honeywell International Inc. and 3M Company occupy positions that exemplify hardware-to-service transition strategies. MSA Safety Incorporated represents the specialized detection archetype competing on calibration reliability and channel density. These three anchors demonstrate how legacy equipment suppliers reconfigure architectures around real-time data streams rather than periodic hardware sales.
| Leading Market Players |
|---|
| Hexagon AB |
| Microsoft Corporation |
| Honeywell International Inc. |
| DuPont |
| Appian Corporation |
| 3M Company |
| MSA Safety Incorporated |
| Drägerwerk AG & Co. KGaA |
| IBM Corporation |
| Others |
Supply Flow & Price Mechanics
Connected sensor manufacturing in Taiwan and South Korea is compressing component costs while concentrating procurement leverage among integrated platform vendors. This dual shift simultaneously lowers hardware price floors and elevates software subscription premiums as buyers prioritize real-time data integration over standalone equipment.
Pricing Analysis
Capacity additions in Taiwan and South Korea are reshaping price floors for MEMS sensors and wireless communication modules. Three-tier pricing structure across premium, standard, and economy levels separates IEC 61508-certified programmable safety systems from basic PPE and disposable respiratory protection. Price differentiation hinges on calibration reliability and after-sales service bundling, with mid-sized manufacturers exhibiting highest price sensitivity due to OSHA compliance cost absorption. Margins are tightening in hardware tiers as semiconductor allocation constraints extend delivery timelines.
Supply Chain Analysis
Freight cost volatility from Asia-Pacific manufacturing hubs to North American and European distribution centers is elevating landed costs for connected protective equipment. Component sourcing draws from Taiwan, South Korea, and China for MEMS sensors, while final assembly concentrates in Germany, the United States, and Mexico. Single-source vulnerability persists for specialized gas detection calibration gases certified to NIST-traceable standards. Distribution runs through direct supplier relationships with mega-contractors, bypassing traditional industrial distributors for high-volume PPE categories.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Workplace safety functions as a stable compounder anchored by regulatory mandates that perpetually refresh replacement demand and compliance-driven technology upgrades.
For Market Incumbents: Cement service contract renewals through predictive maintenance software bundling with mandatory inspection intervals. Deepen backward integration into sensor calibration infrastructure across the US Gulf Coast and Rhine-Ruhr corridor to defend against emerging cloud-based safety management platforms. Channel control over certified technician networks represents the critical defensive lever against software entrants disintermediating hardware relationships. For New Entrants and Emerging Players: Enter via AI-enabled predictive hazard modeling white space where computer vision and sensor fusion converge. India's manufacturing scale-up under the PLI scheme offers the most penetrable geography as foreign operators impose corporate HSE standards on local contract labor. A direct-to-mega-contractor sales model bypasses entrenched distribution relationships and captures volume aggregation through joint venture procurement structures. For Investors and Strategic Acquirers: Valuations sit cheapest among pure-play detection equipment manufacturers with stranded calibration service assets. The five-to-ten-year viability window favors targets with captive technician certification networks aligned to METI-mandated inspection intervals. Monitor divergence between regional IoT data governance standards and safety device connectivity mandates as the signal for platform consolidation inflection.| Strategic Initiative | Industry Significance |
|---|---|
| IoT Sensor Capability Acquisition | Industrial conglomerates gain real-time data streams that anchor long-term service contracts with infrastructure operators. |
| Predictive Maintenance Software Launch | Fixed equipment vendors bundle digital platforms with mandatory inspection contracts to satisfy METI regulatory intervals. |
| Certified Technician Network Expansion | Calibration reliability investments defend market position in gas detection where channel density determines procurement decisions. |
| Direct Mega-Contractor Partnership | Bypassing traditional distributors captures volume aggregation through North American infrastructure joint venture structures. |
| AI Safety Analytics Development | Computer vision and sensor fusion convergence opens proactive intervention systems before threshold breaches occur. |
Methodological Framework
Bottom-up end-use modeling reconciled against top-down supply-side tracking forms the analytical core of this study. Primary interviews with safety equipment procurement managers, plant engineers at petrochemical facilities, certified calibration technicians, and industrial distributor category heads were validated against OSHA enforcement data, EU Machinery Directive implementation reports, customs trade records for PPE imports, and SEC filings from publicly traded safety equipment manufacturers.
Input-output matrices across product type, end-use industry, application segment, and technology deployment were constructed to derive expansion trajectories throughout the forecast period. CAGRs were calibrated using equipment replacement cycle analysis, regulatory mandate implementation timelines, and industrial automation adoption curves. Forecast inputs incorporated semiconductor allocation constraints, certified service network geographic coverage, and divergence patterns between regional IoT data governance standards.
Inputs from OSHA enforcement databases and EU notified body certification registries were available through the study window; gaps in real-time connected equipment deployment metrics introduce uncertainty bands around software revenue projections. Forecasts reflect assumptions regarding regulatory mandate adherence rates and industrial capital expenditure prioritization. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Workplace Safety
Safety Vest Market
Workplace Safety
Industrial Protective Footwear Market
Workplace Safety
Safety Glasses Market
Workplace Safety
Industrial Eye Protection Market
Workplace Safety
Industrial Safety Gloves Market
Workplace Safety
Industrial Head Protection Market
Workplace Safety
Construction Worker Safety Market
Workplace Safety
Machine Safety Market
Workplace Safety
Safety Helmets Market
Workplace Safety
Middle East Industrial Protective Footwear Market
Workplace Safety
Industrial Safety Mats Market
Workplace Safety
Canada Safety Services Market
Workplace Safety
Industrial and Workplace Safety Market
Workplace Safety
Industrial Hand Protection Gloves Market
Workplace Safety
Industrial Safety Market
Workplace Safety
Global Industrial Safety Footwear Market