
 Wireless Fire Detection Systems Market | 2026-2036
Wireless Fire Detection Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Wireless Fire Detection Systems Market Analysis
Installer-dealer networks is rewriting how wireless fire detection systems reach end users across commercial and educational buildings. Robert Bosch GmbH leverages its building technology division to sustain integrated fire safety portfolios across European markets. Hochiki Corporation anchors its position through specialized photoelectric sensing technology and deep channel relationships in Asia-Pacific. Johnson Controls International plc competes by extending its Smart Connected Fire portfolio through direct specification with large facility operators.
Wireless fire detection systems comprise battery-powered or mains-connected sensors that communicate alarm states via radio frequency protocols rather than hardwired signaling circuits, typically operating at 868 MHz or 2.4 GHz with mesh self-healing topology to ensure path redundancy. These systems serve primarily to protect occupants and assets by enabling faster deployment in heritage structures, temporary installations, and retrofit environments where cabling disruption is prohibitive. Smoke detectors lead product type demand due to code-mandated coverage density in residential and commercial occupancies, while multi-sensor detectors capture expanding share by reducing false alarm rates through combined optical-thermal algorithms. Hybrid installations represent the fastest-growing installation type as facilities blend wireless zones with existing wired panels to phase capital expenditure across budget cycles.
NFPA 72 in the United States and EN 54-25 in the European Union establish wireless-specific performance criteria that shape product certification requirements and market access conditions for manufacturers. The FCC in the United States and ETSI in Europe regulate spectrum allocation and transmission power limits that directly constrain radio module design and interoperability testing protocols. Stakeholders must monitor evolving cybersecurity mandates for connected safety devices as building management system integration deepens and network vulnerability exposure expands.
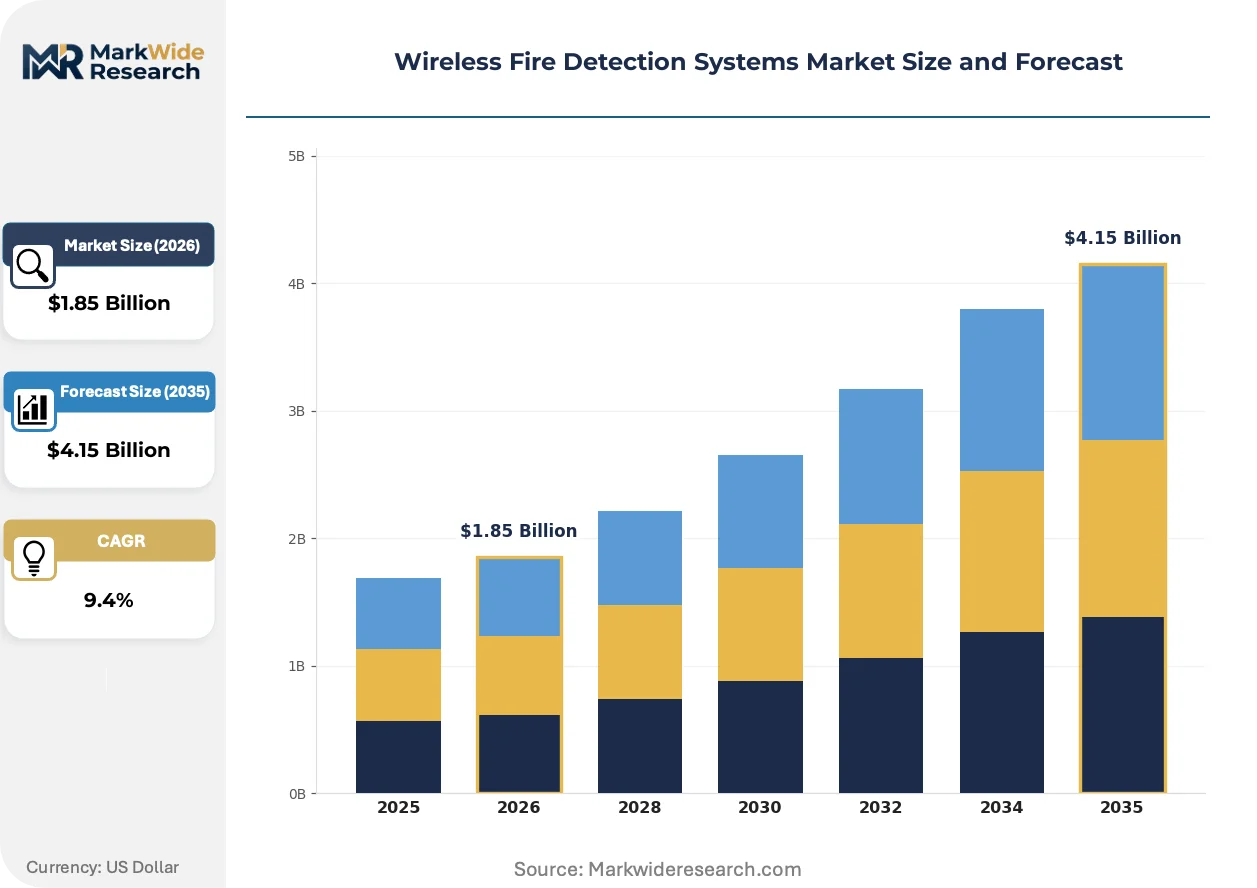
Market Dynamics
Retrofit mandates in aging commercial infrastructure are compressing replacement cycles for wireless fire detection systems, with building operators prioritizing mesh-network deployments that minimize tenant disruption during phased upgrades.
Growth Catalysts
- NFPA 72 updates:United States jurisdictions now require faster alarm verification protocols, pushing facilities toward wireless multi-sensor detectors that reduce false triggers through combined optical-thermal detection.
- Heritage building protection:Historic structures across Italy, France, and Spain face strict preservation codes that prohibit cabling penetration, creating captive demand for battery-powered radio frequency systems.
- Insurance underwriting alignment:Commercial property insurers in Germany and the United Kingdom offer premium discounts for certified wireless installations, accelerating replacement of legacy wired panels.
Market Restraints
- Radio module supply concentration:Production of 868 MHz and 2.4 GHz transceivers concentrates among semiconductor fabricators in Taiwan and South Korea, exposing lead times to geopolitical friction.
- EN 54-25 certification costs:European Union type-approval testing for wireless fire safety devices requires specialized laboratories in the Netherlands and Germany, creating six-to-nine month market entry delays.
- Hardwired system longevity:Existing copper-circuit installations in 1980s-era North American office towers deliver functional service life exceeding thirty years, deferring capital release for wireless conversion.
Strategic Opportunities
- India commercial construction:Smart city initiatives and BIS fire safety mandates in Mumbai, Bangalore, and Delhi create first-mover advantage for mesh-network providers establishing local assembly partnerships.
- Building management system convergence:Integration of fire detection data with HVAC and access control platforms via BACnet and Modbus protocols opens recurring software revenue streams.
- Temporary installation vertical:Construction site safety regulations in Australia and Canada mandate deployable fire protection for high-rise builds, favoring rapid-deployment wireless zones over permanent infrastructure.
Industry Challenges
- RF engineering talent scarcity:Mesh network optimization and spectrum coexistence testing require specialized expertise that outpaces vocational training output in Western European labor markets.
- Legacy panel interoperability:Hybrid installations demand protocol translation gateways that add commissioning complexity and extend project timelines for integrators managing mixed-voltage environments.
- Cybersecurity certification timelines:Connected device penetration testing against IEC 62443 standards creates additional validation layers that delay product launches by four to six months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wireless Fire Detection Systems Market |
| Market Size in 2026 | $1.85 Billion |
| Market Size in 2035 | $4.15 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Smoke Detectors, Heat Detectors, Beam Detectors, Multi-Sensor Detectors End User: Residential, Commercial, Industrial, Educational Technology: Wi-Fi, Zigbee, Bluetooth, Cellular Installation Type: Standalone, Hybrid, Integrated, Networked |
| Companies Covered | Robert Bosch GmbH, Hochiki Corporation, Honeywell International Inc., Electro Detectors Ltd., Apollo Fire Detectors Ltd., Siemens AG, Halma PLC, EMS Security Group, Johnson Controls International plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wireless Fire Detection Systems Market Emerging Trajectories
Wireless fire detection architecture is converging with broader building intelligence platforms, compressing the boundary between safety systems and operational technology infrastructure. Three developments are restructuring competitive positioning.
Multi-sensor detection technology is hybridizing optical smoke sensing with thermal differential algorithms and carbon monoxide detection in single housings. Hospital complexes and data center operators in the United States are specifying these units to reduce nuisance alarms that trigger costly evacuation protocols. The convergence is hybridizing procurement criteria, forcing manufacturers to compete on integrated analytics rather than standalone detection reliability.
ETSI spectrum harmonization across European Union member states is standardizing 868 MHz transmission power limits and duty cycle restrictions for fire safety applications. This regulatory consolidation is eliminating national variants that previously required region-specific radio module configurations. German and French certification bodies are consolidating test protocols, reducing duplicate engineering overhead for pan-European product launches.
Facility management outsourcing is consolidating purchasing authority for fire safety systems under integrated service providers rather than independent installing contractors. Commercial real estate investment trusts in the United Kingdom are centralizing specification decisions across multi-site portfolios, compressing vendor selection to three-to-five year framework agreements. This concentration is visible most acutely in London and Manchester, where property managers prioritize remote diagnostics capabilities over upfront hardware cost in tender evaluations.
Wireless Fire Detection Systems Market Segmentation
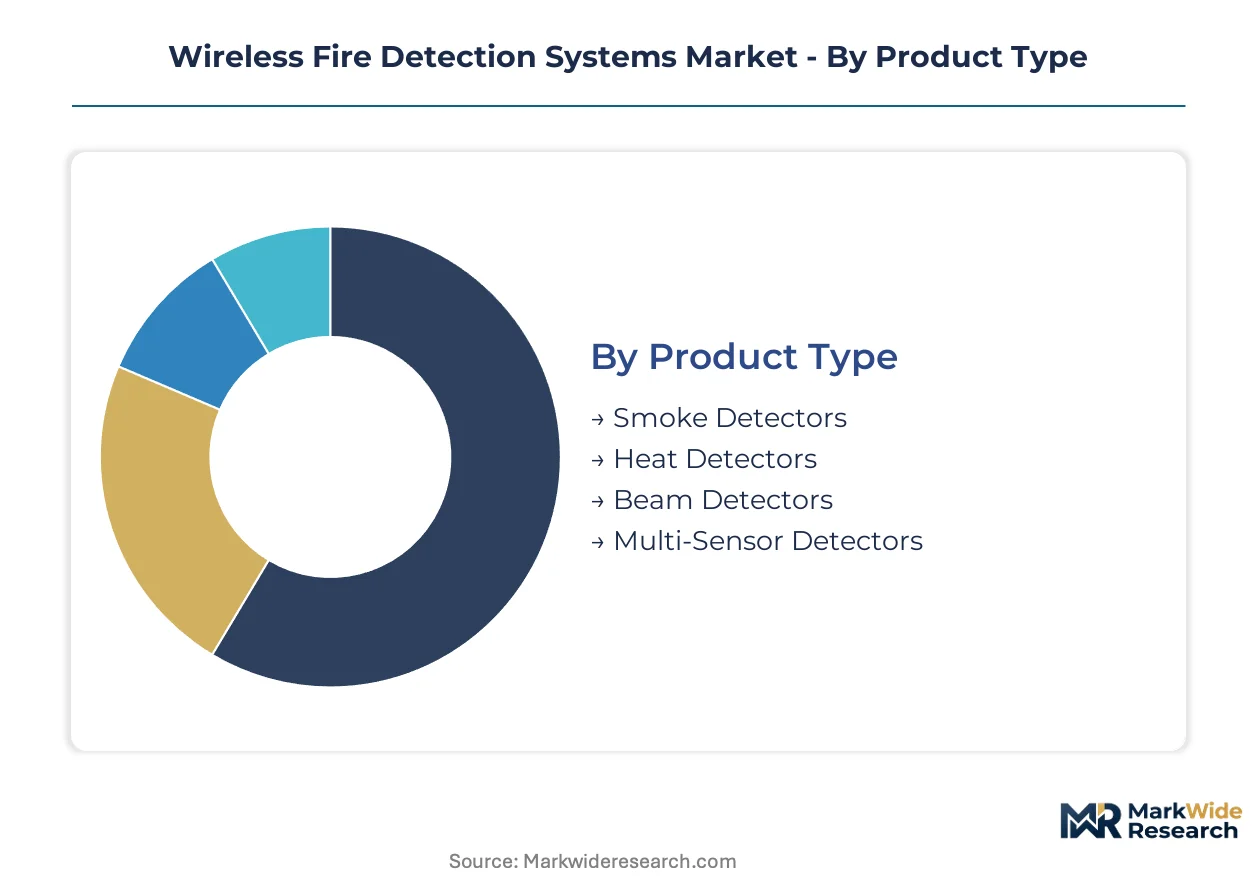
Wireless fire detection systems fragment across four structural dimensions that shape procurement patterns and margin profiles. Product type and installation architecture drive replacement cycle timing, while technology protocol and end-user vertical determine integration complexity and regulatory compliance burden.
Product Type:
Smoke detectors turn over fastest in residential retrofit cycles, while beam detectors in industrial warehouses exhibit the longest replacement intervals due to sealed optical chambers and minimal contamination exposure.
- Smoke Detectors:Photoelectric sensing chambers dominate commercial specifications due to reduced false alarms from cooking aerosols. Demand concentrates in United Kingdom multi-family housing where Approved Document B mandates ceiling coverage density and battery-powered wireless units simplify landlord compliance.
- Multi-Sensor Detectors:Combined optical-thermal-CO algorithms reduce nuisance triggers in healthcare and data center environments. Germany's DIN 14676 standards for sensitive occupancies accelerate specification of these units in Munich and Frankfurt hospital complexes where evacuation costs exceed hardware premiums.
- Heat Detectors:Fixed-temperature and rate-of-rise variants serve kitchen and garage applications where smoke detection proves impractical.
- Beam Detectors:Projected-beam optical systems protect atrium spaces and warehouses with high ceilings where point detection spacing would prove uneconomical.
Smoke detectors anchor the volume base while multi-sensor detectors gain share at the steepest rate.
End User:
Cost tiers separate premium-specified commercial installations from price-sensitive residential deployments, with industrial and educational occupying intermediate positions based on scale economies and maintenance outsourcing.
- Commercial:Office towers and retail portfolios in United States metropolitan corridors specify mesh-network systems with BACnet integration. Insurance underwriters in Chicago and Los Angeles mandate NFPA 72-compliant wireless retrofits for pre-1990s high-rises seeking premium discounts.
- Educational:Campus-wide deployments across United Kingdom universities prioritize phased wireless zones that minimize disruption during term time. Estates directors at Oxford and Cambridge colleges favor hybrid architectures that preserve historic fabric while meeting fire risk assessment obligations.
- Residential:Single-family and multi-family housing drives volume through landlord certification requirements and new construction code adoption.
- Industrial:Manufacturing facilities and logistics warehouses demand explosion-proof housings and extended temperature range operation.
Commercial installations command the highest unit economics while educational procurement is expanding most quickly through consolidated framework agreements.
Technology:
Protocol selection constrains interoperability with existing building management infrastructure and determines cybersecurity exposure surface for connected safety networks.
- Zigbee:Mesh self-healing topology at 2.4 GHz dominates European commercial specifications due to ETSI harmonization and deterministic latency for alarm propagation. German system integrators specify Zigbee 3.0 for Munich airport expansions and Frankfurt financial district retrofits requiring sub-second device-to-panel communication.
- Wi-Fi:IP-native connectivity simplifies integration with enterprise networks and cloud-based monitoring platforms. United States healthcare operators in Texas Medical Center and Mayo Clinic campuses leverage existing WLAN infrastructure to reduce gateway hardware costs.
- Bluetooth:Low-energy variants serve residential and small commercial applications with smartphone-based commissioning and maintenance alerts.
- Cellular:LTE-M and NB-IoT modules enable standalone protection for remote construction sites and temporary installations without local network infrastructure.
Zigbee protocols anchor the volume base while Wi-Fi connectivity is climbing the fastest through building management system convergence.
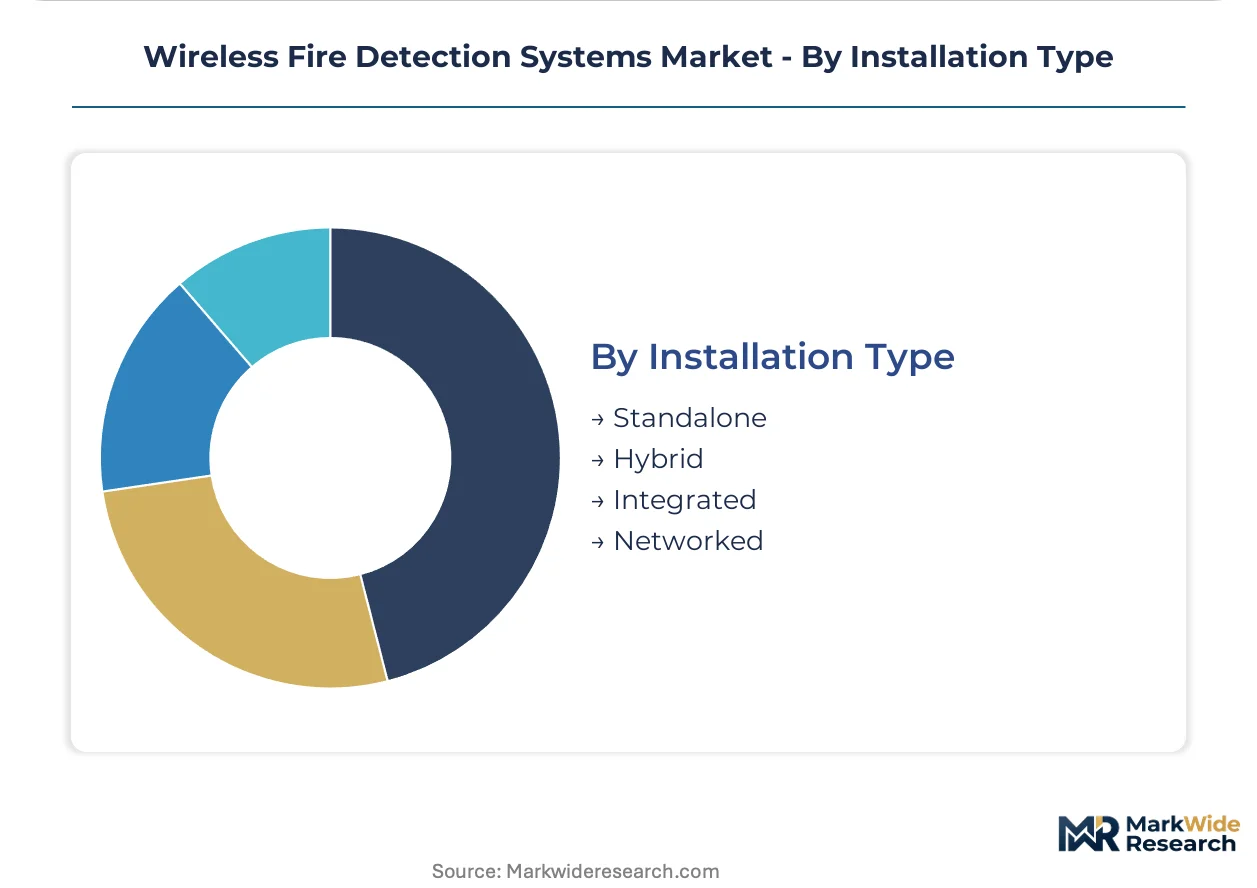
Installation Type:
Maturity gradients separate established standalone products from emerging integrated architectures that demand specialized commissioning expertise and extended project timelines.
- Hybrid:Wireless zones married to legacy wired panels dominate retrofit economics in 1980s-era North American and European commercial stock. United Kingdom facilities managers in Manchester and Birmingham office portfolios phase capital expenditure across budget cycles while preserving existing panel investments.
- Integrated:Single-platform fire, security, and building automation convergence attracts United States healthcare and education verticals seeking unified dashboards. Texas school districts and California hospital networks specify these systems to reduce vendor fragmentation and streamline maintenance contracts.
- Standalone:Self-contained wireless systems serve residential and small commercial applications with minimal infrastructure requirements.
- Networked:Campus-wide mesh deployments with centralized monitoring serve large distributed facilities and multi-site portfolios.
Hybrid installations anchor the volume base while integrated systems are expanding most quickly through facilities management outsourcing consolidation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The North Sea-Baltic rail freight corridor positions Germany as the distribution hub for wireless fire safety hardware across Central Europe. Port throughput at Rotterdam and Hamburg channels mesh-network components into retrofit pipelines serving aging commercial stock.
United States
Chicago Loop office towers and Los Angeles high-rises drive NFPA 72-mandated wireless retrofits as insurers condition premium discounts on faster alarm verification. The FCC regulates 2.4 GHz and 868 MHz spectrum allocation for fire safety applications. Texas Medical Center in Houston specifies Wi-Fi-native detection systems that leverage existing enterprise WLAN infrastructure.
Germany
Munich airport expansions and Frankfurt financial district towers require sub-second device-to-panel communication under DIN 14676 standards for sensitive occupancies. ETSI harmonization of 868 MHz transmission power limits eliminates national radio module variants. Bavarian system integrators consolidate procurement across commercial portfolios through three-to-five year framework agreements.
United Kingdom
London and Manchester property managers prioritize remote diagnostics capabilities in tender evaluations for multi-site commercial real estate investment trusts. Approved Document B mandates ceiling coverage density in multi-family housing, favoring battery-powered wireless units. Oxford and Cambridge colleges deploy hybrid architectures that preserve historic fabric while meeting fire risk assessment obligations.
India
Mumbai, Bangalore, and Delhi smart city initiatives create first-mover advantage for mesh-network providers establishing local assembly partnerships. BIS fire safety mandates accelerate specification of wireless zones in new commercial construction. Telangana and Maharashtra industrial corridors attract component fabricators seeking to bypass Taiwan and South Korea radio module supply concentration.
France
Heritage preservation codes in Paris, Lyon, and Marseille prohibit cabling penetration in historic structures, creating captive demand for battery-powered radio frequency systems. ANSM and CNIL cybersecurity guidance shapes connected device penetration testing timelines. ETSI spectrum consolidation eliminates duplicate engineering overhead for pan-European product launches from French certification bodies.
Wireless Fire Detection Systems Market Vendor Landscape
Platform integrators command the system tier; component specialists sit upstream supplying radio modules and sensing chambers. The vendor base stratifies across three tiers: diversified building technology conglomerates with integrated fire safety portfolios, specialized detection manufacturers with deep channel relationships, and regional system integrators with local specification authority. Two strategic archetypes dominate: full-stack platform providers pursuing building management system convergence, and sensing technology specialists defending position through photoelectric innovation. Competitive moves concentrate on strategic partnerships for BACnet protocol integration and geographic expansion through installer-dealer network consolidation.
Among diversified technology conglomerates, Robert Bosch GmbH and Siemens AG occupy positions spanning European commercial specifications. Hochiki Corporation exemplifies the specialized detection archetype through its photoelectric sensing focus and Asia-Pacific channel density. Johnson Controls International plc represents the platform convergence strategy, extending connected fire portfolios through direct specification with large facility operators in United States healthcare and education verticals.
| Leading Market Players |
|---|
| Robert Bosch GmbH |
| Hochiki Corporation |
| Honeywell International Inc. |
| Electro Detectors Ltd. |
| Apollo Fire Detectors Ltd. |
| Siemens AG |
| Halma PLC |
| EMS Security Group |
| Johnson Controls International plc |
| Others |
Supply Flow & Price Mechanics
The North Sea-Baltic rail freight corridor channels mesh-network components from Rotterdam and Hamburg into Central European retrofit pipelines, with freight rate volatility transmitting directly to landed costs for 868 MHz radio modules and photoelectric sensing chambers. This logistics concentration amplifies price differentiation between certified EN 54-25 systems and uncertified alternatives, while Taiwan and South Korea semiconductor fabricators extract margin through transceiver supply control.
Pricing Analysis
Volume-discount tiering structures separate framework agreement pricing for multi-site commercial portfolios from transactional spot purchases for single-building retrofits. Certification grade under DIN 14676 and NFPA 72 creates premium tiers for healthcare and data center specifications, while standard-grade units serve residential landlords. Cost compression in the standard tier intensifies as Chinese assembly partnerships enter European distribution. Small commercial installers exhibit highest price sensitivity; hospital procurement committees prioritize alarm verification speed over hardware cost.
Supply Chain Analysis
Tariff exposure between Taiwan and European Union member states dominates supply chain risk planning for 868 MHz transceiver procurement. Production concentrates in Taiwan, South Korea, and mainland China for radio modules, with German and Dutch laboratories handling EN 54-25 certification testing. The supply chain rests on lithium battery cells from South Korea, optical chambers from Japan, and injection-molded housings from China. Single-source vulnerability concentrates in 2.4 GHz chipset fabrication. Distribution runs through installer-dealer networks anchored by building technology conglomerates with direct specification relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
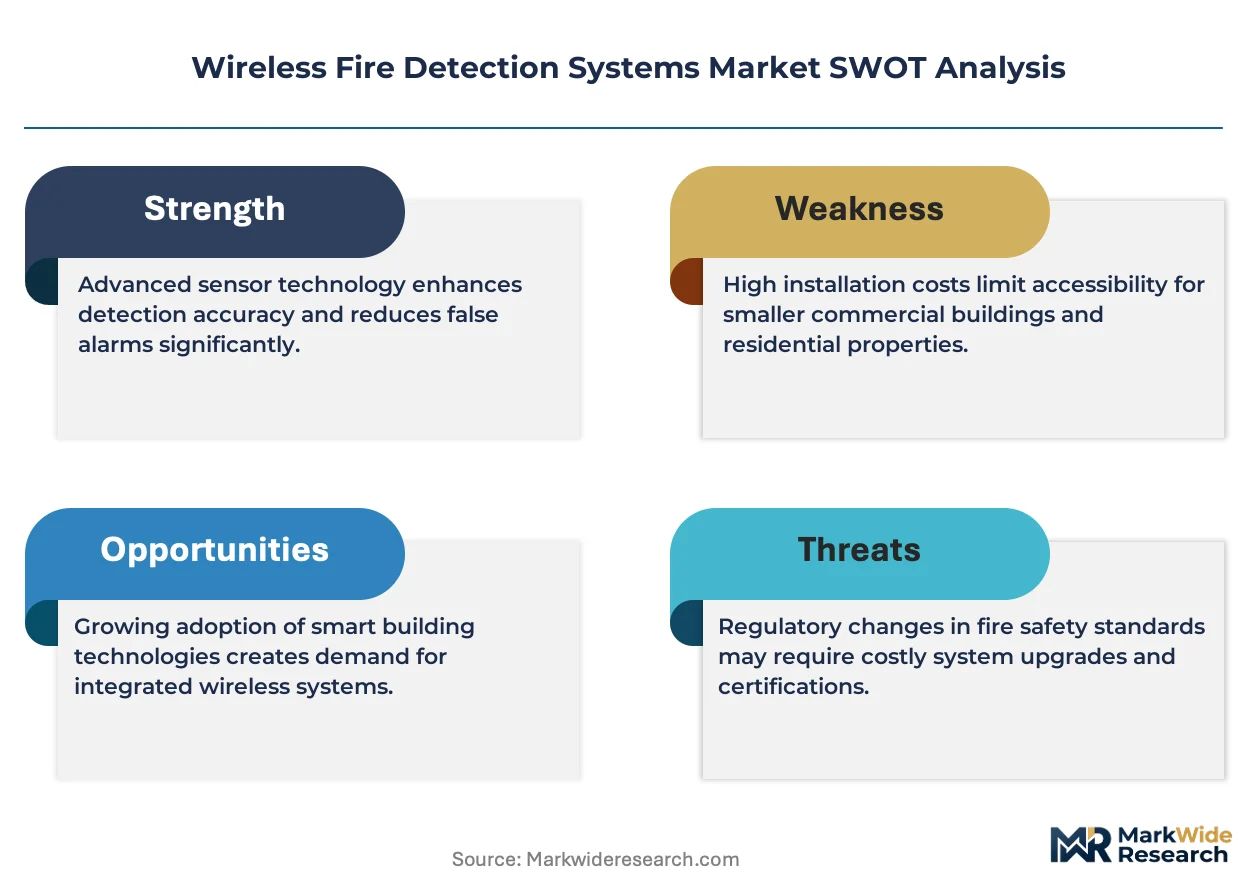
Wireless fire detection systems represent a fragmentation opportunity as building management system convergence splinters procurement authority between facilities management outsourcers, installing contractors, and end-user technical directors. This demand-side shift creates niche entry points for specialized protocol integrators and regional certification specialists.
For Market Incumbents: Pre-empt platform disintermediation by securing BACnet and Modbus integration certifications ahead of facilities management outsourcing consolidation. Deepen upstream control over 868 MHz radio module supply through captive partnerships with Taiwanese fabricators. Lock in three-to-five year framework agreements with United Kingdom commercial real estate investment trusts before hybrid installation demand peaks.
For New Entrants and Emerging Players: Build out local assembly partnerships in Maharashtra and Telangana to bypass Taiwan radio module supply concentration and capture India smart city wireless zone specifications. Target temporary installation verticals in Australian and Canadian construction site safety regulations where rapid-deployment wireless zones command premium pricing. Lead with smartphone-based commissioning tools to reduce RF engineering talent barriers.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified building technology conglomerates seeking to monetize non-core fire safety divisions as platform convergence pressures portfolio rationalization. Long-term viability hinges on cybersecurity certification capabilities against IEC 62443 standards as connected device penetration deepens. Monitor EN 54-25 certification backlog durations at Dutch and German laboratories as demand inflection signal.
| Strategic Initiative | Industry Significance |
|---|---|
| Certification Investment | EN 54-25 type-approval at Dutch laboratories accelerates pan-European market access. |
| Protocol Integration | BACnet gateway development opens recurring software revenue from facilities management outsourcers. |
| Geographic Assembly Partnership | Maharashtra local production bypasses Taiwan radio module supply concentration. |
| Cybersecurity Certification | IEC 62443 penetration testing differentiates connected systems in healthcare tenders. |
| Channel Consolidation | Installer-dealer network acquisition captures specification authority in United Kingdom commercial portfolios. |
Methodological Framework
Operator-level perspectives from fire safety system integrators, facilities management directors, building technology procurement leads, and regulatory certification engineers anchored the qualitative base. Primary interviews combined with secondary validation from FCC spectrum allocation filings, ETSI harmonization directives, NFPA 72 update documentation, and EN 54-25 test protocol records. Bottom-up unit economics triangulated against top-down construction spending data across commercial, educational, and healthcare verticals.
Scenario-bracketing framed projections across the analysis window, with segmentation modeling across product type, installation architecture, technology protocol, and end-user vertical. CAGRs derived from replacement cycle timing, retrofit mandate compliance deadlines, and insurance underwriting incentive diffusion. Forecast inputs incorporated radio module lead time volatility, certification laboratory capacity constraints, and mesh network adoption curves in heritage building protection.
The forecast holds incumbent behavior within observed patterns; aggressive moves by building management system platform providers or cybersecurity-specialist entrants would shift outcomes. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fire Safety & Protection
US Fire Safety Equipment Market
Fire Safety & Protection
Deflagration Flame Arresters Market
Fire Safety & Protection
GCC Firefighting Foam Market
Fire Safety & Protection
Flame Detector System Market
Fire Safety & Protection
Global Smoke Evacuation Systems Market
Fire Safety & Protection
Fire Protection Coating Market
Fire Safety & Protection
Global Fire Resistant Cable Market
Fire Safety & Protection
Global Fire Suppression System Market
Fire Safety & Protection
Fire and Explosion Proof Lights Market
Fire Safety & Protection
Fire Pump Market
Fire Safety & Protection
Civil Combustible Gas Alarm Market
Fire Safety & Protection
US Fire Alarm and Detection Market
Fire Safety & Protection
Laser Smoke Detector Market
Fire Safety & Protection
Automatic Fire Suppression System (AFSS) Market
Fire Safety & Protection
Fire Resistant Glass Market
Fire Safety & Protection
Fire Protection Valves and Fittings Market