
 Sports Gun Market | 2026-2036
Sports Gun Market Size, Share, and Industry Trends Forecast 2026-2036
Sports Gun Market Intelligence
The adoption of modular platforms that permit user customization of stocks, barrels, and optics is reorganizing the market's competitive structure. Sturm Ruger & Company Inc. leverages its extensive manufacturing capabilities to compete across multiple price points. Smith & Wesson Brands Inc. specializes in the handgun and modern sporting rifle segments, while Beretta Holding S.A. sustains its premium position through fine craftsmanship.
Sports guns are firearms and non-powder arms engineered specifically for recreational and competitive use, distinct from standard-issue service weapons. These products are characterized by features like adjustable triggers, ergonomic grips, and precision-rifled barrels designed to maximize accuracy and performance. The pistol and rifle product types command significant market share, with semi-automatic technology leading in competitive shooting applications. Bolt action mechanisms, however, remain dominant for long-range precision target shooting and certain hunting disciplines.
Market access is shaped by a complex patchwork of national and local regulations, including the licensing and background check laws enforced by authorities in the United States and Canada. In Europe, the European Firearms Directive and specific national hunting laws in countries like Germany and France dictate legal firearm types, calibers, and magazine capacities. Navigating these varied and evolving legal frameworks is a critical competency for all market participants.
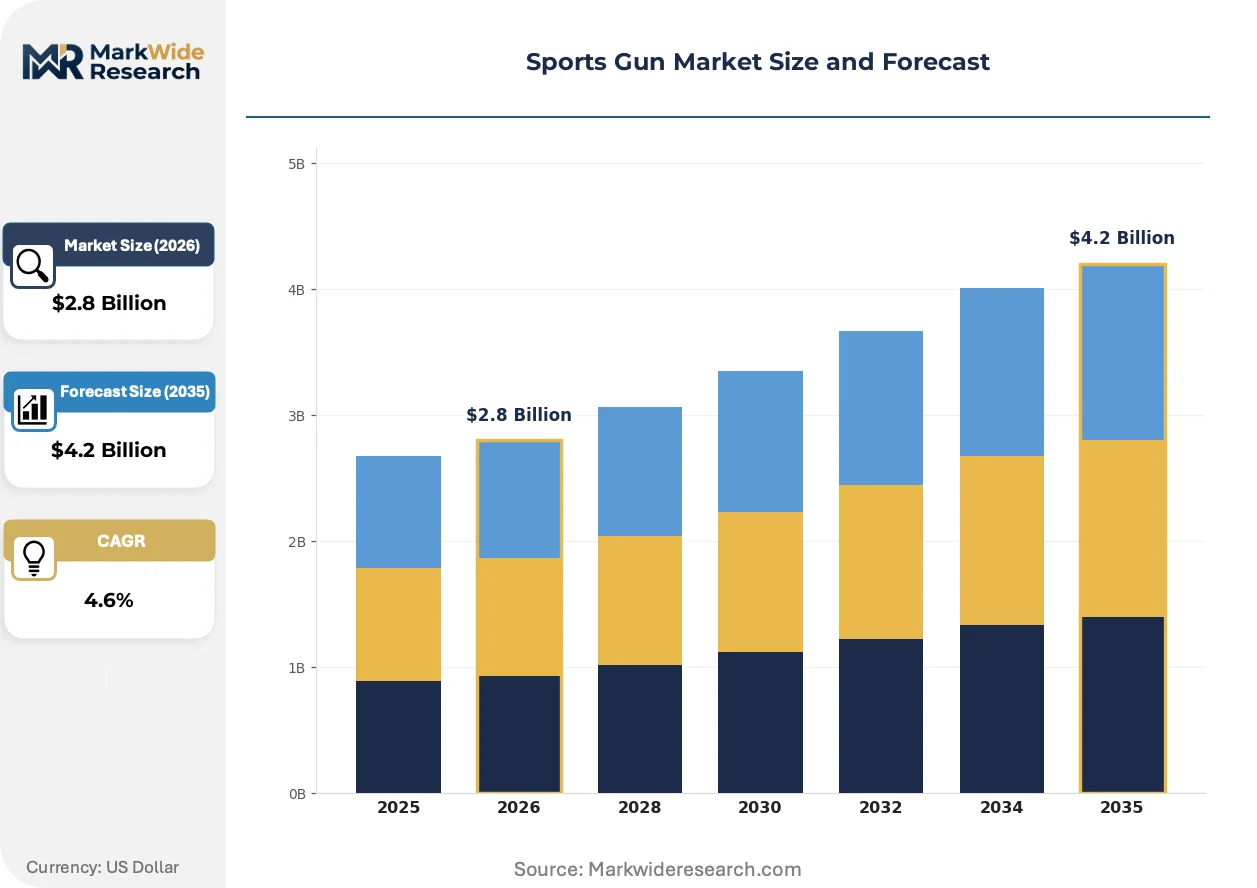
Market Dynamics
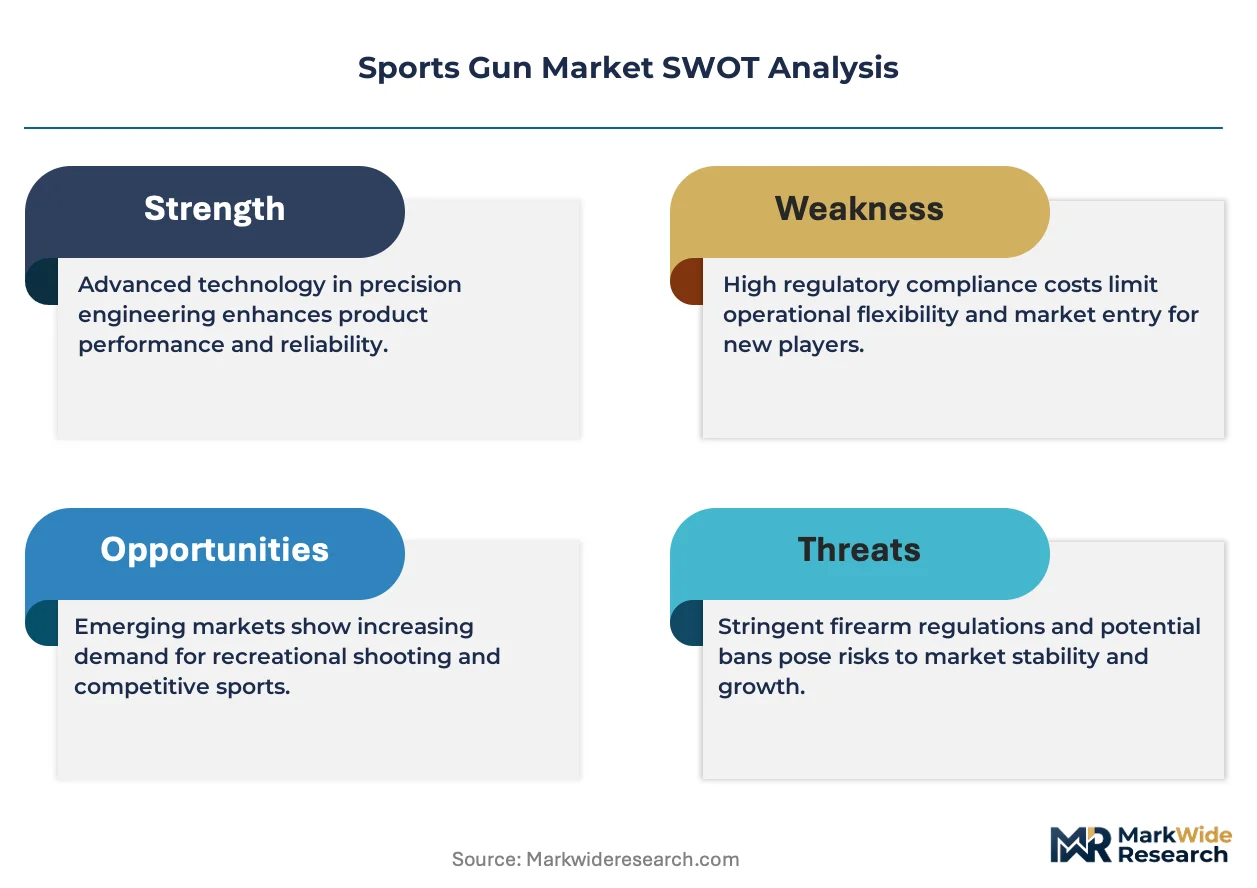
The sports gun market's evolution is governed by a fundamental tension between the demand for mass customization, driven by modular platforms, and an increasingly restrictive and fragmented global regulatory environment. This dynamic forces manufacturers to balance innovation in materials and user-configurable features against the high cost of compliance across diverse legal jurisdictions.
Growth Catalysts
- Expanding Competitive Circuits:The proliferation of organized shooting sports, including disciplines sanctioned by the International Practical Shooting Confederation (IPSC), stimulates demand for performance-oriented pistols and rifles specifically engineered for competition.
- Material Innovation:The integration of carbon fiber barrels and advanced polymer frames reduces firearm weight and improves handling, attracting shooters seeking enhanced performance and durability for both recreational and competitive applications.
- Hunting Legislation:Favorable hunting laws and dedicated conservation programs in countries like Canada and Germany sustain a consistent demand for specialized bolt-action and semi-automatic hunting rifles.
Market Restraints
- Divergent Regulatory Frameworks:A complex patchwork of laws, from the European Firearms Directive to state-level statutes in the United States, creates significant compliance burdens and limits market access for certain product categories.
- Input Material Volatility:Price and supply instability for critical inputs like high-grade steel, aluminum alloys, and specialized polymers can compress manufacturer margins and disrupt production schedules.
- Social and Political Pressure:Heightened public scrutiny and advocacy for stricter gun control measures in various countries can lead to restrictive zoning for shooting ranges and limitations on advertising, impeding market growth.
Strategic Opportunities
- Female Shooter Segment:There is a significant opportunity to develop and market firearms with ergonomic designs, adjustable features, and aesthetics specifically tailored to the growing demographic of female participants in shooting sports.
- Non-Powder Training Systems:Expanding the development of high-fidelity airsoft and CO2-powered replicas offers a path to enter the adjacent training and simulation market for both civilian and professional users.
- Digital Customization Platforms:Investing in online configurators that allow customers to virtually design and order customized firearms can enhance brand loyalty and capture demand for personalized products.
Industry Challenges
- Export Control Complexity:Manufacturers face significant operational hurdles in navigating international trade regulations, such as the U.S. International Traffic in Arms Regulations (ITAR), which govern the export of defense-related articles and services.
- Precision Manufacturing Talent:A shortage of skilled machinists and gunsmiths proficient in both traditional craftsmanship and modern CNC machining poses a challenge to scaling production of high-precision components.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Sports Gun Market |
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.2 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Rifles, Pistols, Shotguns, Air Guns, Crossbows Technology: Bolt Action, Lever Action, Semi-Automatic, Pump Action, Single Shot Application: Target Shooting, Hunting, Biathlon, Competitive Shooting, Recreation End User: Professional Shooters, Amateur Shooters, Sports Clubs, Training Academies, Collectors |
| Companies Covered | Glock Inc., Browning Arms Company, Sturm Ruger & Company Inc., FN America LLC, Mossberg & Sons Inc., Smith & Wesson Brands Inc., Beretta Holding S.A., Colt's Manufacturing Company LLC, Savage Arms Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Sports Gun Market Strategic Shifts & Innovations
The market is defined by a push towards greater personalization and performance enhancement, often running parallel to tightening regulatory oversight. This creates a dynamic where technological advancements in modularity and materials are constantly adapted to meet specific legal and competitive requirements.
Modular chassis systems, which serve as a foundational frame for accepting different barrels, stocks, and grips, are a key product evolution. Competitive shooters and firearm hobbyists are adopting these platforms to create highly specialized configurations for different shooting disciplines. This modularity is displacing the traditional market for fixed-configuration firearms, forcing manufacturers to offer more adaptable and user-serviceable platforms.
Regulatory frameworks are a primary force shaping product design and availability. The European Firearms Directive, for instance, establishes specific classifications and restrictions on semi-automatic firearms and magazine capacities for civilian ownership. This directly impacts product development, compelling manufacturers to engineer compliant variants for sale within EU member states like Germany and France. The semi-automatic rifle segment is most affected by these design constraints.
A significant behavioral shift is occurring as consumers increasingly use digital platforms and online communities to research and plan purchases. This trend disrupts the traditional retailer-led sales process, as customers often enter stores with pre-determined specifications derived from online configurators and reviews. This direct-to-consumer engagement and pre-purchase customization is most visible within the United States' modern sporting rifle market.
Sports Gun Market Segmentation
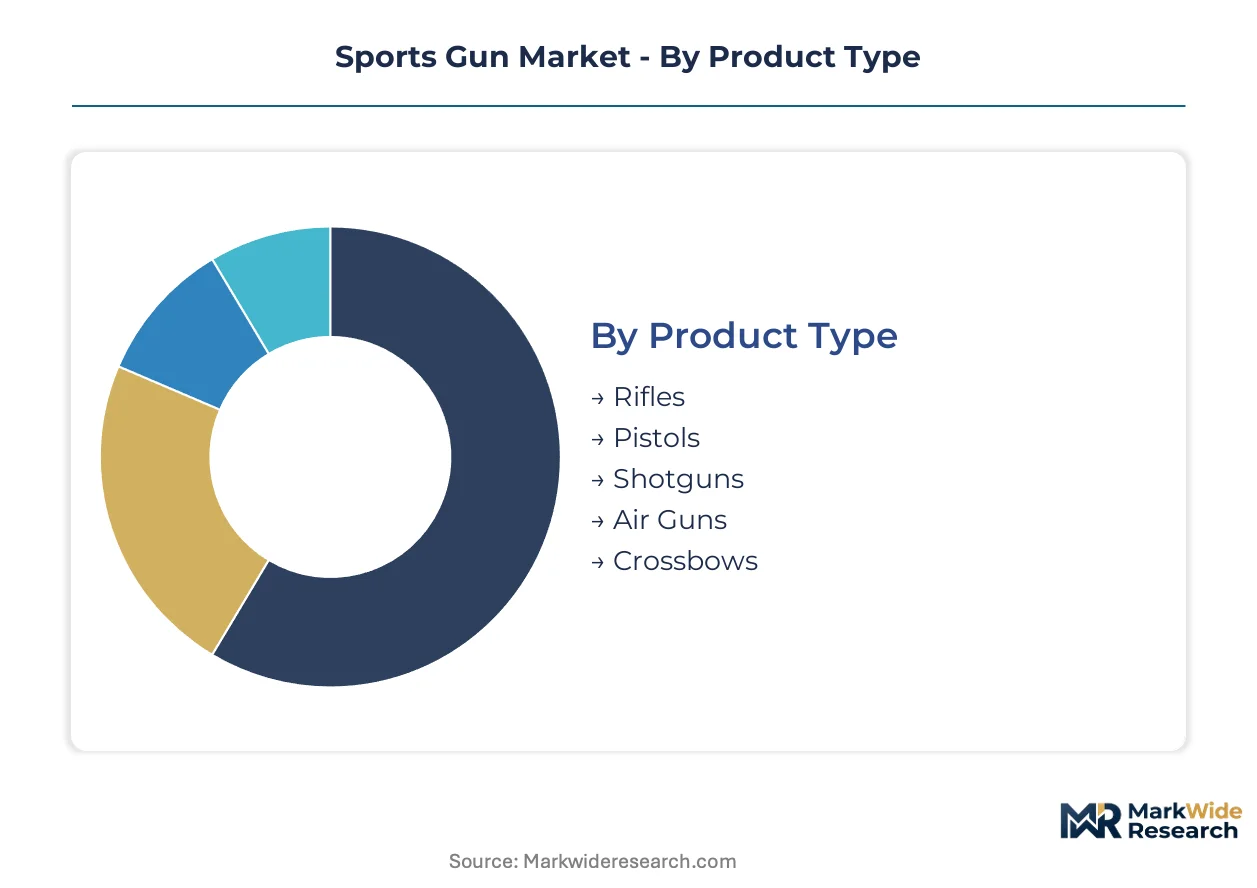
Segmenting the sports gun market reveals distinct product preferences, technological influences, application trends, and end-user demands that shape competitive strategies. Understanding these categories allows manufacturers to tailor product development and market entry efforts effectively across various regional contexts.
Product Type:
The geographic distribution of product types often reflects local regulations and established shooting traditions.
- Rifles:These long firearms feature precision-rifled barrels, designed for accuracy over distance. Demand concentrates heavily in the United States for recreational shooting and hunting, driven by cultural acceptance and vast open spaces.
- Pistols:Handheld firearms characterized by shorter barrels and ergonomic grips, primarily used for competitive shooting and personal defense. Their compact nature makes them popular in organized sports circuits like IPSC, particularly across North America and parts of Europe.
- Shotguns:Smoothbore firearms firing multiple pellets or a single slug, suitable for close-range hunting and clay target sports. Popularity remains consistent in hunting-focused regions like Canada and rural areas of the United States.
- Air Guns:Non-powder arms using compressed air or gas to propel projectiles, often used for target practice and pest control. These products find broad acceptance in countries with strict firearm regulations, such as Germany and the United Kingdom.
- Crossbows:Archery weapons that launch bolts, commonly used for hunting and recreational shooting. Their market presence is notable in specific hunting seasons and regions where traditional firearms may be restricted or less preferred.
Rifles holds the largest share; momentum sits with Pistols.
Technology:
The choice of sports gun technology directly correlates with the specific application and performance requirements of the shooter.
- Semi-Automatic:These firearms automatically load a new round after each shot, requiring a separate trigger pull for every discharge. Competitive shooting applications, particularly in disciplines demanding rapid follow-up shots, drive significant demand for these systems.
- Bolt Action:Manually operated mechanisms where the shooter manipulates a bolt to load, fire, and eject cartridges, known for their precision and reliability. Long-range precision target shooting and various hunting disciplines rely on bolt action rifles for consistent accuracy.
- Lever Action:Firearms operated by a lever beneath the receiver to cycle ammunition. These systems maintain a niche appeal among traditionalists and specific hunting segments, especially in North American markets.
- Pump Action:Shotguns and some rifles where a sliding fore-end is manually operated to cycle ammunition. This technology remains a staple for certain hunting scenarios and practical shooting sports.
- Single Shot:Firearms designed to hold only one round at a time, requiring manual reloading after each shot. They are often favored for their simplicity, reliability, and use in entry-level shooting sports or specific hunting challenges.
Semi-automatic technology exhibits the fastest-growing trajectory, while bolt action mechanisms provide foundational stability.
Application:
Different end-user applications dictate the design features and performance characteristics of sports guns, influencing market demand.
- Competitive Shooting:Disciplines like IPSC and precision rifle series demand highly specialized, performance-oriented firearms with features such as adjustable triggers and ergonomic stocks. This segment attracts both professional and amateur participants seeking optimized equipment for skill-based contests.
- Hunting:The pursuit of game animals requires durable, reliable firearms suited for various environments and target species, often influenced by specific hunting laws and conservation programs. Countries like Canada and Germany sustain consistent demand for specialized hunting rifles and shotguns.
- Target Shooting:Recreational practice focusing on accuracy and skill development at designated ranges, often involving a wide array of firearm types. This broad category forms a significant entry point for new enthusiasts.
- Biathlon:A winter sport combining cross-country skiing and rifle shooting, requiring lightweight, highly accurate rifles designed for extreme conditions. This niche application drives specialized demand within specific European nations.
- Recreation:Casual shooting activities for enjoyment, often involving less specialized equipment than competitive or hunting applications. This segment includes general range use and informal plinking.
Competitive shooting applications drive significant innovation, and hunting maintains a consistent market presence.
End User:
The diverse range of end-users influences product development, marketing, and distribution channels within the sports gun market.
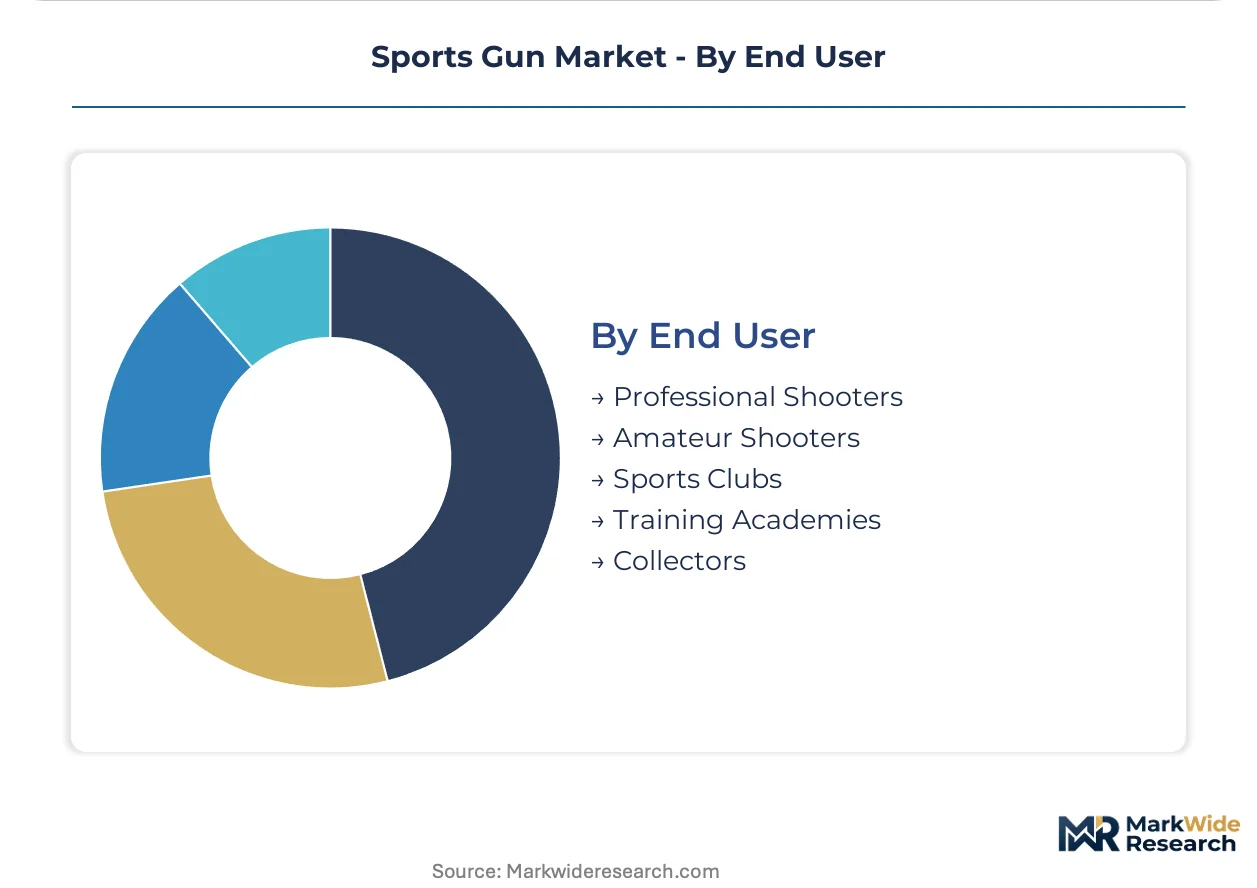
- Professional Shooters:Elite athletes and sponsored individuals who require top-tier, precision-engineered firearms for national and international competitions. Their equipment choices often set trends for the broader market.
- Amateur Shooters:Recreational enthusiasts and club members participating in local competitions or informal shooting activities, seeking reliable and often customizable firearms. This large demographic drives significant volume across various product categories.
- Sports Clubs:Organizations that provide facilities, training, and events for shooting sports, often purchasing firearms for member use or rental. These entities serve as crucial hubs for community engagement and skill development.
- Training Academies:Institutions offering instruction in firearm safety, handling, and marksmanship to civilians and security personnel. They require robust, often modular, firearms suitable for frequent use and diverse training scenarios.
- Collectors:Individuals who acquire firearms based on historical significance, craftsmanship, or rarity, often valuing unique designs and limited editions. This segment contributes to the demand for premium and specialized products.
Amateur shooters represent a substantial customer base, and the female shooter segment offers significant future potential.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manufacturing and product development for sports guns concentrate significantly within countries possessing mature industrial bases and established firearm cultures. Regional demand patterns are heavily influenced by local shooting traditions, hunting practices, and specific regulatory frameworks. This geographic distribution shapes product specialization and market access strategies for manufacturers.
United States
The United States drives substantial demand for rifles and pistols, fueled by its extensive recreational shooting and hunting culture. Federal and state-level licensing and background check laws shape market access for manufacturers. Production and innovation clusters in states like Massachusetts and New Hampshire support major firearm manufacturers.
Germany
Germany exhibits consistent demand for specialized hunting rifles and precision target shooting equipment. The European Firearms Directive and national hunting laws dictate legal firearm types and capacities. Traditional gunsmithing expertise in regions like Suhl maintains a niche for high-craftsmanship firearms.
Canada
Canada sustains a steady demand for hunting rifles and shotguns, supported by dedicated conservation programs and vast wilderness areas. Health Canada regulates firearm classifications and import permissions, influencing product availability. Distribution networks centered in provinces like Ontario facilitate market access for international brands.
France
France maintains a market for hunting and sport shooting, with demand for firearms compliant with European regulations. National hunting laws, alongside the European Firearms Directive, specify allowable calibers and magazine capacities. The historical arms manufacturing hub in Saint-Étienne continues to influence domestic firearm design.
Japan
Japan's sports gun market is highly specialized, focusing on precision target shooting and air guns due to stringent firearm control. METI (Ministry of Economy, Trade and Industry) enforces strict import and ownership regulations for all firearms. Major distribution and sales points in urban centers like Tokyo serve a dedicated community of sport shooters.
Sports Gun Market Key Industry Players
Concentration sits with established manufacturers possessing broad product portfolios and extensive distribution networks. The market exhibits a tiered structure, encompassing large-scale industrial producers, niche specialists focusing on specific disciplines, and premium craft houses. Manufacturers pursue portfolio diversification to cover multiple price points and engage in material innovation to enhance product performance. Geographic expansion into less saturated markets also represents a key competitive move.
Within the established manufacturer tier, Sturm Ruger & Company Inc. exemplifies a broad market approach, leveraging manufacturing capabilities across various price points. Smith & Wesson Brands Inc. occupies a strong position in the handgun and modern sporting rifle segments, catering to high-volume demand. Beretta Holding S.A., an Italian-based company, anchors the premium segment through its focus on fine craftsmanship and heritage designs. These entities collectively shape product development and competitive dynamics.
| Leading Market Players |
|---|
| Glock Inc. |
| Browning Arms Company |
| Sturm Ruger & Company Inc. |
| FN America LLC |
| Mossberg & Sons Inc. |
| Smith & Wesson Brands Inc. |
| Beretta Holding S.A. |
| Colt's Manufacturing Company LLC |
| Savage Arms Inc. |
| Others |
Cost & Logistics Intelligence
Long-term supply agreements for specialized components provide manufacturers with stable input costs and predictable production schedules. This contract-based approach mitigates volatility in material pricing, securing critical supply for high-demand products.
Pricing Analysis
The European Firearms Directive dictates the pricing tier structure for compliant variants sold within EU member states. Per-unit transactional pricing dominates across product types, reflecting direct sales and distribution models. Fine craftsmanship, advanced material integration, and extensive customization levels drive significant price differentiation for premium models. Pricing pressure stems from the high cost of navigating complex regulatory compliance and integrating continuous material innovation. Amateur shooters, seeking entry-level options, exhibit greater price sensitivity than professional or collector segments.
Supply Chain Analysis
The United States, Germany, and Italy anchor the production of high-precision sports guns and critical components, leveraging established manufacturing capabilities. The supply chain draws from specialized input materials, including high-grade steel, aluminum alloys, and advanced polymers, often sourced globally. Input material volatility, alongside export control complexity like U.S. ITAR regulations, represents a key structural risk impacting manufacturer margins and production schedules. Distribution runs primarily through specialized retail networks and increasingly via online platforms, particularly in North American markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The sports gun market is entering a cyclical recovery, driven by the expanding proliferation of organized shooting sports worldwide. This resurgence stimulates demand for performance-oriented equipment.
For Market Incumbents: Secure market share by prioritizing portfolio diversification across price points and product types, catering to both amateur and professional users. Invest in material innovation, such as carbon fiber and advanced polymers, to enhance product durability and performance. Mitigate threats from divergent regulatory frameworks through proactive design for compliance across jurisdictions. R&D in modular platforms offers a crucial lever for sustained competitive advantage against niche players.
For New Entrants and Emerging Players: CE marking pathway expertise offers a direct route into European markets for compliant non-powder products. Target the underserved female shooter segment with ergonomically designed firearms and expand non-powder training systems for adjacent market entry. The air gun segment in countries with strict firearm regulations presents the most penetrable market. Digital customization platforms provide a strong go-to-market angle, enhancing consumer engagement.
For Investors and Strategic Acquirers: Capital is best deployed toward niche specialists demonstrating strong intellectual property in modular designs or advanced materials. The market exhibits long-term viability, sustained by deeply rooted recreational shooting and hunting cultures in key regions like the United States. Acquisition targets should possess robust compliance capabilities across fragmented regulatory landscapes. Growth in competitive shooting participation metrics serves as a critical signal to watch for market expansion.
| Strategic Initiative | Industry Significance |
|---|---|
| Product Launch: Modular Chassis Systems | This initiative allows users to customize firearms, enhancing adaptability for various shooting disciplines. |
| Capacity Expansion: Precision Manufacturing | Scaling production of high-precision components addresses the shortage of skilled machinists and gunsmiths. |
| Strategic Partnership: Digital Platform Integration | Collaborating on online configurators improves direct-to-consumer engagement and personalized product offerings. |
| Brand Extension: Female Shooter Segment | Developing tailored ergonomics and aesthetics attracts the growing demographic of female participants. |
| Regulatory Compliance: EU Market Access | Proactive engineering of compliant variants ensures market access within European Firearms Directive jurisdictions. |
Research Approach
A standing panel of firearm designers, competitive shooters, regulatory experts, and distribution channel managers provided ongoing calibration for market insights. This approach combined primary interviews with industry stakeholders and rigorous secondary validation. Secondary data sources included government firearm registries, shooting sports association reports, manufacturing patent databases, and trade publications. Bottom-up data aggregation and top-down market sizing ensured robust triangulation.
Outputs were validated against external benchmarks to ensure forecast consistency across the analysis window. The analytical framework modeled market dynamics across product type, technology, application, end-user, and regional regulatory environment. Compound annual growth rates were derived from historical growth trends and projected market drivers. Key forecast inputs included material innovation adoption rates and competitive shooting event calendars.
Decision-makers should treat outputs as directional under current regulatory stability and material availability base assumptions; material deviation would warrant model refresh. Forecasts reflect these underlying assumptions. Geopolitical events or rapid shifts in social perception regarding firearm ownership represent key risk factors. Recalibration cycles align with material shifts in named drivers.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Safety Equipment and Personal Protective Equipment (PPE)
Hearing Protection Products Market
Safety Equipment and Personal Protective Equipment (PPE)
Bulletproof Gear Market
Safety Equipment and Personal Protective Equipment (PPE)
Radar Speed Gun Market
Safety Equipment and Personal Protective Equipment (PPE)
Global Surgical Mask and Respirators Market
Safety Equipment and Personal Protective Equipment (PPE)
Tourniquet Cuffs Market
Safety Equipment and Personal Protective Equipment (PPE)
Traffic Baton Market
Safety Equipment and Personal Protective Equipment (PPE)
N95 Mask Market
Safety Equipment and Personal Protective Equipment (PPE)
Self-Contained Breathing Apparatus (SCBA) Cylinders Market
Safety Equipment and Personal Protective Equipment (PPE)
Industrial Personal Protective Equipment Market
Safety Equipment and Personal Protective Equipment (PPE)
Process Safety System Market
Safety Equipment and Personal Protective Equipment (PPE)
Anesthetic Gas Masks Market
Safety Equipment and Personal Protective Equipment (PPE)
US Personal Protective Equipment Market
Safety Equipment and Personal Protective Equipment (PPE)
Safety Eyewear Market
Safety Equipment and Personal Protective Equipment (PPE)
Passenger Emergency Oxygen Deployment Systems Market
Safety Equipment and Personal Protective Equipment (PPE)
US Smart PPE Technology Market
Safety Equipment and Personal Protective Equipment (PPE)
US Law Enforcement PPE Market