
 Rescue Pole Market | 2026-2036
Rescue Pole Market Size, Share, and Industry Trends Forecast 2026-2036
Rescue Pole Market Insights
Specialty fire-service distribution is narrowing as consolidated procurement platforms gain favor among municipal buyers. Akron Brass Company leverages its long-standing dealer network to sustain institutional relationships with fire departments across the Great Lakes region. Ziamatic Corp. competes through vertical integration into mounting hardware and vehicle storage systems that pair with rescue poles. CMC Rescue Inc. specializes in technical rescue training curricula, creating pull-through demand for its pole configurations among search and rescue teams.
A rescue pole is a rigid or telescoping reach-extension device, typically constructed from aluminum alloy or carbon fiber tubing with foam-filled flotation cores, engineered to retrieve personnel from water, ice, or elevated hazards while keeping rescuers at safe standoff distances. The product serves coast guards, fire departments, and search and rescue teams requiring mechanical advantage in confined or unstable environments. Telescopic rescue poles lead volume due to their transportability aboard vessels and aerial platforms, while carbon fiber variants command premium positioning among technical rescue specialists demanding strength-to-weight ratios for high-rise evacuation scenarios. Water rescue applications anchor replacement cycles because saltwater exposure and impact loading accelerate wear on fiberglass and aluminum components.
NFPA 1952 and NFPA 1983 standards govern construction and testing of water rescue equipment in the United States, compelling manufacturers to maintain third-party certification for municipal and federal contracts. OSHA fall protection provisions and Coast Guard boat operations regulations further shape product specifications for maritime safety operators and search and rescue teams. Stakeholders must monitor evolving FEMA grant priorities and state-level mutual aid consortium procurement standards to anticipate shifts in specification requirements and funding availability.
Market Dynamics
Municipal procurement consolidation is compressing vendor margins while elevating specification requirements, forcing rescue pole manufacturers to integrate certification services and training curricula directly into equipment contracts.
Growth Catalysts
- NFPA 1952 Certification Mandates:Updated testing protocols for water rescue equipment are compelling fire departments to replace legacy fiberglass poles with certified carbon fiber and aluminum alloy alternatives.
- FEMA Grant Priorities:Federal funding streams for swift-water and ice rescue capabilities are channeling capital toward reach-extension tools in coastal and Great Lakes municipalities.
- Carbon Fiber Manufacturing Scale:Aerospace composite production spillover is reducing input costs for high-strength tubing, enabling premium pole configurations to penetrate mid-tier municipal budgets.
Market Restraints
- Aluminum Price Volatility:LME aluminum futures swings above historical baselines are squeezing margin on standard-duty telescopic poles, pressuring manufacturers toward fixed-price raw material contracts.
- Regional Supply Concentration:Domestic carbon fiber weaving capacity clusters in a narrow band of Southeast Asian and North American facilities, exposing lead times to geopolitical friction and shipping rate spikes.
- Flotation Core Degradation:Closed-cell foam saturation limits in saltwater environments cap product lifespans regardless of structural tube integrity, accelerating replacement cycles unpredictably.
Strategic Opportunities
- Great Lakes Ice Rescue Expansion:Underpenetrated Canadian and US state-level mutual aid networks present whitespace for pole-and-training bundled offerings as ice-related drownings drive budget reallocations.
- Drone Integration Partnerships:Convergence of telescopic reach tools with unmanned aerial payload delivery systems opens technical rescue scenarios previously inaccessible to ground-based crews.
- OSHA Fall Protection Alignment:Elevated work platform regulations are creating specification overlap between water rescue and industrial confined-space applications, broadening addressable end-use verticals.
Industry Challenges
- Technical Rescue Instructor Scarcity:Certified swift-water and high-angle rescue educators are concentrated in legacy fire academies, constraining training throughput needed to generate pull-through equipment demand.
- Multi-Agency Certification Coordination:Coast Guard, NFPA, and state-level boat operations standards impose overlapping but non-identical testing regimes, extending product development timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Rescue Pole Market |
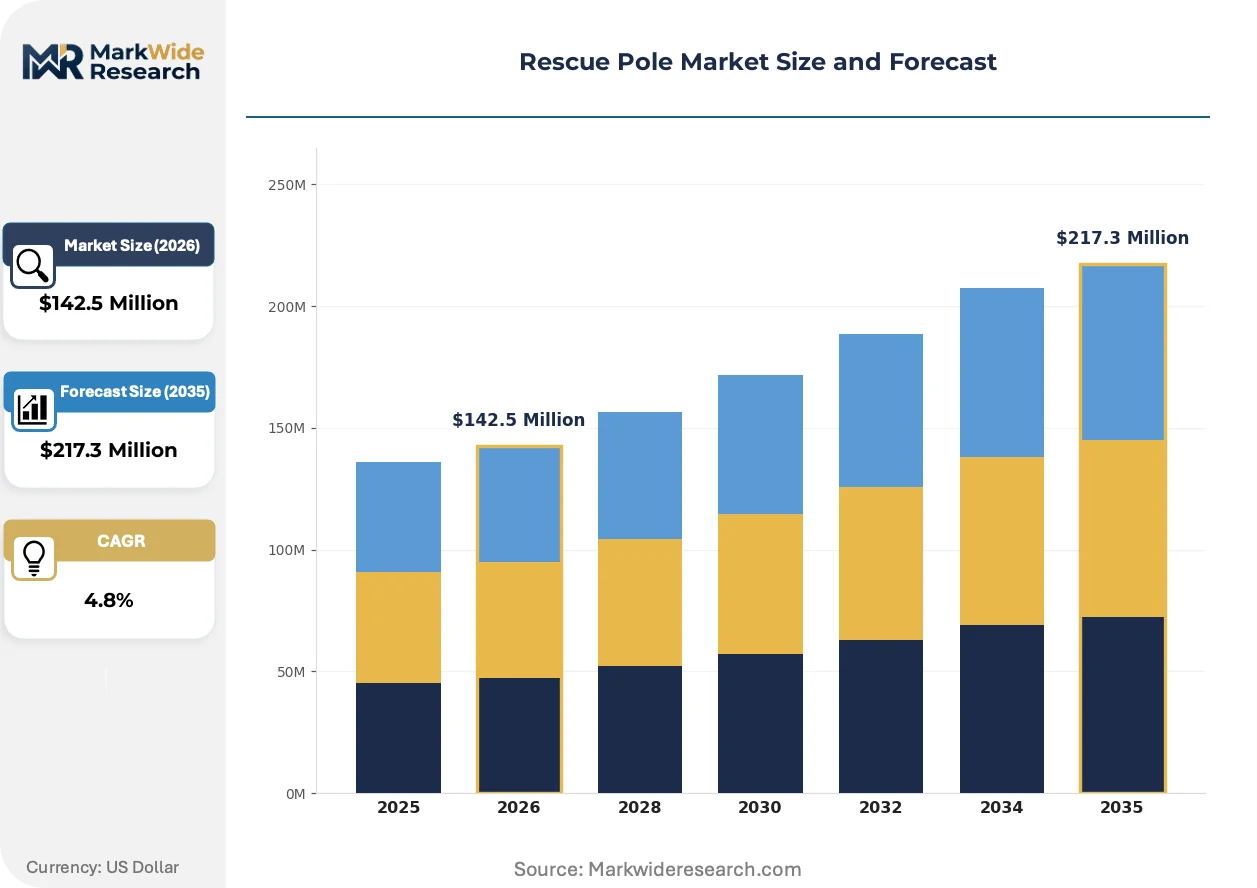
| Market Size in 2026 | $142.5 Million |
| Market Size in 2035 | $217.3 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Telescopic Rescue Pole, Fixed-Length Pole, Foldable Rescue Pole, Extendable Rescue Rod Material: Aluminum Alloy, Fiberglass, Stainless Steel, Carbon Fiber Application: Water Rescue, Firefighting Support, High-Rise Evacuation, Disaster Relief End User: Coast Guard, Fire Departments, Search & Rescue Teams, Maritime Safety Operators |
| Companies Covered | Super Vac, Ziamatic Corp., Akron Brass Company, Fire Hooks Unlimited Inc., CMC Rescue Inc., SavaTech Corp., RUTH LEE Ltd., Tempest Technology Corporation, Water Rescue Innovations, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Rescue Pole Market Trends and Innovations
Embedded sensor architectures and predictive maintenance platforms are digitizing how rescue equipment is specified, deployed, and retired across technical rescue operations.
Carbon fiber layup automation is digitizing quality control in pole manufacturing, enabling batch-to-batch consistency that satisfies third-party certification requirements. Fire departments in coastal California and Florida are specifying these digitally traceable poles for fleet standardization. The technology is digitizing procurement documentation, compressing vendor qualification cycles from months to weeks.
OSHA fall protection provisions are tightening documentation requirements for elevated rescue scenarios, compelling manufacturers to embed load-rated attachment points and serialized testing records directly into pole hardware. Industrial safety managers in petrochemical and utility sectors are now specifying these compliant configurations for confined-space standby teams. The regulation is forcing cross-training between water rescue and industrial rope access disciplines, blurring traditional equipment category boundaries.
Consolidated municipal procurement platforms are aggregating demand across multiple fire districts, displacing legacy dealer relationships with direct manufacturer contracts. State-level mutual aid consortiums in the US Northeast are centralizing specification authority, reducing the number of distinct purchase orders while increasing per-order volume commitments. This concentration is most visible in Massachusetts and New York, where regional purchasing cooperatives now dominate capital equipment acquisition channels.
Rescue Pole Market Segmentation
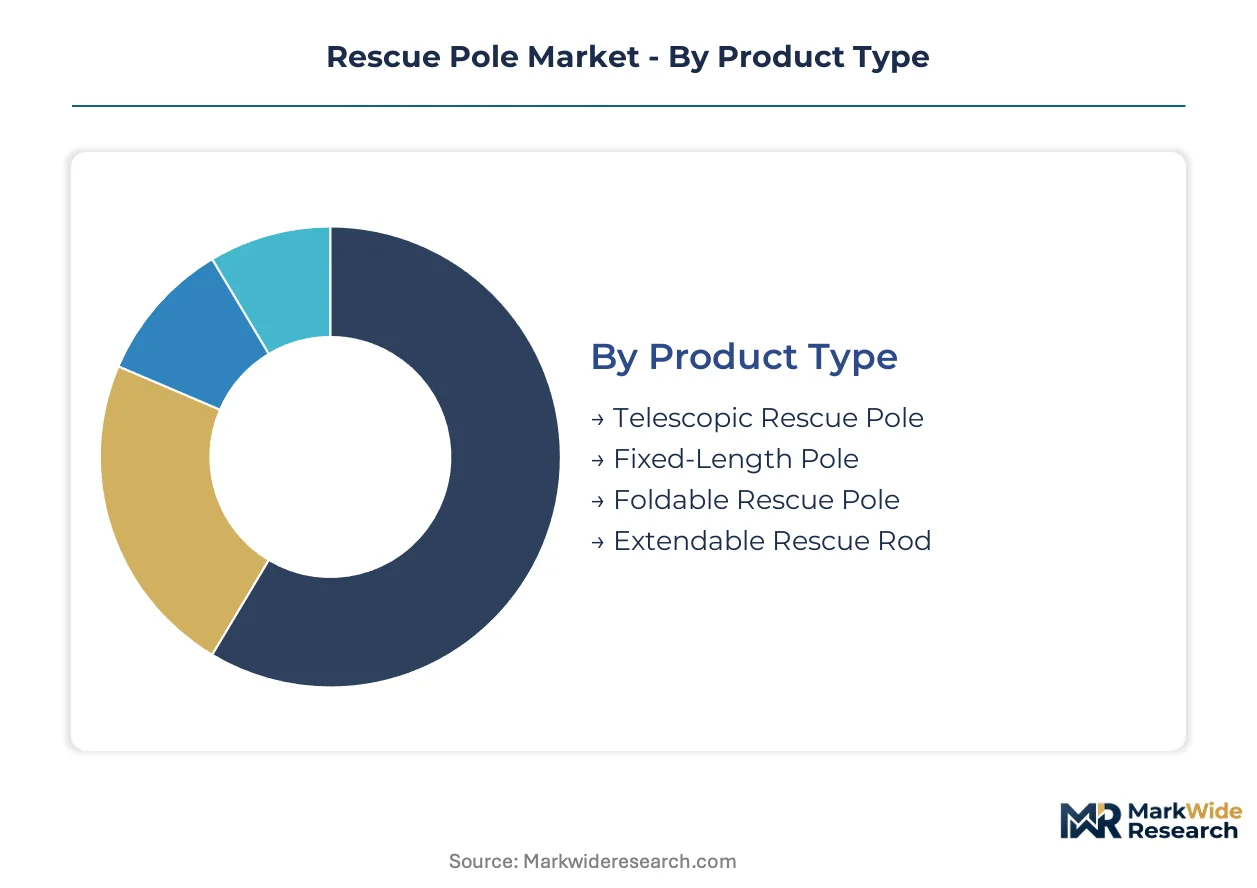
Rescue pole procurement patterns diverge sharply across operational contexts, with after-sales service intensity varying from minimal replacement-part support for fixed-length poles to comprehensive training-and-certification bundles for carbon fiber technical rescue configurations. Understanding these segment boundaries clarifies where manufacturers must embed service capabilities versus compete on unit economics.
Product Type:
After-sales service intensity peaks with telescopic designs requiring periodic seal replacement and lubrication protocols, while fixed-length poles demand minimal post-sale intervention beyond impact-damage assessment.
- Telescopic Rescue Pole:Collapsible aluminum or carbon fiber tubing with twist-lock or cam-lock extension mechanisms enables compact stowage on vessels and aerial platforms. Coast Guard stations in Florida and California specify these for swift-water operations where transportability governs fleet standardization decisions. Saltwater intrusion into locking mechanisms accelerates service intervals, creating recurring revenue streams for OEM maintenance programs.
- Fixed-Length Pole:Rigid single-section construction from aluminum or fiberglass delivers maximum torsional rigidity for ice rescue scenarios requiring direct leverage against shelf ice. Fire departments across the Great Lakes region favor these for predictable load ratings in sub-zero conditions where mechanism failure risks are unacceptable. Simpler construction translates to lower warranty claim rates and reduced field service requirements.
- Foldable Rescue Pole:Hinged joint systems permit breakdown into compact segments for backpack deployment by search and rescue teams operating in remote terrain.
- Extendable Rescue Rod:Threaded or slip-fit extension sections offer modular length adjustment without full telescoping complexity, common in industrial confined-space applications.
By volume, telescopic configurations lead. By growth pace, foldable variants for backcountry technical rescue are climbing fastest.
Material:
Cost tier stratification separates aerospace-grade carbon fiber commanding premium positioning from commodity aluminum serving municipal budget constraints, with fiberglass occupying a narrowing mid-market position.
- Carbon Fiber:Epoxy-impregnated unidirectional and woven prepregs deliver exceptional strength-to-weight ratios for high-rise evacuation scenarios where operator fatigue limits operational duration. Technical rescue specialists in urban search and rescue teams specify these for vertical confinement space entries exceeding 50-foot depths. Manufacturing scale effects from adjacent aerospace supply chains are compressing per-unit costs toward mid-tier accessibility.
- Aluminum Alloy:6061-T6 or 7075-T6 extrusions with anodized finishes provide cost-effective durability for standard-duty water rescue operations where weight penalties are operationally tolerable. Municipal fire departments in the United States specify these for budget-constrained fleet refreshes under FEMA grant programs. LME price volatility remains the dominant margin pressure factor for this segment.
- Fiberglass:Pultruded glass-reinforced polymer tubes offer electrical non-conductivity for utility sector applications, though saltwater saturation limits rescue service lifespans.
- Stainless Steel:Marine-grade 316L tubing persists in heavy-duty commercial fishing vessel applications where impact resistance supersedes weight considerations.
By volume, aluminum alloy dominates procurement. By margin expansion trajectory, carbon fiber is gaining share fastest.
Application:
Customer type concentration varies by rescue scenario, with water rescue anchoring replacement cycle predictability while high-rise evacuation creates specification complexity around OSHA fall protection alignment.
- Water Rescue:Flotation-cored pole configurations for swift-water, ice, and surf zone retrieval operations where rescuer standoff distance is critical. Fire departments in coastal municipalities drive specification authority here, with NFPA 1952 certification serving as the non-negotiable procurement filter. Saltwater exposure and UV degradation impose hard lifespan limits regardless of structural integrity, ensuring steady replacement demand.
- Firefighting Support:Secondary reach tools for victim location in smoke-filled structures and hazardous material zone perimeter marking. Urban fire departments integrate these into rapid intervention team kits for downed-firefighter extraction scenarios. Specification overlap with industrial safety equipment is broadening addressable end-uses.
- High-Rise Evacuation:Technical rescue configurations for window-access extraction and elevated platform transfer operations in dense urban cores.
- Disaster Relief:Rapid-deployment pole kits for collapsed structure void-space search and flood zone victim location in mutual aid deployments.
By volume, water rescue leads. By specification complexity growth, high-rise evacuation is expanding most quickly.
End User:
Geography concentration shapes procurement platform preferences, with Coast Guard modernization programs favoring consolidated federal contracts while municipal fire departments fragment across state-level purchasing cooperatives.
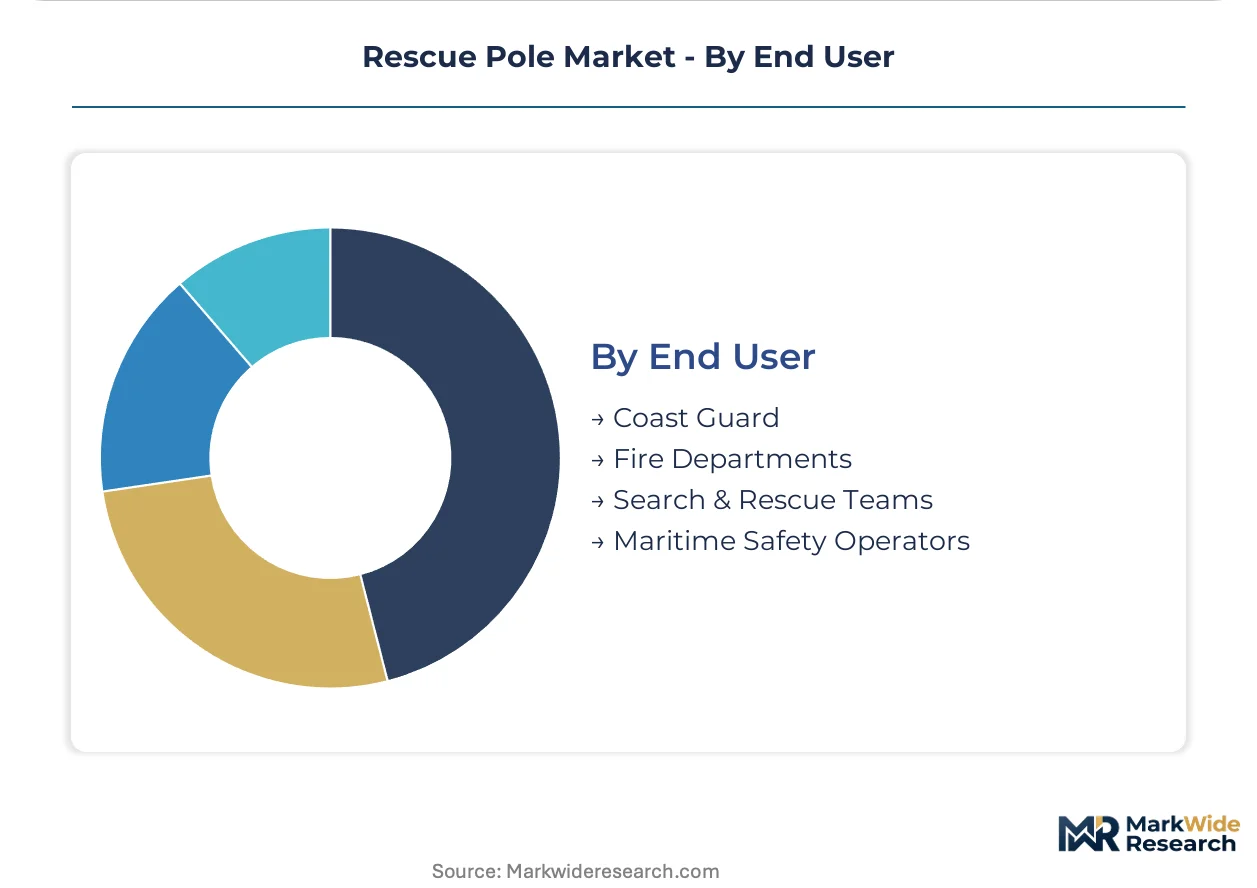
- Fire Departments:Municipal and volunteer agencies representing the largest addressable equipment base, with procurement authority migrating toward regional mutual aid consortiums in Massachusetts, New York, and Great Lakes states. FEMA grant dependency creates cyclical demand spikes following disaster declarations and updated equipment standard releases.
- Coast Guard:Federal maritime safety agencies with centralized specification authority and multi-year fleet modernization programs. United States Coast Guard contracts emphasize interoperability with allied nation equipment standards and integrated logistics support requirements.
- Search & Rescue Teams:Technical rescue specialists operating under state and county emergency management authorities with specialized training-to-equipment bundling preferences.
- Maritime Safety Operators:Commercial port authorities, ferry operators, and offshore energy platforms with OSHA and Coast Guard boat operations compliance obligations.
By volume, fire departments lead. By contract value concentration, Coast Guard procurement is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Great Lakes-St. Lawrence Seaway system underwrites North America's dominance in ice rescue pole procurement, while the English Channel maritime corridor anchors European demand for swift-water configurations.
United States
FEMA grant cycles and Coast Guard station modernization drive procurement concentration along the Gulf and Atlantic coasts. OSHA fall protection alignment with NFPA 1952 standards creates specification overlap between water rescue and industrial safety applications. California fire departments in coastal municipalities specify carbon fiber telescopic poles for surf zone operations.
Canada
Provincial mutual aid networks in Ontario and Quebec are consolidating ice rescue equipment procurement following several high-profile Great Lakes drownings. Transport Canada marine safety regulations now reference NFPA-equivalent testing protocols for reach-extension tools. Toronto and Vancouver port authorities are standardizing pole configurations across harbor response fleets.
United Kingdom
HM Coast Guard fleet renewal programs prioritize interoperability with NATO allied equipment standards for technical rescue scenarios. The Maritime and Coastguard Agency updated its boat operations guidance to specify load-rated attachment points on rescue poles. Aberdeen and Southampton maritime clusters host training centers driving specification authority for North Sea oil platform evacuation tools.
Germany
Industrial confined-space safety regulations from the Federal Institute for Occupational Safety and Health are expanding addressable demand beyond traditional water rescue. German fire service technical rescue teams specify carbon fiber poles for high-angle evacuation scenarios in the Rhine-Ruhr industrial corridor. Hamburg port authority contracts emphasize integrated logistics support requirements.
Australia
Surf Life Saving Australia coordinates state-level procurement for rip current rescue operations along the Gold and Sunshine Coasts. The Australian Maritime Safety Authority mandates third-party certification for all reach-extension equipment aboard commercial vessels. Sydney and Melbourne aerial firefighting fleets specify telescopic poles for window-access extraction in dense urban cores.
Rescue Pole Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in materials and mechanism supply. The vendor base clusters around three strategic archetypes: fire-service distribution platforms with institutional dealer networks, vertically integrated hardware manufacturers controlling mounting and storage systems, and technical rescue training providers generating pull-through equipment demand. Consolidated municipal procurement is compressing margins while elevating specification requirements. Geographic expansion and certification bundling represent the dominant competitive vectors.
Among North American fire-service equipment specialists, Akron Brass Company, Ziamatic Corp., and CMC Rescue Inc. occupy distinct positioning archetypes. Akron Brass exemplifies the institutional distribution platform model with sustained fire department relationships. Ziamatic represents vertical integration into complementary hardware systems. CMC Rescue anchors the training-centric pull-through demand archetype among technical rescue specialists. These three patterns illustrate how market participants are defending position through service embedding rather than unit cost competition alone.
| Leading Market Players |
|---|
| Super Vac |
| Ziamatic Corp. |
| Akron Brass Company |
| Fire Hooks Unlimited Inc. |
| CMC Rescue Inc. |
| SavaTech Corp. |
| RUTH LEE Ltd. |
| Tempest Technology Corporation |
| Water Rescue Innovations |
| Others |
Pricing and Supply Chain Analysis
Trans-Pacific container freight corridors from Southeast Asian carbon fiber weaving facilities to North American municipal buyers govern landed cost structures and compress margin recovery for mid-tier aluminum pole configurations. This logistics dynamic amplifies price differentiation between aerospace-grade carbon fiber rescue poles and commodity aluminum alternatives while forcing manufacturers toward fixed-price raw material contracts.
Pricing Analysis
Volume-discount tiering structures separate Coast Guard fleet modernization contracts commanding bundled training-and-certification packages from single-unit municipal procurement through regional purchasing cooperatives. Three-tier pricing stratification across premium carbon fiber, standard aluminum alloy, and economy fiberglass configurations reflects NFPA 1952 certification grade and after-sales service intensity. Cost compression in aluminum alloy segments is intensifying because LME futures volatility above historical baselines squeezes standard-duty telescopic pole margins. Volunteer fire departments in budget-constrained districts exhibit acute price sensitivity, whereas technical rescue specialists in urban search and rescue teams prioritize strength-to-weight performance over unit cost.
Supply Chain Analysis
Upstream feedstock for carbon fiber prepreg draws from Japanese and US aerospace composite production spillover, while aluminum alloy extrusions source from domestic North American and Chinese smelting capacity. Closed-cell foam flotation cores rely on petrochemical supply chains concentrated in Gulf Coast and Northeast Asian chemical manufacturing clusters. Single-source vulnerability in Southeast Asian carbon fiber weaving facilities exposes lead times to geopolitical friction and shipping rate spikes. Distribution runs through consolidated municipal procurement platforms and fire-service dealer networks, with regional mutual aid consortiums in Massachusetts and New York displacing legacy channel relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity characterizes this market as municipal procurement consolidation creates service-embedding niches that favor specialized training-and-certification bundling over pure equipment manufacturing scale.
For Market Incumbents: Build certification moats by embedding NFPA 1952 third-party validation services directly into equipment contracts and securing exclusive training curriculum partnerships with legacy fire academies. Backward integration into carbon fiber prepreg sourcing from aerospace supply chain spillover defends margin position against aluminum price volatility. Threat from consolidated procurement platforms elevates specification requirements and compresses vendor margins for undifferentiated hardware-only offerings.
For New Entrants and Emerging Players: Pursue Great Lakes ice rescue equipment whitespace in underpenetrated Canadian and US state-level mutual aid networks where ice-related drowning incidents drive budget reallocations. Target foldable rescue pole configurations for backcountry technical rescue teams operating in remote terrain, as this segment climbs fastest by growth pace. Go-to-market angle centers on drone integration partnerships for unmanned aerial payload delivery convergence.
For Investors and Strategic Acquirers: Carve-out targets emerge from fire-service distribution platforms with captive dealer networks in the Great Lakes and Gulf Coast regions, where institutional relationships resist procurement consolidation pressures. Long-term viability over the medium-term horizon rests on service-embedding capabilities rather than manufacturing scale alone. Signal to monitor: FEMA grant priority shifts toward swift-water and ice rescue capabilities as inflection indicator for equipment demand spikes.
| Strategic Initiative | Industry Significance |
|---|---|
| Certification Bundling | Embedding NFPA 1952 validation services into equipment contracts elevates vendor qualification cycles. |
| Drone Integration Partnership | Convergence with unmanned aerial payload delivery opens technical rescue scenarios for ground-based crews. |
| Carbon Fiber Backward Integration | Upstream control over aerospace composite supply chains compresses per-unit costs toward mid-tier accessibility. |
| Regional Training Center Alliance | Partnerships with Toronto and Vancouver harbor response fleets standardize pole configurations across port authorities. |
| Great Lakes Mutual Aid Consortium Penetration | Centralized specification authority in Massachusetts and New York purchasing cooperatives aggregates demand volume. |
Research Methodology
Cross-validation between primary interviews with fire department procurement officers, Coast Guard logistics specialists, and technical rescue training directors anchors the qualitative findings against secondary validation from NFPA standard documentation, FEMA grant allocation records, and municipal purchasing cooperative contract disclosures. Bottom-up triangulation across product type, material grade, and application segmentation integrates with top-down calibration against aluminum and carbon fiber composite trade flow data.
Calibration against historical replacement cycle patterns and certification mandate implementation timelines shapes the analytical framework across the projection horizon. Segmentation dimensions modeled include product configuration, material tier, rescue application scenario, and end-user procurement platform type. CAGRs derive from installed base depreciation curves, FEMA grant cyclicality, and Coast Guard fleet modernization schedules.
Macroeconomic conditions sit as an overlay; deviation in LME aluminum futures, trans-Pacific container freight rates, or aerospace composite production capacity would shift the trajectory. Cross-checking against state-level mutual aid consortium budget appropriations and Transport Canada marine safety regulation updates is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Disaster Recovery Solutions
Rope Rescue Harness Market
Disaster Recovery Solutions
France Ransomware Protection Market
Disaster Recovery Solutions
Incident and Deviation Management Solution Market
Disaster Recovery Solutions
Business Continuity Management Planning Solution Market
Disaster Recovery Solutions
Incident Response Services Market
Disaster Recovery Solutions
Flood Protection Sandbags Market
Disaster Recovery Solutions
Italy Ransomware Protection Market
Disaster Recovery Solutions
Global Data Protection and Recovery Solutions Market
Disaster Recovery Solutions
Global Incident Response Market
Disaster Recovery Solutions
Intelligent Emergency Response Systems and Infrastructure (IRIS) Market
Disaster Recovery Solutions
Global Data Resiliency Market
Disaster Recovery Solutions
Business Continuity Management Solutions Market
Disaster Recovery Solutions
Latin America Incident Response Services Market
Disaster Recovery Solutions
Disaster Preparedness Systems Market
Disaster Recovery Solutions
Spain Ransomware Protection Market
Disaster Recovery Solutions
Global Security Solutions Market