
 Canada Safety Services Market | 2026-2036
Canada Safety Services Market Size, Share, and Industry Trends Forecast 2026-2036
Canada Safety Services Market Outlook
Software-defined safety monitoring is pivoting how Canadian providers bundle recurring revenue with hardware deployments. Blackline Safety leverages cloud-connected wearables to anchor long-term service contracts across remote resource sites. Hercules SLR sustains national coverage through its rigging and fall-protection service network. Fire-Pro Fire Protection Ltd specializes in integrated suppression system maintenance, competing on response-time guarantees rather than equipment margins alone.
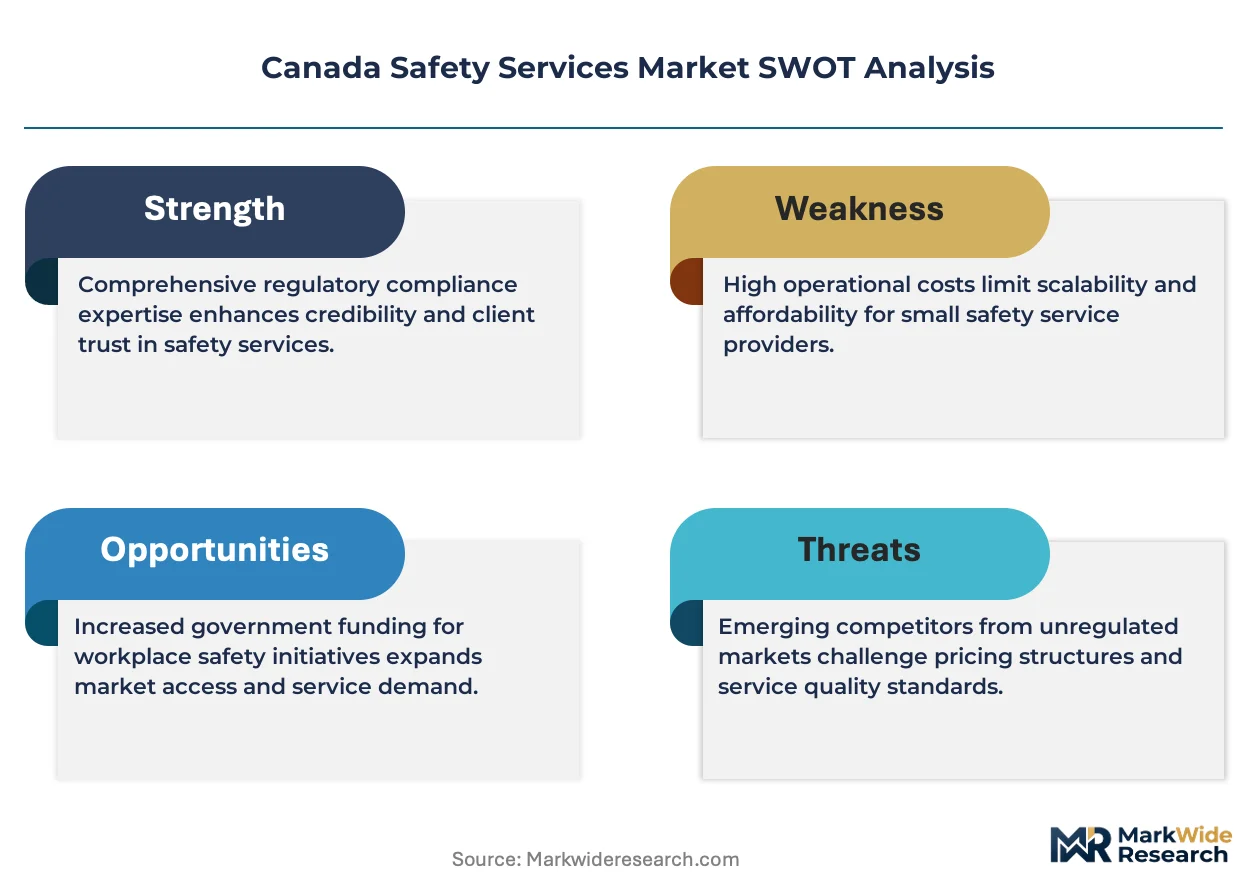
Canada Safety Services encompass technical systems and protocols designed to prevent occupational injury, environmental release, and operational disruption through hazard identification, protective equipment specification, and emergency preparedness planning. These services rely on certified personnel conducting atmospheric testing, fall-arrest calculations, and fire-code compliance verification against CSA and NFPA technical parameters. Wearables and monitoring systems now capture the fastest expansion as real-time biometric and environmental data streams replace periodic manual inspections. Training and auditing maintain mature, high-margin positions where long-standing relationships with provincial safety associations create renewal stickiness. Consulting faces price pressure from software-automated risk assessments, though complex regulatory interpretation retains specialist value.
Health Canada, provincial ministries of labour, and the Canadian Standards Association collectively enforce equipment certification, exposure limits, and incident reporting protocols that directly shape procurement specifications and vendor qualification criteria. The Canadian Welding Bureau anchors quality assurance through its national accreditation scheme for fusion-welding inspectors, filtering market access for training and examination providers. Stakeholders must weigh whether to build in-house compliance capabilities or deepen reliance on third-party specialists as federal carbon-transition mandates layer new process-safety requirements onto existing occupational frameworks.
Market Dynamics
Software-defined safety monitoring is compressing inspection cycles from quarterly site visits to continuous data streams, forcing traditional providers to restructure service contracts around recurring platform fees rather than episodic consulting engagements.
Growth Catalysts
- Alberta oil sands automation:Remote extraction operators mandate integrated gas detection networks that bundle hardware with predictive maintenance subscriptions.
- CSA Z1008 implementation:The Canadian Standards Association's psychological health and safety management standard drives enterprise demand for workplace mental health auditing services.
- Ontario manufacturing corridor density:Automotive and aerospace clusters sustain multi-year certification contracts with specialized training providers.
Market Restraints
- Certified inspector scarcity:The Canadian Welding Bureau's fusion-welding examiner pipeline constrains expansion of industrial training programs.
- Provincial regulatory fragmentation:Non-harmonized occupational health requirements between Quebec and western provinces inflate compliance costs for national operators.
- Equipment margin compression:Commoditized personal protective equipment faces pricing pressure from offshore manufacturing.
Strategic Opportunities
- Carbon transition mandates:Federal process-safety requirements for hydrogen handling and carbon capture infrastructure create new certification categories.
- Indigenous partnership protocols:Impact benefit agreements on northern resource projects require locally delivered safety training programs.
- Wearable-software convergence:Biometric monitoring platforms paired with cloud analytics enable outcome-based pricing models.
Industry Challenges
- Field technician recruitment:Remote site safety officers require dual certification in atmospheric testing and emergency response, narrowing the qualified labor pool.
- Legacy system integration:Paper-based incident reporting infrastructure at established industrial sites resists digitization without operational disruption.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Canada Safety Services Market |
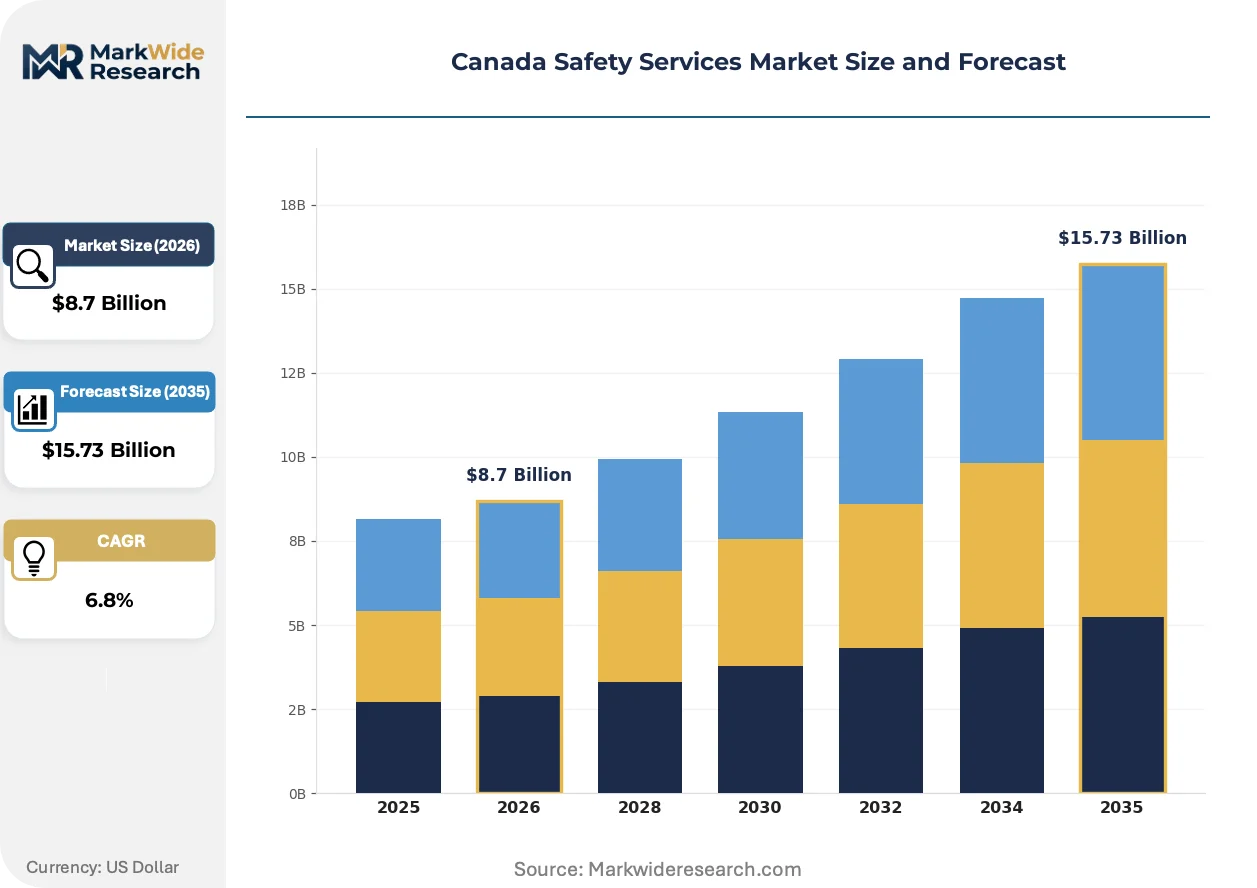
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Consulting, Training, Auditing, Compliance Industry Vertical: Construction, Manufacturing, Healthcare, Oil & Gas Technology: Wearables, Software Solutions, Safety Equipment, Monitoring Systems End User: Corporations, Small Businesses, Government, Non-Profits |
| Companies Covered | Fire-Pro Fire Protection Ltd, Bison Fire Protection Inc., Blackline Safety, Canadian Welding Bureau (CWB Group), Dynamic Rescue Systems, Hercules SLR, Canada Safety Equipment Ltd, Safeguard Industries, Beacon Lite Ltd, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Canada Safety Services Market Strategic Shifts
Real-time environmental sensing and automated compliance documentation are collapsing the traditional boundary between safety equipment vendors and managed service providers.
Cloud-connected biometric wearables are decentralizing hazard monitoring from centralized control rooms to individual worker devices. Oil sands operators and underground mining contractors deploy these units across dispersed crews. The shift compresses emergency response activation from minutes to seconds while fragmenting equipment procurement across multiple sensor suppliers.
Health Canada's updated Occupational Health and Safety regulations tighten exposure limit enforcement for silica and diesel particulate. Provincial ministries of labour now mandate digital incident reporting with standardized data fields. Construction and demolition segments face accelerated compliance timelines that favor providers with pre-configured reporting platforms.
Buyer consolidation among national resource operators concentrates procurement authority with centralized safety departments. Regional distributors lose direct site access as enterprise frameworks mandate approved vendor lists. This pattern concentrates most acutely in Saskatchewan's potash and uranium extraction complexes where two operators dominate capital expenditure planning.
Canada Safety Services Market Segmentation
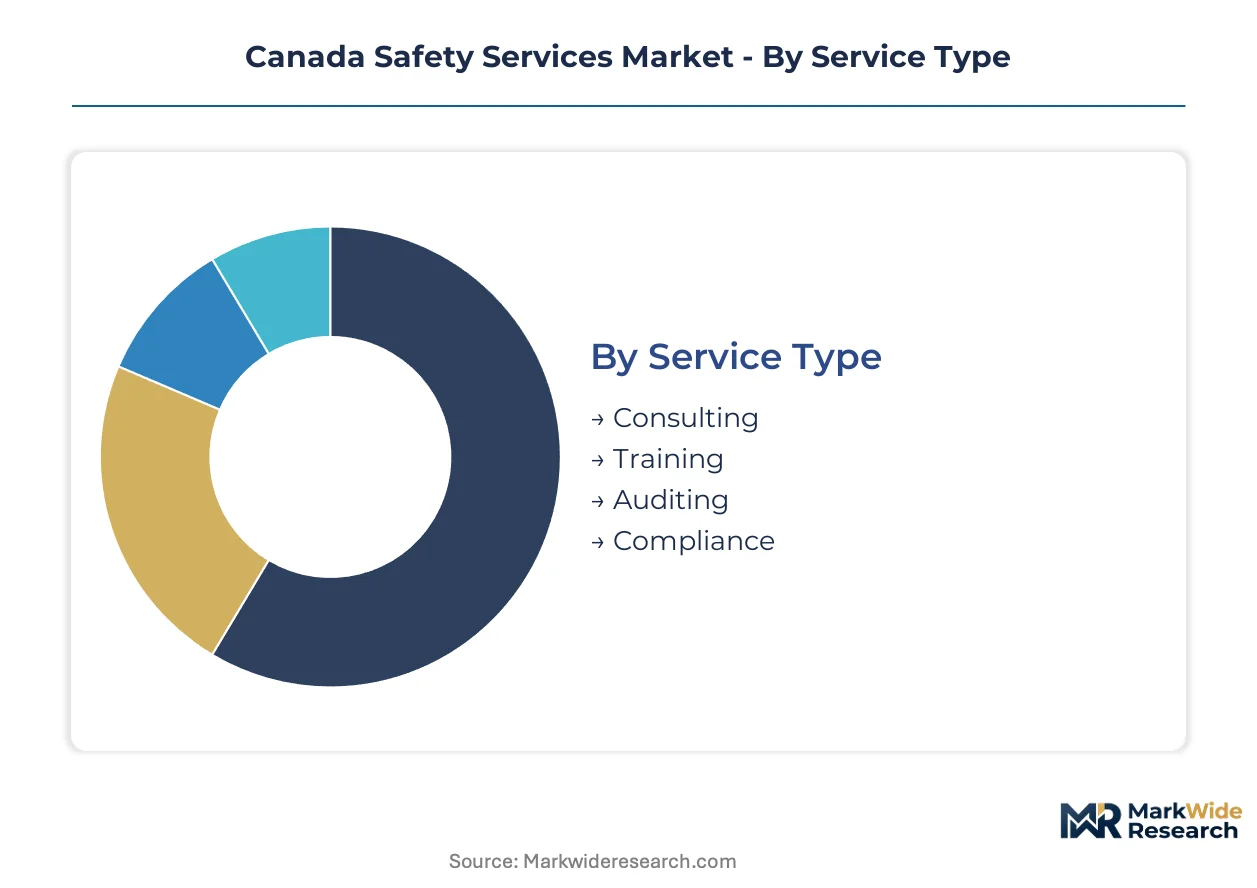
Canada's safety services market fragments across service delivery modes, regulatory complexity tiers, and technology adoption curves. Each segment carries distinct certification burdens from Health Canada, provincial labour ministries, and CSA standards that shape vendor qualification and procurement authority.
Service Type:
CSA Z1008 psychological health certification requirements fall heaviest on auditing and consulting segments, while training providers navigate Canadian Welding Bureau accreditation and provincial safety association endorsements.
- Consulting:Specialist advisory on regulatory interpretation, risk assessment methodology, and compliance gap remediation. Demand concentrates among Ontario automotive manufacturers facing harmonized federal-provincial reporting mandates. Price pressure from automated risk assessment tools compresses margins for routine engagements.
- Training:Certified instruction spanning fall-arrest techniques, atmospheric testing protocols, and emergency response activation. Alberta oil sands operators sustain multi-year contracts for remote site delivery. The Canadian Welding Bureau's examiner pipeline constrains program expansion.
- Auditing:Systematic verification of hazard controls, incident documentation, and corrective action closure against CSA and provincial standards. Quebec's distinct regulatory framework inflates compliance costs for national operators.
- Compliance:Ongoing management of regulatory filings, exposure monitoring, and equipment certification renewals. Federal carbon-transition mandates layer new process-safety requirements onto existing occupational frameworks.
Leading the category by volume: Training. Growing fastest: Compliance.
Industry Vertical:
Capital intensity and regulatory scrutiny vary sharply across verticals, with oil and gas commanding premium service tiers while construction faces commoditization pressure.
- Oil & Gas:Integrated gas detection networks, emergency response protocols, and predictive maintenance subscriptions across remote extraction sites. Alberta's oil sands operators mandate bundled hardware-service contracts. Federal process-safety requirements for hydrogen handling create new certification demand.
- Manufacturing:Worker certification programs, site auditing, and equipment specification across Ontario's automotive and aerospace corridors. Sustained investment from cluster density supports specialized training provider relationships.
- Construction:Fall-protection systems, atmospheric testing, and fire-code compliance verification. Health Canada's tightened silica and diesel particulate exposure limits accelerate compliance timelines.
- Healthcare:Workplace violence prevention, biological hazard controls, and psychological safety management. CSA Z1008 implementation drives enterprise demand for mental health auditing.
Dominating procurement spend: Oil & Gas. Expanding most quickly: Manufacturing.
Technology:
Revenue model displacement from equipment margin to recurring platform fees tracks technology category, with software-defined offerings capturing pricing power.
- Wearables:Cloud-connected biometric devices and environmental sensors deployed across dispersed crews. Oil sands and underground mining contractors compress emergency response activation from minutes to seconds. Outcome-based pricing models emerge from platform-data convergence.
- Software Solutions:Cloud analytics, automated compliance documentation, and predictive maintenance platforms. Provincial digital incident reporting mandates favor pre-configured platform providers.
- Safety Equipment:Personal protective equipment, fall-arrest systems, and respiratory protection. Offshore manufacturing pressure compresses margins on commoditized product lines.
- Monitoring Systems:Fixed gas detection networks, environmental sensing arrays, and centralized control infrastructure. Buyer consolidation among national resource operators concentrates procurement with centralized safety departments.
Highest margin capture: Wearables. Steepest expansion trajectory: Software Solutions.
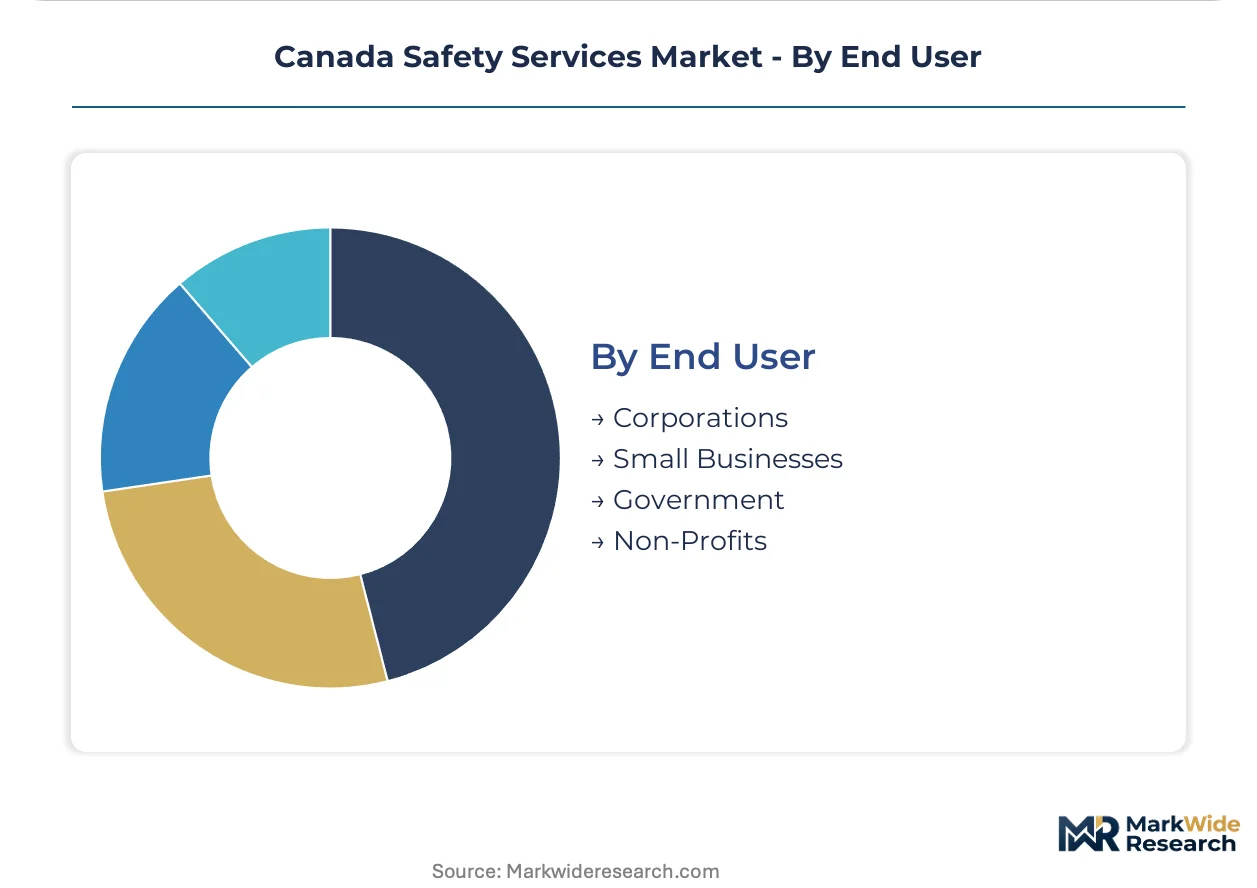
End User:
Procurement sophistication and contract scale diverge sharply by organizational size and sector, reshaping vendor go-to-market requirements.
- Corporations:Enterprise safety frameworks with approved vendor lists, multi-site master agreements, and outcome-based contracting. Saskatchewan's potash and uranium complexes concentrate authority with two dominant operators.
- Government:Municipal, provincial, and federal procurement of inspection services, training delivery, and emergency preparedness planning. Indigenous partnership protocols on northern resource projects require locally delivered programs.
- Small Businesses:Periodic compliance verification, equipment procurement, and certification renewal through regional distributor networks. Loss of direct site access as enterprise frameworks expand.
- Non-Profits:Volunteer safety training, event risk management, and limited-scope auditing engagements. Price sensitivity limits service tier access.
Commanding contract value: Corporations. Gaining share fastest: Government.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Ontario's manufacturing corridor anchors Canadian safety services demand through automotive and aerospace cluster density. Provincial harmonization efforts under the Canadian Federation of Labour framework reshape compliance thresholds across industrial zones.
Ontario
Windsor-Toronto automotive suppliers sustain multi-year worker certification contracts with specialized training providers. Health Canada coordinates with the Ministry of Labour to enforce tightened silica exposure limits in manufacturing facilities. Hamilton's steel corridor drives investment in atmospheric testing and fall-arrest system audits.
Alberta
Remote oil sands extraction operators mandate integrated gas detection networks with predictive maintenance subscriptions. Federal carbon-transition mandates layer new process-safety requirements for hydrogen handling onto existing occupational frameworks. Fort McMurray's bitumen processing complexes concentrate procurement authority with centralized safety departments.
Quebec
Aerospace manufacturing around Montreal sustains demand for Canadian Welding Bureau-accredited fusion-welding inspector programs. Distinct provincial regulatory frameworks inflate compliance costs for national operators seeking cross-border service delivery. Quebec City's shipbuilding sector drives specialized emergency response training procurement.
British Columbia
Coastal port operations and mining contractors deploy cloud-connected biometric wearables across dispersed crews. Provincial digital incident reporting mandates favor providers with pre-configured compliance platforms. Vancouver's construction sector faces accelerated timelines for fire-code verification and fall-protection system audits.
Saskatchewan
Potash and uranium extraction complexes concentrate safety procurement with two dominant resource operators. Indigenous partnership protocols on northern resource projects require locally delivered safety training programs. Regina's industrial fabrication sector sustains demand for rigging and fall-protection service networks.
Canada Safety Services Market Competitive Environment
Capital-heavy equipment fabricators compete with asset-light monitoring platform developers for service contract primacy. The vendor base clusters around three strategic tiers: integrated hardware-service bundlers, specialized certification trainers, and cloud-native analytics providers. Consolidation pressures intensify as enterprise buyers mandate approved vendor lists. Dominant competitive moves include geographic coverage expansion through regional distributor acquisition and technology convergence through wearable-software platform integration.
Within the integrated service tier, Blackline Safety and Hercules SLR exemplify contrasting scale strategies. Blackline Safety anchors recurring revenue through cloud-connected wearables deployed across remote resource sites. Hercules SLR sustains national coverage through its rigging and fall-protection service network. Fire-Pro Fire Protection Ltd occupies a position competing on response-time guarantees rather than equipment margins alone.
| Leading Market Players |
|---|
| Fire-Pro Fire Protection Ltd |
| Bison Fire Protection Inc. |
| Blackline Safety |
| Canadian Welding Bureau (CWB Group) |
| Dynamic Rescue Systems |
| Hercules SLR |
| Canada Safety Equipment Ltd |
| Safeguard Industries |
| Beacon Lite Ltd |
| Others |
Value Chain & Pricing Dynamics
Buyer consolidation among Alberta oil sands operators and Saskatchewan potash complexes concentrates procurement authority with centralized safety departments, forcing regional distributors to absorb margin compression or cede direct site access to approved vendor lists.
Pricing Analysis
Margin tightening in commoditized personal protective equipment traces to offshore manufacturing pressure from Asian suppliers, while subscription-based pricing for cloud-connected wearables captures premium positioning. Three-tier pricing structure across premium certified, standard compliant, and economy unbranded levels separates CSA-accredited providers from uncertified competitors. Cost-down pressure on equipment margins accelerates because enterprise buyers mandate outcome-based contracts bundling hardware with predictive maintenance. Small businesses exhibit highest price sensitivity, whereas oil sands operators prioritize response-time guarantees over unit cost.
Supply Chain Analysis
Certified inspector scarcity in Canada constrains training program expansion, while sensor component manufacturing concentrates in China, South Korea, and Taiwan. Raw material dependencies span lithium-ion cells for wearable power systems, MEMS sensors for environmental detection, and specialized textiles for fall-arrest harnesses. Single-source vulnerability in semiconductor sensor supply creates exposure to export control disruptions. Distribution runs through national service networks like Hercules SLR's rigging infrastructure and regional fire protection contractors maintaining local response capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Enterprise buyer consolidation and approved vendor list mandates are forcing weaker regional distributors out, creating acquisition opportunities for scaled players with national coverage.
For Market Incumbents: Cement recurring revenue streams through wearable-software platform integration, locking in long-term service contracts before emerging cloud-native entrants capture remote site deployments. Deepen backward integration into sensor calibration and repair capabilities to defend against hardware margin erosion from offshore suppliers. Prioritize CSA Z1008 psychological health certification investment as provincial mandates expand auditing requirements. For New Entrants and Emerging Players: Cloud-native biometric monitoring platforms offer a technology-first wedge into mid-market construction contractors underserved by legacy equipment vendors. Target Ontario manufacturing corridor density where automotive suppliers seek digitized compliance documentation without enterprise contract minimums. Lead with pre-configured provincial incident reporting platforms to bypass established distributor relationships. For Investors and Strategic Acquirers: The window for entry favors asset-light monitoring platform developers with proven recurring revenue traction over capital-heavy equipment fabricators facing margin compression. Long-term viability hinges on software-defined service models displacing episodic consulting engagements. Watch for federal carbon-transition mandate acceleration as inflection signal for hydrogen handling certification demand.| Strategic Initiative | Industry Significance |
|---|---|
| Wearable-Platform Integration | Blackline Safety's cloud-connected devices anchor recurring revenue across remote Alberta oil sands sites. |
| CSA Z1008 Certification Investment | Psychological health auditing capabilities capture enterprise demand as provincial mandates tighten. |
| Regional Distributor Acquisition | Hercules SLR's national rigging network demonstrates coverage expansion through targeted buyouts. |
| Indigenous Partnership Protocols | Locally delivered training programs unlock northern Saskatchewan potash and uranium project access. |
| Predictive Maintenance Subscription | Gas detection networks bundled with service contracts displace episodic equipment procurement. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs, combined with primary interviews across safety officers at Alberta oil sands operators, training directors at Canadian Welding Bureau-accredited facilities, procurement leads at Ontario automotive manufacturers, and compliance managers at provincial labour ministries. Health Canada exposure limit documentation, CSA standards publications, provincial incident reporting databases, and federal carbon-transition policy records supplied validation layers. Bottom-up service provider revenue estimates and top-down industry spend allocations underwent iterative triangulation.
Data-stream reconciliation across service type, industry vertical, technology category, and end user size segments shaped the analytical framework throughout the projection horizon. CAGRs derived from historical trajectory analysis, regulatory mandate timing, and technology substitution curves. Workforce certification pipeline constraints, buyer consolidation patterns, and software adoption S-curves informed segment-specific growth assumptions.
Forecast precision tightens around the base case; tail outcomes carry wider variance under accelerated federal carbon-transition mandates or prolonged provincial regulatory fragmentation. Projections reflect assumptions regarding CSA Z1008 adoption velocity, wearable price-performance improvement, and inspector training pipeline expansion. Material deviation in Indigenous partnership protocol enforcement or hydrogen infrastructure deployment timelines warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Workplace Safety
Industrial Protective Footwear Market
Workplace Safety
Construction Worker Safety Market
Workplace Safety
Machine Safety Market
Workplace Safety
Industrial Safety Gloves Market
Workplace Safety
Workplace Safety Market
Workplace Safety
Safety Helmets Market
Workplace Safety
Industrial Eye Protection Market
Workplace Safety
Industrial Head Protection Market
Workplace Safety
Safety Vest Market
Workplace Safety
Global Industrial Safety Footwear Market
Workplace Safety
Industrial and Workplace Safety Market
Workplace Safety
Safety Glasses Market
Workplace Safety
Industrial Safety Market
Workplace Safety
Middle East Industrial Protective Footwear Market
Workplace Safety
Industrial Safety Mats Market
Workplace Safety
Industrial Hand Protection Gloves Market