
 Industrial Safety Gloves Market | 2026-2036
Industrial Safety Gloves Market Size, Share, and Industry Trends Forecast 2026-2036
Industrial Safety Gloves Market Analysis
Malaysia's glove manufacturing corridor is rewriting regional supply dynamics for industrial hand protection. Hartalega leverages automated production lines to sustain cost leadership in nitrile output. Ansell dominates European distribution through specialized chemical-resistant portfolios. Top Glove Corporation anchors volume capacity serving bulk procurement contracts across North American manufacturing.
Industrial safety gloves are engineered hand-protection equipment manufactured from materials including nitrile, latex, polyurethane, and leather, designed to withstand mechanical hazards, chemical permeation, and thermal risks in occupational environments. Nitrile formulations deliver superior puncture resistance and latex-free compatibility for chemical processing and oil field operations. Leather and polyurethane segments occupy mature positions in construction and warehousing applications where abrasion protection and dexterity balance cost sensitivity. Certification tiers under ANSI and EN388 standards stratify margin pools, with premium cut-level ratings commanding pricing premiums in heavy manufacturing.
OSHA mandates govern minimum hand-protection requirements across US industrial workplaces, while EN388 mechanical-risk standards enforced by EU national regulators dictate product compliance for European market access. ISO certification frameworks support cross-border quality recognition, reducing retesting burdens for manufacturers serving multiple jurisdictions. ASTM thermal and chemical-resistance protocols further segment product positioning in specialized oil and gas and chemical processing environments. Stakeholders must monitor evolving cut-level thresholds and emerging bio-based material certifications as procurement criteria tighten across regulated industries.
Market Dynamics
EN388 mechanical-risk standard enforcement is compressing product lifecycles as European regulators tighten cut-level certification thresholds, forcing manufacturers to accelerate R&D cycles and retire legacy glove formulations faster than replacement demand alone would dictate.
Growth Catalysts
- Stricter EN388 Enforcement:EU national regulators are mandating higher cut-resistance ratings for metal fabrication and glass handling operations, creating immediate replacement cycles for non-compliant inventory.
- Nitrile Formulation Advances:Enhanced puncture-resistant polymer blends are displacing natural latex in chemical processing plants due to superior chemical permeation resistance and elimination of Type I hypersensitivity risks.
- Malaysia Capacity Expansion:Automated production corridors near Kuala Lumpur and Penang are scaling nitrile output to serve bulk procurement contracts from North American oil field operators and European automotive manufacturers.
Market Restraints
- Butadiene Price Volatility:Nitrile glove production faces margin compression from fluctuating synthetic rubber feedstock costs tied to petrochemical refining cycles.
- Single-Geography Supply Concentration:Overreliance on Malaysian manufacturing corridors exposes buyers to concentrated geopolitical and logistics disruption risks.
- Technical Limitation in Dexterity:Higher cut-level ratings under ANSI/ISEA 105 and EN388 standards inherently reduce tactile sensitivity, limiting adoption in precision electronics assembly.
Strategic Opportunities
- Underpenetrated Indian Manufacturing:Domestic industrial safety equipment penetration remains below Western benchmarks as BIS certification adoption accelerates in Maharashtra and Gujarat chemical clusters.
- Smart Glove Convergence:Integration of force-sensor arrays with cut-resistant shells enables real-time ergonomic monitoring for repetitive strain injury prevention in warehousing operations.
- US IRA Domestic Content Incentives:Clean energy manufacturing tax credits are stimulating glove demand for solar panel and battery cell production facilities requiring chemical and thermal hand protection.
Industry Challenges
- Certification Timeline Compression:Accelerated EN388:2016+A1:2018 transition deadlines are forcing manufacturers to complete ISO 17025 laboratory testing and Notified Body submissions under compressed schedules.
- Specialized Polymer Chemistry Talent Scarcity:Formulation expertise for nitrile-nitrile blend optimization and additive compatibility testing commands premium compensation in Malaysia and Thailand manufacturing hubs.
- Legacy ERP Integration Friction:Lot-level traceability requirements for PPE compliance documentation are straining inventory management systems at mid-tier distributors serving construction and utilities sectors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Industrial Safety Gloves Market |
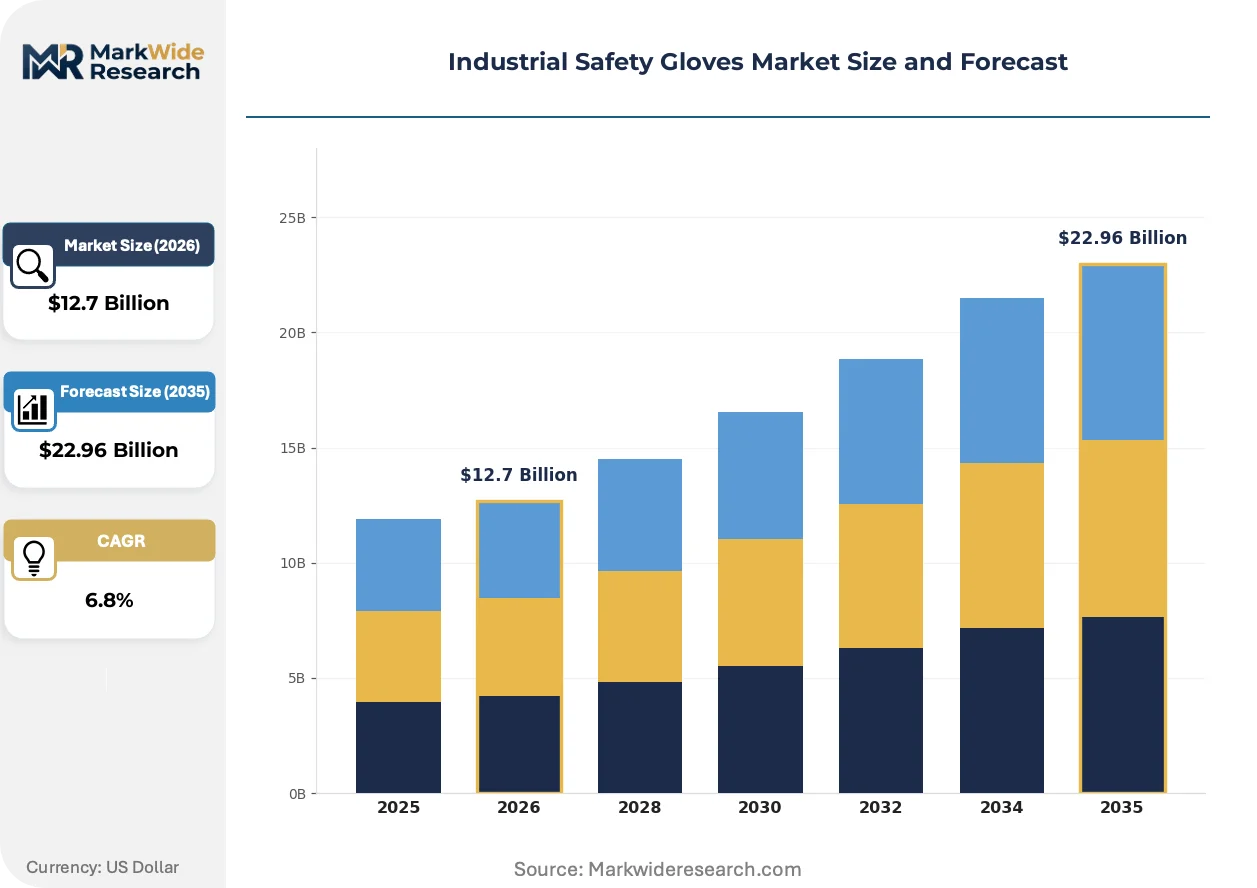
| Market Size in 2026 | $12.7 Billion |
| Market Size in 2035 | $22.96 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material: Leather, Latex, Nitrile, Polyurethane Application: Construction, Manufacturing, Oil & Gas, Warehousing Fit Type: Disposable, Fitted, Standard, Loose Certification: ANSI, EN388, ISO, ASTM |
| Companies Covered | Hartalega, Top Glove Corporation, Ansell, 3M, Honeywell International, MCR Safety, Kossan, Sri Trang, Supermax, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Industrial Safety Gloves Market Emerging Trajectories
Active material science breakthroughs and regulatory threshold adjustments are simultaneously elevating performance benchmarks and compressing acceptable product lifecycles across industrial hand protection categories.
Engineered yarn technologies incorporating high-performance polyethylene fibers are rendering obsolete traditional leather-palm gloves in heavy metal fabrication environments. German automotive stamping plants and Korean shipbuilding yards are adopting these cut-level 5 rated shells at accelerated replacement intervals. The shift is compressing margin pools for tannery-dependent suppliers while concentrating volume with synthetic fiber specialists.
REACH Annex XVII restrictions on chromium VI compounds in leather tanning are eliminating a cost-competitive processing pathway for European glove manufacturers. The regulation forces reformulation toward vegetable-tanned or synthetic alternatives with higher unit economics. Italian and Portuguese leather-glove producers are absorbing certification retesting costs while repositioning toward premium heritage positioning.
Direct-procurement platforms connecting safety managers with certified manufacturers are disintermediating traditional industrial distribution channels. Bulk buyers in Texas petrochemical complexes and Rotterdam refining clusters are negotiating frame contracts with Malaysian producers through digital tendering systems. The model eliminates distributor markup layers while transferring inventory carrying obligations to end-users with sophisticated demand forecasting capabilities.
Industrial Safety Gloves Market Segmentation
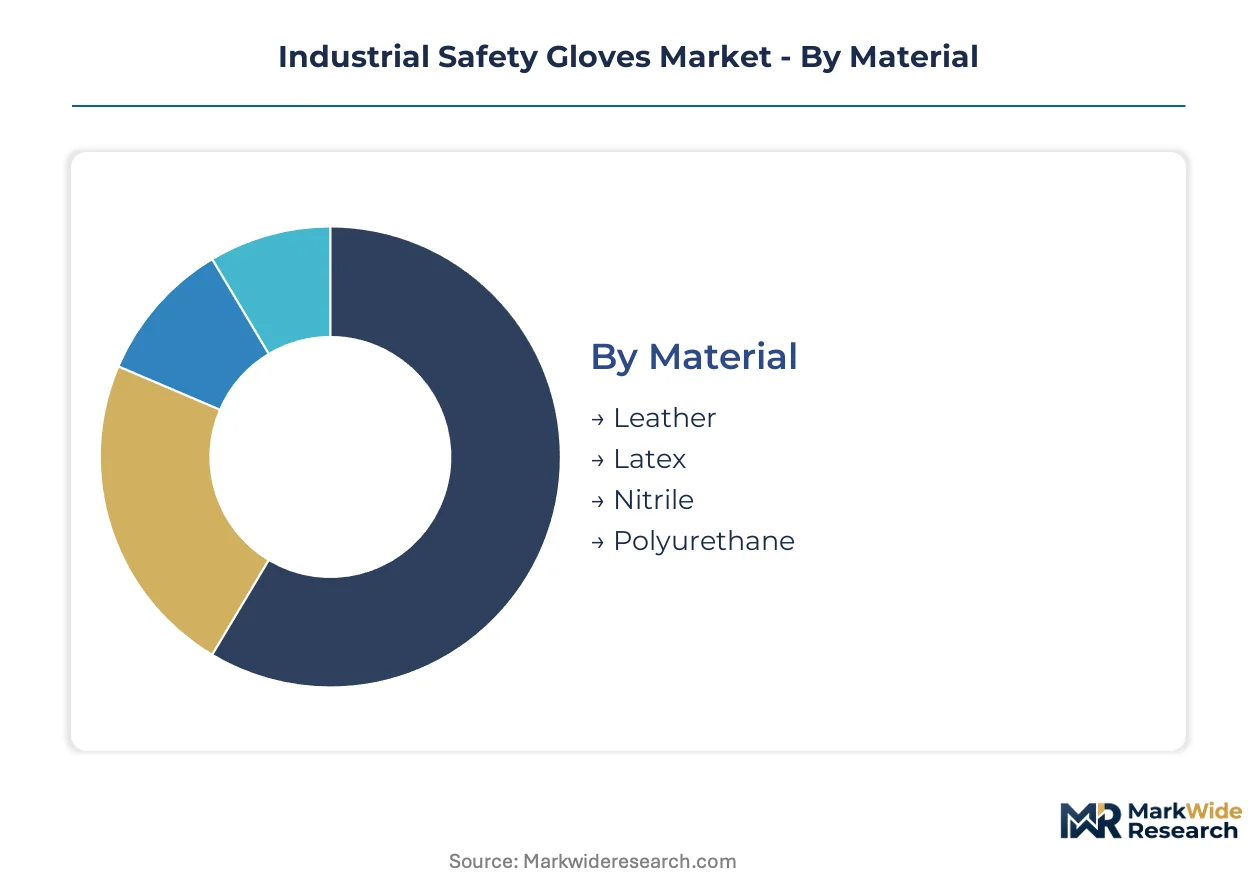
Industrial safety gloves segment across material chemistry, occupational risk profiles, ergonomic specifications, and compliance tiers. Procurement teams weight cut-resistance ratings against dexterity requirements while distributors manage certification documentation for cross-border shipments.
Material:
After-sales service intensity varies sharply by material chemistry, with nitrile formulations requiring technical support for chemical compatibility queries while leather segments rely on replacement scheduling rather than specification consulting.
- Nitrile:Synthetic rubber polymer delivering puncture resistance and chemical impermeability without latex allergen risks. Chemical processing plants in Germany and oil field operators in Texas specify nitrile for aromatic solvent handling where permeation breakthrough time determines worker safety.
- Leather:Tanned hide construction offering abrasion resistance and thermal protection in heavy fabrication environments. German automotive stamping operations and Korean shipbuilding yards specify leather-palm designs for metal handling where cut hazards coexist with heat exposure from welding spatter.
- Latex:Natural rubber compound providing elasticity and tactile sensitivity for precision assembly tasks. Electronics manufacturers in Malaysia specify latex for cleanroom component handling where electrostatic discharge control and fine motor control outweigh chemical exposure risks.
- Polyurethane:Thermoplastic coating applied to knit liners for grip optimization in warehousing and logistics operations. Distribution centers in Rotterdam and Hamburg specify polyurethane-dipped palms for order picking where carton abrasion and barcode scanner dexterity balance cost thresholds.
Nitrile holds the largest share; momentum sits with polyurethane as e-commerce fulfillment scales automated warehouse construction.
Application:
Volume concentration tracks industrial output geography, with manufacturing and construction commanding bulk procurement while oil and gas segments prioritize technical specification compliance over unit cost.
- Manufacturing:Metal fabrication, assembly line, and machinery maintenance operations requiring mechanical hazard protection. Automotive plants in Stuttgart and battery cell facilities in Michigan specify cut-resistant shells for press brake operations and electrode handling where EN388 ratings and ANSI cut levels stratify supplier selection.
- Construction:Masonry, carpentry, and heavy equipment operation demanding abrasion resistance and impact protection. Infrastructure projects in Mumbai and Dubai specify reinforced palm designs for rebar handling and concrete forming where glove replacement cycles align with project phase completion.
- Oil & Gas:Upstream drilling, downstream refining, and pipeline maintenance requiring chemical and thermal resistance. Petrochemical complexes in Texas and refining clusters in Rotterdam specify nitrile-neoprene blends for aromatic hydrocarbon exposure where ASTM permeation testing validates breakthrough thresholds.
- Warehousing:Order fulfillment, pallet handling, and cold storage operations balancing grip performance with thermal insulation. Automated distribution centers in Pennsylvania and temperature-controlled logistics hubs in the Netherlands specify polyurethane-coated knit shells for scanner compatibility and freezer-grade liner combinations.
Manufacturing holds the largest share; warehousing gains share fastest as fulfillment center automation accelerates glove consumption per worker hour.
Fit Type:
Margin structure inverts across fit categories, with fitted and disposable formats commanding premium pricing for contamination control while standard and loose fits compete on volume efficiency in general labor pools.
- Fitted:Ergonomic sizing with anatomical patterning for precision tasks requiring tactile feedback. Electronics assembly operations in Penang and semiconductor fabrication in Dresden specify fitted nitrile shells for die handling and wafer transport where particle shedding and grip security override replacement cost.
- Disposable:Single-use construction for contamination-sensitive environments and chemical splash protection. Pharmaceutical manufacturing in Basel and food processing in Chicago specify disposable nitrile for batch changeover protocols where cross-contamination liability exceeds material cost.
- Standard:Universal sizing for general industrial labor without specialized dexterity requirements. Construction crews in São Paulo and maintenance teams in Jakarta specify standard-fit leather and cotton blends for tool handling and material transport where inventory simplification reduces procurement overhead.
- Loose:Oversized construction for thermal layering and quick donning in emergency response scenarios. Cold storage operations in Calgary and foundry work in Birmingham specify loose-fit insulated designs for liner accommodation and rapid exchange where comfort tolerance permits reduced precision.
Standard fit holds the largest share; fitted formats climb the fastest as precision manufacturing automation demands ergonomic hand protection integration.
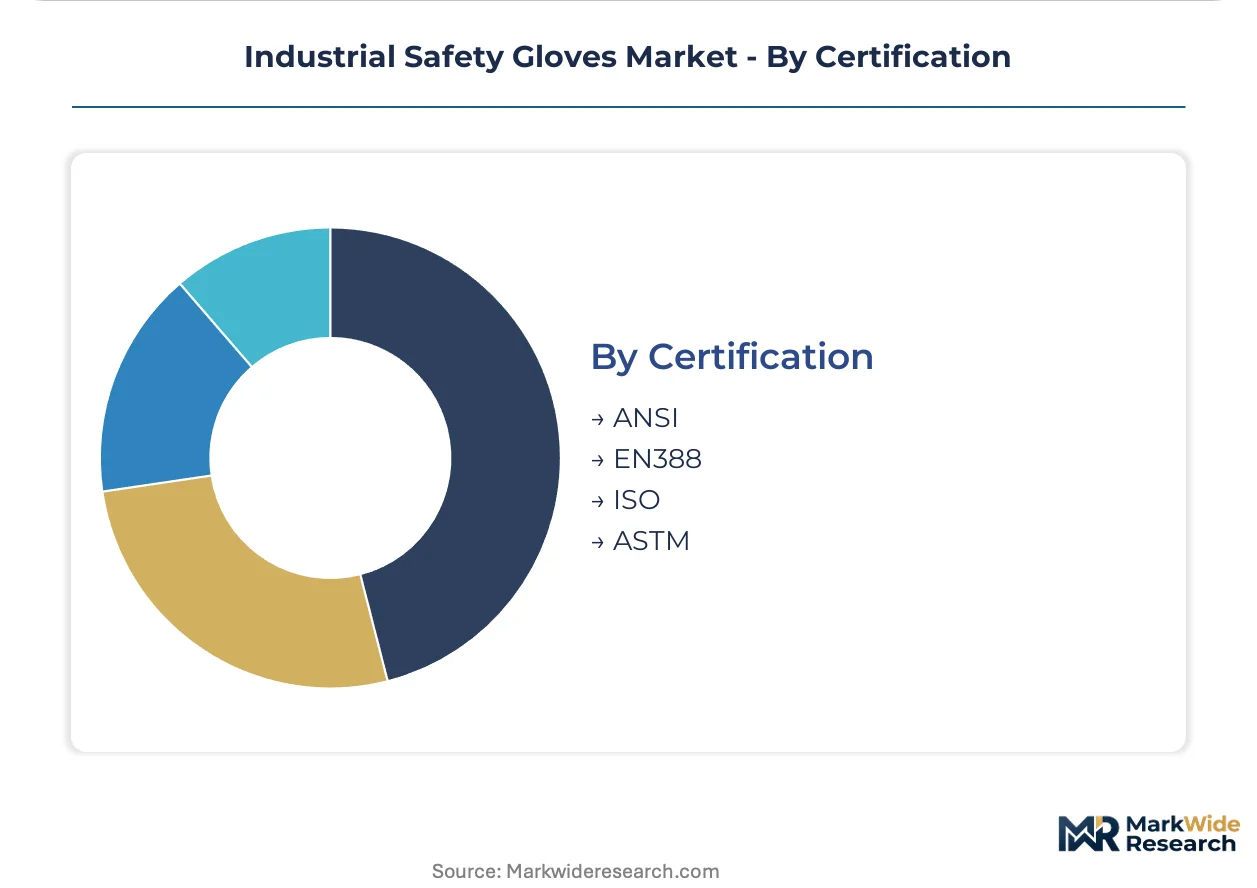
Certification:
Certification tier functions as pricing architecture, with EN388 and ANSI ratings enabling premium positioning while ISO and ASTM frameworks support cross-border quality recognition without mechanical performance differentiation.
- EN388:European mechanical risk standard governing abrasion, cut, tear, and puncture resistance ratings. Metal fabrication shops in Dortmund and glass handling operations in Venice specify EN388:2016+A1:2018 cut level 5 gloves for stamping press and tempered glass panel installation where regulatory enforcement mandates documented compliance.
- ANSI:American National Standards Institute hand protection classification for US market access. Oil field service companies in Houston and chemical processors in Louisiana specify ANSI/ISEA 105 A9 cut levels for downhole tool handling and acidizing operations where OSHA inspection protocols reference standardized ratings.
- ISO:International Organization for Standardization frameworks enabling mutual recognition across jurisdictions. Malaysian manufacturers serving multiple export markets pursue ISO 9001 quality management and ISO 17025 laboratory accreditation to reduce redundant testing for EU, US, and Japanese buyers.
- ASTM:American Society for Testing and Materials protocols for chemical permeation and thermal resistance specialization. Firefighting equipment suppliers and chemical emergency response teams specify ASTM F739 and F1060 ratings for hazardous materials handling where breakthrough time and contact temperature thresholds determine specification.
EN388 holds the largest share; ANSI gains share fastest as US manufacturing reshoring intensifies domestic certification requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Malaysian manufacturing corridors concentrate nitrile glove capacity for export markets, while demand dispersion across industrialized economies shapes procurement patterns. German chemical processors and US oil field operators anchor import volumes. Regulatory divergence between EU EN388 enforcement and US OSHA mandates creates certification complexity for cross-border suppliers.
United States
Petrochemical complexes in Texas and Louisiana drive nitrile glove consumption for aromatic hydrocarbon handling. OSHA mandates govern minimum hand-protection requirements across industrial workplaces. Houston-based oil field service companies specify ANSI/ISEA 105 A9 cut levels for downhole operations where inspection protocols reference standardized ratings.
Germany
Automotive stamping plants in Stuttgart and Dortmund metal fabrication shops accelerate replacement cycles for cut-level 5 rated gloves. EN388:2016+A1:2018 enforcement by national regulators mandates documented compliance for market access. Bavarian chemical processors expand procurement of cut-resistant nitrile formulations under stricter mechanical-risk standards.
Malaysia
Automated production corridors near Kuala Lumpur and Penang scale nitrile output for North American and European contracts. The country's manufacturing base serves bulk procurement from oil field operators and automotive manufacturers. Penang-based facilities leverage cost leadership in synthetic rubber polymer output to capture export market share.
China
Manufacturing hubs in the Yangtze River Delta and Pearl River Delta generate domestic demand for precision assembly gloves. GB standards and emerging regulatory frameworks shape local certification requirements. Shenzhen electronics manufacturers specify fitted nitrile shells for cleanroom component handling where electrostatic discharge control matters.
India
Chemical clusters in Maharashtra and Gujarat accelerate BIS certification adoption for industrial safety equipment. The country's national standards body tightens compliance thresholds for domestic manufacturing penetration. Mumbai infrastructure projects and Ahmedabad textile processors drive replacement demand for abrasion-resistant leather and cotton blends.
Industrial Safety Gloves Market Vendor Landscape
Volume-driven manufacturers and specification-led specialists split the market into distinct competitive arenas. Malaysian producers anchor the supply base through automated nitrile output serving bulk procurement contracts. European and North American incumbents dominate premium tiers through certification depth and distribution relationships. Competitive moves concentrate on capacity expansion in Southeast Asian corridors and portfolio diversification toward smart glove convergence.
Within the Malaysian volume tier, Hartalega Holdings Berhad and Top Glove Corporation exemplify scale-driven positioning through automated production infrastructure. Ansell Limited occupies a specification-led position representing premium-tier penetration in European chemical-resistant portfolios. These three anchors illustrate the structural divide between cost-optimized export manufacturing and compliance-intensive regional distribution.
| Leading Market Players |
|---|
| Hartalega |
| Top Glove Corporation |
| Ansell |
| 3M |
| Honeywell International |
| MCR Safety |
| Kossan |
| Sri Trang |
| Supermax |
| Others |
Supply Flow & Price Mechanics
Malaysian nitrile polymer output concentration feeds directly into margin capture at the automated manufacturing tier, while downstream pricing power fragments across certification-intensive European distributors and volume-negotiating North American bulk buyers.
Pricing Analysis
EN388:2016+A1:2018 dictates the pricing tier structure across European market access, with cut-level 5 certifications commanding premium positioning against unrated commodity alternatives. Three-tier pricing structure across premium certified, standard compliant, and economy unrated levels segments buyer archetypes, with automotive stamping plants in Stuttgart and Dortmund absorbing premium tiers while construction crews in São Paulo prioritize volume efficiency. Cost compression in the economy tier is intensifying because REACH Annex XVII leather tanning restrictions force vegetable-tanned reformulation with higher unit economics. Chemical processors in Texas and Louisiana exhibit lowest price sensitivity due to ASTM permeation testing requirements, whereas warehousing operators in Rotterdam and Hamburg negotiate aggressively on polyurethane-dipped volume contracts.
Supply Chain Analysis
Butadiene synthetic rubber feedstock anchors upstream cost volatility, with Malaysian petrochemical corridors and Thai polymer refineries supplying nitrile monomer to glove manufacturing clusters. Raw material dependencies center on acrylonitrile, butadiene, and specialty coagulants for dipped glove production, while finished goods distribution runs through Rotterdam and Hamburg port complexes for European forwarding and Houston petrochemical channel partners for North American oil field supply. Single-geography manufacturing concentration in Penang and Kuala Lumpur corridors creates tariff exposure vulnerability as EU and US trade remedy investigations target Southeast Asian PPE imports. Direct-procurement platforms are disintermediating traditional industrial distributors, transferring inventory carrying obligations to end-users with sophisticated demand forecasting capabilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Engineered yarn technologies incorporating high-performance polyethylene fibers threaten legacy leather-palm glove incumbents, forcing established manufacturers to defend substitution risk through certification depth and formulation lock-in.
For Market Incumbents: Pre-empt polyethylene fiber displacement by accelerating EN388 cut-level 5 portfolio conversion and securing backward integration into nitrile polymer supply through Malaysian production corridor partnerships. Lock in automotive OEM frame contracts with embedded technical support services that commodity yarn suppliers cannot replicate. Defend against smart glove convergence threats by acquiring force-sensor array specialists before warehouse automation integrators consolidate the category.
For New Entrants and Emerging Players: Pursue BIS certification acceleration in Maharashtra and Gujarat chemical clusters where domestic industrial safety equipment penetration trails Western benchmarks. Target pharmaceutical manufacturing in Basel and Chicago with disposable nitrile batch changeover protocols where cross-contamination liability exceeds material cost sensitivity. Establish direct-procurement platform relationships with Texas petrochemical safety managers to bypass entrenched distributor markup layers.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with mid-tier Malaysian producers that automated production during pandemic-era capacity expansion but lack EN388 Notified Body relationships for European premium tier access. Five-to-ten year viability hinges on certification portfolio breadth rather than unit cost position alone. Monitor ASTM F739 and F1060 testing laboratory acquisition activity as signal for hazardous materials handling specialization interest.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion in Automated Nitrile Lines | Malaysian corridor investments capture North American oil field and European automotive contract volumes. |
| Backward Integration into Polymer Supply | Captive butadiene sourcing insulates margin compression from petrochemical refining cycle volatility. |
| Smart Glove Technology Convergence | Force-sensor integration with cut-resistant shells enables ergonomic monitoring for warehousing automation. |
| Long-term Supply Agreement with OEMs | Automotive frame contracts in Stuttgart and Dortmund anchor replacement cycle visibility. |
| Green Manufacturing Transition | REACH Annex XVII vegetable-tanned alternatives reposition European leather-glove producers toward premium heritage. |
Methodological Framework
Two parallel data streams informed the analysis: structured primary interviews with plant safety managers, procurement leads at downstream OEMs, distribution channel partners, and technical R&D directors; and secondary validation against customs/trade data, SEC 10-K filings, ACC/Cefic industry reports, and EN388 Notified Body certification databases. Bottom-up and top-down triangulation cross-validated volume estimates across material chemistry segments and application verticals.
Forecast inputs considered cut-level rating adoption curves, nitrile formulation substitution rates against natural latex, and warehousing automation penetration across the projection horizon. Segmentation dimensions modeled included material chemistry, occupational risk profile, ergonomic specification, and certification tier. CAGRs were derived from replacement cycle analysis tied to EN388 enforcement deadlines and OSHA inspection protocol evolution.
Sensitivities concentrate around butadiene price volatility, REACH regulatory expansion, and smart glove technology adoption curves. Quarterly review of EN388 Notified Body submission backlogs and Malaysian production corridor utilization rates is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Workplace Safety
Industrial Head Protection Market
Workplace Safety
Machine Safety Market
Workplace Safety
Industrial Eye Protection Market
Workplace Safety
Industrial and Workplace Safety Market
Workplace Safety
Industrial Safety Mats Market
Workplace Safety
Safety Glasses Market
Workplace Safety
Construction Worker Safety Market
Workplace Safety
Industrial Hand Protection Gloves Market
Workplace Safety
Safety Helmets Market
Workplace Safety
Industrial Safety Market
Workplace Safety
Safety Vest Market
Workplace Safety
Middle East Industrial Protective Footwear Market
Workplace Safety
Global Industrial Safety Footwear Market
Workplace Safety
Workplace Safety Market
Workplace Safety
Canada Safety Services Market
Workplace Safety
Industrial Protective Footwear Market