
 Machine Safety Market | 2026-2036
Machine Safety Market Size, Share, and Industry Trends Forecast 2026-2036
Machine Safety Market Intelligence
Certified safety engineering talent scarcity is redrawing competitive boundaries in industrial automation. Siemens AG leverages its TÜV-certified engineering workforce to anchor large-scale automotive safety deployments. Schneider Electric SE sustains channel dominance across European food processing facilities through certified integrator networks. Rockwell Automation, Inc. competes on programmable safety controller depth in North American metalworking plants.
Machine safety encompasses electromechanical and electronic systems designed to detect hazardous conditions and initiate protective responses, including safety-rated torque-off circuits achieving Category 4/PLe per ISO 13849-1. These systems primarily prevent operator injury during mechanical power transmission, robotic interaction, and automated material transfer cycles. Safety sensors and safety controllers together capture the dominant margin pool, with light curtains representing the fastest-growing product category as cobot density rises in packaging units. Electronic technology is displacing electromechanical architectures in new installations, though pneumatic safety valves retain installed-base dominance in legacy chemical processing facilities.
ISO 13849-1 and IEC 62061 shape functional safety design rules for machinery sold into the European Union, while OSHA 1910.147 governs hazardous energy control procedures across United States manufacturing sites. The EU Machinery Directive's 2023 revision tightens requirements for autonomous mobile machinery, forcing recertification investments. Stakeholders must monitor convergence between functional safety and cybersecurity standards as connected safety controllers become default architecture.
Market Dynamics
Electronic safety architectures are displacing electromechanical systems across new machine builds, compressing installation timelines and forcing recertification of legacy component supply chains. This technology transition concentrates margin capture among vendors with TÜV-certified engineering depth.
Growth Catalysts
- EU Machinery Directive 2023 revision:Mandatory recertification for autonomous mobile machinery creates immediate replacement demand for safety controllers and sensor arrays in German and Italian manufacturing clusters.
- Cobot density expansion:Collaborative robot deployments in packaging and electronics assembly require Category 4/PLe-rated light curtains and torque-limiting systems per ISO 13849-1.
- Stuttgart industrial cluster concentration:Automotive OEM safety procurement for automated welding lines generates premium system integration contracts with multi-year service attachments.
Market Restraints
- Semiconductor input volatility:Safety-rated microcontrollers and ASICs face allocation constraints from foundry capacity concentration in Taiwan, extending lead times for programmable safety modules.
- Electromechanical installed-base inertia:Pneumatic safety valves and relay-based interlocks in legacy chemical processing facilities resist electronic retrofit due to explosion-proof recertification costs.
- Functional safety-cybersecurity convergence friction:Connected safety controllers must satisfy both ISO 13849-1 and IEC 62443, doubling engineering validation cycles for new product introductions.
Strategic Opportunities
- Indian manufacturing automation:PLI scheme incentives for automotive and electronics production create first-mover advantage for safety system vendors establishing local certification partnerships with BIS.
- Safety-as-a-service models:Subscription-based safety controller monitoring and predictive maintenance contracts penetrate mid-tier metalworking shops previously priced out of premium system ownership.
- AI-enabled hazard prediction:Machine vision integration with safety PLCs enables pre-contact intervention, opening specification opportunities in high-speed robotic material handling.
Industry Challenges
- TÜV-certified safety engineer scarcity:Functional safety design and validation expertise concentrates in German and Swiss labor markets, constraining project scaling for system integrators.
- Legacy electromechanical integration complexity:Hybrid architectures combining electronic safety PLCs with pneumatic valve manifolds require custom engineering, eroding margin on brownfield retrofits.
- Multi-standard certification timeline compression:Simultaneous UL, CE, and CCC approvals for global machine exports extend time-to-revenue by 8-14 months for new safety product launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Machine Safety Market |
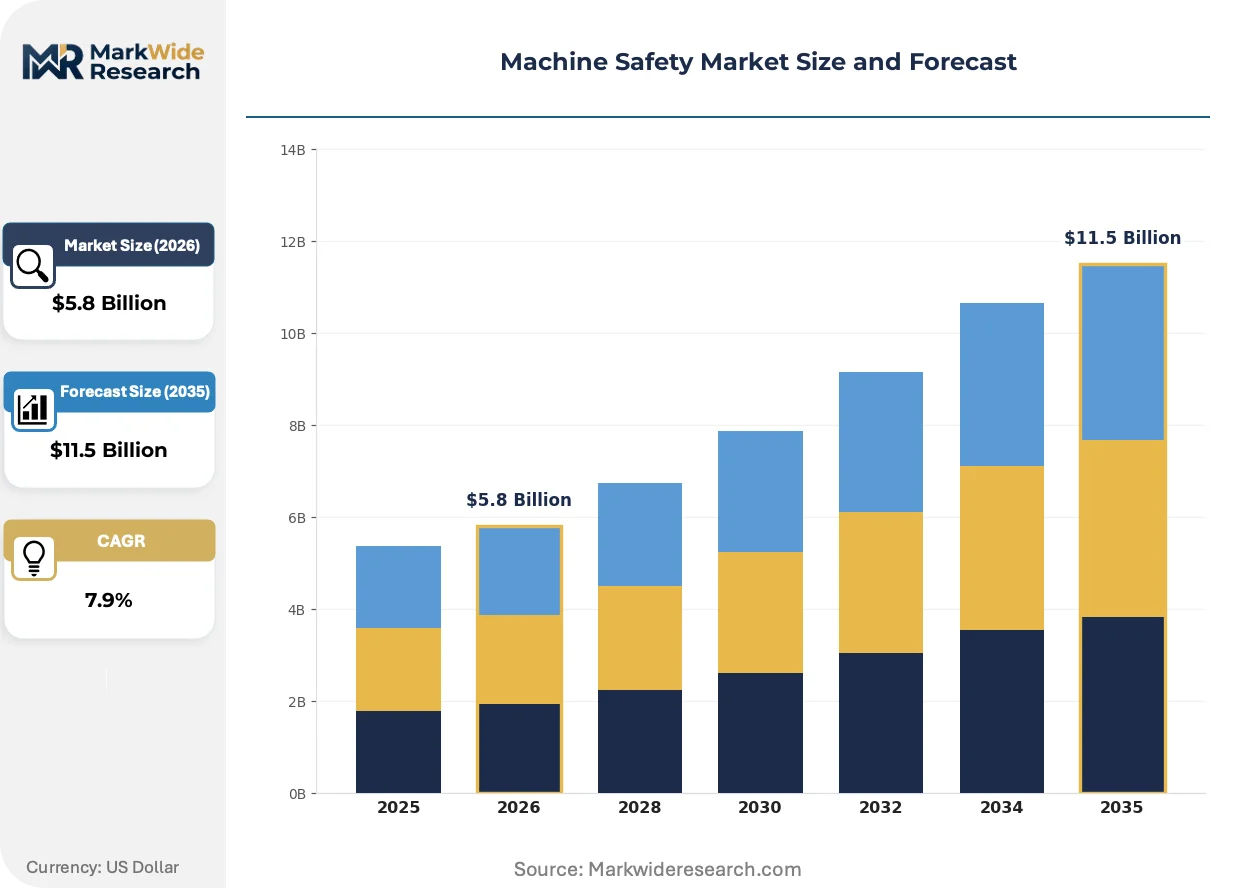
| Market Size in 2026 | $5.8 Billion |
| Market Size in 2035 | $11.5 Billion |
| CAGR (2026 – 2036) | 7.9% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Safety Sensors, Safety Switches, Safety Relays, Light Curtains, Safety Controllers, Emergency Stop Devices Technology: Electromechanical, Hydraulic, Pneumatic, Electronic, Programmable Logic Controllers, RFID Application: Manufacturing Plants, Material Handling, Packaging Units, Heavy Machinery, Textile Production, Metalworking End User Industry: Automotive OEMs, Food & Beverage Facilities, Chemical Processing, Construction Equipment, Aerospace Manufacturers |
| Companies Covered | Siemens AG, Schneider Electric SE, Rockwell Automation, Inc., ABB Ltd, Emerson Electric Co., KEYENCE CORPORATION, Omron Corporation, Honeywell International Inc., SICK AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Machine Safety Market Strategic Shifts & Innovations
Machine safety technology is fragmenting into two performance tiers: premium connected systems for new automation and cost-optimized electromechanical replacements for legacy maintenance. This bifurcation reshapes R&D allocation and channel strategy across the vendor base.
Programmable safety controllers with integrated safety I/O are bifurcating the market between high-performance Category 4 architectures and simplified Category 2 configurations. Automotive OEMs in Germany specify the former for new assembly lines, while metalworking job shops in the US Midwest adopt the latter for retrofit budgets. This split is compressing mid-range product margins and forcing vendors to choose certification depth over portfolio breadth.
The EU Machinery Directive's 2023 autonomous machinery amendments tighten risk assessment documentation for self-navigating industrial vehicles. Manufacturers must now demonstrate SIL 2 or PL d minimums for navigation safety functions, triggering redesign cycles for automated guided vehicle suppliers. German logistics operators are responding by consolidating procurement around integrators with notified body relationships.
Buyer preference is hardening toward pre-certified safety subsystems over component-level sourcing. Packaging machinery builders in Italy and the Netherlands now specify complete safety controller-light curtain-encoder bundles with unified documentation. This shift favors distributors with application engineering staff over catalog-only channels, concentrating aftermarket service attach rates among technical specialists.
Machine Safety Market Segmentation
Machine safety procurement patterns diverge sharply across product architectures, compliance tiers, and automation maturity levels. Understanding these segment boundaries clarifies where engineering validation investments concentrate and where cost-optimized replacements penetrate.
Product Type:
ISO 13849-1 Category ratings and SIL certifications create tiered specification thresholds that reshape vendor qualification requirements across each product class.
- Safety Sensors:Photoelectric and capacitive variants detect operator presence in robotic work envelopes, achieving Category 2 through Category 4 ratings depending on redundancy architecture. Automotive OEMs in Germany specify dual-channel inductive sensors for welding line position verification, driven by TÜV-certified integration mandates and multi-year service contract attachments.
- Safety Controllers:Programmable units with integrated safety I/O execute logic for complex multi-zone protection, supporting SIL 3/PLe through redundant processing cores. Demand clusters in Stuttgart automotive clusters where autonomous welding cells require coordinated light curtain, door interlock, and torque-limiting subsystems under unified certification documentation.
- Safety Switches:Interlock and limit configurations guard access points on guarded machinery, spanning hinge-mounted, slide-bolt, and non-contact RFID-coded variants.
- Safety Relays:Force-guided contact architectures provide electromechanical safety outputs for legacy machine retrofits where programmable controllers face explosive atmosphere constraints.
- Light Curtains:Active infrared arrays create invisible safety perimeters around cobot collaborative workspaces, with resolution grades from finger-detection to body-presence.
- Emergency Stop Devices:Mushroom-head pushbuttons and pull-wire switches initiate immediate machine shutdown through hardwired safety circuits.
Established volume favors safety sensors; emerging adoption favors safety controllers.
Technology:
Cost tiers separate legacy maintenance spending from new-build automation investment, with electronic architectures commanding premium pricing against electromechanical replacements.
- Electronic:Solid-state safety outputs and microprocessor-based diagnostics enable rapid fault detection and modular expansion. Packaging units in Italy specify electronic safety relays for high-speed form-fill-seal lines, pressured by EU Machinery Directive documentation requirements for autonomous material handling.
- Programmable Logic Controllers:Safety-rated PLCs integrate motion control, vision, and safety I/O on unified platforms, compressing panel space and wiring labor. Metalworking plants in the US Midwest adopt these for brownfield press retrofits, balancing Category 4 performance against limited maintenance staff technical depth.
- Electromechanical:Relay-based interlocks and contactor safety circuits persist in legacy installed bases where explosion-proof recertification costs resist electronic migration.
- Pneumatic:Safety valves and pressure-sensitive mats dominate chemical processing facilities with intrinsic safety requirements and pneumatic actuator heritage.
- Hydraulic:Pressure-relief and blocking valves protect personnel during high-force pressing and forming operations.
- RFID:Coded non-contact switches defeat tampering through unique identifier validation in high-security access applications.
Maintenance budgets anchor electromechanical and pneumatic; new automation specification climbs fastest for programmable logic controllers.
Application:
End-use operational tempo and hazard energy levels dictate safety system performance grade and response time requirements.
- Manufacturing Plants:Discrete assembly and process operations integrate multi-layer safety architectures from perimeter guarding to point-of-operation protection. German automotive OEMs deploy Category 4/PLe systems across Stuttgart and Munich clusters, compelled by OSHA lockout-tagout alignment for exported equipment and EU Machinery Directive recertification cycles.
- Packaging Units:High-speed robotic palletizing and case packing require rapid-response light curtains and collaborative robot torque limiting. Italian and Dutch machinery builders specify pre-certified safety subsystems with unified documentation, shifting procurement toward distributor channels with application engineering depth.
- Material Handling:Conveyor guarding and automated guided vehicle navigation demand SIL-rated position sensing and zone control.
- Heavy Machinery:Mining and construction equipment safety interlocks must survive vibration, contamination, and extreme temperature cycling.
- Metalworking:Mechanical power press safeguarding combines clutch/brake monitoring with two-hand control and point-of-operation devices.
- Textile Production:High-speed spinning and weaving machinery requires sensitive presence-sensing for thread break intervention and maintenance access.
Installed base concentration sits with manufacturing plants; steepest expansion trajectory belongs to packaging units.
End User Industry:
Customer technical sophistication and regulatory exposure determine whether procurement favors component sourcing or integrated subsystem bundles.
- Automotive OEMs:Final assembly and powertrain operations specify enterprise-wide safety platforms with centralized diagnostics and predictive maintenance integration. German manufacturers anchor premium safety system procurement, leveraging TÜV-certified engineering partnerships for automated welding and paint line deployments with multi-year service attachments.
- Food & Beverage Facilities:Washdown-rated safety components and hygienic design priorities dominate specification, with Schneider Electric channel networks sustaining European market position through certified integrator relationships.
- Chemical Processing:Explosion-proof and intrinsically safe architectures resist electronic migration due to recertification cost barriers and pneumatic valve installed base inertia.
- Construction Equipment:Functional safety for autonomous and semi-autonomous machine control follows ISO 25119 and emerging EU machinery requirements for mobile robotics.
- Aerospace Manufacturers:High-reliability safety systems support composite layup, automated drilling, and large-part handling with extensive documentation and traceability mandates.
Procurement scale concentrates in automotive OEMs; specification flexibility expands fastest in food and beverage facilities.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Machine safety procurement patterns diverge sharply by geography. German automotive OEMs specify Category 4/PLe architectures for new automation, while US metalworking shops prioritize cost-optimized retrofits and Indian manufacturers build first-generation safety infrastructure under PLI incentives.
United States
OSHA 1910.147 lockout-tagout enforcement drives replacement demand across Midwest metalworking plants. The Department of Labor's injury reduction mandates pressure smaller fabricators toward electronic safety relays. Detroit-area automotive stamping facilities anchor premium system integration contracts with multi-year predictive maintenance attachments.
Germany
TÜV-certified engineering scarcity concentrates project execution around Stuttgart and Munich industrial clusters. The EU Machinery Directive's 2023 autonomous machinery amendments force recertification investments for automated guided vehicle fleets. Bavarian automotive OEMs specify unified safety controller-light curtain bundles with centralized diagnostics platforms.
China
GB standards alignment with ISO 13849-1 accelerates domestic certification capacity building for export-oriented machinery builders. MIIT industrial upgrading programs subsidize safety system adoption in Yangtze River Delta electronics assembly. Suzhou and Shenzhen packaging machinery manufacturers specify pre-certified safety subsystems to shorten European market entry timelines.
India
PLI scheme incentives for automotive and electronics production create first-mover positioning for vendors establishing BIS certification partnerships. The Ministry of Heavy Industries' automation push drives safety controller demand in Tamil Nadu and Gujarat manufacturing corridors. Pune and Chennai industrial clusters witness initial cobot deployments requiring Category 2 minimum protection architectures.
Japan
METI's Society 5.0 initiative embeds functional safety requirements in next-generation manufacturing facility specifications. JIS standards harmonization with IEC 62061 streamlines validation for domestic robot integrators. Nagoya-area automotive suppliers upgrade legacy interlock systems to accommodate collaborative robot density expansion in compact assembly cells.
Machine Safety Market Key Industry Players
A small set of integrated leaders sits above a broader specialist tier in machine safety supply. Tier-one vendors combine TÜV-certified engineering depth with global distribution infrastructure, while mid-scale specialists concentrate on regional certification relationships or application-specific sensor architectures. Three archetypes dominate: diversified industrial automation conglomerates, safety-focused component specialists, and programmable controller-centric platform vendors. Competitive moves center on certified integrator network expansion and pre-certified subsystem bundling to capture specification influence at machinery builders.
Within the diversified industrial tier, Siemens AG and Schneider Electric SE exemplify platform-scale positioning. Rockwell Automation, Inc. occupies a distinct vector centered on programmable safety controller depth. These three anchors demonstrate how certification-intensive engineering resources concentrate competitive advantage in a market where validation documentation determines procurement outcomes.
| Leading Market Players |
|---|
| Siemens AG |
| Schneider Electric SE |
| Rockwell Automation, Inc. |
| ABB Ltd |
| Emerson Electric Co. |
| KEYENCE CORPORATION |
| Omron Corporation |
| Honeywell International Inc. |
| SICK AG |
| Others |
Cost & Logistics Intelligence
Electronic safety controller architectures displacing electromechanical relay systems are redrawing component sourcing maps from German engineering centers toward Taiwanese semiconductor foundries while compressing price premiums for legacy pneumatic safety valves.
Pricing Analysis
Long-term service contracts with multi-year predictive maintenance attachments dominate procurement for German automotive OEMs, while spot-market component sourcing persists for US Midwest metalworking retrofits. Three-tier pricing structure across Category 4/PLe premium systems, Category 2 mid-range controllers, and economy-grade electromechanical replacements separates specification tiers. Cost compression in mid-range programmable safety modules is intensifying because certified engineering scarcity concentrates integration margins with TÜV-qualified vendors. Automotive OEMs in Stuttgart show least price sensitivity due to compliance mandate rigidity, whereas Indian PLI-scheme manufacturers exhibit highest sensitivity as they build first-generation safety infrastructure.
Supply Chain Analysis
Extended lead times for safety-rated microcontrollers and ASICs now stretch eighteen to twenty-four months, forcing inventory pre-positioning among European system integrators. Manufacturing concentrates in Germany for engineered safety subsystems, Taiwan for semiconductor inputs, and China for electromechanical component production. Safety controller production draws from foundry-constrained wafers, TÜV-certified firmware validation, and explosion-proof housing alloys. Single-source vulnerability concentrates in Taiwanese foundry capacity for safety-rated processors. Distribution runs through technical distributors with application engineering staff rather than catalog-only channels, concentrating aftermarket service attach rates.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is shifting toward machinery builders demanding pre-certified safety subsystems with unified documentation, fragmenting procurement influence away from component specialists toward integrated platform vendors.
For Market Incumbents: Shield certification moats by deepening TÜV-certified engineering partnerships in Stuttgart and Munich clusters against emerging programmable safety controller specialists from Asia-Pacific. Prioritize backward integration into safety-rated semiconductor sourcing to mitigate foundry allocation constraints. Expand certified integrator networks to capture specification influence at Italian packaging machinery builders. For New Entrants and Emerging Players: BIS certification fast-track partnerships in Tamil Nadu and Gujarat manufacturing corridors open first-mover positioning under India's PLI scheme incentives. Target mid-tier US metalworking shops with subscription-based safety-as-a-service models previously priced out of premium system ownership. Penetrate Dutch and Italian packaging machinery segments through pre-certified safety subsystem bundles with unified documentation. For Investors and Strategic Acquirers: The market sits at a technology-transition phase that favors vendors with certified engineering depth over pure-play component manufacturers. Five-to-ten year viability hinges on convergence between functional safety and cybersecurity validation capabilities. Acquisition focus should center on programmable safety controller specialists with IEC 62443 cybersecurity certification progress. Monitor EU Machinery Directive enforcement intensity as inflection indicator for replacement demand velocity.| Strategic Initiative | Industry Significance |
|---|---|
| TÜV Certification Expansion | Deepens engineering moats for German automotive safety deployments with multi-year service attachments. |
| Pre-Certified Subsystem Bundling | Captures specification influence at Italian and Dutch packaging machinery builders consolidating procurement. |
| Foundry Partnership Diversification | Mitigates single-source vulnerability for safety-rated microcontrollers facing Taiwanese capacity constraints. |
| Safety-as-a-Service Launch | Penetrates mid-tier US metalworking shops through subscription-based predictive maintenance contracts. |
| Cybersecurity-Functional Safety Integration | Addresses IEC 62443 convergence requirements for connected safety controllers in EU markets. |
Research Approach
Two parallel data streams informed the analysis: structured primary interviews with safety system engineering directors, plant maintenance managers, OEM procurement teams, and TÜV certification specialists; and secondary validation against SEC filings, EU Machinery Directive implementation databases, OSHA enforcement records, and customs trade data. Bottom-up triangulation across component-level bill-of-materials analysis and top-down demand modeling from end-use industry automation investment patterns anchored volume estimates.
Across the projection horizon, the analytical framework modeled demand across product architecture tiers, compliance certification levels, end-use automation maturity stages, and regional regulatory enforcement intensity. CAGRs derived from segment-level growth rate synthesis rather than single-point extrapolation. Industry-specific forecast inputs incorporated EU Machinery Directive recertification cycle timing and collaborative robot deployment density trajectories in packaging applications.
Decision-makers should treat outputs as directional under assumptions of sustained OSHA and EU Machinery Directive enforcement intensity; material deviation in regulatory implementation timelines or semiconductor supply normalization would warrant model refresh. Specific risk factors include foundry capacity allocation shifts, autonomous machinery standard revisions, and functional safety-cybersecurity standard convergence friction. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Workplace Safety
Industrial Safety Mats Market
Workplace Safety
Industrial Hand Protection Gloves Market
Workplace Safety
Safety Glasses Market
Workplace Safety
Industrial Safety Gloves Market
Workplace Safety
Industrial Protective Footwear Market
Workplace Safety
Industrial Safety Market
Workplace Safety
Middle East Industrial Protective Footwear Market
Workplace Safety
Safety Helmets Market
Workplace Safety
Global Industrial Safety Footwear Market
Workplace Safety
Safety Vest Market
Workplace Safety
Industrial and Workplace Safety Market
Workplace Safety
Construction Worker Safety Market
Workplace Safety
Industrial Eye Protection Market
Workplace Safety
Industrial Head Protection Market
Workplace Safety
Workplace Safety Market
Workplace Safety
Canada Safety Services Market