
 Middle East Industrial Protective Footwear Market | 2026-2036
Middle East Industrial Protective Footwear Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East Industrial Protective Footwear Market Foresight
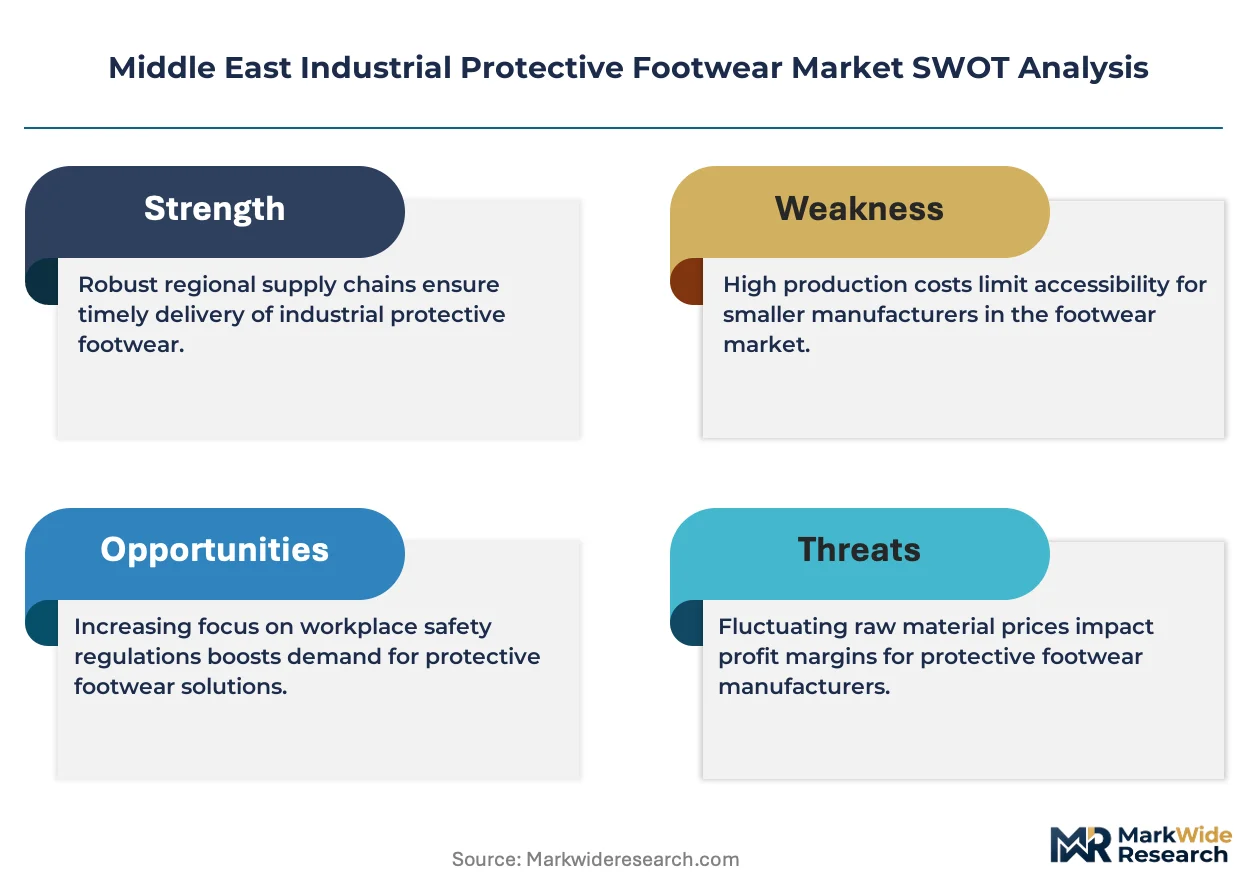
Specialized safety distributors across the Gulf Cooperation Council is fragmenting as direct-to-industrial procurement and e-procurement platforms gain share. Bata Corporation leverages its regional manufacturing footprint to sustain price competitiveness in bulk contracts. Honeywell International Inc. anchors its position through integrated personal protective equipment portfolios that bundle footwear with respiratory and eye protection. COFRA Holding AG differentiates via European-certified product lines that command premium positioning among multinational contractors operating in Qatar and Kuwait.
Middle East industrial protective footwear comprises engineered safety boots and specialized occupational shoes designed with reinforced toe caps, penetration-resistant midsoles, and chemical-resistant compounds to shield workers from impact, compression, and hazardous substance exposure in heavy industrial environments. Steel-toe boots incorporating alloy or composite safety toes rated to withstand significant impact energies dominate volume sales across construction and manufacturing end users, while chemical-resistant footwear commands margin premiums in oil and gas applications where hydrocarbon and solvent exposure risks are acute. Leather materials retain structural leadership in high-heat environments, though synthetic compounds are displacing traditional compositions in waterproof and lightweight segments favored by outdoor work crews across the region's extreme climate conditions.
Saudi Arabia's national occupational safety regulator and the UAE's standardization bodies enforce workplace protective equipment mandates that elevate compliance-driven replacement cycles for industrial footwear. The Gulf Standardization Organization's technical regulations for personal protective equipment, aligned with European EN ISO 20345 benchmarks, create a harmonized compliance ceiling that manufacturers must meet for market access across member states. Stakeholders should monitor evolving nationalization requirements for safety equipment sourcing and the pace at which local certification laboratories expand testing capacity to reduce import dependency for conformity assessments.
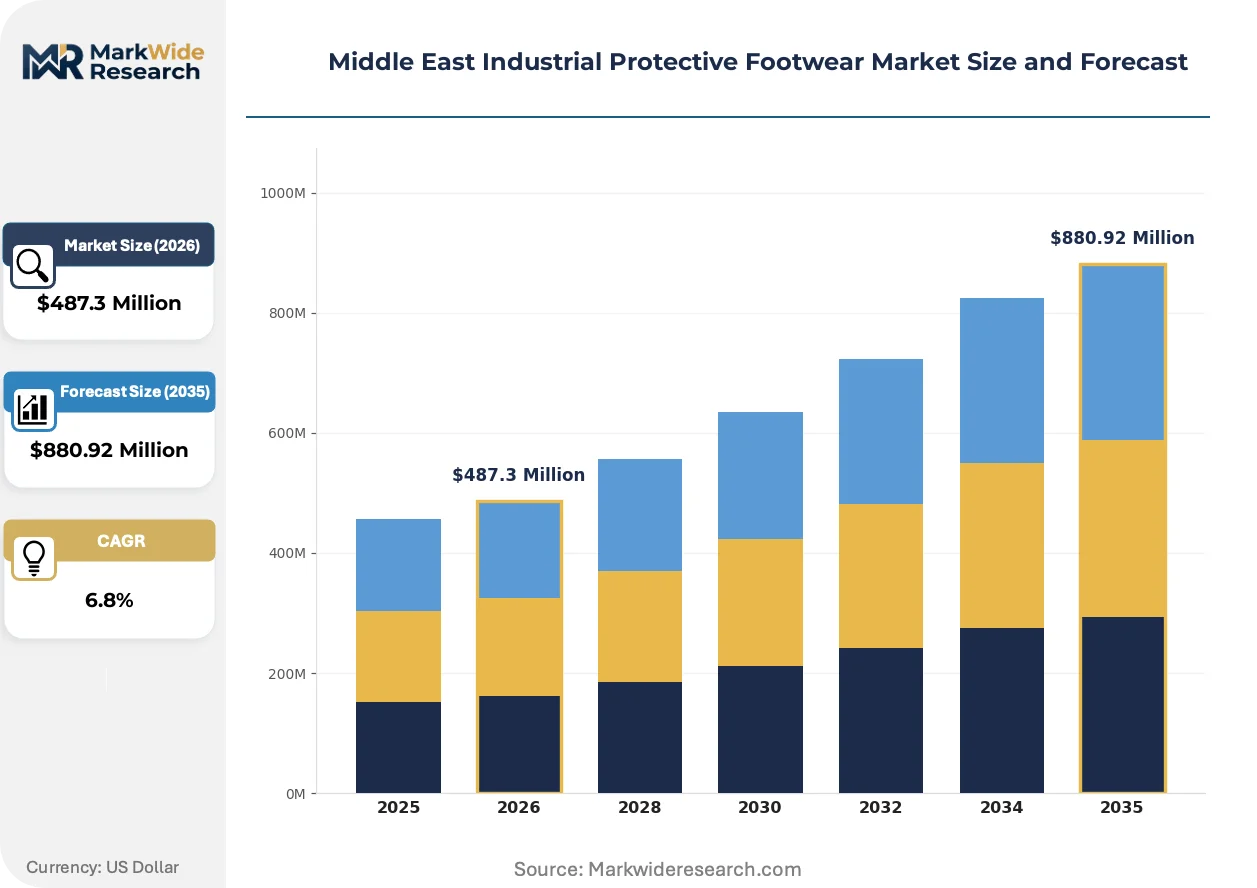
Market Dynamics
Stricter Gulf Standardization Organization mandates for personal protective equipment compliance are compressing replacement cycles and forcing distributors to consolidate certification capabilities ahead of harmonized EN ISO 20345 enforcement timelines.
Growth Catalysts
- Petrochemical cluster expansion:Saudi Arabia's Eastern Province industrial corridor generates concentrated bulk orders for chemical-resistant safety boots as refining and downstream complexes scale operations.
- SFDA and MOHAP alignment:Saudi Arabia's national occupational safety regulator and the UAE's standardization bodies enforce workplace protective equipment mandates that elevate compliance-driven procurement volumes.
- Composite safety toe adoption:Lightweight non-metallic toe caps rated to withstand impact energies are penetrating construction and logistics segments where metal detection protocols apply.
Market Restraints
- Leather input cost volatility:Full-grain hide prices fluctuate with livestock supply cycles and tanning capacity constraints, squeezing margin structures for premium boot manufacturers.
- Import dependency for conformity assessments:Limited local certification laboratory capacity across Gulf Cooperation Council states forces extended lead times for EN ISO 20345 testing and market access approvals.
- Synthetic rubber substitution in midsole compounds:Alternative elastomer formulations from Asian suppliers threaten traditional polyurethane dominance in penetration-resistant layers.
Strategic Opportunities
- Qatar and Kuwait multinational contractor premium positioning:European-certified product lines command price premiums among international engineering firms executing infrastructure and energy projects.
- E-procurement platform penetration:Direct-to-industrial digital channels are disintermediating traditional safety distributors, enabling volume aggregators to capture share in bulk contract segments.
- Local content requirements:Evolving nationalization mandates for safety equipment sourcing create first-mover advantages for manufacturers establishing regional assembly or testing facilities.
Industry Challenges
- Heat stress engineering talent scarcity:Specialized footwear designers capable of optimizing thermal comfort for 50°C ambient conditions remain concentrated in European and East Asian technical centers.
- Multi-standard certification complexity:Simultaneous compliance with Gulf Standardization Organization technical regulations, European EN benchmarks, and end-user corporate specifications extends product development timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East Industrial Protective Footwear Market |
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $880.92 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Safety Boots, Steel-Toe Boots, Chemical-Resistant Footwear, Waterproof Footwear End User: Manufacturing, Construction, Oil & Gas, Mining Material: Leather, Rubber, PVC, Synthetic Application: Heavy-Duty Work, Hazardous Environments, Outdoor Work, Assembly Lines |
| Companies Covered | Bata Corporation, COFRA Holding AG, Honeywell International Inc., VF Corporation, Dunlop Protective Footwear, Rahman Group, UVEX Safety Group, Jallatte Group, Wolverine World Wide Inc., Others |
| Regions Covered | Middle East: Saudi Arabia, UAE, Qatar, Israel, Kuwait, Oman, Bahrain, Iran, Iraq, Rest of Middle East |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East Industrial Protective Footwear Market Shifts & Advancements
Material science breakthroughs and regulatory harmonization are compressing product lifecycles while reshaping how industrial buyers evaluate total cost of ownership across extreme climate operating conditions.
Advanced composite toe cap technologies incorporating carbon fiber and aramid fiber matrices are rendering obsolete traditional steel and alloy safety toes in weight-sensitive applications. Oil and gas contractors operating in Saudi Arabia's Rub al Khali desert fields specify these materials to reduce fatigue during extended shifts. The shift is rendering obsolete legacy metallic toe inventory across regional distributor networks.
Gulf Standardization Organization technical regulations for personal protective equipment, aligned with European EN ISO 20345 benchmarks, create a harmonized compliance ceiling that manufacturers must meet for market access across member states. This regulatory convergence elevates testing documentation burdens while eliminating fragmented national standards that previously enabled lower-tier suppliers. Multinational contractors operating in Qatar and Kuwait now specify dual-certified products that satisfy both Gulf and European requirements.
Industrial buyers are consolidating vendor relationships and unbundling after-sales service from equipment procurement to drive total cost transparency. Direct-to-facility e-procurement platforms displace traditional safety distributor networks in Saudi Arabia's Eastern Province petrochemical complexes. This behavioral shift concentrates purchasing power with volume aggregators capable of integrating footwear with respiratory and eye protection bundles.
Middle East Industrial Protective Footwear Market Segmentation
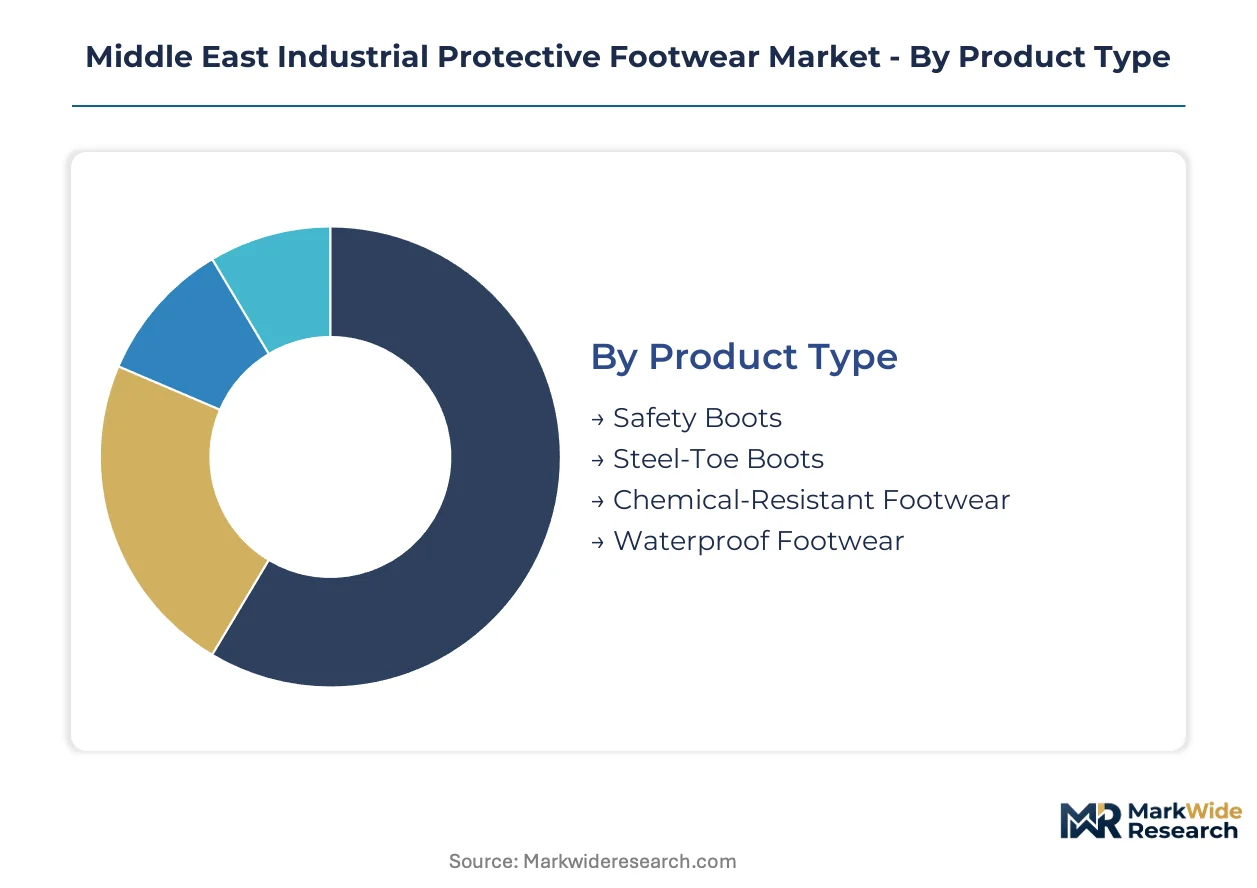
Segmentation in the Middle East industrial protective footwear market reflects divergent procurement priorities across petrochemical corridors and construction zones. Buyers in Saudi Arabia's Eastern Province prioritize chemical resistance and heat tolerance, while UAE logistics operators emphasize lightweight composites for extended wear cycles.
Product Type:
Mature steel-toe configurations dominate volume procurement, while emerging composite and chemical-resistant variants capture margin expansion in specialized applications.
- Safety Boots:Reinforced ankle support and penetration-resistant midsoles define this foundational category. Procurement concentrates in Saudi Aramco contractor networks across the Eastern Province, where SFDA-mandated replacement cycles drive predictable reorder volumes.
- Steel-Toe Boots:Alloy and traditional steel toe caps rated to EN ISO 20345 impact standards remain the default specification for construction and manufacturing end users. Dubai's Jebel Ali industrial zone generates concentrated bulk orders from general contracting firms serving Expo legacy infrastructure projects.
- Chemical-Resistant Footwear:Nitrile and neoprene compounds shield against hydrocarbon exposure in refining environments. Qatar's North Field expansion projects specify these for downstream processing crews.
- Waterproof Footwear:Membrane-lined synthetic uppers address outdoor work in coastal humidity and occasional flash flooding. Kuwait's port modernization contractors favor these for stevedoring operations.
Safety Boots handle the majority of throughput; Chemical-Resistant Footwear is climbing the fastest on share as petrochemical capacity expands.
End User:
Cost tier differentiation separates high-volume standardized procurement from premium certified specifications demanded by multinational operators.
- Manufacturing:Assembly-line workers require lightweight, anti-fatigue midsoles for repetitive standing operations. MOHAP compliance mandates in Sharjah's industrial free zones elevate replacement frequency.
- Construction:Impact and puncture hazards dominate specification sheets. Abu Dhabi's infrastructure buildout generates seasonal demand spikes aligned with project mobilization schedules.
- Oil & Gas:Hydrogen sulfide exposure and flash fire risks necessitate specialized materials. Saudi Aramco's Master Gas System expansion commands the region's most stringent certification requirements.
- Mining:Underground operations in Oman's Al Hajar mountains drive demand for metatarsal guards and electrical hazard protection. Limited local supply concentrates procurement with specialized distributors.
Oil & Gas commands the highest per-unit spend; Construction delivers the steepest volume expansion trajectory as Gulf infrastructure budgets accelerate.
Material:
Supply concentration in tanning and polymer feedstocks shapes regional availability and price volatility exposure.
- Leather:Full-grain hides retain dominance in high-heat welding and foundry applications. Bahrain's aluminum smelter maintenance crews specify these for spark resistance.
- Rubber:Natural and synthetic compounds excel in electrical hazard and slip-resistant applications. UAE electrical utility contractors mandate these for substation work.
- PVC:Injection-molded boots offer chemical splash protection at economy price points. Saudi food processing plants utilize these for washdown environments.
- Synthetic:Microfiber and textile composites reduce weight while maintaining EN ISO 20345 compliance. Qatar Airways' ground handling operations specify these for baggage handlers in summer heat.
Leather maintains structural leadership in premium heat-resistant applications; Synthetic materials are expanding most quickly as weight reduction becomes a procurement priority.
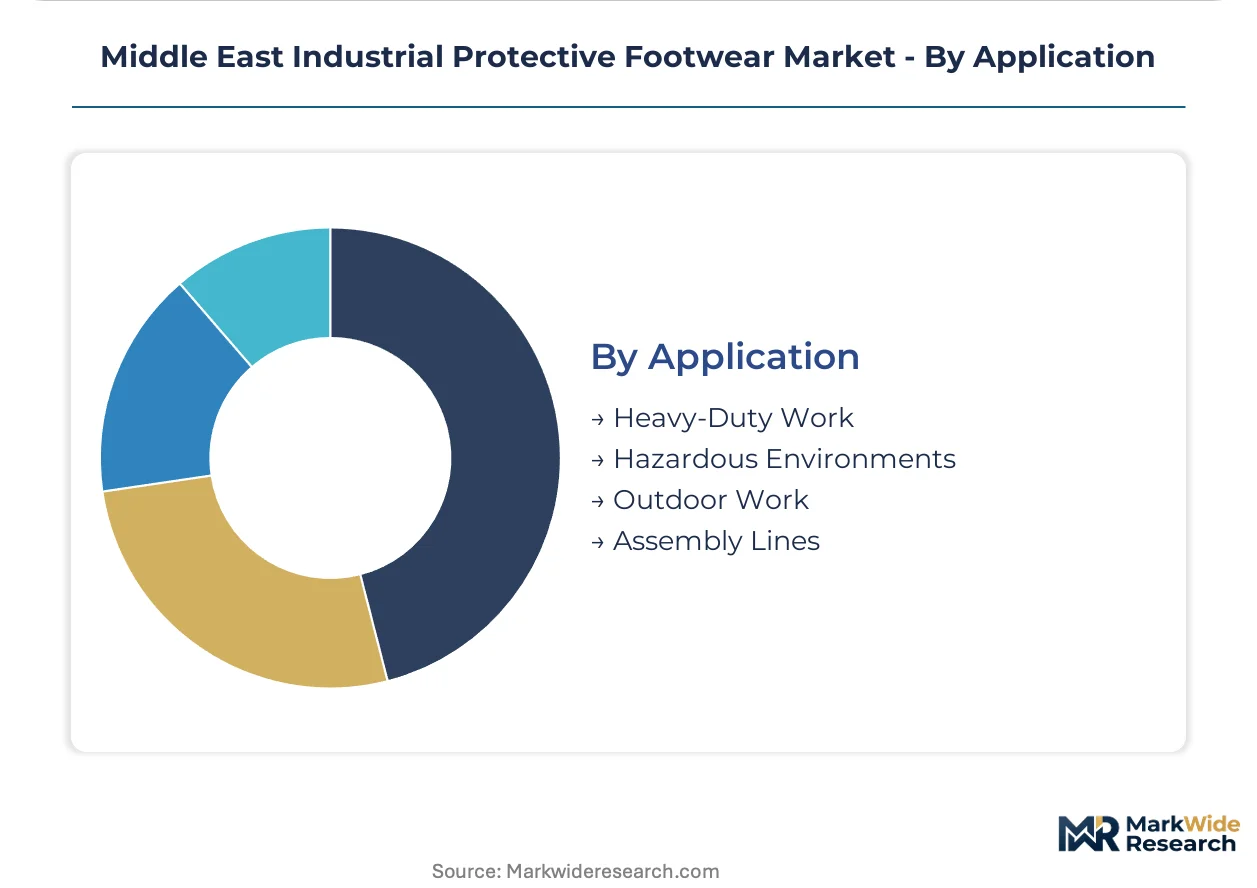
Application:
Geographic clustering aligns application requirements with specific industrial corridor conditions across the Gulf.
- Heavy-Duty Work:Reinforced toe caps, metatarsal guards, and puncture-resistant soles protect against crushing hazards. Saudi Arabia's Red Sea Project construction sites generate concentrated demand.
- Hazardous Environments:Chemical, thermal, and biological threat protection defines this specification tier. Kuwait's Mina Al-Ahmadi refinery turnaround campaigns drive episodic bulk procurement.
- Outdoor Work:Breathable uppers and moisture-wicking linings address 50°C ambient conditions. UAE solar farm installation crews prioritize these specifications.
- Assembly Lines:Ergonomic design and anti-static properties dominate. Dubai's automotive parts manufacturing cluster sources these through integrated PPE contracts.
Heavy-Duty Work absorbs the largest procurement volumes; Hazardous Environments is gaining share fastest as downstream petrochemical complexity increases.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The King Fahd Industrial Port underwrites Saudi Arabia's dominance in Middle East industrial protective footwear procurement, channeling petrochemical exports through the Eastern Province corridor where bulk safety equipment orders concentrate.
Saudi Arabia
Saudi Aramco's Master Gas System expansion and Red Sea Project construction generate concentrated demand for chemical-resistant and heavy-duty safety boots. SFDA workplace protective equipment mandates enforce strict replacement cycles across contractor networks. Jubail Industrial City and Yanbu anchor procurement volumes for refining and downstream processing crews.
United Arab Emirates
Jebel Ali Port throughput and Expo legacy infrastructure sustain construction sector safety boot procurement at scale. MOHAP standardization bodies align personal protective equipment requirements with Gulf Standardization Organization technical regulations. Dubai's logistics free zones and Abu Dhabi's energy infrastructure buildout drive seasonal demand spikes.
Qatar
North Field expansion projects command premium-certified safety footwear for downstream petrochemical and LNG processing operations. Multinational engineering contractors specify dual-certified products meeting both Gulf and European standards. Ras Laffan Industrial City concentrates procurement among international firms executing energy infrastructure contracts.
Kuwait
Mina Al-Ahmadi refinery turnaround campaigns generate episodic bulk orders for hazardous environment footwear specifications. The country's standardization authority enforces Gulf Standardization Organization-aligned compliance for personal protective equipment market access. Al-Zour refinery and port modernization projects sustain demand for chemical-resistant and waterproof boot categories.
Oman
Al Hajar mountain mining operations and Duqm special economic zone construction drive demand for metatarsal guard and electrical hazard protection footwear. Limited local supply concentrates procurement with specialized distributors serving underground and heavy industrial applications. The Port of Duqm's development as a multimodal logistics hub expands safety equipment procurement channels.
Middle East Industrial Protective Footwear Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in material and certification layers. The Middle East industrial protective footwear market structures around three tiers: multinational personal protective equipment conglomerates bundling footwear with respiratory and eye protection; European-certified specialists commanding premium positioning among international contractors; and regional manufacturers leveraging local assembly for price competitiveness in bulk contracts. Consolidation pressures intensify as direct-to-industrial e-procurement platforms disintermediate traditional safety distributors. Dominant competitive moves include backward integration into regional testing facilities and portfolio diversification across climate-adapted product lines.
Within the multinational integrator tier, Honeywell International Inc. exemplifies platform breadth through integrated personal protective equipment portfolios. Bata Corporation anchors the regional manufacturing archetype with price-competitive positioning in bulk contract segments. COFRA Holding AG represents European-certified premium specialists serving multinational contractors in Qatar and Kuwait. These three archetypes capture distinct procurement channels: bundled enterprise contracts, high-volume national tenders, and premium specifications for international engineering firms.
| Leading Market Players |
|---|
| Bata Corporation |
| COFRA Holding AG |
| Honeywell International Inc. |
| VF Corporation |
| Dunlop Protective Footwear |
| Rahman Group |
| UVEX Safety Group |
| Jallatte Group |
| Wolverine World Wide Inc. |
| Others |
Supply & Pricing Matrix
Undercapacity in regional EN ISO 20345 certification laboratories concentrates pricing power with accredited testing providers, forcing manufacturers to absorb extended lead times or pay expedite premiums for Gulf Standardization Organization market access. This bottleneck cascades into procurement costs as distributors stock certified inventory ahead of contract awards, elevating working capital requirements across the value chain.
Pricing Analysis
Volume-discount tiering structures separate multinational contractor premiums from national tender economy bids. Three-tier pricing stratification across European-certified premium lines, mid-grade Gulf-compliant products, and economy PVC injection-molded boots reflects certification grade and after-sales bundling intensity. Pricing pressure stems from direct-to-industrial e-procurement platforms disintermediating traditional safety distributors and compressing channel margins. Construction sector buyers exhibit highest price sensitivity due to standardized specifications and seasonal project mobilization cycles, while oil and gas operators prioritize total cost of ownership over unit price.
Supply Chain Analysis
Tariff exposure between Asian polymer feedstock suppliers and Gulf manufacturing hubs elevates landed cost volatility for synthetic upper materials and polyurethane midsole compounds. Production gravity centers on China for aramid fiber toe caps, India for full-grain leather tanning, and Italy for European-certified component finishing. Raw material portfolios draw from nitrile rubber compounds, carbon fiber matrices, and waterproof membrane technologies. Single-source vulnerability concentrates in specialized heat-stress engineering talent pools tethered to European technical centers. Distribution runs through petrochemical corridor procurement offices, safety equipment distributors, and emerging direct-to-facility digital platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The market's platform-economics inflection accelerates as integrated personal protective equipment bundles displace standalone footwear procurement, with interoperability between respiratory, eye protection, and footwear systems becoming the decisive vendor selection criterion.
For Market Incumbents: Harden certification capabilities through backward integration into regional testing facilities ahead of Gulf Standardization Organization enforcement timelines. Deepen channel control by embedding after-sales service within direct e-procurement platforms to defend against price-transparent volume aggregators. Anchor enterprise relationships through climate-adapted product line extensions addressing 50°C ambient operating conditions. For New Entrants and Emerging Players: Build out white-space positioning in Oman's mining sector and Duqm special economic zone construction, where limited local supply concentrates procurement with specialized distributors willing to trial new vendors. Target metatarsal guard and electrical hazard protection segments as the most penetrable application tier. Pursue go-to-market partnerships with established safety equipment distributors holding existing contractor relationships in Qatar's North Field expansion projects. For Investors and Strategic Acquirers: Capital is best deployed toward European-certified specialists with dual Gulf Standardization Organization compliance capabilities and established multinational contractor relationships in Qatar and Kuwait. Long-term viability hinges on regulatory harmonization acceleration and local content mandate evolution. Watch for inflection signals in nationalization requirement announcements and regional laboratory capacity expansion commitments as early indicators of competitive position shifts.| Strategic Initiative | Industry Significance |
|---|---|
| Regional Testing Facility Establishment | Captures Gulf Standardization Organization certification revenue currently flowing to European laboratories. |
| Composite Safety Toe Technology Licensing | Accelerates carbon fiber and aramid fiber adoption in Saudi Aramco contractor specifications. |
| Integrated PPE Platform Integration | Bundles footwear with Honeywell respiratory systems for Eastern Province petrochemical procurement offices. |
| Direct-to-Industrial E-Procurement Launch | Disintermediates traditional safety distributors serving Dubai Jebel Ali logistics free zones. |
| Heat-Stress Engineering Talent Acquisition | Addresses specialized design scarcity for 50°C ambient condition optimization in UAE solar farm applications. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with safety equipment procurement managers at Saudi Aramco contractor networks, plant engineers at Jubail Industrial City refining complexes, and distribution channel heads serving Qatar's Ras Laffan Industrial City. Secondary validation drew from Gulf Standardization Organization technical regulation filings, SFDA workplace protective equipment mandate documentation, customs and trade data for polymer feedstock imports, and SEC filings of multinational personal protective equipment conglomerates. Bottom-up segment sizing triangulated against top-down industrial employment and replacement cycle assumptions.
Calibration anchored volume and value outputs to petrochemical capacity expansion timelines, infrastructure project mobilization schedules, and regulatory enforcement phase-in patterns across the analysis window. Segmentation dimensions modeled encompassed product type tier, end-use industry vertical, material composition, and geographic industrial corridor cluster. CAGRs derived from regression analysis against historical procurement volumes and projected industrial workforce expansion. Industry-specific forecast inputs incorporated SFDA-mandated replacement cycle frequencies and composite safety toe adoption penetration curves.
Sensitivities concentrate around Gulf Standardization Organization laboratory capacity expansion pace, nationalization requirement evolution, and leather input cost volatility from livestock supply cycles. Forecasts reflect documented assumptions regarding regulatory harmonization timelines and petrochemical project completion rates. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Workplace Safety
Safety Vest Market
Workplace Safety
Safety Glasses Market
Workplace Safety
Construction Worker Safety Market
Workplace Safety
Workplace Safety Market
Workplace Safety
Industrial Safety Market
Workplace Safety
Industrial Hand Protection Gloves Market
Workplace Safety
Industrial Eye Protection Market
Workplace Safety
Industrial Head Protection Market
Workplace Safety
Industrial and Workplace Safety Market
Workplace Safety
Safety Helmets Market
Workplace Safety
Industrial Protective Footwear Market
Workplace Safety
Canada Safety Services Market
Workplace Safety
Global Industrial Safety Footwear Market
Workplace Safety
Industrial Safety Mats Market
Workplace Safety
Industrial Safety Gloves Market
Workplace Safety
Machine Safety Market