
 Crowd Management System Market | 2026-2036
Crowd Management System Market Size, Share, and Industry Trends Forecast 2026-2036
Crowd Management System Market Outlook
System integrator relationships are rewriting how crowd management technology reaches end users in large venues. Allied Universal leverages its security services footprint to bundle hardware and monitoring contracts. GardaWorld anchors its position through protective services contracts at Canadian and US transit authorities. Outsight differentiates through lidar-based people-flow analytics without biometric capture.
A crowd management system integrates sensor networks, real-time analytics engines, and communication interfaces to monitor, predict, and direct human density across physical spaces, typically processing video feeds at 30 frames per second with sub-second alert latency. Event venues represent the most mature application segment, with established procurement cycles and standardized safety certifications, while edge computing deployments are expanding fastest as venues seek on-site processing to reduce bandwidth costs and latency. Cloud-based platforms still command the largest margin pools through recurring software subscriptions and centralized model updates.
The EU AI Act, GDPR, and the US FAA's venue security directives collectively shape product roadmaps by restricting biometric storage, mandating audit trails, and requiring redundant communication pathways in aviation-adjacent facilities. ISO 22320 for emergency management and NFPA 101 life safety codes further constrain system design in North American public assemblies. Stakeholders must weigh privacy-preserving sensor architectures against the performance advantages of facial recognition as regulatory fragmentation intensifies.
Market Dynamics
Edge computing architectures are compressing deployment timelines as venues prioritize sub-second latency over cloud-dependent processing, forcing hardware vendors to redesign sensor-to-analytics pipelines for on-premise inference.
Growth Catalysts
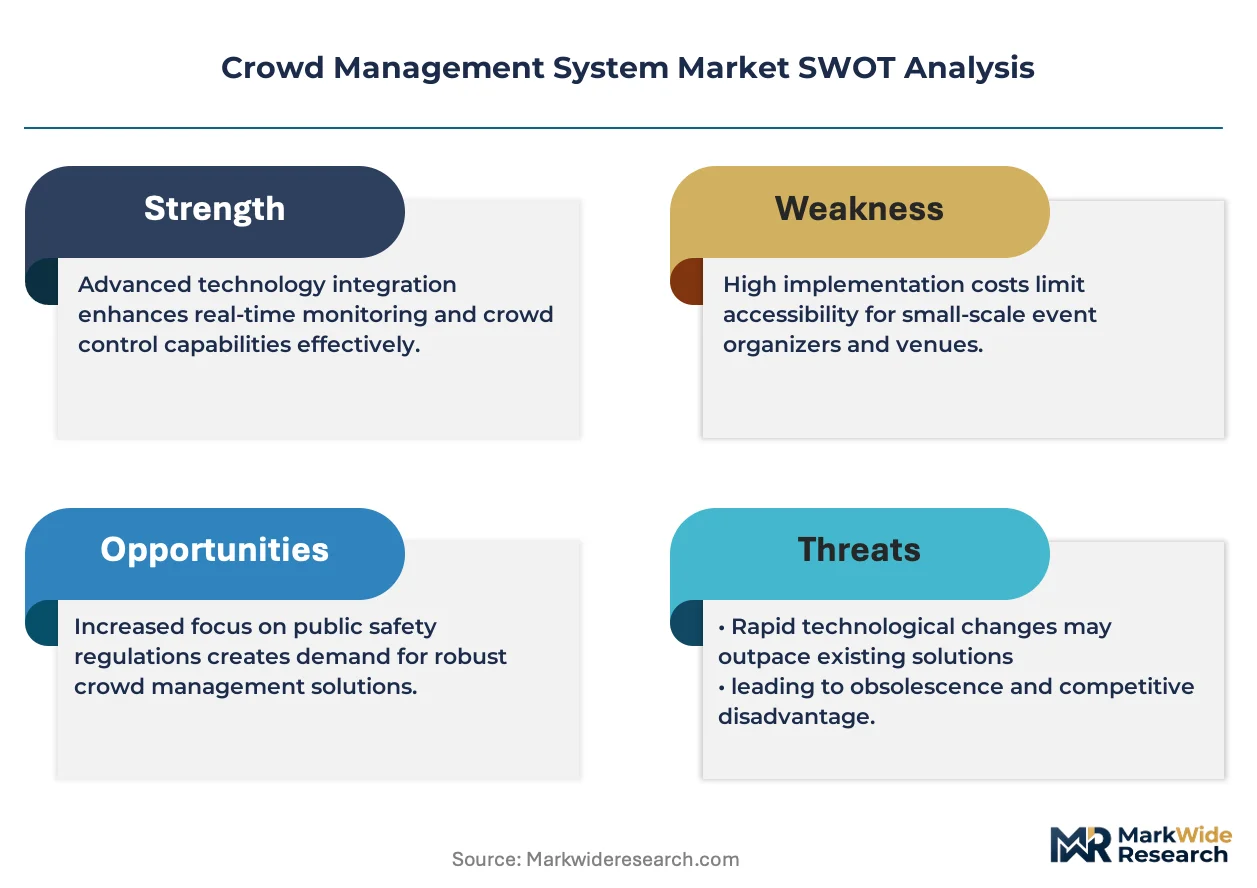
- EU AI Act compliance mandates:Stadium operators across Germany, France, and Italy are accelerating procurement of privacy-preserving lidar and thermal sensor arrays to meet biometric storage prohibitions before enforcement deadlines.
- Major event infrastructure cycles:Qatar, Saudi Arabia, and Australia are completing venue construction and retrofit programs tied to multi-year sports tournament calendars, embedding crowd analytics into base architectural specifications.
- Sensor fusion advances:Multi-modal systems combining radar, computer vision, and acoustic detection are reducing false-positive rates below 2%, expanding addressable applications from controlled entry points to open concourse monitoring.
Market Restraints
- Semiconductor supply concentration:Specialized AI inference chips for edge deployment remain concentrated among Taiwan-based foundries, creating 14-18 week lead time volatility for hardware integrators.
- GDPR audit trail requirements:European data protection authorities are mandating granular logging of all automated decision triggers, increasing software development overhead by 25-40% for cloud-platform vendors.
- Legacy analog infrastructure:North American public assembly venues built before 2010 retain coaxial cable plant incompatible with IP-based sensor networks, requiring complete electrical subsystem replacement.
Strategic Opportunities
- India smart city integration:Municipal corporations in Mumbai, Delhi, and Bangalore are bundling crowd management into transit hub modernization contracts, creating localized demand clusters outside traditional event venue procurement.
- Healthcare facility overflow monitoring:Hospital systems in Japan and South Korea are repurposing density analytics originally designed for entertainment venues to manage emergency department queuing and triage flow.
- CSRD sustainability reporting:European venue operators must document occupant safety metrics under corporate sustainability disclosure rules, converting crowd analytics from operational tool to compliance infrastructure.
Industry Challenges
- Cross-functional integration expertise:Deployment teams must simultaneously command network engineering, data science, and facilities management competencies, creating talent scarcity in mid-tier system integrators.
- ISO 22320 certification timelines:Emergency management standard compliance requires 8-14 month validation cycles for new software releases, compressing product iteration velocity relative to cloud-native competitors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Crowd Management System Market |
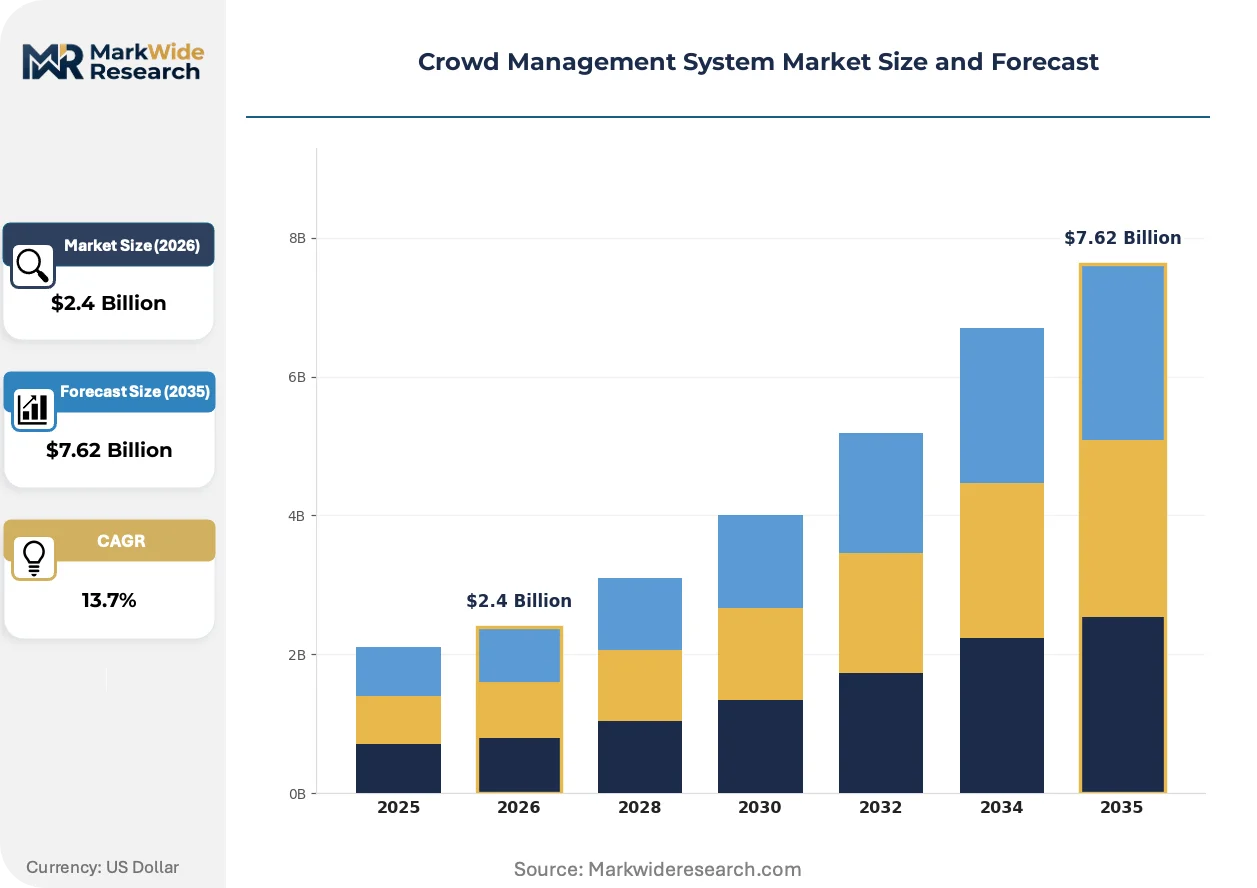
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $7.62 Billion |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application Type: Event Venues, Transport Hubs, Sports Arenas, Public Spaces Deployment Model: On-Premises, Cloud-Based, Hybrid, Edge Computing End User: Government Agencies, Security Firms, Event Organizers, Transportation Authorities Technology: AI Analytics, IoT Sensors, Mobile Alerts, Data Visualization |
| Companies Covered | GardaWorld, IDenTV, BEST Crowd Management, Telenet, Outsight, Contemporary Services Corporation, Virtualitis, MyConnector, Allied Universal, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Crowd Management System Market Strategic Shifts
Real-time spatial analytics are fragmenting across specialized sensor modalities as privacy regulations and performance requirements diverge, creating parallel technology tracks rather than unified platform consolidation.
Lidar-based people-flow tracking is migrating from experimental pilot installations to standard specification in German and Qatari stadium projects. Bundesliga venue operators now require anonymized spatial trajectory data without biometric capture, compressing demand for facial recognition systems in European sports infrastructure. Hardware vendors are responding with solid-state lidar arrays priced below thermal camera equivalents.
The EU AI Act's risk classification framework for automated surveillance is forcing product architecture redesigns before 2025 enforcement. High-risk system designations apply to real-time biometric identification in publicly accessible spaces, compelling vendors to strip facial matching capabilities from European deployments. Cloud-platform providers are segmenting their codebases into region-specific compliance branches.
Subscription-based software licensing is displacing perpetual license sales in North American venue procurement. Municipal buyers in Chicago, Los Angeles, and Toronto now prioritize operational expenditure models that bundle continuous model updates and centralized threat intelligence feeds. This shift compresses upfront vendor revenue while extending customer lifetime value horizons.
Crowd Management System Market Segmentation
Crowd management procurement cycles vary dramatically by segment, with transport hubs operating on decade-long infrastructure timelines while event venues refresh technology every 3-4 years. Understanding these velocity differences shapes vendor go-to-market strategy and R&D prioritization across the ecosystem.
Application Type:
Replacement cycles stretch from 12-15 years in fixed infrastructure to 3-5 years in temporary installations, creating divergent revenue recognition patterns for hardware versus software suppliers.
- Event Venues:Concert halls and exhibition centers deploy modular sensor arrays with rapid reconfiguration capabilities for varying capacity loads. German Bundesliga stadiums now mandate lidar-based spatial tracking in all new construction, compressing procurement timelines as operators race to meet EU AI Act biometric prohibitions.
- Transport Hubs:Airports and rail terminals integrate crowd analytics into multi-year capital improvement programs with 10-15 year asset lifecycles. Mumbai Metro and Delhi Airport Authority are embedding density monitoring into station modernization contracts, creating localized demand clusters with extended vendor relationships.
- Sports Arenas:Professional venues balance spectator safety with commercial analytics for concession optimization and traffic flow.
- Public Spaces:Municipal plazas and pedestrian zones prioritize low-cost thermal monitoring for emergency response coordination.
Transport hubs anchor the volume base while event venues gain share at the steepest rate.
Deployment Model:
Cost structures stratify sharply between capital-intensive edge installations and recurring cloud subscriptions, with hybrid architectures capturing mid-tier budgets.
- On-Premises:Dedicated server installations with localized data retention meet stringent GDPR audit trail requirements for European public sector buyers. French and Italian stadium operators prefer this model to maintain sovereign control over surveillance data.
- Cloud-Based:Centralized platforms deliver continuous model updates and threat intelligence feeds through subscription licensing. Chicago, Los Angeles, and Toronto municipal buyers now prioritize operational expenditure models that bundle software maintenance and centralized monitoring.
- Hybrid:Split architectures process sensitive biometric data locally while pushing anonymized analytics to cloud dashboards.
- Edge Computing:On-device inference reduces bandwidth costs and achieves sub-second alert latency for real-time crowd safety.
Cloud-based deployments dominate recurring revenue pools while edge computing climbs the fastest among new installations.
End User:
Procurement sophistication varies from centralized federal frameworks to fragmented private event contracts, shaping sales cycle duration and technical specification depth.
- Government Agencies:National and municipal purchasers operate under public tender regulations with extended compliance validation. Japanese and South Korean hospital systems are repurposing venue-originated density analytics for emergency department overflow management.
- Security Firms:Allied Universal and GardaWorld bundle hardware deployment with protective services contracts, creating integrated procurement channels at Canadian and US transit authorities.
- Event Organizers:Temporary installation specialists prioritize rapid deployment and strike capabilities over permanent infrastructure.
- Transportation Authorities:Rail and aviation regulators mandate redundant communication pathways under FAA venue security directives.
Government agencies anchor the volume base while security firms gain share at the steepest rate.
Technology:
Margin profiles diverge between commoditized sensor hardware and proprietary analytics software, with integration layers capturing value at architecture boundaries.
- AI Analytics:Computer vision and predictive models process video feeds at 30 frames per second with sub-second alert latency. Multi-modal systems fusing radar, computer vision, and acoustic detection have reduced false-positive rates below 2%, expanding applications from controlled entry points to open concourse monitoring.
- IoT Sensors:Lidar, thermal, and radar arrays provide anonymized people-flow data without biometric capture. Solid-state lidar priced below thermal camera equivalents is now standard specification in German and Qatari stadium projects.
- Mobile Alerts:Push notification systems deliver evacuation instructions and capacity warnings directly to attendee devices.
- Data Visualization:Dashboard platforms aggregate multi-source inputs for security operations center coordination.
IoT sensors anchor the volume base while AI analytics gains share at the steepest rate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The EU AI Act anchors European procurement patterns, compelling stadium operators to accelerate privacy-preserving sensor deployments ahead of enforcement deadlines. Procurement cycles diverge sharply between German infrastructure upgrades and Gulf state mega-projects.
Germany
Bundesliga venue operators mandate lidar-based spatial tracking in all new construction, compressing demand for facial recognition systems. The EU AI Act's biometric storage prohibitions drive operators toward anonymized people-flow analytics. Munich and Dortmund stadium clusters anchor the continent's fastest hardware refresh cycle.
United States
Municipal buyers in Chicago, Los Angeles, and Toronto prioritize subscription-based operational expenditure models. FAA venue security directives mandate redundant communication pathways in aviation-adjacent facilities. Legacy coaxial infrastructure in pre-2010 public assembly venues requires complete electrical subsystem replacement.
Qatar
Multi-year sports tournament calendars embed crowd analytics into base architectural specifications for venue construction and retrofit programs. Solid-state lidar arrays priced below thermal camera equivalents dominate procurement specifications. Doha stadium infrastructure operates on accelerated deployment timelines.
India
Municipal corporations in Mumbai, Delhi, and Bangalore bundle crowd management into transit hub modernization contracts. Localized demand clusters emerge outside traditional event venue procurement with extended vendor relationships. Mumbai Metro and Delhi Airport Authority anchor density monitoring integration.
Japan
Hospital systems repurpose venue-originated density analytics for emergency department overflow management and triage flow optimization. METI guidelines shape sensor deployment standards in healthcare facility adaptations. Tokyo and Osaka medical clusters drive cross-sector technology transfer.
Crowd Management System Market Competitive Environment
Security service integrators and specialized sensor vendors split the market into divergent commercialization channels. Allied Universal leverages protective services contracts to bundle hardware and monitoring agreements at North American transit authorities. GardaWorld anchors its position through Canadian and US transit authority relationships. Two dominant competitive moves reshape positioning: system integrators deepen protective services bundling, while hardware vendors redesign sensor-to-analytics pipelines for on-premise inference.
Within the privacy-preserving sensor tier, Outsight exemplifies lidar-based people-flow analytics without biometric capture, occupying a position aligned with EU AI Act compliance trajectories. Allied Universal and GardaWorld represent the security services bundling archetype, anchoring integrated procurement channels through protective services contracts rather than standalone technology sales. Contemporary Services Corporation sits within the event venue specialization cluster.
| Leading Market Players |
|---|
| GardaWorld |
| IDenTV |
| BEST Crowd Management |
| Telenet |
| Outsight |
| Contemporary Services Corporation |
| Virtualitis |
| MyConnector |
| Allied Universal |
| Others |
Value Chain & Pricing Dynamics
Taipei-based foundry capacity for specialized AI inference chips governs hardware pricing power across the crowd management ecosystem, with 14-18 week lead time volatility compressing margins for system integrators dependent on edge computing deployments.
Pricing Analysis
North American municipal procurement shows 30-40% subscription premiums over European perpetual license baselines, reflecting divergent buyer sophistication and after-sales service bundling. Three-tier pricing structure across premium, standard, and economy levels separates GDPR-compliant on-premise installations from cloud-native SaaS tiers and stripped-down sensor-only configurations. Cost compression in the economy tier is intensifying as solid-state lidar arrays displace thermal camera equivalents. Government agencies exhibit highest price sensitivity due to public tender regulations, while Gulf state mega-projects demonstrate lowest sensitivity given embedded architectural specification mandates.
Supply Chain Analysis
Extended payment terms from Taiwanese foundries to German lidar assemblers are tightening working capital requirements for mid-tier hardware vendors. Semiconductor fabrication concentrates in Taiwan, South Korea, and the United States, while solid-state lidar assembly localizes in Germany and Qatar. Specialized AI inference chips, thermal sensor arrays, and coaxial-to-IP conversion modules constitute critical input dependencies. Single-source vulnerability around Taiwan-based foundry capacity represents the dominant structural risk. Distribution runs through security service integrators bundling hardware with protective services contracts at North American and European transit authorities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market rewards regulatory entrenchment as a defensive moat, with EU AI Act compliance timelines creating switching costs that lock venue operators into validated vendor relationships.
For Market Incumbents: Build certification moats by accelerating ISO 22320 validation cycles for new software releases before cloud-native competitors achieve compliance. Anchor capacity addition in German stadium clusters where Bundesliga mandates compress procurement timelines. Deepen channel control through exclusive system integrator relationships with Allied Universal and GardaWorld, neutralizing emerging lidar specialists threatening biometric-free positioning. For New Entrants and Emerging Players: Build out healthcare facility overflow monitoring as the most penetrable application segment, repurposing venue-originated density analytics for Japanese and South Korean hospital emergency department queuing. Target Indian smart city integration through transit hub modernization contracts in Mumbai and Delhi, where municipal bundling creates localized demand clusters outside established event venue procurement channels. Pursue CSRD sustainability reporting positioning as the go-to-market angle, converting crowd analytics from operational tool to compliance infrastructure for European venue operators. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors privacy-preserving sensor specialists with EU AI Act-aligned product architectures over facial recognition incumbents facing compliance stripping requirements. Long-term viability hinges on regulatory fragmentation persisting across biometric storage prohibitions and audit trail mandates. Acquisition target archetype: lidar-based people-flow analytics vendors with German stadium reference installations. The signal to watch is enforcement deadline acceleration for biometric prohibitions in publicly accessible spaces.| Strategic Initiative | Industry Significance |
|---|---|
| Privacy-Preserving Sensor Architecture | EU AI Act high-risk designations force facial recognition stripping from European deployments. |
| Edge Computing Pipeline Redesign | On-premise inference achieves sub-second latency for German stadium safety mandates. |
| Security Services Bundling | Allied Universal leverages protective services contracts to anchor hardware deployment channels. |
| Healthcare Application Expansion | Japanese hospital systems repurpose venue density analytics for emergency department overflow. |
| CSRD Compliance Positioning | European venue operators convert crowd analytics to sustainability disclosure infrastructure. |
Study Parameters
A spread of perspectives from stadium operations directors, security service procurement leads, system integration engineers, and municipal tender administrators converged on the working assumptions underlying this analysis. Primary interview intelligence combined with secondary validation from EU AI Act implementation guidance, GDPR audit trail precedents, FAA venue security directives, and ISO 22320 certification timelines. Bottom-up venue installation counts triangulated against top-down security services contract values.
Demand-supply-balance framing anchored the analytical framework across the projection horizon, modeling deployment model, application type, end user sophistication, and regional regulatory cluster as core segmentation dimensions. CAGRs derived from hardware refresh cycle analysis and software subscription renewal patterns. Industry-specific forecast inputs included Bundesliga stadium construction pipelines and Indian smart city transit hub modernization contract awards.
Stress conditions across semiconductor lead time volatility, EU AI Act enforcement acceleration, and legacy infrastructure replacement rates were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about regulatory persistence and technology substitution trajectories. Macroeconomic contraction, biometric prohibition reversal, or edge computing cost breakthrough would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Public Safety
US Mass Notification Systems Market
Public Safety
Global Public Safety Solution Market
Public Safety
Latin America Public Safety Market
Public Safety
LAMEA Wireless Broadband in Public Safety Market
Public Safety
Global Public Safety in Building Wireless Das System Market
Public Safety
Global Wireless Broadband in Public Safety Market
Public Safety
Voice Evacuation Systems Market
Public Safety
Europe Road Safety Market
Public Safety
Global Public Safety Solution for Smart City Market
Public Safety
Crime Risk Report Market
Public Safety
Public Safety in-Building Wireless Distributed Antenna System (DAS) Market
Public Safety
Public Safety Market
Public Safety
North America Road Safety Market
Public Safety
Public Safety Drones Market
Public Safety
Public Safety LTE Market
Public Safety
Global Public Safety Analytics Market