
 Industrial Eye Protection Market | 2026-2036
Industrial Eye Protection Market Size, Share, and Industry Trends Forecast 2026-2036
Industrial Eye Protection Market Analysis
Chemical processing plants are unwinding the long-standing dominance of construction buyers in industrial eye protection procurement. 3M Company leverages its integrated materials science platform to control distribution across high-hazard environments. Honeywell International Inc. anchors its position through R&D intensity in anti-fog and scratch-resistant coatings. MSA Safety Incorporated specializes in full-face respiratory-vision integrated systems for confined-space applications.
Industrial eye protection comprises personal protective equipment engineered to shield ocular tissue from mechanical impact, chemical splash, optical radiation, and particulate intrusion, typically constructed with polycarbonate lenses rated for high-velocity impact resistance. Polycarbonate lenses dominate volume due to their superior strength-to-weight ratio and UV absorption properties, while face shields capture expanding share in welding and grinding operations where full facial coverage is mandated. Safety glasses remain the mature baseline category, though goggles are displacing them in chemical handling applications where sealed peripheries prevent vapor ingress.
OSHA's eye and face protection standards under 29 CFR 1910.133 mandate employer-provided equipment calibrated to specific workplace hazards, while ANSI Z87.1 certification defines optical clarity and impact performance thresholds for market access. The EU's PPE Regulation 2016/425 enforces CE marking and module conformity assessment, tightening compliance costs for non-European suppliers. Stakeholders must monitor the divergence between regional certification regimes as a strategic sourcing and portfolio allocation decision.
Market Dynamics
ANSI Z87.1 and EN 166 certification divergence is fragmenting supplier portfolios as manufacturers face incompatible testing protocols across North American and European procurement channels.
Growth Catalysts
- OSHA 29 CFR 1910.133 enforcement:US employers must provide hazard-calibrated equipment, mandating employer-funded replacement cycles that sustain recurring revenue for certified suppliers.
- Chemical processing plant expansion:Sealed-periphery goggles are displacing safety glasses in vapor-exposure environments, creating specification upgrades across petrochemical and pharmaceutical facilities.
- Polycarbonate UV absorption properties:Lens material innovation enables single-product compliance for both impact and optical radiation hazards, reducing SKU complexity for industrial distributors.
Market Restraints
- Raw material concentration:Bisphenol A supply for polycarbonate synthesis concentrates in Asian petrochemical corridors, exposing manufacturers to feedstock volatility and tariff exposure.
- EU PPE Regulation 2016/425 module assessment:CE marking requires notified body intervention for Category III eye protection, extending time-to-market for non-European suppliers by 8-14 months.
- Face shield substitution:Full facial coverage mandates in welding and grinding operations are compressing safety glass volumes in metal fabrication end-uses.
Strategic Opportunities
- India's PLI scheme for manufacturing:Production-linked incentives for industrial safety equipment create localized supply base potential for export-oriented suppliers.
- Wearable sensor convergence:Integration of proximity detection and fatigue monitoring into smart eyewear opens premium positioning in logistics and heavy machinery operations.
- E-commerce procurement channels:Direct-to-facility platforms are disintermediating traditional industrial distributors, enabling specification-grade purchasing by mid-size chemical processors.
Industry Challenges
- Optical metrology talent scarcity:ANSI Z87.1 high-velocity impact testing requires specialized laboratory capability that concentrates in Germany, the United States, and Japan.
- Legacy respiratory-vision integration:MSA Safety's confined-space systems set interoperability benchmarks that smaller suppliers struggle to match without dedicated R&D allocation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Industrial Eye Protection Market |
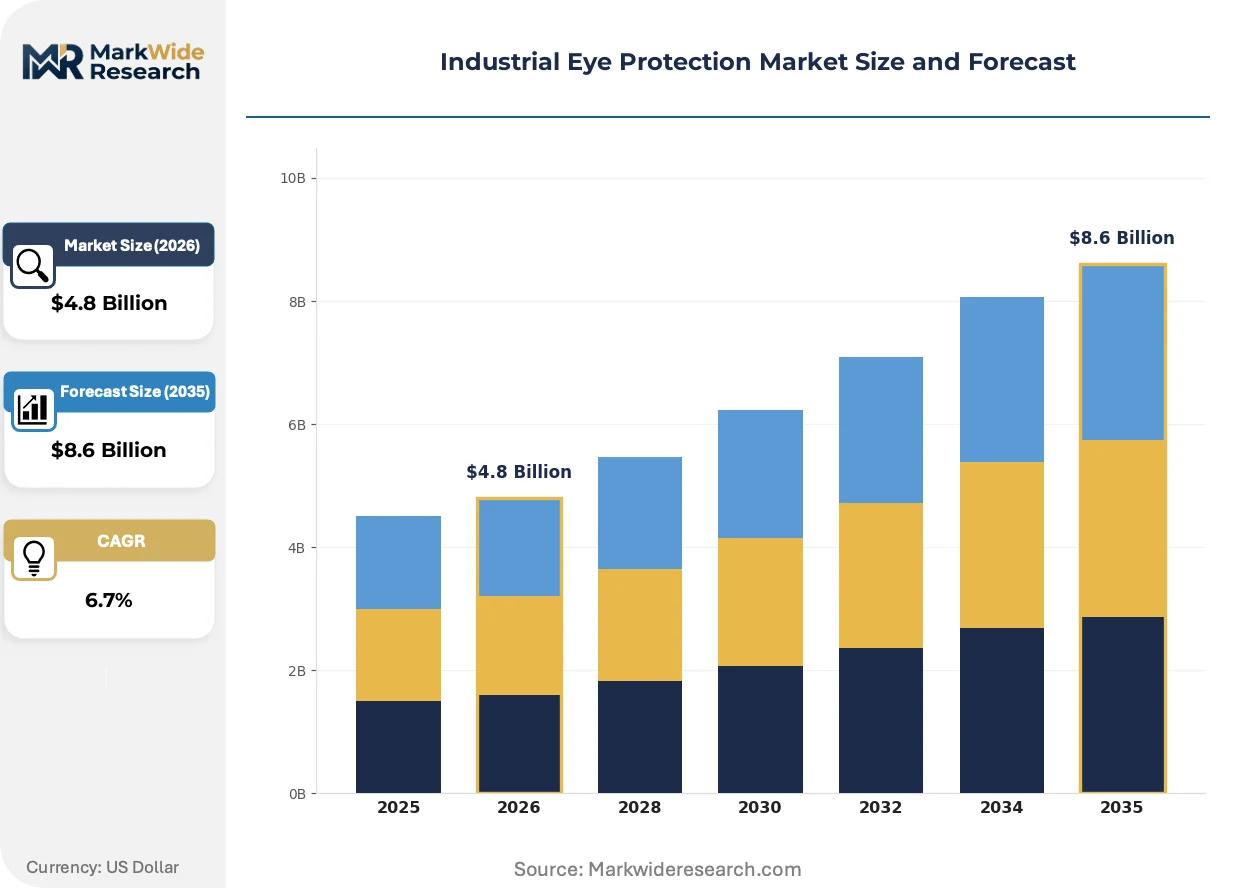
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Safety Glasses, Goggles, Face Shields, Welding Helmets Application: Construction, Manufacturing, Mining, Oil & Gas Material: Polycarbonate, Glass, Acetate, Nylon End User: Workers, Contractors, Emergency Responders, Inspectors |
| Companies Covered | 3M Company, Honeywell International Inc., MSA Safety Incorporated, Uvex Safety Group, Bollé Safety, Pyramex Safety Products, LLC, Radians, Inc., Delta Plus Group, MCR Safety, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Industrial Eye Protection Market Emerging Trajectories
Smart eyewear architectures are converging with industrial IoT platforms, while regulatory divergence between ANSI and EN frameworks forces parallel product development tracks.
Photochromic lens technology is fragmenting the traditional fixed-tint product hierarchy. These adaptive optics automatically modulate visible light transmission across welding arc intensities and outdoor construction glare. Automotive manufacturing clusters in Germany and precision electronics facilities in Japan are piloting these lenses at scale. The technology is fragmenting procurement categories that previously separated indoor and outdoor SKUs, compressing distributor inventory requirements while raising unit price points.
REACH substance restrictions on polycarbonate additives are tightening formulation freedom for lens manufacturers serving European industrial buyers. ECHA scrutiny of bisphenol derivatives is forcing reformulation cycles that delay CE marking timelines. Chemical processing and pharmaceutical manufacturing verticals face the steepest compliance burden, with some suppliers maintaining parallel product lines to isolate regulatory risk.
Consolidated procurement through integrated facility management providers is concentrating specification authority away from individual plant safety officers. Sodexo and ISS Facility Services now dictate eye protection standards across multi-site chemical and automotive manufacturing portfolios. This concentration is visible most acutely in Germany's Ruhr industrial corridor, where single contracts cover dozens of facilities and lock out non-preferred suppliers for 3-5 year terms.
Industrial Eye Protection Market Segmentation
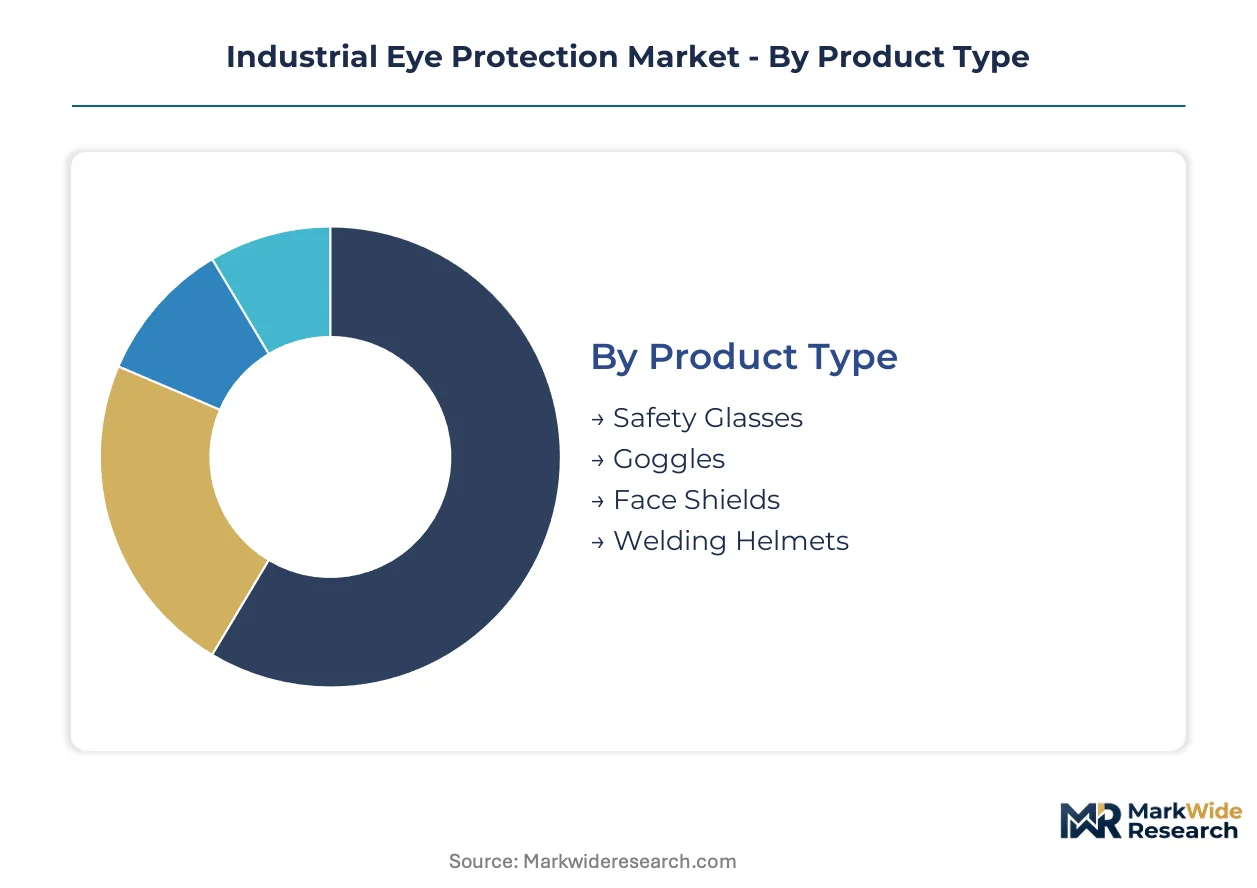
Segmentation in industrial eye protection reveals how substitution dynamics and material science advances redistribute procurement budgets across hazard-specific applications. Buyers now calibrate protection levels to precise workplace exposures rather than defaulting to universal safety glass specifications.
Product Type:
Face shields and welding helmets exert the strongest substitution pressure on legacy safety glasses as full-facial coverage mandates expand across metal fabrication and chemical handling environments.
- Safety Glasses:Lightweight polycarbonate frames with side shields dominate baseline industrial procurement. Construction sites in the United States and Germany still specify these for general mechanical hazard protection despite specification erosion in chemical environments.
- Goggles:Sealed-periphery designs with indirect ventilation prevent vapor ingress in petrochemical and pharmaceutical processing. ANSI Z87.1 D3/D4 splash and dust ratings now displace open-frame glasses in facilities handling corrosive intermediates.
- Face Shields:Full facial coverage for grinding sparks and chemical splash protection, often worn over primary eyewear. Welding and foundry operations mandate these for secondary defense against molten metal projection.
- Welding Helmets:Auto-darkening filter technology integrates with respiratory systems for arc flash protection. Shipbuilding clusters and pipeline construction drive demand for helmets with adjustable shade settings.
Safety glasses retain volume leadership; welding helmets hold the steepest expansion curve.
Application:
Cost tier stratification separates premium sealed-system procurement in oil and gas from commodity safety glass volumes in residential construction.
- Construction:General contractors deploy ANSI Z87.1 basic impact-rated glasses across multi-trade sites. Residential and commercial building activity in the United States sustains high-volume, low-margin procurement cycles.
- Manufacturing:Automotive and electronics facilities specify anti-fog coatings and prescription insert compatibility. Germany's precision manufacturing corridor demands optical clarity standards that exceed baseline construction specifications.
- Mining:Underground operations require dust-tight sealing and helmet-mounted lighting integration. Surface extraction sites in Australia and Canada prioritize UV protection for extended outdoor exposure.
- Oil & Gas:Offshore platforms and refineries mandate chemical splash goggles with flame-resistant headgear. Explosion-proof certifications and H2S exposure protocols drive premium equipment specifications.
Construction commands absolute unit volume; oil and gas generates the highest per-worker equipment expenditure.
Material:
Supply concentration in Asian petrochemical corridors shapes material availability and formulation compliance costs across regional markets.
- Polycarbonate:Bisphenol A-derived thermoplastic with superior strength-to-weight ratio and inherent UV absorption. REACH restrictions on additive formulations complicate European supply chains while North American procurement proceeds under less stringent EPA oversight.
- Glass:Scratch-resistant mineral lenses retain niche demand in laboratories and precision inspection roles. Optical clarity advantages persist despite weight penalties and fracture risks under impact.
- Acetate:Cellulose-derived frames offer chemical resistance in pharmaceutical cleanroom environments. Limited thermal stability constrains deployment in high-temperature industrial zones.
- Nylon:Flexible frame material for wraparound sport-style safety eyewear. Injection molding efficiency supports rapid color customization for corporate branding programs.
Polycarbonate dominates lens volume; nylon frames are climbing the fastest in fashion-conscious industrial sectors.
End User:
Procurement authority fragmentation between employers and contingent labor platforms creates divergent specification and replacement cycle patterns.
- Workers:Direct employees receive employer-funded equipment with scheduled replacement intervals. OSHA 29 CFR 1910.133 mandates hazard-calibrated provision without cost transfer to personnel.
- Contractors:Temporary staffing agencies and subcontractor fleets often self-provision to minimum compliance thresholds. Cost pressure drives shorter product lifecycles and higher replacement frequency.
- Emergency Responders:Fire services and hazmat teams require ballistic-rated eyewear with compatibility for SCBA masks. NFPA standards and interoperability with respiratory systems constrain supplier selection.
- Inspectors:Regulatory auditors and insurance assessors carry portable kits for site evaluation across multiple hazard categories. Prescription compatibility and all-day wear comfort prioritize lightweight frame designs.
Workers represent the installed base majority; emergency responders sustain the most specialized equipment requirements.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German precision manufacturers export sealed-system eyewear to North American chemical processors, while Chinese polycarbonate suppliers feed lens fabrication across Southeast Asian assembly hubs.
United States
OSHA 29 CFR 1910.133 enforcement sustains employer-funded replacement cycles across construction and manufacturing verticals. The EPA oversees bisphenol A discharge limits affecting polycarbonate feedstock availability. Houston's petrochemical corridor drives specification-grade goggle procurement for refinery maintenance operations.
Germany
Automotive and precision electronics clusters demand optical clarity standards exceeding baseline construction specifications. REACH substance restrictions on polycarbonate additives complicate formulation freedom for lens manufacturers serving industrial buyers. The Ruhr industrial corridor concentrates consolidated procurement through integrated facility management providers locking multi-site contracts.
China
Domestic chemical processing expansion and export-oriented manufacturing sustain dual demand tracks for impact-rated and sealed-periphery designs. MIIT oversees industrial safety equipment standards alignment with international certification protocols. Yangtze River Delta fabrication hubs supply polycarbonate lens blanks to European and North American eyewear finishers.
India
Production-linked incentives for industrial safety equipment create localized supply base potential for export-oriented suppliers. BIS certification requirements for personal protective equipment tighten product specifications for domestic procurement. Gujarat's chemical processing belt and Maharashtra's automotive clusters drive premium eyewear adoption among multinational facility operators.
Japan
Precision electronics and automotive manufacturing facilities specify anti-fog coatings and prescription insert compatibility. METI promotes JIS standards harmonization with ANSI Z87.1 and EN 166 frameworks to reduce dual-certification burdens. Kansai manufacturing corridors pilot photochromic lens technology at scale for welding and outdoor construction applications.
Industrial Eye Protection Market Vendor Landscape
Listed leaders compete with private specialists across certification bandwidth and integrated system capability. The vendor base stratifies between diversified industrial conglomerates controlling materials science platforms and focused safety equipment pure-plays. Three archetypes dominate: integrated materials-to-eyewear conglomerates, respiratory-vision integration specialists, and regional compliance-focused fabricators. Competitive moves concentrate on R&D intensity in coating technologies and geographic expansion through notified body partnerships for CE marking acceleration.
Within the integrated conglomerate tier, 3M Company and Honeywell International Inc. exemplify materials science control extending from polycarbonate synthesis to distribution network ownership. MSA Safety Incorporated occupies a distinct position anchoring the respiratory-vision integration archetype for confined-space applications. Among European-focused specialists, Uvex Safety Group and Delta Plus Group represent compliance-engineered portfolio breadth spanning ANSI, EN, and regional certification requirements.
| Leading Market Players |
|---|
| 3M Company |
| Honeywell International Inc. |
| MSA Safety Incorporated |
| Uvex Safety Group |
| Bollé Safety |
| Pyramex Safety Products, LLC |
| Radians, Inc. |
| Delta Plus Group |
| MCR Safety |
| Others |
Supply Flow & Price Mechanics
Photochromic lens substitution for fixed-tint alternatives is redrawing procurement geography and pricing power across industrial eye protection, as adaptive optics consolidate indoor-outdoor SKUs and compress distributor inventory positions while raising unit economics for manufacturers with coating mastery.
Pricing Analysis
Technology-generation pricing gaps separate legacy fixed-tint safety glasses from emerging photochromic and smart eyewear tiers. Three-tier pricing structure across premium, standard, and economy levels stratifies by ANSI Z87.1 certification grade and anti-fog coating durability. Cost compression in economy safety glasses intensifies because Asian polycarbonate suppliers are expanding molding capacity. Chemical processing plants exhibit the lowest price sensitivity due to vapor-exposure liability, while residential construction contractors face acute budget constraints.
Supply Chain Analysis
Just-in-time inventory preferences dominate downstream distribution, though raw material volatility is forcing strategic stockpiling of polycarbonate resin among tier-one manufacturers. Bisphenol A feedstock draws from China, South Korea, and Saudi Arabia. Lens fabrication depends on optical-grade polycarbonate pellets, anti-scratch coating chemicals, and injection molding equipment. Single-source vulnerability concentrates in German precision metrology labs for ANSI Z87.1 high-velocity testing. Distribution runs through integrated facility management providers and industrial distributors with specification-grade technical support.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Industrial eye protection sits in early-cycle expansion as chemical processing plants unwind construction's procurement dominance and specification upgrades accelerate across hazardous environments.
For Market Incumbents: Secure coating technology leadership through captive R&D in anti-fog and photochromic formulations before REACH restrictions tighten further. Anchor distribution relationships with Sodexo and ISS Facility Services to lock multi-site contracts across Germany's Ruhr corridor. Defend against respiratory-vision integration specialists by accelerating confined-space system interoperability investments. For New Entrants and Emerging Players: CE marking fast-track partnerships with German notified bodies compress time-to-market for Category III eye protection by 8-14 months. India's PLI scheme for manufacturing offers the most penetrable geography for export-oriented supply base establishment. Target mid-size chemical processors through direct-to-facility e-commerce channels that disintermediate legacy industrial distributors. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors materials-science conglomerates with backward integration into polycarbonate synthesis. Long-term viability rests on certification bandwidth spanning ANSI, EN, and emerging Asian standards rather than single-region compliance. Watch for REACH substance restriction announcements on bisphenol derivatives as the inflection signal forcing parallel product line investments.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polycarbonate Resin | Captive Bisphenol A supply insulates margin from Asian petrochemical volatility and tariff exposure. |
| Notified Body Partnership for CE Acceleration | German laboratory alliances compress Category III eye protection certification timelines for European market access. |
| Smart Eyewear Sensor Integration | Proximity detection and fatigue monitoring modules open premium positioning in logistics and heavy machinery. |
| Integrated Facility Management Contracting | Multi-site agreements with Sodexo and ISS lock specification authority across chemical and automotive portfolios. |
| Photochromic Coating Capacity Expansion | Adaptive lens production scales meet automotive and precision electronics pilot demand in Germany and Japan. |
Methodological Framework
Operator-level perspectives from plant safety officers, procurement leads at chemical processors, distribution channel partners, and optical metrology laboratory directors anchored the qualitative base for this study. Primary fieldwork combined structured interviews with secondary validation through OSHA enforcement data, ANSI Z87.1 certification registries, EU PPE Regulation 2016/425 conformity assessments, and customs trade records for polycarbonate lens blanks. Bottom-up demand modeling across end-use segments triangulated with top-down market sizing from industrial safety equipment trade associations.
Sensitivity analysis tested volume and value outputs across the projection horizon against feedstock price volatility and regulatory timeline scenarios. Segmentation dimensions modeled include product type, application vertical, material formulation, and end-user procurement authority. CAGRs derived from segment-level growth trajectory analysis incorporating substitution dynamics between safety glasses, goggles, and face shields. Forecast inputs integrated REACH substance restriction timelines and India's PLI scheme uptake rates.
Decision-makers should treat outputs as directional under stable OSHA enforcement and REACH implementation assumptions; material deviation would warrant model refresh. Forecasts reflect these documented assumptions about certification divergence persistence and polycarbonate supply concentration. Revision becomes warranted when Bisphenol A regulatory restrictions or tariff regimes cross thresholds that alter feedstock economics.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Workplace Safety
Global Industrial Safety Footwear Market
Workplace Safety
Industrial Protective Footwear Market
Workplace Safety
Industrial and Workplace Safety Market
Workplace Safety
Workplace Safety Market
Workplace Safety
Safety Glasses Market
Workplace Safety
Industrial Safety Mats Market
Workplace Safety
Machine Safety Market
Workplace Safety
Construction Worker Safety Market
Workplace Safety
Industrial Head Protection Market
Workplace Safety
Middle East Industrial Protective Footwear Market
Workplace Safety
Safety Vest Market
Workplace Safety
Safety Helmets Market
Workplace Safety
Industrial Safety Market
Workplace Safety
Industrial Safety Gloves Market
Workplace Safety
Canada Safety Services Market
Workplace Safety
Industrial Hand Protection Gloves Market