
 Construction Worker Safety Market | 2026-2036
Construction Worker Safety Market Size, Share, and Industry Trends Forecast 2026-2036
Construction Worker Safety Market Analysis
Specialty safety distributors is reshaping how construction sites source protective equipment, consolidating fragmented procurement into national accounts with technical service layers. Ansell Limited leverages its vertically integrated glove manufacturing to sustain margin advantages in cut-resistant and chemical-handling categories. MSA Safety Incorporated anchors its position through respiratory protection systems that integrate gas detection with connected monitoring platforms. Honeywell International Inc. competes across the full PPE stack, from hard hats to fall-arrest systems, extending its industrial automation brand into site-safety workflows.
Construction worker safety encompasses engineered equipment and systems designed to prevent injury, exposure, and fatality during building, infrastructure, and demolition activities, spanning impact-rated helmets meeting ANSI Z89.1 standards, harnesses tested to 5,000-pound tensile loads, and sensor-enabled garments that transmit biometric and environmental data to centralized dashboards. Its primary commercial purpose is regulatory compliance and liability reduction for employers operating in high-hazard environments. Protective gloves and safety helmets command the largest revenue pools due to universal mandating across trades and shorter replacement cycles from abrasion and impact degradation. Wearable devices within the installation dimension represent the fastest structural expansion, as accelerometers, GPS beacons, and environmental sensors shift safety management from reactive incident response to predictive hazard intervention.
OSHA enforces permissible exposure limits and fall-protection standards that directly dictate product specifications and site-level purchasing minimums, while the European Union's CE marking and PPE Regulation (EU) 2016/425 govern market access for equipment sold across member states. ISO 45001 certification requirements are pushing general contractors to document safety-system performance, creating audit-trail demand for connected PPE with data-logging capabilities. Stakeholders must evaluate whether their product portfolios align with the migration from passive protection to real-time, data-generating safety infrastructure before procurement specifications lock in vendor selections.
Market Dynamics
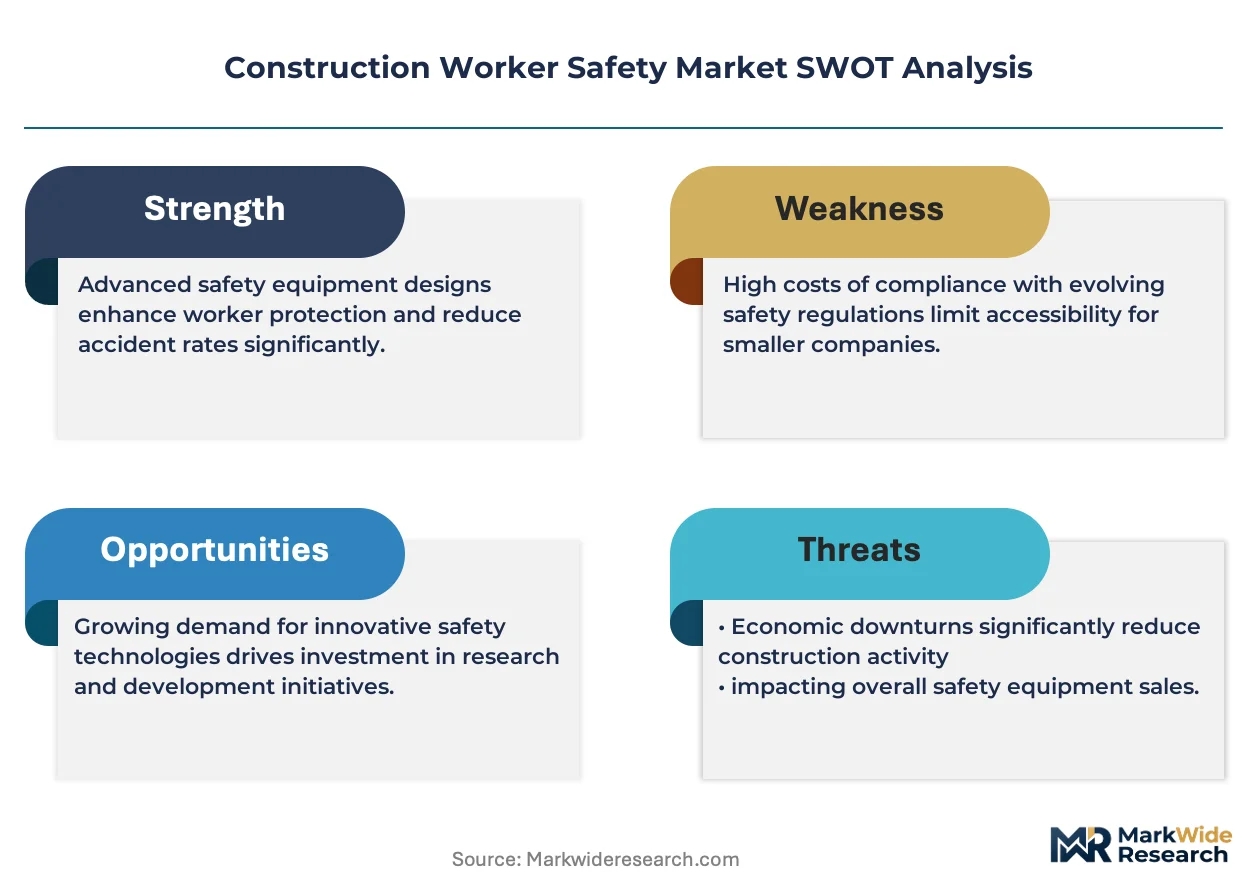
Connected PPE platforms are collapsing the traditional boundary between personal protection and site-wide risk management, forcing equipment vendors to restructure around data services rather than hardware margins.
Growth Catalysts
- OSHA Silica Rule Enforcement:Stricter respirator mandates on American jobsites are accelerating replacement cycles for dust-control equipment and powered air-purifying respirators across concrete cutting and demolition trades.
- Biometric Garment Adoption:Sensor-embedded vests and hard hats transmitting heat stress and fall detection data are penetrating commercial high-rise construction in dense urban corridors.
- Federal Infrastructure Spending:Bridge and highway appropriations in the United States are compressing safety-equipment procurement timelines for general contractors managing multiple simultaneous projects.
Market Restraints
- Semiconductor Supply Concentration:Taiwan and South Korea fabrication dominance creates vulnerability for connected PPE sensor arrays and gas detection chipsets.
- Raw Material Volatility:Aramid fiber and high-performance polymer prices fluctuate with petroleum feedstock costs, squeezing margin on cut-resistant gloves and ballistic helmets.
- Interoperability Limitations:Proprietary data protocols from competing platform vendors fragment site-level dashboard integration, slowing unified safety system deployment.
Strategic Opportunities
- India Infrastructure Build-Out:Metro rail and smart city projects under the country's central government capital expenditure programs are opening demand for ANSI-equivalent helmets and fall-arrest systems.
- ISO 45001 Certification Tailwind:Third-party audit requirements for occupational health management systems are creating pull for PPE with embedded data-logging and incident-traceability features.
- AI-Computer Vision Convergence:Hard hat-mounted cameras with edge-processing capability are enabling real-time hazard recognition without centralized server dependency.
Industry Challenges
- Embedded Systems Engineering Gap:Shortage of firmware developers with industrial IoT experience delays connected safety product roadmaps for traditional PPE manufacturers.
- CE Marking Timeline Compression:EU 2016/425 PPE Regulation conformity assessment bottlenecks at notified bodies extend market entry schedules for respiratory and chemical-protective equipment.
- Legacy Equipment Integration Friction:Retrofitting sensor networks onto existing hard hats and harness inventories requires custom mounting solutions that complicate warranty and liability frameworks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Construction Worker Safety Market |
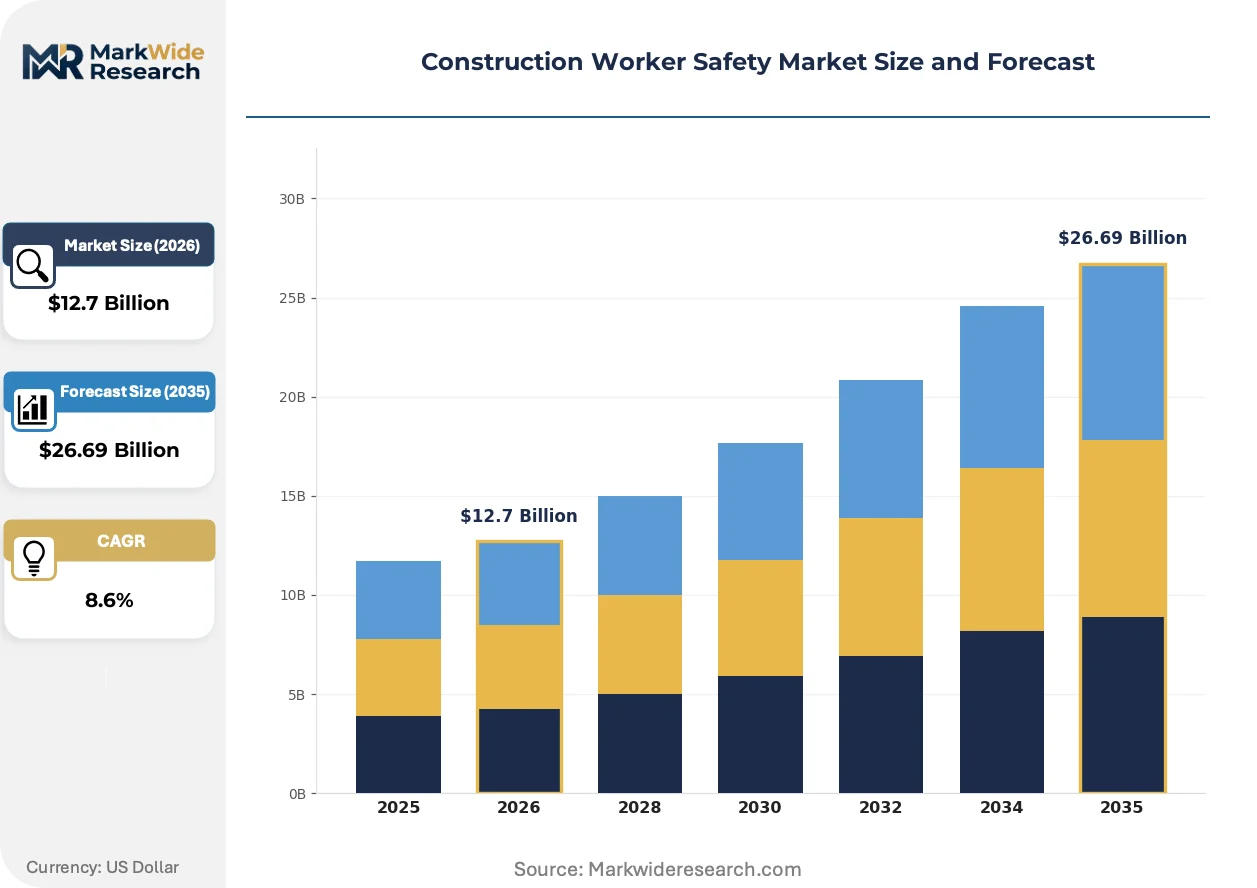
| Market Size in 2026 | $12.7 Billion |
| Market Size in 2035 | $26.69 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Safety Helmets, Protective Gloves, Safety Harnesses, High-Visibility Vests End User: General Contractors, Subcontractors, Construction Workers, Safety Managers Application: Site Safety, Personal Protection, Equipment Safety, Emergency Response Installation: Wearable Devices, Monitoring Systems, Safety Signage, Barrier Systems |
| Companies Covered | Ansell Limited, DuPont, Honeywell International Inc., Drägerwerk AG & Co. KGaA, W. L. Gore & Associates, 3M Company, Hilti AG, Lakeland Industries, MSA Safety Incorporated, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Construction Worker Safety Market Emerging Trajectories
Sensor miniaturization and edge computing are dissolving the hardware-software boundary in protective equipment, converting standalone gear into networked safety nodes.
Gas detection microsensors embedded directly into hard hat shells are collapsing the distinction between respiratory protection and atmospheric monitoring. General contractors on petrochemical and confined-space projects are piloting these integrated units ahead of standard procurement cycles. The technology is collapsing redundant device layers and consolidating vendor relationships around single-platform suppliers.
EU 2016/425 PPE Regulation updates are mandating modular design standards for chemical-protective suits and respiratory equipment to enable component-level replacement. Industrial laundries and rental service providers across Germany and France are restructuring maintenance contracts around these interchangeability requirements. European specialty distributors are expanding technical service teams to manage compliance documentation for modular system configurations.
Site-level procurement consolidation is compressing supplier relationships from fragmented local purchases to national account structures with embedded training and certification services. Large general contractors in the United States are unbundling safety equipment from traditional industrial distribution and contracting directly with manufacturers for multi-year fleet management agreements. This pattern is most visible on federal infrastructure megaprojects where bonding requirements and safety performance metrics dominate vendor selection criteria.
Construction Worker Safety Market Segmentation
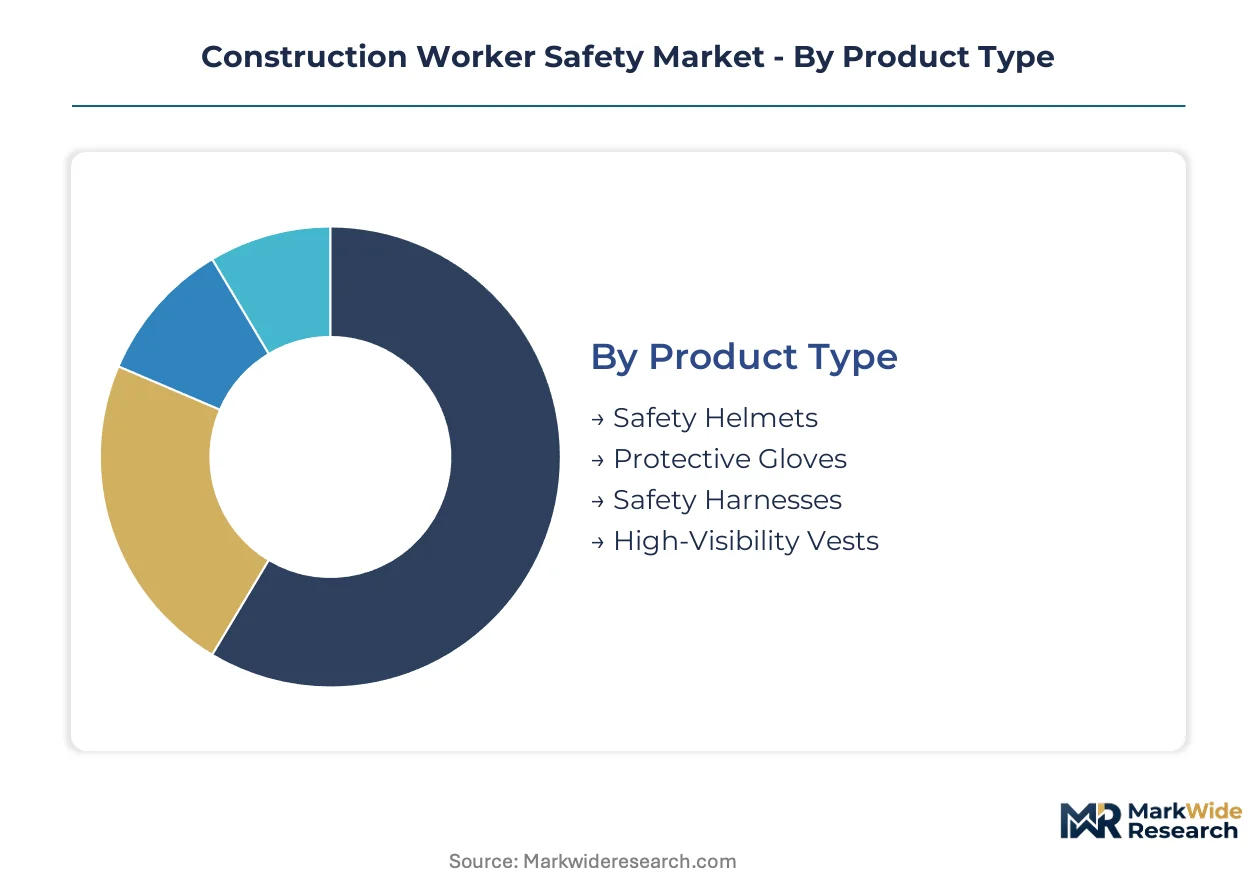
Segmentation in construction worker safety reveals how procurement cycles, liability exposure, and technology adoption vary across equipment categories and user types. Understanding these divisions helps vendors align product roadmaps with replacement rhythms and compliance mandates.
Product Type:
Replacement cycles range from weeks for abrasion-degraded gloves to years for impact-rated helmets, creating divergent margin and service attachment opportunities.
- Safety Helmets:Injection-molded ABS or HDPE shells meeting ANSI Z89.1 Type I/II standards dominate commercial and industrial sites. Demand concentrates in United States federal infrastructure corridors where bonding requirements mandate documented head protection compliance.
- Protective Gloves:Cut-resistant aramid blends and chemical-handling nitrile formulations face the shortest replacement windows from abrasion and permeation degradation. High-rise concrete and masonry trades in dense urban centers drive volume through rapid turnover.
- Safety Harnesses:Full-body designs with dorsal D-rings and shock-absorbing lanyards tested to 5,000-pound tensile loads serve fall-arrest applications.
- High-Visibility Vests:ANSI/ISEA 107 Class 2 and Class 3 polyester mesh or solid fabrics with retroreflective striping address struck-by hazards.
Protective gloves dominate installed base volume through sheer replacement frequency. Safety helmets are where expansion concentrates as smart-shell platforms penetrate commercial high-rise projects.
End User:
Procurement authority and technical sophistication vary sharply across this dimension, from enterprise fleet managers to individual trade workers.
- General Contractors:Multi-project operators with bonding requirements and OSHA recordable incident exposure drive national account consolidation. These buyers demand integrated training, certification documentation, and multi-year fleet management structures.
- Safety Managers:Site-level compliance officers with direct OSHA interaction specify equipment to satisfy inspection protocols and incident investigation needs. Their influence is climbing fastest as ISO 45001 certification requirements expand audit-trail demands.
- Subcontractors:Trade-specific operators in electrical, mechanical, and concrete disciplines purchasing for defined-scope engagements.
- Construction Workers:Individual end-users whose direct feedback on fit, comfort, and durability shapes repeat procurement decisions.
General contractors dominate contract value through consolidated purchasing. Safety managers are gaining decision authority fastest as data-logging and traceability requirements tighten.
Application:
Functional purpose determines specification intensity, from universal-mandate baseline protection to incident-triggered emergency systems.
- Site Safety:Collective protection systems including guardrails, netting, and warning lines that shield multiple workers simultaneously. Federal highway and bridge projects in the United States compress procurement timelines for these systems.
- Personal Protection:Individual equipment assignments including respiratory, head, hand, and foot protection governed by OSHA permissible exposure limits. This segment spans the widest user base across all construction trades.
- Equipment Safety:Lockout-tagout devices, machine guarding, and tool tethering systems protecting against mechanical hazards.
- Emergency Response:Self-contained breathing apparatus, rescue harnesses, and first-aid stations deployed for confined-space and height-rescue scenarios.
Personal protection commands the broadest installed base through universal mandating. Site safety systems are expanding most quickly as general contractors consolidate vendor relationships around single-platform suppliers.
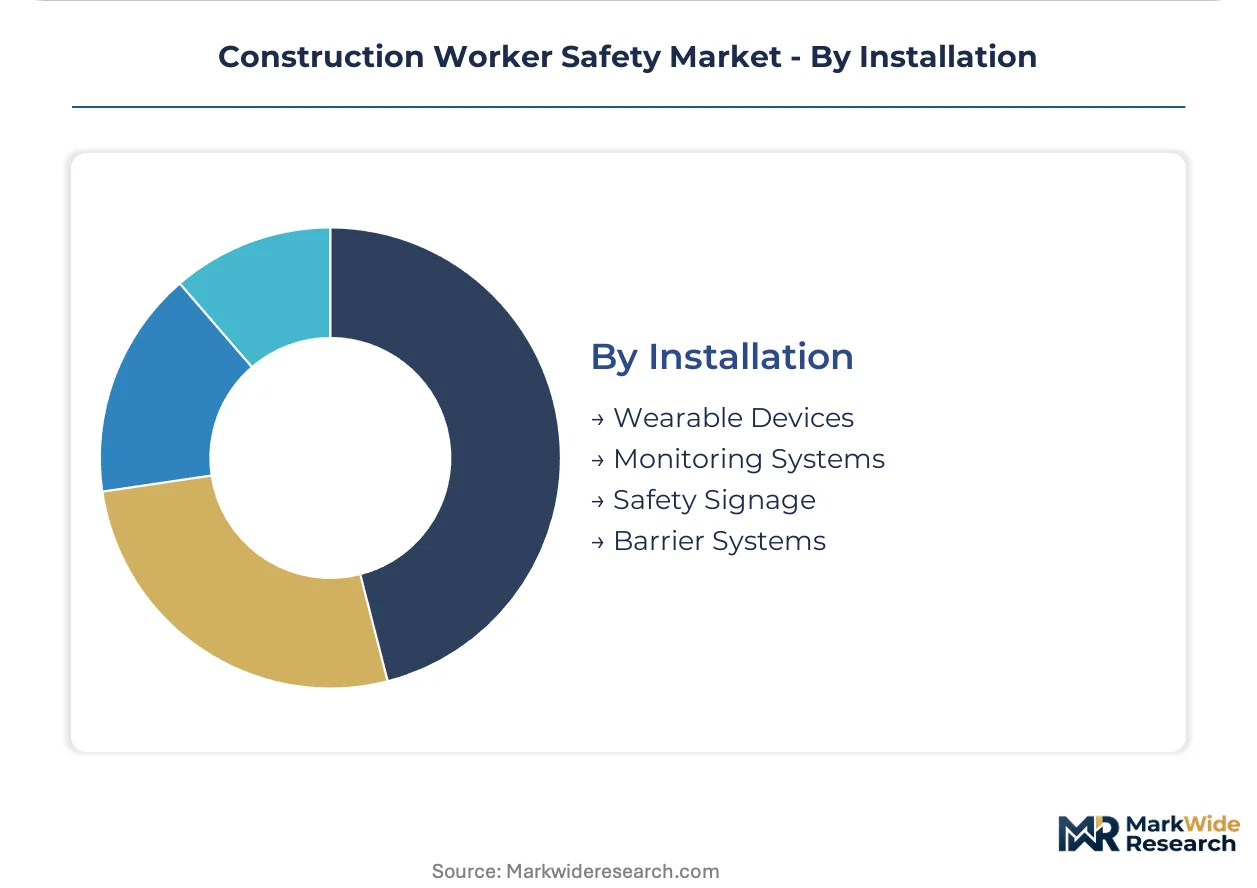
Installation:
Physical deployment mode separates passive protective elements from active monitoring infrastructure with data-generation capabilities.
- Wearable Devices:Sensor-embedded hard hats, biometric vests, and GPS-enabled badges transmitting heat stress, fall detection, and location data. Commercial high-rise construction in dense urban corridors pilots these units ahead of standard procurement cycles.
- Monitoring Systems:Centralized dashboards aggregating wearable outputs with gas detection and environmental sensors for predictive hazard intervention. These platforms are displacing reactive incident response workflows.
- Safety Signage:ANSI Z535-compliant visual warnings and directional markers for hazard communication.
- Barrier Systems:Physical separation including temporary fencing, trench boxes, and debris netting.
Barrier systems dominate physical footprint on active sites. Wearable devices are where technology investment concentrates as edge computing and sensor miniaturization mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Federal infrastructure appropriations in the United States are compressing safety-equipment procurement timelines. OSHA's updated silica exposure rules are tightening respirator mandates across American jobsites. Commercial high-rise density in urban centers worldwide is accelerating smart PPE pilot programs.
United States
Bridge and highway megaprojects under the Infrastructure Investment and Jobs Act are driving fleet-level safety-equipment replacement. OSHA enforces permissible exposure limits and fall-protection standards that dictate product specifications and purchasing minimums. General contractors in Texas and California are consolidating vendor relationships around national accounts with embedded training services.
Germany
Industrial construction and chemical plant maintenance sustain demand for chemical-protective suits and respiratory systems. The EU 2016/425 PPE Regulation governs market access with CE marking requirements for equipment sold across member states. Specialty distributors in the Ruhr industrial cluster are expanding technical service teams to manage modular system compliance documentation.
China
Metro rail and smart city projects under central government capital expenditure programs are opening demand for impact-rated helmets and fall-arrest systems. GB standards and MIIT regulations establish technical specifications for domestically manufactured safety equipment. Construction activity in the Yangtze River Delta is concentrating procurement for high-rise commercial developments.
India
Urban infrastructure build-out under the central government's capital expenditure programs is creating demand for ANSI-equivalent protective equipment. BIS certification requirements establish quality benchmarks for safety products sold in domestic markets. Metro rail construction in Maharashtra and Karnataka is driving volume for site safety systems and personal protection gear.
United Arab Emirates
Expo legacy developments and NEOM-scale megaprojects are sustaining demand for high-specification fall-protection and atmospheric monitoring equipment. MOHAP and local emirate-level regulations mandate compliance with international safety standards on major construction sites. Dubai's commercial high-rise pipeline is piloting sensor-enabled hard hats and biometric monitoring vests ahead of standard procurement cycles.
Construction Worker Safety Market Vendor Landscape
On the supply side, the industry is consolidating around integrated platform providers that bundle hardware with data services. Specialty distributors with technical service capabilities are capturing procurement relationships from fragmented local suppliers. Three archetypes dominate: vertically integrated manufacturers controlling raw material inputs, full-stack industrial conglomerates spanning multiple PPE categories, and connected-safety platform vendors restructuring around software margins. Competitive moves center on national account consolidation and sensor-platform partnerships that embed vendors within multi-year fleet management structures.
Within the integrated manufacturing tier, Ansell Limited and DuPont exemplify material-science specialists leveraging captive fiber and polymer production. Honeywell International Inc. anchors the full-stack conglomerate position across head, hand, and fall-protection categories. MSA Safety Incorporated occupies a position within the connected-safety platform segment, representing the shift from standalone respiratory equipment to integrated gas detection and monitoring systems.
| Leading Market Players |
|---|
| Ansell Limited |
| DuPont |
| Honeywell International Inc. |
| Drägerwerk AG & Co. KGaA |
| W. L. Gore & Associates |
| 3M Company |
| Hilti AG |
| Lakeland Industries |
| MSA Safety Incorporated |
| Others |
Supply Flow & Price Mechanics
Trans-Pacific container freight corridors linking Shanghai to Los Angeles and Long Beach impose cost volatility that amplifies pricing spreads between domestic-certified and import-equivalent safety equipment. This logistics pressure concentrates margin leverage with distributors holding bonded warehouse inventory near United States federal infrastructure corridors.
Pricing Analysis
Certification level (ANSI Z89.1/CE marking tier) creates the primary spread between premium and standard safety helmets. Three-tier pricing structure across premium, standard, and economy levels dominates, with connected PPE platforms commanding recurring SaaS fees atop hardware margins. Cost compression in the economy tier is intensifying because Chinese manufacturers with BIS-equivalent certification are penetrating Indian metro rail projects. Subcontractors purchasing for single-scope engagements exhibit highest price sensitivity; general contractors with national accounts and bonding requirements show lowest.
Supply Chain Analysis
Tariff exposure between China and the United States dominates supply chain risk planning for aramid fiber and injection-molded shell components. Manufacturing concentrates in China, Taiwan, and South Korea for sensor arrays and gas detection chipsets; Vietnam and Bangladesh are expanding cut-resistant glove stitching capacity. Raw material dependencies center on petroleum-derived polymers, high-tenacity aramid fibers, and semiconductor wafers. Distribution runs through specialty safety distributors with technical service capabilities rather than fragmented local procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Connected PPE platforms transform one-time hardware transactions into multi-year fleet management relationships where training, certification documentation, and dashboard analytics generate recurring revenue expanding faster than equipment replacement cycles.
For Market Incumbents: Insulate core respiratory and fall-protection franchises by embedding firmware teams to close the embedded systems engineering gap delaying rival product roadmaps. Pursue backward integration into aramid fiber production to offset petroleum feedstock volatility squeezing cut-resistant glove margins. Anchor national account structures with ISO 45001 audit-trail documentation that raises switching costs for general contractors managing federal infrastructure megaprojects. For New Entrants and Emerging Players: Establish a beachhead in India's metro rail and smart city build-out where BIS certification requirements are less entrenched than ANSI-equivalent standards in mature markets. Target safety manager decision authority segments gaining procurement influence fastest through data-logging and traceability mandates. Deploy direct-to-contractor digital channels bypassing legacy specialty distributor relationships concentrated in the United States and Germany. For Investors and Strategic Acquirers: Sensor-platform vendors with captive gas detection algorithms and established API partnerships represent the highest-conviction acquisition archetype for consolidation plays. Long-term viability hinges on defensible data-layer revenue rather than hardware commoditization across the projection horizon. Watch for CE marking timeline compression at EU notified bodies as an inflection indicator signaling regulatory moat widening for compliant incumbents.| Strategic Initiative | Industry Significance |
|---|---|
| Connected Platform Integration | Collapses hardware-software boundaries into recurring SaaS revenue streams for MSA Safety and Honeywell. |
| Backward Integration into Aramid Fiber | Captures margin otherwise lost to petroleum feedstock volatility affecting Ansell and DuPont glove production. |
| ISO 45001 Certification Tailwind | Creates audit-trail demand pulling data-logging PPE into general contractor national accounts. |
| India Infrastructure Beachhead | Opens volume for ANSI-equivalent helmets and fall-arrest systems in Maharashtra and Karnataka metro projects. |
| CE Marking Compliance Investment | Extends market entry barriers at EU notified bodies for respiratory and chemical-protective equipment categories. |
Methodological Framework
The analysis maps smart PPE platforms, traditional protective equipment, and site safety systems, each validated through safety managers, general contractor procurement leads, specialty distributor technical service teams, and OSHA compliance officers. Primary interview intelligence triangulates against secondary sources including OSHA enforcement data, EU 2016/425 PPE Regulation conformity assessment records, SEC 10-K filings from listed safety equipment manufacturers, and federal infrastructure appropriations documentation. Bottom-up segment sizing and top-down macro validation converge through iterative reconciliation.
Assumptions held fixed across the modeling period include OSHA silica rule enforcement intensity, federal infrastructure spending authorization levels, and semiconductor fabrication capacity concentration in Taiwan and South Korea. Variables allowed to fluctuate encompass aramid fiber pricing, CE marking timeline durations, and India BIS certification adoption rates. Segmentation dimensions span product type, end-user archetype, application purpose, and installation mode. CAGRs derive from replacement cycle analysis, technology penetration curves, and regulatory mandate implementation schedules.
Stress conditions across raw material cost bands, tariff rate scenarios, and notified body capacity constraints were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions subject to revision from regulatory enforcement shifts, supply chain restructuring, or platform interoperability breakthroughs. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Workplace Safety
Safety Vest Market
Workplace Safety
Safety Glasses Market
Workplace Safety
Industrial Hand Protection Gloves Market
Workplace Safety
Global Industrial Safety Footwear Market
Workplace Safety
Canada Safety Services Market
Workplace Safety
Industrial Safety Gloves Market
Workplace Safety
Industrial and Workplace Safety Market
Workplace Safety
Industrial Eye Protection Market
Workplace Safety
Industrial Head Protection Market
Workplace Safety
Machine Safety Market
Workplace Safety
Middle East Industrial Protective Footwear Market
Workplace Safety
Safety Helmets Market
Workplace Safety
Industrial Safety Market
Workplace Safety
Industrial Safety Mats Market
Workplace Safety
Industrial Protective Footwear Market
Workplace Safety
Workplace Safety Market