
 Industrial and Workplace Safety Market | 2026-2036
Industrial and Workplace Safety Market Size, Share, and Industry Trends Forecast 2026-2036
Industrial and Workplace Safety Market Foresight
Modular safety system bundling is consolidating buyer preference across heavy industrial sites. Honeywell International Inc. leverages its integrated platform architecture to anchor large manufacturing contracts. 3M Company differentiates through material science depth in respiratory and hearing protection. MSA Safety Incorporated specializes in fixed gas detection and competes aggressively in oil and gas verticals.
Industrial and workplace safety encompasses engineered controls, protective equipment, and procedural safeguards designed to eliminate or mitigate occupational hazards, typically specified by impact resistance ratings, chemical permeation breakthrough times, and functional safety integrity levels per IEC 61508. Its primary purpose is preventing worker injury, equipment damage, and operational downtime in hazardous commercial environments. Personal protective equipment occupies the largest revenue pool among product types due to mandatory replacement cycles and broad cross-industry applicability. Wearable devices represent the fastest-expanding technology segment as biometric monitoring and real-time location tracking migrate from pilot programs to standard deployment. Training programs within service types remain structurally fragmented, with margin concentration held by providers bundling compliance consulting with digital delivery platforms.
OSHA standards in the United States, EU Machinery Directive and CE marking requirements in Europe, and China's GB standards administered by SAMR collectively shape product certification pathways and market access conditions for safety equipment suppliers. Regulatory divergence between jurisdictions forces manufacturers to maintain multiple testing protocols, elevating compliance costs but also creating defensive moats for certified incumbents. Stakeholders must monitor how AI-enabled hazard prediction interfaces with evolving functional safety standards before committing capital to next-generation platform investments.
Market Dynamics
Connected fall protection systems are consolidating procurement specifications across North American construction sites as OSHA tightens enforcement protocols and insurers demand verifiable compliance data streams.
Growth Catalysts
- EU Machinery Directive:German manufacturers must integrate automated safety sensors directly into production lines, forcing sensor suppliers to embed functional safety certification at the component level.
- Biometric monitoring:Wearable devices with real-time location tracking are migrating from pilot programs to standard deployment in oil and gas verticals.
- China:SAMR-administered GB standards are accelerating domestic certification requirements for imported respiratory protection equipment.
Market Restraints
- Semiconductor input volatility:Safety system microcontrollers face allocation constraints from automotive and consumer electronics demand pull.
- Testing protocol fragmentation:Regulatory divergence between OSHA, EU Machinery Directive, and China's GB standards forces manufacturers to maintain multiple certification pathways.
- Technical limitation:Gas detection sensor drift in high-humidity environments degrades fixed system reliability in Gulf Coast petrochemical corridors.
Strategic Opportunities
- India:Underpenetrated heavy manufacturing sectors present white space for respiratory protection bundling with BIS-certified training programs.
- AI-enabled hazard prediction:Convergence of computer vision and IEC 61508 functional safety architectures creates new platform licensing models.
- Digital delivery platforms:Compliance consulting bundled with virtual reality training is displacing classroom-only providers in fragmented service markets.
Industry Challenges
- Functional safety engineering talent:IEC 61508 SIL certification expertise concentrates in German and Swiss industrial clusters, creating recruitment bottlenecks.
- Legacy system integration:Brownfield manufacturing sites require custom gateway architectures to connect new sensor networks to existing SCADA infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Industrial and Workplace Safety Market |
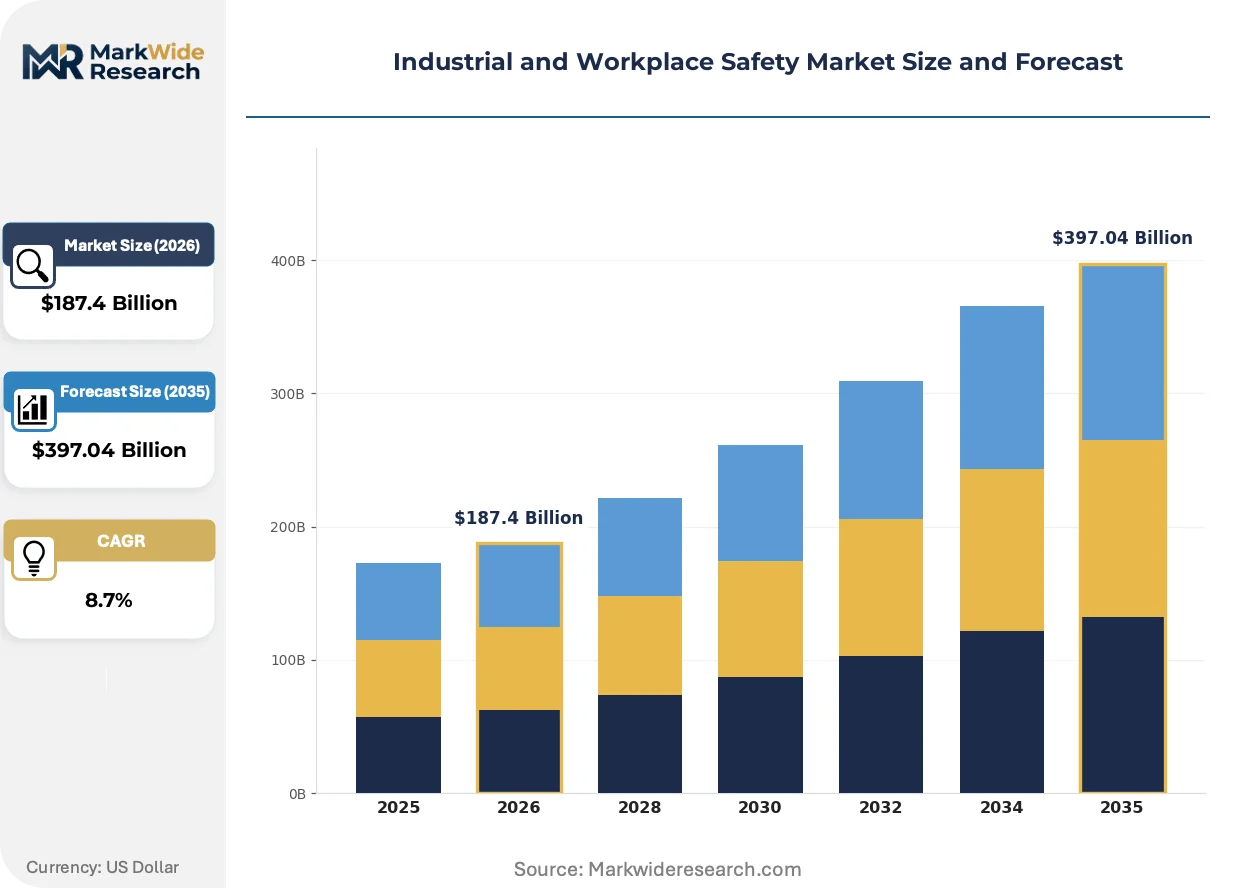
| Market Size in 2026 | $187.4 Billion |
| Market Size in 2035 | $397.04 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Personal Protective Equipment, Safety Signage, Safety Sensors, Fall Protection Systems End User: Manufacturing, Construction, Oil & Gas, Transportation Service Type: Training Programs, Risk Assessment, Incident Investigation, Compliance Consulting Technology: Wearable Devices, Automated Safety Systems, Air Monitoring Systems, Emergency Response Technologies |
| Companies Covered | Honeywell International Inc., 3M Company, MSA Safety Incorporated, DuPont de Nemours, Inc., Drägerwerk AG & Co. KGaA, Rockwell Automation, Inc., Siemens AG, Schneider Electric SE, ABB Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Industrial and Workplace Safety Market Shifts & Advancements
Wearable biometric technologies are compressing replacement cycles for traditional personal protective equipment while forcing incumbents to develop software competencies.
Computer vision systems with edge-based fall detection algorithms are rewriting site safety protocols. Construction firms in Texas and Alberta are deploying these systems on megaproject sites within eighteen-month procurement windows. The technology is compressing incident response times from minutes to seconds and displacing manual spotter roles in high-risk zones.
REACH substance restrictions are forcing reformulation of chemical protective garment materials. European manufacturers face accelerated testing timelines for permeation breakthrough compliance. The respiratory protection segment is absorbing the highest compliance costs as legacy activated carbon suppliers exit the market.
Buyer consolidation among multinational engineering-procurement-construction firms is compressing vendor qualification timelines. Tier-one contractors now mandate API-compatible data architectures for all connected safety equipment. This pattern is most visible in Middle Eastern petrochemical developments where single-source accountability clauses dominate tender specifications.
Industrial and Workplace Safety Market Segmentation
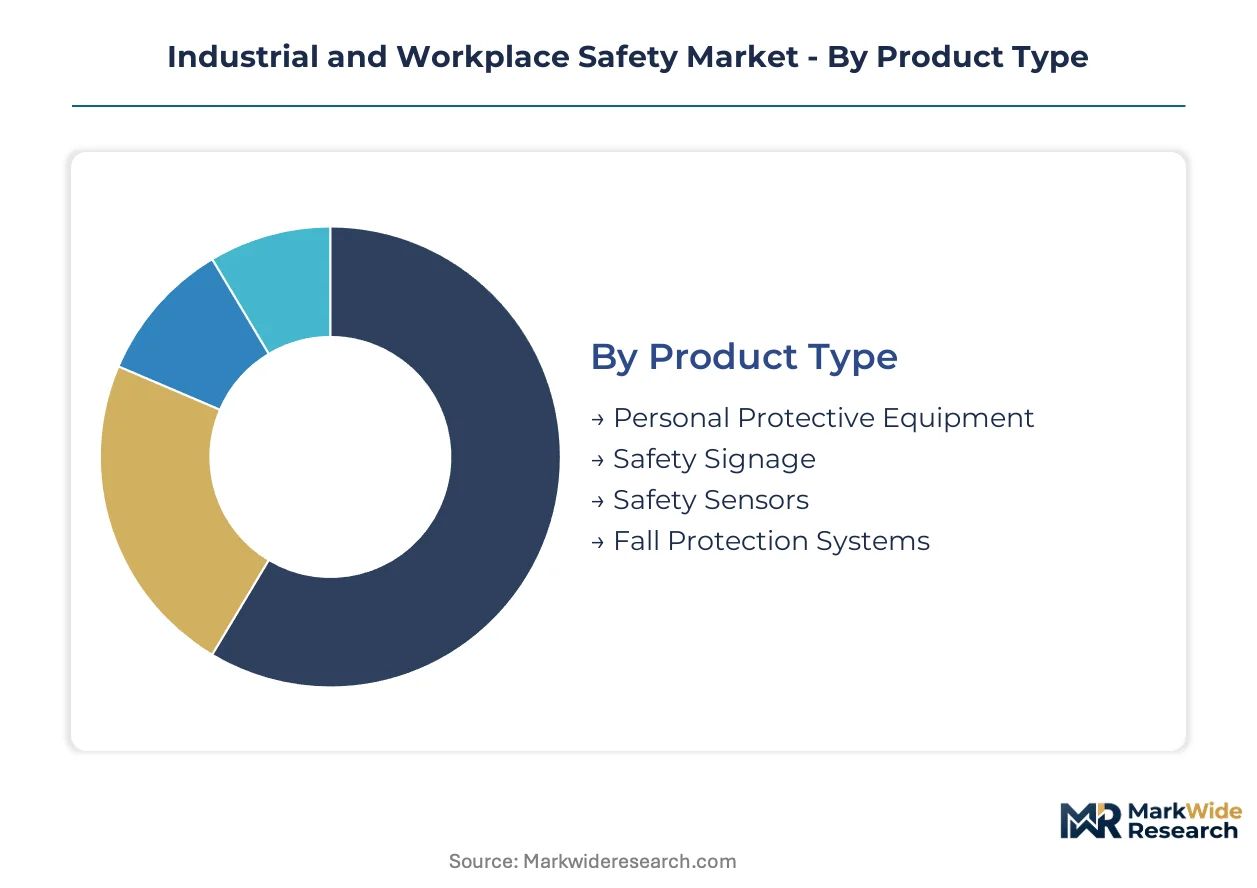
Segmentation in industrial safety reveals distinct procurement patterns across embedded versus standalone system architectures. Product type and technology dimensions show the clearest divergence between legacy replacement cycles and connected platform investments.
Product Type:
Standalone equipment dominates replacement-driven procurement, while embedded sensor networks require line-integrated installation contracts.
- Personal Protective Equipment:Comprises respiratory masks, hearing protection, and chemical-resistant garments with defined replacement intervals per OSHA exposure limits. Manufacturing facilities in Germany and construction sites across the United States drive volume through mandatory turnover schedules and bulk purchasing agreements.
- Fall Protection Systems:Harnesses, lanyards, and anchor points with integrated RFID tracking for compliance verification. North American construction firms are consolidating specifications around connected systems that stream data to insurer platforms.
- Safety Signage:Visual warning systems including photoluminescent egress markings and ANSI-compliant hazard labels.
- Safety Sensors:Proximity detectors and light curtains embedded directly into machinery per EU Machinery Directive requirements.
Personal Protective Equipment leads volumes today; Safety Sensors are gaining share fastest.
End User:
Capital intensity and regulatory exposure create divergent technology adoption curves across verticals.
- Manufacturing:Automated production lines in Germany and Switzerland absorb the highest sensor density per worker as BG ETAM standards mandate integrated safety architectures.
- Oil & Gas:Offshore platforms and Gulf Coast refineries deploy fixed gas detection networks with SIL-certified redundancy. High-humidity corrosion challenges in Louisiana and Texas corridors accelerate replacement cycles for electrochemical sensors.
- Construction:Project-based procurement favors rental models for fall protection with connected compliance tracking.
- Transportation:Warehouse logistics and aviation maintenance operations concentrate demand for hearing protection and high-visibility garments.
Manufacturing leads volumes today; Oil & Gas shows the steepest expansion trajectory for connected monitoring.
Service Type:
Margin concentration follows bundling depth, with standalone training commoditizing fastest.
- Compliance Consulting:Regulatory navigation across OSHA, EU Machinery Directive, and SAMR-administered GB standards for multinational equipment suppliers. Providers embedding digital delivery platforms capture recurring revenue streams.
- Training Programs:Virtual reality modules for hazard simulation are displacing classroom instruction in fragmented markets.
- Risk Assessment:Facility-wide hazard mapping with AI-enabled predictive analytics.
- Incident Investigation:Root-cause analysis services tied to insurance claim reduction.
Training Programs lead volumes today; Compliance Consulting is climbing the fastest on platform bundling.
Technology:
Hardware-software integration depth determines vendor switching costs and contract duration.
- Wearable Devices:Biometric monitors with real-time location tracking and physiological stress indicators. Oil and gas operators in Alberta and Texas are migrating from pilot deployments to fleet-wide standardization.
- Automated Safety Systems:Machine-integrated interlocks and collaborative robot fencing with IEC 61508 SIL certification. German automotive suppliers require component-level functional safety documentation.
- Air Monitoring Systems:Fixed and portable gas detection with wireless mesh networking.
- Emergency Response Technologies:Mass notification systems and connected lone-worker alarms.
Air Monitoring Systems lead volumes today; Wearable Devices are expanding most quickly on biometric standardization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Industrial safety systems trace their modern codification to nineteenth-century British factory inspectors, yet contemporary demand concentrates where manufacturing density intersects with stringent regulatory enforcement. Today's procurement patterns reflect this heritage across five critical national markets.
United States
OSHA enforcement tightening drives connected fall protection procurement across Texas and Gulf Coast petrochemical corridors. The agency's digitized inspection protocols now require verifiable compliance data streams from construction sites. Houston refineries deploy fixed gas detection networks with SIL-certified redundancy despite high-humidity sensor drift challenges.
Germany
Automotive suppliers in Bavaria and Baden-Württemberg absorb the highest safety sensor density per worker globally. BG ETAM standards mandate integrated safety architectures directly into production lines. Stuttgart's machine tool clusters force component-level functional safety certification from embedded sensor suppliers.
China
SAMR-administered GB standards accelerate domestic certification requirements for imported respiratory protection equipment. Yangtze River Delta manufacturing hubs absorb connected monitoring systems as provincial environmental bureaus tighten workplace exposure limits. Shanghai's chemical parks drive fleet standardization of biometric wearables.
India
BIS certification requirements create defensive moats for respiratory protection bundling with certified training programs. Maharashtra's heavy manufacturing sectors present underpenetrated white space for integrated safety platforms. Mumbai-Pune industrial corridor firms face escalating insurer demands for verifiable hazard mitigation documentation.
United Arab Emirates
Middle Eastern petrochemical developments mandate API-compatible data architectures for all connected safety equipment. Dubai and Abu Dhabi megaprojects concentrate single-source accountability clauses in tender specifications. ADNOC-led developments compress vendor qualification timelines through multinational engineering-procurement-consolidation.
Industrial and Workplace Safety Market Competitive Landscape
The competitive structure tilts toward diversified industrial conglomerates with platform integration capabilities. Consolidation pressures favor vendors bundling hardware, software, and compliance services under single-source contracts. Three archetypes dominate: integrated platform architects, material science specialists, and functional safety engineering houses. M&A activity concentrates on sensor technology acquisitions and vertical software stack integration.
Within the integrated platform tier, Honeywell International Inc. and 3M Company occupy positions anchored by cross-industry procurement relationships. MSA Safety Incorporated exemplifies the functional safety specialization archetype, sitting within oil and gas verticals where fixed gas detection requirements concentrate. Rockwell Automation, Inc. and Siemens AG represent the automation-to-safety convergence pattern, embedding safety architectures directly into control system hierarchies.
| Leading Market Players |
|---|
| Honeywell International Inc. |
| 3M Company |
| MSA Safety Incorporated |
| DuPont de Nemours, Inc. |
| Drägerwerk AG & Co. KGaA |
| Rockwell Automation, Inc. |
| Siemens AG |
| Schneider Electric SE |
| ABB Ltd |
| Others |
Supply & Pricing Matrix
Buyer consolidation among multinational engineering-procurement-construction firms is compressing vendor qualification timelines and forcing suppliers to absorb upfront certification costs. This procurement concentration shifts pricing power toward tier-one contractors while squeezing margins for component manufacturers unable to bundle hardware with compliance services.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates connected safety equipment procurement, with differentiation anchored in SIL certification grade and after-sales service bundling. Premium tiers command substantial markups for IEC 61508-certified architectures with embedded functional safety documentation. Price erosion runs through economy-tier respiratory protection as legacy activated carbon suppliers exit and Chinese manufacturers expand GB-certified export capacity. Construction rental fleets show highest price sensitivity, while German automotive suppliers demonstrate lowest sensitivity due to mandated BG ETAM compliance requirements.
Supply Chain Analysis
Regional distribution centers in Rotterdam, Singapore, and Houston anchor hub-and-spoke patterns for safety equipment fulfillment. Manufacturing concentration in China, Germany, and the United States shapes component availability, with German machine tool clusters supplying precision safety sensors and Chinese facilities dominating respiratory mask production. Semiconductor microcontrollers for safety systems draw from Taiwanese and South Korean foundries, creating single-source vulnerability during automotive demand surges. Distribution runs through certified distributor networks requiring documented chain-of-custody for regulated products.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The industrial and workplace safety market compounds steadily as regulatory enforcement tightens across OSHA, EU Machinery Directive, and SAMR jurisdictions. Mandatory replacement cycles and connected compliance mandates create predictable revenue streams for positioned suppliers.
For Market Incumbents: Hedge against semiconductor input volatility through strategic inventory positions and alternative microcontroller sourcing from industrial-grade suppliers. Consolidate position in German automotive safety sensor clusters where BG ETAM standards and IEC 61508 SIL certification expertise create defensive moats against Asian competitors.
For New Entrants and Emerging Players: Launch via digital delivery platforms bundling virtual reality training with BIS-certified compliance consulting in India's underpenetrated Maharashtra manufacturing corridor. Target oil and gas biometric wearable standardization in Alberta and Texas where pilot-to-fleet migration creates immediate replacement demand.
For Investors and Strategic Acquirers: Asymmetric upside sits with functional safety engineering houses possessing IEC 61508 SIL certification capabilities concentrated in German and Swiss industrial clusters. Monitor AI-enabled hazard prediction platform licensing models as inflection indicator for next-generation safety architecture adoption.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Sensor Manufacturing | Captures margin from safety-critical microcontroller supply constrained by automotive demand pull. |
| Platform Integration with SCADA Systems | Addresses brownfield manufacturing demand for custom gateway architectures connecting new sensor networks. |
| Acquisition of Functional Safety Engineering Firm | Secures scarce IEC 61508 SIL certification expertise concentrated in Stuttgart and Zurich clusters. |
| Geographic Expansion into Indian BIS Certification | Establishes defensive moat for respiratory protection bundling with certified training programs. |
| Strategic Partnership with Insurer Data Platforms | Enables connected fall protection procurement specifications requiring verifiable compliance data streams. |
Research Methodology
Bottom-up end-use modeling reconciled against top-down supply-side tracking forms the analytical core of this study. Primary interviews with plant engineers, EHS directors, OEM procurement teams, and aftermarket service heads informed demand-side assumptions. Secondary validation drew from OSHA enforcement databases, EU Machinery Directive implementation reports, SAMR GB standard filings, and customs trade records for respiratory protection equipment. Cross-referencing bottom-up facility-level estimates against top-down manufacturer shipment data ensured dimensional consistency.
Input-output matrices mapped safety equipment procurement across manufacturing, oil and gas, construction, and transportation verticals. Segmentation dimensions included product type, technology architecture, service bundling depth, and regional regulatory cluster. CAGRs were derived from elasticity-adjusted demand curves incorporating replacement cycle dynamics and connected platform adoption rates. Forecast inputs incorporated semiconductor allocation constraints, REACH substance restriction timelines, and insurer compliance data requirements.
Forecast precision tightens around the base case; tail outcomes carry wider variance under tariff escalation or prolonged semiconductor supply disruption. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Workplace Safety
Industrial Safety Gloves Market
Workplace Safety
Industrial Safety Mats Market
Workplace Safety
Middle East Industrial Protective Footwear Market
Workplace Safety
Safety Glasses Market
Workplace Safety
Global Industrial Safety Footwear Market
Workplace Safety
Safety Helmets Market
Workplace Safety
Machine Safety Market
Workplace Safety
Construction Worker Safety Market
Workplace Safety
Workplace Safety Market
Workplace Safety
Industrial Hand Protection Gloves Market
Workplace Safety
Safety Vest Market
Workplace Safety
Canada Safety Services Market
Workplace Safety
Industrial Eye Protection Market
Workplace Safety
Industrial Head Protection Market
Workplace Safety
Industrial Protective Footwear Market
Workplace Safety
Industrial Safety Market