
 Safe City Market | 2026-2036
Safe City Market Size, Share, and Industry Trends Forecast 2026-2036
Safe City Market Intelligence
Chinese surveillance equipment manufacturing is expanding output capacity for AI-enabled camera networks. Honeywell International leverages its building automation heritage to anchor integrated command-and-control platforms. Siemens sustains European dominance through specialized rail and transit security systems. NEC Corporation dominates biometric identification technology for law enforcement applications across East Asia.
Safe City denotes an urban environment where networked sensors, video analytics, and centralized data platforms enable real-time threat detection and coordinated emergency response, typically requiring sub-100-millisecond latency for critical alerts. These systems primarily serve municipal governments seeking to reduce incident response times and optimize public resource deployment. Surveillance Systems technology leads current procurement volumes due to mature hardware supply chains and established installation protocols. Smart Lighting application segments show accelerating traction as LED infrastructure retrofits create mounting points for environmental sensors and wireless access nodes. Cloud Services solutions concentrate margin pools through recurring subscription architectures that lock municipalities into long-term operational expenditure models.
China's MIIT enforces GB standards for IoT device interoperability that shape product certification requirements for foreign suppliers. India's CEA mandates cybersecurity protocols for critical infrastructure that filter vendor eligibility in smart city tenders. The EU AI Act imposes risk classification rules on biometric surveillance that will redirect procurement specifications across European municipalities. Stakeholders must monitor how divergent data sovereignty regimes fragment platform architectures and force localization investments.
Market Dynamics
Sub-100-millisecond latency requirements for critical alert processing are compressing procurement specifications toward edge-computing architectures and forcing municipalities to abandon legacy centralized data center models.
Growth Catalysts
- GB Standards Compliance:China's MIIT interoperability mandates for IoT device certification are accelerating replacement cycles for non-compliant surveillance hardware across municipal networks.
- LED Retrofit Infrastructure:Street lighting replacement programs in India and Southeast Asian cities are creating mounting points for environmental sensors and wireless access nodes at marginal incremental cost.
- Biometric Surveillance Mandates:Law enforcement agencies across East Asia are deploying facial recognition systems for real-time threat detection in high-density urban corridors.
Market Restraints
- Semiconductor Supply Concentration:AI-enabled camera networks depend on specialized edge-processing chips concentrated in Taiwanese and South Korean fabrication facilities.
- EU AI Act Risk Classification:Biometric surveillance systems face heightened compliance burdens and potential deployment restrictions across European municipalities.
- Legacy System Integration Costs:Existing analog CCTV infrastructure in mature cities requires substantial capital outlay for digital conversion and platform unification.
Strategic Opportunities
- India Smart Cities Mission:Central government funding for urban security and traffic management applications is opening procurement windows for integrated command platforms.
- Cloud Service Subscription Models:Recurring operational expenditure architectures are displacing capital-intensive ownership structures and locking municipalities into long-term vendor relationships.
- Rail and Transit Security Convergence:Specialized detection systems for underground and high-speed rail networks represent underpenetrated application segments with distinct technical requirements.
Industry Challenges
- Edge-AI Engineering Talent Scarcity:Municipal IT departments lack personnel capable of configuring low-latency inference pipelines and managing distributed sensor networks.
- Multi-Vendor Platform Interoperability:Proprietary data formats from competing surveillance equipment manufacturers complicate centralized command-and-control integration.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Safe City Market |
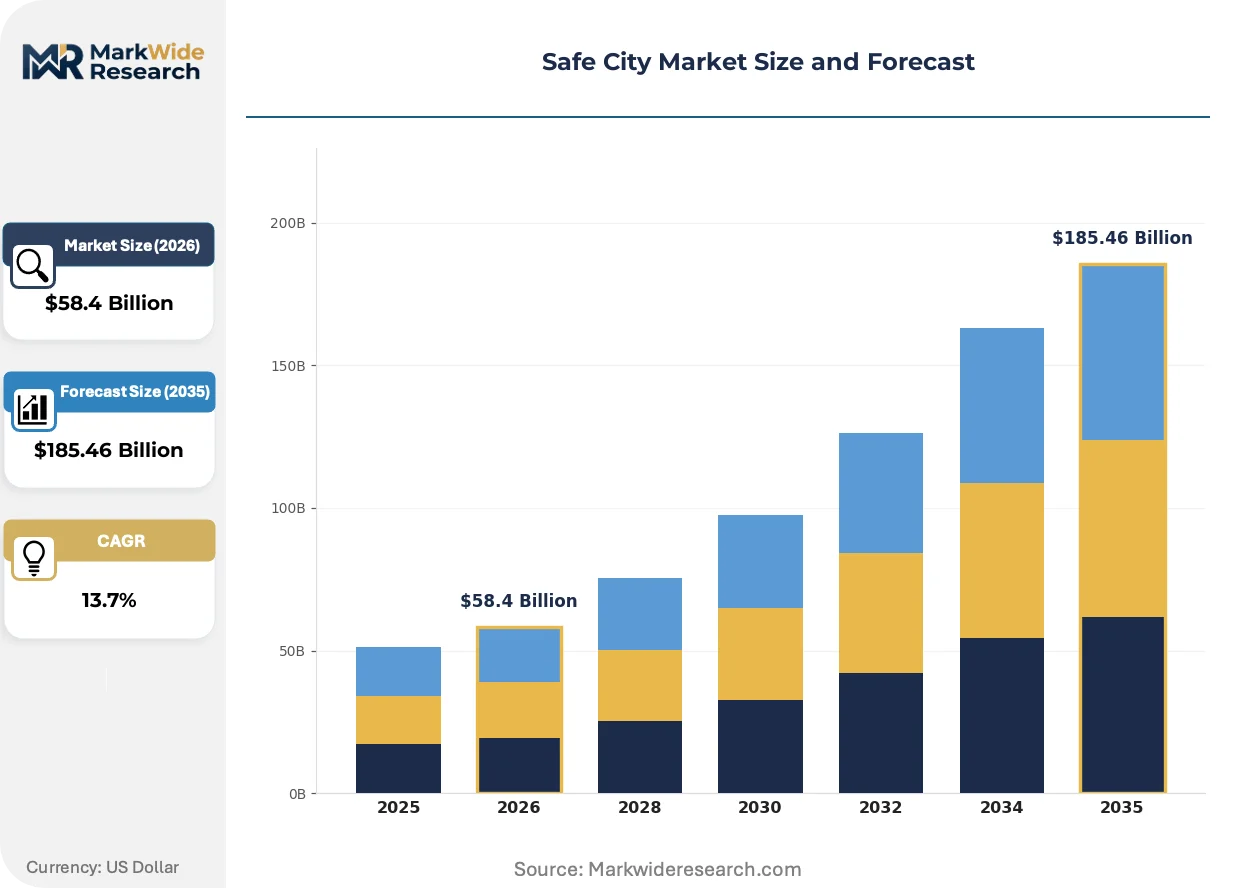
| Market Size in 2026 | $58.4 Billion |
| Market Size in 2035 | $185.46 Billion |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Surveillance Systems, Access Control, Emergency Response, Environmental Monitoring Application: Urban Security, Traffic Management, Disaster Recovery, Smart Lighting End User: Municipalities, Law Enforcement, Private Sector, Educational Institutions Solution: Data Analytics, Cloud Services, IoT Platforms, Mobility Solutions |
| Companies Covered | Honeywell International, Siemens, NEC Corporation, Bosch Security Systems, Thales Group, ABB Group, BAE Systems PLC, Cisco Systems, IBM, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Safe City Market Strategic Shifts & Innovations
Real-time video analytics is displacing human monitoring in municipal control centers, compressing incident detection timelines while generating new data governance obligations for urban administrators.
Edge-based AI inference engines are automating threat classification at the camera level, eliminating round-trip latency to centralized servers. Municipal governments in China and Singapore are deploying these processors across high-priority surveillance corridors. The technology is automating shift reductions in control room staffing while demanding higher-grade local maintenance capabilities.
The EU AI Act imposes risk-tier classification rules on biometric identification systems deployed in public spaces. European municipalities must now conduct fundamental rights impact assessments before procuring facial recognition infrastructure. Vendors are responding by developing anonymization overlays and purpose-limitation protocols for law enforcement applications.
Subscription-based operational expenditure models are displacing capital-intensive ownership structures in municipal procurement. City governments in India and Southeast Asia favor multi-year service contracts that bundle hardware, software, and maintenance into predictable annual payments. This shift concentrates margin pools with platform vendors capable of financing upfront infrastructure deployment.
Safe City Market Segmentation
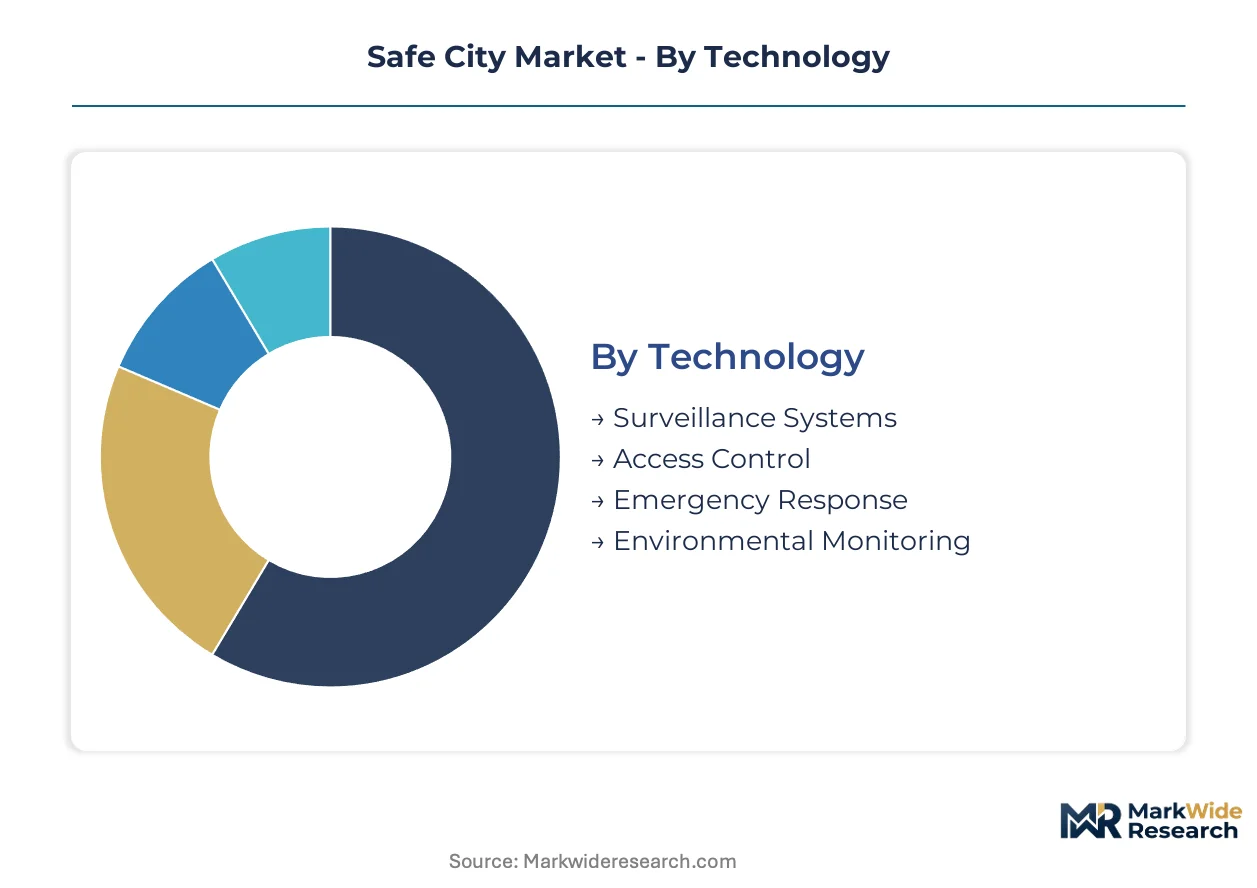
Safe City procurement patterns diverge sharply across technology maturity, application urgency, and buyer budget cycles. Municipal IT departments prioritize solutions that compress incident response latency while minimizing long-term operational expenditure commitments.
Technology:
Procurement specifications center on latency tolerance thresholds and legacy infrastructure compatibility.
- Surveillance Systems:AI-enabled camera networks with edge-processing chips automate threat classification at the point of capture. India's Smart Cities Mission and China's municipal networks absorb the majority of hardware procurement volumes as GB standards compliance mandates accelerate replacement cycles for non-compliant legacy installations.
- Emergency Response:Integrated command platforms coordinate multi-agency dispatch through sub-100-millisecond alert pipelines. Singapore and high-density Chinese urban corridors concentrate demand as these jurisdictions prioritize coordinated disaster response over siloed departmental systems.
- Access Control:Biometric identification terminals for critical infrastructure entry points.
- Environmental Monitoring:Distributed sensor networks for air quality, noise, and hazardous material detection.
Volume sits with Surveillance Systems; growth tilts toward Emergency Response.
Application:
Public safety budget allocation follows incident frequency patterns and visible infrastructure upgrade opportunities.
- Urban Security:Centralized threat detection platforms serving high-density commercial and residential districts. Law enforcement agencies across East Asian megacities deploy facial recognition corridors as core procurement priorities, with EU municipalities facing compliance friction from the EU AI Act's risk classification regime.
- Smart Lighting:LED retrofit programs create mounting infrastructure for environmental sensors and wireless access nodes at marginal incremental cost. Indian and Southeast Asian cities favor this application for its dual utility in energy efficiency and sensor deployment.
- Traffic Management:Real-time signal optimization and incident detection for arterial road networks.
- Disaster Recovery:Coordinated evacuation and resource mobilization systems for seismic and flood-prone regions.
Urban Security commands the largest budget share; Smart Lighting expands most quickly through infrastructure retrofit synergies.
End User:
Buyer sophistication and procurement authority determine platform complexity and contract structure preferences.
- Municipalities:City governments with consolidated IT departments favor multi-year subscription contracts bundling hardware, software, and maintenance into predictable operational expenditure streams. India's central government funding mechanisms accelerate procurement velocity for integrated command platforms.
- Law Enforcement:Police departments prioritize biometric surveillance and real-time identification capabilities. East Asian agencies lead deployment intensity while European counterparts navigate fundamental rights impact assessment requirements under the EU AI Act.
- Private Sector:Commercial property developers and facility managers.
- Educational Institutions:Campus security administrators with limited integration budgets.
Municipalities dominate contract value; Law Enforcement shows the steepest expansion trajectory for biometric identification systems.
Solution:
Vendor margin concentration follows recurring revenue potential and platform lock-in dynamics.
- Cloud Services:Subscription architectures displace capital-intensive ownership models through multi-year service contracts. Indian and Southeast Asian city governments favor this structure for budget predictability, concentrating margin pools with platform vendors capable of financing upfront infrastructure deployment.
- IoT Platforms:Device interoperability layers governed by China's MIIT GB standards and India's CEA cybersecurity protocols. Foreign suppliers face certification complexity that advantages domestic platform providers in municipal tender processes.
- Data Analytics:Video and sensor data processing for pattern recognition and predictive alerting.
- Mobility Solutions:Transit-integrated security and passenger flow optimization systems.
Cloud Services captures recurring revenue concentration; IoT Platforms gain share fastest through regulatory interoperability mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Silicon fabrication clusters in Taiwan and South Korea supply the specialized edge-processing chips that power AI-enabled municipal surveillance networks across urban centers worldwide.
China
Municipal governments in Beijing, Shanghai, and Shenzhen are replacing legacy analog CCTV with GB-compliant AI camera networks. MIIT enforces interoperability mandates that accelerate hardware replacement cycles for non-compliant installations. The Yangtze River Delta concentrates procurement volume as provincial authorities consolidate command platforms across megacity clusters.
India
The Smart Cities Mission channels central government funding toward urban security and traffic management applications in 100 designated municipalities. CEA cybersecurity protocols for critical infrastructure filter vendor eligibility in municipal tenders. Maharashtra and Gujarat absorb the bulk of procurement velocity as Mumbai and Ahmedabad deploy integrated command platforms.
Singapore
The city-state prioritizes sub-100-millisecond emergency response latency through coordinated multi-agency dispatch systems. National research programs under the Smart Nation initiative fund edge-computing pilot deployments in high-density commercial districts. The Jurong Lake District serves as a testbed for autonomous threat classification and automated shift reduction in control room operations.
Germany
Rail and transit security systems dominate procurement specifications as Deutsche Bahn expands specialized detection infrastructure across underground and high-speed networks. The EU AI Act's risk classification rules impose fundamental rights impact assessment requirements on biometric surveillance tenders. Bavaria and Baden-Württemberg concentrate vendor activity around Stuttgart and Munich's integrated transport authorities.
United States
Municipal IT departments favor multi-year subscription contracts bundling hardware, software, and maintenance into predictable operational expenditure streams. Federal transit security grants accelerate procurement for rail-integrated detection systems in major metropolitan areas. The Northeast Corridor from Boston to Washington DC represents the densest concentration of legacy system integration projects requiring digital conversion.
Safe City Market Key Industry Players
Established producers occupy the standard tier; emerging entrants pursue cloud-native subscription architectures and edge-AI specialization. The market structures around three tiers: diversified industrial conglomerates with building automation heritage, specialized security equipment fabricators, and platform vendors financing upfront infrastructure deployment. Strategic moves concentrate on M&A to absorb edge-computing capabilities and capacity expansion for AI-enabled camera production.
Within the diversified industrial tier, Honeywell International and Siemens exemplify archetypes leveraging building automation and rail security heritage respectively. NEC Corporation occupies a distinct position representing biometric identification specialists serving law enforcement applications across East Asian markets. These three anchors illustrate how vendor positioning diverges between integrated command platform provision, transit-specific security systems, and facial recognition corridor deployment.
| Leading Market Players |
|---|
| Honeywell International |
| Siemens |
| NEC Corporation |
| Bosch Security Systems |
| Thales Group |
| ABB Group |
| BAE Systems PLC |
| Cisco Systems |
| IBM |
| Others |
Cost & Logistics Intelligence
Edge-computing migration in municipal surveillance networks is compressing hardware margins while concentrating procurement power with vendors capable of financing distributed infrastructure deployment across Indian and Southeast Asian cities.
Pricing Analysis
Extended warranty and predictive maintenance bundling separates premium-tier command platform vendors from unbundled hardware suppliers in municipal tenders. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade under China's MIIT GB standards and India's CEA cybersecurity protocols. Cost compression in standard-tier surveillance hardware is intensifying because Taiwanese and South Korean chip fabrication capacity constraints limit edge-processor availability. Municipal governments in India exhibit highest price sensitivity due to central funding allocation cycles, while Singaporean agencies prioritize latency performance over unit economics.
Supply Chain Analysis
Direct-to-municipality channels handle integrated command platform deployments, while systems integrators distribute discrete surveillance hardware. Specialized edge-processing chip fabrication concentrates in Taiwan and South Korea, with backend assembly and camera housing production anchored in China and Vietnam. AI-enabled camera networks draw from CMOS sensors, thermal imaging modules, and encrypted storage components. Single-source vulnerability in Taiwanese foundry capacity exposes procurement timelines to geopolitical disruption. Distribution runs through regional systems integrators who manage GB standards compliance and CEA certification for foreign suppliers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized edge-processing chip fabrication capacity constraints prop pricing power for vendors with secured foundry allocations, compressing margins for hardware-assemblers without upstream semiconductor relationships.
For Market Incumbents: Anticipate margin erosion in commoditized camera hardware by deepening software subscription attach rates and platform lock-in. Accelerate certification investment under India's CEA cybersecurity protocols to filter tender eligibility. Counter emerging cloud-native entrants through captive financing of upfront municipal infrastructure deployment.
For New Entrants and Emerging Players: Capture white-space in rail and transit security convergence, where specialized detection requirements for underground networks remain underpenetrated. Target India's Smart Cities Mission secondary municipalities beyond Mumbai and Ahmedabad, where procurement velocity exceeds incumbent service capacity. Pursue edge-AI engineering talent scarcity as a go-to-market wedge through managed services packaging.
For Investors and Strategic Acquirers: Exit pathways concentrate in platform vendor acquisitions by diversified industrial conglomerates seeking command-and-control software capabilities. Long-term viability favors vendors with recurring revenue concentration above project-based hardware sales. Monitor EU AI Act enforcement intensity across German and French municipalities as inflection indicator for biometric surveillance demand redirection.
| Strategic Initiative | Industry Significance |
|---|---|
| Edge-AI Talent Acquisition | Addresses municipal IT capability gaps through managed inference pipeline services. |
| GB Standards Certification Investment | Unlocks China's MIIT-compliant municipal tender participation for foreign suppliers. |
| Cloud Service Subscription Migration | Concentrates margin pools with vendors financing upfront infrastructure deployment. |
| Rail Security Specialization | Captures underpenetrated underground detection segments with distinct technical requirements. |
| Foundry Capacity Securement | Insulates procurement timelines from Taiwanese fabrication concentration risks. |
Research Approach
Document review covered municipal procurement databases, smart city mission funding disclosures, and regulatory filings from China's MIIT and India's CEA, complemented by interviews with municipal IT directors, law enforcement technology procurement officers, systems integrators, and edge-computing hardware engineers. Secondary validation drew from customs trade data, SEC filings of listed security equipment vendors, and EU AI Act implementation guidance. Bottom-up segment sizing triangulated against top-down macroeconomic indicators across the analysis window.
Historical deployment trajectories cross-referenced against expert panel input on procurement cycle timing and regulatory enforcement intensity. Segmentation modeling spanned technology maturity tiers, application urgency levels, end-user sophistication archetypes, and solution delivery models. CAGRs derived from installed base growth rates and replacement cycle compression under interoperability mandates. Edge-computing adoption curves and subscription contract penetration informed scenario-weighted projections.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to EU AI Act biometric surveillance restrictions, Taiwanese foundry capacity allocation, and Indian central funding continuity. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Public Safety
North America Road Safety Market
Public Safety
Outdoor Public Safety Market
Public Safety
LAMEA Wireless Broadband in Public Safety Market
Public Safety
Latin America Public Safety Market
Public Safety
Global Public Safety Solution Market
Public Safety
Global Wireless Broadband in Public Safety Market
Public Safety
Global Public Safety Solution for Smart City Market
Public Safety
Global Public Safety in Building Wireless Das System Market
Public Safety
Crime Risk Report Market
Public Safety
Middle East Crime and Combat Market
Public Safety
Europe Road Safety Market
Public Safety
Public Safety LTE Market
Public Safety
Crowd Management System Market
Public Safety
Europe Public Infrastructure Safety Market
Public Safety
Counter Terror and Public Safety Technology Market
Public Safety
Global IoT for Public Safety Market