
 Middle East Crime and Combat Market | 2026-2036
Middle East Crime and Combat Market Size, Share, and Industry Trends Forecast 2026-2036
Middle East Crime and Combat Market Insights
Market Dynamics
The capability gap between software-centric fraud detection platforms and hardware-heavy defense contractors is collapsing as cybersecurity and physical security budgets merge across Middle East government buyers. Elbit Systems Ltd. anchors its regional position through integrated electro-optical and unmanned systems for border surveillance. NICE Ltd. leverages AI-powered analytics to sustain demand from law enforcement agencies modernizing digital evidence management. Oracle Corporation competes through cloud infrastructure contracts that support classified data workloads for intelligence agencies.
Technology and Segmentation
Middle East Crime and Combat encompasses integrated systems for threat detection, physical force application, and digital defense, spanning thermal imaging resolutions below 50 millikelvin sensitivity and encrypted command networks operating at NATO RESTRICTED equivalency. Surveillance Equipment and Cybersecurity Solutions command the largest product-type allocations as Gulf states harden critical infrastructure against hybrid attacks. Facial Recognition and Cyber Defense technologies are absorbing disproportionate technology investment due to cross-border data-sharing agreements and centralized biometric registry expansion across the region.
Regulatory Environment
Saudi Arabia's General Authority for Military Industries and the UAE's Tawazun Council are reshaping supplier eligibility through offset requirements and local content thresholds. Israel's Ministry of Defense and Jordan's armed forces procurement directorate enforce divergent technical standards that fragment vendor certification pathways. Stakeholders must monitor how Gulf localization mandates redefine partnership structures for foreign technology providers seeking long-term service contracts.
Market Dynamics
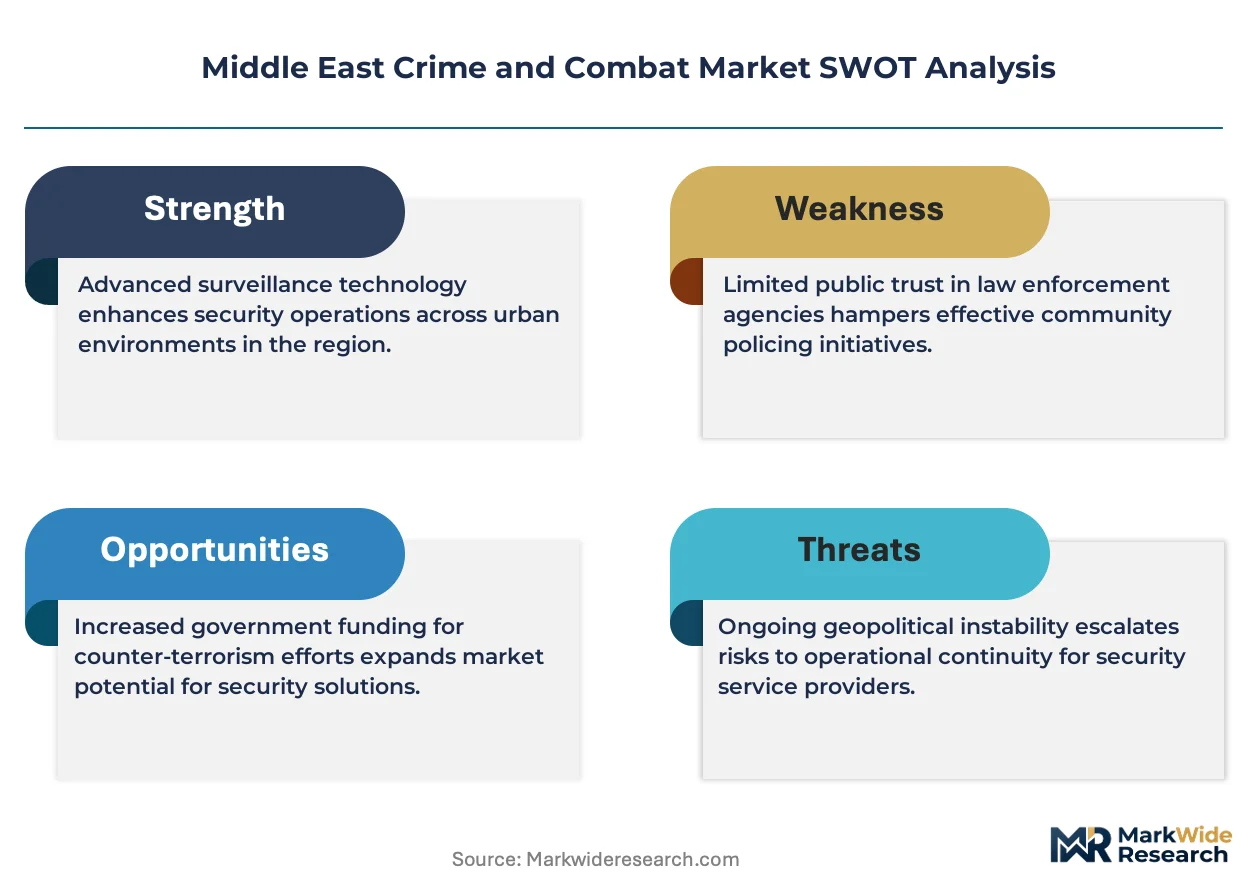
Saudi Arabia's GAMI localization mandates are forcing foreign defense contractors into domestic joint ventures, restructuring supplier obligations across Gulf security procurement. This regulatory pressure is collapsing the traditional separation between hardware-heavy military systems and software-centric cybersecurity platforms.
Growth Catalysts
- Biometric Registry Expansion:Centralized facial recognition databases across UAE federal and emirate-level agencies are accelerating demand for integrated surveillance hardware. Law enforcement modernization budgets now flow to vendors offering unified digital-physical security stacks.
- Offset Requirements:Tawazun Council localization thresholds in the UAE are redirecting foreign supplier investment toward domestic manufacturing partnerships. Defense contractors must meet local content ratios to maintain eligibility for long-term service contracts.
- Hybrid Threat Response:Critical infrastructure protection mandates are merging cybersecurity and physical security procurement budgets. Government buyers now specify NATO RESTRICTED equivalency for encrypted command networks in border surveillance tenders.
Market Restraints
- Input Cost Volatility:Thermal imaging sensor components face supply concentration in East Asian semiconductor foundries. Sub-50 millikelvin sensitivity detectors require specialized indium antimonide substrates with limited alternative sourcing.
- Regulatory Fragmentation:Israel's Ministry of Defense and Jordan's armed forces procurement directorate enforce divergent technical certification standards. Vendors must maintain separate compliance pathways for electro-optical systems across adjacent markets.
- Localization Timeline Compression:Saudi GAMI mandates require rapid domestic joint venture formation. Foreign technology providers face compressed windows to establish local manufacturing before contract renewal cycles.
Strategic Opportunities
- Emerging Application Convergence:Unmanned border surveillance systems are integrating AI-powered analytics for real-time threat classification. Vendors combining electro-optical hardware with edge-computing software capture premium positioning in UAE federal tenders.
- Channel Innovation:Cloud infrastructure contracts for classified intelligence workloads are displacing on-premise data center deployments. Oracle and comparable providers are establishing sovereign cloud architectures to meet data residency requirements.
- Regulatory Tailwind:Abu Dhabi and Dubai consolidation of federal and emirate-level security spending creates single-point procurement for integrated system vendors. Consolidated buyers favor end-to-end platform providers over component specialists.
Industry Challenges
- Skill Convergence Gap:Defense contractors lack personnel proficient in both electro-optical hardware engineering and AI software development. Recruitment for hybrid physical-digital security system architects lags behind procurement demand.
- Integration Complexity:Legacy border surveillance infrastructure in Saudi Arabia and Jordan operates on proprietary command protocols. New encrypted network deployments must maintain backward compatibility with existing thermal imaging installations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Middle East Crime and Combat Market |
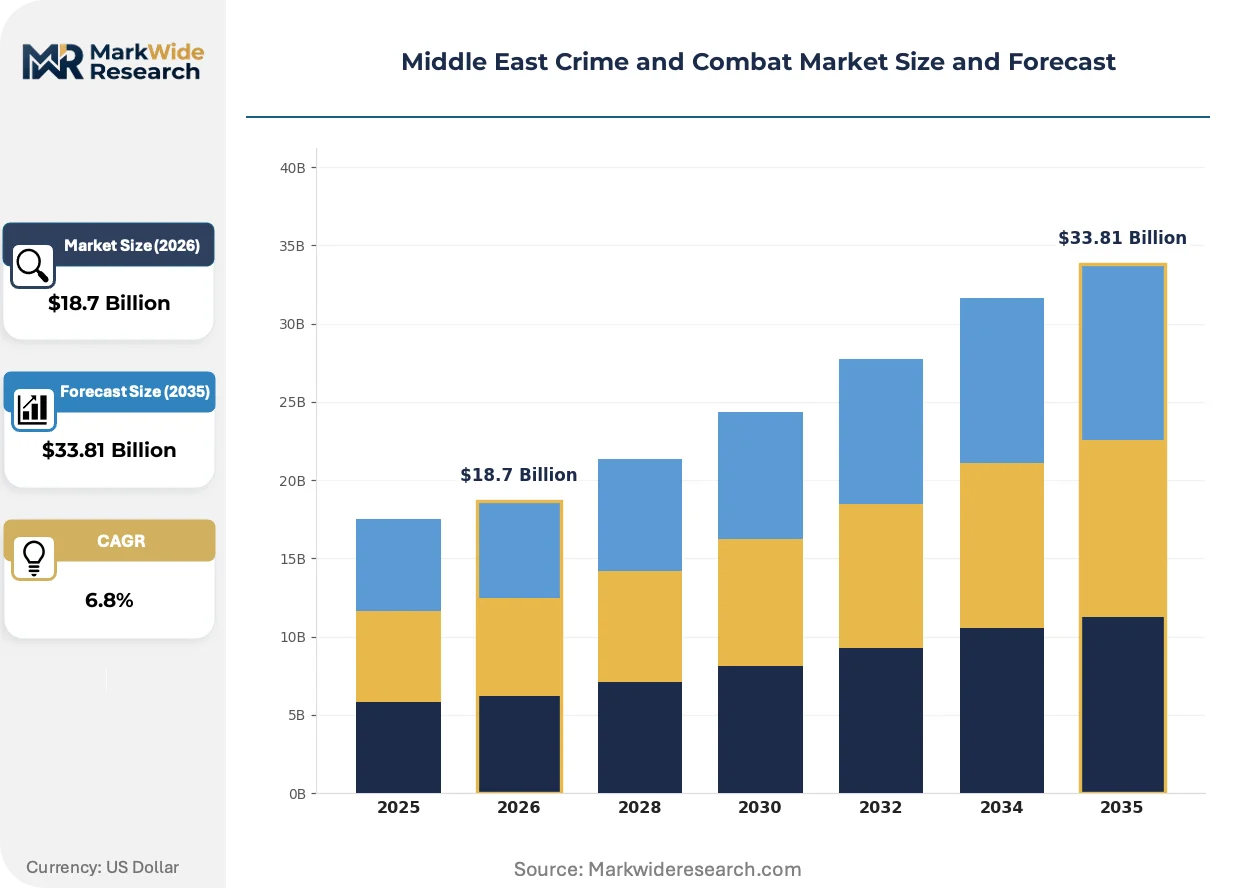
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Surveillance Equipment, Tactical Gear, Weapon Systems, Cybersecurity Solutions Service Type: Consulting Services, Live Training, Security Assessments, Risk Management Technology: Facial Recognition, Drones, Biometrics, Cyber Defense End User: Law Enforcement, Military, Private Security, Intelligence Agencies |
| Companies Covered | SAS Institute Inc., NICE Ltd, Fair Isaac Corporation, ACI Worldwide Inc., Oracle Corporation, Symphony Innovation LLC, Fiserv Inc., Tata Consultancy Services Limited, Elbit Systems Ltd., Others |
| Regions Covered | Middle East: Saudi Arabia, UAE, Qatar, Israel, Kuwait, Oman, Bahrain, Iran, Iraq, Rest of Middle East |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Middle East Crime and Combat Market Trends and Innovations
Software-defined surveillance architectures are collapsing the capability gap between traditional defense hardware and cybersecurity platforms. Three forces are reshaping how Gulf states procure integrated security systems.
Edge-deployed AI inference engines are supplanting centralized server-based analytics for real-time facial recognition at border checkpoints. UAE Ministry of Interior units are specifying on-device processing to reduce latency in high-throughput surveillance corridors. This distributed architecture is compressing demand for bulk data transmission infrastructure while elevating thermal camera vendors with embedded computing partnerships.
Tawazun Council offset frameworks now require technology transfer clauses in contracts exceeding specified thresholds. Foreign suppliers must license core intellectual property to domestic joint venture partners to maintain eligibility. Defense electronics segments face accelerated pressure to localize printed circuit board assembly and final system integration within UAE free zones.
Consolidated federal procurement in Abu Dhabi is displacing fragmented emirate-level tendering for surveillance and cybersecurity systems. Single-point buyers now demand unified service-level agreements spanning hardware maintenance and software updates. This concentration is most visible in critical infrastructure protection contracts where Dubai's civil defense authority merged specifications with federal interior ministry requirements.
Middle East Crime and Combat Market Segmentation
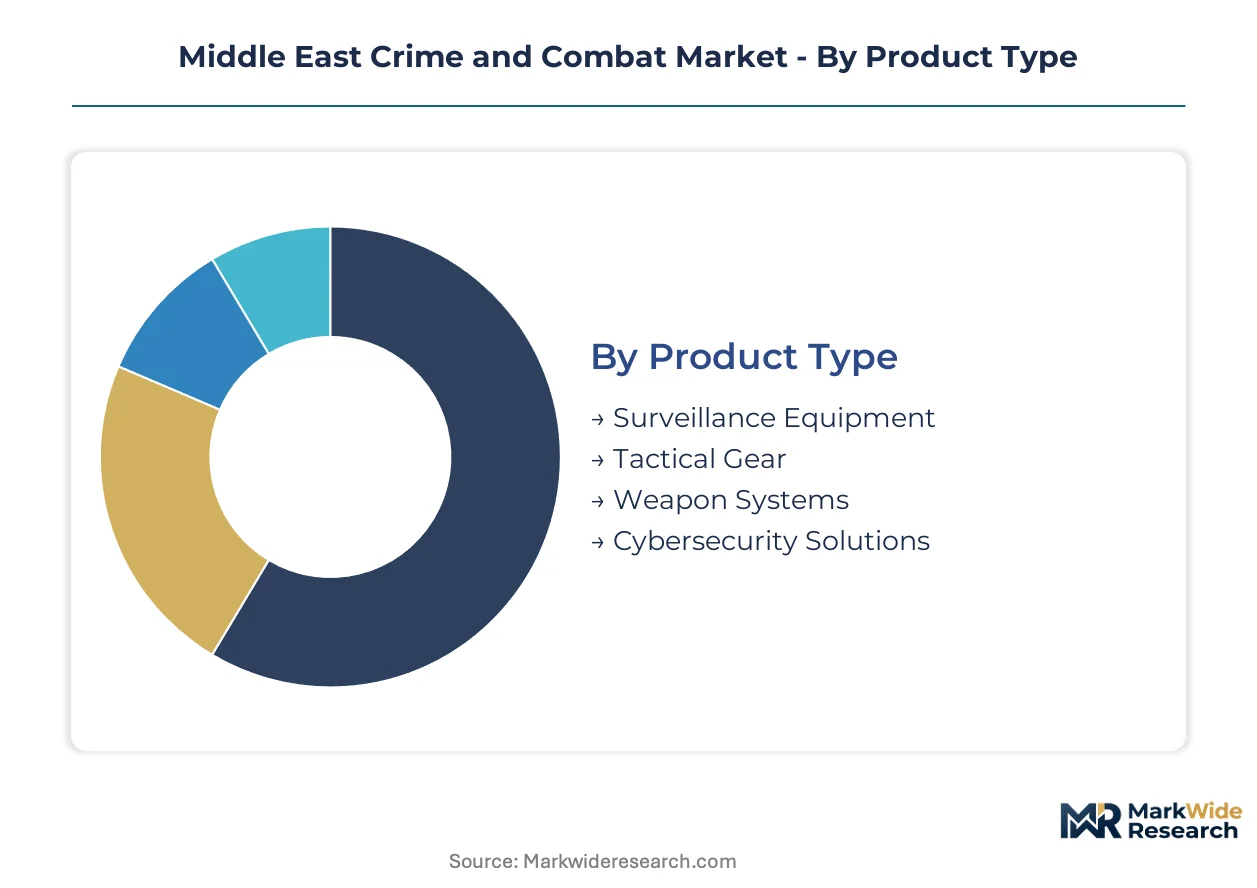
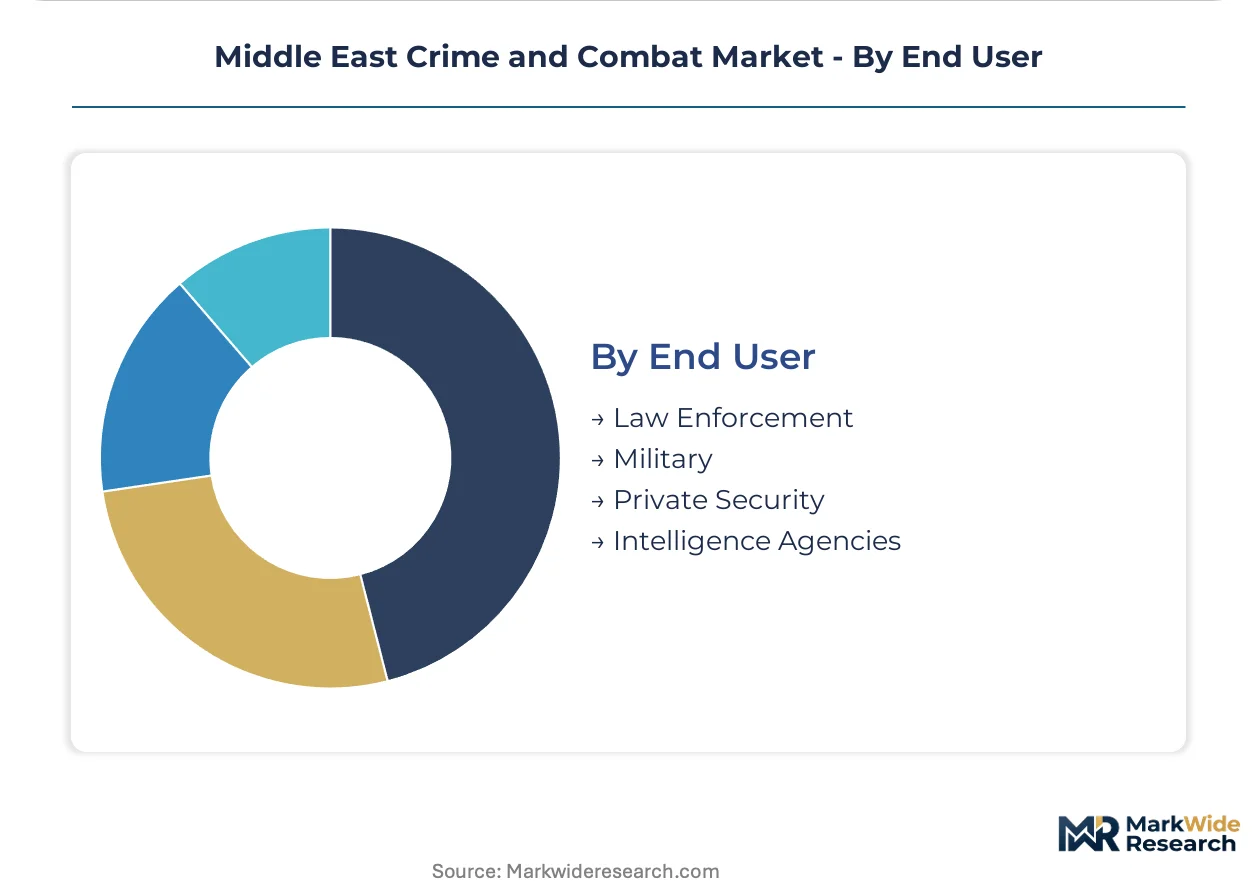
Segmentation reveals where procurement budgets are consolidating across Middle East security buyers. Gulf defense ministries now specify integrated platforms rather than standalone components, collapsing traditional category boundaries between physical and digital security systems.
Product Type:
Surveillance Equipment faces acute substitution pressure as software-defined architectures displace dedicated hardware arrays.
- Surveillance Equipment:Thermal imaging systems with sub-50 millikelvin sensitivity anchor border security infrastructure across Saudi Arabia and the UAE. Saudi GAMI localization mandates redirect foreign supplier obligations toward domestic joint ventures for electro-optical manufacturing.
- Cybersecurity Solutions:Encrypted command networks operating at NATO RESTRICTED equivalency protect critical infrastructure against hybrid attacks. Abu Dhabi and Dubai consolidation of federal and emirate-level security spending drives demand for unified digital-physical security stacks.
- Tactical Gear:Ballistic protection and communications equipment for ground forces.
- Weapon Systems:Small arms and crew-served weapons for counterterrorism operations.
Surveillance Equipment anchors the volume base while Cybersecurity Solutions gains share at the steepest rate.
Service Type:
Cost tier stratification separates premium advisory contracts from standardized training packages across Gulf procurement offices.
- Live Training:Scenario-based exercises for special operations units and rapid response forces. UAE Tawazun Council offset requirements mandate technology transfer clauses in contracts exceeding specified thresholds, elevating domestic training provider partnerships.
- Consulting Services:Strategic advisory for defense modernization and capability gap analysis. Israeli and Jordanian armed forces procurement directorates enforce divergent technical standards that fragment vendor certification pathways for advisory engagements.
- Security Assessments:Vulnerability evaluation for critical infrastructure protection.
- Risk Management:Threat intelligence and operational continuity planning.
Consulting Services commands the highest margin tier while Live Training expands most quickly through localization mandates.
Technology:
Application maturity varies sharply, with facial recognition deployments outpacing drone integration in operational readiness.
- Facial Recognition:AI-powered analytics for real-time biometric identification at border checkpoints. UAE Ministry of Interior units specify on-device processing to reduce latency in high-throughput surveillance corridors.
- Cyber Defense:Network monitoring and incident response for classified intelligence workloads. Oracle and comparable providers establish sovereign cloud architectures to meet data residency requirements across Gulf states.
- Drones:Unmanned aerial systems for border surveillance and target acquisition.
- Biometrics:Multi-modal identity verification beyond facial templates.
Cyber Defense captures the steepest investment trajectory while Facial Recognition provides the installed base for platform expansion.
End User:
Customer type concentration favors consolidated federal buyers over fragmented private sector procurement.
- Military:Integrated electro-optical and unmanned systems for border surveillance and force protection. Saudi Arabia's General Authority for Military Industries redirects foreign supplier investment toward domestic manufacturing partnerships.
- Law Enforcement:Digital evidence management and AI-powered analytics for criminal investigation. NICE Ltd. sustains demand through modernization of federal and emirate-level agency capabilities.
- Private Security:Commercial protection services for critical infrastructure and high-value assets.
- Intelligence Agencies:Classified data workloads and encrypted communications infrastructure.
Military procurement anchors contract values while Law Enforcement climbs fastest through biometric registry expansion.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Pricing power concentrates in Abu Dhabi and Dubai, where consolidated federal procurement commands premium vendor terms, while Riyadh's localization mandates compress margins for foreign suppliers through joint venture requirements.
Saudi Arabia
Riyadh anchors the region's largest defense modernization budgets through GAMI-mandated domestic manufacturing partnerships. The General Authority for Military Industries enforces local content thresholds that redirect foreign supplier obligations toward joint ventures for electro-optical system assembly. The Eastern Province hosts expanding production clusters where international firms establish captive facilities to maintain contract eligibility.
United Arab Emirates
Abu Dhabi and Dubai are consolidating federal and emirate-level security spending into single-point procurement for integrated surveillance platforms. The Tawazun Council mandates technology transfer clauses above contract thresholds, elevating domestic training and manufacturing partnerships. Dubai's civil defense authority has merged specifications with federal interior ministry requirements, streamlining vendor certification.
Israel
Israel's Ministry of Defense enforces divergent technical standards for electro-optical systems that fragment regional vendor pathways. Domestic defense electronics clusters around Haifa and Tel Aviv supply integrated unmanned and surveillance systems for border security applications. Israeli procurement prioritizes NATO RESTRICTED equivalency for encrypted command networks in tender specifications.
Jordan
Jordan's armed forces procurement directorate maintains separate certification standards from Gulf Cooperation Council states, complicating cross-border supplier operations. The country's strategic position drives demand for hybrid physical-digital security stacks at border checkpoints with Syria and Iraq. Amman-based security contractors increasingly partner with UAE and Saudi entities to access larger procurement pools.
Qatar
Qatar's defense modernization accelerates through centralized procurement for critical infrastructure protection against hybrid threats. The country's national security apparatus specifies integrated cybersecurity and physical security platforms for liquefied natural gas facilities and transportation corridors. Doha-based joint ventures with European and American suppliers are expanding domestic maintenance and training capabilities.
Middle East Crime and Combat Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, with specialized defense electronics firms commanding premium positioning in electro-optical segments while IT services conglomerates compete on scale in cybersecurity deployment. The market structure stratifies across three tiers: integrated platform providers with end-to-end capabilities, component specialists focused on thermal imaging or biometric hardware, and software-centric analytics vendors. Dominant competitive moves include forced domestic joint venture formation under Gulf localization mandates and sovereign cloud architecture establishment to meet data residency requirements.
Within the integrated defense electronics tier, Elbit Systems Ltd. and NICE Ltd. exemplify contrasting archetypes—Israel-based electro-optical specialists versus analytics-software vendors modernizing law enforcement digital evidence management. Oracle Corporation occupies a position among cloud infrastructure providers establishing classified-data architectures for intelligence agency workloads. These three entities represent the spectrum from hardware-heavy border surveillance to software-centric fraud detection platforms now merging under consolidated procurement budgets.
| Leading Market Players |
|---|
| SAS Institute Inc. |
| NICE Ltd |
| Fair Isaac Corporation |
| ACI Worldwide Inc. |
| Oracle Corporation |
| Symphony Innovation LLC |
| Fiserv Inc. |
| Tata Consultancy Services Limited |
| Elbit Systems Ltd. |
| Others |
Pricing and Supply Chain Analysis
Ninety-day lead times for indium antimonide thermal imaging substrates concentrate procurement leverage with East Asian foundries, compressing margin buffers for electro-optical system integrators while elevating pricing power for domestic joint ventures in Saudi Arabia's Eastern Province.
Pricing Analysis
Configured-to-order premiums for NATO RESTRICTED equivalency encrypted networks run 40-60% above standard surveillance hardware pricing. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and after-sales service bundling. Cost compression in standard-tier thermal imaging stems from GAMI-mandated local content thresholds. Federal buyers in Abu Dhabi exhibit lowest price sensitivity due to consolidated procurement authority, while Jordanian border security units face acute budget constraints.
Supply Chain Analysis
Strategic stockpiling of sub-50 millikelvin sensitivity detectors dominates inventory strategy as Gulf states buffer against East Asian semiconductor supply volatility. Manufacturing concentration centers on Taiwan, South Korea, and Japan for specialized indium antimonide substrates. Supply chains draw from German precision optics, Israeli electro-optical engineering, and UAE free-zone assembly. Single-source vulnerability concentrates in East Asian foundry capacity for thermal imaging sensors. Distribution runs through sovereign procurement channels and defense ministry tender platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating through Abu Dhabi and Dubai's consolidation of federal and emirate-level security spending, fragmenting vendor negotiation leverage across component specialists.
For Market Incumbents: Fortify domestic joint venture positions in Saudi Arabia's Eastern Province production clusters to defend against emerging UAE-based electro-optical integrators. Prioritize technology transfer licensing to Tawazun Council-compliant partners as the priority lever for contract renewal eligibility. Capture backward integration into indium antimonide substrate sourcing to offset East Asian supply concentration risks. For New Entrants and Emerging Players: Lead with sovereign cloud architecture capabilities for classified intelligence workloads, targeting Qatar's liquefied natural gas facility protection mandates as the most penetrable entry point. Exploit skill convergence gaps in hybrid physical-digital security system architecture. Deploy through Oracle-compatible channel partnerships to bypass lengthy defense ministry certification cycles. For Investors and Strategic Acquirers: Carve-out targets emerge from European defense electronics parents seeking to exit non-core Middle East service contracts. Long-term viability hinges on localization mandate compliance depth rather than technology differentiation alone. Monitor GAMI joint venture formation velocity as the signal for contract renewal cycle timing.| Strategic Initiative | Industry Significance |
|---|---|
| Domestic Joint Venture Formation | GAMI and Tawazun Council mandates redirect foreign supplier investment toward Saudi and UAE manufacturing partnerships. |
| Sovereign Cloud Architecture Deployment | Oracle and comparable providers establish classified-data infrastructures to meet Gulf intelligence agency residency requirements. |
| Technology Transfer Licensing | Foreign electro-optical vendors license core IP to domestic partners to maintain Tawazun Council contract eligibility. |
| Edge AI Inference Integration | Thermal camera vendors embed on-device processing to capture UAE Ministry of Interior high-throughput corridor tenders. |
| Consolidated Procurement Platform Positioning | End-to-end system vendors displace component specialists as Abu Dhabi merges federal and emirate-level security spending. |
Research Methodology
A standing panel of defense procurement officers, electro-optical system engineers, cybersecurity architects, and Tawazun Council compliance specialists provided ongoing calibration across primary interview cycles. Secondary validation drew from GAMI localization directives, UAE federal tender databases, NATO RESTRICTED equivalency specifications, and customs records for thermal imaging component trade flows. Bottom-up segment sizing triangulated against top-down defense budget allocation analysis.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework modeled product type, service tier, technology maturity, and end-user concentration dimensions. CAGRs derived from regression analysis of historical procurement patterns and policy mandate implementation timelines. Industry-specific inputs included GAMI joint venture formation rates and Tawazun Council offset threshold adjustments.
Forecasts assume regulatory continuity in Saudi GAMI and UAE Tawazun Council regimes; material policy shifts would require re-modeling of supplier eligibility pathways. Specific risk factors encompass East Asian semiconductor export restrictions and NATO equivalency standard revisions. Revision becomes warranted when localization timeline compression crosses supplier adaptation capacity thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Public Safety
Europe Road Safety Market
Public Safety
Global Public Safety in Building Wireless Das System Market
Public Safety
Public Safety in-Building Wireless Distributed Antenna System (DAS) Market
Public Safety
Public Safety Market
Public Safety
AI for Public Security and Safety Market
Public Safety
US Mass Notification Systems Market
Public Safety
Global Public Safety Solution Market
Public Safety
Global Public Safety Analytics Market
Public Safety
Europe Wireless Broadband in Public Safety Market
Public Safety
Global Public Safety Solution for Smart City Market
Public Safety
Global Public Safety and Security Market
Public Safety
Latin America Public Safety Market
Public Safety
Public Safety LTE Market
Public Safety
Crowd Management System Market
Public Safety
Global Wireless Broadband in Public Safety Market
Public Safety
Asia-Pacific Public Safety Market