
 North America Road Safety Market | 2026-2036
North America Road Safety Market Size, Share, and Industry Trends Forecast 2026-2036
North America Road Safety Market Insights
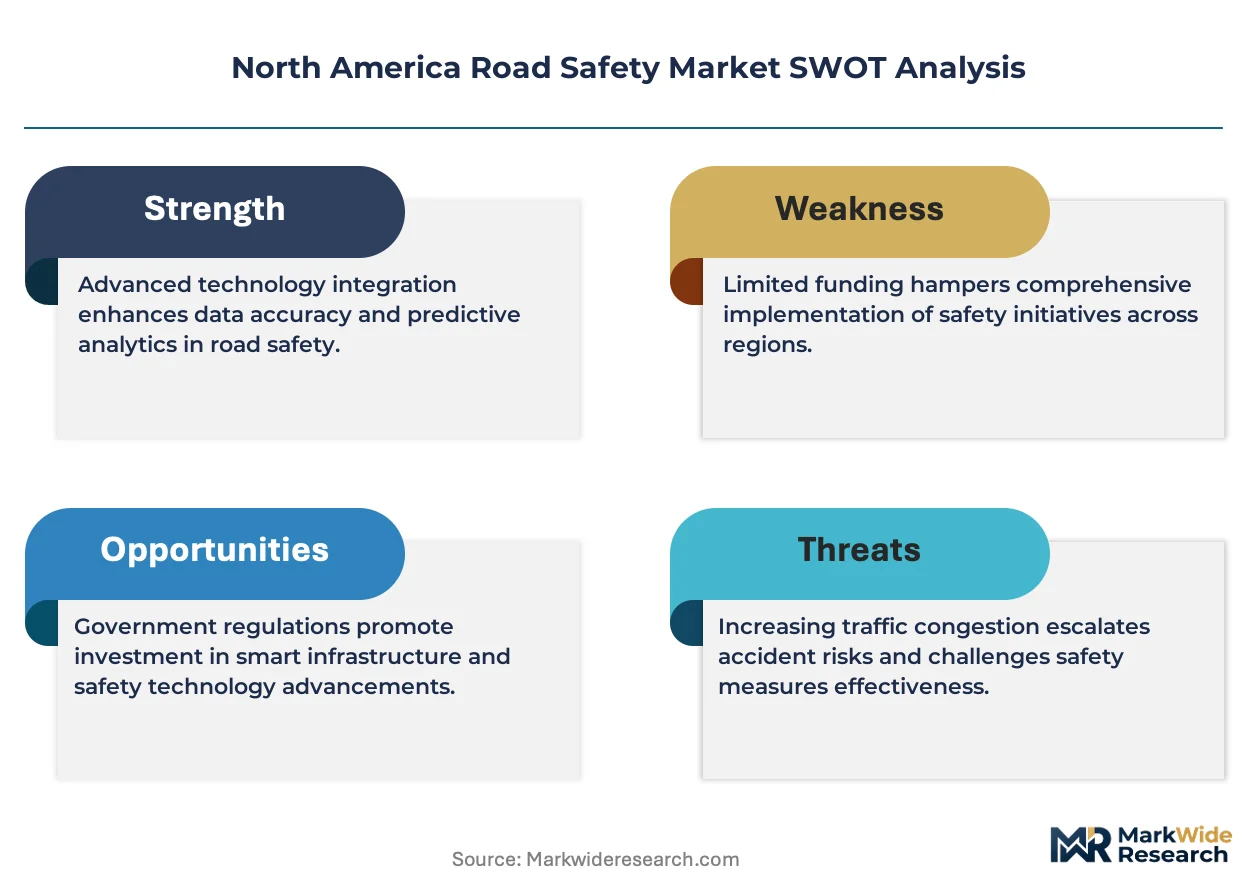
Aftermarket service revenue for traffic management infrastructure is fragmenting across hardware maintenance, software subscription, and data analytics tiers. Kapsch TrafficCom leverages its transatlantic installed base to sustain recurring service contracts. Siemens anchors its position through deep integration of signaling hardware with cloud-based traffic optimization platforms. Iteris competes on sensor fusion capabilities that blend video, radar, and thermal detection for intersection monitoring.
Road safety encompasses engineered systems, electronic surveillance, and physical protective equipment designed to prevent collisions, control vehicle speeds, and shield vulnerable road users. Smart sensors incorporating lidar, radar, and machine vision algorithms process real-time traffic flow data with sub-100-millisecond latency to trigger automated signal adjustments or alert dispatchers to incidents. Guardrails and road barriers dominate product type revenue due to mandatory federal highway specifications, while smart sensors represent the fastest-expanding technology segment as municipalities retrofit legacy intersections. Government agencies and municipalities absorb the majority of end user spending through capital improvement bonds and federal grant programs.
The Federal Highway Administration enforces Manual on Uniform Traffic Control Devices standards that dictate sign placement, signal timing, and barrier specifications across all federally funded roads. NHTSA coordinates vehicle-to-infrastructure communication protocols that shape sensor and software procurement requirements for state departments of transportation. State regulators in California, Texas, and New York impose supplemental specifications exceeding federal minimums, creating regional compliance complexity. Stakeholders must monitor how IIJA funding disbursement timelines and evolving V2X technology standards reshape competitive positioning between integrated platform vendors and specialized component suppliers.
Market Dynamics
Federal infrastructure disbursements from the Infrastructure Investment and Jobs Act are compressing procurement timelines for intelligent traffic systems across state departments of transportation. Municipal bond issuances for Vision Zero compliance are accelerating retrofit cycles at legacy intersections.
Growth Catalysts
- IIJA Funding Windows:The Infrastructure Investment and Jobs Act channels dedicated capital toward vehicle-to-infrastructure deployment, forcing state DOTs to advance sensor procurement schedules.
- California SB 743:This state mandate redefines traffic impact metrics around vehicle miles traveled, compelling developers to fund advanced signalization at project sites.
- Lidar-Radar Fusion:Multi-modal detection arrays are replacing single-sensor intersection monitors, opening upgrade revenue for systems integrators.
Market Restraints
- Semiconductor Supply Concentration:Traffic controller manufacturing depends on captive foundry capacity in East Asia, exposing North American deployments to shipping volatility.
- Copper and Aluminum Input Costs:Guardrail and barrier fabrication faces margin pressure from base metal price swings tied to energy-intensive smelting.
- Legacy Signal Interoperability:Pre-2010 traffic control hardware lacks firmware architecture to support V2X protocol stacks, fragmenting upgrade paths.
Strategic Opportunities
- Texas Urban Corridors:Houston and Dallas-Fort Worth congestion pricing pilots are creating first-mover advantage for integrated mobility platform vendors.
- Predictive Maintenance Analytics:Cloud-based degradation modeling for signal heads and loop detectors is unbundling from hardware contracts into standalone SaaS tiers.
- Canadian Federal Active Transportation Fund:Ottawa's dedicated cycling and pedestrian infrastructure program is expanding demand for physical protective equipment beyond highway applications.
Industry Challenges
- V2X Certification Bottlenecks:NHTSA interoperability testing protocols remain in draft form, delaying equipment approvals and freezing procurement commitments.
- Embedded Systems Talent Scarcity:Real-time firmware engineering for sub-100-millisecond signal processing commands wage premiums that erode project margins.
- Multi-Agency Coordination Friction:Municipal traffic departments, state DOTs, and utility operators maintain incompatible data standards, complicating corridor-wide deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Road Safety Market |
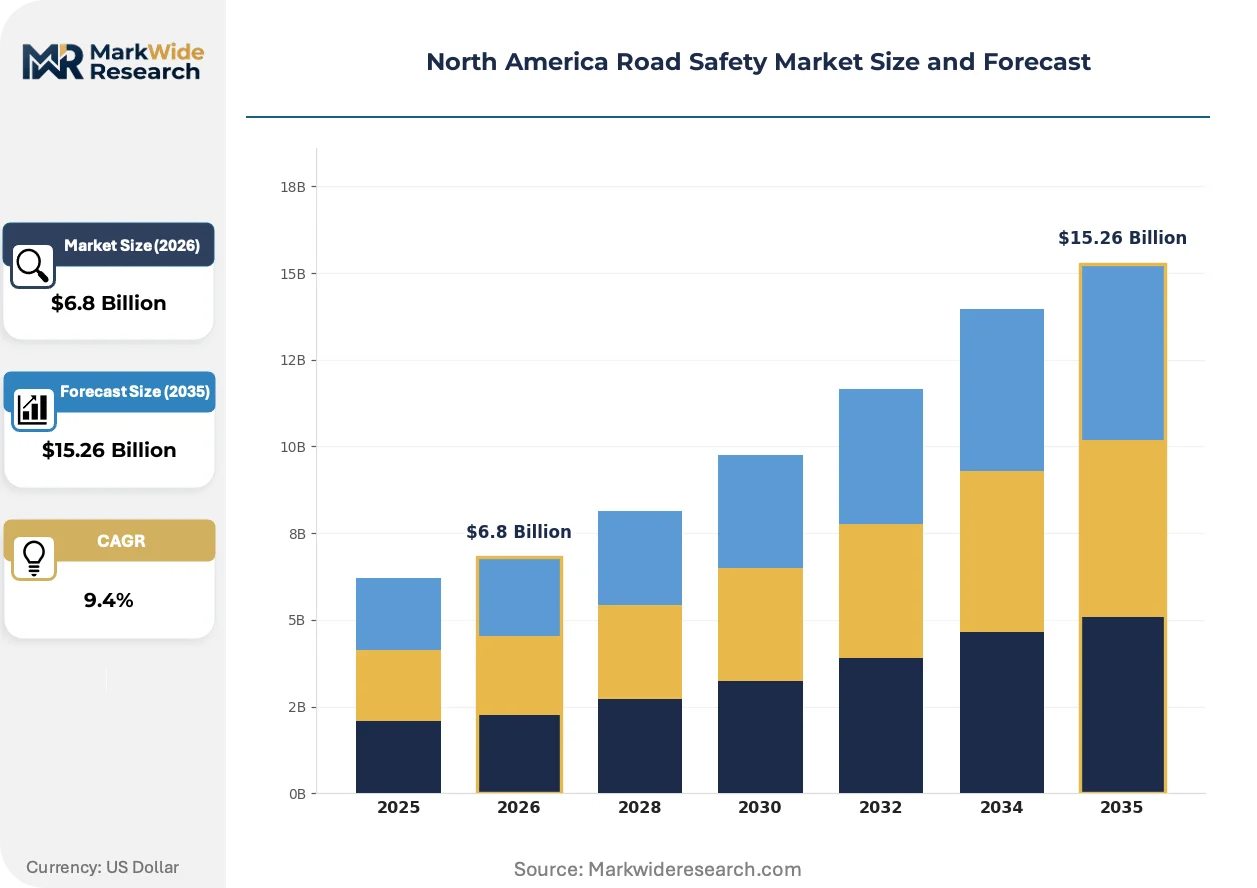
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $15.26 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Traffic Signals, Speed Cameras, Road Barriers, Smart Sensors Product Type: Guardrails, Traffic Cones, Warning Signs, Automatic Flare Systems Application: Urban Roads, Highways, Construction Sites, School Zones End User: Government Agencies, Transport Companies, Construction Firms, Municipalities |
| Companies Covered | Kapsch TrafficCom, Conduent, Verra Mobility, Iteris, Teledyne FLIR, Motorola Solutions, Siemens, Cubic Corporation, Jenoptik, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Road Safety Market Trends and Innovations
Edge computing architectures are redistributing processing loads from centralized traffic management centers to roadside units. This shift is compressing latency budgets and enabling autonomous signal decisions without backhaul dependency.
Multi-sensor fusion arrays combining lidar, radar, and thermal imaging are collapsing the functional distinction between vehicle detection and pedestrian classification at intersections. Arizona DOT and Ontario's MTO are piloting these configurations at high-collision corridors. The technology is collapsing procurement categories that previously separated camera-only from in-ground loop systems into unified detection contracts.
NHTSA's pending rulemaking on vehicle-to-everything communication security credentials is tightening procurement specifications for roadside unit encryption. Equipment vendors must now pre-integrate hardware security modules before deployment. State DOTs in California and Texas are front-running federal mandates with supplemental cybersecurity clauses in RFPs.
Municipal purchasing departments are consolidating traffic signal maintenance into multi-year performance contracts that bundle hardware, software, and response-time guarantees. Los Angeles DOT and Toronto Transportation Services have shifted from unit-based spare-part procurement to uptime-based subscription models. This restructuring is most visible in jurisdictions with mature asset management systems and bond-rated infrastructure authorities.
North America Road Safety Market Segmentation
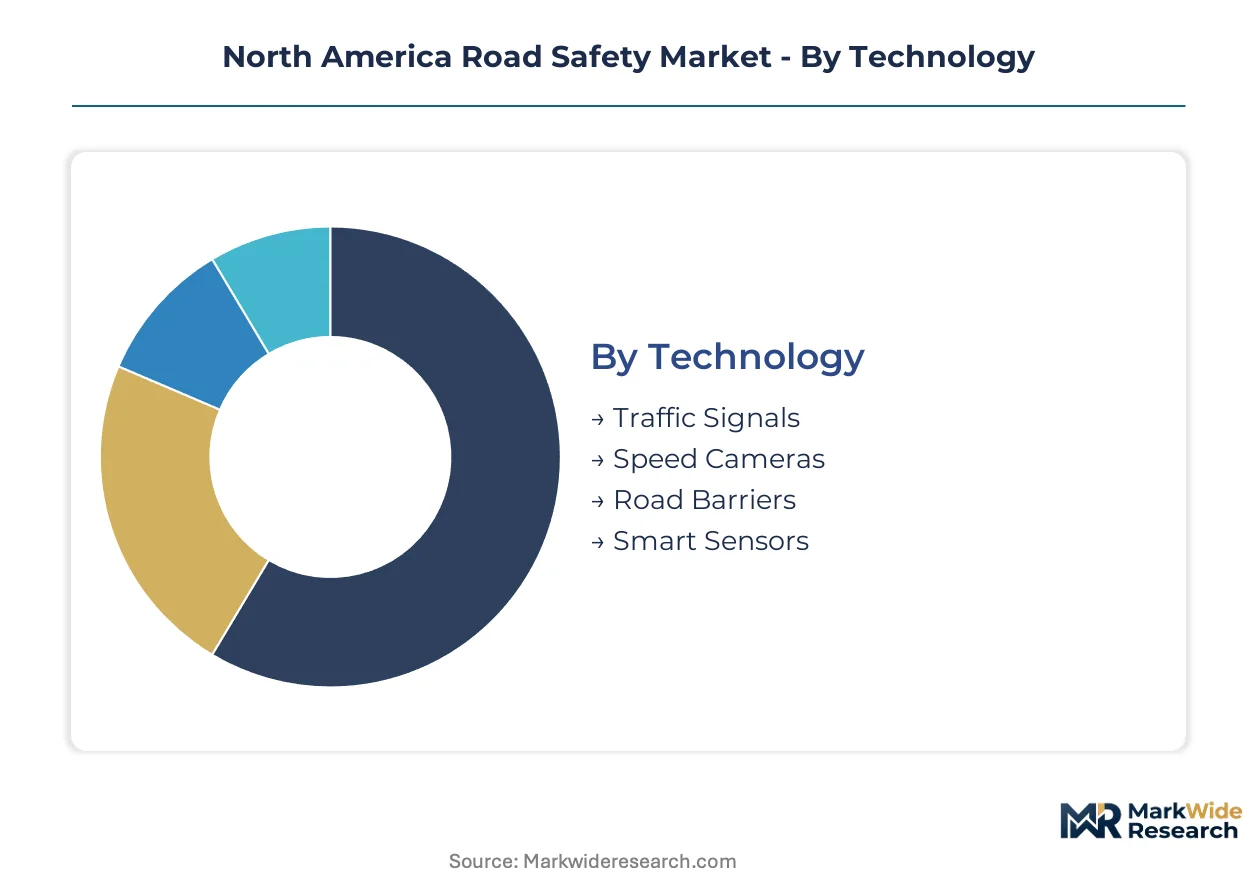
Road safety procurement cycles vary dramatically across technology tiers, with physical infrastructure enduring 15-20 year replacement windows while sensor systems face 3-5 year obsolescence pressures. Understanding these velocity differentials helps vendors align service contract structures and inventory positions with actual replacement demand.
Technology:
Traffic Signals and Smart Sensors turn over fastest as municipalities chase V2X compliance, while Road Barriers and legacy Speed Cameras persist for decades with minimal retrofit.
- Traffic Signals:Electromechanical and LED signal heads with embedded firmware for adaptive timing algorithms. California DOT and Texas DOT are consolidating procurement into performance-based maintenance contracts that bundle hardware replacement with uptime guarantees.
- Smart Sensors:Lidar-radar fusion arrays with sub-100-millisecond edge processing for real-time vehicle-to-infrastructure communication. Ontario's MTO and Arizona DOT are deploying these at high-collision corridors ahead of federal certification deadlines.
- Speed Cameras:Fixed and mobile enforcement units with automated license plate recognition.
- Road Barriers:Steel beam guardrails and concrete median barriers engineered to NCHRP 350 crash-test specifications.
Road Barriers dominate installed base. Smart Sensors are where expansion concentrates.
Product Type:
Cost tier stratification separates premium engineered systems from consumable field equipment, with fabrication intensity and raw material exposure defining margin profiles.
- Guardrails:W-beam and thrie-beam steel configurations with zinc or polymer coatings for corrosion resistance. Federal highway specifications mandate these across interstate corridors, though copper and aluminum input volatility compresses fabricator margins.
- Automatic Flare Systems:LED-based sequential warning devices with solar charging and remote activation for incident response. California Highway Patrol and Ontario Provincial Police are replacing pyrotechnic flares to reduce fire risk and supply chain dependency.
- Traffic Cones:PVC or rubber channelizing devices with reflective collars.
- Warning Signs:Aluminum substrate signs with diamond-grade or engineer-grade retroreflective sheeting.
Guardrails anchor replacement schedules. Automatic Flare Systems are climbing the fastest.
Application:
Volume concentration follows funding authorization patterns, with federal-aid highways absorbing capital-intensive systems and municipal streets driving retrofit sensor demand.
- Highways:Interstate and principal arterial corridors governed by Federal Highway Administration design standards. IIJA disbursements are compressing procurement timelines for intelligent traffic systems across state DOTs in Texas and California.
- School Zones:Reduced-speed corridors with beacon-activated warning systems and pedestrian detection. Vision Zero mandates in New York and Toronto are accelerating camera enforcement and curb extension installations near educational facilities.
- Urban Roads:Signalized intersections and corridor networks within municipal boundaries.
- Construction Sites:Temporary traffic control zones with portable barriers and message boards.
Highways capture the largest contract values. School Zones are gaining share fastest.
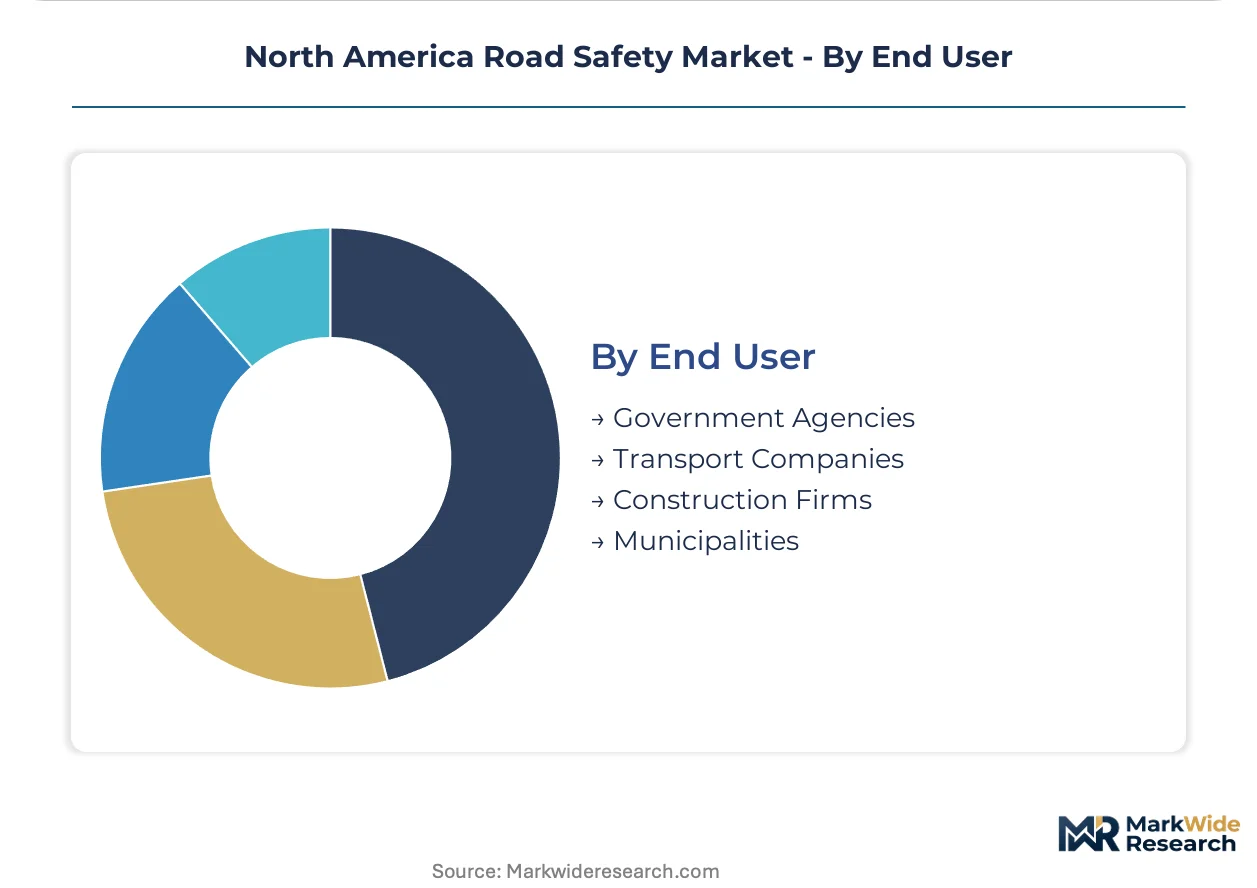
End User:
Customer type determines procurement mechanics, with bond-rated authorities favoring performance contracts and private operators prioritizing capital efficiency.
- Government Agencies:State departments of transportation and federal land management authorities with multi-year capital improvement programs. NHTSA coordinates V2X protocol requirements that shape their sensor procurement specifications.
- Municipalities:City and county traffic departments with asset management systems and municipal bond capacity. Los Angeles DOT and Toronto Transportation Services have shifted from unit-based spare-part procurement to uptime-based subscription models.
- Transport Companies:Fleet operators and logistics providers with private road networks.
- Construction Firms:General contractors and specialty traffic control subcontractors.
Government Agencies control the deepest project pipelines. Municipalities are where contract structures are evolving most rapidly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Traffic management system manufacturing clusters concentrate in the United States and Canada, with Mexican assembly operations emerging for barrier fabrication and signal housing production serving cross-border highway projects.
United States
California DOT and Texas DOT drive procurement volume through IIJA-funded corridor upgrades. NHTSA coordinates V2X protocol requirements that shape sensor specifications for state departments of transportation. Los Angeles and Houston anchor demand for integrated mobility platforms with congestion pricing pilots underway.
Canada
Ontario's Ministry of Transportation deploys lidar-radar fusion arrays at high-collision corridors ahead of federal certification deadlines. Ottawa's Federal Active Transportation Fund expands cycling and pedestrian infrastructure demand. Toronto Transportation Services shifted from unit-based spare-part procurement to uptime-based subscription models.
Mexico
Nuevo León and the Bajío Region host assembly operations for guardrail and barrier components serving USMCA trade corridors. The Secretariat of Infrastructure, Communications and Transportation channels federal highway modernization funds toward intelligent traffic system retrofits. Mexico City Metro accelerates signalization upgrades for Vision Zero compliance.
North America Road Safety Market Competitive Landscape
Integrated platform vendors and specialized component suppliers split the market along technology integration depth. The vendor base organizes into three strategic archetypes: transatlantic systems integrators sustaining recurring service contracts, hardware-anchored conglomerates bundling signaling equipment with cloud optimization, and sensor fusion specialists competing on multi-modal detection capabilities. Dominant competitive moves include cloud-based traffic optimization platform integration and performance-based maintenance contract restructuring.
Among transatlantic systems integrators, Kapsch TrafficCom leverages its installed base to sustain recurring service contracts. Siemens anchors market position through deep integration of signaling hardware with cloud-based platforms. Iteris competes on sensor fusion capabilities that blend video, radar, and thermal detection for intersection monitoring.
| Leading Market Players |
|---|
| Kapsch TrafficCom |
| Conduent |
| Verra Mobility |
| Iteris |
| Teledyne FLIR |
| Motorola Solutions |
| Siemens |
| Cubic Corporation |
| Jenoptik |
| Others |
Pricing and Supply Chain Analysis
Overcapacity in East Asian semiconductor foundries is compressing lead times for traffic controller chipsets while simultaneously eroding pricing power for North American systems integrators dependent on those inputs. This utilization dynamic forces suppliers into volume-commitment contracts that lock in component costs, reshaping how domestic vendors structure long-term service agreements with municipal buyers.
Pricing Analysis
Aftermarket service revenue tiers—spanning hardware maintenance, software subscription, and predictive analytics—now drive lifetime value capture for integrated platform vendors. Three-tier pricing structure across premium, standard, and economy levels separates bundled performance contracts from transactional spare-part procurement. Cost compression in physical protective equipment intensifies because copper and aluminum input volatility compresses fabricator margins. Municipal traffic departments exhibit highest price sensitivity due to bond-issuance constraints, while federal-aid highway programs demonstrate lowest sensitivity given IIJA capital availability.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk planning for lidar sensor and edge-computing hardware procurement. Manufacturing concentration centers on Taiwan, South Korea, and Malaysia for semiconductor components feeding traffic signal firmware and roadside unit processors. Raw material dependencies span copper and zinc for guardrail coatings, aluminum for sign substrates, and rare earth elements for magnet assemblies in electromechanical signal heads. Single-source vulnerability in East Asian foundry capacity exposes North American deployments to shipping volatility. Distribution runs through state DOT central warehouses and municipal bonded storage facilities with multi-year inventory positions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Embedded systems firmware engineering for sub-100-millisecond signal processing commands wage premiums that erode project margins, creating acute capability scarcity across the vendor base. This talent gap constrains expansion velocity for integrated platform vendors and opens defensive consolidation opportunities for incumbents with captive engineering benches.
For Market Incumbents: Entrench market position by acquiring specialized sensor fusion engineering teams in Arizona and Ontario corridor deployment zones, neutralizing the embedded systems talent scarcity that threatens margin structures. Consolidate backward integration into copper and aluminum coating operations to defend against base metal price volatility eroding guardrail fabrication margins. Prioritize certification investment for NHTSA V2X interoperability protocols ahead of final rulemaking to lock in state DOT procurement preference. For New Entrants and Emerging Players: Mid-size Canadian municipalities with Federal Active Transportation Fund allocations but immature asset management systems represent the most penetrable entry point for physical protective equipment vendors seeking first-mover positioning. Predictive maintenance analytics for signal head degradation modeling—currently unbundling from hardware contracts—offers SaaS-tier entry with minimal capital intensity. Go-to-market execution should anchor on uptime-based subscription pricing that mirrors Los Angeles DOT and Toronto Transportation Services contract structures. For Investors and Strategic Acquirers: Long-term, this sits as a recurring-revenue infrastructure play because municipal performance-based maintenance contracts are restructuring procurement from unit-sales to subscription economics, embedding vendor relationships across 15-20 year replacement windows. Acquisition target archetype: sensor fusion specialists with deployed lidar-radar arrays at high-collision corridors and existing NHTSA pilot certifications. Signal to watch: final NHTSA V2X security credential rulemaking release, which will unlock frozen procurement commitments and accelerate deployment timelines.| Strategic Initiative | Industry Significance |
|---|---|
| Performance-Based Maintenance Contract Restructuring | Los Angeles DOT and Toronto Transportation Services subscription models embed vendors across multi-decade replacement cycles. |
| Backward Integration into Coating Operations | Captive zinc and polymer coating capacity insulates guardrail fabricators from copper price volatility. |
| Edge Computing Architecture Deployment | Roadside unit processing compression enables autonomous signal decisions without backhaul dependency. |
| Multi-Sensor Fusion Array Certification | Arizona DOT and Ontario MTO pilot deployments create referenceable installations for federal V2X compliance. |
| Predictive Maintenance Analytics Unbundling | Cloud-based degradation modeling for signal heads shifts from hardware bundle to standalone SaaS tier. |
Research Methodology
Two parallel data streams informed the analysis: primary interviews with state DOT procurement officers, municipal traffic department directors, intelligent traffic systems integrators, and embedded systems firmware engineers; and secondary validation through FHWA Manual on Uniform Traffic Control Devices filings, NHTSA V2X protocol documentation, IIJA funding disbursement records, and municipal bond issuance databases. Bottom-up triangulation across vendor shipment records and top-down reconciliation against federal-aid highway obligation balances anchored volume estimates.
Forecast inputs span technology tier replacement velocities, federal infrastructure authorization timelines, and state-level Vision Zero mandate adoption curves across the projection horizon. Segmentation dimensions modeled include product type stratification, end-user procurement mechanics, and corridor-specific deployment intensity. CAGRs were derived from regression analysis of historical state DOT capital improvement patterns against obligated IIJA disbursement schedules. Industry-specific inputs incorporate semiconductor lead time volatility and base metal price regression coefficients.
Macroeconomic conditions sit as an overlay; deviation in municipal bond issuance spreads or East Asian shipping lane disruption would shift the trajectory. Forecasts reflect documented assumptions regarding NHTSA rulemaking finalization and state DOT procurement acceleration. Material shifts in V2X certification timelines or IIJA reauthorization would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Public Safety
Public Safety Market
Public Safety
Voice Evacuation Systems Market
Public Safety
Europe Road Safety Market
Public Safety
Global IoT for Public Safety Market
Public Safety
Public Safety LTE Market
Public Safety
Middle East Crime and Combat Market
Public Safety
LAMEA Wireless Broadband in Public Safety Market
Public Safety
Asia-Pacific Public Safety Market
Public Safety
Safe City Market
Public Safety
Global Public Safety Analytics Market
Public Safety
AI for Public Security and Safety Market
Public Safety
Europe Public Safety Market
Public Safety
Outdoor Public Safety Market
Public Safety
Global Public Safety Solution Market
Public Safety
US Mass Notification Systems Market
Public Safety
Crime Risk Report Market