
 Outdoor Public Safety Market | 2026-2036
Outdoor Public Safety Market Size, Share, and Industry Trends Forecast 2026-2036
Outdoor Public Safety Market Analytics
Project finance and leasing arrangements for surveillance infrastructure is narrowing the competitive field to vendors with balance-sheet capacity for multi-year service contracts. Motorola Solutions leverages its vertical integration across radio and video systems to sustain long-term municipal relationships. Honeywell anchors its position through building-automation cross-sell into public safety verticals. Axis Communications specializes in open-architecture camera platforms that compete on interoperability rather than bundled lock-in.
Outdoor public safety encompasses hardened electronic systems deployed in uncontrolled environments for threat detection, emergency communication, and situational awareness, typically rated for extended temperature ranges, ingress protection, and electromagnetic resilience. These installations serve first responders and municipal operators who require continuous visibility across transportation corridors, utility infrastructure, and mass gathering venues. Surveillance cameras and communication radios constitute the mature revenue base where replacement cycles and upgrade paths are well understood. AI analytics within the technology dimension captures expanding margin pools as agencies prioritize automated object recognition and behavioral pattern detection over passive recording. Drones represent the fastest-growing product category, though regulatory fragmentation around beyond-visual-line-of-sight operations constrains deployment velocity in multiple jurisdictions.
The EU AI Act, FCC equipment authorization rules in the United States, and India's BIS certification requirements for electronic safety equipment collectively shape product development roadmaps and market access conditions for cross-border suppliers. Compliance with these frameworks adds fixed certification costs that favor established vendors with dedicated regulatory affairs functions. Stakeholders must weigh the trade-off between platform consolidation for compliance efficiency against maintaining vendor diversity for supply chain resilience and pricing leverage.
Market Dynamics
Multi-year municipal procurement cycles are compressing vendor selection windows while simultaneously demanding extended service commitments, forcing suppliers to restructure balance sheets around lease-based revenue recognition rather than upfront hardware sales.
Growth Catalysts
- Federal modernization programs:United States infrastructure spending directs capital toward interoperable first-responder networks. State-level emergency management agencies prioritize unified command platforms.
- EU AI Act certification:Automated threat detection systems gain procurement preference when vendors demonstrate compliance with European algorithmic transparency mandates. Municipal buyers in Germany and France accelerate replacement timelines.
- Edge computing deployment:On-device analytics reduce bandwidth dependency for rural surveillance corridors. Indian smart city authorities specify local processing for traffic monitoring nodes.
Market Restraints
- Beyond-visual-line-of-sight limitations:FAA operational waivers for drone patrols remain jurisdictionally fragmented. Urban air mobility regulators impose altitude and corridor restrictions that constrain automated response coverage.
- Semiconductor supply concentration:Specialized image sensors for low-light detection depend on Taiwanese foundry capacity. Geopolitical friction exposes lead time volatility for hardened camera modules.
- Legacy radio spectrum scarcity:Narrowband Land Mobile Radio frequencies face congestion in dense metropolitan deployments. First responders encounter dead zones where broadband alternatives lack hardened reliability.
Strategic Opportunities
- India BIS certification pathway:Domestic manufacturing incentives under the PLI scheme attract component localization for video analytics hardware. State police modernization budgets expand procurement eligibility for certified suppliers.
- Predictive maintenance integration:Convergence of vibration sensors and thermal imaging enables pre-failure detection on critical infrastructure. Utility operators adopt condition-based monitoring for substation security.
- Subscription analytics platforms:Cloud-based evidence management displaces on-premise storage capital expenditure. Smaller municipalities access tiered software licensing without dedicated IT infrastructure.
Industry Challenges
- Cybersecurity workforce scarcity:Hardened system architects with industrial control security clearance command premium compensation. Municipal agencies struggle to retain talent against private sector compensation.
- Interoperability certification timelines:Project Stedfast compliance testing for multi-vendor radio networks extends deployment schedules. Integration laboratories face backlog queues that delay field activation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Outdoor Public Safety Market |
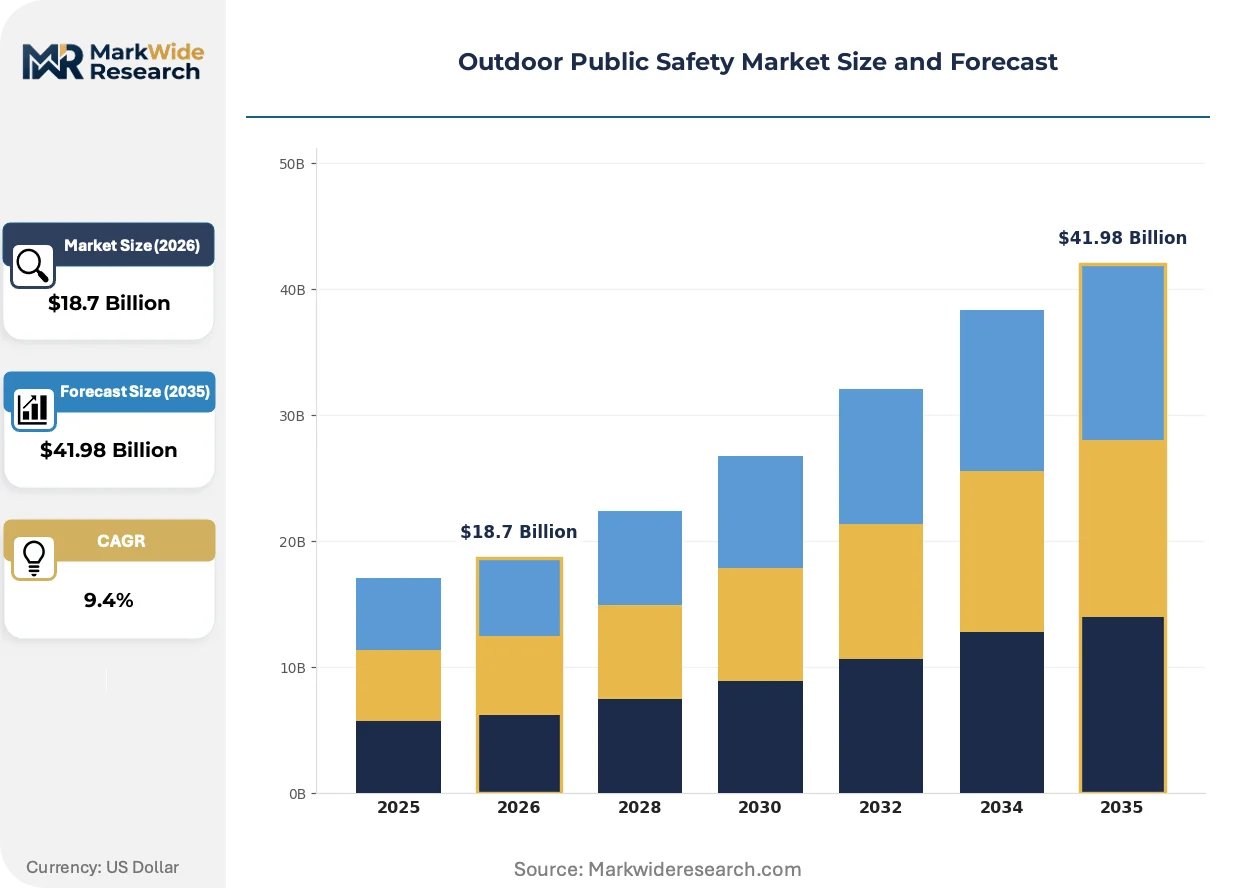
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $41.98 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: GPS Devices, Surveillance Cameras, Communication Radios, Drones End User: Emergency Services, Public Safety Organizations, Municipalities, NGOs Technology: IoT Solutions, Cloud-Based Systems, Mobile Applications, AI Analytics Installation: Fixed Infrastructure, Portable Systems, Remote Deployment, Integrated Solutions |
| Companies Covered | Motorola Solutions, Cisco Systems, Honeywell, L3Harris Technologies, Siemens, Axis Communications, IBM, Hexagon, Bosch Security Systems, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Outdoor Public Safety Market Evolving Landscape
Computational architectures are migrating intelligence toward network peripheries while regulatory frameworks harden algorithmic accountability requirements. Procurement psychology shifts from capital ownership toward operational expenditure models.
Software-defined video management is virtualizing hardware-dependent encoding and storage functions. Large-scale stadium operators and transportation authorities adopt hyperconverged platforms that abstract camera-specific protocols into unified APIs. This architecture is virtualizing traditional NVR appliance markets by collapsing dedicated server infrastructure into commodity compute layers.
GDPR algorithmic impact assessments now extend to automated biometric identification in public spaces. European data protection authorities mandate human-in-the-loop review for facial recognition deployments. Public transit operators in the Netherlands and Spain reconfigure platform surveillance to exclude real-time identity matching, prioritizing behavioral anomaly detection instead.
Municipal buyers increasingly unbundle hardware acquisition from multi-decade service obligations. Competitive evaluation weights total cost of ownership over initial purchase price. German municipal purchasing cooperatives consolidate demand across city boundaries to extract volume pricing on maintenance and software update entitlements.
Outdoor Public Safety Market Segmentation
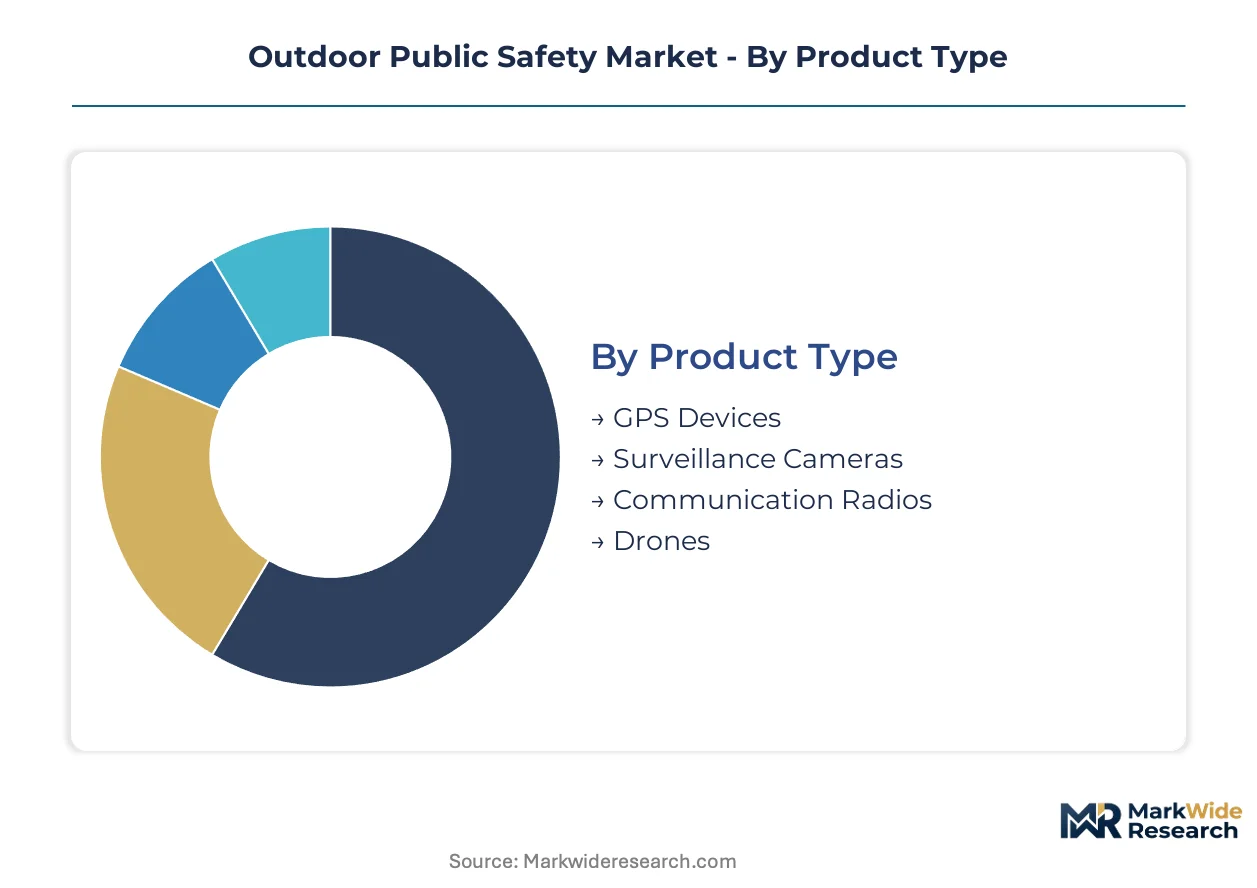
Segmentation in outdoor public safety reveals how procurement priorities diverge across institutional buyers and operational contexts. Technology maturity and regulatory compliance requirements create distinct competitive arenas within each dimension.
Product Type:
Mature hardware categories dominate installed bases while emerging platforms reshape capital allocation patterns.
- Surveillance Cameras:Hardened imaging systems with IP67+ ratings and extended temperature tolerance serve as the foundational revenue layer. Municipal traffic management authorities in Germany and the United States drive replacement cycles toward AI-enabled models with on-device analytics.
- Communication Radios:Land Mobile Radio systems with narrowband and broadband interoperability anchor first-responder coordination networks. State emergency management agencies in the United States prioritize Project Stedfast certification for multi-vendor compatibility.
- GPS Devices:Ruggedized positioning hardware supports asset tracking across utility corridors and search operations.
- Drones:Beyond-visual-line-of-sight platforms face FAA operational waiver fragmentation that constrains deployment velocity in urban airspace.
Surveillance cameras retain volume leadership; drones hold the steepest expansion curve.
End User:
Institutional scale and procurement authority separate high-volume contract opportunities from specialized deployment niches.
- Municipalities:City governments consolidate demand through purchasing cooperatives that extract volume pricing on maintenance entitlements and software update rights. German municipal purchasing networks exemplify this aggregation strategy.
- Emergency Services:Fire departments and ambulance authorities prioritize hardened reliability over feature breadth. Interoperability mandates from the FCC and EU AI Act compliance accelerate platform consolidation decisions.
- Public Safety Organizations:State police and highway patrol units specify equipment for traffic corridor monitoring and incident response coordination.
- NGOs:Humanitarian operators deploy portable surveillance for disaster assessment and camp security in conflict zones.
Municipalities command the largest contract values; emergency services impose the most stringent certification requirements.
Technology:
Architecture migration from centralized processing to edge intelligence redistributes margin pools across the technology stack.
- AI Analytics:Automated object recognition and behavioral pattern detection algorithms capture expanding procurement preference as agencies shift from passive recording to predictive alerting. EU AI Act transparency mandates accelerate certified platform adoption in France and the Netherlands.
- Cloud-Based Systems:Evidence management platforms displace on-premise storage capital expenditure through subscription licensing. Smaller municipalities access tiered software without dedicated IT infrastructure.
- IoT Solutions:Sensor networks enable predictive maintenance integration for critical infrastructure protection.
- Mobile Applications:Smartphone-based situational awareness tools extend command visibility to field personnel without dedicated hardware investment.
AI analytics is gaining share fastest; cloud systems are displacing traditional capital expenditure models most aggressively.
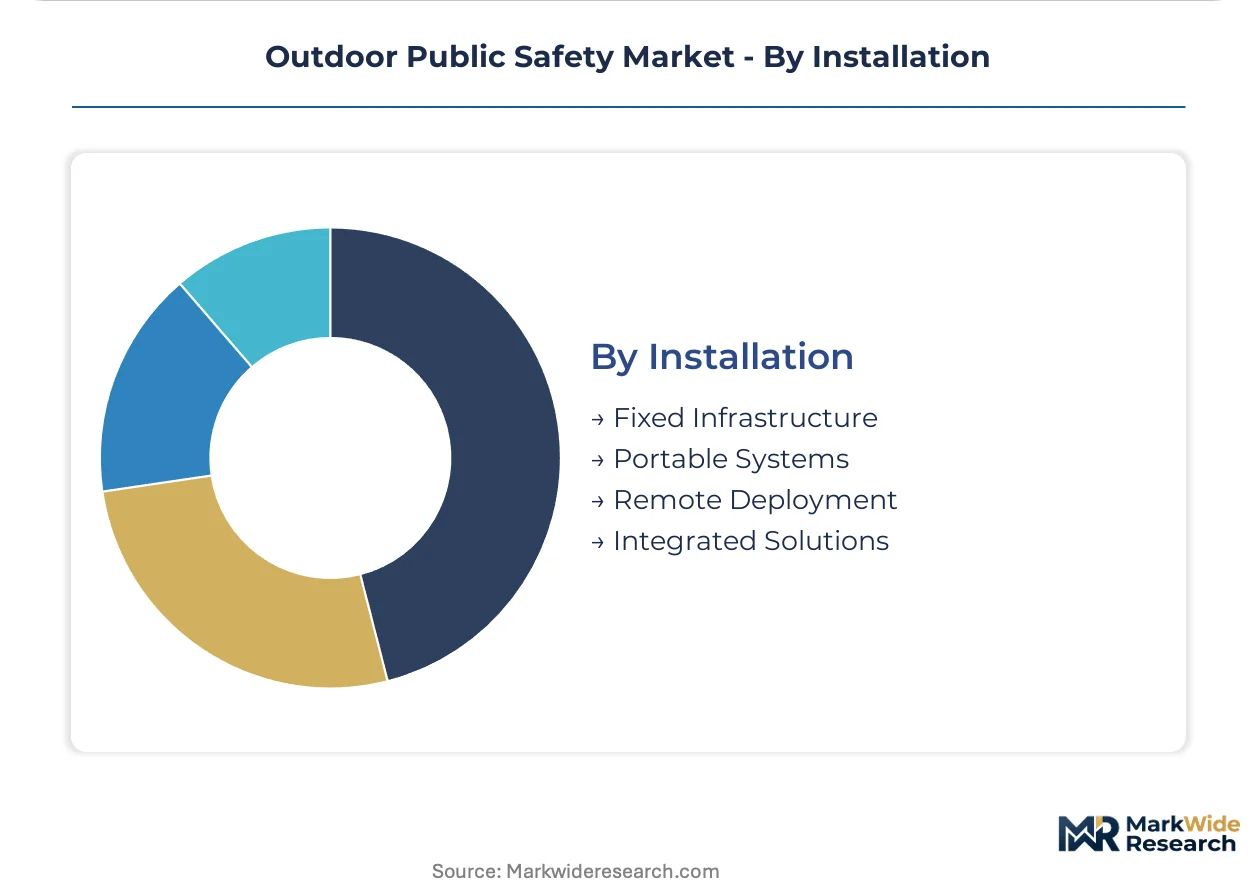
Installation:
Deployment flexibility requirements separate permanent infrastructure investments from rapid-response capability procurement.
- Fixed Infrastructure:Permanent camera mounts and communication towers constitute the mature installed base with predictable replacement cycles. Indian smart city authorities specify hardened enclosures for traffic monitoring nodes under BIS certification requirements.
- Remote Deployment:Solar-powered and satellite-linked systems enable surveillance coverage in rural corridors lacking grid connectivity. Edge computing specifications reduce bandwidth dependency for these installations.
- Portable Systems:Rapidly deployable units support temporary event security and emergency response staging.
- Integrated Solutions:Multi-modal platforms combining cameras, sensors, and radios into unified command interfaces.
Fixed infrastructure retains the largest installed base; remote deployment is climbing the fastest as rural coverage gaps drive procurement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import dynamics for surveillance hardware and AI analytics platforms concentrate procurement authority in three distinct regulatory zones. Cross-border certification costs favor established vendors with dedicated compliance functions in each jurisdiction.
United States
Federal infrastructure spending directs capital toward interoperable first-responder networks through the FCC's Project Stedfast certification requirements. State emergency management agencies in Texas and California prioritize unified command platforms with hardened broadband alternatives. Motorola Solutions anchors municipal relationships across the Southwest through vertical integration across radio and video systems.
Germany
Municipal purchasing cooperatives consolidate demand across city boundaries to extract volume pricing on maintenance entitlements. The EU AI Act's algorithmic transparency mandates accelerate certified platform adoption in Berlin and Munich. Bosch Security Systems exemplifies the compliance-heavy archetype dominating procurement in Baden-Württemberg's industrial corridor.
India
State police modernization budgets expand procurement eligibility for BIS-certified suppliers under the PLI scheme's domestic manufacturing incentives. Smart city authorities in Maharashtra and Karnataka specify edge computing for traffic monitoring nodes. Hexagon occupies a position among vendors navigating India's regulatory localization requirements.
France
Public transit operators in Paris and Lyon reconfigure platform surveillance to exclude real-time identity matching under CNIL guidance. GDPR algorithmic impact assessments mandate human-in-the-loop review for facial recognition deployments. Axis Communications represents the open-architecture specialists competing on interoperability rather than bundled lock-in.
United Kingdom
Transportation authorities adopt hyperconverged platforms that abstract camera-specific protocols into unified APIs across London and Birmingham. Evidence management platforms displace on-premise storage capital expenditure through subscription licensing. Cisco Systems sits within the cloud-systems tier addressing smaller municipalities without dedicated IT infrastructure.
Outdoor Public Safety Market Competitive Landscape
On the supply side, the industry is consolidating around vendors with balance-sheet capacity for multi-year service contracts. Tiered competitive dynamics separate full-stack integrators from component specialists and software-centric challengers. Dominant competitive moves include strategic partnerships for regulatory certification and portfolio diversification into predictive analytics.
Among US-based defense-electronics conglomerates, L3Harris Technologies and Honeywell exemplify the full-stack integration archetype, while Siemens represents European industrial diversification into public safety verticals. These three anchors illustrate how cross-sell capabilities from adjacent building-automation and critical infrastructure sectors reshape municipal procurement evaluation criteria.
| Leading Market Players |
|---|
| Motorola Solutions |
| Cisco Systems |
| Honeywell |
| L3Harris Technologies |
| Siemens |
| Axis Communications |
| IBM |
| Hexagon |
| Bosch Security Systems |
| Others |
Value Network & Pricing Analysis
Semiconductor supply concentration in Taiwanese foundries exposes outdoor public safety hardware vendors to lead time volatility that compresses margin pools at the economy tier while premium vendors absorb certification costs into bundled service pricing. This single-source dependency for specialized image sensors forces procurement officers to accept extended delivery schedules or pay expedite premiums, reshaping how municipal buyers evaluate total cost of ownership across vendor tiers.
Pricing Analysis
Municipal purchasing cooperatives anchor pricing structures around multi-year service entitlements rather than upfront hardware acquisition. Three-tier pricing stratifies across certified AI analytics platforms, standard interoperability-compliant systems, and economy-grade passive recording equipment. Cost compression in the economy tier intensifies because Indian and Southeast Asian suppliers compete on component localization under domestic manufacturing incentives. State emergency management agencies in the United States exhibit lowest price sensitivity due to federal infrastructure funding, while smaller municipalities in Eastern Europe face acute budget constraints that drive subscription-based analytics adoption.
Supply Chain Analysis
Specialized image sensors for low-light detection draw from Taiwanese foundry capacity, with secondary sourcing from South Korean memory suppliers and German optical component specialists. Hardened camera modules rest on aluminum enclosure fabrication, electromagnetic shielding materials, and edge computing chipsets. Single-source vulnerability concentrates in Taiwanese semiconductor fabrication, where geopolitical friction threatens lead time stability for critical infrastructure deployments. Distribution runs through authorized systems integrators who bundle installation with maintenance entitlements, extending vendor control over multi-decade asset lifecycles.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Outdoor public safety sits at an early-cycle expansion phase where AI-enabled edge analytics penetration in municipal procurement remains below saturation thresholds, with federal modernization programs in the United States and EU AI Act compliance mandates in Germany accelerating replacement timelines.
For Market Incumbents: Entrench municipal relationships through captive financing arms that underwrite lease-based revenue recognition, matching Motorola Solutions' balance-sheet capacity for decade-long service contracts. Invest in Project Stedfast certification laboratories to reduce interoperability testing backlogs that delay field activation. Counter emerging cloud-native challengers by bundling predictive maintenance analytics with hardware refresh cycles. For New Entrants and Emerging Players: Rural coverage gaps in India's smart city corridors offer the most penetrable entry point, where edge computing specifications reduce bandwidth dependency and BIS certification pathways reward domestic manufacturing localization. Target state police modernization budgets in Maharashtra and Karnataka with solar-powered remote deployment systems. Pursue partnership routes with established systems integrators rather than direct municipal sales to bypass procurement qualification barriers. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors full-stack integrators with regulatory affairs functions across multiple jurisdictions. Long-term viability hinges on algorithmic transparency compliance as EU AI Act enforcement tightens. Acquisition target archetypes include edge computing specialists with hardened hardware IP and certified AI analytics platforms with municipal reference deployments. Watch FAA operational waiver progress for beyond-visual-line-of-sight drone patrols as inflection indicator for automated response coverage expansion.| Strategic Initiative | Industry Significance |
|---|---|
| AI Analytics Platform Certification | EU AI Act compliance accelerates procurement preference in German and French municipal tenders. |
| Domestic Manufacturing Localization | India's PLI scheme attracts component sourcing for BIS-certified video analytics hardware. |
| Edge Computing Deployment | On-device processing reduces bandwidth costs for rural surveillance corridors in Maharashtra. |
| Subscription Evidence Management | Cloud-based platforms displace capital expenditure for smaller municipalities without IT infrastructure. |
| Predictive Maintenance Integration | Convergence of thermal imaging and vibration sensors enables pre-failure detection on utility substations. |
Research Methodology
A standing panel of municipal procurement officers, state emergency management directors, systems integration engineers, and regulatory affairs specialists provided ongoing calibration across the study period. Primary interviews with hardened electronics manufacturers and smart city authority technical directors combined with secondary validation against FCC equipment authorization databases, EU AI Act implementation guidance, and Indian BIS certification registries. Bottom-up demand modeling from municipal budget allocations triangulated against top-down vendor revenue segmentation across product categories.
Scenario-bracketing framed volume and value outputs across the projection horizon, with sensitivity testing for regulatory acceleration and supply disruption events. Segmentation dimensions modeled include product type, end-user institution scale, technology architecture, and installation flexibility. CAGRs derived from replacement cycle analysis and upgrade path penetration curves incorporated edge computing adoption rates and AI analytics certification timelines as industry-specific forecast inputs.
The forecast holds incumbent behavior within observed patterns; aggressive moves by cloud-native analytics challengers or rapid FAA regulatory liberalization for drone operations would shift outcomes beyond modeled ranges. Cross-checking against municipal capital expenditure disclosures and federal infrastructure spending appropriations is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Public Safety
Global Wireless Broadband in Public Safety Market
Public Safety
Crime Risk Report Market
Public Safety
Europe Public Safety Market
Public Safety
Public Safety Market
Public Safety
US Mass Notification Systems Market
Public Safety
Crowd Management System Market
Public Safety
Global Public Safety in Building Wireless Das System Market
Public Safety
Public Safety Drones Market
Public Safety
Latin America Public Safety Market
Public Safety
Middle East Crime and Combat Market
Public Safety
Voice Evacuation Systems Market
Public Safety
LAMEA Wireless Broadband in Public Safety Market
Public Safety
Global Public Safety Analytics Market
Public Safety
Public Safety in-Building Wireless Distributed Antenna System (DAS) Market
Public Safety
Global Public Safety and Security Market
Public Safety
Global Public Safety Solution Market