
 Household Smart Safe Market | 2026-2036
Household Smart Safe Market Size, Share, and Industry Trends Forecast 2026-2036
Household Smart Safe Market Insights
Biometric authentication is fragmenting the traditional lock-and-key architecture that long dominated residential security. SentrySafe leverages its brand strength in fire-resistant enclosures to extend into fingerprint-enabled models. Yale Safe anchors its position through deep channel control with locksmith networks and home improvement retailers. Hupai competes on manufacturing scale, supplying OEM biometric modules to multiple private-label brands across Asia.
A household smart safe is an electronically controlled residential security container incorporating sensors, wireless communication modules, and motorized locking mechanisms, typically constructed from 12- to 18-gauge steel with fireboard insulation rated for temperatures exceeding 1,700°F for 30-60 minutes, designed to protect documents, firearms, jewelry, and digital media from theft, fire, and unauthorized access. Biometric safes and smart connected safes command the widest margin pools as consumers trade up from keypad models for faster access and remote monitoring. The homeowner segment dominates unit volume, while property managers represent the fastest-growing channel as multifamily operators standardize on IoT-integrated units for amenity differentiation.
FCC certification governs wireless transmission protocols for Wi-Fi and Bluetooth-enabled safes sold in the United States, while CE marking and GDPR compliance shape product design and data handling for European market access. China's MIIT enforces GB standards for wireless device interoperability within domestic smart home ecosystems. Stakeholders must monitor evolving cybersecurity mandates across jurisdictions, as firmware update requirements and encryption standards increasingly determine which connected safe architectures remain commercially viable.
Market Dynamics
Biometric authentication modules and wireless connectivity protocols are compressing replacement cycles while fragmenting the traditional lock-and-key architecture that dominated residential security for decades. FCC certification requirements in the United States and GDPR compliance mandates in Europe are forcing architectural redesigns that favor modular firmware-upgradable platforms over fixed-electronics designs.
Growth Catalysts
- GDPR-Driven Cybersecurity Upgrades:European data protection mandates are compelling manufacturers to embed hardware encryption and secure boot protocols, creating pull for premium connected safe models that command wider margins than keypad-only alternatives.
- Smart Home Ecosystem Integration:China's MIIT-enforced GB standards for wireless interoperability are accelerating adoption of safes that communicate with domestic IoT platforms, shortening replacement cycles relative to Western markets.
- Multifamily Amenity Competition:Property managers across suburban developments are standardizing on biometric-enabled units as differentiation tools, converting a historically individual-purchase category into bulk procurement contracts.
Market Restraints
- Steel Input Volatility:Fluctuations in 12- to 18-gauge cold-rolled steel pricing compress margin pools for manufacturers lacking long-term supply agreements with mill operators.
- Biometric Sensor Supply Concentration:OEM fingerprint module production clusters heavily in select Asian manufacturing zones, exposing brands to single-source risk during logistics disruptions.
- Fireboard Insulation Sourcing:Specialized mineral wool and ceramic fiber formulations rated for 1,700°F protection face limited qualified suppliers, constraining rapid capacity expansion.
Strategic Opportunities
- Underpenetrated German Market:CE marking and F-Gas Regulation familiarity among local distributors creates lower barriers for connected safe entry compared to markets requiring fresh certification infrastructure.
- Convergence of Biometrics and Battery Chemistry:Lithium-ion cell improvements enabling 12+ month standby operation without hardwiring are unlocking retrofit demand among renters prohibited from electrical modifications.
- Direct-to-Consumer Channel Expansion:Bypassing locksmith networks and home improvement retailers through manufacturer-owned e-commerce captures margin previously allocated to wholesale intermediaries.
Industry Challenges
- Firmware Engineering Talent Scarcity:Embedded systems developers capable of implementing over-the-air update architectures with rollback safeguards command premium compensation, straining R&D budgets.
- Multi-Jurisdiction Certification Timelines:Simultaneous pursuit of FCC, CE marking, and MIIT approvals extends time-to-market by 8-14 months for new connected safe platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Household Smart Safe Market |
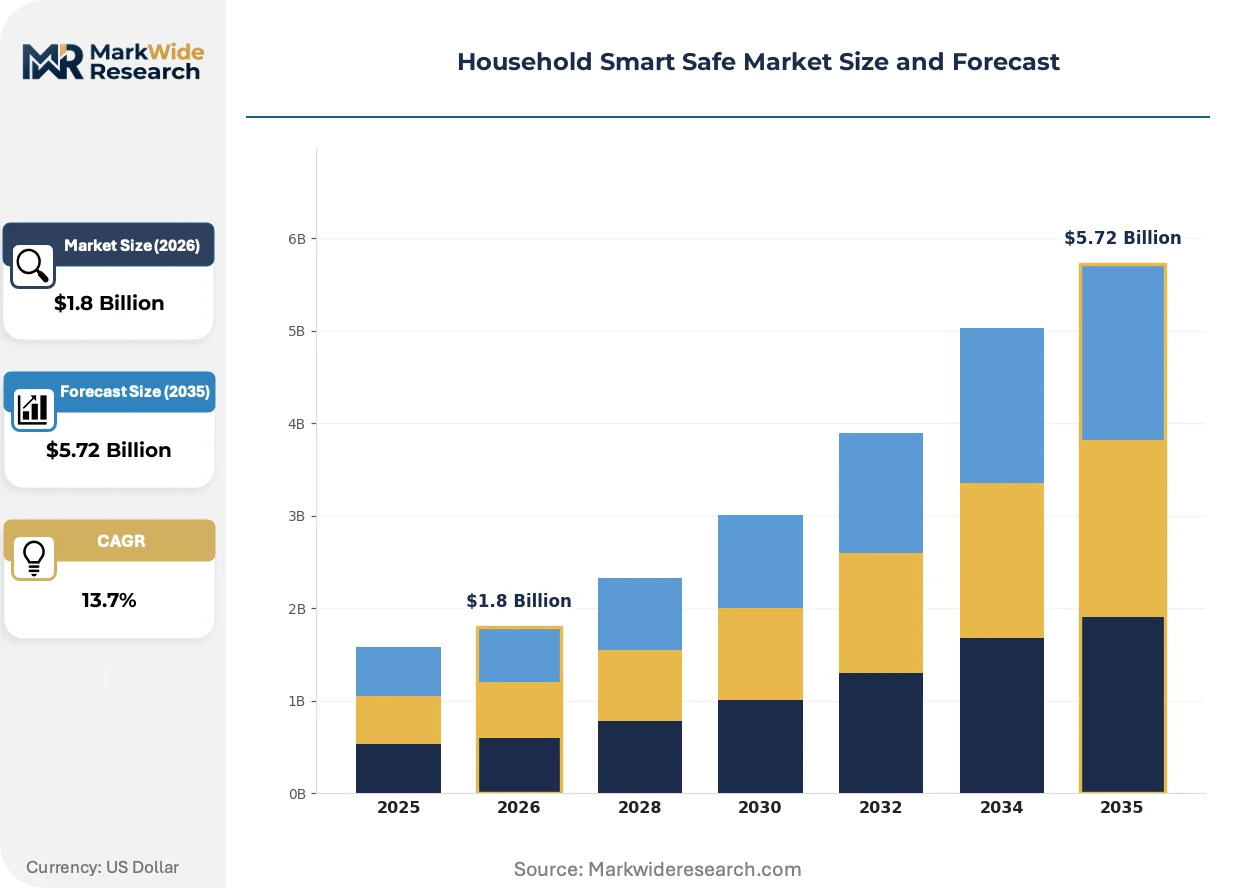
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $5.72 Billion |
| CAGR (2026 – 2036) | 13.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Biometric Safes, Keypad Safes, Digital Safes, Smart Connected Safes End User: Homeowners, Renters, Small Business Owners, Property Managers Connectivity: Wi-Fi Enabled, Bluetooth Enabled, IoT Integrated, Standalone Security Level: Basic Security, Moderate Security, High Security, Ultra High Security |
| Companies Covered | SentrySafe, Yale Safe, Phoenix Safe, Gunnebo, Hupai, FireKing, Fort Knox, Boca do Lobo, Buben & Zorweg, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Household Smart Safe Market Trends and Innovations
Capacitive fingerprint sensors with liveness detection are displacing optical biometric modules across mid-tier and premium residential safe lines. This sensor transition coincides with wireless protocol standardization pressures that favor architectures capable of firmware evolution without hardware replacement.
Capacitive fingerprint sensors with spoof-resistant algorithms are rendering obsolete optical biometric modules that remain vulnerable to lifted-print attacks. Homeowners in suburban developments are adopting these units at accelerated pace as insurance underwriters begin recognizing certified biometric protection for premium discounts. The technology shift is compressing margin pools for manufacturers still dependent on optical sensor supply chains.
GDPR Article 32 security-of-processing requirements are mandating hardware-level encryption for connected safes storing access logs or biometric templates. Manufacturers targeting European market access must redesign data handling architectures to achieve pseudonymization by default. This regulatory pressure most acutely affects Wi-Fi-enabled models with cloud backup features, driving migration toward local-only storage configurations.
Subscription-based remote monitoring services are unbundling from hardware purchases as property managers seek operational expenditure treatment for security amenities. Multifamily operators in China are piloting per-unit monthly fees that include firmware maintenance and breach alert dispatch, displacing traditional capital expenditure ownership models. This service unbundling is most visible in smart home ecosystem-integrated developments where platform operators already command resident relationship infrastructure.
Household Smart Safe Market Segmentation
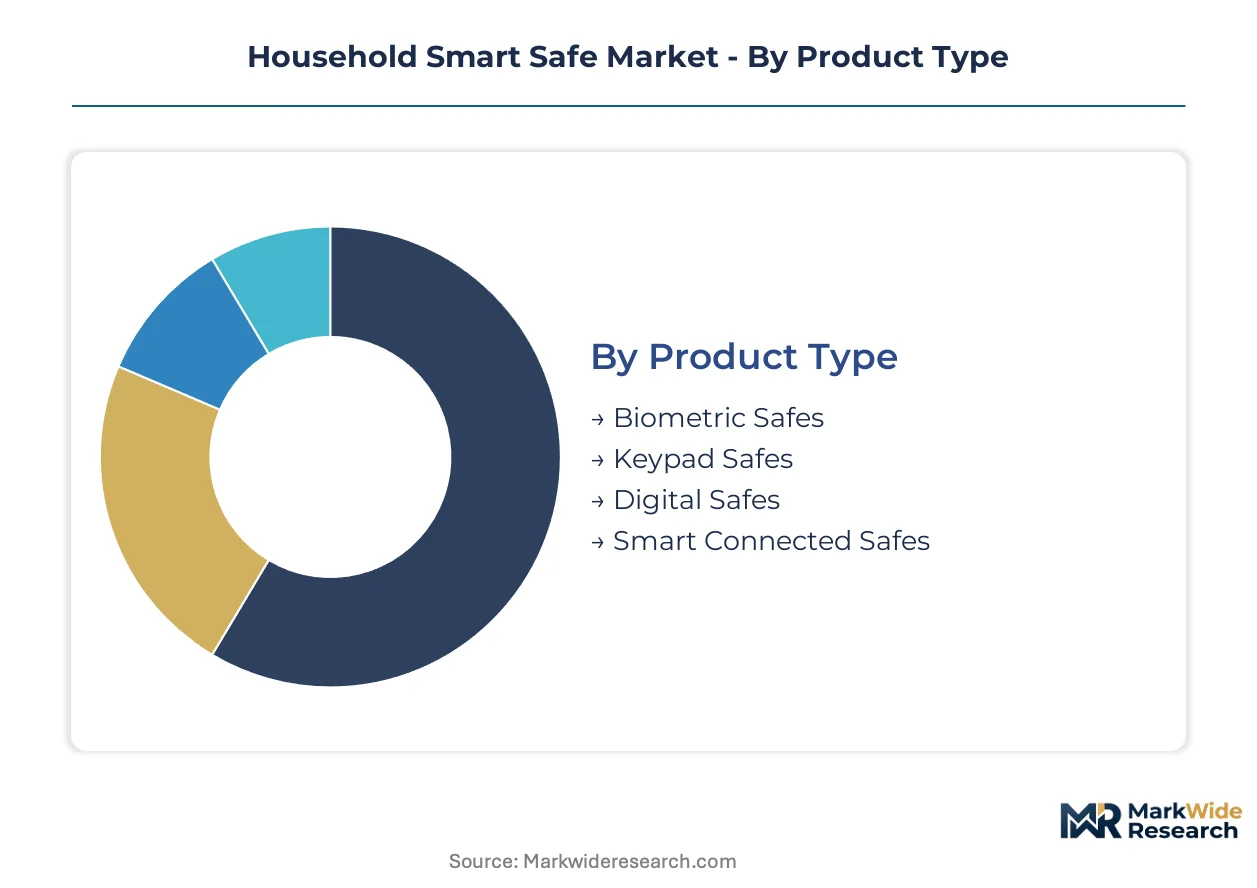
Segmentation in the household smart safe market exposes divergent replacement dynamics. Biometric and connected models compress hardware cycles through firmware-dependent feature evolution, while mechanical alternatives persist in price-sensitive channels.
Product Type:
Replacement velocity varies sharply across this dimension, with connected platforms demanding annual firmware refreshes while mechanical designs endure for decades.
- Biometric Safes:Capacitive fingerprint sensors with liveness detection now dominate premium residential lines. Demand clusters in suburban US developments where insurance underwriters recognize certified biometric protection for premium discounts.
- Smart Connected Safes:Wi-Fi and Bluetooth architectures enable remote monitoring and over-the-air security patches. China's MIIT-enforced GB standards accelerate adoption where smart home ecosystem integration shortens replacement cycles relative to Western markets.
- Keypad Safes:Electromechanical PIN entry systems retain cost advantage in multifamily bulk procurement contracts.
- Digital Safes:LCD-display electronic locks without wireless connectivity occupy the mid-tier price band for document storage applications.
Keypad safes anchor the volume base while smart connected safes gain share at the steepest rate.
End User:
Procurement authority and installation constraints reshape product specifications across customer types, from hardwired permanent fixtures to battery-powered portable units.
- Homeowners:Permanent installation tolerance enables hardwired connected safes with cloud backup features. GDPR Article 32 compliance costs in Europe push this segment toward local-storage architectures.
- Property Managers:Multifamily operators standardize on biometric-enabled units as amenity differentiation tools. FCC certification requirements in the US extend procurement timelines but lock in supplier relationships.
- Renters:Lease restrictions on electrical modifications drive demand for lithium-ion powered models with 12+ month standby operation.
- Small Business Owners:Commercial-grade fire resistance ratings intersect with residential form factors for home-office document protection.
Homeowners dominate absolute unit volume while property managers expand most quickly through bulk standardization.
Connectivity:
Wireless protocol selection determines regulatory exposure and ongoing service revenue potential, with cloud-dependent architectures facing tightening data localization mandates.
- IoT Integrated:Deep smart home platform binding enables automated scene triggers and centralized monitoring. China's domestic ecosystem operators command resident relationship infrastructure that accelerates service unbundling.
- Wi-Fi Enabled:Direct internet connectivity supports remote breach alerts but triggers GDPR hardware encryption requirements for European market access.
- Bluetooth Enabled:Local-range wireless avoids FCC transmission certification complexity while enabling smartphone-based access logging.
- Standalone:Non-connected electromechanical designs persist where cybersecurity skepticism or connectivity infrastructure gaps dominate.
Standalone units retain the installed base while IoT integrated configurations climb the fastest.
Security Level:
Certification tier determines steel gauge specifications, fireboard insulation ratings, and biometric sensor accuracy thresholds, with cost scaling non-linearly at the top tier.
- High Security:12-gauge steel construction with 1,700°F fireboard insulation and capacitive biometric modules. CE marking and F-Gas Regulation familiarity in Germany lower distribution barriers for this tier.
- Ultra High Security:Reinforced door bolts, drill-resistant hardplates, and multi-factor authentication combining biometrics with PIN. Limited qualified suppliers for specialized mineral wool formulations constrain capacity expansion.
- Moderate Security:16-gauge steel with optical fingerprint sensors or keypad entry for jewelry and document storage.
- Basic Security:18-gauge steel construction with mechanical override keys for low-value item protection.
Moderate security holds the broadest channel presence while ultra high security commands the steepest margin expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chinese manufacturers export biometric-enabled safe modules to European distributors navigating GDPR hardware encryption mandates, while US buyers source fire-resistant enclosures from domestic fabricators facing FCC certification timelines.
United States
Suburban homeowners in Texas and Florida drive demand for insurance-recognized biometric protection. FCC certification governs Wi-Fi and Bluetooth transmission protocols for connected safe architectures. Dallas-Fort Worth hosts distribution centers supplying locksmith networks and home improvement retailers across the Sun Belt.
Germany
CE marking familiarity and F-Gas Regulation compliance among Bavarian distributors lower barriers for premium connected safe entry. GDPR Article 32 mandates hardware-level encryption for cloud-backup models storing access logs. Stuttgart industrial clusters specialize in capacitive sensor integration for mid-tier residential lines.
China
MIIT-enforced GB standards accelerate smart home ecosystem integration, shortening replacement cycles versus Western markets. Domestic platform operators command resident relationship infrastructure enabling subscription-based remote monitoring pilots. Shenzhen manufacturing zones concentrate OEM fingerprint module production for private-label brands across Asia.
United Kingdom
GDPR compliance costs push homeowners toward local-storage architectures without cloud backup features. London property managers standardize on biometric-enabled units as multifamily amenity differentiation tools. Midlands distribution hubs coordinate locksmith network procurement for suburban developments.
Japan
METI guidelines shape wireless device interoperability standards for smart home platform binding. Kanto region homeowners prioritize lithium-ion powered models with extended standby operation for rental restrictions on electrical modifications. Osaka-based fabricators supply fireboard-insulated enclosures rated for 1,700°F protection.
Household Smart Safe Market Competitive Landscape
Channel-controlling players compete with product-specialist players across tiered market positions. The vendor base separates into scale-driven OEM suppliers, brand-holding distributors with locksmith network relationships, and premium-tier design houses. Three archetypes dominate: manufacturing-scale module suppliers, fire-resistance heritage brands extending into biometrics, and luxury-positioned craftsmanship specialists. Competitive moves concentrate on firmware-upgradable platform redesigns and direct-to-consumer channel bypass of wholesale intermediaries.
Within the manufacturing-scale tier, Hupai exemplifies OEM biometric module supply to multiple private-label brands. SentrySafe and Yale Safe occupy positions on opposite vectors: the former represents fire-resistant enclosure heritage extending into fingerprint-enabled lines, while the latter anchors channel control through deep locksmith network and home improvement retailer relationships. These three names illustrate how competitive positioning fragments across manufacturing scale, brand extension, and distribution architecture.
| Leading Market Players |
|---|
| SentrySafe |
| Yale Safe |
| Phoenix Safe |
| Gunnebo |
| Hupai |
| FireKing |
| Fort Knox |
| Boca do Lobo |
| Buben & Zorweg |
| Others |
Pricing and Supply Chain Analysis
Steel input volatility in 12- to 18-gauge cold-rolled steel pricing determines both pricing tier spreads and supply chain shape, forcing manufacturers to lock in mill agreements or absorb margin compression that widens the gap between basic keypad units and premium biometric models.
Pricing Analysis
Capacitive fingerprint sensors with liveness detection command a generation gap premium over optical modules and mechanical alternatives. Three-tier pricing structure across premium, standard, and economy levels separates biometric-enabled connected safes from keypad electromechanical units and basic mechanical designs. Cost compression in mid-tier digital safes is intensifying because optical sensor oversupply from Asian module producers erodes differentiation. Property managers in multifamily procurement exhibit highest price sensitivity, while suburban homeowners seeking insurance-recognized biometric protection show lowest elasticity.
Supply Chain Analysis
Shenzhen manufacturing zones concentrate OEM biometric module production for private-label brands across Asia. Supply draws from China for fingerprint sensors, Japan for fireboard insulation rated to 1,700°F, and Germany for capacitive sensor integration equipment. Single-source vulnerability in specialized mineral wool formulations constrains rapid capacity expansion for ultra high security tiers. Distribution runs through locksmith networks and home improvement retailers in Western markets, while direct-to-consumer channels gain share in smart home ecosystem-integrated developments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Firmware engineering talent capable of implementing over-the-air update architectures with rollback safeguards represents the critical capability gap separating viable connected safe platforms from obsolete fixed-electronics designs.
For Market Incumbents: Harden supply chain resilience by securing long-term agreements with 12-gauge steel mill operators and qualifying secondary biometric sensor sources outside Shenzhen manufacturing zones. Deepen channel control through exclusive locksmith network partnerships before direct-to-consumer competitors erode wholesale intermediation margins. For New Entrants and Emerging Players: Battery-powered biometric safes with 12+ month standby operation represent the most penetrable entry point among renters prohibited from electrical modifications in Japanese and German urban markets. Target property manager bulk procurement contracts by piloting subscription-based remote monitoring services that convert capital expenditure to operational expenditure treatment. For Investors and Strategic Acquirers: The market sits at a firmware-platform consolidation phase that favors acquirers of modular architecture specialists with GDPR-compliant hardware encryption capabilities. Long-term viability hinges on ownership of over-the-air update infrastructure rather than hardware manufacturing scale. Watch for MIIT certification acceleration in China as the signal indicating which platform architectures will dominate smart home ecosystem integration.| Strategic Initiative | Industry Significance |
|---|---|
| Firmware-Platform Modularization | GDPR Article 32 compliance demands hardware-upgradable architectures that avoid hardware replacement cycles. |
| Biometric Sensor Backward Integration | Captive supply of capacitive fingerprint modules with liveness detection reduces single-source exposure to Shenzhen disruptions. |
| Direct-to-Consumer Channel Launch | Manufacturer-owned e-commerce captures margin previously allocated to Yale Safe's locksmith network intermediaries. |
| Subscription Service Unbundling | Property managers in China pilot per-unit monthly fees including firmware maintenance and breach alert dispatch. |
| Fireboard Insulation Supplier Diversification | Qualifying secondary mineral wool sources outside Japan unlocks capacity expansion for ultra high security tier production. |
Research Methodology
A standing panel of smart safe product managers, biometric sensor procurement leads at OEM manufacturers, property technology directors at multifamily operators, and locksmith network category buyers provided ongoing calibration across the analysis window. Primary interview findings were cross-validated against FCC certification databases, CE marking registries, MIIT GB standard filings, and customs trade records for steel gauge and fireboard insulation inputs. Bottom-up unit shipment estimates from distribution channel partners were triangulated with top-down smart home ecosystem penetration models.
Scenario-bracketing framed demand projections across baseline, accelerated replacement, and extended-cycle assumptions without year-specific milestones. Segmentation dimensions modeled include biometric authentication generation, connectivity protocol, security certification tier, and end-user procurement authority. CAGRs were derived from installed base turnover rates and smart home platform binding intensity. Forecast inputs incorporated lithium-ion cell chemistry improvements enabling extended standby operation and evolving GDPR hardware encryption mandate timelines.
Stress conditions across steel price volatility bands, biometric sensor supply disruptions, and certification timeline extensions were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding smart home ecosystem adoption curves and multifamily amenity standardization rates. Quarterly review of FCC certification queue lengths, MIIT GB standard revision announcements, and insurance underwriter biometric recognition policy changes is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Safety Equipment and Personal Protective Equipment (PPE)
Disposable Protective Clothing Market
Safety Equipment and Personal Protective Equipment (PPE)
Ballistic Shields Market
Safety Equipment and Personal Protective Equipment (PPE)
Isolation Gloves Market
Safety Equipment and Personal Protective Equipment (PPE)
Ballistic Floatation Vest Market
Safety Equipment and Personal Protective Equipment (PPE)
Disposable Respirator Market
Safety Equipment and Personal Protective Equipment (PPE)
Earmuffs Market
Safety Equipment and Personal Protective Equipment (PPE)
Non-Powered Air Purifying Respirator Market
Safety Equipment and Personal Protective Equipment (PPE)
Asia Pacific Gas Detector Market
Safety Equipment and Personal Protective Equipment (PPE)
Industrial Fall Protection Equipment Market
Safety Equipment and Personal Protective Equipment (PPE)
Smart Barrier Gate Market
Safety Equipment and Personal Protective Equipment (PPE)
Fall Protection Equipment Market
Safety Equipment and Personal Protective Equipment (PPE)
Global Face Shield Market
Safety Equipment and Personal Protective Equipment (PPE)
Asia-Pacific Fall Protection Market
Safety Equipment and Personal Protective Equipment (PPE)
Middle East and Africa N95 Mask Market
Safety Equipment and Personal Protective Equipment (PPE)
Supplied Air Respirators Market
Safety Equipment and Personal Protective Equipment (PPE)
Passenger Security Equipment Market