
 Public Safety LTE Market | 2026-2036
Public Safety LTE Market Size, Share, and Industry Trends Forecast 2026-2036
Public Safety LTE Market Analysis
The split between hardened mission-critical infrastructure and commercial-off-the-shelf broadband is realigning procurement patterns across public safety agencies. Motorola Solutions leverages decades of land-mobile-radio integration to anchor premium-tier contracts with federal customers. Samsung Electronics competes on device volume and chipset customization for hybrid deployment models. Ericsson dominates core network buildouts where governments prioritize vendor neutrality.
Public Safety LTE denotes a dedicated broadband wireless ecosystem operating on prioritized spectrum bands, typically between 700 MHz and 4.9 GHz, delivering sub-100-millisecond latency for real-time video and push-to-talk-over-cellular services. Its primary purpose is replacing narrowband voice systems with multimedia-capable networks that unify command, control, and situational awareness for emergency responders. Mission Critical Communications commands the largest value pool as agencies validate 3GPP Release 16 features for ultra-reliable low-latency performance. Private LTE deployments are expanding fastest among municipalities seeking sovereign control over subscriber identity management and encryption keys. Cloud-Based deployment models remain nascent in this sector due to stringent data residency requirements.
FCC FirstNet rules, ETSI MCX standards, and 3GPP security specifications collectively define product certification barriers and interoperability testing regimes. The FCC mandates Band 14 exclusivity for primary public safety users, while ETSI frameworks govern cross-border mutual aid compatibility in Europe. Stakeholders must weigh spectrum sovereignty against the operational flexibility of roaming onto commercial 5G networks during large-scale incidents.
Market Dynamics
The migration from narrowband Land Mobile Radio to broadband LTE infrastructure is compressing equipment refresh cycles and forcing agencies to renegotiate long-term vendor relationships around 3GPP Release 16 capabilities.
Growth Catalysts
- FCC FirstNet Band 14 Mandate:The United States reserves 700 MHz spectrum exclusively for primary public safety users, compelling municipal agencies to accelerate LTE procurement timelines.
- 3GPP Release 16 MCX Standards:Mission-critical push-to-talk-over-cellular specifications enable cross-border mutual aid compatibility across European emergency response networks.
- Urban Corridor Density:Metropolitan fire and police departments in Seoul, London, and New York City drive aggregate infrastructure spending through consolidated command center modernization.
Market Restraints
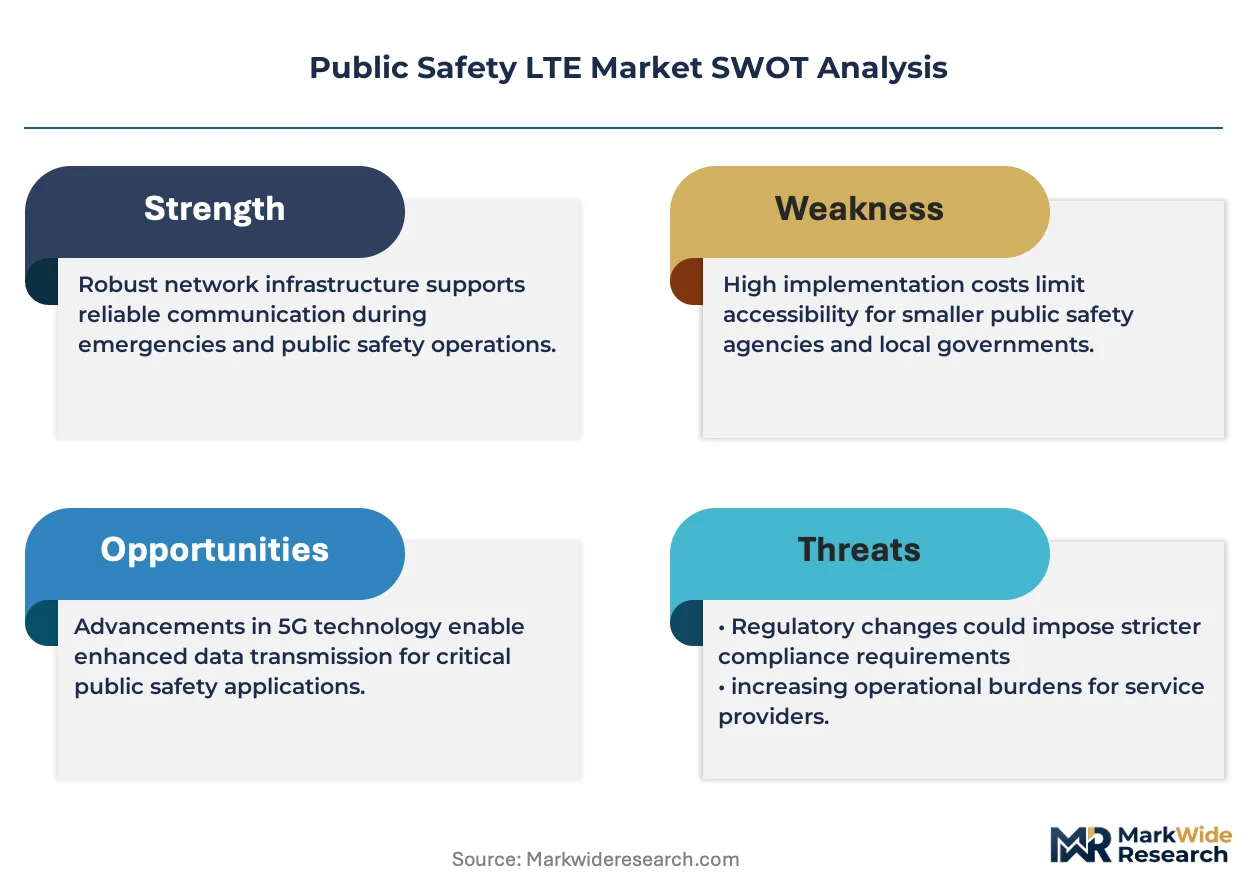
- Semiconductor Supply Concentration:Baseband processor fabrication depends on concentrated East Asian foundry capacity, creating procurement delays for mission-critical chipsets.
- ETSI Certification Friction:Multi-year interoperability testing timelines extend product launch schedules for equipment vendors seeking European market entry.
- LMR Infrastructure Sunk Costs:Existing narrowband tower and handset investments create organizational resistance to full broadband replacement in budget-constrained agencies.
Strategic Opportunities
- Private LTE Sovereignty Models:German municipalities are deploying subscriber identity management and encryption key control independent of commercial carriers.
- Cloud-Edge Hybrid Architectures:South Korean agencies pilot containerized core network functions with local breakout for video analytics at incident sites.
- 5G-IoT Sensor Convergence:Wearable biometric monitors and environmental hazard detectors integrate with LTE command dashboards for wildland firefighting crews.
Industry Challenges
- MCPTT Application Integration:Legacy dispatch console workflows require expensive middleware development to interoperate with broadband push-to-talk interfaces.
- Spectrum Engineering Talent Scarcity:Radio frequency planning expertise concentrated in aging LMR specialist pools does not translate to LTE network design requirements.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Public Safety LTE Market |
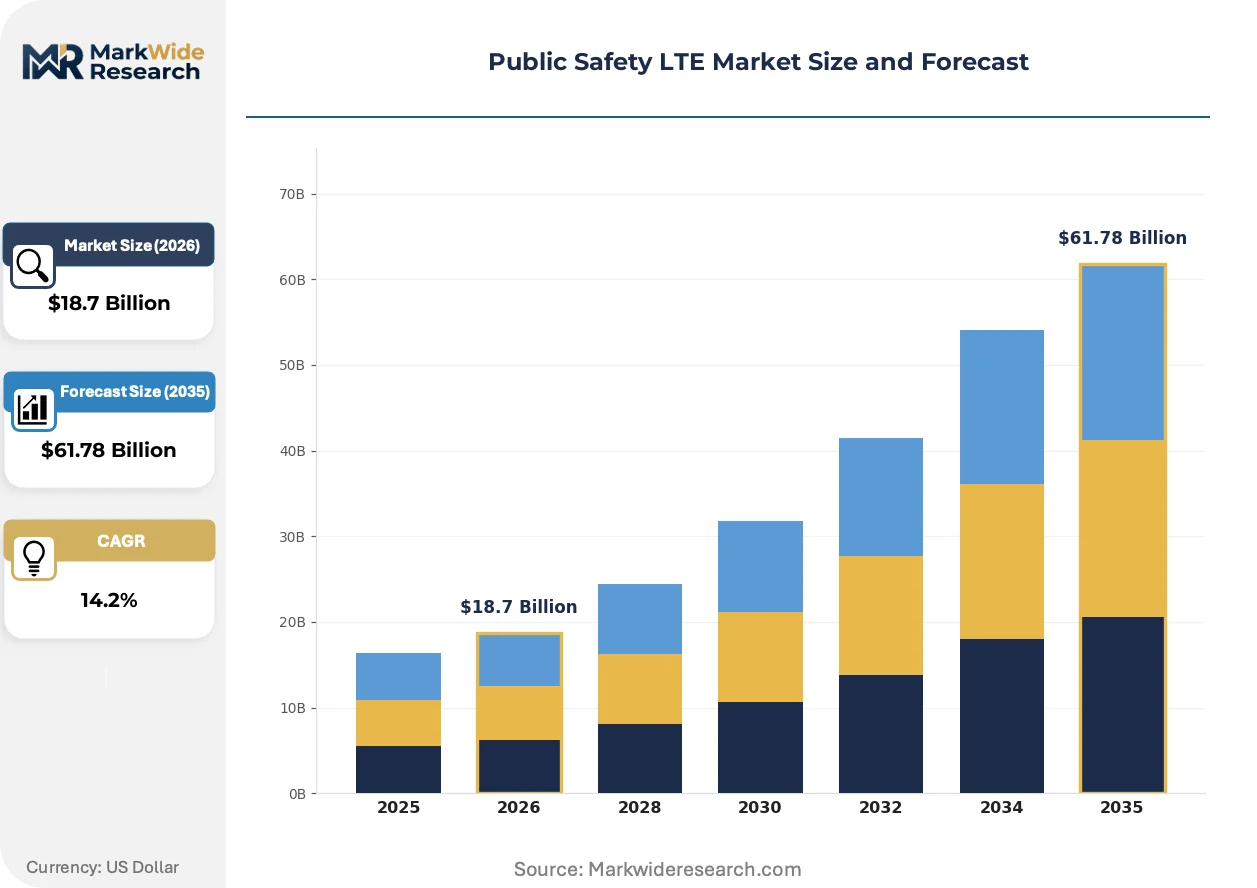
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $61.78 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
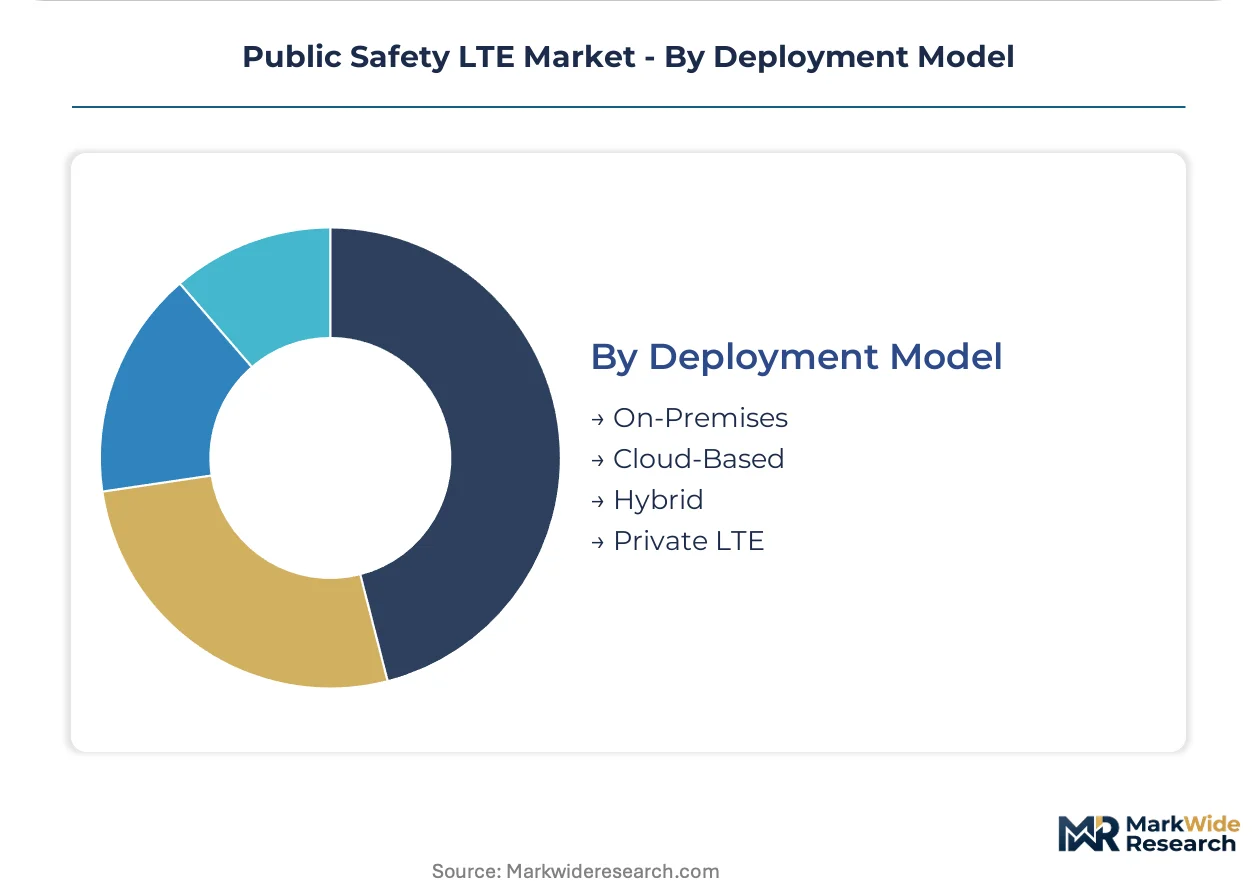
| Segmentation | Technology: Long Term Evolution, 5G NR, HSPA, CDMA End User: Fire Departments, Law Enforcement Agencies, Emergency Medical Services, Government Services Application: Mission Critical Communications, Video Surveillance, Data Sharing, Voice Communication Deployment Model: On-Premises, Cloud-Based, Hybrid, Private LTE |
| Companies Covered | Nokia Corporation, AT&T, Motorola Solutions, L3Harris Technologies, Hytera Communications Corporation Limited, General Dynamics Mission Systems, Ericsson, Samsung Electronics, Airbus SE, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Public Safety LTE Market Emerging Trajectories
Equipment vendors and system integrators are racing to certify hardened endpoints that bridge the reliability expectations of public safety users with the feature velocity of commercial smartphone platforms.
Push-to-talk-over-cellular technology is expanding into voice services that unify broadband data and narrowband reliability for frontline responders. State-level emergency management agencies in Texas and California are mandating MCPTT compatibility in new procurement specifications. This convergence is compressing the addressable market for standalone LMR handset manufacturers while opening subscription revenue streams for carrier-integrated service providers.
ETSI Mission-Critical Services standards are mandating cross-border interoperability testing for equipment deployed across European Union member states. Manufacturers must now validate MCX-compliant implementations against national regulatory variants in Germany, France, and Italy before securing framework contracts. The certification burden falls heaviest on mid-tier infrastructure vendors lacking dedicated European compliance teams.
Consolidated procurement vehicles are displacing single-agency purchasing for LTE infrastructure in the United States. The FirstNet Authority's nationwide contract vehicle enables state and local agencies to acquire pre-qualified equipment without independent RFP processes. Texas and California emergency communications offices have shifted the majority of their LTE spending through this centralized mechanism, reducing vendor sales cycle variability.
Public Safety LTE Market Segmentation
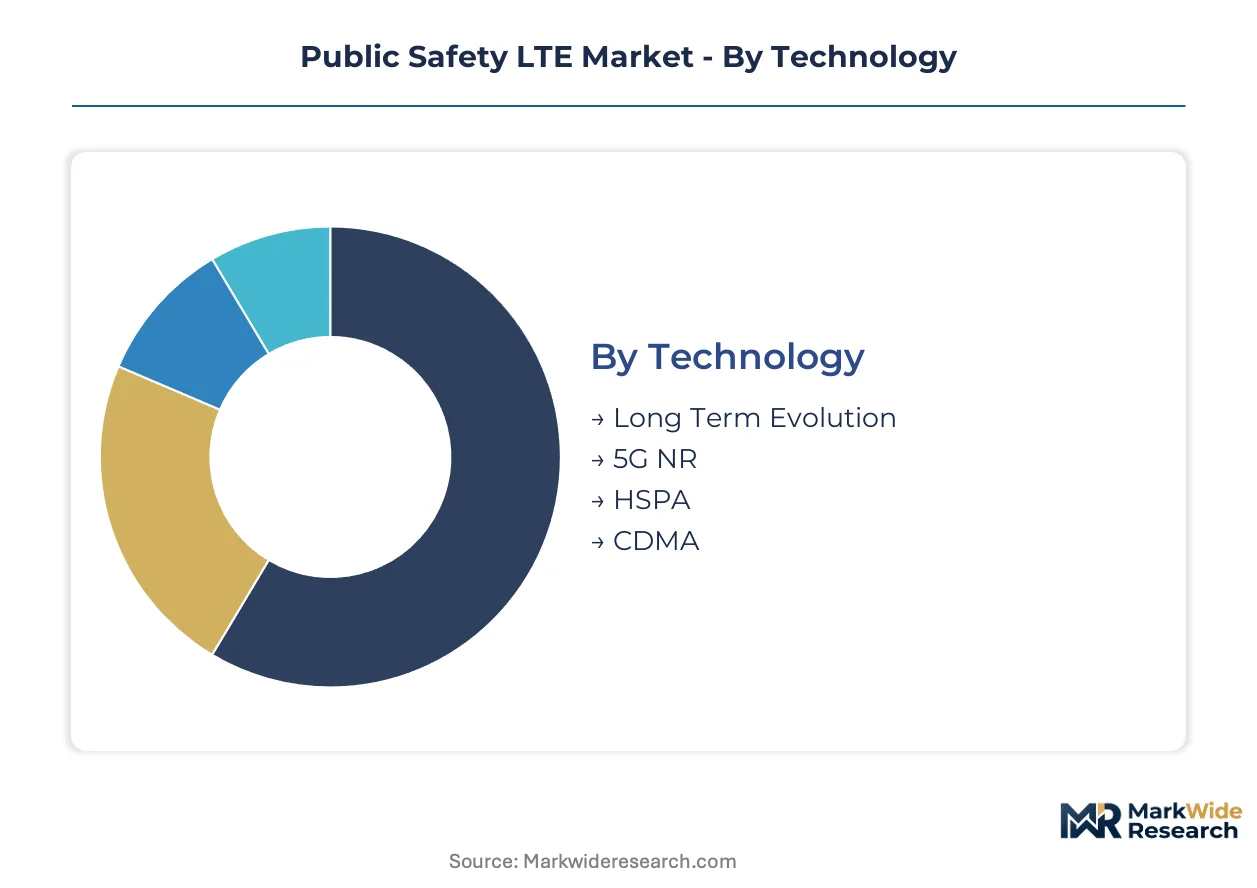
Agencies prioritize segments that minimize disruption to legacy dispatch workflows while enabling broadband multimedia. Procurement committees weigh spectrum sovereignty against interoperability mandates when evaluating deployment configurations.
Technology:
Equipment refresh cycles are compressing as agencies validate 3GPP Release 16 features against hardened reliability requirements.
- Long Term Evolution:Mature broadband infrastructure operating on prioritized 700 MHz and 4.9 GHz bands delivers sub-100-millisecond latency for real-time video streaming. Fire departments in Seoul and London are consolidating command center procurement around LTE core networks to replace narrowband voice systems.
- 5G NR:Next-generation radio interface enables network slicing for guaranteed quality-of-service during large-scale incidents. South Korean emergency management agencies pilot 5G-IoT convergence for wearable biometric monitors in wildland firefighting crews.
- HSPA:Legacy high-speed packet access provides transitional broadband capability where LTE spectrum allocation remains pending.
- CDMA:Older code-division multiple access infrastructure persists in budget-constrained rural jurisdictions with deferred upgrade timelines.
Volume placements concentrate in Long Term Evolution; the faster expansion belongs to 5G NR.
End User:
Procurement authority varies sharply across agency types, with consolidated state-level vehicles displacing single-department purchasing.
- Fire Departments:Frontline responders require hardened endpoints that survive thermal exposure and water immersion during structural fire operations. Metropolitan departments in New York City drive aggregate infrastructure spending through unified command center modernization mandates.
- Law Enforcement Agencies:Police departments demand encrypted broadband for body-worn video upload and real-time facial recognition at incident perimeters. Texas and California emergency communications offices have shifted the majority of LTE spending through FirstNet's centralized contract mechanism.
- Emergency Medical Services:Ambulance crews prioritize lightweight devices with seamless handoff between commercial and priority networks during patient transport.
- Government Services:Cross-agency coordination units require subscriber identity management independent of commercial carriers.
Fire Departments anchor current procurement volume; Emergency Medical Services are climbing the fastest as mobile health integration expands.
Application:
Functional requirements are diverging between voice-replacement mandates and emerging multimedia workloads.
- Mission Critical Communications:Ultra-reliable low-latency push-to-talk-over-cellular services replace legacy LMR systems with guaranteed availability during network congestion. State-level agencies in Texas and California mandate MCPTT compatibility in new procurement specifications.
- Video Surveillance:Real-time streaming from body-worn cameras and drone feeds demands prioritized bandwidth allocation. German municipalities deploying private LTE models retain sovereign control over encryption keys for sensitive footage.
- Data Sharing:Cross-agency incident databases require standardized interfaces for CAD system integration.
- Voice Communication:Narrowband voice persists as fallback where broadband coverage gaps remain unaddressed.
Mission Critical Communications dominates committed spending; Video Surveillance shows the steepest expansion trajectory as camera density increases.
Deployment Model:
Sovereignty requirements and data residency constraints are fragmenting architecture choices across jurisdictional boundaries.
- Private LTE:Independent subscriber identity management and encryption key control satisfy German municipal sovereignty mandates. German cities are deploying subscriber identity management and encryption key control independent of commercial carriers.
- On-Premises:Physical core network equipment at agency facilities meets stringent data residency requirements for sensitive operational data.
- Hybrid:Containerized core functions with local breakout for video analytics balance cloud economics with edge latency requirements. South Korean agencies pilot containerized core network functions with local breakout for video analytics at incident sites.
- Cloud-Based:Fully virtualized infrastructure remains nascent due to certification barriers and organizational resistance to off-premises control planes.
Private LTE is gaining share fastest as sovereignty concerns intensify; Hybrid architectures are climbing quickly where pilot programs demonstrate operational viability.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Seoul anchors Asia-Pacific infrastructure deployment as South Korean emergency management agencies pilot 5G-IoT convergence for wildland firefighting crews. Metropolitan command centers in London and New York City drive comparable modernization spending across their respective national frameworks.
United States
FCC Band 14 exclusivity compels municipal agencies to accelerate LTE procurement timelines for primary public safety users. The FirstNet Authority's nationwide contract vehicle enables state and local agencies to acquire pre-qualified equipment without independent RFP processes. Texas and California emergency communications offices have shifted the majority of their LTE spending through this centralized mechanism.
Germany
German municipalities are deploying subscriber identity management and encryption key control independent of commercial carriers to satisfy sovereignty mandates. ETSI MCX standards govern cross-border mutual aid compatibility across European emergency response networks. Industrial corridors in Bavaria and North Rhine-Westphalia concentrate private LTE deployment activity among municipal agencies.
South Korea
South Korean agencies pilot containerized core network functions with local breakout for video analytics at incident sites. The national spectrum regulator allocates prioritized bands between 700 MHz and 4.9 GHz for mission-critical communications. Seoul metropolitan fire and police departments consolidate command center procurement around hardened broadband infrastructure.
United Kingdom
Metropolitan police departments in London demand encrypted broadband for body-worn video upload and real-time facial recognition at incident perimeters. ETSI certification requirements extend product launch schedules for equipment vendors seeking European market entry. Greater Manchester and West Midlands emergency services coordinate cross-agency interoperability testing for MCPTT-compatible systems.
Public Safety LTE Market Vendor Landscape
Premium-margin players sit above commodity-margin players across spectrum integration depth and mission-critical certification breadth. The vendor base stratifies between hardened infrastructure specialists and commercial broadband adaptors. Three archetypes dominate: legacy LMR integrators pivoting to broadband, telecom equipment manufacturers customizing carrier-grade platforms, and defense contractors leveraging federal security clearances. Dominant competitive moves include strategic partnerships for interoperability certification and vertical integration into chipset customization.
Within the legacy integration tier, Motorola Solutions and L3Harris Technologies exemplify archetypes built on decades of federal customer relationships and land-mobile-radio infrastructure. Nokia Corporation and Ericsson occupy positions as telecom-native vendors prioritizing core network buildouts where governments emphasize vendor neutrality. Samsung Electronics anchors the device-volume segment through chipset customization for hybrid deployment models.
| Leading Market Players |
|---|
| Nokia Corporation |
| AT&T |
| Motorola Solutions |
| L3Harris Technologies |
| Hytera Communications Corporation Limited |
| General Dynamics Mission Systems |
| Ericsson |
| Samsung Electronics |
| Airbus SE |
| Others |
Supply Flow & Price Mechanics
The hardened-mission-critical versus commercial-off-the-shelf divide manifests in divergent pricing architectures and supply chain footprints across public safety LTE procurement. Premium-tier vendors command value-based premiums through FCC FirstNet certification and ETSI MCX validation, while commodity device manufacturers compete on volume scale with thinner margins and distributed sourcing.
Pricing Analysis
Uptime-guarantee contracts anchor value-based pricing for mission-critical infrastructure, with federal agencies paying substantial premiums for sub-100-millisecond latency assurance and Band 14 exclusivity. Price differentiation rests on certification grade—FCC FirstNet-approved equipment commands substantial premiums over non-certified alternatives—and vertical integration depth, with vendors controlling baseband chipset customization capturing margin from foundry-dependent competitors. Cost compression in commercial-off-the-shelf devices is intensifying because Samsung Electronics and other volume players are driving commoditization of hybrid deployment endpoints. Municipal fire departments exhibit highest price sensitivity due to budget constraints and sunk LMR investments, while federal emergency management agencies show lowest sensitivity given congressional appropriation security.
Supply Chain Analysis
Reverse-logistics networks for hardened endpoint refurbishment concentrate in South Korea and Taiwan, where Samsung Electronics and specialized defense contractors maintain captive remanufacturing facilities for thermal-damaged and water-immersed devices. Baseband processor fabrication draws from concentrated East Asian foundry capacity in Taiwan and South Korea, with mission-critical chipsets sourcing from TSMC and Samsung Foundry. Single-source vulnerability in semiconductor supply creates procurement delays when foundry capacity reallocates to commercial 5G volume. Distribution runs through consolidated procurement vehicles—FirstNet Authority's nationwide contract mechanism in the United States and framework agreements in Germany—rather than direct agency purchasing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Public Safety LTE operates as a cost-of-compliance market where FCC FirstNet certification and ETSI MCX validation create substantial barrier-to-entry moats that protect incumbent positions against unqualified challengers.
For Market Incumbents: Anticipate margin pressure from commercial 5G convergence by deepening backward integration into baseband chipset customization and securing captive foundry allocation agreements. Prioritize certification investment in ETSI MCX interoperability testing to defend European market share against telecom-native entrants lacking legacy LMR integration expertise. Channel control through FirstNet Authority pre-qualification status remains the critical defensive lever against emerging hybrid-deployment specialists.
For New Entrants and Emerging Players: Cloud-native core network virtualization offers the most penetrable wedge for market entry, targeting German municipalities seeking sovereign subscriber identity management independent of commercial carriers. Focus initial deployment on private LTE sovereignty models where data residency requirements disadvantage incumbent infrastructure vendors optimized for carrier-integrated architectures. A device-agnostic software go-to-market angle—containerized MCPTT middleware for legacy dispatch console integration—bypasses hardware certification timelines that entrench established players.
For Investors and Strategic Acquirers: Exit pathways concentrate in defense contractor acquisitions of hardened endpoint specialists possessing federal security clearances and FirstNet Authority relationships. Long-term viability favors vendors with demonstrated 3GPP Release 16 feature validation and cross-border ETSI certification breadth across multiple European jurisdictions. Monitor South Korean 5G-IoT convergence pilot outcomes as the critical inflection signal for sensor-integrated command platform adoption timelines.
| Strategic Initiative | Industry Significance |
|---|---|
| ETSI MCX Certification Investment | Cross-border interoperability validation opens framework contracts across Germany, France, and Italy. |
| Backward Integration into Baseband Chipsets | Captive supply of mission-critical processors insulates against Taiwan foundry allocation volatility. |
| Private LTE Sovereignty Deployment | German municipal mandates for encryption key control create premium-margin deployment opportunities. |
| Cloud-Edge Hybrid Architecture Pilot | South Korean agency validation of containerized core functions demonstrates operational viability. |
| 5G-IoT Sensor Platform Convergence | Wearable biometric integration with LTE command dashboards expands addressable market for wildland operations. |
Methodological Framework
FCC FirstNet deployment filings, ETSI MCX certification registries, and 3GPP standardization documents formed the secondary backbone for market sizing and competitive positioning analysis. Primary interviews with public safety communications directors, emergency management procurement officers, network infrastructure engineers, and carrier account executives validated equipment refresh cycle assumptions and sovereignty requirement trajectories. Bottom-up triangulation aggregated agency-level procurement data across Texas, California, New York, London, and Seoul metropolitan authorities, while top-down cross-checks applied national spectrum allocation frameworks to constrain total addressable market boundaries.
Analytical lens alternated between bottom-up agency aggregation and top-down spectrum allocation modeling across the projection horizon. Segmentation dimensions modeled include technology generation, end-user agency type, application function, and deployment architecture sovereignty level. CAGRs derived from equipment replacement cycle compression rates observed in FirstNet migration timelines and 3GPP Release 16 feature adoption curves. Industry-specific forecast inputs incorporated semiconductor foundry capacity allocation forecasts and ETSI certification pipeline durations.
Forecast precision tightens around the base case; tail outcomes carry wider variance under prolonged ETSI interoperability testing delays or sudden FCC spectrum reallocation decisions. Practitioners should monitor South Korean 5G-IoT pilot program outcomes and German municipal private LTE procurement award patterns for early signals of architecture preference shifts.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Public Safety
Europe Road Safety Market
Public Safety
Global Wireless Broadband in Public Safety Market
Public Safety
Crowd Management System Market
Public Safety
LAMEA Wireless Broadband in Public Safety Market
Public Safety
Europe Public Safety Market
Public Safety
Public Safety in-Building Wireless Distributed Antenna System (DAS) Market
Public Safety
AI for Public Security and Safety Market
Public Safety
Global IoT for Public Safety Market
Public Safety
Public Safety Market
Public Safety
Latin America Public Safety Market
Public Safety
Global Public Safety and Security Market
Public Safety
Voice Evacuation Systems Market
Public Safety
Europe Wireless Broadband in Public Safety Market
Public Safety
Asia-Pacific Public Safety Market
Public Safety
Global Public Safety Solution Market
Public Safety
Crime Risk Report Market