
 Global Smoke Evacuation Systems Market | 2026-2036
Global Smoke Evacuation Systems Market Size, Share, and Industry Trends Forecast 2026-2036
Global Smoke Evacuation Systems Market Foresight
HEPA-ultrasonic hybrid filtration is narrowing the performance gap between portable and centralized smoke evacuation architectures. CONMED Corporation leverages its electrosurgery portfolio to bundle evacuation units with generator sales. Medtronic anchors hospital-wide contracts through integrated operating room programs. Stryker competes on filter replacement economics and service attach rates.
Smoke evacuation systems are electromechanical devices that capture, filter, and neutralize surgical plume generated by electrosurgical instruments, lasers, and ultrasonic scalpels; systems typically achieve particle filtration efficiency exceeding 0.3 microns through multi-stage HEPA and activated carbon media, with flow rates calibrated to maintain clear visualization fields during procedures. Wall-mounted systems dominate installed base in tertiary hospitals where permanent infrastructure supports high-volume throughput, while portable units represent the fastest-growing category as ambulatory care facilities prioritize capital flexibility and room-to-room mobility. Ultrasonic filtration technology leads R&D investment due to its ability to address both particulate and gaseous phase contaminants in a single stage.
FDA 510(k) clearance pathways and EU MDR technical documentation requirements shape product development timelines and market access barriers for manufacturers seeking multi-jurisdictional placement. OSHA's surgical smoke hazard recognition initiatives and Japan's MHLW medical device quality standards further elevate filtration performance benchmarks across major markets. Stakeholders must monitor evolving national occupational exposure limits and filter certification protocols to anticipate procurement specification shifts.
Market Dynamics
HEPA-ultrasonic hybrid filtration is compressing the historical performance gap between portable and centralized smoke evacuation architectures, forcing manufacturers to recalibrate R&D roadmaps and hospital procurement committees to rewrite technical specifications.
Growth Catalysts
- OSHA workplace exposure limits:The United States agency's surgical smoke hazard recognition initiatives mandate enhanced filtration in operating rooms, compelling ambulatory surgical centers to upgrade legacy systems.
- Ambulatory surgical center expansion:Capital flexibility requirements at outpatient facilities in Germany and Japan accelerate portable unit placement over permanent wall-mounted infrastructure.
- EU MDR device classification rules:Tightened technical documentation requirements elevate filtration performance benchmarks across European procurement specifications.
Market Restraints
- Activated carbon media cost volatility:Supply concentration for specialized filtration materials in select Asian manufacturing clusters creates input price instability.
- Filter replacement economics:Recurring consumable expenses burden smaller ambulatory facilities with constrained operational budgets.
- Technical limitation in single-stage gaseous capture:Conventional HEPA systems fail to neutralize volatile organic compounds without secondary activated carbon stages.
Strategic Opportunities
- Underpenetrated outpatient networks:India's expanding private hospital sector lacks standardized smoke evacuation protocols, creating first-mover positioning for compliant system vendors.
- Technology convergence:Integration of electrosurgical generators with intelligent evacuation controls enables real-time plume detection and automated flow adjustment.
- Japan's MHLW medical device quality standards:Stringent certification requirements favor established manufacturers with documented quality management systems.
Industry Challenges
- Biomedical engineering talent scarcity:Specialized expertise in electromechanical filtration system design concentrates at established manufacturers, constraining new entrant scaling.
- FDA 510(k) clearance timelines:Multi-jurisdictional technical documentation requirements extend product development cycles and delay commercial launch windows.
- Legacy operating room integration complexity:Retrofitting wall-mounted evacuation infrastructure into existing surgical suites requires facility downtime and construction coordination.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Smoke Evacuation Systems Market |
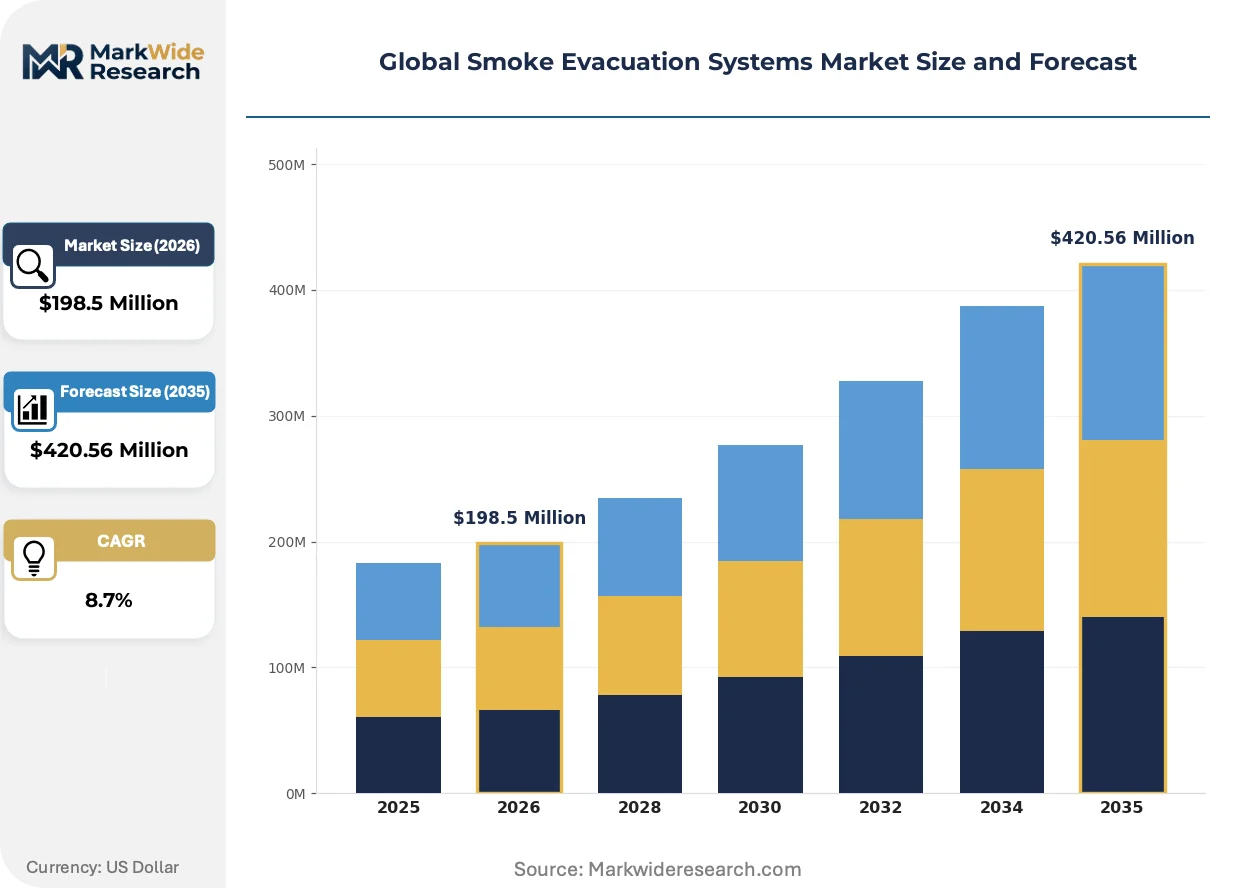
| Market Size in 2026 | $198.5 Million |
| Market Size in 2035 | $420.56 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Portable Units, Wall-Mounted Systems, Centralized Systems, Battery-Operated Devices Technology: Ultrasonic Filtration, HEPA Filtration, Activated Carbon Filtration, Electrostatic Precipitation Application: Minimally Invasive Surgery, Open Surgery, Dental Procedures, Dermatological Treatment End User: Surgical Centers, Dental Clinics, Ambulatory Care Facilities, Dermatology Clinics |
| Companies Covered | CONMED Corporation, Medtronic, Stryker, Johnson & Johnson, Olympus Corporation, Ecolab, Danaher Corporation, Zimmer Biomet, Utah Medical Products, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Smoke Evacuation Systems Market Shifts & Advancements
Filtration technology is converging with intelligent sensing and automated control systems, compressing the traditional trade-off between capture efficiency and operational flexibility that has historically segmented the installed base.
Ultrasonic filtration technology is virtualizing the distinction between particulate and gaseous phase contaminant management by addressing both hazards within a single processing stage. Tertiary hospitals in the United States and Germany are piloting these systems for high-volume laser surgery suites. This convergence is virtualizing the procurement category itself, collapsing what were previously separate HEPA and activated carbon evaluation criteria into unified performance specifications.
EU MDR technical documentation requirements are extending product development timelines and elevating barrier-to-entry thresholds for manufacturers seeking European market access. The regulation mandates comprehensive clinical evidence and post-market surveillance protocols that smaller competitors struggle to resource. Portable system categories face disproportionate compliance burden given their shorter product lifecycles and faster iteration cadences.
Hospital procurement committees are consolidating vendor relationships through integrated operating room program contracts rather than standalone equipment purchases. This behavioral shift concentrates purchasing authority at health system headquarters and displaces distributor-mediated transactions. The United States exhibits the most pronounced concentration, with multi-facility networks standardizing across dozens of surgical sites simultaneously.
Global Smoke Evacuation Systems Market Segmentation
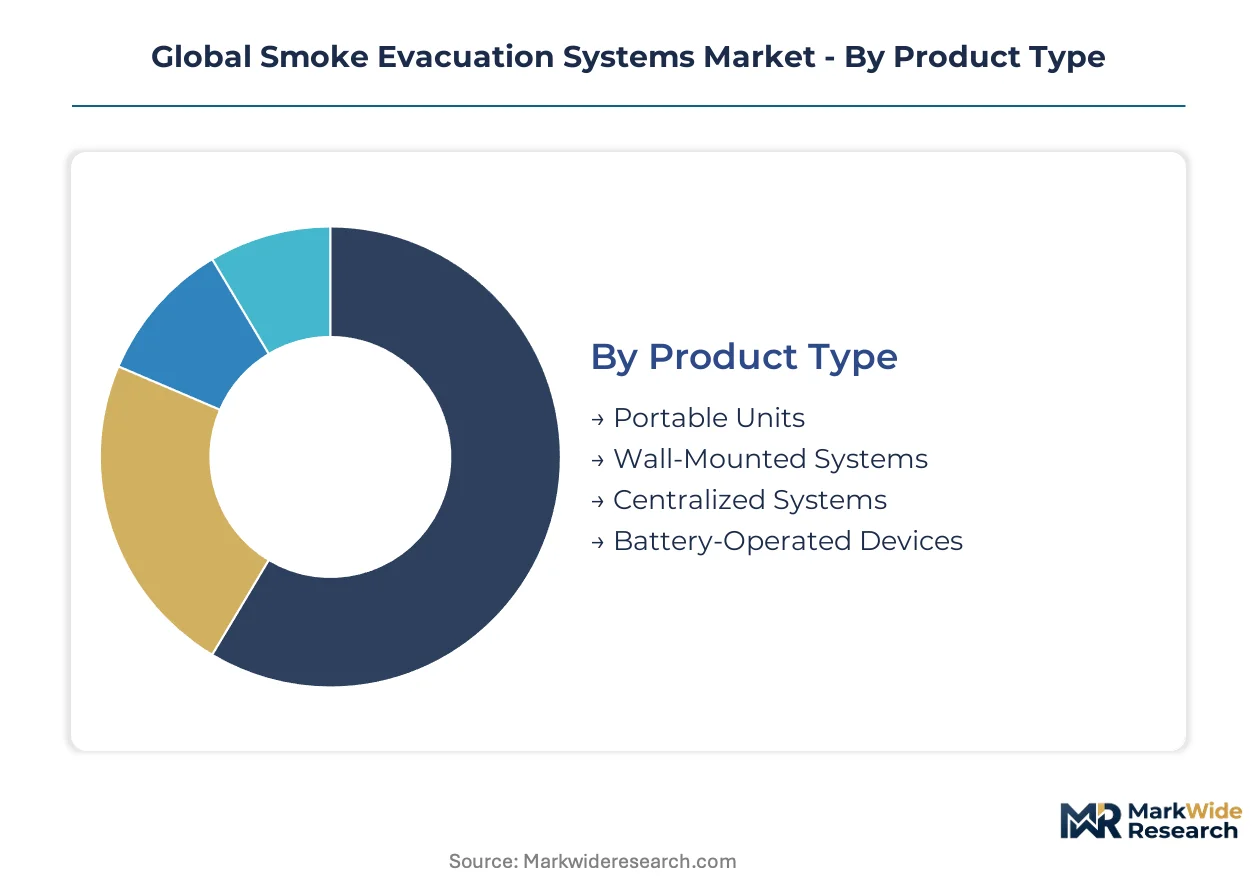
Surgical plume management requirements vary dramatically across facility types and procedure volumes, driving manufacturers to architect product portfolios that span mobility grades and filtration intensities. Procurement committees evaluate systems against procedure mix, infrastructure constraints, and regulatory exposure rather than unit economics alone.
Product Type:
Use-case spectrum spans capital-intensive permanent installations to flexible mobile units serving multi-room surgical workflows.
- Portable Units:Mobile electromechanical systems with castor-mounted housings and quick-connect tubing enable room-to-room deployment without facility modification. Demand concentrates at ambulatory surgical centers in Germany and Japan where capital flexibility outweighs throughput optimization.
- Wall-Mounted Systems:Fixed infrastructure integrated into surgical suite architecture delivers sustained high-flow filtration for high-volume electrosurgery and laser procedures. Tertiary hospitals in the United States favor permanent installations where procedure density justifies construction investment.
- Centralized Systems:Building-wide vacuum networks with distributed filtration nodes serve multiple operating theaters from a single mechanical plant.
- Battery-Operated Devices:Cordless evacuation units address field surgical applications and emergency response scenarios where electrical infrastructure is compromised or unavailable.
The dominant share belongs to Wall-Mounted Systems, while Portable Units are closing the gap fastest.
Technology:
Filtration performance hierarchy reflects contaminant phase complexity rather than particle size alone.
- Ultrasonic Filtration:Single-stage processing employs high-frequency mechanical vibration to agglomerate particulate matter and oxidize gaseous contaminants simultaneously. Tertiary hospitals in the United States pilot these systems for laser surgery suites where volatile organic compound neutralization is mandatory.
- HEPA Filtration:Multi-stage mechanical media achieving 99.97% efficiency at 0.3 microns remains the baseline specification for particulate capture in standard electrosurgical applications.
- Activated Carbon Filtration:Adsorptive media beds target odor and chemical vapor constituents that mechanical filtration cannot address.
- Electrostatic Precipitation:Ionization-based particle collection offers reduced pressure drop and extended service intervals compared to barrier filtration.
HEPA Filtration commands installed base leadership, though Ultrasonic Filtration is expanding most quickly as procurement specifications consolidate around unified performance metrics.
Application:
Procedure invasiveness determines plume generation intensity and evacuation flow rate requirements.
- Minimally Invasive Surgery:Laparoscopic and endoscopic procedures generate concentrated smoke columns requiring continuous suction maintenance of optical clarity. Surgical centers in Japan prioritize compact evacuation integration with trocar instrumentation.
- Open Surgery:Large incision exposure produces diffuse plume dispersion patterns demanding higher capture velocities and broader suction field coverage.
- Dental Procedures:High-speed instrumentation and laser soft-tissue applications generate localized aerosol burdens in confined operatory environments.
- Dermatological Treatment:Ablative laser and electrosurgical cosmetic procedures create intermittent smoke bursts requiring rapid response filtration.
Minimally Invasive Surgery anchors volume demand, while Dental Procedures are gaining share fastest as OSHA workplace exposure recognition extends to outpatient oral health settings.
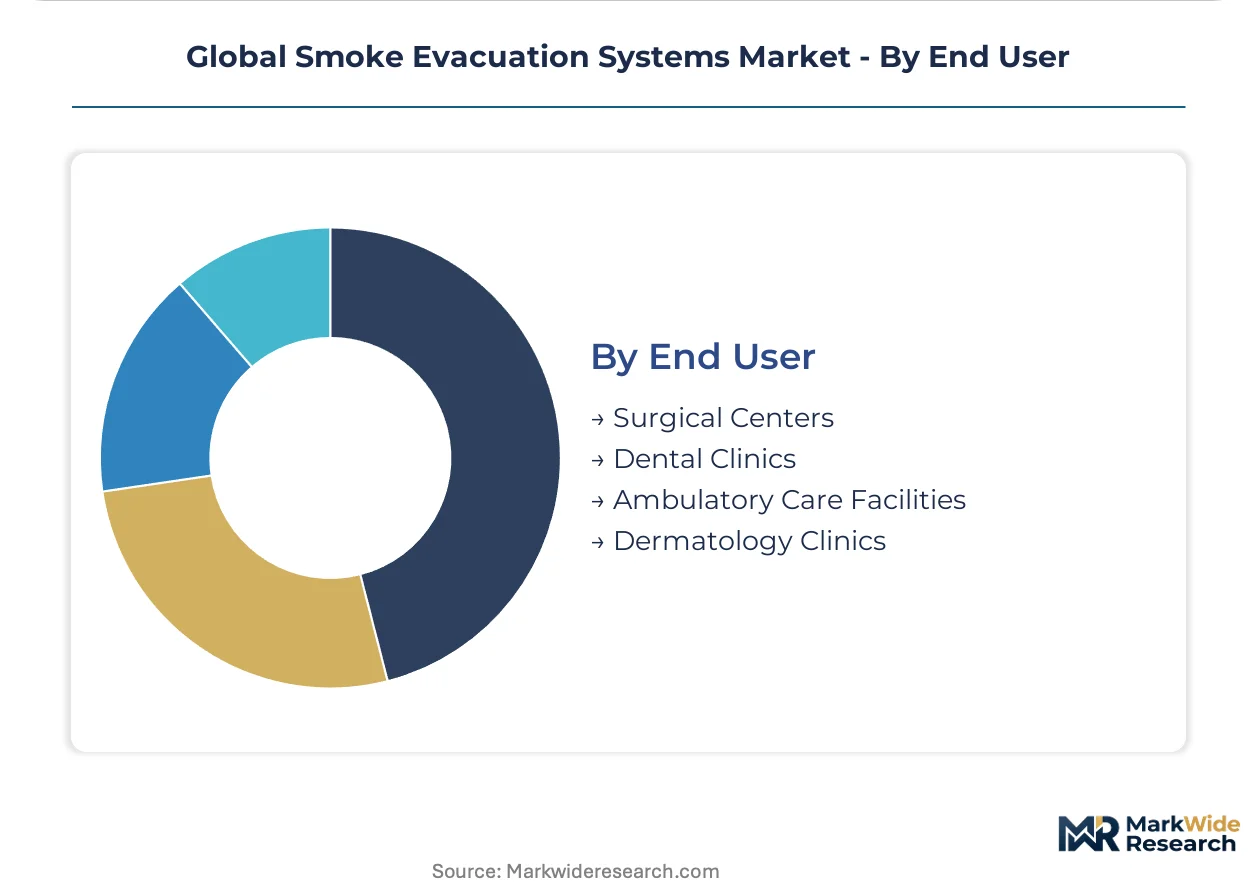
End User:
Facility scale and reimbursement structure dictate procurement authority concentration and equipment financing preferences.
- Surgical Centers:Dedicated outpatient facilities performing multi-specialty procedures under anesthesia generate sustained high-volume evacuation demand. Health system networks in the United States consolidate purchasing across facility portfolios.
- Ambulatory Care Facilities:Generalist outpatient settings with intermittent surgical capability prioritize portable units and service-inclusive leasing over capital acquisition.
- Dental Clinics:Solo and group practices face OSHA compliance deadlines for legacy equipment replacement without dedicated biomedical engineering support.
- Dermatology Clinics:Cosmetic procedure concentration drives demand for compact, aesthetic-compatible evacuation units with minimal operatory footprint.
Surgical Centers retain procurement volume leadership, though Ambulatory Care Facilities are climbing the fastest as certificate-of-need restrictions ease and outpatient migration accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany exports precision filtration components to surgical equipment manufacturers across the United States and Japan. Trade corridors concentrate high-value electromechanical subsystems within established medical device manufacturing networks.
United States
Ambulatory surgical center expansion and OSHA workplace exposure initiatives drive procurement of portable evacuation units. FDA 510(k) clearance pathways shape product development timelines for multi-jurisdictional manufacturers. Texas and Florida health system networks consolidate purchasing across facility portfolios.
Germany
Tertiary hospital infrastructure investment and EU MDR technical documentation requirements elevate filtration performance benchmarks. The country's national medical device regulator enforces stringent post-market surveillance protocols. Bavarian surgical equipment clusters supply integrated operating room programs across Central Europe.
Japan
Minimally invasive procedure volume growth and MHLW medical device quality standards accelerate unit replacement cycles. METI industrial policy supports domestic manufacturing of advanced filtration media. Osaka-Kobe medical device production corridors concentrate electromechanical system assembly.
India
Private hospital sector expansion creates first-mover positioning for compliant system vendors without standardized smoke evacuation protocols. CDSCO medical device registration requirements are tightening for imported electrosurgical accessories. Maharashtra and Karnataka urban hospital networks drive initial portable unit adoption.
United Kingdom
NHS procurement consolidation favors integrated operating room contracts over standalone equipment purchases. MHRA post-Brexit device regulations align with EU MDR technical standards. London and Southeast England health system headquarters centralize vendor selection authority.
Global Smoke Evacuation Systems Market Competitive Landscape
Channel-controlling players compete with product-specialist players for procurement committee attention in consolidated health system networks. The vendor base organizes around three strategic archetypes: diversified medical technology conglomerates with electrosurgery portfolios, dedicated surgical equipment specialists, and integrated operating room solution providers. Dominant competitive moves include bundling evacuation units with generator sales and anchoring hospital-wide contracts through service-inclusive leasing structures.
Within the diversified conglomerate tier, CONMED Corporation and Medtronic exemplify channel-control strategies that leverage existing surgical equipment relationships. Stryker occupies a position emphasizing filter replacement economics and service attach rates. These three entities represent contrasting approaches to procurement authority concentration: portfolio bundling, integrated program contracting, and consumable-driven recurring revenue models.
| Leading Market Players |
|---|
| CONMED Corporation |
| Medtronic |
| Stryker |
| Johnson & Johnson |
| Olympus Corporation |
| Ecolab |
| Danaher Corporation |
| Zimmer Biomet |
| Utah Medical Products |
| Others |
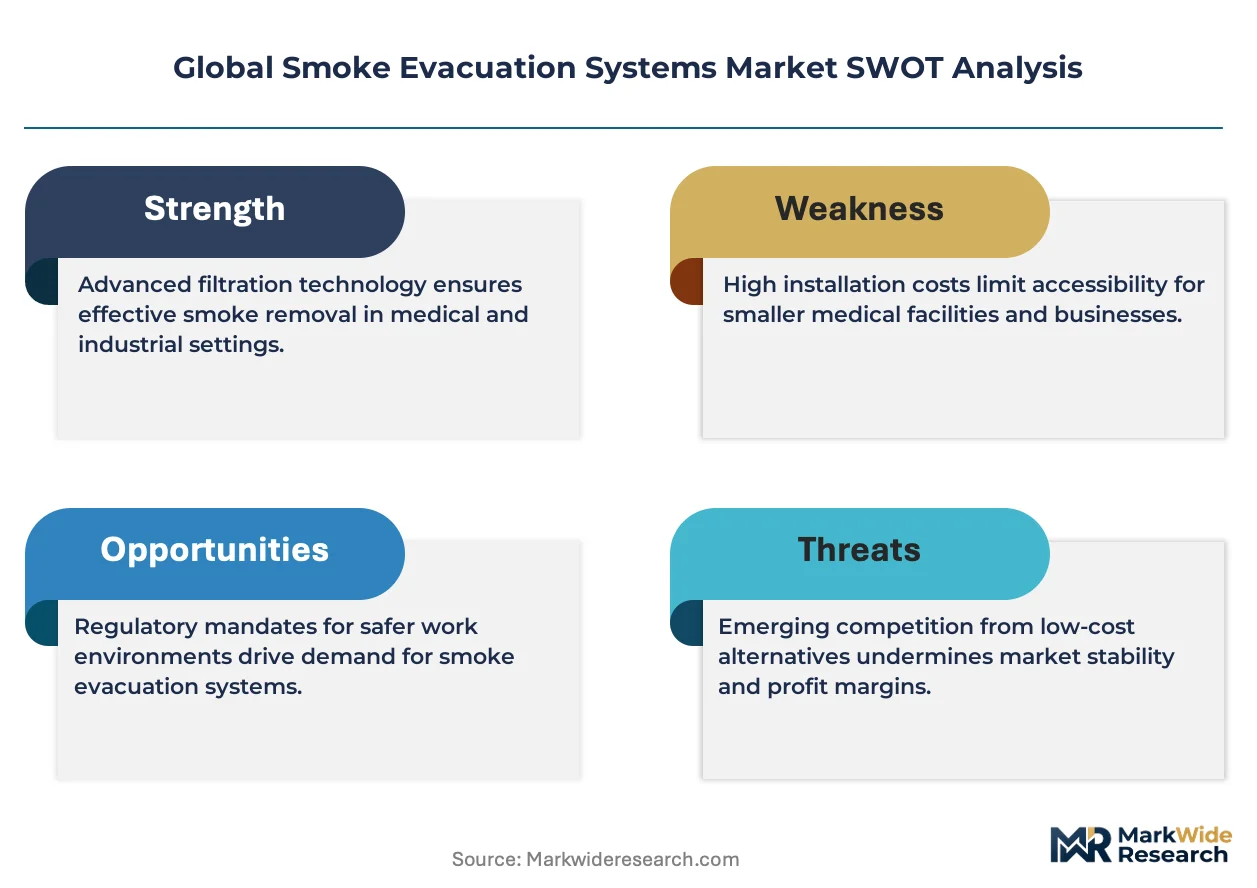
Supply & Pricing Matrix
Undercapacity in activated carbon media manufacturing across South Korean and Chinese production clusters is compressing supplier margins and amplifying pricing volatility for filtration system OEMs. This utilization squeeze forces manufacturers to absorb input cost spikes or pass through to hospital procurement committees already facing budget constraints from ambulatory surgical center expansion.
Pricing Analysis
The pricing gap between ultrasonic next-generation systems, conventional HEPA current-generation units, and legacy electrostatic prior-generation architectures spans three performance tiers. Three-tier pricing structure across premium, standard, and economy levels reflects FDA 510(k) clearance tier, EU MDR certification status, and after-sales service bundling intensity. Pricing pressure stems from activated carbon media cost volatility as supply concentrates in Asian manufacturing clusters. Ambulatory surgical centers exhibit highest price sensitivity due to constrained operational budgets, while tertiary hospital networks in the United States demonstrate lowest sensitivity through integrated operating room program contracting.
Supply Chain Analysis
Extended payment terms from German precision filtration component suppliers and supply-chain finance facilities anchored by Japanese electromechanical system assemblers shape working capital dynamics across the value chain. Manufacturing concentrates in Germany, Japan, and the United States for high-value subsystems, with China and South Korea supplying activated carbon media and HEPA membrane substrates. The supply chain draws from specialized filtration materials, electromechanical vacuum pumps, and intelligent sensor arrays. Single-source vulnerability in activated carbon media creates structural risk exposure. Distribution runs through integrated operating room solution providers and medical device distributors serving hospital procurement committees.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation opportunity persists as ambulatory surgical center expansion fragments procurement authority away from centralized health system headquarters toward facility-level decision-making, creating niche entry points for specialized vendors.
For Market Incumbents: Entrench hospital-wide contract positions by deepening backward integration into activated carbon media production and accelerating ultrasonic filtration R&D investment. CONMED Corporation's bundling strategy with electrosurgery portfolios faces emerging threat from standalone evacuation specialists winning ambulatory facility tenders. Channel control through service-inclusive leasing structures remains the priority lever for margin defense.
For New Entrants and Emerging Players: Build out portable unit specialization targeting India's private hospital sector where standardized smoke evacuation protocols remain absent. Dental clinics in the United States facing OSHA compliance deadlines represent the most penetrable segment without legacy infrastructure lock-in. Go-to-market angle should emphasize rapid FDA 510(k) clearance pathways and filter replacement economics transparency.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among portable system specialists with established filter replacement programs and service attach rates above industry median. Long-term viability over the projection horizon favors manufacturers with documented EU MDR quality management systems and multi-jurisdictional regulatory clearance portfolios. Acquisition target archetype: mid-cap filtration technology specialists with ultrasonic R&D pipelines. Signal to watch: health system consolidation pace in Texas and Florida networks.
| Strategic Initiative | Industry Significance |
|---|---|
| EU MDR Technical Documentation Investment | Elevates barrier-to-entry thresholds for European market access and procurement specification compliance. |
| Ultrasonic Filtration R&D Acceleration | Addresses single-stage gaseous capture limitations that constrain conventional HEPA system performance. |
| Hospital System Partnership Expansion | Concentrates purchasing authority at health system headquarters displacing distributor-mediated transactions. |
| Filter Replacement Program Development | Generates recurring revenue streams with higher margin profiles than initial equipment sales. |
| Software Companion Development | Enables real-time plume detection and automated flow adjustment integrated with electrosurgical generators. |
Research Methodology
Initial hypotheses were tested against primary input from hospital purchasing committee members, biomedical engineering directors, GPO contracts managers, and ambulatory surgical center administrators and refined through secondary validation. Primary fieldwork combined structured interviews with secondary analysis of FDA 510(k) clearance databases, EU MDR technical documentation filings, hospital procurement contract registries, and OSHA workplace exposure limit guidance. Bottom-up unit shipment estimates triangulated against top-down market value reconstruction across product type, technology, application, and end user segmentation dimensions.
Demand-supply-balance framing anchored the analytical framework across the projection horizon, modeling filtration system placement against surgical procedure volume growth and regulatory compliance deadline clustering. Segmentation dimensions included product mobility grade, filtration technology generation, procedure invasiveness category, and facility scale tier. CAGRs derived from procedure volume elasticity analysis and replacement cycle compression factors. Industry-specific forecast inputs incorporated EU MDR implementation timeline phasing and OSHA surgical smoke hazard recognition initiative rollout pace.
The forecast holds incumbent behavior within observed patterns; aggressive vertical integration moves by activated carbon media suppliers or ultrasonic technology specialists would shift outcomes. Forecasts reflect documented assumptions about regulatory implementation pacing and health system consolidation trajectories. Macroeconomic contraction affecting ambulatory surgical center capital budgets, accelerated EU MDR enforcement, or breakthrough single-stage filtration technology would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fire Safety & Protection
Global Fire Suppression System Market
Fire Safety & Protection
Automatic Fire Ball Extinguisher Market
Fire Safety & Protection
Fire Safety Equipment Market
Fire Safety & Protection
Fire Extinguisher Inspection Services Market
Fire Safety & Protection
Smoke and Carbon Monoxide Alarm Market
Fire Safety & Protection
Deflagration Flame Arresters Market
Fire Safety & Protection
Fireproof Insulation Market
Fire Safety & Protection
Fire Department Software Market
Fire Safety & Protection
Fire and Explosion Proof Lights Market
Fire Safety & Protection
GCC Firefighting Foam Market
Fire Safety & Protection
Fire Suppression Equipment Market
Fire Safety & Protection
Global Flame Detector Market
Fire Safety & Protection
Fire Safety Systems Market
Fire Safety & Protection
Fire Resistant Silicone Sealant Market
Fire Safety & Protection
Global Fire Extinguisher Cylinders Market
Fire Safety & Protection
UAE Firefighting Foam Market