
 Europe Public Infrastructure Safety Market | 2026-2036
Europe Public Infrastructure Safety Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Public Infrastructure Safety Market Insights
Software-defined maintenance contracts is recalibrating how safety systems get monetized across European public infrastructure. Siemens AG leverages its digital service portfolio to anchor long-term utility relationships in transport and energy networks. Thales Group competes through specialized signaling and perimeter security integration for rail and critical facilities. Bosch Security Systems sustains manufacturing scale across video analytics and intrusion detection hardware.
Europe public infrastructure safety encompasses engineered systems for threat detection, emergency response, and asset protection across publicly owned transport, civic, and utility structures, typically integrating sensors, control interfaces, and communication backbone operating on 24/7 availability parameters with IEC 61508-derived reliability grades. Surveillance Systems leads product type revenue due to mandatory CCTV coverage in transport hubs and urban centers under national policing frameworks. AI Analytics within technology layers represents the fastest-expanding margin pool as municipalities pilot predictive threat detection and automated incident triage. Parks and Municipal Buildings within application categories carry mature, specification-driven procurement cycles with slower technology refresh rates.
The EU AI Act and CE marking under the Machinery Directive are reshaping product compliance timelines for automated safety platforms across member states. Germany's KBA and France's ANSN enforce sector-specific rail and road safety certifications that filter vendor participation. ECHA's REACH restrictions on flame-retardant chemicals in fire safety equipment are forcing material reformulation across supply chains. Stakeholders must weigh interoperability standards against national certification fragmentation when scaling platforms across borders.
Market Dynamics
Software-defined maintenance contracts are recalibrating vendor monetization across European public infrastructure, anchoring long-term utility relationships through predictive service models rather than discrete hardware sales.
Growth Catalysts
- EU Green Deal retrofit mandates:The revised Energy Performance of Buildings Directive accelerates fire safety and access control upgrades in municipal structures across member states.
- Germany's railway modernization:Federal building codes and Deutsche Bahn infrastructure programs drive sustained procurement of integrated safety platforms for transport networks.
- AI Analytics adoption:Municipalities pilot predictive threat detection and automated incident triage, expanding margin pools beyond hardware specifications.
Market Restraints
- REACH chemical restrictions:ECHA's flame-retardant limitations force material reformulation across fire safety equipment supply chains, compressing margins.
- Certification fragmentation:Germany's KBA and France's ANSN enforce divergent rail and road safety standards that filter vendor participation across borders.
- Legacy system interoperability:IEC 61508-derived reliability grades create technical lock-in that slows platform migration for 24/7 critical infrastructure.
Strategic Opportunities
- Polish municipal infrastructure:Underpenetrated smart surveillance deployment in Eastern European transport hubs offers first-mover positioning ahead of EU cohesion funding cycles.
- EU AI Act compliance services:CE marking under the Machinery Directive creates advisory revenue streams for automated safety platform certification.
- Edge-to-cloud convergence:Video analytics and sensor fusion architectures enable new subscription pricing for perimeter security in critical facilities.
Industry Challenges
- Cyber-physical systems integration:IT/OT convergence in safety-critical infrastructure demands scarce cross-functional engineering talent fluent in both operational technology and enterprise security.
- Multi-jurisdictional certification timelines:National policing frameworks for CCTV mandate divergent technical specifications that extend product validation cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Public Infrastructure Safety Market |
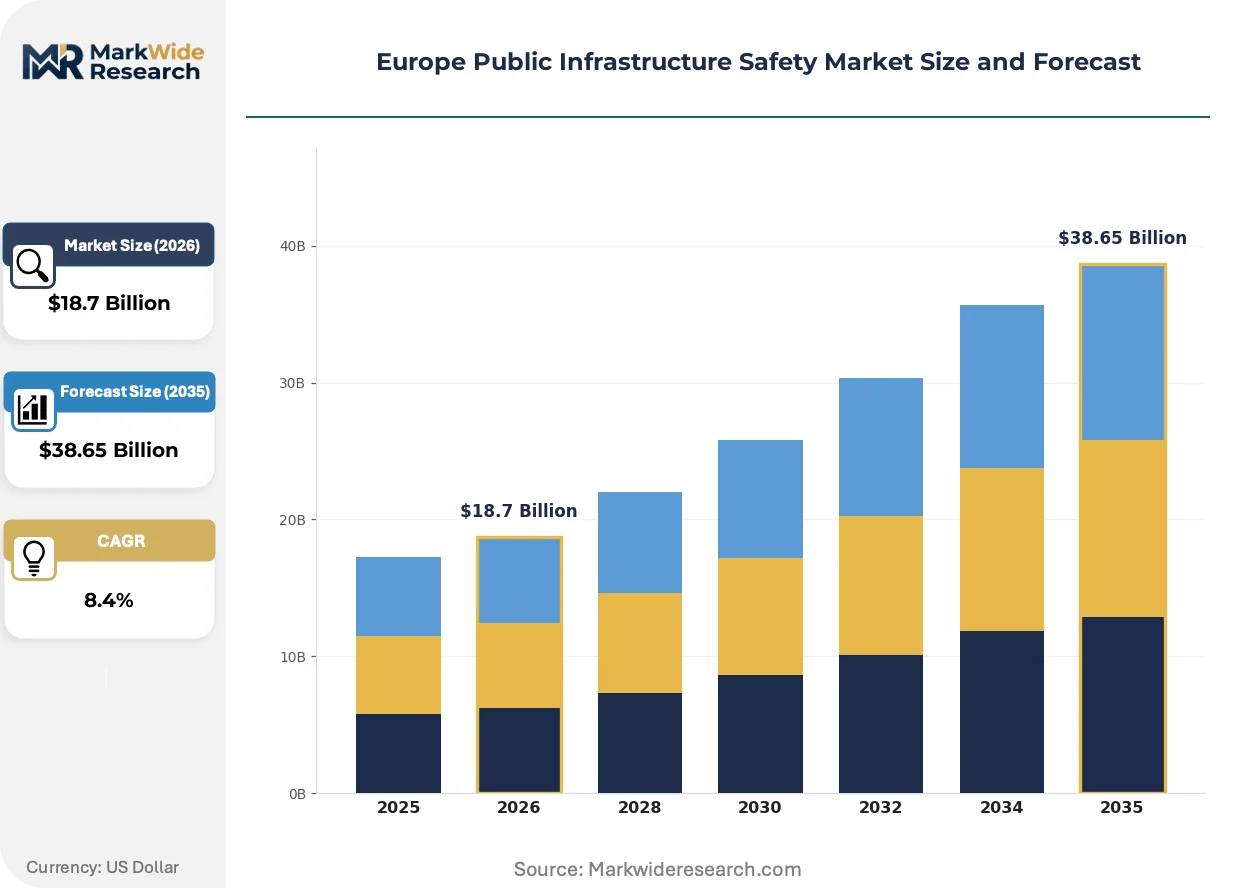
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $38.65 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Surveillance Systems, Fire Safety Equipment, Access Control Systems, Emergency Response Tools Application: Parks, Bridges, Highways, Municipal Buildings Technology: IoT Solutions, AI Analytics, Cloud Platforms, Physical Security Systems End User: Government Agencies, Private Contractors, Infrastructure Developers, Public Safety Organizations |
| Companies Covered | Siemens AG, Thales Group, Bosch Security Systems, Honeywell Building Solutions, Atos SE, Securitas AB, Schneider Electric, Axis Communications, ABB Ltd, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Public Infrastructure Safety Market Trends and Innovations
Three interconnected shifts are restructuring European public infrastructure safety: predictive maintenance architectures, regulatory compliance automation, and procurement model fragmentation. Each trend carries distinct vendor implications.
Edge AI inference engines are electrifying real-time video analytics deployment across transport hubs and urban centers. Deutsche Bahn and municipal police authorities pilot on-device threat recognition to reduce latency for automated incident response. This distributed processing architecture is electrifying competitive positioning around hardware-software integration depth.
CE marking under the Machinery Directive and the EU AI Act's risk-based classification system are compressing product launch timelines for automated safety platforms. Vendors must pre-validate algorithmic transparency and human oversight mechanisms before market entry. Rail signaling and perimeter security categories face the steepest compliance burden given their safety-critical classification.
Specification-driven procurement for parks and municipal buildings is fragmenting as outcome-based service contracts gain traction with budget-constrained local authorities. Discrete hardware purchases give way to availability-guaranteed performance agreements. French and German urban centers lead this transition, with smaller municipalities following as reference cases accumulate.
Europe Public Infrastructure Safety Market Segmentation
Procurement patterns across European public infrastructure diverge sharply by asset criticality and regulatory exposure. Buyers prioritize predictive capability in transport networks while municipal buildings follow slower specification cycles. Understanding these segment dynamics clarifies where vendor investment yields sustainable margin.
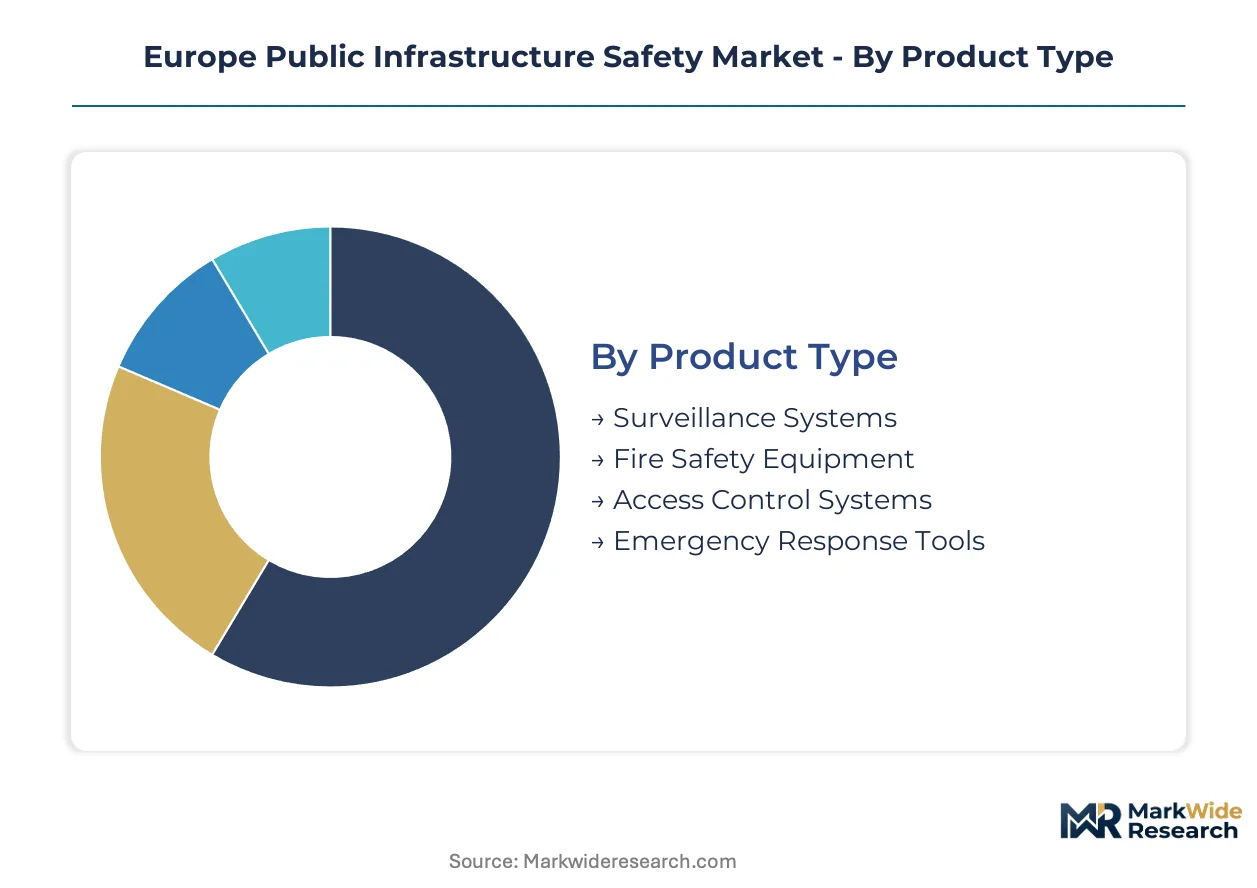
Product Type:
Buyers weight lifecycle cost against retrofit complexity when selecting safety system categories.
- Surveillance Systems:Integrated CCTV networks with edge AI inference engines process real-time threat detection at transport hubs. Deutsche Bahn and municipal police authorities mandate coverage under national policing frameworks, driving recurring software maintenance contracts.
- Fire Safety Equipment:Detection, suppression, and evacuation systems engineered to IEC 61508 reliability grades. ECHA's REACH restrictions on flame-retardant chemicals force material reformulation across German and French supply chains, compressing hardware margins.
- Access Control Systems:Biometric and credential-based entry management for critical facilities.
- Emergency Response Tools:Mass notification and coordinated dispatch systems for incident command.
Volume sits with Surveillance Systems; growth tilts toward Fire Safety Equipment as Green Deal retrofit mandates accelerate.
Application:
Asset ownership structures determine procurement centralization and technology refresh cadence.
- Highways:Perimeter intrusion detection and automated incident response for tolled corridors and tunnels. Italy's Autostrade and Spain's DGT deploy integrated safety platforms where traffic density justifies capital intensity.
- Bridges:Structural health monitoring fused with access control for critical span infrastructure.
- Municipal Buildings:Specification-driven fire safety and access control with slower refresh rates.
- Parks:Distributed surveillance and emergency call points across urban green space networks.
Procurement concentrates in Highways; Parks show steepest expansion trajectory as smart city pilots proliferate.
Technology:
Margin distribution follows data processing architecture choices and regulatory compliance burden.
- AI Analytics:Predictive threat detection and automated incident triage algorithms. The EU AI Act's risk-based classification imposes pre-validation requirements for algorithmic transparency, creating advisory revenue streams for compliance services.
- IoT Solutions:Sensor networks for environmental and structural monitoring.
- Cloud Platforms:Centralized data aggregation and cross-jurisdictional information sharing.
- Physical Security Systems:Hardware-layer detection and deterrence without networked intelligence.
Revenue pools deepest in AI Analytics; Cloud Platforms gain share fastest as interoperability standards mature.
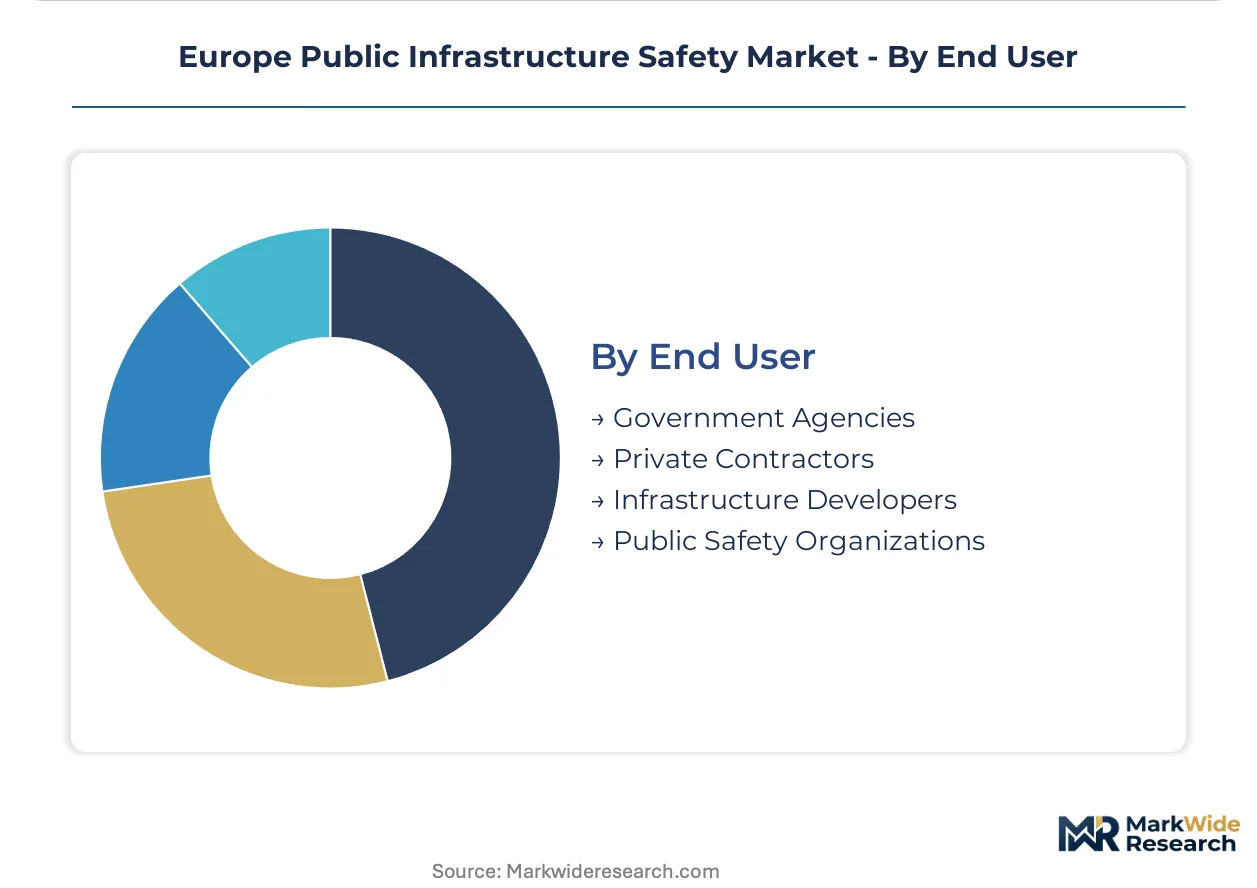
End User:
Budget authority and technical staffing shape solution complexity preferences.
- Government Agencies:National and municipal authorities with direct procurement authority over transport and civic infrastructure. Germany's KBA and France's ANSN enforce sector-specific certifications that filter vendor participation.
- Private Contractors:Build-operate-transfer concessionaires seeking availability-guaranteed performance contracts.
- Infrastructure Developers:Greenfield project sponsors integrating safety systems during construction phase.
- Public Safety Organizations:Police and emergency services with operational requirements for incident response integration.
Contract value concentrates with Government Agencies; Private Contractors drive outcome-based pricing adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production of safety system hardware concentrates in Germany and France, while deployment demand spreads across Central and Eastern Europe as cohesion funding cycles accelerate municipal modernization programs.
Germany
Deutsche Bahn's infrastructure programs and federal building codes drive sustained procurement of integrated rail and municipal safety platforms. The KBA enforces sector-specific rail certifications that filter vendor participation for signaling and perimeter systems. Siemens AG anchors manufacturing in Munich and Nuremberg, while Thales Group maintains specialized signaling integration capabilities for critical transport networks.
France
Urban center smart surveillance pilots and automated incident response systems expand municipal technology refresh rates. The ANSN enforces divergent rail and road safety standards that extend product validation timelines for automated platforms. Paris and Lyon lead outcome-based service contract adoption, with smaller municipalities following as reference cases accumulate for availability-guaranteed performance agreements.
United Kingdom
Transport hub CCTV mandates under national policing frameworks drive recurring software maintenance contracts for edge AI inference engines. The UK's departure from EU regulatory alignment creates parallel certification tracks for CE-marked safety equipment. London's integrated transport authority pilots predictive threat detection across Underground and surface rail networks.
Poland
Underpenetrated smart surveillance deployment in Eastern European transport hubs offers first-mover positioning ahead of EU cohesion funding cycles. National infrastructure programs prioritize highway perimeter intrusion detection and tunnel automated incident response. Warsaw and Krakow concentrate pilot deployments as municipalities test interoperability standards against legacy system architectures.
Italy
Autostrade and tolled corridor operators deploy integrated safety platforms where traffic density justifies capital intensity for perimeter security and structural health monitoring. The country's national transport regulator enforces tunnel safety specifications that mandate redundant detection systems. Milan and Rome anchor demand for fire safety retrofit mandates in municipal buildings under EU Green Deal implementation timelines.
Europe Public Infrastructure Safety Market Competitive Landscape
Top-tier vendors anchor premium-tier signaling and integrated platform supply, while mid-scale specialists compete on modular surveillance and access control hardware. The vendor base stratifies across three functional tiers: diversified industrial conglomerates with digital service portfolios, security-focused technology providers with manufacturing scale, and regional system integrators with local certification relationships. Dominant competitive moves include predictive maintenance contract anchoring and cross-border interoperability standard alignment.
Within the diversified industrial tier, Siemens AG represents long-term utility relationship anchoring through digital service portfolios across transport and energy networks. Thales Group occupies a position in specialized signaling and perimeter security integration for rail and critical facilities. Bosch Security Systems exemplifies manufacturing scale across video analytics and intrusion detection hardware.
| Leading Market Players |
|---|
| Siemens AG |
| Thales Group |
| Bosch Security Systems |
| Honeywell Building Solutions |
| Atos SE |
| Securitas AB |
| Schneider Electric |
| Axis Communications |
| ABB Ltd |
| Others |
Pricing and Supply Chain Analysis
Edge AI inference engine deployment across Deutsche Bahn and municipal police networks simultaneously compresses hardware margins and concentrates procurement power among systems integrators capable of software-defined service delivery. This technology shift rewards vendors with predictive maintenance architectures while squeezing pure hardware manufacturers.
Pricing Analysis
Margin tightening in fire safety equipment reflects ECHA's REACH flame-retardant restrictions forcing material reformulation across German and French supply chains. Three-tier pricing structure across premium, standard, and economy levels separates IEC 61508-certified signaling systems from municipal CCTV installations. Cost-down pressure on surveillance hardware accelerates as Polish municipalities consolidate procurement around EU cohesion funding cycles. Government agencies demonstrate lowest price sensitivity given mandate-driven replacement schedules; private contractors exhibit highest elasticity where availability-guaranteed performance contracts compete on total lifecycle cost.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale demand from Deutsche Bahn and national railway operators, while systems integrators serve fragmented municipal buyer bases. Manufacturing concentrates in Germany, France, and the Netherlands for rail signaling and perimeter security hardware. Supply chains draw from semiconductor foundries in Taiwan, specialized sensor suppliers in South Korea, and flame-retardant chemical producers facing ECHA regulatory restriction. Single-source vulnerability sits with edge AI chipsets for real-time video analytics. Distribution runs through certified systems integrators holding KBA and ANSN rail safety credentials.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cross-functional engineering talent scarcity for IT/OT convergence in safety-critical infrastructure props vendor pricing power and extends contract durations. Certified integration capability acts as the binding capacity constraint.
For Market Incumbents: Hedge against REACH chemical substitution costs by anchoring long-term utility relationships through predictive maintenance contracts rather than discrete hardware sales. Siemens AG and Thales Group should deepen backward integration into edge AI chipset sourcing to reduce single-source exposure. Certification investment in Poland ahead of cohesion funding disbursement cycles defends positioning against emerging regional system integrators. For New Entrants and Emerging Players: The price-point gap between premium IEC 61508-certified rail systems and economy-tier municipal CCTV installations offers white-space positioning for mid-tier surveillance providers. Polish transport hubs and Italian Autostrade corridors represent the most penetrable geographies given underdeveloped smart surveillance deployment. A compliance-as-a-service go-to-market angle targeting EU AI Act pre-validation requirements captures advisory revenue ahead of hardware competition. For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to diversified industrial conglomerates seeking digital service portfolio expansion. The five-to-ten year viability window favors platforms with recurring software maintenance contract bases over pure hardware manufacturers. Acquisition target archetype: regional system integrators holding KBA or ANSN certifications with established municipal reference cases. Watch for EU AI Act enforcement intensity as inflection indicator for compliance service demand.| Strategic Initiative | Industry Significance |
|---|---|
| EU AI Act Compliance Service Launch | Pre-validation advisory revenue captures margin ahead of hardware commoditization in automated safety platforms. |
| Edge-to-Cloud Platform Integration | Video analytics and sensor fusion architectures enable subscription pricing for Deutsche Bahn perimeter security contracts. |
| Polish Municipal Infrastructure Partnership | First-mover positioning in Warsaw and Krakow transport hubs ahead of EU cohesion funding acceleration. |
| REACH-Compliant Material Reformulation | Flame-retardant chemistry substitution defends fire safety equipment margins against ECHA regulatory compression. |
| Predictive Maintenance Contract Anchoring | Software-defined service models displace discrete hardware sales in German federal building code procurement cycles. |
Research Methodology
Independent corroboration across procurement officers at Deutsche Bahn and municipal police authorities, regulatory affairs specialists at ECHA and national certification bodies, and systems integration engineers at tier-1 vendors underwrites the qualitative findings. Primary interviews with transport network planners, fire safety equipment procurement leads, and edge AI platform developers combined with secondary validation through EU regulatory filings, national railway infrastructure program disclosures, and municipal budget appropriations documents. Bottom-up segment sizing and top-down macroeconomic anchoring provided cross-checks across the analysis window.
Comparable-period anchoring to historical railway modernization and Green Deal implementation timelines established baseline growth rates across the projection horizon. The analytical framework modeled product type segmentation across surveillance, fire safety, access control, and emergency response systems; application segmentation across highways, bridges, municipal buildings, and parks; and technology layering across AI analytics, IoT solutions, cloud platforms, and physical security systems. CAGRs derived from weighted average of vendor guidance, public procurement pipeline values, and regulatory mandate compliance deadlines. Forecast inputs incorporated EU cohesion funding disbursement schedules and REACH chemical restriction phase-in timelines.
Inputs from Deutsche Bahn infrastructure program disclosures and ECHA regulatory consultation records were available through the study window; gaps in real-time municipal procurement pipeline data introduce uncertainty bands around Polish and Italian segment projections. Forecasts reflect documented assumptions regarding AI Act enforcement intensity and cohesion funding absorption rates. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Public Safety
Public Safety Drones Market
Public Safety
Outdoor Public Safety Market
Public Safety
Asia-Pacific Public Safety Market
Public Safety
Global Public Safety Analytics Market
Public Safety
Europe Public Safety Market
Public Safety
Public Safety Market
Public Safety
US Mass Notification Systems Market
Public Safety
Europe Road Safety Market
Public Safety
Global Public Safety in Building Wireless Das System Market
Public Safety
Global Public Safety Solution for Smart City Market
Public Safety
Global Wireless Broadband in Public Safety Market
Public Safety
Global IoT for Public Safety Market
Public Safety
Europe Wireless Broadband in Public Safety Market
Public Safety
Global Public Safety and Security Market
Public Safety
AI for Public Security and Safety Market
Public Safety
LAMEA Wireless Broadband in Public Safety Market