
 Europe Road Safety Market | 2026-2036
Europe Road Safety Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Road Safety Market Insights
EU Green Deal mobility mandates are recalibrating the cost-of-entry calculus for road safety vendors across Europe. Kapsch TrafficCom AG leverages its Vienna headquarters to dominate intelligent tolling and traffic management corridors. Jenoptik AG specializes in photonic sensor arrays for speed enforcement and red-light monitoring. Siemens AG anchors large-scale urban mobility digitization through its Munich-based infrastructure division.
Road safety encompasses engineered systems and services designed to prevent collisions, reduce traffic fatalities, and manage vehicle-pedestrian interactions through physical infrastructure, electronic surveillance, and data-driven traffic control platforms. Core specifications include EN 12966-compliant variable message signs, radar detection accurate to within 1 km/h, and AI inference engines processing 30+ frames per second for real-time incident detection. Speed cameras and smart traffic management systems command the largest installed base, while AI systems represent the fastest-expanding technology segment as municipalities replace legacy loop detectors. Government agencies absorb the majority of procurement volume, though construction companies are emerging as a discrete buyer class through public-private highway maintenance contracts.
EMA safety performance standards, CE marking requirements for roadside equipment, and the EU AI Act's risk classification framework collectively shape product certification timelines and market access conditions across member states. The EU F-Gas Regulation additionally constrains thermal imaging component supply chains for speed camera manufacturers. Stakeholders must monitor the interplay between national transportation authority procurement calendars and the European Commission's forthcoming harmonized cybersecurity standards for connected infrastructure.
Market Dynamics
The EU Green Deal's sustainable mobility mandates are forcing municipal transportation authorities to retire legacy loop detectors and procure AI-enabled traffic management infrastructure at accelerated procurement calendars.
Growth Catalysts
- EU AI Act risk classification:The framework mandates algorithmic accountability for automated enforcement systems, compelling authorities to upgrade to certified AI inference platforms that process 30+ frames per second for real-time incident detection.
- Benelux urban corridor digitization:Municipal transportation authorities across Belgium, the Netherlands, and Luxembourg are consolidating procurement for intelligent traffic signal control and pedestrian detection networks.
- Photonic sensor arrays:Speed enforcement and red-light monitoring systems are integrating radar detection accurate to within 1 km/h, replacing inductive loop infrastructure with non-invasive roadside mounting.
Market Restraints
- F-Gas Regulation constraints:The EU F-Gas Regulation restricts hydrofluorocarbon supply chains for thermal imaging components used in speed camera manufacturers, compressing availability of cooled infrared detectors.
- CE marking certification timelines:EN 12966-compliant variable message signs face extended conformity assessment periods, delaying deployment of urban mobility digitization projects.
- Technical debt in legacy infrastructure:Northern Italian municipalities retain extensive inductive loop detector networks, creating integration friction with AI-enabled traffic management platforms.
Strategic Opportunities
- Public-private highway maintenance contracts:Construction companies are emerging as a discrete buyer class through long-term road concession agreements in France and Spain.
- CSRD disclosure requirements:The Corporate Sustainability Reporting Directive creates procurement preference for road safety vendors with verified supply chain carbon footprints.
- Edge-to-cloud convergence:Municipalities are piloting hybrid architectures combining roadside AI inference with centralized traffic optimization, opening deployment models for mid-tier technology integrators.
Industry Challenges
- Cybersecurity standardization delays:The European Commission's forthcoming harmonized cybersecurity standards for connected infrastructure remain unpublished, freezing procurement specifications for networked traffic control systems.
- EMA safety performance compliance:Variable message sign manufacturers face overlapping national transportation authority requirements alongside pan-European certification, extending product validation cycles.
- Skill scarcity in photonic integration:Speed camera producers compete for optical engineers capable of designing sensor arrays meeting both precision and environmental durability specifications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Road Safety Market |
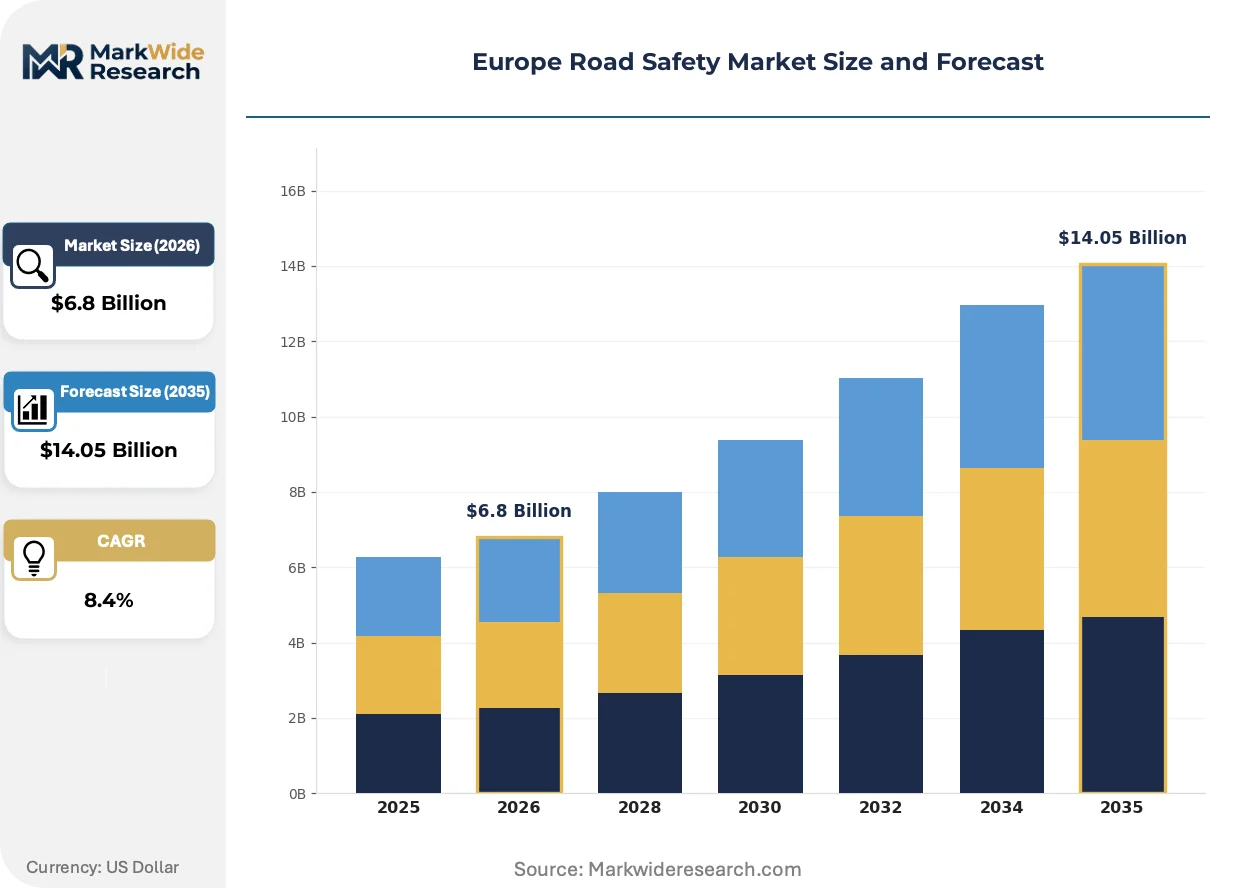
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $14.05 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Traffic Signs, Road Barriers, Speed Cameras, Reflective Vests Technology: AI Systems, Smart Traffic Management, Blockchain Solutions, Autonomous Vehicles End User: Government Agencies, Transportation Authorities, Construction Companies, NGOs Installation: On-road Systems, Off-road Installations, Urban Applications, Rural Deployments |
| Companies Covered | Kapsch TrafficCom AG, Jenoptik AG, Siemens AG, Motorola Solutions, Inc., Teledyne FLIR LLC, SWARCO AG, Sensys Gatso Group AB, Verra Mobility Corp., IDEMIA SAS, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Road Safety Market Trends and Innovations
Artificial intelligence inference engines are overtaking rule-based traffic control algorithms across European urban corridors, compressing incident response times while enabling predictive congestion management.
Radar-based vehicle detection is overtaking inductive loop technology as the default sensing modality for speed enforcement and traffic signal actuation. German transportation authorities are mandating non-invasive installation methods for roadway preservation. The structural consequence is overtaking legacy maintenance contracts that bundled detector replacement with pavement resurfacing cycles.
The EU AI Act's risk classification framework for automated decision-making systems is reshaping product development roadmaps for enforcement technology vendors. High-risk system designations now require human-in-the-loop verification for penalty issuance, adding architectural complexity. French and British speed camera operators are most affected, restructuring backend workflows to accommodate appeal review protocols.
Municipal procurement patterns are fragmenting from centralized national frameworks toward regional cluster purchasing. Aggregated demand from northern Italian provinces and Benelux corridor authorities is displacing single-country tender structures. This rotation is most visible in variable message sign deployments, where multi-municipal consortia negotiate volume pricing directly with manufacturers.
Europe Road Safety Market Segmentation
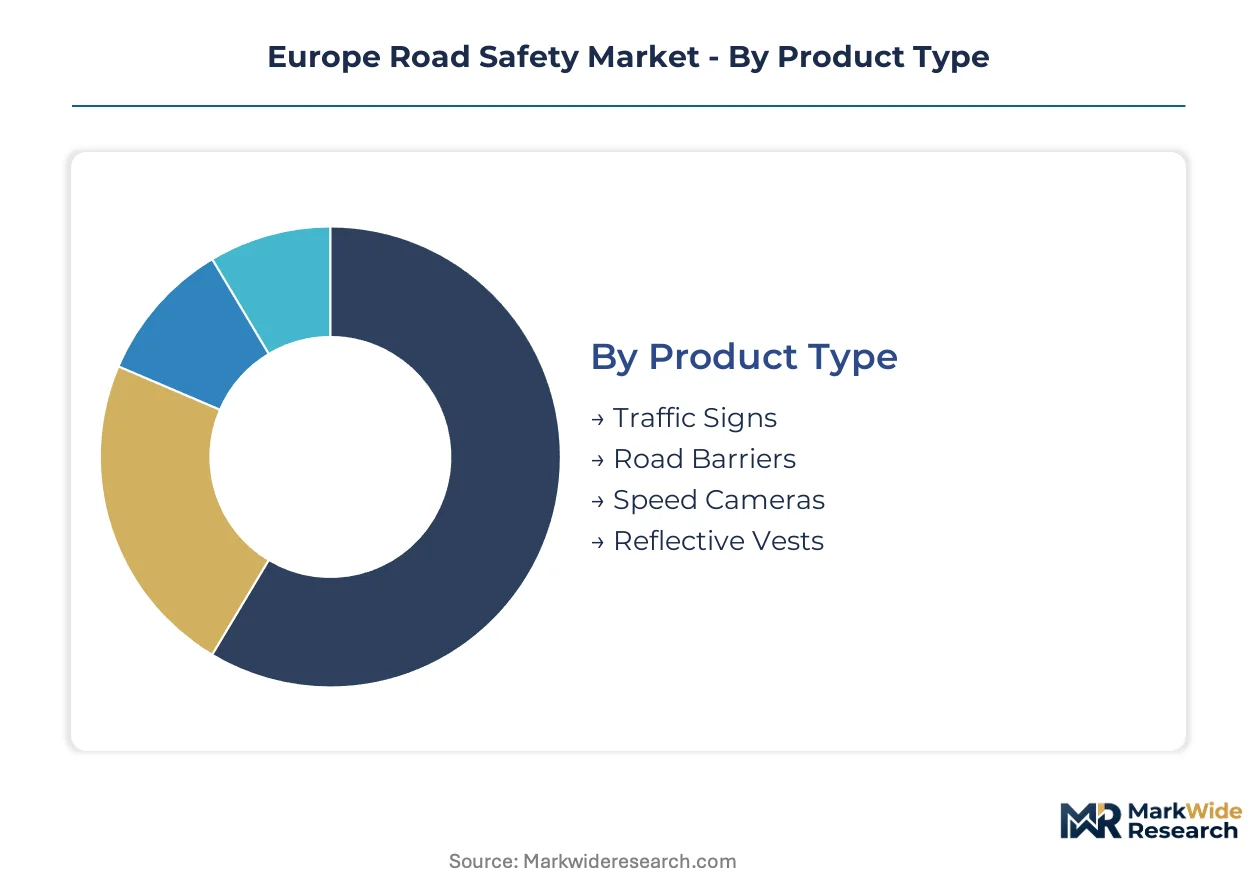
European procurement authorities structure purchasing decisions across product, technology, and end-user dimensions. Municipal transportation departments in Germany, France, and the United Kingdom maintain distinct specifications that fragment vendor addressable markets. Understanding these segment boundaries clarifies where AI-enabled infrastructure investments concentrate versus legacy equipment replacement cycles.
Product Type:
Replacement cycles for physical road safety equipment are compressing as EU Green Deal mandates accelerate urban corridor digitization timelines.
- Speed Cameras:Photonic sensor arrays integrating radar detection accurate to within 1 km/h now dominate new procurement. French and British operators are restructuring backend workflows to accommodate EU AI Act human-in-the-loop verification requirements for penalty issuance.
- Smart Traffic Management Systems:AI inference engines processing 30+ frames per second for real-time incident detection are displacing legacy loop detectors across Benelux urban corridors. Municipalities in northern Italy pilot hybrid edge-to-cloud architectures combining roadside inference with centralized optimization.
- Traffic Signs:EN 12966-compliant variable message signs face extended CE marking conformity assessment periods that delay deployment schedules.
- Road Barriers:Passive protection systems retain steady replacement demand through highway maintenance contracts in France and Spain.
- Reflective Vests:Personal protective equipment procurement concentrates in construction company buyer classes through public-private road concession agreements.
Speed cameras sit at the top of the volume ranking, with smart traffic management systems climbing the fastest.
Technology:
Technology selection in European road safety follows a cost-tier logic where certified AI platforms command premium positioning against legacy rule-based systems.
- AI Systems:Algorithmic accountability mandates under the EU AI Act risk classification framework compel authorities to upgrade enforcement infrastructure. High-risk system designations require documented human oversight protocols that reshape product development roadmaps.
- Smart Traffic Management:Non-invasive radar-based vehicle detection is overtaking inductive loop technology as German authorities mandate roadway preservation. The structural consequence is terminating legacy maintenance contracts that bundled detector replacement with pavement resurfacing.
- Blockchain Solutions:Distributed ledger applications for traffic data integrity remain experimental, with pilot programs limited to Nordic municipal consortia.
- Autonomous Vehicles:V2X communication infrastructure for automated mobility operates at pre-commercial scale, constrained by unpublished European Commission cybersecurity standards for connected infrastructure.
Smart traffic management commands the largest installed base, while AI systems gain share fastest through mandated compliance upgrades.
End User:
Customer-type segmentation reveals a bifurcation between centralized government procurement and emerging private-sector buyer classes.
- Government Agencies:National transportation authorities in Germany, France, and the United Kingdom absorb the majority of procurement volume through centralized frameworks now fragmenting toward regional cluster purchasing.
- Transportation Authorities:Municipal and provincial entities across the Benelux region and northern Italy are consolidating demand through multi-municipal consortia that negotiate volume pricing directly with manufacturers.
- Construction Companies:Long-term highway maintenance and road concession agreements in France and Spain are creating a discrete buyer class with distinct specification requirements.
- NGOs:Non-governmental organizations concentrate procurement for pedestrian safety and school zone interventions, particularly in urban applications across Italian provinces.
Government agencies retain dominant procurement share, with construction companies expanding most quickly through concession contract structures.
Installation:
Geographic deployment patterns track urbanization density and infrastructure maturity gradients across European member states.
- Urban Applications:Dense sensor networks for pedestrian detection and intelligent traffic signal control concentrate in Benelux corridor authorities and northern Italian provinces undergoing coordinated digitization.
- On-road Systems:Speed enforcement and variable message sign deployments dominate arterial highway procurement calendars, with German KBA specifications influencing cross-border vendor certification.
- Rural Deployments:Lower-density installations face extended replacement cycles and tighter budget constraints from regional transportation authorities.
- Off-road Installations:Construction zone and temporary traffic management systems follow project-based procurement tied to specific infrastructure development timelines.
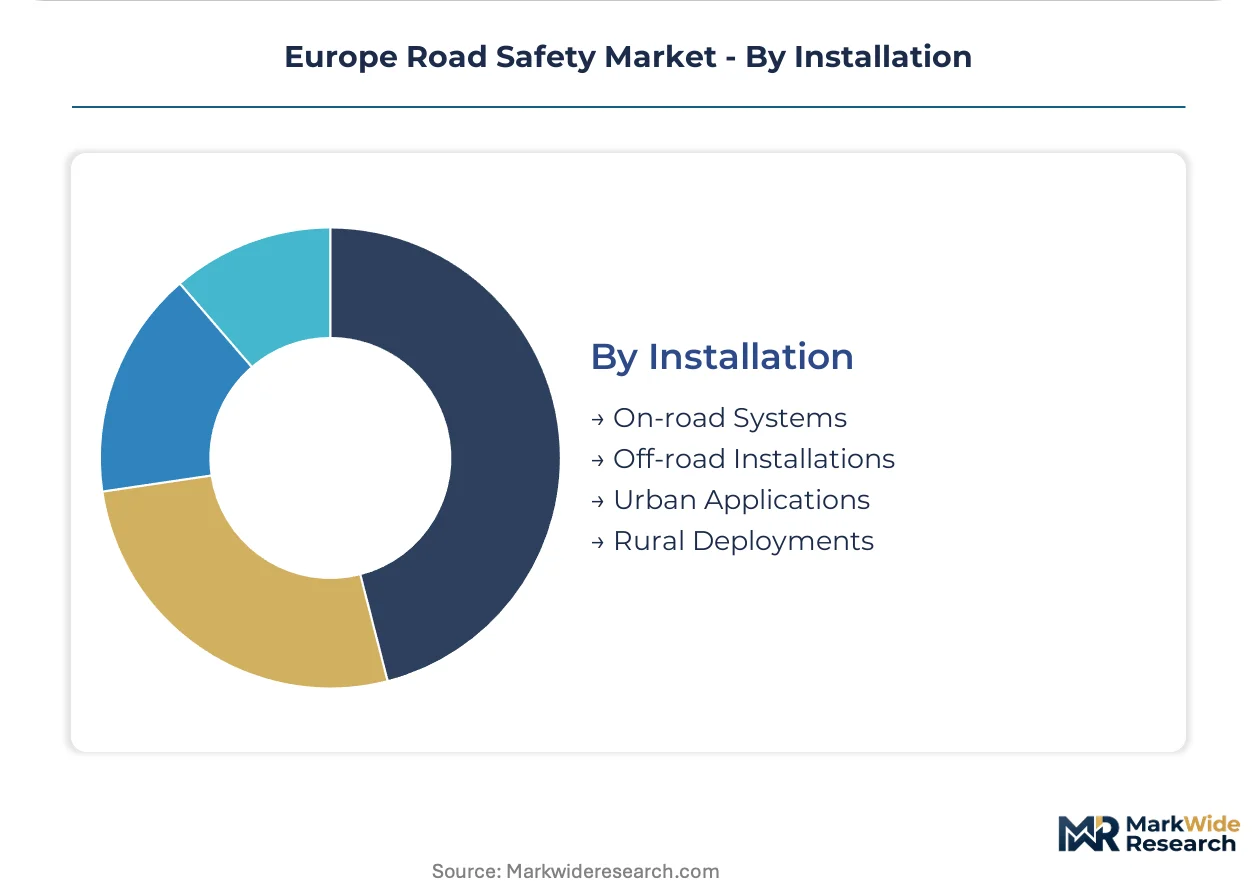
Urban applications lead deployment volume, with on-road systems showing the steepest expansion trajectory through accelerated enforcement infrastructure programs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Optical engineering talent clusters in southern Germany and photonics research centers in the Netherlands anchor European road safety technology development. Vienna hosts intelligent traffic management headquarters while Milan anchors sensor manufacturing corridors.
Germany
KBA specifications for speed enforcement equipment drive cross-border vendor certification requirements. The EU AI Act's high-risk system designations mandate human-in-the-loop verification protocols that German operators are implementing first. Bavarian municipalities are replacing inductive loop detectors with radar-based detection across Munich and Nuremberg urban corridors.
United Kingdom
Transport for London's procurement frameworks for intelligent traffic signal control attract specialized technology vendors. The EU Green Deal's sustainable mobility mandates influence post-Brexit regulatory alignment discussions for automated enforcement systems. Birmingham and Manchester metropolitan authorities are consolidating demand through regional cluster purchasing for pedestrian detection networks.
France
ANSM oversight of automated decision-making systems intersects with transportation authority procurement for speed camera networks. Long-term highway concession agreements in the Auvergne-Rhône-Alpes region are creating construction company buyer classes distinct from government procurement. The Île-de-France region is piloting hybrid edge-to-cloud traffic optimization architectures combining roadside AI with centralized control.
Netherlands
Benelux corridor authorities are consolidating procurement for intelligent traffic signal control and variable message sign deployments. CE marking requirements for EN 12966-compliant equipment face extended conformity assessment periods that Dutch regulators are streamlining. The Randstad metropolitan cluster including Amsterdam and Rotterdam leads urban corridor digitization with coordinated multi-municipal specifications.
Italy
Northern Italian provinces retain extensive technical debt from legacy inductive loop detector networks that complicate AI-enabled platform integration. The EU F-Gas Regulation constrains thermal imaging component supply chains for speed camera manufacturers serving Italian transportation authorities. Lombardy municipalities including Milan are negotiating volume pricing directly with manufacturers through aggregated demand consortia.
Europe Road Safety Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across technology tiers in European road safety. The vendor base organizes around three strategic archetypes: infrastructure conglomerates with urban mobility divisions, photonics specialists with enforcement sensor expertise, and traffic management pure-plays with software-centric platforms. Dominant competitive moves include geographic anchoring near transportation authority headquarters and technology licensing partnerships for AI inference engine certification.
Within the infrastructure conglomerate tier, Siemens AG exemplifies scale-driven positioning through its Munich-based operations. Among traffic management specialists, Kapsch TrafficCom AG and SWARCO AG represent archetypes of Vienna-headquartered and Innsbruck-centered vendors respectively, each occupying positions aligned with Central European transportation authority procurement patterns.
| Leading Market Players |
|---|
| Kapsch TrafficCom AG |
| Jenoptik AG |
| Siemens AG |
| Motorola Solutions, Inc. |
| Teledyne FLIR LLC |
| SWARCO AG |
| Sensys Gatso Group AB |
| Verra Mobility Corp. |
| IDEMIA SAS |
| Others |
Pricing and Supply Chain Analysis
Photonic sensor component indices cascade through European road safety equipment supply chains, compressing margins for speed camera manufacturers while amplifying pricing power for AI inference engine vendors serving Benelux corridor authorities. The F-Gas Regulation's hydrofluorocarbon constraints tighten cooled infrared detector availability, forcing tiered cost absorption across enforcement technology procurement tiers.
Pricing Analysis
Bundled hardware-software service contracts dominate municipal procurement, separating premium AI-enabled traffic management platforms from standard loop-detector replacements and economy-tier passive signage. Price differentiation hinges on EU AI Act certification grade and after-sales maintenance bundling. Cost compression in thermal imaging components intensifies because F-Gas Regulation supply constraints limit cooled detector availability. Construction companies through French highway concession agreements exhibit highest price sensitivity; German KBA-certified vendors command lowest sensitivity due to specification lock-in.
Supply Chain Analysis
Optical engineering workforce scarcity in southern Germany and the Netherlands constrains photonic sensor array production capacity for speed enforcement equipment. Manufacturing concentrates in Germany, Austria, and northern Italy, drawing from specialized infrared detector, radar module, and AI chipset inputs. Single-source vulnerability runs through Taiwanese semiconductor foundries supplying inference processors. Distribution runs through transportation authority procurement frameworks and direct manufacturer negotiations with multi-municipal consortia.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
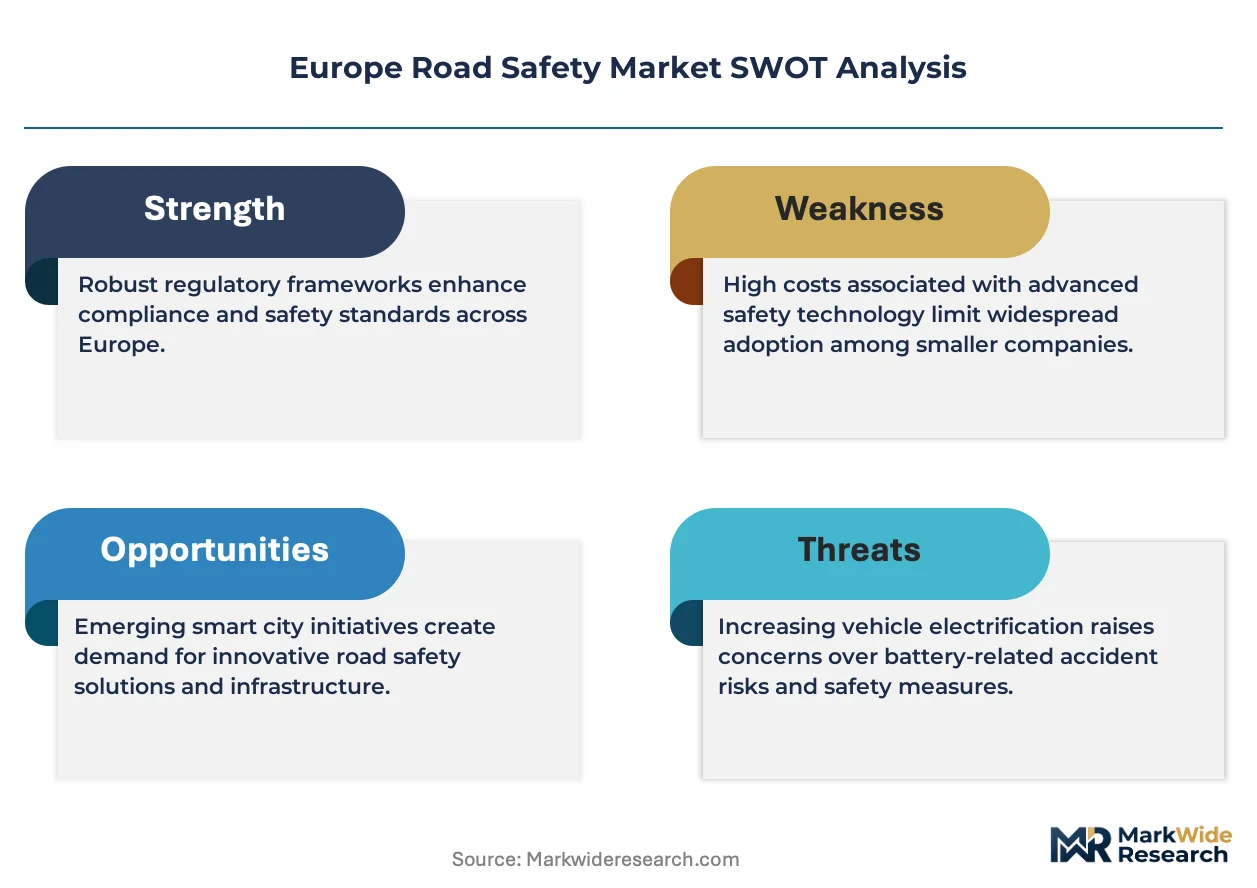
European road safety investment functions as a regulatory-arbitrage play: the EU AI Act's algorithmic accountability mandates impose compliance costs that favor vendors with pre-certified platforms in Germany while penalizing legacy-dependent operators in northern Italy.
For Market Incumbents: Deploy certification-first R&D pipelines to lock in municipal procurement specifications before harmonized cybersecurity standards publish. Incumbents must consolidate channel control through exclusive maintenance contracts with Benelux corridor authorities and accelerate backward integration into photonic sensor manufacturing to offset F-Gas Regulation supply risk. The threat of edge-to-cloud hybrid architectures from mid-tier integrators demands pre-emptive platform integration investments.
For New Entrants and Emerging Players: AI-first pedestrian detection networks offer the most penetrable wedge against established speed camera vendors. White-space targets include northern Italian provincial consortia seeking loop-detector migration paths and French construction companies requiring temporary traffic management systems for highway concession workflows. A specifications-first go-to-market angle targeting EN 12966 compliance gaps in variable message sign deployments bypasses incumbent certification moats.
For Investors and Strategic Acquirers: Asymmetric upside sits with photonics specialists possessing in-house optical engineering talent and existing CE marking pathways. Long-term viability favors vendors with demonstrated EU AI Act high-risk system certification rather than hardware-commoditized loop-detector replacements. The signal to watch is publication timing for European Commission harmonized cybersecurity standards, which will freeze or unlock procurement specifications for connected infrastructure.
| Strategic Initiative | Industry Significance |
|---|---|
| AI Inference Engine Certification | EU AI Act compliance locks in municipal procurement specifications ahead of competitor platforms. |
| Photonic Sensor Backward Integration | In-house radar array production bypasses F-Gas Regulation thermal imaging supply constraints. |
| Multi-Municipal Consortium Partnerships | Direct negotiations with Benelux corridor authorities displace national tender intermediaries. |
| Edge-to-Cloud Hybrid Architecture Pilot | Roadside inference combined with centralized optimization opens mid-tier integrator deployment models. |
| Construction Company Channel Development | Long-term highway concession agreements in France and Spain create discrete buyer class access. |
Research Methodology
Bottom-up municipal procurement modeling reconciled against top-down vendor shipment tracking forms the analytical core of this study. Primary interviews with transportation authority procurement officers, photonics engineering directors, traffic management system integrators, and construction company project managers combined with secondary validation from KBA type-approval databases, CE marking conformity assessment records, EU Green Deal implementation reports, and municipal tender documentation. Triangulation across these sources anchors volume and value estimates.
Input-output matrices map AI inference engine deployment rates, photonic sensor array production capacity, and procurement calendar phasing across the projection horizon. Segmentation dimensions modeled include product type, technology tier, end-user archetype, and installation geography. CAGRs derive from regression analysis of historical procurement patterns against regulatory mandate timelines, incorporating EN 12966 certification backlog data and F-Gas Regulation supply constraint projections as industry-specific forecast inputs.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to European Commission cybersecurity standard publication delays and EU AI Act enforcement interpretation variance. Forecasts reflect documented assumptions regarding municipal budget continuity and photonics component supply normalization. Material deviation in harmonized standard timelines or F-Gas Regulation amendment scope warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Public Safety
Global Public Safety and Security Market
Public Safety
Europe Public Safety Market
Public Safety
Outdoor Public Safety Market
Public Safety
Counter Terror and Public Safety Technology Market
Public Safety
US Mass Notification Systems Market
Public Safety
Crime Risk Report Market
Public Safety
North America Road Safety Market
Public Safety
Public Safety Market
Public Safety
Global Public Safety Analytics Market
Public Safety
Europe Wireless Broadband in Public Safety Market
Public Safety
Public Safety Drones Market
Public Safety
Voice Evacuation Systems Market
Public Safety
Middle East Crime and Combat Market
Public Safety
Global Public Safety Solution for Smart City Market
Public Safety
Global Public Safety in Building Wireless Das System Market
Public Safety
Global Public Safety Solution Market