
 Passenger Security Equipment Market | 2026-2036
Passenger Security Equipment Market Size, Share, and Industry Trends Forecast 2026-2036
Passenger Security Equipment Market Outlook
Subscription-based predictive maintenance and software-defined threat-detection upgrades is restructuring how airport authorities procure passenger security infrastructure. Smiths Detection Group Ltd. leverages its service-contract model to lock in recurring revenue across European hub airports. L3Harris Technologies, Inc. anchors its position through deep integration of millimeter-wave firmware with TSA checkpoint protocols. Rapiscan Systems competes on manufacturing scale, sustaining cost advantages in high-volume X-ray belt scanner deployments.
Passenger security equipment encompasses electromechanical and electromagnetic systems engineered to detect concealed threats, weapons, and contraband on persons and in baggage, typically operating at frequencies from 1 kHz to 300 GHz with detection thresholds calibrated to regulatory threat libraries. The primary commercial purpose is to enforce access control at transportation nodes and mass-gathering venues without impeding throughput. X-Ray Machines and body scanners capture the dominant share of capital expenditure as airports replace single-view systems with computed-tomography baggage scanners capable of resolving liquid explosives and layered threats. Millimeter Wave technology leads new installations given its passive, non-ionizing radiation profile and compatibility with privacy-preserving software that obscures anatomical detail while flagging anomalies.
TSA mandates under the FAA Reauthorization Act and EASA's Implementing Regulation 2019/103 set baseline detection standards that OEMs must certify against before airport deployment, directly shaping R&D priorities and product roadmaps. China's NMPA and MIIT enforce GB standards for electromagnetic emissions that constrain import eligibility and drive localization partnerships. Stakeholders must monitor how AI-enabled video analytics reclassifies regulatory compliance from hardware certification to algorithmic audit trails.
Market Dynamics
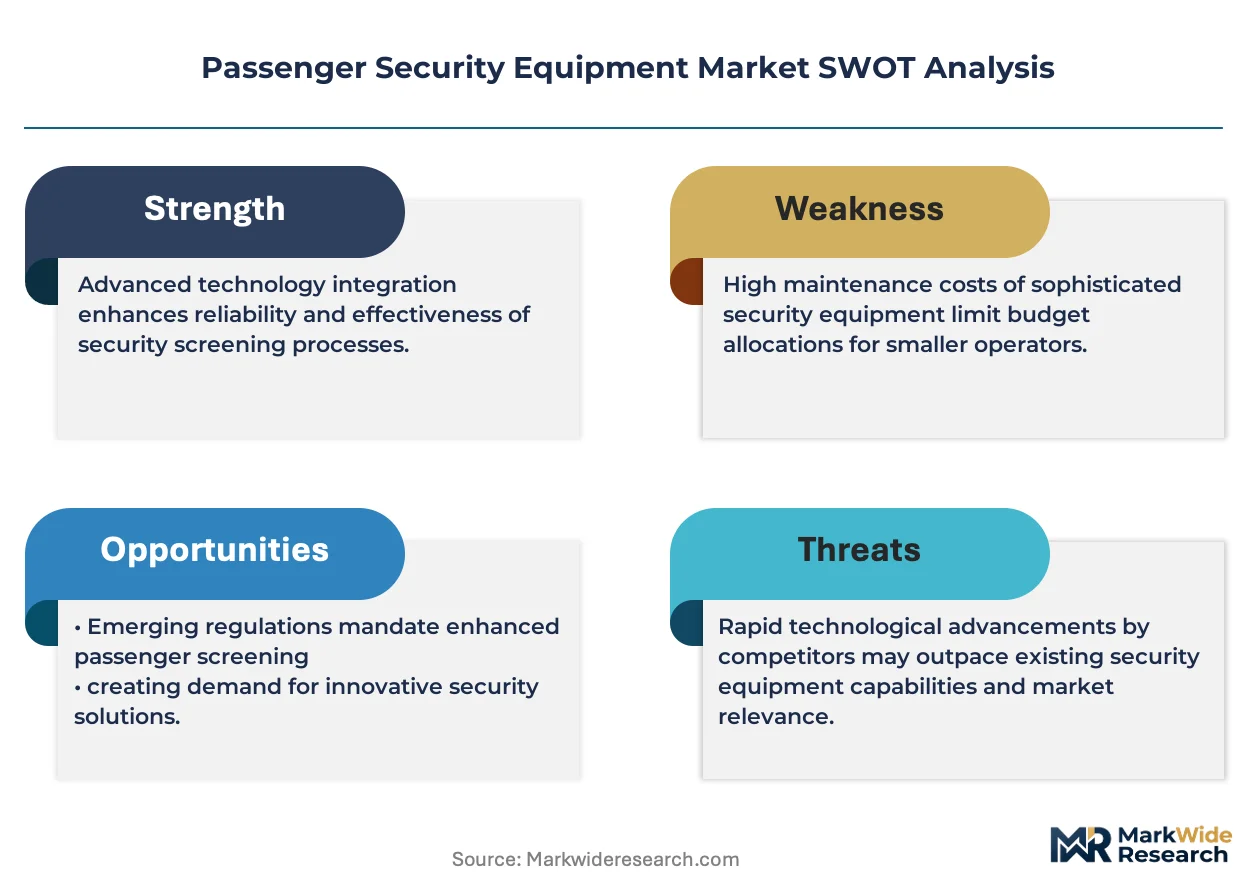
Millimeter-wave body scanners are displacing legacy metal detectors at aviation checkpoints as TSA and EASA mandate detection of non-metallic threats including liquid explosives and ceramic weapons. This hardware refresh cycle concentrates procurement authority among national aviation regulators and hub airport operators.
Growth Catalysts
- FAA Reauthorization Act mandates:TSA's updated detection standards require Advanced Imaging Technology deployment at Category X airports, forcing immediate replacement of single-view metal detection portals.
- Computed tomography baggage screening:European hub airports under EASA's Implementing Regulation 2019/103 are retrofitting hold baggage and cabin baggage lines with CT scanners capable of resolving layered threats without physical bag inspection.
- China's airport infrastructure buildout:MIIT and NMPA are certifying domestic millimeter-wave scanner production for deployment at Beijing Daxing, Shanghai Pudong, and Guangzhou Baiyun international terminals.
Market Restraints
- Gallium nitride component concentration:High-frequency RF modules for millimeter-wave arrays depend on limited semiconductor foundry capacity concentrated in Taiwan and South Korea, creating input cost volatility and delivery uncertainty.
- Regulatory fragmentation:China's GB electromagnetic emission standards and India's BIS certification requirements impose duplicative testing protocols that extend time-to-market for OEMs seeking multi-territory deployment.
- Passive millimeter-wave substitution:Lower-cost terahertz imaging prototypes under development at European research institutes threaten to displace active millimeter-wave systems in secondary checkpoint applications.
Strategic Opportunities
- India's greenfield airport expansion:The Jewar and Navi Mumbai airport projects lack legacy metal detector infrastructure, enabling direct deployment of integrated CT baggage and millimeter-wave passenger screening lanes without retrofit constraints.
- AI-enabled threat detection algorithms:Machine learning models trained on open-source threat libraries are converging with edge-computing hardware to enable software-defined detection upgrades without full hardware replacement.
- Saudi Arabia's Giga-project venues:NEOM and Red Sea Project mass-gathering sites require passenger screening infrastructure at non-aviation transportation nodes, opening demand outside traditional airport procurement channels.
Industry Challenges
- Algorithm audit trail compliance:EU AI Act requirements for high-risk AI systems mandate documented training data provenance and bias testing for automated threat detection algorithms, extending certification timelines.
- Legacy system integration complexity:Hub airports in Germany and the United States must synchronize new millimeter-wave scanner outputs with existing centralized security operations center software architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Passenger Security Equipment Market |
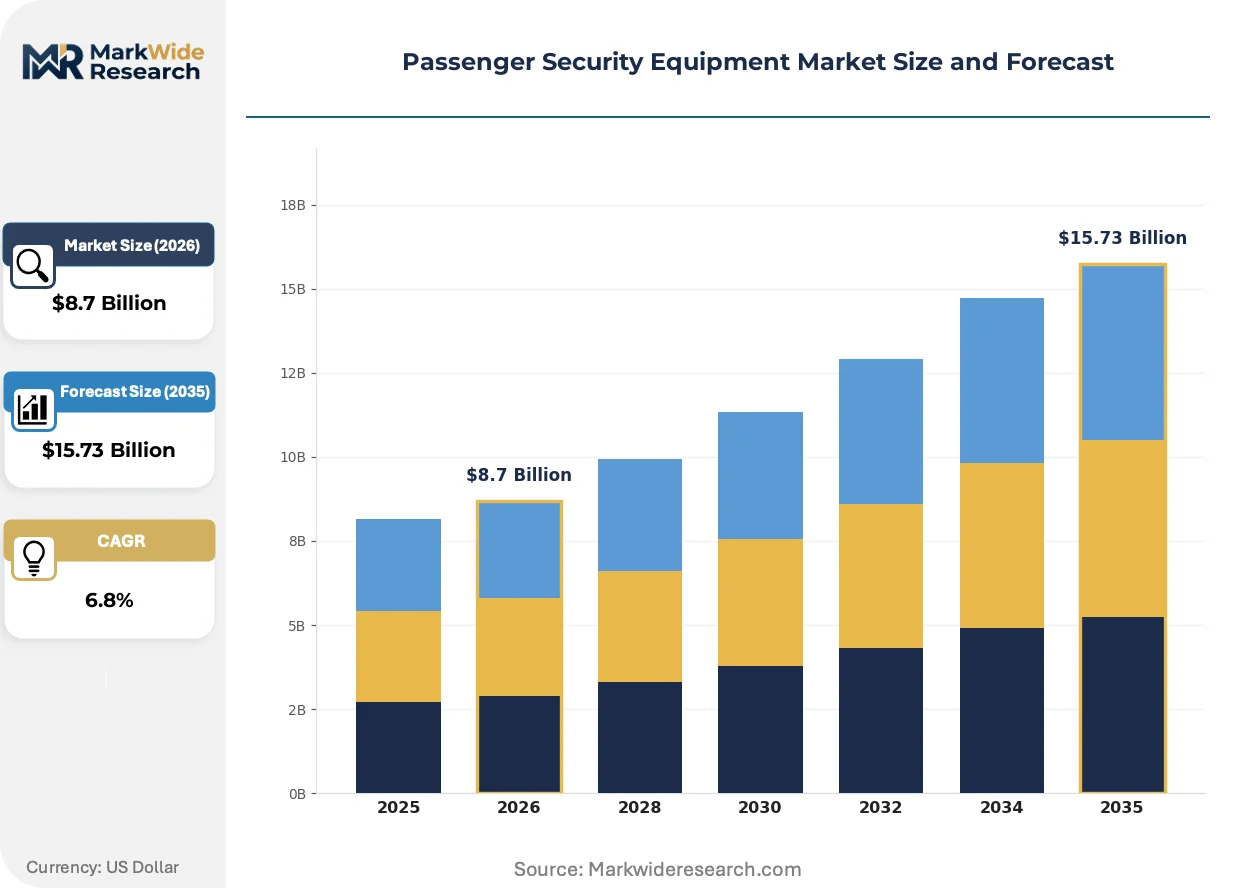
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Metal Detectors, X-Ray Machines, Body Scanners, CCTV Systems Technology: Electromagnetic, Millimeter Wave, Infrared, Video Analytics End User: Aviation, Maritime, Public Transportation, Event Venues Installation: Fixed, Portable, Modular, Integrated Systems |
| Companies Covered | Honeywell International Inc., Smiths Detection Group Ltd., L3Harris Technologies, Inc., Rapiscan Systems, Siemens AG, Bosch Sicherheitssysteme GmbH, OSI Systems Inc., SITA, Thales Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Passenger Security Equipment Market Strategic Shifts
Deep learning inference at the network edge is compressing detection latency and enabling real-time threat classification without cloud dependency. This architectural shift redefines hardware-software boundaries and procurement evaluation criteria.
Computed tomography baggage scanners are integrating dual-energy X-ray sources with photon-counting detectors to discriminate organic from inorganic materials at molecular resolution. Major European hub operators including Frankfurt and Amsterdam Schiphol are deploying these systems in cabin baggage lanes to eliminate liquid restrictions. The technology is integrating threat libraries directly into firmware, reducing dependency on centralized server infrastructure.
EASA's Implementing Regulation 2019/103 and successor cabin baggage screening directives are mandating automatic detection of explosives and prohibited items without human image analysis. OEMs must certify algorithms against standardized threat test sets before airport deployment. The regulation most affects hold baggage screening lines at Category 1 airports in France, Germany, and the Netherlands, where operators are accelerating CT retrofit programs to meet compliance deadlines.
Subscription-based service contracts are displacing capital purchase models for checkpoint infrastructure. Airport authorities in the United States and United Kingdom now prioritize total cost-of-ownership metrics and guaranteed uptime service-level agreements over upfront equipment cost. This pattern is most visible at TSA-managed checkpoints and London Heathrow, where multi-year performance contracts bundle hardware, software updates, and predictive maintenance.
Passenger Security Equipment Market Segmentation
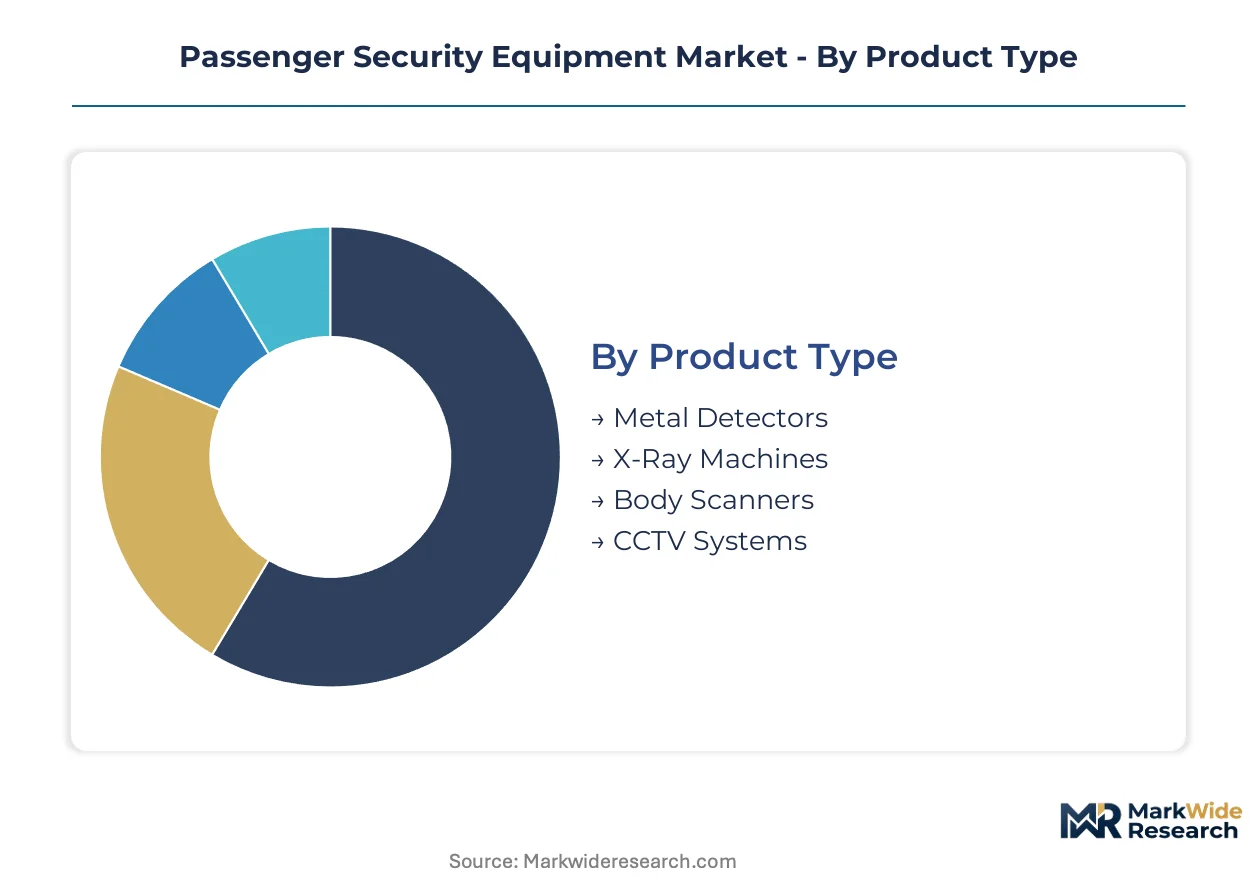
Passenger security equipment procurement varies sharply by threat environment, throughput requirements, and regulatory compliance burden. Understanding how demand fragments across product types, technologies, and installation modes reveals where capital concentrates and where replacement cycles accelerate.
Product Type:
Volume deployments concentrate in legacy metal detection and X-ray screening, while premium expenditure shifts toward advanced imaging systems with algorithmic threat detection.
- X-Ray Machines:Dual-energy and computed-tomography variants now dominate baggage screening lanes at Category X airports under TSA and EASA mandates. Frankfurt and Amsterdam Schiphol operators are retrofitting cabin baggage lines to eliminate liquid restrictions through molecular-resolution material discrimination.
- Body Scanners:Millimeter-wave arrays with passive, non-ionizing radiation profiles are displacing metal detectors at aviation checkpoints. The technology's compatibility with privacy-preserving software that obscures anatomical detail drives procurement at Beijing Daxing, Shanghai Pudong, and Guangzhou Baiyun international terminals.
- Metal Detectors:Legacy portal systems persist at secondary checkpoints and event venues where cost constraints outweigh threat complexity requirements.
- CCTV Systems:AI-enabled video analytics integration is reclassifying surveillance infrastructure from passive recording to active threat detection layers.
Today's leader: X-Ray Machines. Tomorrow's challenger: Body Scanners.
Technology:
Electromagnetic foundations support high-volume deployments, while millimeter-wave and video analytics capture innovation investment and regulatory attention.
- Millimeter Wave:Active and passive array systems operating at 30-300 GHz enable non-invasive concealed threat detection without physical pat-downs. TSA Advanced Imaging Technology requirements and EASA cabin baggage directives are accelerating certification and deployment timelines for these systems.
- Video Analytics:Deep learning inference at the network edge compresses detection latency and enables real-time threat classification without cloud dependency. EU AI Act requirements for algorithmic audit trails and bias testing are extending certification timelines for automated detection systems.
- Electromagnetic:Induction-based metal detection remains the workhorse for high-throughput, low-complexity screening environments.
- Infrared:Thermal imaging supplements passenger screening in temperature-monitoring applications and perimeter security layers.
Millimeter Wave commands current procurement authority; Video Analytics is climbing the fastest as AI-enabled detection redefines compliance frameworks.
End User:
Aviation security mandates concentrate R&D investment and capital expenditure, while maritime and event venue applications expand addressable market boundaries.
- Aviation:Airport authorities across the United States, Germany, and China are modernizing aging checkpoint infrastructure at major international hubs. FAA Reauthorization Act mandates and EASA Implementing Regulation 2019/103 set baseline detection standards that OEMs must certify against before deployment.
- Event Venues:Saudi Arabia's NEOM and Red Sea Project mass-gathering sites require passenger screening infrastructure at non-aviation transportation nodes, opening demand outside traditional airport procurement channels.
- Maritime:Port security applications favor portable and modular systems adaptable to vessel boarding and cargo inspection workflows.
- Public Transportation:Subway and rail networks prioritize high-throughput, low-friction screening compatible with commuter flow patterns.
Aviation anchors revenue concentration. Event Venues represent the steepest expansion trajectory as giga-projects diversify procurement channels.
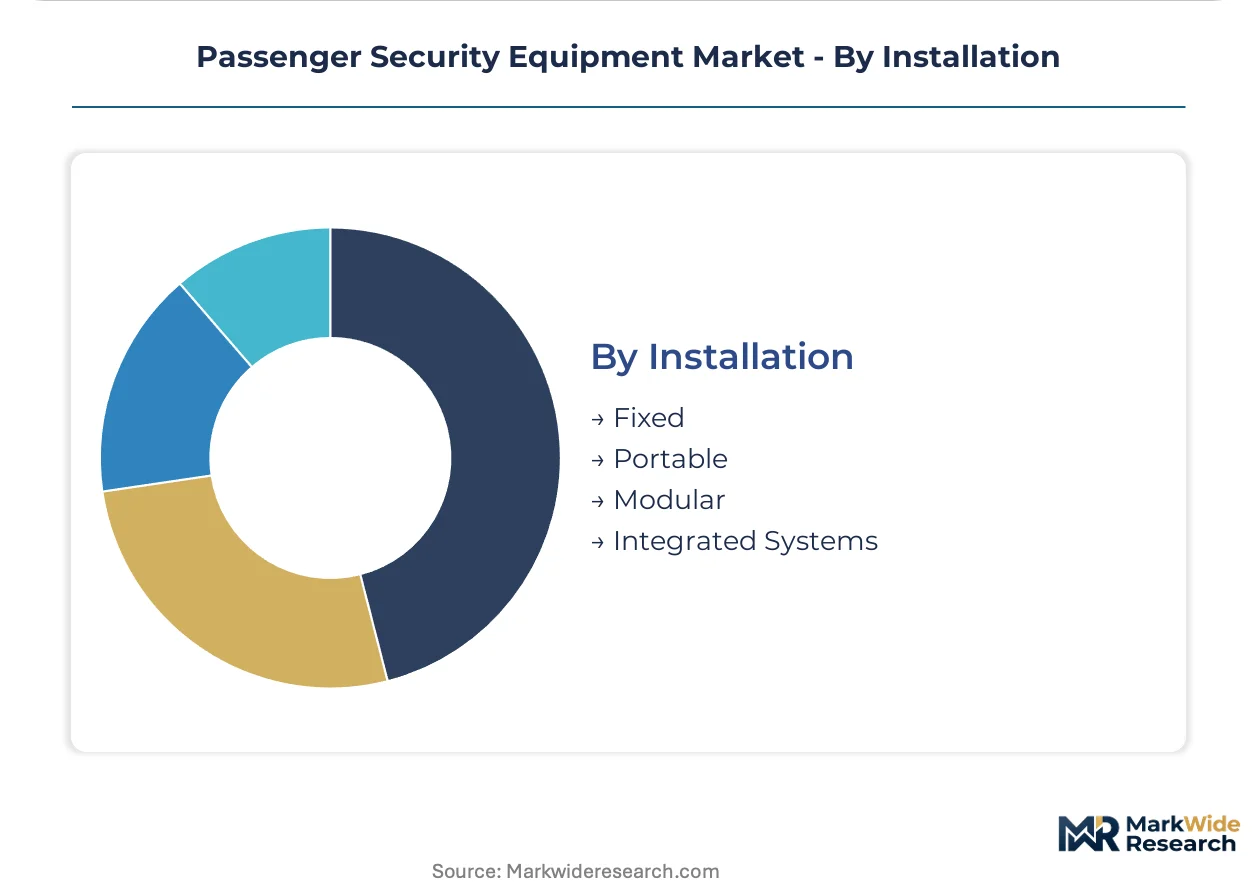
Installation:
Fixed infrastructure captures hub airport modernization budgets, while portable and modular configurations address greenfield flexibility requirements.
- Fixed:Permanent checkpoint lanes at TSA-managed airports and London Heathrow bundle hardware, software updates, and predictive maintenance under multi-year performance contracts. Subscription-based service models are displacing capital purchase approaches.
- Modular:India's Jewar and Navi Mumbai airport projects enable direct deployment of integrated CT baggage and millimeter-wave passenger screening lanes without retrofit constraints from legacy metal detector infrastructure.
- Portable:Rapid-deployment configurations serve temporary checkpoints, special events, and emergency response scenarios.
- Integrated Systems:Centralized security operations center synchronization requirements in Germany and the United States drive demand for unified hardware-software architectures.
Fixed installations dominate current contract value. Modular systems are gaining share fastest as greenfield projects bypass legacy constraints.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's airport infrastructure investment outpaces France's modernization timeline, while China's greenfield terminal construction creates fundamentally different procurement patterns than retrofit-heavy European hubs.
United States
TSA checkpoint modernization drives millimeter-wave scanner deployment at Category X airports under FAA Reauthorization Act mandates. The agency's Advanced Imaging Technology requirements force replacement of single-view metal detection portals at Atlanta, Dallas-Fort Worth, and Denver international terminals. Subscription-based service contracts now dominate procurement at TSA-managed checkpoints, bundling hardware, software updates, and predictive maintenance under multi-year performance agreements.
Germany
Frankfurt and Munich airports lead EASA-mandated computed tomography baggage screening retrofits under Implementing Regulation 2019/103. The country's Federal Aviation Office enforces certification timelines that accelerate CT deployment in cabin baggage lanes to eliminate liquid restrictions. Hub operators in North Rhine-Westphalia and Bavaria must synchronize new millimeter-wave scanner outputs with existing centralized security operations center software architectures, creating integration complexity for legacy infrastructure.
China
Beijing Daxing, Shanghai Pudong, and Guangzhou Baiyun international terminals drive domestic millimeter-wave scanner certification under NMPA and MIIT GB standards for electromagnetic emissions. The country's airport infrastructure buildout favors integrated CT baggage and passenger screening lanes without retrofit constraints from aging metal detector systems. Localization partnerships with foreign OEMs accelerate as GB standards constrain import eligibility for non-compliant equipment.
India
Jewar and Navi Mumbai greenfield airport projects enable direct deployment of modern screening infrastructure without legacy system integration burdens. The Bureau of Indian Standards certification requirements for passenger security equipment create duplicative testing protocols that extend time-to-market for international OEMs. Maharashtra and Uttar Pradesh aviation hubs represent the steepest procurement trajectory as these projects bypass retrofit constraints entirely.
Saudi Arabia
NEOM and Red Sea Project mass-gathering sites require passenger screening infrastructure at non-aviation transportation nodes, opening demand outside traditional airport procurement channels. The country's national aviation regulator enforces detection standards for giga-project venues that mirror aviation checkpoint requirements. Western Region and Northwest development corridors concentrate deployment of modular and portable screening configurations for rapid-deployment scenarios.
Passenger Security Equipment Market Competitive Environment
Top-tier vendors anchor aviation security mandates, while mid-tier specialists compete on manufacturing scale and regional certification expertise. The market structure concentrates procurement authority among national regulators and hub airport operators, forcing OEMs to certify against TSA, EASA, and NMPA standards before deployment. Three strategic archetypes dominate: firmware-integrated protocol specialists, manufacturing-scale cost leaders, and service-contract recurring revenue platforms. Competitive moves center on algorithmic threat-detection licensing and predictive maintenance subscription models that displace capital purchase approaches.
Within the protocol-integrated tier, Smiths Detection Group Ltd. and L3Harris Technologies, Inc. exemplify vendors that have aligned millimeter-wave firmware with regulatory checkpoint standards. These companies occupy positions where deep integration with TSA and EASA mandates creates certification barriers for challengers. Rapiscan Systems represents the manufacturing-scale archetype, sustaining cost advantages in high-volume X-ray belt scanner deployments through production efficiency rather than firmware differentiation.
| Leading Market Players |
|---|
| Honeywell International Inc. |
| Smiths Detection Group Ltd. |
| L3Harris Technologies, Inc. |
| Rapiscan Systems |
| Siemens AG |
| Bosch Sicherheitssysteme GmbH |
| OSI Systems Inc. |
| SITA |
| Thales Group |
| Others |
Value Chain & Pricing Dynamics
Captive production of gallium nitride RF modules in Taiwan and South Korea anchors both component availability and OEM pricing power, as millimeter-wave array manufacturers secure wafer capacity through multi-year foundry commitments that lock in cost positions while constraining challenger access.
Pricing Analysis
Capacity additions in China's domestic scanner production are reshaping price floors for standard X-ray belt systems, compressing margins for manufacturing-scale exporters. Subscription-based service contracts now dominate premium tiers, with TSA-managed checkpoints and London Heathrow bundling predictive maintenance and firmware upgrades under performance-based agreements. Price differentiation rests on certification tier—EASA and TSA protocol integration commands premiums against BIS-only certified alternatives. Cost compression in entry-level metal detection portals is intensifying as Indian greenfield projects solicit volume tenders without legacy integration burdens.
Supply Chain Analysis
China's GB electromagnetic emission standards and domestic-content certification requirements are reshaping sourcing patterns, forcing foreign OEMs into localization partnerships for NMPA eligibility. High-frequency semiconductor fabrication concentrates in Taiwan and South Korea, while precision mechanical assemblies source from Germany and Japan. Gallium nitride wafer supply draws from limited foundry capacity, creating single-source vulnerability for active millimeter-wave arrays. Distribution runs through national aviation regulators and hub airport procurement authorities rather than open-channel distributors, concentrating buyer power among TSA, EASA, and CAAC certification holders.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Passenger security equipment procurement has shifted toward algorithmic performance guarantees and guaranteed-uptime contracts, rewarding vendors with certified firmware integration and predictive maintenance platforms over pure hardware manufacturers.
For Market Incumbents: Cement protocol-integrated positions by deepening EASA and TSA certification moats before EU AI Act algorithmic audit requirements extend compliance timelines for challengers. Prioritize backward integration into gallium nitride RF module supply through foundry partnerships in Taiwan and South Korea, locking in component access against capacity constraints. Expand service-contract recurring revenue at London Heathrow and Frankfurt to displace capital-purchase competitors.
For New Entrants and Emerging Players: The price-point gap between premium protocol-integrated systems and economy metal detection portals offers entry space for AI-enabled video analytics specialists targeting event venue and maritime applications outside aviation procurement channels. Saudi Arabia's NEOM and Red Sea Project mass-gathering sites lack incumbent service relationships, enabling direct modular deployment. Pursue BIS certification for India's Jewar and Navi Mumbai greenfield airports where legacy integration burdens do not apply.
For Investors and Strategic Acquirers: Roll-up economics work for mid-tier OEMs with regional certification expertise because regulatory fragmentation across TSA, EASA, and NMPA standards prevents single-vendor global dominance. Five-to-ten-year viability favors acquisition targets holding dual EASA-TSA protocol integration alongside software-defined detection platforms. Monitor EU AI Act implementation timelines as inflection indicator for algorithmic audit compliance costs that could consolidate vendor tiers.
| Strategic Initiative | Industry Significance |
|---|---|
| Algorithmic Threat Detection Licensing | EASA's Implementing Regulation 2019/103 mandates automated detection without human image analysis, forcing firmware upgrades. |
| Predictive Maintenance Platform Expansion | Subscription service contracts at TSA checkpoints and London Heathrow displace capital purchase models with recurring revenue. |
| Localization Partnership Formation | China's GB standards constrain import eligibility, requiring joint ventures for NMPA certification at Beijing Daxing and Shanghai Pudong. |
| Gallium Nitride Supply Commitment | Foundry capacity concentration in Taiwan and South Korea creates input cost volatility for millimeter-wave array production. |
| Greenfield Direct Deployment | India's Jewar and Navi Mumbai projects enable integrated CT and millimeter-wave lanes without retrofit constraints. |
Study Parameters
Coverage spans the United States, Germany, China, India, and Saudi Arabia, with primary inputs from each market combining interviews with airport procurement directors, aviation security regulators, OEM product managers, and predictive maintenance service heads alongside secondary validation. Regulatory filings from TSA, EASA, NMPA, and BIS provided certification timeline and mandate data. Trade customs records, airport infrastructure investment disclosures, and semiconductor foundry capacity reports supplied bottom-up volume estimates triangulated against top-down market sizing.
Granularity-level modeling disaggregated the analysis window by product type, technology, end user, and installation mode, with additional segmentation by regulatory certification tier. CAGRs derived from regression analysis of historical procurement cycles and mandate-driven replacement timelines, incorporating EASA's Implementing Regulation 2019/103 compliance deadlines and FAA Reauthorization Act checkpoint modernization schedules as structural demand anchors.
Caveats apply where gallium nitride foundry capacity constraints, EU AI Act algorithmic audit delays, or India's BIS certification timeline extensions could materially shift the outlook. Forecasts reflect assumptions about regulatory mandate adherence and infrastructure investment continuity. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Safety Equipment and Personal Protective Equipment (PPE)
Hazardous Disposal Bag Market
Safety Equipment and Personal Protective Equipment (PPE)
Road Flares Market
Safety Equipment and Personal Protective Equipment (PPE)
Global Surgical Mask and Respirators Market
Safety Equipment and Personal Protective Equipment (PPE)
Hearing Protection Equipment Market
Safety Equipment and Personal Protective Equipment (PPE)
PPE Detection Market
Safety Equipment and Personal Protective Equipment (PPE)
Surface Protection Services Market
Safety Equipment and Personal Protective Equipment (PPE)
Household Eye Protection Lamp Market
Safety Equipment and Personal Protective Equipment (PPE)
Welding Helmets Market
Safety Equipment and Personal Protective Equipment (PPE)
Military Gas Mask Market
Safety Equipment and Personal Protective Equipment (PPE)
Lightning Protection Technologies Market
Safety Equipment and Personal Protective Equipment (PPE)
Respiratory Protective Equipment Market
Safety Equipment and Personal Protective Equipment (PPE)
Safety IO Modules Market
Safety Equipment and Personal Protective Equipment (PPE)
Hand Sanitizer Spray Pen Market
Safety Equipment and Personal Protective Equipment (PPE)
Europe Safes and Vaults Market
Safety Equipment and Personal Protective Equipment (PPE)
Medical Radiation Protection Aprons Market
Safety Equipment and Personal Protective Equipment (PPE)
Electrical Safety Gloves Market