
 Crime Risk Report Market | 2026-2036
Crime Risk Report Market Size, Share, and Industry Trends Forecast 2026-2036
Crime Risk Report Market Analysis
The capability gap between cloud-native analytics platforms and legacy on-premise systems is collapsing as crime risk data migrates to real-time streaming architectures. CoreLogic leverages its property data backbone to anchor geospatial crime correlation models. LexisNexis Risk Solutions sustains dominance in legal-record enrichment for fraud detection. IBM competes through Watson-powered natural language processing of unstructured crime reports.
Crime risk reports aggregate multi-source intelligence—government incident filings, insurance claims histories, surveillance sensor feeds, and social media signals—into standardized risk scores for property valuation, underwriting, and security planning. These outputs typically quantify probabilistic loss exposure across postal-code or census-tract granularity using statistical modeling and predictive analytics. The risk type dimension shows cyber crime and fraud segments outpacing property crime in growth velocity as digital transaction volumes expand. Client type concentration tilts toward insurance companies and security firms where recurring subscription models generate superior retention economics.
US insurers navigate NHTSA data-sharing protocols for vehicle theft risk while FCC regulations govern location data privacy in mobile-derived crime analytics. The EU AI Act imposes conformity assessment requirements on automated risk scoring systems deployed by European law enforcement agencies. Stakeholders must monitor evolving algorithmic accountability standards that determine market access for predictive crime platforms.
Market Dynamics
The migration of crime risk analytics from batch-processed historical reports to real-time streaming architectures is compressing competitive differentiation between established data aggregators and cloud-native entrants. This technical inflection is redistributing value capture toward platforms that can ingest sensor feeds, social signals, and insurance claims into sub-second risk scores.
Growth Catalysts
- EU AI Act compliance mandates:European law enforcement agencies must deploy conformity-assessed automated risk scoring systems, creating procurement pull for transparent algorithmic platforms.
- Real-time crime center deployments:Federal agencies across the United States are expanding operational command infrastructure that demands live crime risk visualization and predictive alerting.
- Digital transaction volume expansion:E-commerce platforms and fintechs require fraud risk integration at checkout, embedding crime analytics into payment workflows.
Market Restraints
- Location data privacy constraints:FCC regulations on mobile-derived geolocation impose consent and retention limits that constrain predictive accuracy in urban crime modeling.
- Input data fragmentation:Municipal police departments maintain incompatible incident reporting formats, forcing expensive normalization overhead for multi-jurisdiction risk aggregation.
- Algorithmic accountability liability:Courts in multiple jurisdictions are establishing precedents that expose risk scoring vendors to civil action for disparate impact in policing decisions.
Strategic Opportunities
- Cyber crime risk unbundling:Ransomware and business email compromise now generate standalone risk products distinct from traditional property crime analytics.
- Insurance-linked securities channel:Catastrophe bond structures are incorporating crime risk tranches, opening institutional capital markets to risk transfer instruments.
- Social media signal integration:Natural language processing of geotagged content enables pre-incident anomaly detection for event security and retail loss prevention.
Industry Challenges
- Data science talent scarcity:The intersection of criminology, statistical modeling, and streaming infrastructure engineering remains thinly staffed relative to platform expansion timelines.
- Legacy system integration friction:Property insurers and security firms maintain decades-old policy administration systems that resist API-based risk score ingestion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Crime Risk Report Market |
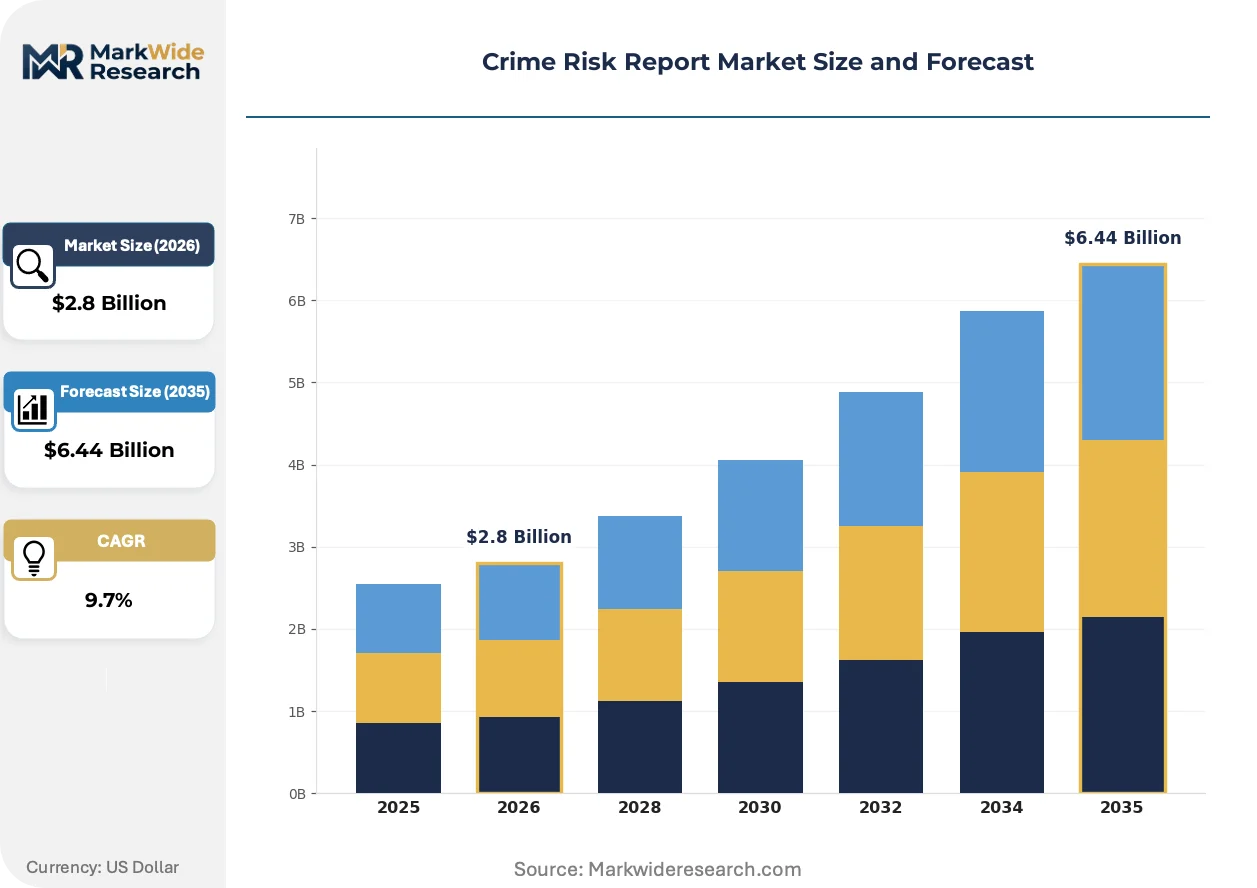
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $6.44 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Data Source: Government Reports, Insurance Claims, Surveillance Data, Social Media Analytics Risk Type: Property Crime, Violent Crime, Cyber Crime, Fraud Client Type: Insurance Companies, Law Enforcement Agencies, Security Firms, Corporations Analysis Method: Statistical Modeling, Predictive Analytics, Risk Assessment, Mapping |
| Companies Covered | CAP Index Inc., CoreLogic, LexisNexis Risk Solutions, Fenergo, Fiserv Inc., IBM, Oracle, ACI Worldwide, Verisk Analytics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Crime Risk Report Market Emerging Trajectories
Crime risk analytics is undergoing a platform shift from static risk ratings to dynamic, event-driven scoring systems that recalculate exposure continuously. This transformation is altering how insurers price policies, how security firms allocate resources, and how law enforcement agencies deploy personnel.
Edge computing for video analytics is fragmenting the traditional centralized processing model for surveillance-derived crime detection. Retail chains and smart city operators are deploying GPU-equipped cameras that run object recognition and behavioral anomaly models locally, reducing latency for theft intervention from seconds to milliseconds. This distributed architecture is fragmenting vendor relationships as customers mix hardware OEMs, AI model providers, and cloud backends rather than buying integrated stacks.
The EU AI Act's risk classification framework for biometric identification and predictive policing systems is forcing algorithmic transparency disclosures that were previously voluntary. Vendors must now document training data provenance, performance metrics across demographic groups, and human oversight protocols to access European public sector contracts. Law enforcement agencies in Germany and France are delaying procurement cycles to assess conformity assessment pathways, compressing near-term revenue recognition for platform providers.
Subscription-based risk intelligence is displacing per-report transactional purchasing among mid-market property managers and regional insurers. Buyers prefer unlimited query access with quarterly model refreshes over one-off postal code risk downloads. This preference shift is most visible in the United States, where CoreLogic and LexisNexis have restructured pricing tiers to capture recurring revenue from customers previously served through ad hoc data marketplaces.
Crime Risk Report Market Segmentation
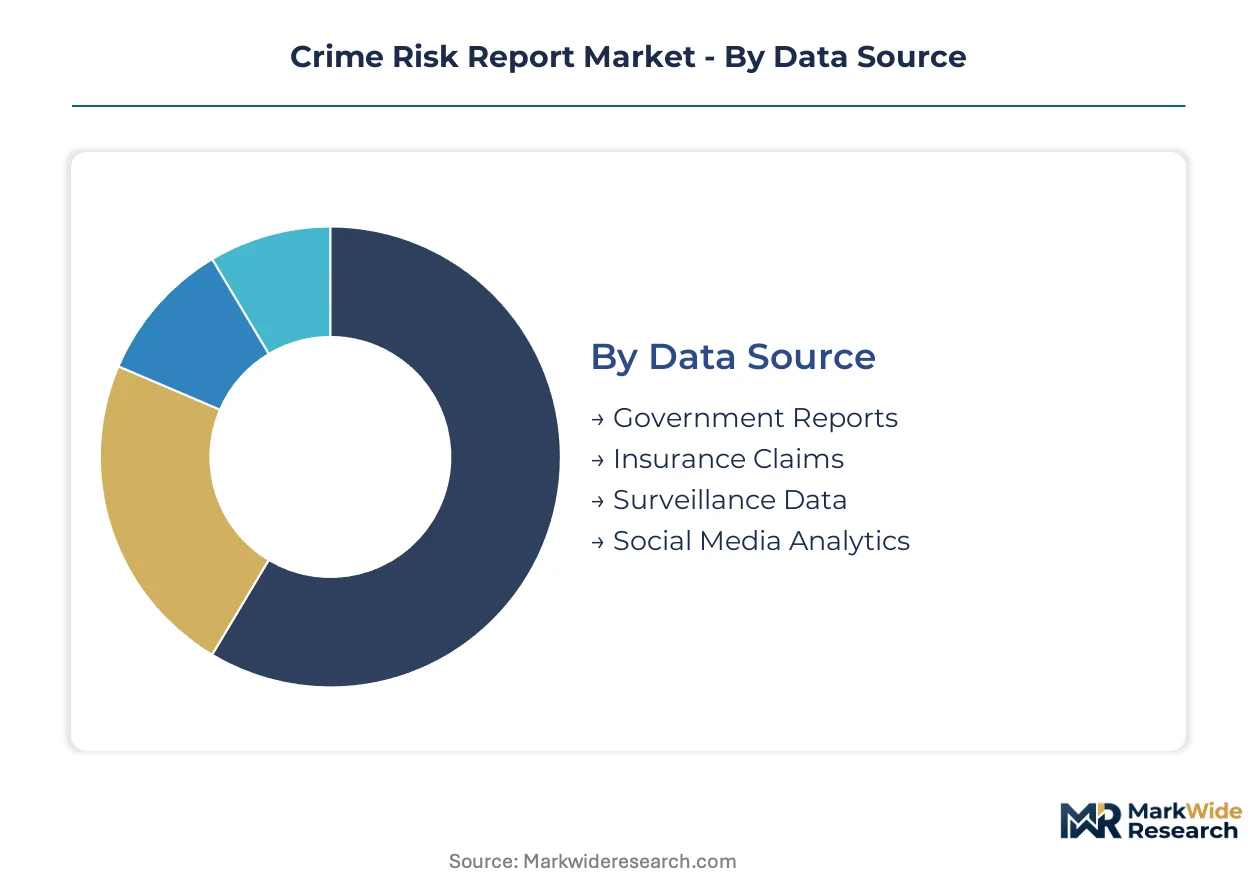
Crime risk report segmentation reflects divergent data provenance, regulatory exposure, and client procurement workflows. Each category shapes how vendors architect subscription tiers, compliance documentation, and API delivery specifications.
Data Source:
EU AI Act transparency mandates and FCC location privacy rules create divergent compliance burdens across input channels.
- Government Reports:Municipal police filings and federal incident databases provide foundational crime statistics with standardized taxonomy. US agencies navigate NHTSA vehicle theft protocols while European counterparts face GDPR constraints on cross-border data pooling.
- Insurance Claims:Historical loss records from property and casualty carriers enable actuarial-grade risk calibration. Demand concentrates among US underwriters embedding scores into policy pricing workflows, constrained by state-level rate filing regulations.
- Surveillance Data:Video analytics feeds from retail and municipal camera networks deliver real-time behavioral signals. Edge computing deployments in smart city pilots across Germany and France fragment vendor relationships as GPU-equipped cameras run localized inference.
- Social Media Analytics:Geotagged content and natural language processing of public posts enable pre-incident anomaly detection. FCC regulations on mobile-derived geolocation impose consent architectures that limit predictive accuracy in urban modeling.
Established volume favors Government Reports; emerging adoption favors Social Media Analytics.
Risk Type:
Client procurement budgets and incident frequency curves determine segment prioritization across underwriting and security planning functions.
- Property Crime:Burglary, theft, and vandalism risk scoring dominates residential real estate valuation and commercial property underwriting. US insurers maintain the largest deployment base, though saturation is compressing pricing power in mature postal-code models.
- Violent Crime:Homicide, assault, and robbery analytics serve law enforcement resource allocation and corporate security site selection. Federal real-time crime center deployments across the United States drive concentrated demand for live visualization dashboards.
- Cyber Crime:Ransomware and business email compromise risk products now unbundle from traditional property crime portfolios. E-commerce platforms and fintechs embed fraud analytics into payment workflows, climbing the fastest among all risk categories.
- Fraud:Identity theft, insurance fraud, and financial crime detection leverages legal-record enrichment and transaction pattern analysis. LexisNexis sustains dominance through proprietary court filing databases.
Property Crime anchors current revenue; Cyber Crime captures expansion capital.
Client Type:
Procurement sophistication and renewal economics vary sharply across institutional buyers with divergent technical integration capabilities.
- Insurance Companies:Recurring subscription models for underwriting workflow integration generate superior retention economics. CoreLogic and LexisNexis have restructured pricing tiers to capture this segment from ad hoc data marketplaces.
- Law Enforcement Agencies:Real-time crime center infrastructure demands sub-second risk visualization and predictive alerting. EU AI Act conformity assessments delay procurement cycles in Germany and France as agencies evaluate transparency documentation.
- Security Firms:Physical security providers require mobile-accessible risk briefings for guard deployment and event planning. Legacy policy administration systems resist API-based score ingestion, creating integration friction.
- Corporations:Retail chains and logistics operators use crime risk data for site selection, supply chain routing, and loss prevention staffing. Edge computing video analytics enables millisecond-latency theft intervention.
Insurance Companies dominate recurring revenue; Corporations show steepest expansion trajectory.
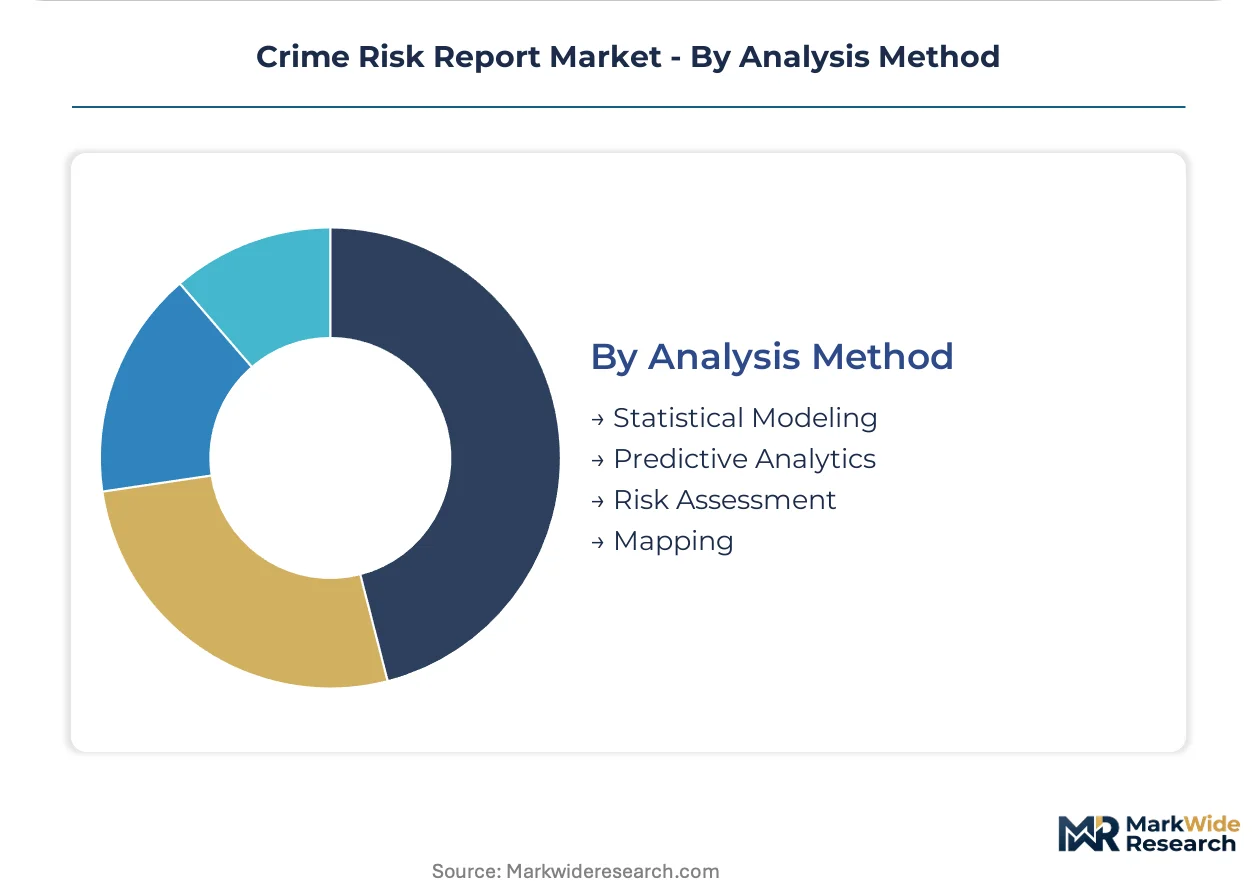
Analysis Method:
Technical architecture choices determine latency, explainability, and regulatory defensibility across deployment contexts.
- Statistical Modeling:Regression-based approaches on historical incident frequencies provide transparent, auditable risk ratings favored by rate-regulated US insurers.
- Predictive Analytics:Machine learning models on multi-source intelligence enable forward-looking exposure quantification. EU AI Act mandates force algorithmic transparency disclosures previously voluntary.
- Risk Assessment:Structured expert judgment protocols support security consulting engagements with documented human oversight.
- Mapping:Geospatial visualization layers anchor property valuation workflows and law enforcement patrol optimization.
Statistical Modeling retains regulatory preference; Predictive Analytics gains technical adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price sensitivity varies sharply across geographies. United States buyers absorb premium pricing for real-time streaming capabilities, while European procurement cycles stretch longer under EU AI Act compliance burdens.
United States
Federal law enforcement agencies drive concentrated demand through real-time crime center expansions. FCC regulations on mobile-derived geolocation impose consent architectures that constrain predictive accuracy in urban crime modeling. Texas and Florida metropolitan clusters anchor the largest deployments of streaming crime risk infrastructure.
Germany
Bundesministerium des Innern procurement budgets prioritize algorithmic transparency documentation under EU AI Act mandates. KBA vehicle theft data-sharing protocols enable cross-border risk correlation with neighboring jurisdictions. Berlin and Munich police departments delay vendor selection to assess conformity assessment pathways.
United Kingdom
City of London Police and Metropolitan Police Service embed crime risk scores into counter-fraud workflows. Information Commissioner's Office guidance on automated decision-making shapes vendor disclosure requirements. London's financial services cluster generates concentrated demand for cyber crime risk unbundling.
France
CNIL enforcement actions on algorithmic profiling accelerate procurement of auditable risk scoring platforms. ANSM data governance frameworks influence how health sector security planners access crime analytics. Paris and Lyon smart city pilots deploy edge computing video analytics with localized inference capabilities.
Japan
METI industrial security guidelines drive manufacturing site selection demand for crime risk data. PMDA-adjacent data handling standards shape how pharmaceutical logistics operators integrate risk scores. Tokyo and Osaka metropolitan areas anchor the regional deployment base for property crime analytics.
Crime Risk Report Market Vendor Landscape
A small set of integrated leaders sits above a broader specialist tier in the Crime Risk Report Market. Consolidation pressure intensifies as cloud-native platforms erode legacy data aggregator differentiation. Three archetypes dominate: property data backbone providers, legal-record enrichment specialists, and AI-powered natural language processors. Competitive moves concentrate on API-based workflow integration and recurring subscription model restructuring.
Within the integrated data backbone tier, CoreLogic and LexisNexis Risk Solutions occupy anchor positions exemplifying geospatial correlation and legal-record enrichment archetypes respectively. IBM represents the AI-native processing vector through Watson-powered platforms. These three entities collectively illustrate how vendor relationships fragment as customers mix hardware OEMs, AI model providers, and cloud backends rather than purchasing integrated technology stacks.
| Leading Market Players |
|---|
| CAP Index Inc. |
| CoreLogic |
| LexisNexis Risk Solutions |
| Fenergo |
| Fiserv Inc. |
| IBM |
| Oracle |
| ACI Worldwide |
| Verisk Analytics |
| Others |
Supply Flow & Price Mechanics
Streaming data infrastructure is displacing batch-processed historical reports as the dominant delivery architecture, simultaneously concentrating vendor relationships around cloud-native platforms and compressing pricing premiums for legacy data aggregators. This substitution dynamic reshapes supply geography toward hyperscaler regions and forces pricing economics toward subscription-based recurring revenue models.
Pricing Analysis
Recurring subscription revenue from quarterly model refreshes and unlimited API query access now drives lifetime value for crime risk platforms. Three-tier pricing structure across premium real-time streaming, standard daily batch updates, and economy historical-only access separates large insurers from mid-market property managers from occasional ad hoc buyers. Pricing pressure stems from cloud-native entrants undercutting established data aggregators with lower infrastructure overhead. Mid-market security firms show highest price sensitivity, while federal law enforcement agencies absorb premium pricing for sub-second risk visualization.
Supply Chain Analysis
Port congestion on trans-Pacific lanes and container availability constraints on Asia-North America routes elevate inbound logistics costs for GPU-equipped edge computing hardware deployed in smart city pilots. Data ingestion pipelines draw from United States municipal police filings, European cross-border incident databases, and Asian manufacturing hubs for surveillance hardware components. Single-source vulnerability concentrates in Taiwan semiconductor fabrication for AI inference chips. Distribution runs through direct API integrations with insurance policy administration systems and law enforcement real-time crime center platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Crime risk analytics is undergoing a platform-economics inflection as API-first architectures displace file-based data exchanges, with interoperability mandates from the EU AI Act accelerating ecosystem consolidation around transparent algorithmic standards.
For Market Incumbents: Secure recurring revenue lock-in by restructuring pricing tiers toward unlimited query subscriptions with embedded quarterly model refreshes. Defend against cloud-native entrants through backward integration into proprietary data backbones like CoreLogic's property records or LexisNexis's court filing databases. Prioritize EU AI Act conformity assessment documentation to maintain European public sector procurement access.
For New Entrants and Emerging Players: Lead with cyber crime risk unbundling as the most penetrable white-space segment, where ransomware and business email compromise products remain distinct from legacy property crime portfolios. Target mid-market property managers in United States metropolitan clusters with mobile-accessible risk briefings for guard deployment. Pursue channel partnerships with insurance policy administration system vendors to bypass legacy API integration friction.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed data aggregators holding stagnant batch-processed report revenues but undervalued real-time streaming infrastructure. Long-term viability hinges on successful platform migration toward event-driven scoring systems with sub-second latency. Watch EU AI Act conformity assessment completion rates as the inflection indicator for European public sector revenue recognition.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | API-first architectures enable seamless embedding of risk scores into insurance underwriting workflows. |
| Geographic Expansion | Real-time crime center deployments in Texas and Florida metropolitan clusters anchor United States demand concentration. |
| Regulatory Compliance Investment | EU AI Act conformity assessments unlock European law enforcement procurement budgets in Germany and France. |
| Acquisition of Specialist Firm | Edge computing video analytics providers fragment vendor relationships in smart city pilots. |
| Product Launch | Cyber crime risk unbundling captures fastest-growing segment as fintechs embed fraud analytics into payment workflows. |
Methodological Framework
A spread of perspectives from insurance underwriting executives, law enforcement procurement officers, security firm operations directors, and municipal data governance leads converged on the working assumptions. Primary interviews combined with secondary validation from FCC regulatory filings, EU AI Act implementation guidance, NHTSA data-sharing protocols, and SEC disclosures from publicly traded data aggregators. Bottom-up sizing of subscription revenue tiers and top-down cross-check against federal procurement databases anchored the analytical framework.
Segmentation dimensions modeled span data source provenance, risk type categorization, client procurement archetype, and analytical method architecture across the projection horizon. CAGRs derived from trend extrapolation of real-time infrastructure deployment rates and subscription pricing tier adoption curves. Forecast inputs incorporate streaming data volume growth trajectories and EU AI Act compliance timeline assumptions.
Forecasts assume regulatory continuity in FCC location privacy rules and EU AI Act enforcement patterns; material policy shifts would require re-modeling. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Public Safety
Europe Road Safety Market
Public Safety
Voice Evacuation Systems Market
Public Safety
Public Safety Drones Market
Public Safety
LAMEA Wireless Broadband in Public Safety Market
Public Safety
Middle East Crime and Combat Market
Public Safety
Public Safety LTE Market
Public Safety
AI for Public Security and Safety Market
Public Safety
Safe City Market
Public Safety
Europe Public Safety Market
Public Safety
Global Public Safety in Building Wireless Das System Market
Public Safety
Public Safety in-Building Wireless Distributed Antenna System (DAS) Market
Public Safety
Global Wireless Broadband in Public Safety Market
Public Safety
Global IoT for Public Safety Market
Public Safety
Europe Wireless Broadband in Public Safety Market
Public Safety
Global Public Safety Analytics Market
Public Safety
Crowd Management System Market