
 Global Airport and Marine Port Security Market | 2026-2036
Global Airport and Marine Port Security Market Size, Share, and Industry Trends Forecast 2026-2036
Global Airport and Marine Port Security Market Analysis
Israeli perimeter detection manufacturers is recalibrating production capacity to meet surging orders from Mediterranean and Gulf port authorities. Thales Group leverages its command-and-control software heritage to anchor large-scale airport security integration contracts across France and Southeast Asia. Siemens AG competes on digital twin platforms that simulate threat scenarios before physical deployment.
Airport and marine port security encompasses layered physical and electronic protection systems designed to intercept weapons, explosives, and unauthorized personnel at transportation nodes, typically integrating millimeter-wave scanners, underwater sonar arrays, and AI-enhanced video analytics operating at 30-60 frames per second for real-time threat classification. Detection Systems represents the most mature revenue pool, while Biometric Systems captures the fastest upgrade cycle as facial recognition gates replace legacy document checks. Managed Services now attracts margin concentration as operators outsource 24/7 monitoring rather than maintaining in-house security operations centers.
FAA mandates under US federal aviation law, EU Green Deal port electrification requirements, and Singapore's MPA port security codes collectively tighten compliance thresholds for equipment certification and staff training protocols. The EU AI Act further constrains automated passenger screening algorithms deployed at Schengen Area airports. Stakeholders must weigh interoperability investments against the risk of stranded assets when regulatory technical standards shift.
Market Dynamics
Integrated command-and-control architectures are displacing standalone detection hardware as port authorities prioritize interoperability over point solutions. This shift compresses vendor margins on equipment while expanding recurring software revenue pools.
Growth Catalysts
- EU Green Deal port electrification mandates:Coastal terminals in Rotterdam and Hamburg must upgrade shore power infrastructure, triggering parallel security system overhauls to monitor electrified cargo zones.
- Millimeter-wave body scanners:Airport operators in Singapore and Dubai are replacing metal detectors with walk-through units that detect non-metallic threats without passenger divestment.
- Underwater drone proliferation:Hull inspection protocols at Gulf of Aden transshipment hubs now require autonomous underwater vehicles, creating demand for sonar-integrated perimeter arrays.
Market Restraints
- Semiconductor supply concentration:FPGA chips for real-time video analytics face allocation bottlenecks from Taiwanese foundries, extending lead times for AI-enhanced screening gates.
- EU AI Act algorithmic constraints:Automated passenger screening systems deployed at Schengen Area airports must maintain human-in-the-loop review, increasing staffing overhead.
- Legacy copper cable infrastructure:Marine ports along the US Eastern Seaboard require fiber backhaul replacement before supporting 4K video analytics at 60 frames per second.
Strategic Opportunities
- Vietnam's Lach Huyen deep-water port expansion:Greenfield terminal construction offers vendors clean-slate deployment of integrated biometric-border management systems without legacy integration burden.
- Convergence of digital twin simulation with physical access control:Siemens AG and Thales Group are anchoring contracts by modeling threat scenarios before hardware procurement.
- Outcome-based managed security services:Port operators in the United Kingdom are outsourcing 24/7 monitoring to specialist firms rather than maintaining in-house security operations centers.
Industry Challenges
- Cyber-physical systems integration:Converging IT and OT networks at automated marine terminals exposes screening equipment to ransomware vectors previously isolated from operational technology.
- Multi-jurisdiction certification timelines:Equipment vendors must secure separate FAA, EASA, and CAAC approvals for millimeter-wave scanners, fragmenting product roadmaps.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Airport and Marine Port Security Market |
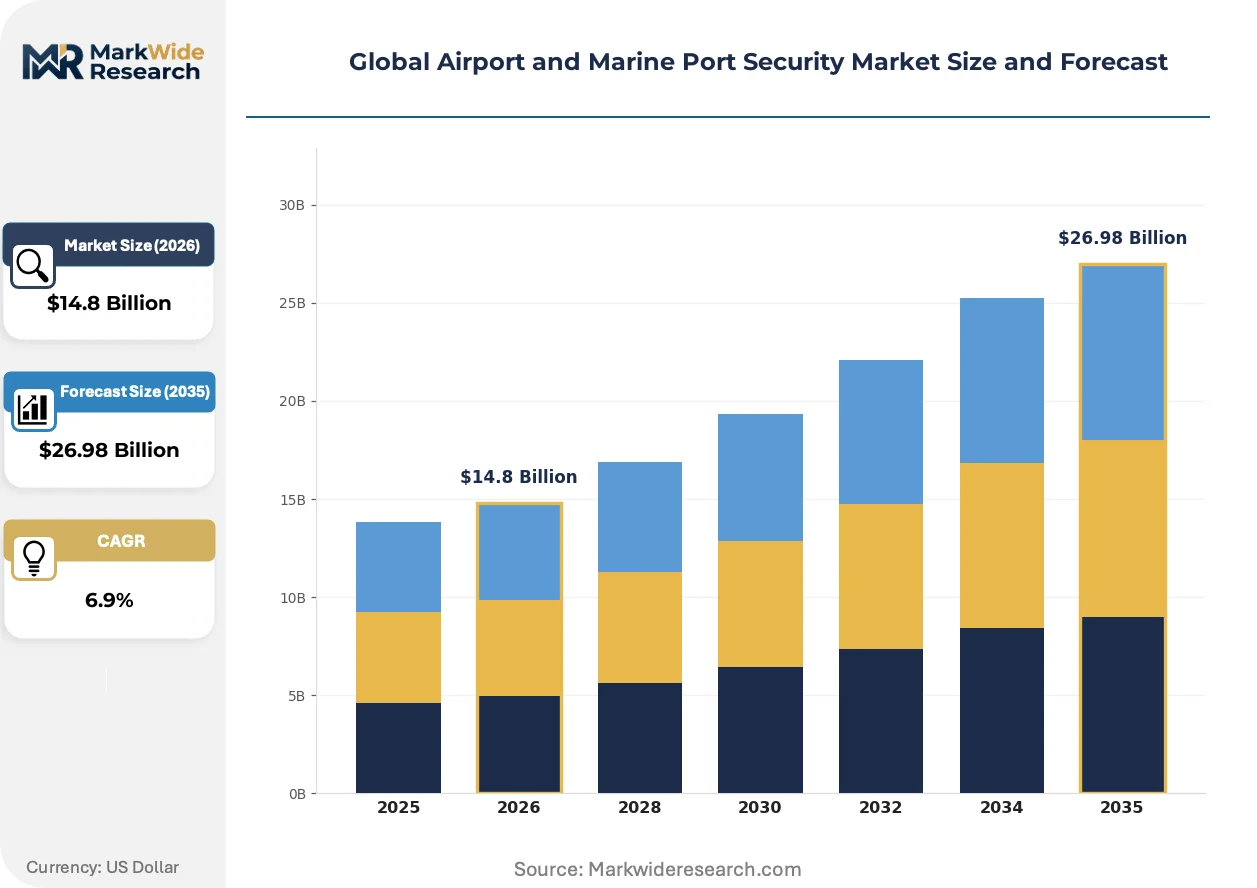
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $26.98 Billion |
| CAGR (2026 – 2036) | 6.9% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Biometric Systems, Surveillance Cameras, Access Control, Detection Systems Service Type: Consulting, Implementation, Managed Services, Training Application: Cargo Screening, Passenger Screening, Perimeter Security, Threat Detection End User: Airports, Shipping Companies, Government Agencies, Security Firms |
| Companies Covered | Thales Group, Siemens AG, Honeywell International Inc., Saab AB, Raytheon Technologies Corporation, Bosch Security Systems Inc., Smiths Detection Group Ltd., Motorola Solutions Inc., FLIR Systems Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Airport and Marine Port Security Market Emerging Trajectories
Artificial intelligence inference at the network edge is compressing response latency for threat classification while reducing backhaul bandwidth requirements. This architectural shift enables real-time decision-making in bandwidth-constrained maritime environments.
Millimeter-wave scanner arrays is modularizing from fixed-gantry installations toward reconfigurable, trailer-mounted units for temporary event security and emergency port capacity expansion. Saudi Arabia's Red Sea Project and Qatar's World Cup legacy infrastructure are deploying these mobile configurations for seasonal pilgrimage traffic. The technology is modularizing vendor business models from capital equipment sales toward lease-and-operate arrangements.
EU AI Act algorithmic accountability requirements are forcing facial recognition gate manufacturers to maintain audit trails for automated passenger screening decisions. French and German airport operators now demand explainable AI modules that flag anomalies with human-interpretable confidence scores. Biometric system vendors are responding by embedding local processing units that generate compliance documentation without transmitting raw passenger imagery to central servers.
Buyer consolidation among mega-port operators is compressing vendor negotiation cycles and unbundling after-sales service contracts from initial equipment procurement. DP World and PSA International now negotiate enterprise security frameworks across multiple terminal locations rather than site-by-site purchases. This concentration is most visible in the Indo-Pacific rim where Singapore's MPA port security codes serve as reference standards for regional procurement templates.
Global Airport and Marine Port Security Market Segmentation
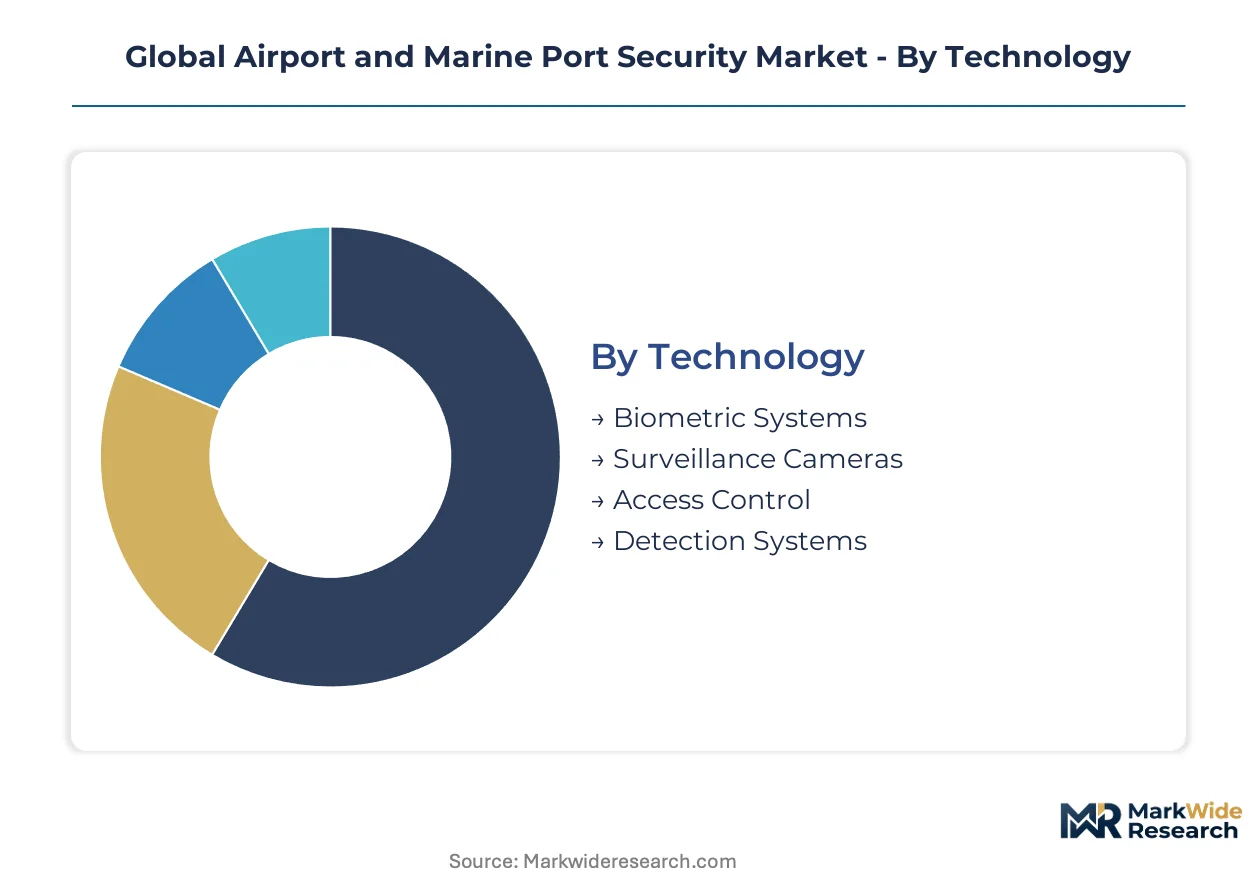
Segmentation in airport and marine port security reflects divergent integration depths across physical infrastructure, digital services, and operational workflows. Technology layers range from standalone perimeter hardware to fully embedded biometric-IT architectures. Service and application segments track whether procurement prioritizes capital equipment or recurring operational expenditure.
Technology:
Standalone detection hardware dominates retrofit installations, while embedded biometric and AI-video systems anchor greenfield integrated command platforms.
- Detection Systems:Millimeter-wave scanners, X-ray baggage units, and underwater sonar arrays form the foundational screening layer. Demand concentrates at Gulf of Aden transshipment hubs and Singapore's Tuas terminal expansion, where hull inspection protocols now mandate autonomous underwater vehicle integration. FPGA chip allocation bottlenecks from Taiwanese foundries currently extend lead times.
- Biometric Systems:Facial recognition gates, fingerprint enrollment stations, and iris capture modules replace legacy document verification. Singapore Changi and Dubai International are deploying walk-through units that eliminate passenger divestment, though EU AI Act human-in-the-loop requirements increase staffing overhead at Schengen Area deployments.
- Surveillance Cameras:4K video analytics operating at 30-60 frames per second enable real-time threat classification. US Eastern Seaboard marine ports require fiber backhaul replacement before supporting full frame-rate analytics.
- Access Control:Physical credential readers and biometric-enabled turnstiles manage personnel movement through restricted zones. Rotterdam and Hamburg terminals upgrade these systems in parallel with shore power electrification under EU Green Deal mandates.
Detection Systems leads volumes today; Biometric Systems is gaining share fastest.
Service Type:
Procurement patterns split between upfront capital expenditure on implementation and operational expenditure shifting toward outsourced monitoring.
- Managed Services:Twenty-four-hour monitoring, threat alert response, and system health diagnostics delivered under outcome-based contracts. Port operators in the United Kingdom now outsource security operations center functions rather than maintaining in-house teams, compressing vendor negotiation cycles toward enterprise frameworks.
- Implementation:Hardware installation, software configuration, and network integration for new screening infrastructure. Vietnam's Lach Huyen deep-water port expansion offers clean-slate deployment without legacy system burden.
- Consulting:Risk assessment, compliance gap analysis, and security architecture design preceding procurement. FAA, EASA, and CAAC certification fragmentation drives demand for multi-jurisdiction guidance.
- Training:Operator certification, maintenance technician instruction, and emergency response drills. EU AI Act audit trail requirements now mandate documented staff competency for automated screening oversight.
Implementation captures the largest contract values currently; Managed Services shows the steepest expansion trajectory.
Application:
Application segments map directly to threat vector priorities, with passenger and cargo flows demanding divergent detection sensitivities.
- Passenger Screening:Walk-through millimeter-wave portals, biometric identity verification, and carry-on baggage X-ray systems. Dubai and Singapore airports are replacing metal detectors with non-metallic threat detection units.
- Cargo Screening:Large-scale X-ray and gamma-ray inspection for containerized and bulk freight. Saudi Arabia's Red Sea Project deploys trailer-mounted modular scanners for seasonal pilgrimage traffic surges.
- Perimeter Security:Fence-mounted sensors, radar arrays, and thermal cameras protecting terminal boundaries. Israeli manufacturers are recalibrating production capacity for Mediterranean and Gulf port authority orders.
- Threat Detection:AI-enhanced video analytics and behavioral recognition algorithms identifying anomalies in real-time. Edge inference architectures reduce backhaul bandwidth requirements for maritime bandwidth-constrained environments.
Passenger Screening leads volumes today; Cargo Screening is gaining share fastest.
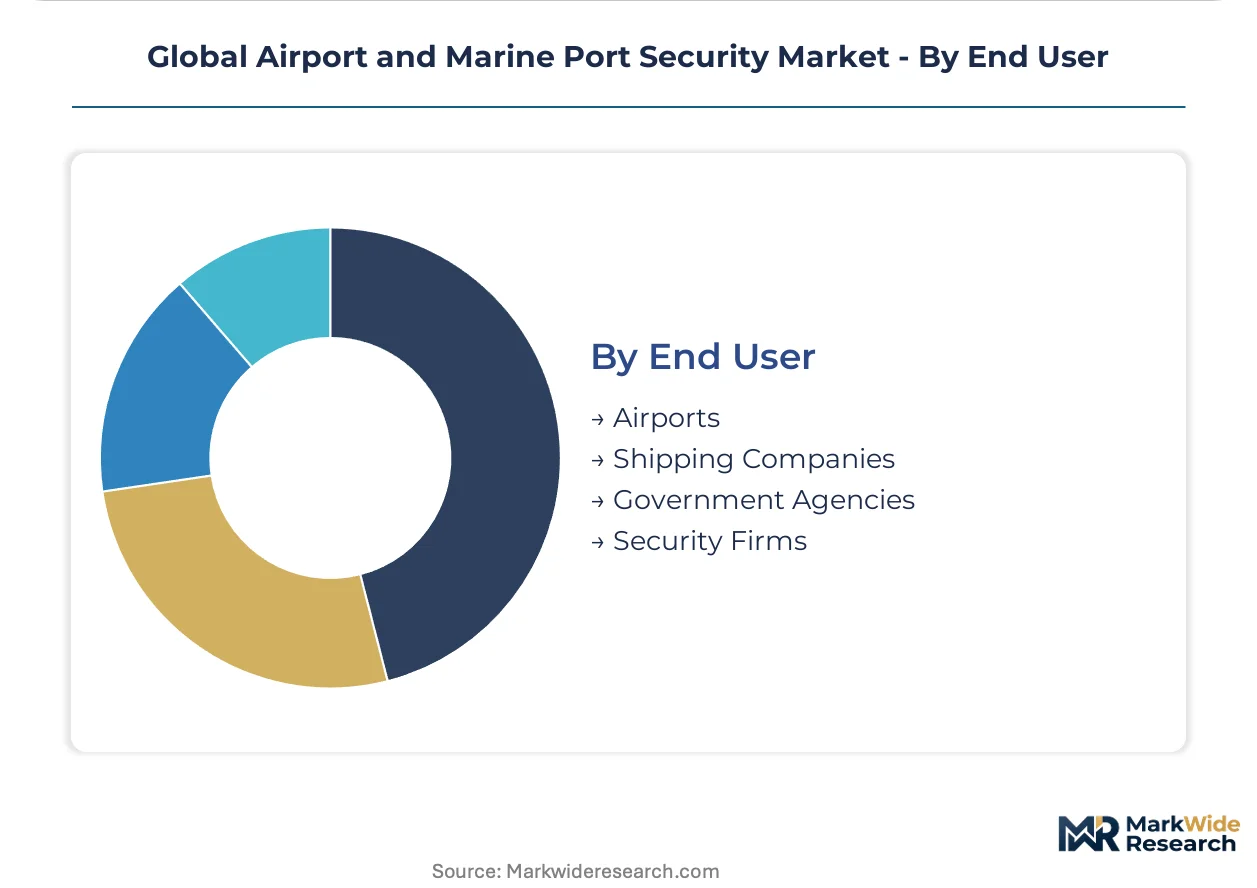
End User:
End user concentration reflects whether procurement authority sits with infrastructure owners, vessel operators, or sovereign regulators.
- Airports:Terminal operators and aviation authorities procuring integrated passenger and baggage screening. French and German operators now demand explainable AI modules with human-interpretable confidence scores.
- Government Agencies:Customs, border control, and national security directorates setting certification standards and funding infrastructure. The United States, United Kingdom, and Singapore are expanding integrated screening procurement.
- Shipping Companies:Container lines and bulk operators securing vessel access and cargo integrity. DP World and PSA International negotiate enterprise security frameworks across multiple terminal locations.
- Security Firms:Specialist contractors delivering outsourced monitoring and rapid response services. Buyer consolidation among mega-port operators is unbundling after-sales service contracts from initial equipment procurement.
Airports lead volumes today; Government Agencies is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is shifting procurement toward jurisdictions with harmonized certification standards, as vendors seek to minimize multi-jurisdiction approval costs. The United States, Germany, Singapore, United Arab Emirates, and Japan concentrate demand through distinct compliance frameworks and infrastructure investment cycles.
United States
FAA mandates under federal aviation law drive integrated screening infrastructure procurement at Atlanta Hartsfield-Jackson and Los Angeles International. The Infrastructure Investment and Jobs Act channels funding toward port electrification and parallel security upgrades along the Eastern Seaboard. Miami and Long Beach terminals require fiber backhaul replacement before supporting 4K video analytics at full frame rates.
Germany
EU Green Deal port electrification requirements accelerate security system overhauls at Hamburg and Rotterdam terminals monitoring electrified cargo zones. The EU AI Act constrains automated passenger screening algorithms, forcing human-in-the-loop review protocols at Frankfurt and Munich airports. Bavaria-based manufacturers supply explainable AI modules with human-interpretable confidence scores to meet audit trail requirements.
Singapore
Maritime and Port Authority security codes serve as reference standards for regional procurement templates across Southeast Asia. Changi Airport operators deploy walk-through millimeter-wave units eliminating passenger divestment while capturing non-metallic threats. The Tuas terminal expansion mandates autonomous underwater vehicle integration for hull inspection protocols.
United Arab Emirates
Dubai International and Abu Dhabi airports replace metal detectors with millimeter-wave scanners detecting non-metallic threats without passenger divestment. Federal transport authority regulations align procurement with EU and US certification standards to attract transshipment traffic. Jebel Ali port modernization incorporates trailer-mounted modular scanners for seasonal capacity surges.
Japan
METI standards harmonize airport security equipment certification with ICAO guidelines, reducing vendor fragmentation. Tokyo Narita and Haneda terminals prioritize biometric border management systems integrating facial recognition gates. Osaka Kansai marine terminal operators adopt digital twin simulation platforms for threat scenario modeling before hardware procurement.
Global Airport and Marine Port Security Market Vendor Landscape
European producers anchor the integrated systems tier; Israeli specialists hold perimeter detection and command-and-control software positions. The vendor base stratifies across three layers: diversified industrial conglomerates delivering end-to-end platforms, security-focused mid-caps concentrating on detection hardware, and software specialists monetizing recurring analytics subscriptions. Consolidation pressure intensifies as mega-port operators negotiate enterprise frameworks across multiple terminal locations. Dominant competitive moves include outcome-based managed service contracting and digital twin simulation anchoring hardware procurement decisions.
Within the diversified systems tier, Thales Group and Siemens AG exemplify platform providers leveraging command-and-control heritage and digital twin capabilities respectively. Thales occupies a position anchoring large-scale airport security integration contracts through software-centric delivery models. Siemens sits within the infrastructure simulation segment, modeling threat scenarios prior to physical deployment. Israeli perimeter detection manufacturers represent a distinct specialization cluster recalibrating production capacity for Mediterranean and Gulf port authority demand surges.
| Leading Market Players |
|---|
| Thales Group |
| Siemens AG |
| Honeywell International Inc. |
| Saab AB |
| Raytheon Technologies Corporation |
| Bosch Security Systems Inc. |
| Smiths Detection Group Ltd. |
| Motorola Solutions Inc. |
| FLIR Systems Inc. |
| Others |
Supply Flow & Price Mechanics
EU Green Deal port electrification mandates gate qualified supply and premium-tier pricing access, as terminals in Rotterdam and Hamburg must certify shore power-compatible security systems before procurement eligibility. This environmental compliance layer separates vendors with certified electrification-ready portfolios from commodity equipment suppliers, compressing margins at the standard tier while sustaining premium pricing for integrated platforms.
Pricing Analysis
Distributor margins in the 15-25% range separate OEM-direct contracting from systems integrator channels serving mid-tier port authorities. Three-tier pricing structure across premium, standard, and economy levels tracks certification grade and after-sales service bundling, with FAA- and EASA-certified millimeter-wave scanners commanding substantial premiums over uncertified alternatives. Cost compression in the standard tier intensifies because buyer consolidation among mega-port operators unbundles service contracts from hardware procurement. Government agencies exhibit lowest price sensitivity due to regulatory compliance mandates, while independent marine terminal operators in emerging markets demonstrate highest sensitivity to upfront capital expenditure.
Supply Chain Analysis
Single-source vulnerability sits with Taiwanese foundries for FPGA chips powering real-time video analytics at 30-60 frames per second. Manufacturing concentrates in Germany, Israel, and the United States for perimeter detection systems, millimeter-wave scanner arrays, and command-and-control software platforms respectively. Raw material dependencies include gallium arsenide for millimeter-wave sensors, rare earth elements for magnet assemblies, and specialized optical glass for surveillance lenses. Tariff exposure on semiconductor components from East Asian suppliers threatens margin stability for AI-enhanced screening gate manufacturers. Distribution runs through authorized systems integrators anchoring large-scale airport contracts and direct OEM relationships for government procurement frameworks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder, where successive mandates from the EU AI Act, FAA federal aviation law, and Singapore MPA security codes generate replacement demand regardless of macroeconomic cycles.
For Market Incumbents: Deepen software-centric delivery models to capture recurring revenue from managed security services, as port operators in the United Kingdom and Singapore outsource 24/7 monitoring functions. Anchor hardware procurement decisions through digital twin simulation capabilities that model threat scenarios before physical deployment, defending against margin erosion from standalone detection equipment commoditization. Invest in multi-jurisdiction certification infrastructure to accelerate FAA, EASA, and CAAC approvals for millimeter-wave scanners.
For New Entrants and Emerging Players: Begin with biometric system modules for greenfield port expansions in Vietnam's Lach Huyen deep-water terminal and Indonesia's Patimban port, where legacy integration burden is absent. Target outcome-based managed service contracts rather than capital equipment sales, as procurement patterns shift toward operational expenditure. Pursue partnerships with Israeli perimeter detection specialists to access Mediterranean and Gulf port authority demand surges without building full-stack capabilities.
For Investors and Strategic Acquirers: Roll-up economics work for mid-cap security software specialists because buyer consolidation among DP World and PSA International compresses vendor negotiation cycles toward enterprise frameworks. Five-to-ten year viability hinges on recurring revenue exposure from SaaS-anchored command-and-control platforms rather than transactional equipment sales. Monitor FPGA chip allocation bottlenecks from Taiwanese foundries as an inflection indicator for AI-enhanced screening gate supply constraints.
| Strategic Initiative | Industry Significance |
|---|---|
| Digital Twin Platform Deployment | Siemens AG and Thales Group anchor contracts by modeling threat scenarios before hardware procurement. |
| Managed Security Service Outsourcing | Port operators in the United Kingdom shift 24/7 monitoring to specialist firms, compressing vendor negotiation cycles. |
| Multi-Jurisdiction Certification Investment | Equipment vendors must secure separate FAA, EASA, and CAAC approvals for millimeter-wave scanner deployments. |
| Biometric-Border System Integration | Vietnam's Lach Huyen expansion offers clean-slate deployment without legacy system integration burden. |
| Edge AI Inference Architecture | Network-edge processing reduces backhaul bandwidth requirements for maritime bandwidth-constrained environments. |
Methodological Framework
Direct dialogue with airport security directors, marine port authority procurement officers, systems integrator technical leads, and biometric system engineering heads grounded qualitative findings in operational reality. Secondary validation drew from FAA certification databases, EU AI Act regulatory filings, Singapore MPA security code documentation, and customs trade records for screening equipment imports. Bottom-up demand modeling across terminal-level procurement pipelines triangulated against top-down infrastructure investment forecasts from government budget disclosures.
Segmented outputs across the analysis window reflect technology layer, service type, application vector, and end-user concentration dimensions, with additional granularity for regulatory framework clusters affecting certification timelines. CAGRs were derived from installed base growth rates, replacement cycle acceleration, and greenfield expansion pipelines rather than extrapolated trend lines. Industry-specific forecast inputs included autonomous underwater vehicle integration mandates at Gulf of Aden transshipment hubs and millimeter-wave scanner deployment schedules at Dubai and Singapore airports.
Several conditions sit outside the modeled scope, including sudden regulatory reversals, semiconductor supply disruptions beyond current allocation bottlenecks, and cyber-physical system ransomware events affecting operational technology networks. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Critical Infrastructure Protection
Smart Sandbag Market
Critical Infrastructure Protection
GCC Protective Relay Market
Critical Infrastructure Protection
Global Threat Intelligence Platform Market
Critical Infrastructure Protection
Latin America Public Infrastructure Safety Market
Critical Infrastructure Protection
Critical Infrastructure Monitoring Market
Critical Infrastructure Protection
Middle East and Africa Public Infrastructure Safety Market
Critical Infrastructure Protection
Global Railway Platform Security Market
Critical Infrastructure Protection
Europe Tank Protection Market
Critical Infrastructure Protection
Middle East and Africa Pipeline Security Market
Critical Infrastructure Protection
Perimeter Defense System Market
Critical Infrastructure Protection
North America Public Infrastructure Safety Market
Critical Infrastructure Protection
Tank Protection Market
Critical Infrastructure Protection
Europe Pipeline Security Market
Critical Infrastructure Protection
Utilities Security Market
Critical Infrastructure Protection
Asia-Pacific High-Integrity Pressure Protection System (HIPPS) Market
Critical Infrastructure Protection
Guardrail Protection System Market