
 Counter Terror and Public Safety Technology Market | 2026-2036
Counter Terror and Public Safety Technology Market Size, Share, and Industry Trends Forecast 2026-2036
Counter Terror and Public Safety Technology Market Analysis
Modular threat-detection kits is broadening buyer choice across municipal and federal agencies. Thales Group leverages its command-and-control integration heritage to anchor large-scale European infrastructure contracts. Raytheon Technologies Corporation sustains dominance in layered defense architectures through classified sensor fusion programs. Motorola Solutions Inc specializes in portable encrypted communications for first responders, occupying a defensible niche in urban emergency networks.
Counter terror and public safety technology encompasses integrated hardware-software systems for threat identification, perimeter security, and crisis coordination, typically operating across RF spectra, thermal imaging bands, and encrypted data networks with sub-second latency requirements. Its primary purpose is to prevent, detect, and neutralize asymmetric threats while enabling interoperable response across fragmented agency jurisdictions. Surveillance Systems leads technology type revenue due to persistent upgrades in video analytics and drone-mounted monitoring platforms. Threat Detection registers the fastest expansion as hyperspectral imaging and chemical-biological sensors penetrate airport and mass-transit nodes. System Integration captures disproportionate margin pools within service type, since legacy infrastructure retrofit demands bespoke architectural design rather than commodity hardware.
The EU AI Act and GDPR constrain biometric surveillance deployment across European public spaces, forcing vendors to engineer explainable-algorithm variants with auditable decision trails. The FAA and FCC jointly regulate drone-based surveillance and dedicated public-safety spectrum allocations in the United States, shaping product certification timelines and channel access protocols. India's BIS mandates equipment testing for critical infrastructure protection systems, adding compliance layers for foreign suppliers. Stakeholders must monitor evolving encryption export controls and AI liability frameworks as procurement criteria shift from technical specifications to governance-ready platform assurances.
Market Dynamics
The EU AI Act's algorithmic transparency mandates are forcing biometric surveillance vendors to rebuild detection architectures around auditable decision trails, compressing product development cycles and disqualifying black-box systems from European public procurement.
Growth Catalysts
- Smart city security mandates:India's Ministry of Home Affairs is channeling central funds into integrated command-and-control centers across 100 urban agglomerations, creating bundled procurement opportunities for threat detection suites.
- EU AI Act compliance deadlines:The European Parliament's risk-classification framework for biometric identification systems is accelerating replacement cycles for legacy surveillance infrastructure in France, Germany, and Italy.
- Hyperspectral imaging maturation:Airport authorities in the United States are deploying chemical-biological sensor arrays at mass-transit nodes, expanding the addressable market for multi-spectral threat detection platforms.
Market Restraints
- Semiconductor supply concentration:Advanced FPGA and ASIC fabrication for sensor fusion processors remains concentrated in Taiwan, exposing vendors to geopolitical disruption in wafer supply.
- GDPR biometric friction:The European Data Protection Board's strict interpretation of lawful basis for facial recognition in public spaces is blocking deployment of real-time analytics in Belgian and Dutch municipal networks.
- Legacy system lock-in:Municipal police departments in the United States face sunk-cost barriers when integrating AI-enhanced platforms with decades-old CAD/RMS infrastructure.
Strategic Opportunities
- India's critical infrastructure protection:The Bureau of Indian Standards' mandatory equipment testing regime creates first-mover advantages for vendors establishing domestic certification partnerships ahead of foreign competitors.
- Drone-based perimeter surveillance:The FAA's expanded beyond-visual-line-of-sight waivers for public safety operators is opening airspace-dependent monitoring applications at energy facilities and transportation corridors.
- Encrypted mesh networks:Convergence of 5G private networks with tactical LTE is enabling interoperable first-responder communications in subterranean and dense urban environments where legacy radio fails.
Industry Challenges
- AI explainability engineering:Vendors lack sufficient machine learning operations talent capable of building interpretable neural architectures that satisfy European conformity assessment requirements.
- Cross-agency certification fragmentation:Equipment must simultaneously meet FCC spectrum rules, FAA airworthiness standards, and state-level encryption export controls, extending time-to-revenue by 14-22 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Counter Terror and Public Safety Technology Market |
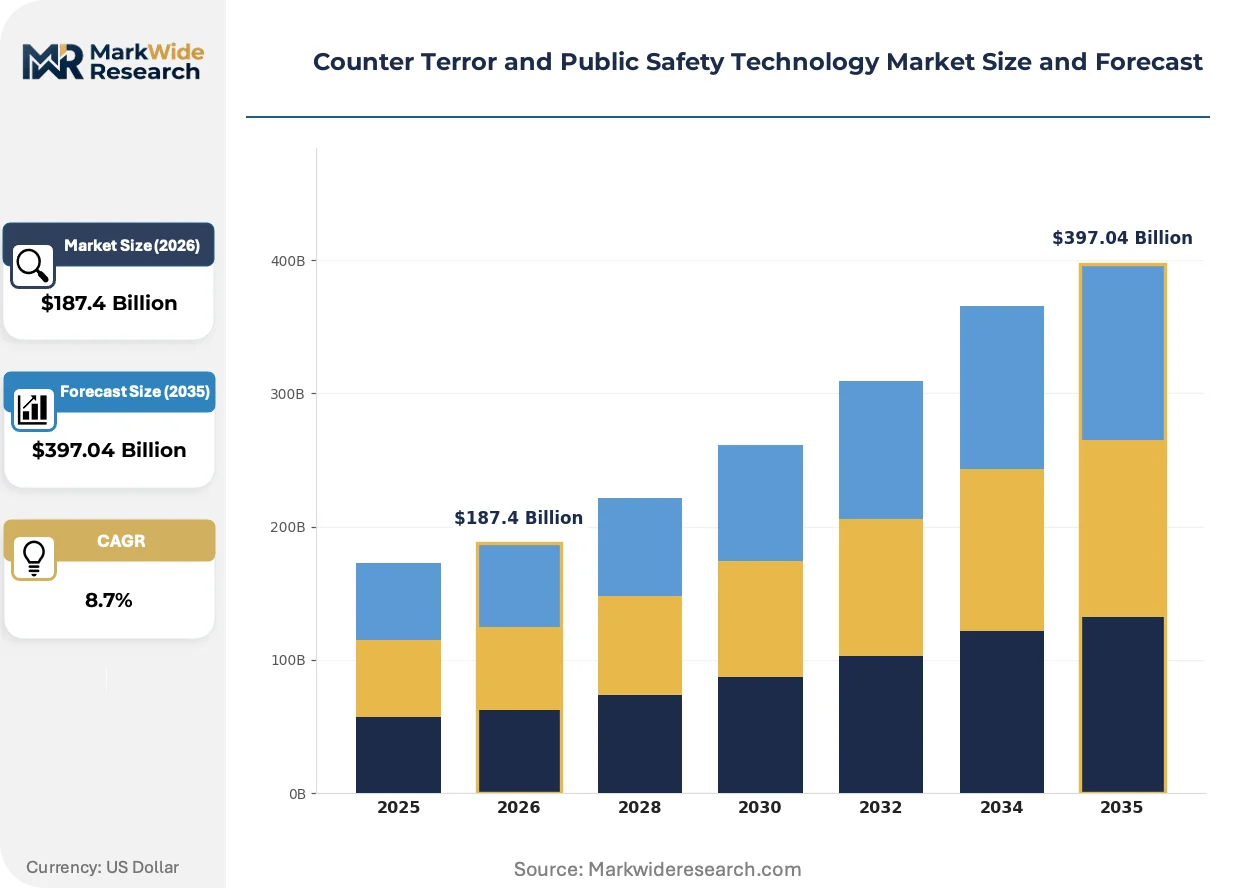
| Market Size in 2026 | $187.4 Billion |
| Market Size in 2035 | $397.04 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology Type: Surveillance Systems, Access Control, Threat Detection, Communication Systems End User: Law Enforcement, Military, Private Security, Public Safety Organizations Application Area: Border Security, Event Security, Critical Infrastructure Protection, Emergency Response Service Type: Consultation, System Integration, Maintenance, Training |
| Companies Covered | Thales Group, Honeywell International Inc, Lockheed Martin Corporation, Raytheon Technologies Corporation, BAE Systems, Northrop Grumman Corporation, Motorola Solutions Inc, General Dynamics Corporation, Palantir Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Counter Terror and Public Safety Technology Market Emerging Trajectories
Edge computing architectures are redistributing processing load from centralized data centers to sensor nodes, enabling sub-second threat classification while reducing bandwidth costs and jurisdictional data sovereignty risks.
Hyperspectral imaging is converging with machine learning inference at the network edge, allowing chemical signature detection without cloud round-trips. Mass-transit authorities in Singapore and the United Arab Emirates are piloting these fused systems at airport terminals and metro interchanges. The compression of detection-to-alert latency from seconds to milliseconds is forcing legacy video-analytics vendors to rearchitect around GPU-accelerated edge hardware.
The EU AI Act's high-risk system classification is mandating human-in-the-loop overrides for biometric identification in publicly accessible spaces. Vendors serving European police forces must now engineer real-time operator intervention capabilities that interrupt automated detention triggers. German and French interior ministries are rewriting technical specifications to require conformity assessment by notified bodies before contract award.
Municipal procurement departments are consolidating vendor relationships around platform-as-a-service contracts that bundle hardware, software, and maintenance into per-camera or per-sensor monthly fees. This consumption-based model displaces capital-intensive upfront purchases that strained city budget cycles. California and Texas municipal agencies are leading this transition, with Los Angeles and Houston police departments restructuring five-year agreements around operational expenditure frameworks.
Counter Terror and Public Safety Technology Market Segmentation
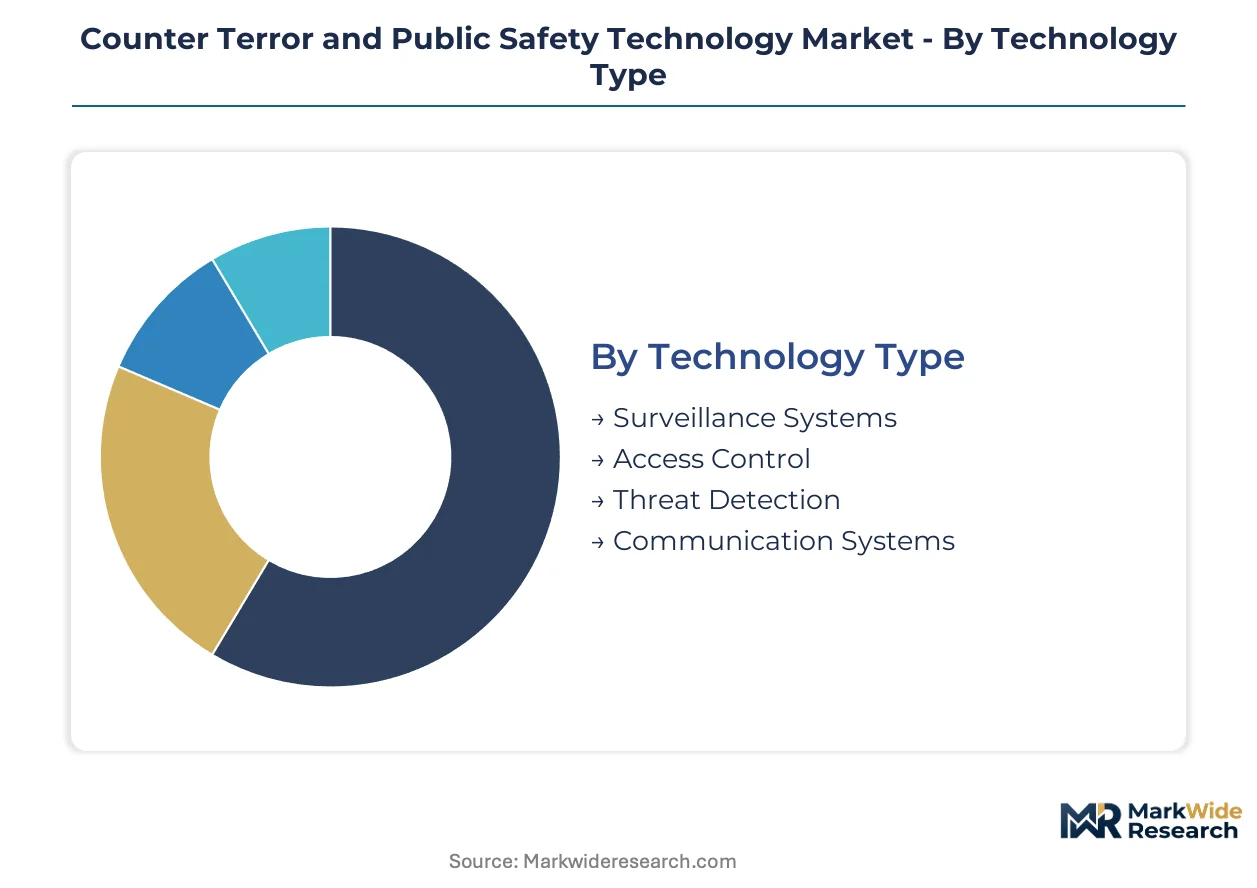
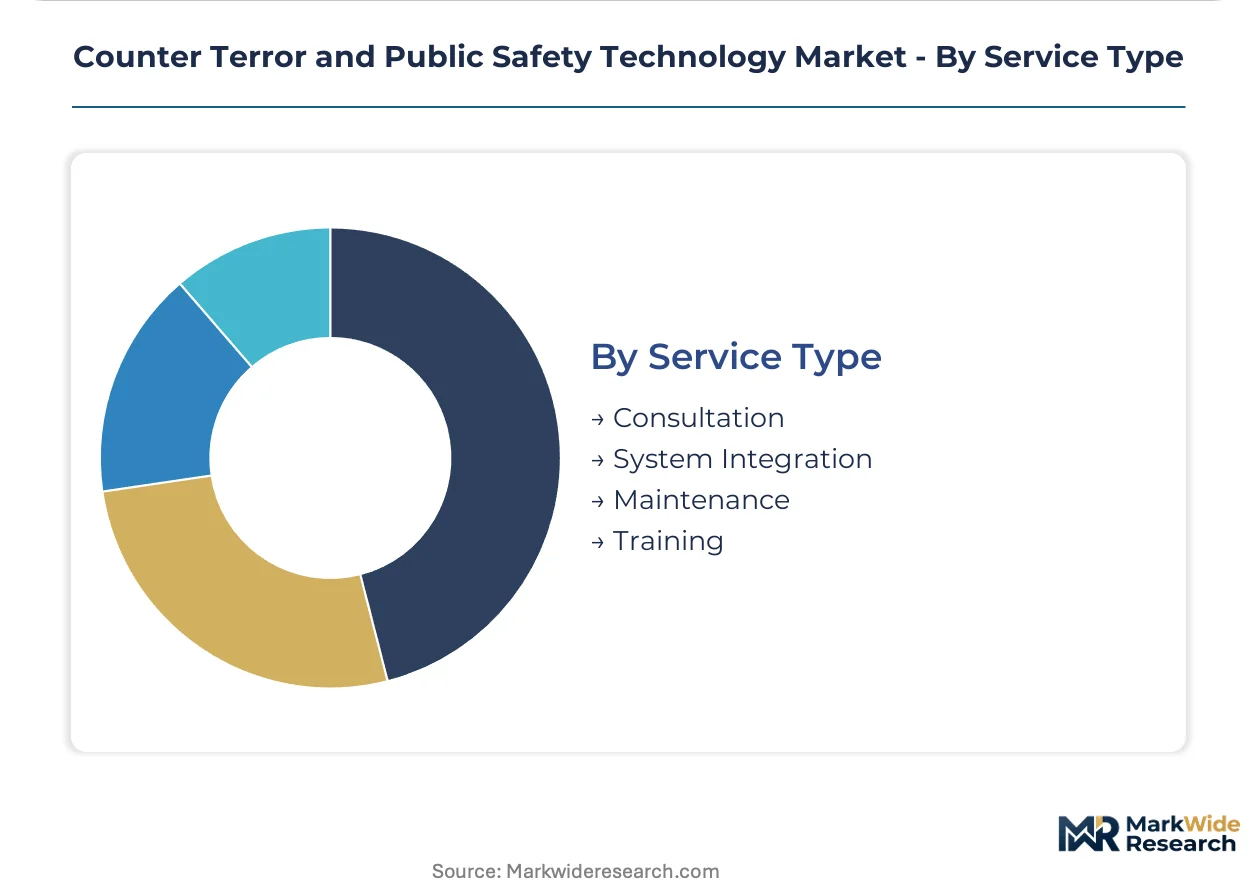
Counter terror and public safety technology procurement fragments across incompatible agency workflows, legacy infrastructure vintages, and divergent regulatory exposure profiles. Vendors must architect modular product lines that bridge these divides without sacrificing certification velocity or margin structure.
Technology Type:
Supply concentration in sensor fusion processors and encrypted RF components shapes vendor positioning across hardware categories.
- Surveillance Systems:Integrated video analytics platforms combining thermal imaging, drone-mounted optics, and edge AI inference engines. Demand concentrates in India's smart city command centers and US municipal police departments upgrading from analog CCTV networks, constrained by EU AI Act transparency mandates for biometric analytics.
- Threat Detection:Hyperspectral imaging arrays and chemical-biological sensor nodes operating at mass-transit chokepoints. Airport authorities in the United States and Singapore are deploying these at passenger screening zones, driven by sub-second detection latency requirements and FAA spectrum coordination for drone-mounted variants.
- Access Control:Biometric authentication gates and perimeter breach detection for critical infrastructure facilities.
- Communication Systems:Encrypted mesh networks and tactical LTE platforms enabling interoperable first-responder coordination.
Today's leader: Surveillance Systems. Tomorrow's challenger: Threat Detection.
End User:
Customer procurement authority determines contract structure, with federal agencies favoring platform-as-a-service frameworks while municipal buyers retain capital expenditure models.
- Law Enforcement:Municipal police departments and federal investigative agencies requiring portable encrypted communications and real-time biometric identification. Procurement in France and Germany accelerates under EU AI Act replacement cycles for non-compliant legacy surveillance, while Indian agencies bundle purchases through Ministry of Home Affairs central funding.
- Military:Classified sensor fusion programs and layered defense architectures operating across contested electromagnetic environments. Layered defense requirements in the United States sustain demand for RF spectrum dominance and counter-drone systems, subject to FCC and FAA joint certification timelines.
- Private Security:Corporate campus protection and event venue perimeter control for commercial clients.
- Public Safety Organizations:Fire departments, emergency medical services, and disaster response coordinators requiring interoperable crisis coordination platforms.
Law Enforcement commands current procurement volume. Military contracts deliver the steepest expansion trajectory.
Application Area:
Regulatory jurisdiction density varies sharply across deployment contexts, with border zones facing multi-agency oversight and event security operating under temporary waivers.
- Border Security:Perimeter surveillance arrays, drone patrol corridors, and biometric entry-exit systems at land and maritime frontiers. US Customs and Border Protection expands procurement of beyond-visual-line-of-sight drone platforms under FAA waiver programs, while India's Bureau of Indian Standards mandates equipment testing for foreign suppliers.
- Critical Infrastructure Protection:Energy facilities, transportation nodes, and telecommunications hubs requiring hardened access control. European operators navigate GDPR biometric friction and EDPB strictures on facial recognition in publicly accessible spaces.
- Event Security:Temporary surveillance deployments and crowd analytics for stadium and convention center environments.
- Emergency Response:Mobile command centers and interoperable communications for disaster coordination.
Critical Infrastructure Protection anchors replacement spending. Border Security is gaining share fastest.
Service Type:
Margin pools concentrate in architectural design capabilities rather than commodity hardware, as legacy infrastructure retrofit demands bespoke integration.
- System Integration:Custom architectural design binding legacy CAD/RMS infrastructure with AI-enhanced platforms. Municipal police departments in the United States face sunk-cost barriers that extend engagement duration, while European conformity assessment requirements under EU AI Act add certification layers.
- Consultation:Threat assessment, compliance advisory, and procurement specification drafting for agency buyers.
- Maintenance:Firmware updates, sensor calibration, and encryption key rotation across deployed hardware networks.
- Training:Operator certification for human-in-the-loop override systems mandated by EU AI Act high-risk classifications.
System Integration captures disproportionate margin. Training services are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The counter terror and public safety technology industry traces its modern scale to post-2001 security infrastructure buildouts in the United States and subsequent NATO alliance standardization programs. Defense procurement networks in North America and Europe established the foundational vendor ecosystems and certification protocols that now govern global equipment interoperability. Today, demand fragmentation across regulatory jurisdictions shapes distinct national market structures.
United States
Municipal police departments in Los Angeles and Houston are restructuring procurement around platform-as-a-service contracts with per-sensor monthly fees. The FAA and FCC jointly regulate drone-based surveillance and dedicated public-safety spectrum allocations, extending product certification timelines. The Department of Homeland Security channels funds through the Urban Areas Security Initiative, concentrating deployment in New York, Chicago, and Houston metropolitan corridors.
India
The Ministry of Home Affairs is directing central funds into integrated command-and-control centers across 100 urban agglomerations including Delhi, Mumbai, and Bangalore. The Bureau of Indian Standards mandates equipment testing for critical infrastructure protection systems, adding compliance layers for foreign suppliers. Smart city security modernization programs in Gujarat and Maharashtra are creating bundled procurement opportunities for threat detection suites.
Germany
Federal and state interior ministries are accelerating replacement cycles for legacy surveillance infrastructure under EU AI Act compliance deadlines. The Federal Office for Information Security enforces encryption standards for first-responder communications networks. Industrial clusters in Bavaria and Baden-Württemberg host system integration specialists serving European critical infrastructure operators.
France
The National Commission on Informatics and Liberty enforces strict biometric surveillance limitations in publicly accessible spaces under GDPR interpretations. The Ministry of the Interior is rewriting technical specifications to require EU AI Act conformity assessment by notified bodies before contract award. Paris and Lyon metropolitan police commands are piloting human-in-the-loop override systems for automated threat detection.
Singapore
Mass-transit authorities are deploying hyperspectral imaging arrays with machine learning inference at Changi Airport and metro interchanges. The Infocomm Media Development Authority coordinates 5G private network allocations for encrypted mesh first-responder communications. The city-state's Smart Nation initiative is concentrating pilot programs for edge-computing threat classification in the central business district.
Counter Terror and Public Safety Technology Market Vendor Landscape
Premium-margin players sit above commodity-margin players across system integration and classified defense programs, while hardware fabricators compete on volume and certification velocity. The vendor base clusters around three strategic archetypes: diversified aerospace-defense conglomerates with classified sensor fusion capabilities, communications specialists with encrypted RF heritage, and data analytics platforms with government intelligence relationships. Competitive dynamics center on M&A activity targeting niche sensor technologies and strategic partnerships for AI explainability engineering talent.
Among diversified aerospace-defense conglomerates, Thales Group and Raytheon Technologies Corporation exemplify the integrated platform archetype, anchoring large-scale infrastructure and layered defense contracts respectively. Motorola Solutions Inc occupies a distinct position in portable encrypted communications for urban emergency networks. These three entities represent the tiered competitive structure: Thales leverages European command-and-control integration heritage, Raytheon sustains dominance through classified programs, and Motorola defends a defensible niche in first-responder interoperability.
| Leading Market Players |
|---|
| Thales Group |
| Honeywell International Inc |
| Lockheed Martin Corporation |
| Raytheon Technologies Corporation |
| BAE Systems |
| Northrop Grumman Corporation |
| Motorola Solutions Inc |
| General Dynamics Corporation |
| Palantir Technologies |
| Others |
Supply Flow & Price Mechanics
FPGA wafer pricing indices from Taiwan Semiconductor Manufacturing Company cascade through three distinct pricing tiers for sensor fusion processors, compressing margins on commoditized threat detection hardware while amplifying premiums for EU AI Act-certified systems with auditable algorithmic trails.
Pricing Analysis
Platform-as-a-service contracts with per-sensor monthly fees now dominate municipal procurement in Los Angeles and Houston, displacing capital-intensive upfront purchases. Price differentiation hinges on EU AI Act conformity assessment tier and encryption certification grade under FCC rules. Cost compression in standard surveillance hardware is intensifying because Indian smart city programs are consolidating bundled vendor relationships. Municipal police departments exhibit highest price sensitivity, while federal layered defense programs show least.
Supply Chain Analysis
Single-source vulnerability sits with Taiwan for advanced FPGA and ASIC fabrication, South Korea for high-bandwidth memory modules, and the United States for classified sensor fusion intellectual property. Raw material dependencies include gallium arsenide substrates, rare earth magnets for drone motors, and specialized optical glass for hyperspectral lenses. Tariff exposure runs through Bureau of Indian Standards mandatory testing requirements for foreign suppliers. Distribution runs through system integration specialists serving fragmented agency procurement workflows.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market offers margin expansion through the shift from commodity hardware to governance-ready platform-as-a-service bundles, as EU AI Act compliance requirements disqualify black-box systems and concentrate procurement among certified vendors.
For Market Incumbents: To counter emerging AI explainability engineering talent scarcity, Thales Group and Raytheon Technologies Corporation should deepen backward integration into edge computing hardware design while accelerating conformity assessment partnerships with European notified bodies. Certification velocity in France and Germany interior ministry procurement cycles represents the critical defensive lever. For New Entrants and Emerging Players: Mid-tier Indian municipal corporations outside Delhi and Mumbai present the most penetrable buyer archetype, as Ministry of Home Affairs central funding creates bundled procurement opportunities without legacy CAD/RMS lock-in. A drone-based perimeter surveillance specialization aligned with FAA beyond-visual-line-of-sight waiver pathways offers the strongest go-to-market angle. For Investors and Strategic Acquirers: Consolidation pressure builds where AI explainability engineering capabilities concentrate among boutique machine learning operations firms serving European conformity assessment requirements. Long-term viability favors platform-as-a-service vendors with recurring revenue visibility over hardware fabricators exposed to FPGA price volatility. The signal to watch is Indian Bureau of Indian Standards domestic certification partnership announcements as first-mover inflection indicators.| Strategic Initiative | Industry Significance |
|---|---|
| AI Explainability Engineering Acquisition | Secures EU AI Act conformity assessment capabilities for European public procurement eligibility. |
| Indian BIS Certification Partnership | Establishes first-mover compliance pathway for Ministry of Home Affairs smart city command center contracts. |
| Platform-as-a-Service Transition | Converts municipal police department capital expenditure constraints into recurring revenue streams. |
| Edge Computing Hardware Integration | Reduces FPGA dependency while enabling sub-second threat classification at sensor nodes. |
| Drone BVLOS Regulatory Engagement | Unlocks airspace-dependent monitoring applications at US energy facilities and transportation corridors. |
Methodological Framework
Direct dialogue with municipal police procurement officers, federal homeland security program managers, system integration specialists, and drone surveillance operators combined with secondary validation against FAA waiver databases, EU AI Act implementation guidance, Bureau of Indian Standards equipment testing protocols, and SEC 10-K filings from diversified aerospace-defense conglomerates. Bottom-up deployment data triangulated against top-down ministry budget allocations.
Segment-level value outputs across technology type, end user, application area, and service type dimensions were modeled over the projection horizon, with CAGRs derived from historical procurement cycle analysis and forward-looking regulatory compliance deadline impacts. Forecast inputs incorporated EU AI Act replacement cycle acceleration, Indian smart city security modernization program phasing, and hyperspectral imaging maturation curves at US airport authorities.
Underlying measurement precision varies by segment; surveillance systems and threat detection carry tighter precision than communication systems due to more transparent procurement documentation. Forecasts reflect documented assumptions about regulatory implementation timelines and technology adoption curves. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Public Safety
US Mass Notification Systems Market
Public Safety
Public Safety in-Building Wireless Distributed Antenna System (DAS) Market
Public Safety
Global Public Safety Solution Market
Public Safety
Global Public Safety and Security Market
Public Safety
Public Safety LTE Market
Public Safety
Public Safety Market
Public Safety
Europe Road Safety Market
Public Safety
Voice Evacuation Systems Market
Public Safety
Europe Wireless Broadband in Public Safety Market
Public Safety
Latin America Public Safety Market
Public Safety
Global IoT for Public Safety Market
Public Safety
Outdoor Public Safety Market
Public Safety
Crime Risk Report Market
Public Safety
North America Road Safety Market
Public Safety
Middle East Crime and Combat Market
Public Safety
Global Public Safety Analytics Market