
 Global Wireless Broadband in Public Safety Market | 2026-2036
Global Wireless Broadband in Public Safety Market Size, Share, and Industry Trends Forecast 2026-2036
Global Wireless Broadband in Public Safety Market Foresight
The EU Green Deal is expanding the mandate for energy-efficient digital infrastructure across public safety networks. Motorola Solutions Inc. anchors North American first responder broadband through its consolidated Land Mobile Radio and LTE offerings. Ericsson competes in European emergency network modernization with 3GPP-standardized mission-critical solutions. Nokia Corporation specializes in private wireless deployments for police and fire services across Nordic markets.
Wireless broadband in public safety denotes dedicated high-capacity radio networks delivering voice, video, and data services to emergency responders during critical incidents, typically operating in 700 MHz public safety bands with sub-50 millisecond latency requirements for command-and-control applications. 5G network type segments are capturing disproportionate investment as agencies demand ultra-reliable low-latency communication for drone surveillance and augmented reality incident command. Mesh networking technology leads in disaster recovery scenarios where infrastructure damage severs conventional backhaul, while beamforming concentrates margin pools in dense urban surveillance deployments requiring precise signal targeting.
The Federal Communications Commission in the United States governs spectrum allocation and interoperability standards for public safety broadband, while the European Telecommunications Standards Institute defines mission-critical service requirements under 3GPP Release specifications. China's Ministry of Industry and Information Technology mandates domestic encryption protocols for government emergency networks, shaping vendor market access conditions. Stakeholders must monitor evolving spectrum harmonization between FirstNet and European Band 68 allocations to anticipate cross-border equipment compatibility demands.
Market Dynamics
First responder agencies worldwide are consolidating fragmented Land Mobile Radio infrastructure toward unified LTE and 5G platforms, driven by bandwidth demands for real-time video analytics and cross-jurisdictional data interoperability.
Growth Catalysts
- EU Green Deal mandates:Energy-efficiency requirements are accelerating replacement of legacy TETRA networks with lower-carbon digital infrastructure across German federal police and fire services.
- Mission-critical push-to-talk over cellular:3GPP Release specifications enable broadband voice services that match TETRA reliability while adding video and data capabilities.
- Urban drone surveillance programs:Police departments in the United States require ultra-reliable low-latency communication for aerial incident command and suspect tracking.
Market Restraints
- 700 MHz spectrum scarcity:Limited public safety band allocation in dense metropolitan areas constrains network capacity expansion for multiple simultaneous video streams.
- Equipment certification delays:FCC Part 90 rules impose lengthy authorization timelines for mission-critical devices, stretching procurement cycles to 18-24 months.
- TETRA infrastructure lock-in:European agencies face high switching costs from decades-old narrowband investments, slowing migration to broadband platforms.
Strategic Opportunities
- Mesh networking for disaster recovery:Self-healing ad-hoc architectures address infrastructure damage scenarios where conventional backhaul fails, opening rural and remote deployment markets.
- Augmented reality incident command:Overlay systems for firefighters and hazmat teams create demand for guaranteed sub-50 millisecond latency services.
- Private 5G network leasing:Neutral host models allow agencies to share infrastructure costs with utilities and transportation operators under FCC CBRS rules.
Industry Challenges
- Multi-band device engineering:Handset manufacturers must integrate TETRA, LTE, and 5G radios while maintaining battery life and thermal performance standards.
- Interoperability testing complexity:Cross-border emergency response requires harmonized encryption and authentication protocols between FirstNet and European Band 68 allocations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Wireless Broadband in Public Safety Market |
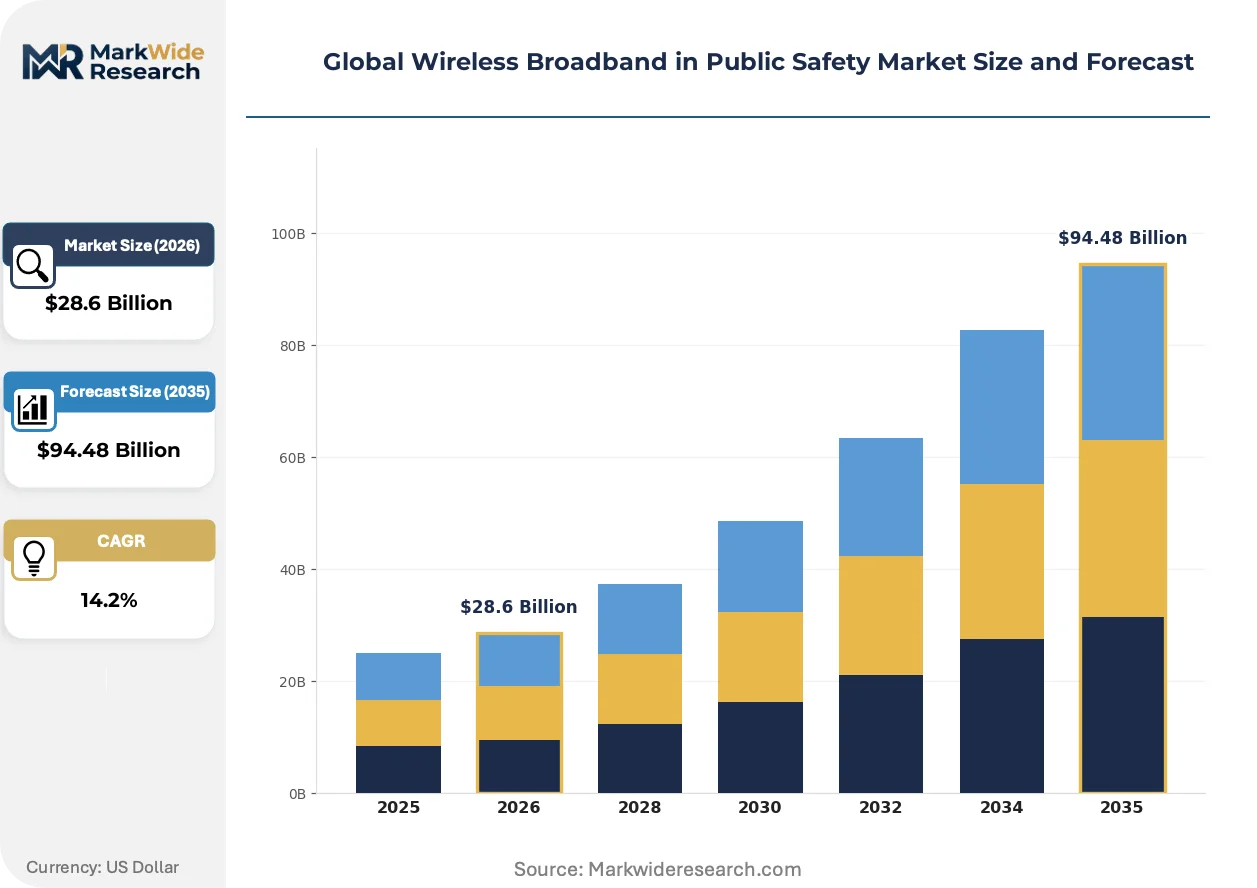
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $94.48 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Network Type: LTE, 5G, WiMAX, TETRA, Satellite Application: Emergency Response, Disaster Management, Surveillance, Incident Command Technology: Mesh Networking, MIMO, OFDM, Beamforming, Cognitive Radio End User: Police, Fire Services, Emergency Medical Services, Coast Guard |
| Companies Covered | Motorola Solutions Inc., AT&T Mobility LLC, Ericsson, Nokia Corporation, Huawei, Cisco Systems Inc., Verizon Communications Inc, Juniper Networks Inc., Aruba Networks, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Wireless Broadband in Public Safety Market Shifts & Advancements
Public safety communication architecture is pivoting from voice-centric narrowband systems to multimedia broadband platforms capable of supporting artificial intelligence-enabled analytics at the network edge.
Beamforming antenna arrays are converging with fixed wireless access deployments to deliver precise signal targeting in dense urban environments. Police departments in Chicago and Los Angeles are installing sectorized base stations that concentrate RF energy on specific incident perimeters rather than broadcasting across wide areas. This spatial concentration is converging with video analytics requirements to create premium pricing tiers for surveillance-grade connectivity.
ETSI mission-critical service standards under 3GPP Release 17 are mandating enhanced network slicing for emergency responder priority access. European member states must demonstrate compliance with these specifications to receive cohesion fund allocations for digital infrastructure. Germany and France are deploying pre-standard testbeds to validate quality-of-service guarantees before nationwide procurement.
Consolidated procurement frameworks are displacing fragmented agency-level purchasing across United States first responder networks. State-level master service agreements with single-vendor ecosystems are reducing equipment interoperability testing burdens while locking agencies into long-term technology roadmaps. California and Texas have adopted this model, consolidating hundreds of municipal contracts into unified statewide arrangements.
Global Wireless Broadband in Public Safety Market Segmentation
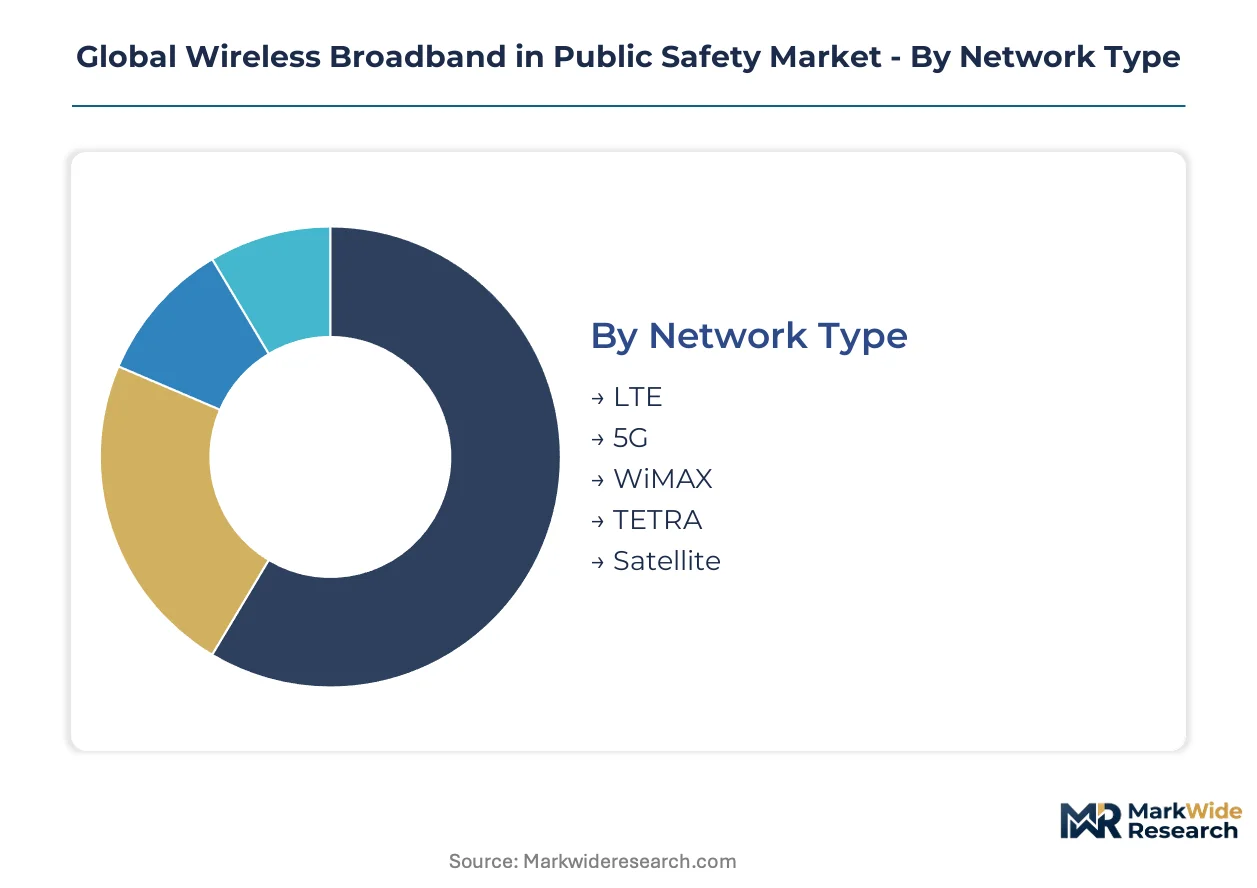
Agencies face distinct procurement calculus across network generations, application workloads, and responder disciplines. Each segmentation axis reveals where budget authority concentrates and which technical specifications dominate vendor selection criteria.
Network Type:
Legacy infrastructure replacement cycles are compressing as bandwidth requirements for real-time video overwhelm narrowband capacity limits.
- LTE:Proven 3GPP-standardized platforms deliver mission-critical push-to-talk over cellular with hardened quality-of-service guarantees. German federal police and fire services are consolidating fragmented TETRA investments toward unified LTE cores under EU Green Deal energy-efficiency mandates.
- 5G:Ultra-reliable low-latency communication enables drone surveillance and augmented reality incident command with sub-50 millisecond performance. United States police departments in Chicago and Los Angeles are deploying sectorized base stations for dense urban coverage.
- WiMAX:Fixed wireless access deployments persist in rural jurisdictions where fiber backhaul remains uneconomical.
- TETRA:Narrowband voice systems retain installed base in European agencies facing high switching costs from decades-old infrastructure investments.
- Satellite:Beyond-line-of-sight connectivity serves remote and disaster-impacted zones where terrestrial infrastructure fails.
LTE sits at the top of the volume ranking, with 5G climbing the fastest as agencies validate network slicing for guaranteed responder priority access.
Application:
Workload intensity varies sharply between routine patrol operations and catastrophic event response, driving divergent equipment specifications.
- Emergency Response:Real-time video streaming from body-worn cameras and vehicle dash units demands sustained uplink capacity. First responder agencies require guaranteed bandwidth allocation during multi-agency incidents.
- Disaster Management:Self-healing mesh architectures activate when conventional backhaul sustains damage. Rural and remote deployment markets open where infrastructure redundancy is mission-critical.
- Surveillance:Fixed and drone-mounted cameras generate continuous high-definition feeds requiring precise signal targeting through beamforming arrays.
- Incident Command:Unified communications platforms integrate voice, video, and data for multi-jurisdictional coordination under unified command structures.
Emergency Response captures the largest addressable base, while Disaster Management is gaining share fastest as climate adaptation budgets expand.
Technology:
Radio frequency engineering choices determine coverage economics and interference resilience in contested spectrum environments.
- Mesh Networking:Ad-hoc self-organizing topologies deploy rapidly where infrastructure damage severs conventional connectivity. Disaster recovery scenarios favor this architecture for operational continuity.
- MIMO:Multiple-input multiple-output arrays multiply spectral efficiency through spatial multiplexing. Dense urban deployments leverage this for capacity expansion without additional spectrum allocation.
- OFDM:Orthogonal frequency-division multiplexing provides robust performance against multipath interference in complex propagation environments.
- Beamforming:Phased antenna arrays concentrate RF energy on specific incident perimeters rather than broadcasting across wide areas. Chicago and Los Angeles police departments are installing sectorized base stations for surveillance-grade connectivity.
- Cognitive Radio:Dynamic spectrum sensing enables opportunistic access to underutilized bands during emergency declarations.
Mesh Networking leads deployment counts, with Beamforming expanding most quickly as urban surveillance programs scale.
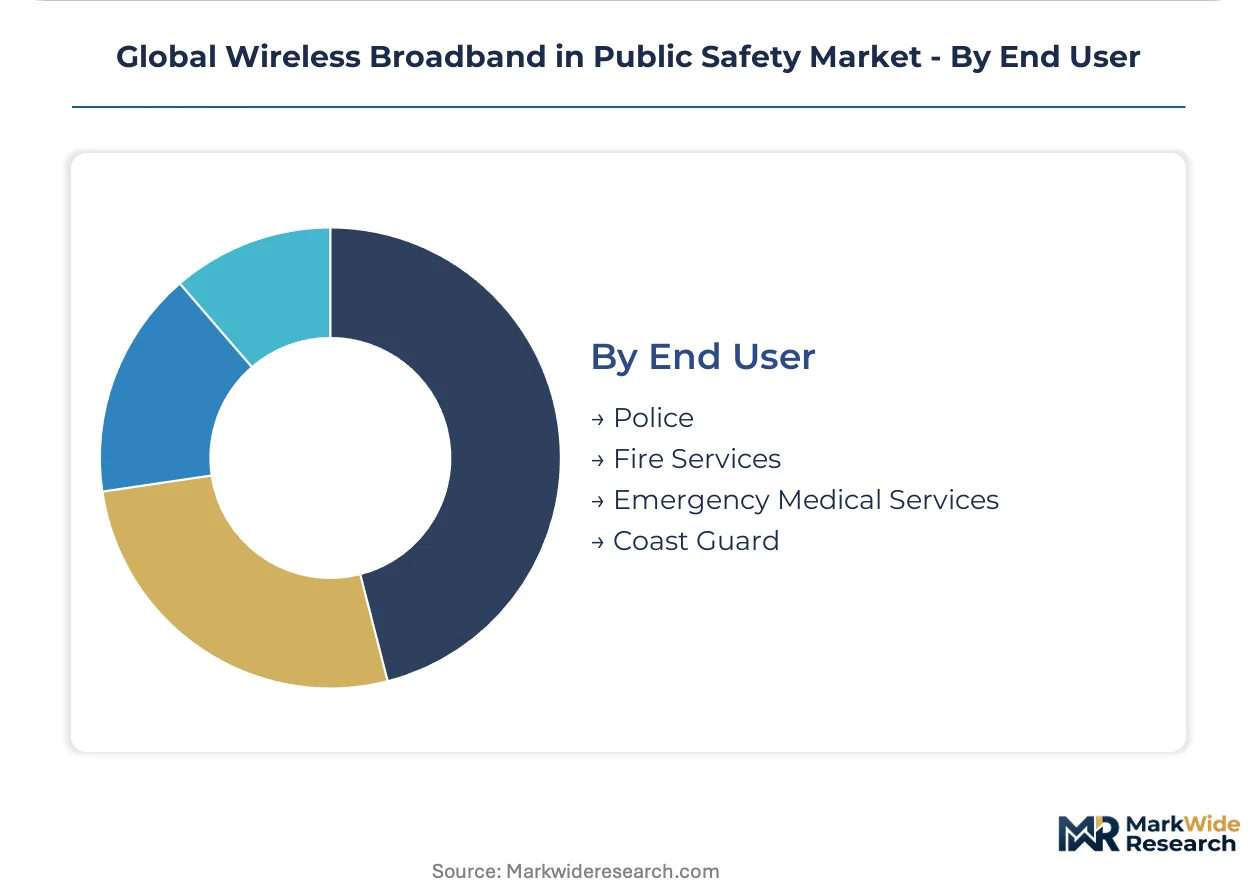
End User:
Operational requirements diverge across responder disciplines, from patrol vehicle mobility to hazardous environment survivability.
- Police:Body-worn cameras, license plate recognition, and real-time crime center integration drive sustained bandwidth demand. United States departments are consolidating procurement through statewide master service agreements.
- Fire Services:Thermal imaging, building floor plans, and personnel accountability systems require hardened devices with extreme temperature tolerance. Augmented reality overlay systems for hazmat teams create demand for guaranteed latency services.
- Emergency Medical Services:Telemetry from ambulances and telemedicine consultation with receiving hospitals prioritize reliable connectivity in high-mobility scenarios.
- Coast Guard:Maritime patrol and search operations require beyond-line-of-sight coverage through satellite integration and coastal base station networks.
Police represents the largest installed base, with Fire Services showing the steepest expansion trajectory as building safety mandates tighten.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Wireless broadband for public safety originated in the United States with the creation of FirstNet, the dedicated nationwide network for first responders that established the template for mission-critical LTE deployment.
United States
FirstNet's consolidated procurement framework has displaced fragmented agency-level purchasing across state-level master service agreements. The FCC governs 700 MHz spectrum allocation and Part 90 equipment certification rules that stretch procurement cycles to 18-24 months. Chicago and Los Angeles police departments are deploying sectorized 5G base stations with beamforming arrays for dense urban surveillance.
Germany
Federal police and fire services are consolidating legacy TETRA networks toward unified LTE cores under EU Green Deal energy-efficiency mandates for lower-carbon digital infrastructure. The national regulator enforces interoperability standards aligned with ETSI mission-critical service specifications. Bavaria hosts pre-standard testbeds validating quality-of-service guarantees before nationwide procurement.
China
The Ministry of Industry and Information Technology mandates domestic encryption protocols for government emergency networks, shaping vendor market access conditions. MIIT spectrum allocation prioritizes dedicated public safety bands within 3GPP framework compliance. Beijing-Tianjin-Hebei corridor serves as the primary testbed for integrated command-and-control broadband platforms.
United Kingdom
The Home Office oversees the Emergency Services Network program replacing Airwave TETRA with LTE-based mission-critical communications. Ofcom manages spectrum harmonization with European Band 68 allocations for cross-border equipment compatibility. London anchors deployment with metropolitan police and fire services testing augmented reality incident command systems.
France
The national security agency coordinates broadband modernization for police, gendarmerie, and fire services under 3GPP Release 17 network slicing requirements. ANFR manages spectrum allocation aligned with EU cohesion fund digital infrastructure eligibility criteria. Paris and Marseille are deploying pre-commercial 5G testbeds for drone surveillance and real-time crime center integration.
Global Wireless Broadband in Public Safety Market Competitive Landscape
Premium-margin players sit above commodity-margin players across spectrum access and mission-critical certification dimensions. The vendor base concentrates around telecommunications equipment specialists with 3GPP standardization expertise and systems integrators with first responder agency relationships. Three archetypes dominate: established radio infrastructure vendors pivoting from TETRA, carrier-led network operators with spectrum holdings, and IT networking firms layering security and analytics software. Consolidation through strategic partnerships and vertical integration into end-to-end solution stacks represent the dominant competitive vectors.
Within the infrastructure vendor tier, Motorola Solutions Inc. and Nokia Corporation occupy positions anchored to regional regulatory ecosystems—Motorola representing North American first responder broadband consolidation and Nokia exemplifying European emergency network modernization. Ericsson sits between these geographies with 3GPP-standardized mission-critical offerings. AT&T Mobility LLC anchors the carrier-operator archetype through its FirstNet contract structure.
| Leading Market Players |
|---|
| Motorola Solutions Inc. |
| AT&T Mobility LLC |
| Ericsson |
| Nokia Corporation |
| Huawei |
| Cisco Systems Inc. |
| Verizon Communications Inc |
| Juniper Networks Inc. |
| Aruba Networks |
| Others |
Supply & Pricing Matrix
Private-equity-rolled-up infrastructure specialists now dominate radio equipment manufacturing, concentrating supply capacity among three consolidated platforms that exercise pricing discipline through mission-critical certification control and long-term service bundling. This ownership pattern feeds directly into procurement economics: agencies face elevated upfront equipment costs offset by decade-long maintenance contracts that lock in recurring revenue streams for vendors.
Pricing Analysis
Three-tier pricing structure across mission-critical, business-critical, and standard commercial levels governs public safety broadband procurement, with price differentiation anchored in FCC Part 90 certification grade and guaranteed latency service-level agreements. Cost compression in the standard commercial tier is intensifying because utilities and transportation operators are entering shared infrastructure agreements under CBRS rules. Police departments exhibit the highest price sensitivity due to municipal budget constraints, while federal agencies demonstrate the least sensitivity given sovereign funding guarantees.
Supply Chain Analysis
Mission-critical device certification gates supply access, with FCC Part 90 and ETSI MCPTT approvals creating 18-24 month authorization timelines that constrain vendor entry. Manufacturing concentrates in Finland, Sweden, and the United States for base station infrastructure, while handset assembly feeds from facilities in China and Mexico. Raw material dependencies include gallium nitride semiconductors for RF power amplifiers, lithium-ion cells for portable devices, and specialized aluminum alloys for ruggedized enclosures. Single-source vulnerability in gallium nitride substrate supply presents structural risk. Distribution runs through systems integrators with first responder agency relationships rather than direct vendor sales.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play between the United States and Germany, where EU Green Deal energy-efficiency mandates accelerate replacement cycles faster than FCC certification timelines permit in North America, compressing payback periods for infrastructure investors.
For Market Incumbents: Cement market position by deepening backward integration into RF semiconductor fabrication and securing exclusive statewide master service agreements before competitors complete interoperability testing. The threat of carrier-led neutral host models under CBRS rules demands preemptive channel control through long-term service bundling. For New Entrants and Emerging Players: The premium-to-economy price gap in mission-critical handsets opens white-space opportunity in fire services thermal imaging integration and rural mesh networking deployments. Target Bavaria and Texas pre-standard testbeds for early reference accounts, then leverage proven interoperability credentials for nationwide procurement frameworks. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-tier systems integrators lacking proprietary radio infrastructure but holding sticky agency relationships. Long-term viability over a 5-10 year window rests on 3GPP Release 17 network slicing adoption velocity. Watch ETSI mission-critical service certification completion rates as the inflection signal for vendor consolidation timing.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into RF Semiconductor Fabrication | Captive supply of gallium nitride substrates insulates Motorola Solutions and Nokia Corporation from substrate shortages. |
| Statewide Master Service Agreement Consolidation | California and Texas procurement frameworks reduce interoperability testing burdens while locking competitors out. |
| ETSI MCPTT Certification Investment | Pre-standard testbed participation in Germany and France secures cohesion fund eligibility for digital infrastructure. |
| Mesh Networking Specialist Acquisition | Self-healing ad-hoc capabilities address disaster recovery scenarios where conventional backhaul fails. |
| CBRS Neutral Host Infrastructure Partnership | Shared spectrum access with utilities creates incremental revenue streams beyond dedicated public safety contracts. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with public safety procurement officers, network engineering directors at infrastructure vendors, FCC regulatory affairs specialists, and ETSI standardization committee participants with secondary validation. Secondary sources included FCC Part 90 equipment authorization databases, ETSI mission-critical service specifications, FirstNet deployment disclosures, and EU cohesion fund digital infrastructure allocations. Bottom-up equipment shipment tracking and top-down budget appropriation analysis provided triangulation across the analysis window.
Comparable-period anchoring linked projection assumptions to verified deployment trajectories from FirstNet rollout phases and German BDBOS modernization cycles. Segmentation modeling spanned network generation, responder discipline, technology architecture, and application intensity. CAGRs were derived from equipment replacement cycle compression rates and bandwidth demand elasticity for real-time video services. Forecast inputs included 3GPP Release specification adoption curves and EU Green Deal compliance deadlines.
Caveats apply where FCC spectrum reallocation decisions or ETSI standardization delays could materially shift the outlook. Forecasts reflect assumptions about TETRA-to-LTE migration velocity and 5G network slicing commercialization timelines. A model refresh is warranted upon material change in mission-critical push-to-over-cellular certification completion rates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Public Safety
Asia-Pacific Public Safety Market
Public Safety
Europe Public Infrastructure Safety Market
Public Safety
Safe City Market
Public Safety
Crime Risk Report Market
Public Safety
Public Safety Market
Public Safety
Global Public Safety Solution Market
Public Safety
Counter Terror and Public Safety Technology Market
Public Safety
Middle East Crime and Combat Market
Public Safety
Europe Public Safety Market
Public Safety
LAMEA Wireless Broadband in Public Safety Market
Public Safety
Global Public Safety Analytics Market
Public Safety
Public Safety Drones Market
Public Safety
Crowd Management System Market
Public Safety
Europe Road Safety Market
Public Safety
US Mass Notification Systems Market
Public Safety
Voice Evacuation Systems Market