
 Global Public Safety Solution Market | 2026-2036
Global Public Safety Solution Market Size, Share, and Industry Trends Forecast 2026-2036
Global Public Safety Solution Market Foresight
Project finance and long-term service leasing is narrowing the competitive field for public safety technology vendors. Motorola Solutions leverages its installed base of radio infrastructure to sustain recurring revenue from government clients. IBM Corporation anchors its position through predictive analytics platforms that integrate with legacy emergency systems. Huawei Technologies competes aggressively on communication platforms in markets where procurement budgets favor cost-optimized network builds.
Public safety solutions encompass integrated hardware and software systems designed for real-time threat detection, emergency coordination, and critical incident response, typically incorporating sub-100 millisecond latency specifications for dispatch communications. These systems serve law enforcement agencies, fire departments, and emergency medical services by unifying disparate data streams into actionable operational intelligence. Video surveillance and incident management software command the largest revenue pools, while predictive analytics represents the fastest-expanding segment as agencies deploy machine learning for crime pattern recognition. Cloud-based deployment modes are displacing on-premises installations among budget-constrained municipal buyers seeking scalable subscription models.
The Federal Communications Commission mandates interoperability standards for public safety broadband networks in the United States, while the European Union's GDPR and CE marking frameworks impose data governance and equipment certification requirements on cross-border vendors. China's MIIT enforces GB standards for encryption and network security in government procurement, creating divergent compliance pathways for multinational suppliers. Stakeholders must weigh regulatory fragmentation against the operational benefits of unified platform architectures when allocating R&D investment across geographic markets.

Market Dynamics
Municipal budget constraints are forcing procurement officers toward subscription-based cloud deployments, compressing traditional hardware sales cycles and elevating recurring revenue models as the dominant competitive battleground.
Growth Catalysts
- FirstNet Mandate:The FCC's nationwide public safety broadband network creates uniform interoperability standards that accelerate equipment refresh cycles across US emergency services.
- AI Video Analytics:Machine learning algorithms deployed on edge computing devices enable real-time threat detection without centralized processing delays.
- Urbanization Concentration:Megacity clusters in China and India generate procurement scale that justifies integrated command platform investments previously uneconomical for smaller municipalities.
Market Restraints
- Semiconductor Supply Concentration:Taiwan-based foundry capacity constraints create 18-24 month lead times for specialized radio frequency chipsets essential to dispatch hardware.
- GDPR Compliance Friction:Cross-border data transfer restrictions complicate cloud architecture design for vendors serving European police forces with international cooperation mandates.
- Legacy System Entrenchment:TETRA and P25 radio infrastructure sunk costs deter rapid migration to LTE-based alternatives despite superior bandwidth capabilities.
Strategic Opportunities
- India Smart Cities Mission:Federal funding for 100 urban centers creates concentrated demand for integrated surveillance and emergency response platforms.
- Drone-Bodycam Convergence:Aerial footage integration with officer-worn cameras enables three-dimensional incident reconstruction for court admissibility.
- EU Critical Entities Resilience Directive:Mandatory security assessments for essential service operators generate compliance-driven software procurement across member states.
Industry Challenges
- Cybersecurity Talent Scarcity:Municipal IT departments lack personnel to manage zero-trust network architectures required for connected officer devices.
- Interoperability Certification Delays:Multi-vendor testing protocols for P25 compliance extend product launch timelines by 9-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Public Safety Solution Market |
| Market Size in 2026 | $542.8 Billion |
| Market Size in 2035 | $1,150.02 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Solution Type: Emergency Response Systems, Video Surveillance, Incident Management Software, Communication Platforms, Predictive Analytics Application: Disaster Management, Crime Prevention, Traffic Monitoring, Fire Control, Search and Rescue End User: Law Enforcement Agencies, Fire Departments, Emergency Medical Services, Homeland Security, Public Safety Departments Deployment Mode: Cloud-based, On-Premises, Hybrid, Mobile Platforms, Edge Computing |
| Companies Covered | IBM Corporation, General Dynamics Corporation, Motorola Solutions, NEC Corporation, Northrop Grumman Corporation, Cisco Systems, Thales Group, Huawei Technologies, Honeywell International, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Public Safety Solution Market Shifts & Advancements
Edge computing architectures are redistributing processing loads away from centralized data centers, enabling sub-50 millisecond response times for time-critical emergency applications.
Digital twin technology is digitizing physical emergency response infrastructure, allowing fire departments and police agencies to simulate incident scenarios before deploying actual resources. US metropolitan departments in Chicago and Los Angeles have adopted these platforms for training and pre-positioning optimization. The technology compresses decision cycles during multi-agency coordination events by providing shared situational awareness.
The EU AI Act's risk classification framework imposes mandatory conformity assessments on biometric identification systems deployed by law enforcement. Vendors must demonstrate algorithmic accuracy thresholds and human oversight protocols before market entry. High-risk system categories face documentation burdens that favor established suppliers with dedicated regulatory affairs teams over emerging competitors.
Municipal buyers are consolidating vendor relationships through multi-year enterprise agreements that bundle hardware, software, and managed services. This behavior displaces point-solution procurement that characterized previous refresh cycles. German state police forces have pioneered this approach, negotiating framework contracts covering 5-7 year operational horizons with single-source accountability.
Global Public Safety Solution Market Segmentation
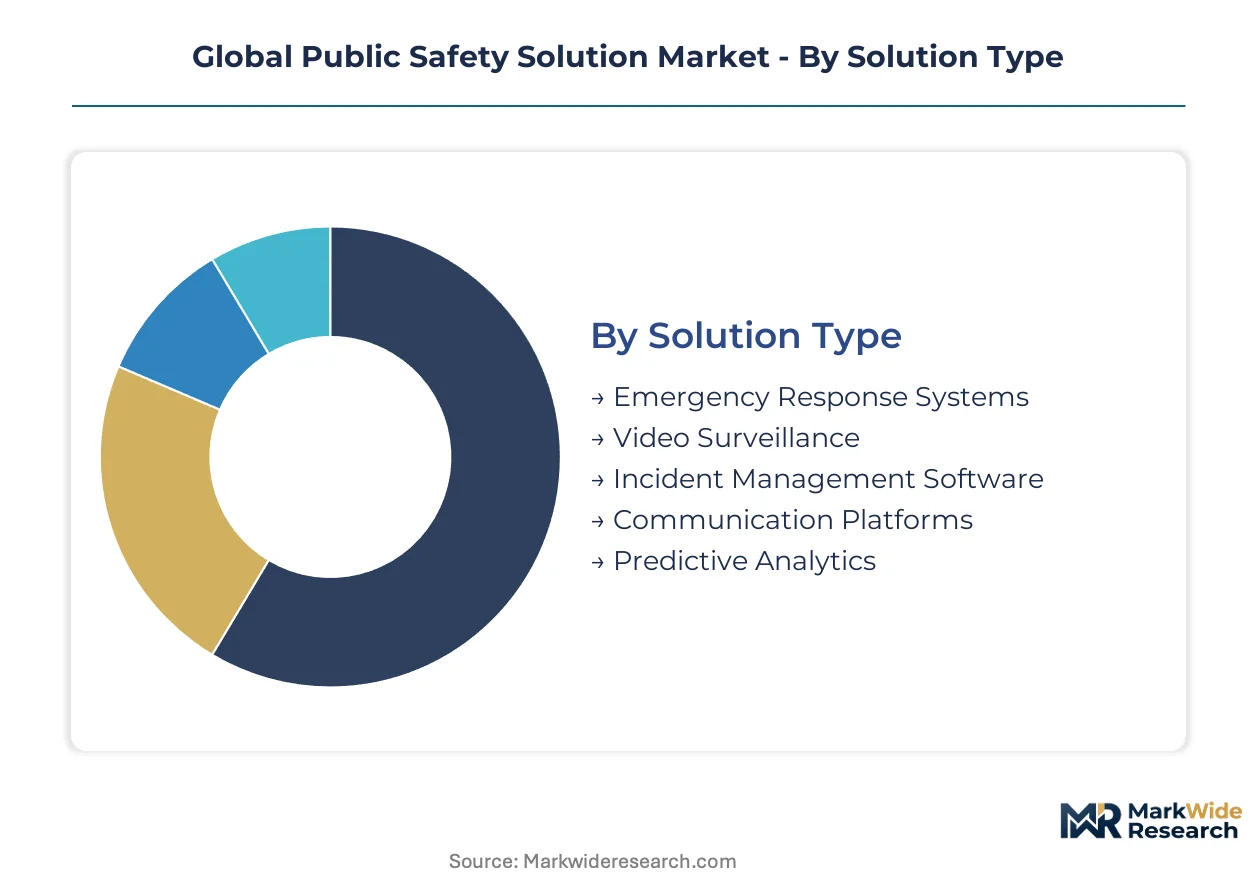
Public safety procurement patterns diverge sharply across solution architectures, operational contexts, and infrastructure maturity. Segmentation reveals where municipal budgets concentrate and which technology transitions command capital allocation priority.
Solution Type:
Cost tier structures separate established hardware infrastructure from software-centric recurring revenue models.
- Video Surveillance:Fixed and mobile camera networks with edge analytics capabilities process footage locally to reduce bandwidth costs. Megacity clusters in China and India deploy these at scale for crowd density monitoring and automated license plate recognition.
- Incident Management Software:Unified command platforms integrate dispatch, resource tracking, and inter-agency communication into single-pane workflows. Fire departments in Germany and the United States drive replacement demand as legacy CAD systems reach end-of-life.
- Emergency Response Systems:Computer-aided dispatch and location services routing emergency calls to nearest available units.
- Communication Platforms:Mission-critical voice and data networks including P25, TETRA, and LTE-based alternatives.
- Predictive Analytics:Machine learning models applied to historical crime data for patrol optimization and resource pre-positioning.
Video Surveillance holds installed capacity. Predictive Analytics is rotating up the share rankings.
Application:
Operational intensity varies by incident frequency and consequence severity, shaping technology specifications and procurement urgency.
- Crime Prevention:Real-time video analytics and gunshot detection systems feed directly into patrol dispatch protocols. Chicago Police Department and Los Angeles Sheriff's Department have deployed predictive policing platforms that adjust beat boundaries based on algorithmic risk scoring.
- Disaster Management:Multi-agency coordination platforms manage evacuation logistics, shelter allocation, and mutual aid resource sharing across jurisdictional boundaries.
- Fire Control:Thermal imaging integration with dispatch systems enables pre-arrival situational awareness for structural fire response.
- Traffic Monitoring:Automated incident detection and variable message sign control for highway safety management.
- Search and Rescue:Drone-mounted thermal sensors and GPS beacon triangulation for wilderness and urban collapse scenarios.
Crime Prevention dominates current procurement volumes. Disaster Management is climbing the fastest as climate adaptation budgets expand.
End User:
Customer type determines purchasing authority complexity and funding source stability.
- Law Enforcement Agencies:Municipal police departments and county sheriff offices with discretionary technology budgets tied to public safety millage rates.
- Fire Departments:Combination career-volunteer organizations with apparatus replacement cycles that create bundled technology upgrade opportunities.
- Emergency Medical Services:Hospital-based and municipal third-service providers requiring patient data integration with hospital admission systems.
- Homeland Security:Federal agencies with classified procurement channels and counter-terrorism mission requirements.
- Public Safety Departments:Consolidated agencies merging police, fire, and EMS under unified command structures.
Law Enforcement Agencies anchor vendor relationships. Public Safety Departments are gaining share fastest through municipal consolidation trends.
Deployment Mode:
Infrastructure maturity and cybersecurity posture separate cloud-adopting municipalities from those retaining on-premises control.
- Cloud-based:Subscription models with elastic compute scaling reduce capital expenditure requirements for budget-constrained cities. GDPR compliance friction limits European police force adoption despite operational advantages.
- Edge Computing:Distributed processing nodes at camera and sensor locations enable sub-50 millisecond response times for time-critical threat detection. Shenzhen and Singapore have deployed city-wide edge architectures for real-time facial recognition and anomaly detection.
- On-Premises:Dedicated data center installations maintaining physical air-gapping for sensitive criminal justice information systems.
- Hybrid:Tiered architectures with sensitive operations on-premises and analytics workloads in commercial cloud environments.
- Mobile Platforms:Officer-worn devices and vehicle-mounted terminals extending system access beyond fixed command centers.
On-Premises retains legacy footprint. Edge Computing is rotating up the share rankings as latency specifications tighten.

Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Public safety technology trade flows reflect divergent regulatory regimes and procurement maturity. Export-heavy vendors in the United States and Germany supply integrated command platforms to budget-constrained municipalities in emerging markets, while Chinese manufacturers capture domestic volume through cost-optimized network builds.
United States
FirstNet deployment and federal modernization programs drive equipment refresh cycles across municipal police and fire departments. The FCC mandates interoperability standards for public safety broadband networks, creating uniform procurement specifications nationwide. Chicago and Los Angeles metropolitan departments have adopted digital twin platforms for training and resource pre-positioning optimization.
Germany
State police forces negotiate framework contracts covering 5-7 year operational horizons with single-source accountability, consolidating vendor relationships. The EU Critical Entities Resilience Directive generates compliance-driven software procurement across member states. Bavaria and North Rhine-Westphalia lead in integrated command platform adoption for cross-border emergency coordination.
China
Megacity clusters in Shenzhen and Beijing deploy city-wide edge architectures for real-time facial recognition and anomaly detection at scale. MIIT enforces GB standards for encryption and network security in government procurement, creating divergent compliance pathways for multinational suppliers. Domestic vendors capture procurement volume through cost-optimized communication platform builds.
India
The Smart Cities Mission federal funding for 100 urban centers creates concentrated demand for integrated surveillance and emergency response platforms. BIS certification requirements shape equipment procurement specifications for municipal buyers. Maharashtra and Karnataka state governments have initiated large-scale command center deployments in Mumbai and Bangalore metropolitan regions.
United Kingdom
GDPR compliance friction complicates cloud architecture design for police forces with international cooperation mandates. The EU AI Act's risk classification framework imposes mandatory conformity assessments on biometric identification systems deployed by law enforcement. London metropolitan police anchor procurement volume for predictive analytics platforms adjusting patrol boundaries based on algorithmic risk scoring.
Global Public Safety Solution Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream supplying radio frequency chipsets and edge processing hardware. Market structure consolidates around three to five full-stack vendors with established government relationships, while niche players populate analytics and cybersecurity sub-segments. Dominant archetypes include infrastructure incumbents with installed radio bases, cloud-native analytics specialists, and cost-optimized network builders. Competitive moves concentrate on multi-year enterprise agreement bundling and edge computing capacity expansion.
Among infrastructure incumbents with recurring revenue foundations, Motorola Solutions leverages its installed base to sustain government client relationships. IBM Corporation anchors positioning through predictive analytics platforms. Huawei Technologies competes aggressively on communication platforms in markets where procurement budgets favor cost-optimized network builds.
| Leading Market Players |
|---|
| IBM Corporation |
| General Dynamics Corporation |
| Motorola Solutions |
| NEC Corporation |
| Northrop Grumman Corporation |
| Cisco Systems |
| Thales Group |
| Huawei Technologies |
| Honeywell International |
| Others |
Supply & Pricing Matrix
Taiwanese foundry undercapacity for radio frequency chipsets is compressing supplier margins and forcing tiered pricing stratification across dispatch hardware tiers. Municipal procurement officers face 18-24 month lead time premiums that elevate total cost of ownership calculations against cloud-based subscription alternatives.
Pricing Analysis
Municipal government buyers anchor a three-tier pricing structure across premium, standard, and economy levels. Price differentiation rests on Federal Communications Commission certification grade and post-deployment managed service bundling. Cost compression in economy-tier radio infrastructure is intensifying because semiconductor supply bottlenecks favor vendors with captive foundry relationships. Small-city police departments exhibit highest price sensitivity, while consolidated Public Safety Departments prioritize interoperability over unit cost.
Supply Chain Analysis
Export controls on advanced semiconductors limit Taiwan-to-China chipset flows and constrain vendor sourcing flexibility. Manufacturing concentrates in Taiwan, South Korea, and Malaysia for specialized RF components, while final assembly draws from Mexico and Vietnam for tariff-advantaged delivery to North American buyers. Single-source vulnerability pervades 7-nanometer edge processing hardware. Distribution runs through authorized government contractors with security clearance requirements.

Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The FirstNet mandate and EU AI Act risk classification are accelerating procurement bifurcation between compliant full-stack vendors and point-solution specialists. Municipal consolidation trends favor vendors with multi-agency deployment experience.
For Market Incumbents: Harden recurring revenue foundations by embedding predictive analytics modules into existing command platform installations. Acquire edge computing hardware specialists to secure sub-50 millisecond latency specifications. Prioritize GDPR-compliant cloud architectures for European police force retention against emerging cloud-native entrants. For New Entrants and Emerging Players: Mid-tier Indian Smart Cities Mission municipalities represent the most penetrable entry point for integrated surveillance platforms. Drone-bodycam convergence analytics for three-dimensional incident reconstruction offers differentiation against established video vendors. Partner with system integrators holding state-level framework contracts to bypass lengthy procurement cycles. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across edge computing infrastructure deployments. Five-to-ten year viability favors vendors with demonstrated interoperability certification velocity. Target acquisition candidates with dedicated regulatory affairs teams navigating EU AI Act conformity assessments. Monitor P25 compliance certification timelines as inflection indicator for product launch competitiveness.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Unifies dispatch, video analytics, and radio systems into single-pane workflows for Chicago and Los Angeles departments. |
| Edge Computing Capacity Expansion | Enables Shenzhen-grade sub-50 millisecond facial recognition without centralized processing delays. |
| Regulatory Compliance Investment | Builds dedicated EU AI Act documentation capabilities for biometric system market entry. |
| Multi-Year Enterprise Agreement Bundling | Mirrors German state police 5-7 year framework contracts with single-source accountability. |
| Acquisition of Cybersecurity Specialist | Addresses municipal IT talent scarcity for zero-trust network architecture deployment. |
Research Methodology
Operator-level perspectives from emergency dispatch directors, municipal procurement officers, interoperability certification engineers, and federal broadband program managers anchored the qualitative base. Primary fieldwork combined structured interviews with secondary validation against FCC FirstNet deployment filings, EU Critical Entities Resilience Directive implementation reports, and MIIT GB standards documentation. Customs data on radio frequency equipment trade flows and municipal budget appropriation records provided demand-side triangulation. Bottom-up segment sizing and top-down macroeconomic cross-checks converged on volume estimates.
Scenario-bracketing around semiconductor supply recovery timelines and FirstNet adoption velocity shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include solution type, deployment mode, end-user agency structure, and regional regulatory cluster. CAGRs derived from equipment refresh cycle analysis, cloud migration elasticity coefficients, and AI video analytics penetration curves. Forecast inputs incorporated TETRA-to-LTE infrastructure replacement rates and Smart Cities Mission funding allocation trajectories.
Practitioners should monitor foundry capacity utilization reports and EU AI Act implementing guidance for early signals of supply constraint easing or compliance burden escalation. Forecasts reflect documented assumptions on federal modernization program continuity and municipal budget resilience. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Public Safety
Global Public Safety Solution for Smart City Market
Public Safety
Europe Wireless Broadband in Public Safety Market
Public Safety
Public Safety Drones Market
Public Safety
Voice Evacuation Systems Market
Public Safety
Global Public Safety in Building Wireless Das System Market
Public Safety
Crowd Management System Market
Public Safety
Europe Public Safety Market
Public Safety
North America Road Safety Market
Public Safety
US Mass Notification Systems Market
Public Safety
Safe City Market
Public Safety
Counter Terror and Public Safety Technology Market
Public Safety
Europe Road Safety Market
Public Safety
Crime Risk Report Market
Public Safety
Europe Public Infrastructure Safety Market
Public Safety
Global Public Safety and Security Market
Public Safety
Latin America Public Safety Market