
 Global Public Safety Solution for Smart City Market | 2026-2036
Global Public Safety Solution for Smart City Market Size, Share, and Industry Trends Forecast 2026-2036
Global Public Safety Solution for Smart City Market Foresight
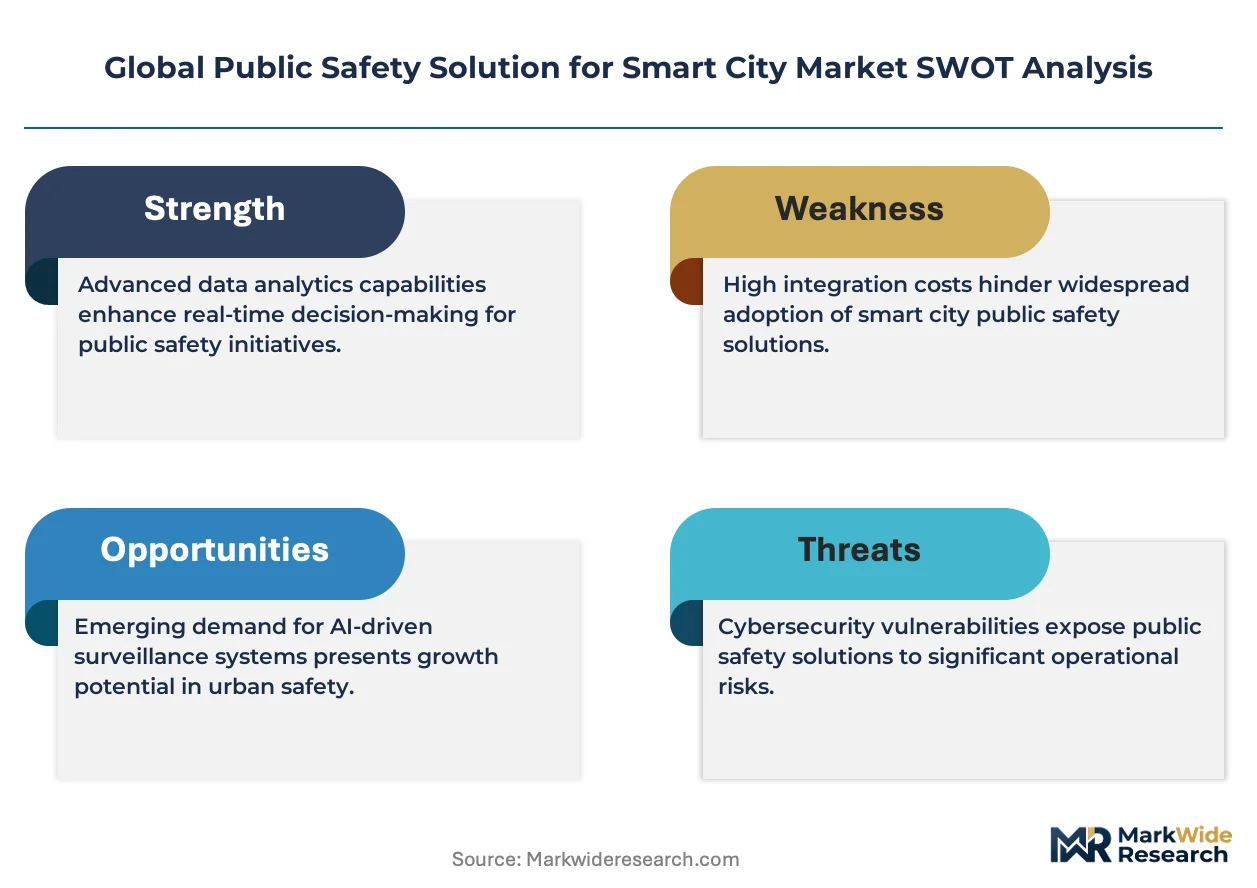
The EU AI Act is expanding compliance obligations for biometric surveillance and automated threat detection, forcing vendors to reengineer software architectures and certify algorithmic audit trails before accessing public procurement channels. Motorola Solutions Inc leverages its installed base of land-mobile radio networks to anchor long-term service contracts with municipal clients. NEC Corporation specializes in multimodal biometric fusion systems that differentiate its portfolio in airport and transit hub deployments. Huawei Technologies Co Ltd navigates geopolitical restrictions by competing aggressively on price in Middle Eastern and Southeast Asian smart city tenders where Western vendor access faces scrutiny.
Public safety solutions for smart cities integrate sensor networks, real-time data analytics platforms, and command-and-control software to detect, verify, and coordinate responses to security incidents, environmental hazards, and civil emergencies across urban environments. These systems typically process video feeds, acoustic signatures, and IoT telemetry through edge-computing nodes with sub-100-millisecond latency thresholds to enable actionable alerting. Surveillance Systems currently occupies the largest solution-type revenue pool as cities retrofit analog camera networks with AI-enabled analytics, while Cloud-Based deployment models are gaining share among mid-sized municipalities seeking to avoid capital-intensive on-premises infrastructure. Emergency Communication retains durable margins due to hardened network requirements and spectrum licensing barriers that limit new entrants.
The Federal Communications Commission in the United States mandates interoperability standards for public safety broadband through FirstNet, while the European Union's GDPR and forthcoming AI Act impose strict data governance and human-in-the-loop obligations on automated decision systems. China's GB standards for intelligent surveillance and Saudi Arabia's SFDA-aligned cybersecurity frameworks for critical infrastructure collectively fragment certification requirements, forcing vendors to maintain region-specific compliance teams. Stakeholders must monitor evolving procurement rules around algorithmic bias auditing and cross-border data residency, as these will determine which solution architectures win in the next wave of municipal tenders.
Market Dynamics
Algorithmic transparency mandates embedded in the EU AI Act are forcing vendors to reengineer software architectures and certify audit trails before accessing public procurement channels, fundamentally reshaping competitive positioning in automated surveillance systems.
Growth Catalysts
- Federal infrastructure grants:United States municipalities are accelerating smart city deployments through dedicated funding streams for command center modernization and sensor network densification.
- FirstNet interoperability standards:The FCC mandates hardened broadband networks for public safety, creating durable demand for certified equipment and locking in long-term service relationships.
- Edge-computing latency thresholds:Sub-100-millisecond processing requirements are driving replacement cycles for legacy analog camera networks with AI-enabled analytics platforms.
Market Restraints
- GDPR data residency rules:Cross-border data transfer restrictions fragment cloud deployment architectures and inflate compliance costs for multi-national vendors.
- Spectrum licensing barriers:Emergency communication networks require hardened infrastructure and exclusive frequency allocations that limit new entrant participation.
- Silicon supply concentration:Edge-computing node production depends on concentrated semiconductor fabrication capacity in East Asia, exposing deployment timelines to geopolitical disruption.
Strategic Opportunities
- Saudi Arabia SFDA-aligned frameworks:Cybersecurity certification requirements for critical infrastructure create first-mover advantages for vendors establishing local compliance capabilities.
- Multimodal biometric fusion:Convergence of facial recognition, gait analysis, and acoustic signature processing opens premium positioning in airport and transit hub deployments.
- Mid-sized municipality cloud migration:Capital-constrained cities are bypassing on-premises infrastructure through subscription-based deployment models.
Industry Challenges
- Algorithmic bias auditing:Municipal tenders now require documented fairness testing protocols that extend sales cycles and demand specialized technical staff.
- Legacy radio network integration:Land-mobile radio systems anchor existing vendor relationships, creating switching friction for new analytics platform entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Public Safety Solution for Smart City Market |
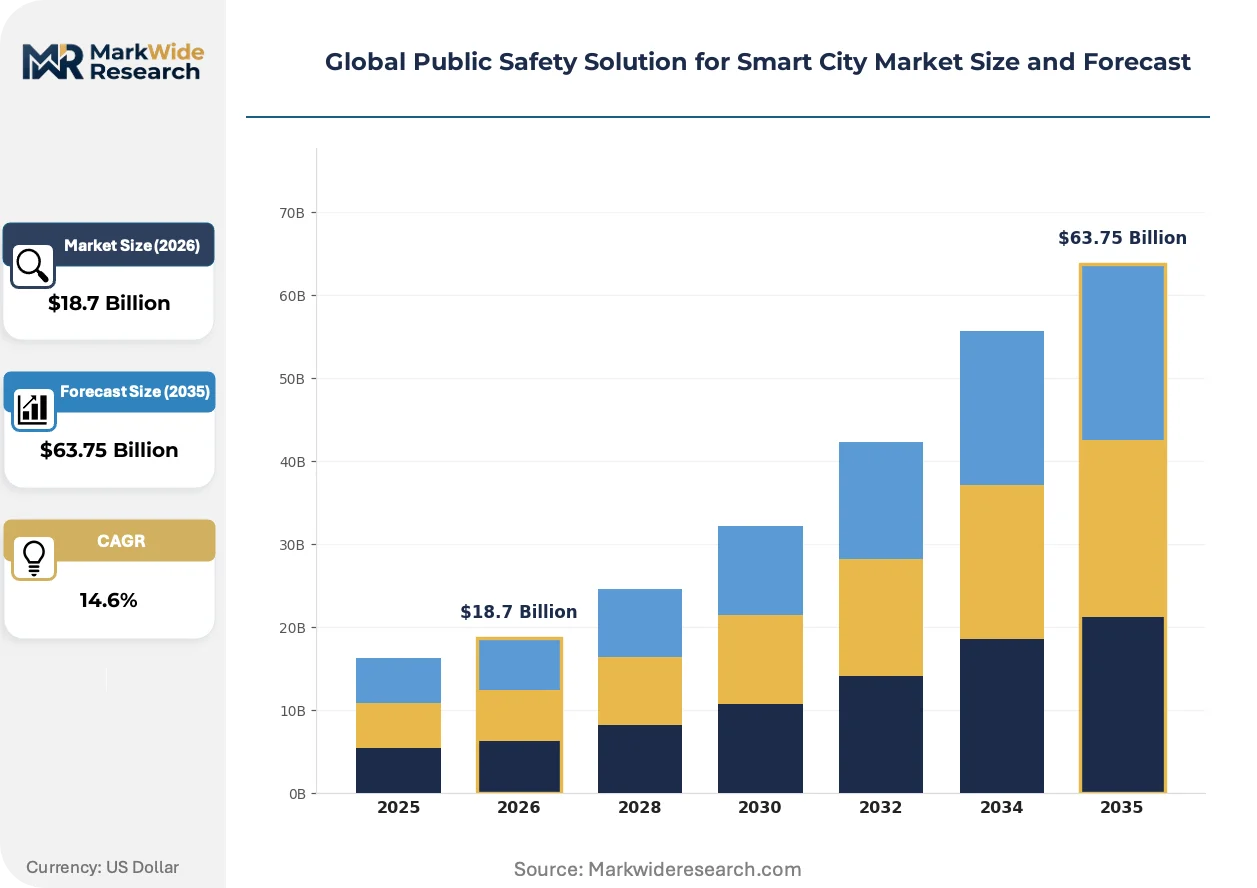
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $63.75 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Solution Type: Surveillance Systems, Emergency Communication, Incident Management, Access Control, Fire Detection Deployment Model: Cloud-Based, On-Premises, Hybrid, Edge Computing, Distributed Architecture Application: Traffic Monitoring, Crime Prevention, Disaster Response, Crowd Management, Environmental Monitoring End User: Law Enforcement Agencies, Emergency Services, City Operators, Urban Planners, Security Contractors |
| Companies Covered | Honeywell International Inc, NEC Corporation, Motorola Solutions Inc, Schneider Electric SE, Thales Group, Cisco Systems Inc, L3Harris Technologies Inc, Huawei Technologies Co Ltd, IBM Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Public Safety Solution for Smart City Market Shifts & Advancements
Real-time sensor fusion and automated threat verification are compressing emergency response coordination from minutes to seconds, while procurement criteria increasingly weight algorithmic explainability alongside raw detection accuracy.
Computer vision analytics is converging with acoustic gunshot detection to enable multi-sensor incident verification without human operator intervention. Transit authorities in Chicago and Singapore are deploying these fused systems in high-density corridors. The technology is converging with edge-computing architectures to reduce bandwidth costs and enable actionable alerting during network degradation.
The EU AI Act's human-in-the-loop obligations for automated decision systems are mandating operator override capabilities in biometric surveillance deployments. Vendors must now engineer pause-and-escalate workflows that interrupt algorithmic processing. Airport security operators in Frankfurt and Amsterdam are piloting these intervention protocols ahead of enforcement deadlines.
Municipal procurement teams are unbundling hardware acquisition from analytics software licensing to avoid vendor lock-in. Mid-sized cities in Texas and Ohio are separating camera network installation from AI service subscriptions. This pattern is most visible in North American municipalities where federal grant structures favor capital-light operational expenditure models.
Global Public Safety Solution for Smart City Market Segmentation
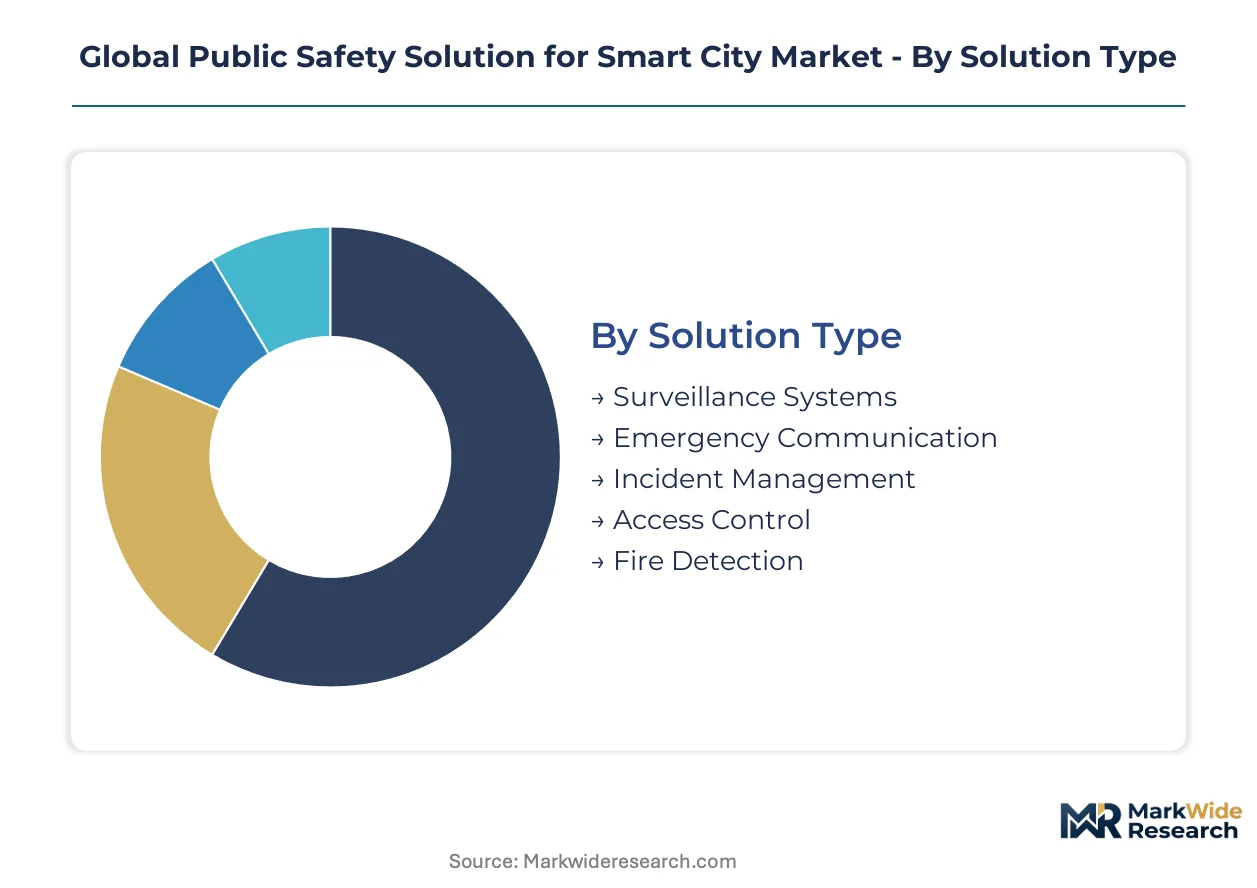
Segmentation in public safety solutions reveals how procurement priorities diverge across municipal budget tiers, regulatory environments, and operational maturity levels. Understanding these axes helps vendors align product architectures with specific buyer constraints and compliance obligations.
Solution Type:
Technical specifications and integration complexity differentiate solution tiers, with AI-enabled platforms commanding premium positioning against legacy infrastructure.
- Surveillance Systems:Video analytics platforms process multi-sensor feeds through edge-computing nodes with sub-100-millisecond latency. Cities in the United States are retrofitting analog networks with computer vision capabilities to meet federal grant requirements for command center modernization.
- Emergency Communication:Hardened broadband networks and land-mobile radio systems require exclusive spectrum allocations and FCC FirstNet certification. These specifications create durable vendor relationships with municipal clients seeking guaranteed interoperability during critical incidents.
- Incident Management:Command-and-control software orchestrates multi-agency response coordination through unified dashboards.
- Access Control:Biometric and credential-based entry systems secure critical infrastructure facilities and transit hubs.
- Fire Detection:IoT sensor networks and thermal imaging arrays provide early warning for structural and wildfire events.
Surveillance Systems leads on scale; Emergency Communication leads on margin durability.
Deployment Model:
Capital intensity and data sovereignty requirements shape deployment preferences across municipality size classes and regulatory jurisdictions.
- Cloud-Based:Subscription models eliminate upfront infrastructure investment while enabling rapid scaling. Mid-sized cities in Texas and Ohio favor this approach to convert capital expenditures into operational budgets aligned with federal grant structures.
- On-Premises:Dedicated hardware installations satisfy GDPR data residency mandates and air-gapped security requirements. German and French municipalities mandate these configurations for biometric surveillance systems under EU AI Act human-in-the-loop obligations.
- Hybrid:Split architectures process sensitive data locally while leveraging cloud analytics for non-critical workloads.
- Edge Computing:Distributed processing nodes enable actionable alerting during network degradation or bandwidth constraints.
- Distributed Architecture:Federated sensor networks reduce single points of failure across geographically dispersed urban zones.
On-Premises dominates in regulated European markets; Cloud-Based is climbing the fastest among capital-constrained North American municipalities.
Application:
Operational use cases determine sensor density requirements, algorithmic training data needs, and inter-agency coordination protocols.
- Traffic Monitoring:Computer vision systems analyze vehicle flows, incident detection, and automated enforcement across arterial corridors. Singapore and Chicago transit authorities deploy these capabilities with acoustic gunshot fusion for multi-sensor verification.
- Crime Prevention:Predictive analytics and hotspot mapping guide patrol resource allocation. Law enforcement agencies represent the steepest expansion trajectory as cities modernize command centers with real-time intelligence platforms.
- Disaster Response:Integrated sensor networks coordinate evacuation routing and resource mobilization during environmental emergencies.
- Crowd Management:Density estimation and flow analysis secure stadiums, transit terminals, and public gathering spaces.
- Environmental Monitoring:Air quality, noise, and radiation sensors feed municipal health and safety dashboards.
Traffic Monitoring leads on installed base; Crime Prevention leads on technology refresh rates.
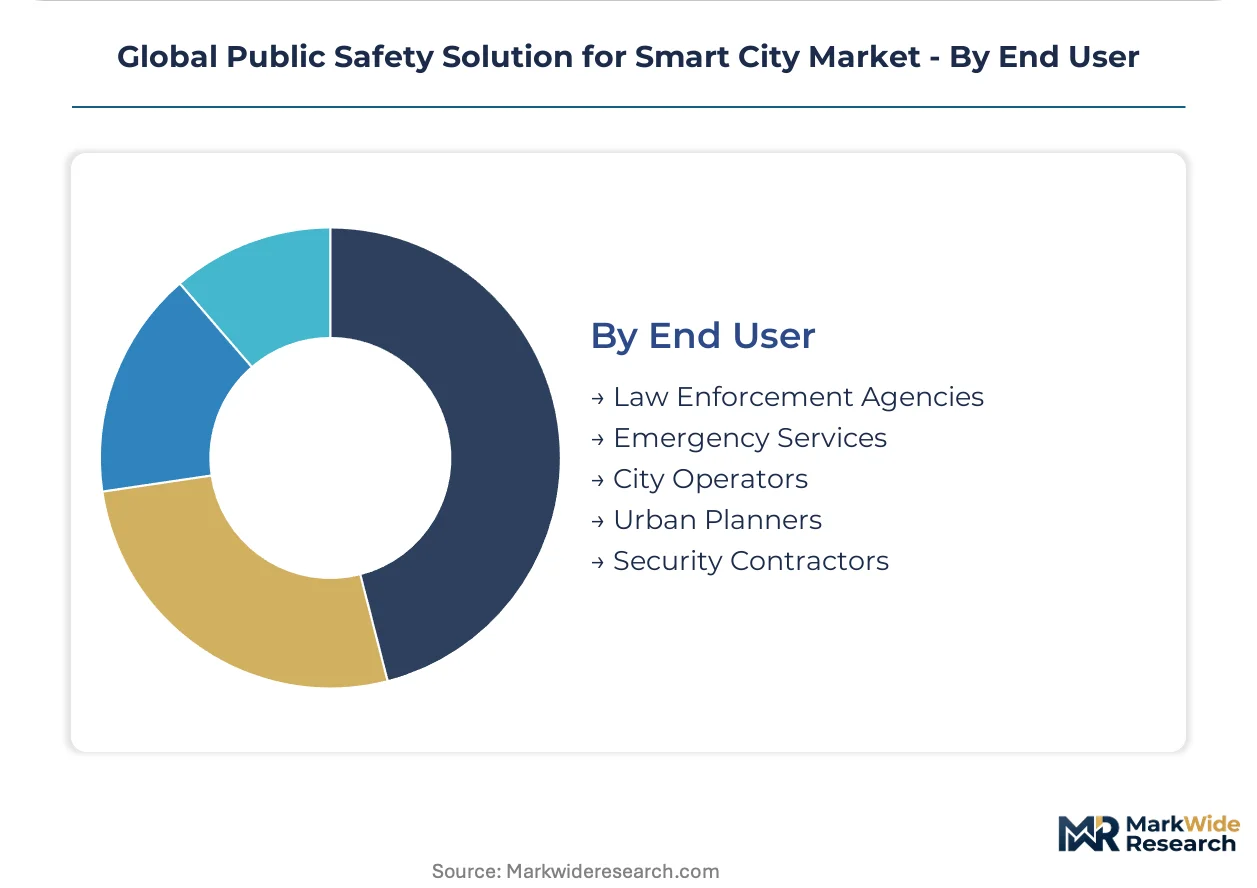
End User:
Procurement authority and technical sophistication vary sharply across buyer categories, shaping sales cycle length and implementation support requirements.
- Law Enforcement Agencies:Police departments command dedicated budgets for intelligence-led policing platforms and forensic analytics integration. These buyers prioritize algorithmic explainability and bias audit documentation under emerging municipal tender requirements.
- Emergency Services:Fire and medical response units require hardened communication networks with guaranteed availability during infrastructure failure. FCC FirstNet mandates lock in long-term equipment certification relationships for this segment.
- City Operators:Centralized municipal IT departments consolidate procurement across departmental silos to achieve vendor leverage.
- Urban Planners:Long-term infrastructure investment teams evaluate safety systems within broader smart city master plans.
- Security Contractors:Private operators deliver managed services under municipal outsourcing arrangements.
Law Enforcement Agencies leads on decision-making authority; Emergency Services leads on contract tenure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Engineering talent clusters in Boston, Singapore, and Munich anchor solution development for command center analytics and edge-computing architectures. Procurement concentration follows federal funding disbursements and regulatory enforcement timelines across distinct national markets.
United States
FirstNet interoperability mandates from the FCC lock in long-term equipment certification relationships for hardened broadband networks. Federal infrastructure grants accelerate sensor network densification in Chicago and Dallas transit corridors. Motorola Solutions Inc leverages its installed base to anchor municipal service contracts.
Germany
GDPR data residency rules and EU AI Act human-in-the-loop obligations mandate on-premises architectures for biometric surveillance. Frankfurt and Amsterdam airports pilot operator override workflows ahead of enforcement deadlines. NEC Corporation positions multimodal biometric fusion systems for premium transit hub deployments.
China
GB standards for intelligent surveillance create domestic certification pathways that favor local edge-computing node production. Shenzhen and Hangzhou smart city clusters deploy computer vision analytics at municipal scale. Huawei Technologies Co Ltd competes on price in tenders where Western vendor access faces scrutiny.
Saudi Arabia
SFDA-aligned cybersecurity frameworks for critical infrastructure establish first-mover advantages for vendors building local compliance capabilities. NEOM and Riyadh command center modernizations drive demand for integrated sensor networks. Thales Group and Schneider Electric SE target premium positioning in giga-project tenders.
Singapore
Acoustic gunshot detection fused with computer vision compresses emergency response coordination in high-density transit corridors. National research programs fund sub-100-millisecond latency threshold validation for edge-computing architectures. The city-state serves as a testbed for multi-sensor incident verification without human operator intervention.
Global Public Safety Solution for Smart City Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across solution tiers, creating a bifurcated structure where scale advantages clash with integration speed. The vendor base clusters around three strategic archetypes: legacy radio network incumbents extending into analytics, IT infrastructure giants bundling safety modules, and biometric specialists defending premium positioning. Dominant competitive moves include M&A to fill portfolio gaps and strategic partnerships to satisfy region-specific compliance requirements.
Among diversified technology conglomerates, Honeywell International Inc and IBM Corporation represent the full-stack integration archetype, while Cisco Systems Inc exemplifies network infrastructure leverage into safety verticals. Motorola Solutions Inc and NEC Corporation occupy distinct specialist positions—one anchored in land-mobile radio relationships, the other in multimodal biometric systems. L3Harris Technologies Inc and Thales Group sit within the defense-industrial tier, leveraging hardened communication expertise for municipal command center tenders. Huawei Technologies Co Ltd exemplifies price-competitive positioning in geographies with procurement restrictions on Western vendors.
| Leading Market Players |
|---|
| Honeywell International Inc |
| NEC Corporation |
| Motorola Solutions Inc |
| Schneider Electric SE |
| Thales Group |
| Cisco Systems Inc |
| L3Harris Technologies Inc |
| Huawei Technologies Co Ltd |
| IBM Corporation |
| Others |
Supply & Pricing Matrix
Embedded software engineers clustered in Boston, Singapore, and Munich command wage premiums that widen spreads between premium-tier AI-enabled platforms and economy-tier legacy installations. Labor-cost differentials between these talent hubs and emerging development centers in Eastern Europe and Southeast Asia enable vendors to stratify pricing across certification-grade tiers while maintaining margin structures.
Pricing Analysis
Hardware-software unbundling reshapes municipal procurement economics. Three-tier pricing structure across premium, standard, and economy levels separates FCC FirstNet-certified emergency communication systems from cloud-based subscription analytics and unlicensed sensor hardware. Price differentiation hinges on algorithmic audit documentation and EU AI Act compliance certification. Pricing pressure stems from federal grant structures favoring operational expenditure models over capital-intensive deployments. Mid-sized municipalities exhibit highest price sensitivity; airport and transit hub operators demonstrate lowest.
Supply Chain Analysis
Saudi Arabia's SFDA-aligned domestic-content mandates and China's GB standards for intelligent surveillance reshape component sourcing for vendors seeking public procurement eligibility. Edge-computing node production draws from concentrated semiconductor fabrication capacity in Taiwan, South Korea, and China. Supply chains rest on advanced GPU accelerators, hardened broadband chipsets, and thermal imaging sensors. Single-source vulnerability in East Asian wafer fabrication exposes deployment timelines to geopolitical disruption. Distribution runs through systems integrators and direct municipal contracting channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in public safety solutions hinges on cloud-based deployment models converting capital expenditures into recurring subscription revenue, while premium-tier positioning in biometric surveillance captures compliance-driven upgrade cycles.
For Market Incumbents: Extend land-mobile radio relationships into AI-enabled analytics platforms through firmware upgrade pathways that preserve existing municipal contracts. Anchor service relationships with FCC FirstNet certification lock-in while building algorithmic audit capabilities to defend against pure-play biometric specialists threatening airport and transit hub deployments. Vertical integration into edge-computing hardware reduces silicon supply exposure. For New Entrants and Emerging Players: Capital-constrained mid-sized municipalities in Texas, Ohio, and comparable North American markets represent the most penetrable buyer archetype. White-space targets include subscription-based incident management software and acoustic-computer vision fusion systems for high-density transit corridors. Go-to-market through federal grant facilitation services accelerates procurement access. For Investors and Strategic Acquirers: Defense-industrial conglomerates with hardened communication expertise are the most active acquirer in this space, seeking municipal command center capabilities. Long-term viability favors vendors with dual-use technology spanning public safety and critical infrastructure protection. Acquisition target archetype: biometric specialists with EU AI Act compliance documentation. Signal to watch: municipal tender language around algorithmic bias auditing requirements.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Unifies land-mobile radio networks with AI analytics through Motorola Solutions Inc's installed base leverage. |
| Acquisition of Specialist Firm | Fills biometric fusion gaps for NEC Corporation's airport and transit hub positioning. |
| Geographic Expansion | Huawei Technologies Co Ltd penetrates Middle Eastern tenders where Western vendor access faces scrutiny. |
| Strategic Partnership | Schneider Electric SE aligns with SFDA frameworks for Saudi giga-project command center modernization. |
| Product Launch | Thales Group deploys hardened broadband networks meeting FCC FirstNet interoperability mandates. |
Research Methodology
Multiple input streams — municipal procurement officer interviews, systems integrator channel assessments, and regulatory filing analysis — were reconciled to construct segment-level demand estimates. Primary fieldwork engaged command center operations directors, smart city IT architects, FCC certification specialists, and EU AI Act compliance consultants. Secondary validation drew from SEC 10-K disclosures of listed vendors, municipal bond prospectuses for smart city infrastructure projects, and FirstNet deployment progress reports. Bottom-up triangulation across solution-type deployments was cross-checked against top-down federal grant disbursement tracking.
Historical deployment velocity was cross-referenced against expert panel inputs to anchor growth assumptions across the analysis window. Segmentation modeling incorporated solution type, deployment model, application, and end-user dimensions with regional regulatory cluster overlays. CAGR derivation weighted edge-computing latency requirement adoption curves and biometric surveillance compliance deadline impacts. Forecast inputs included federal infrastructure grant pipeline visibility and EU AI Act enforcement timeline phasing.
Underlying measurement precision varies by segment; cloud-based deployment models and law enforcement agency end-users carry tighter precision than emerging biometric fusion applications. Forecasts embed assumptions around federal funding continuity and semiconductor supply normalization. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Public Safety
Public Safety LTE Market
Public Safety
Safe City Market
Public Safety
US Mass Notification Systems Market
Public Safety
AI for Public Security and Safety Market
Public Safety
North America Road Safety Market
Public Safety
Global Wireless Broadband in Public Safety Market
Public Safety
Counter Terror and Public Safety Technology Market
Public Safety
Crowd Management System Market
Public Safety
Outdoor Public Safety Market
Public Safety
Europe Road Safety Market
Public Safety
Europe Wireless Broadband in Public Safety Market
Public Safety
Middle East Crime and Combat Market
Public Safety
Global Public Safety in Building Wireless Das System Market
Public Safety
Asia-Pacific Public Safety Market
Public Safety
Global IoT for Public Safety Market
Public Safety
Public Safety in-Building Wireless Distributed Antenna System (DAS) Market