
 Global Public Safety in Building Wireless Das System Market | 2026-2036
Global Public Safety in Building Wireless Das System Market Size, Share, and Industry Trends Forecast 2026-2036
Global Public Safety in Building Wireless Das System Market Foresight
North American infrastructure contractors is consolidating procurement around fewer certified integrators capable of meeting NFPA 1221 and IFC 510 code bundles. CommScope Inc. leverages its cable and connectivity heritage to anchor large-scale stadium and airport deployments. Corning Incorporated sustains optical backbone advantages that feed into hybrid DAS architectures. Ericsson competes through radio access network expertise ported into public safety spectrum blocks.
Public Safety in Building Wireless DAS Systems are distributed antenna networks engineered to amplify 700 MHz, 800 MHz, and FirstNet band signals throughout structurally complex interiors, ensuring uninterrupted radio connectivity for emergency personnel during critical incidents. Active DAS dominates current deployment value due to its fiber-fed, multi-carrier amplification capability across sprawling footprints. Passive DAS retains cost advantages in smaller commercial buildings where single-tenant coverage suffices. Hybrid DAS configurations are capturing accelerated interest as facility managers seek to bridge capital efficiency with future digital upgrade paths.
FCC mandates, NFPA 1221 fire code provisions, and IFC 510 standards collectively mandate minimum signal strength thresholds that force building owners toward compliant infrastructure investment rather than risk occupancy penalties. EMEA jurisdictions apply CE marking and country-specific spectrum licensing through national regulators such as BNetzA in Germany and Ofcom in the United Kingdom. Stakeholders must monitor evolving FirstNet interoperability requirements and emerging sub-6 GHz spectrum reallocations that could reshape hardware compatibility commitments.
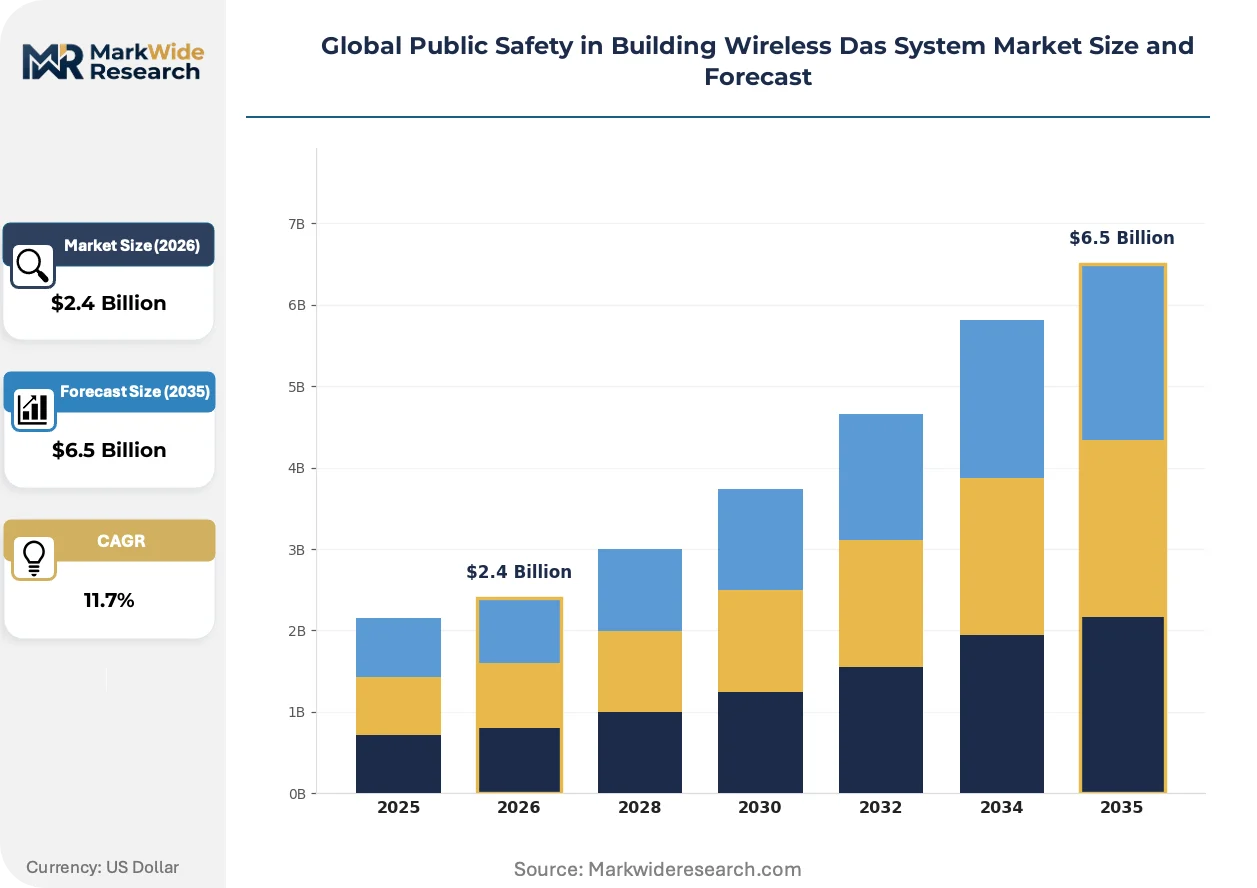
Market Dynamics
FCC's tightening in-building coverage mandates for public safety bands are forcing capital deployment toward compliant distributed antenna infrastructure, compressing procurement cycles and consolidating vendor selection around certified integrators capable of meeting bundled NFPA 1221 and IFC 510 code requirements.
Growth Catalysts
- FirstNet Band Expansion:The dedicated public safety broadband network is mandating interoperable coverage in commercial high-rises, driving DAS upgrades across Class A office buildings and healthcare facilities.
- Germany BNetzA Spectrum Licensing:Germany's national regulator has tightened indoor emergency communication requirements for critical infrastructure, accelerating passive-to-hybrid DAS conversions in Frankfurt and Munich financial districts.
- High-Rise Fire Code Bundles:Combined NFPA 1221 and IFC 510 enforcement in dense urban cores is eliminating grandfathered exemptions, compelling retrofit investments in legacy commercial towers.
Market Restraints
- Fiber-Optic Component Volatility:Specialized low-loss coaxial cable and precision RF connectors face concentrated supply from Asian manufacturing clusters, exposing project timelines to input cost swings.
- Certified Labor Pool Scarcity:BICSI-certified DAS technicians remain geographically concentrated in Texas and California, creating installation bottlenecks for multi-site rollouts.
- Passive DAS Obsolescence Risk:Single-carrier passive architectures face functional displacement as FirstNet multi-band requirements render legacy splitters and diplexers non-compliant.
Strategic Opportunities
- Japan METI Smart Building Integration:Japan's Ministry of Economy, Trade and Industry is incentivizing converged public safety and commercial cellular DAS in Tokyo and Osaka mixed-use developments.
- Sub-6 GHz Spectrum Reallocation:Emerging 4.9 GHz and 3.5 GHz band assignments for critical communications are creating upgrade pathways for future-proofed hybrid architectures.
- Digital DAS Remote Monitoring:Cloud-based RF performance analytics platforms are opening recurring revenue streams for system integrators managing distributed campus portfolios.
Industry Challenges
- Multi-Code Compliance Timelines:Simultaneous NFPA 1221, IFC 510, and FCC Part 90 certification processes extend project delivery windows by 4-8 months for complex stadium and airport deployments.
- Legacy BDA Integration Friction:Existing bidirectional amplifier infrastructure from pre-2010 installations requires complete signal path redesign rather than incremental upgrade, doubling effective replacement costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Public Safety in Building Wireless Das System Market |
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $6.5 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | System Type: Active DAS, Passive DAS, Hybrid DAS, Digital DAS, RF Repeaters Application: Emergency Response, Fire Alarms, Security Monitoring, Evacuation Coordination, Hazard Detection Deployment Environment: Commercial Buildings, Educational Institutions, Government Facilities, Transportation Hubs, Event Venues End User: First Responders, Facility Management, Security Agencies, Infrastructure Operators, Safety Consultants |
| Companies Covered | CommScope Inc., Corning Incorporated, TE Connectivity Ltd., Ericsson, Nokia Corporation, Cisco Systems Inc., SOLiD Technologies LLC, Advanced RF Technologies Inc., Zinwave Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Public Safety in Building Wireless Das System Market Shifts & Advancements
Intelligent RF management software and converged public safety-commercial architectures are displacing siloed single-purpose networks, while remote monitoring capabilities compress operational response times for distributed facility portfolios.
AI-powered RF optimization engines are automating real-time power balancing across multi-carrier DAS nodes, eliminating manual drive-test calibration cycles. Large-scale stadium operators and airport authorities are deploying these platforms to maintain FirstNet signal integrity during crowd density spikes. The technology is automating what previously required on-site technician intervention, reducing recurring operational expenditure by compressing fault detection-to-resolution intervals.
REACH substance restrictions and RoHS 3 compliance deadlines in the European Union are forcing component suppliers to eliminate legacy lead-based solder and cadmium-plated connectors from RF distribution hardware. Industrial consequence includes accelerated qualification cycles for alternative plating chemistries and polymer compounds. German and French integrators are responding by consolidating procurement around pre-certified compliant component lines, narrowing approved vendor lists.
Building owners are unbundling DAS maintenance from initial capital contracts, creating standalone multi-year service agreements with performance-based SLA structures. This displaces the traditional single-source design-build-maintain model. The shift is most visible in United States healthcare systems and university campuses, where facilities management teams seek operational budget predictability separate from capital project accounting.
Global Public Safety in Building Wireless Das System Market Segmentation
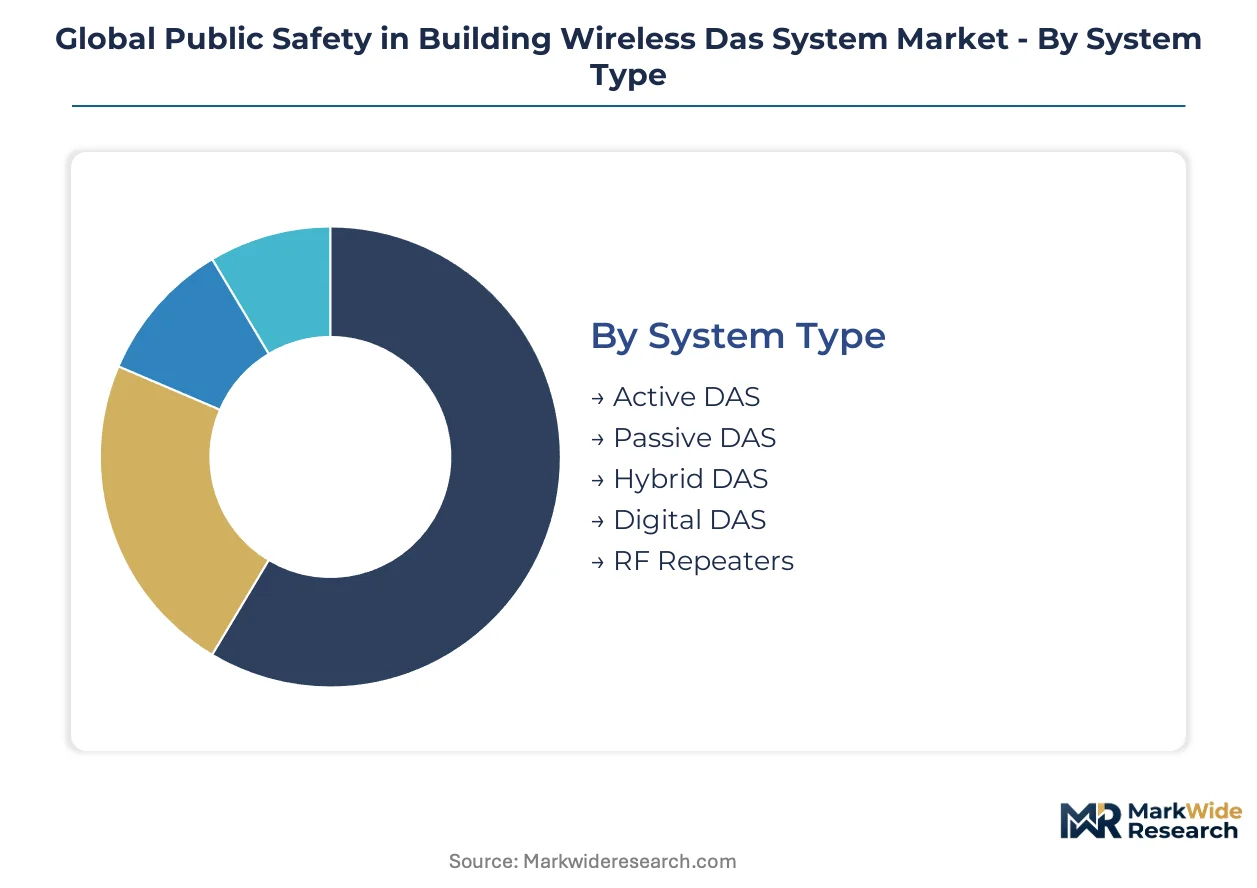
Different system architectures, deployment settings, and user groups impose distinct RF engineering requirements and compliance burdens. Segmentation reveals where capital concentrates and which specifications command premium pricing.
System Type:
Technical architecture dictates fiber backhaul requirements, carrier aggregation capability, and upgrade pathways.
- Active DAS:Fiber-fed distributed nodes with dedicated amplification per frequency band. Stadium and airport authorities in the United States deploy these for multi-carrier FirstNet interoperability across sprawling footprints.
- Passive DAS:Coaxial cable distribution with passive splitters and diplexers. Small commercial buildings in Germany retain these for single-tenant coverage where capital constraints outweigh future-proofing needs.
- Hybrid DAS:Combines fiber backbone with passive distribution legs. Tokyo mixed-use developments are adopting these to bridge cost efficiency with sub-6 GHz upgrade paths.
- Digital DAS:Converts RF to digital at the headend for Ethernet transport. Emerging in healthcare campuses requiring centralized monitoring across dispersed buildings.
- RF Repeaters:Single-band amplification for coverage gap filling. Deployed in rural Japanese government facilities where full DAS deployment proves economically unviable.
Mature deployment sits with Passive DAS. Newer deployment is concentrated in Hybrid DAS.
Application:
Functional use case determines signal reliability thresholds and integration complexity with building systems.
- Emergency Response:Mission-critical voice and data connectivity for police, fire, and EMS personnel. High-rise commercial towers in Frankfurt mandate these systems under BNetzA enforcement.
- Fire Alarms:NFPA 1221-compliant radio links for fire command operations. United States educational institutions face combined fire code and FCC mandates driving retrofit cycles.
- Security Monitoring:Real-time video backhaul and access control integration. Osaka smart building developments under METI incentives converge these with commercial cellular.
- Evacuation Coordination:Mass notification and responder communication during crowd events. Munich transportation hubs deploy these for coordinated emergency protocols.
- Hazard Detection:Chemical, radiological, and biological sensor connectivity. Government facilities in Japan integrate these with national disaster response frameworks.
Steepest expansion trajectory belongs to Emergency Response. Fire Alarms retain the largest installed base.
Deployment Environment:
Physical setting shapes RF propagation challenges and regulatory jurisdiction.
- Commercial Buildings:Class A office towers and retail complexes. United States high-rise markets face elimination of grandfathered exemptions under bundled NFPA 1221 and IFC 510 enforcement.
- Educational Institutions:University campuses and K-12 facilities. Texas and California school districts consolidate multi-site procurement around certified integrators.
- Government Facilities:Federal, state, and municipal buildings. German critical infrastructure regulations accelerate passive-to-hybrid conversions in Berlin administrative centers.
- Transportation Hubs:Airports, rail terminals, and seaports. Tokyo and Osaka aviation authorities deploy AI-powered RF optimization for crowd density spike management.
- Event Venues:Stadiums, convention centers, and arenas. These facilities are gaining share fastest as FirstNet mandates extend to temporary high-occupancy structures.
Procurement volume concentrates in Commercial Buildings. Technical complexity peaks in Transportation Hubs.
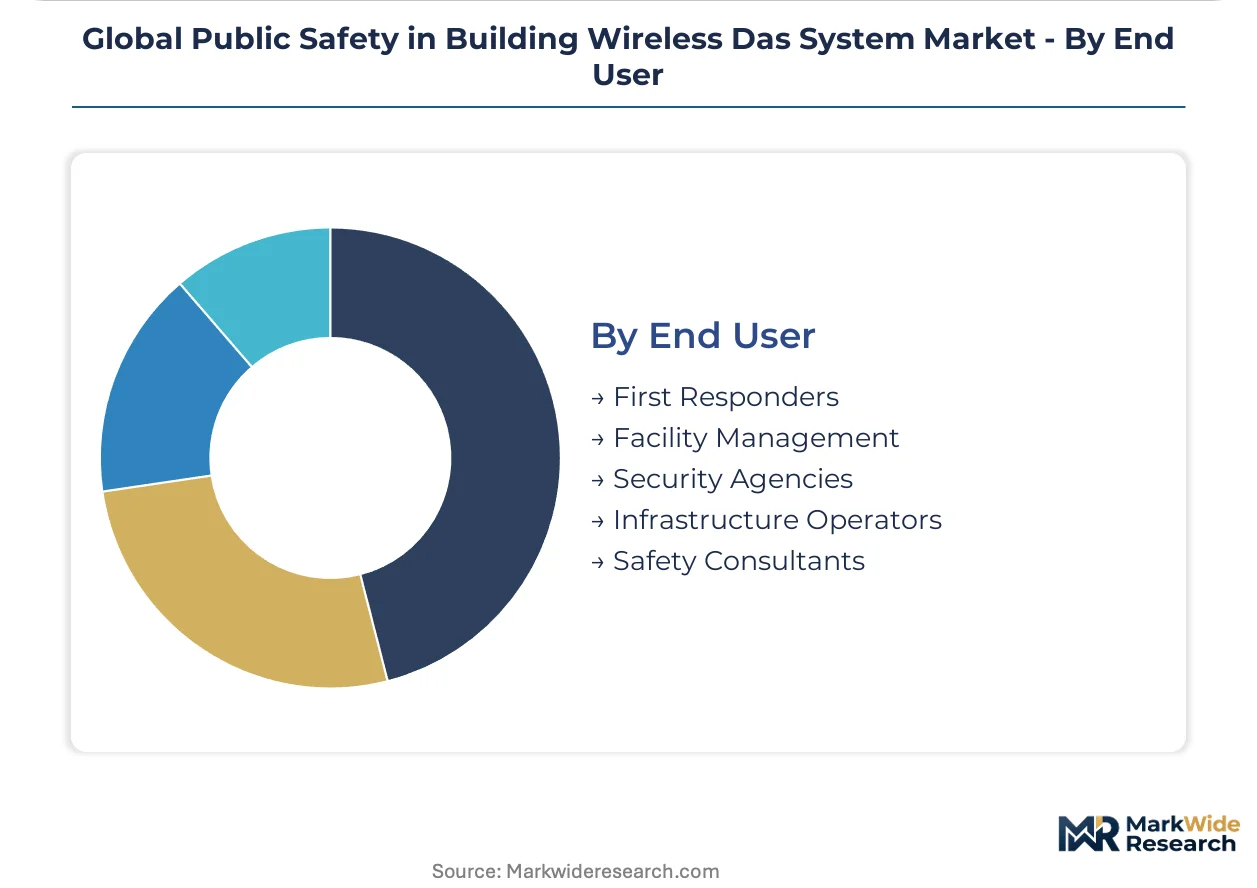
End User:
Buyer type determines procurement authority, budget source, and technical specification authority.
- First Responders:Police, fire, and emergency medical agencies. These agencies drive specification authority through FirstNet interoperability requirements in United States markets.
- Facility Management:Building operations teams assuming maintenance responsibility. United States healthcare systems unbundle DAS maintenance into standalone multi-year service agreements.
- Security Agencies:Private and public security operations centers. German financial district buildings engage these users for converged safety and commercial network planning.
- Infrastructure Operators:Airport, transit, and utility authorities. These operators consolidate procurement around fewer certified integrators capable of bundled code compliance.
- Safety Consultants:Third-party compliance and design advisors. Japanese smart building developments rely on these advisors for METI incentive qualification.
Specification authority rests with First Responders. Contracting authority is shifting toward Facility Management.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Fiber-optic cable manufacturing concentrates in Japan and Germany, anchoring component supply chains for distributed antenna infrastructure across three continents. Regulatory mandates in these localities cascade through procurement specifications worldwide.
United States
FirstNet interoperability requirements and bundled NFPA 1221-IFC 510 enforcement drive retrofit cycles in legacy commercial towers. FCC Part 90 mandates eliminate grandfathered exemptions for in-building coverage. Dallas-Fort Worth and Houston construction corridors concentrate certified BICSI technician pools for multi-site healthcare rollouts.
Germany
Frankfurt and Munich financial districts accelerate passive-to-hybrid DAS conversions under BNetzA indoor emergency communication tightening. REACH substance restrictions and RoHS 3 compliance deadlines force component requalification. Berlin administrative centers anchor critical infrastructure upgrade demand for government facility mandates.
Japan
Tokyo and Osaka mixed-use developments integrate converged public safety-commercial cellular under METI smart building incentives. AI-powered RF optimization platforms deploy at Narita and Haneda aviation authorities for crowd density management. Kanto region manufacturing clusters supply precision RF connectors to regional integrators.
United Kingdom
Ofcom spectrum licensing frameworks shape indoor coverage requirements for London high-rise commercial complexes. CE marking obligations align with evolving FirstNet-equivalent interoperability standards. Southeast England educational institutions consolidate multi-site procurement around certified fire code compliance integrators.
Global Public Safety in Building Wireless Das System Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue cloud-based RF analytics and AI-powered optimization software. The vendor base clusters around three strategic archetypes: cable and connectivity heritage players, radio access network specialists, and optical backbone fabricators. Consolidation pressures favor certified integrators capable of bundled NFPA 1221 and IFC 510 code compliance. Dominant competitive moves include strategic partnerships with facilities management platforms and geographic expansion into METI-incentivized Japanese developments.
Within the connectivity heritage tier, CommScope Inc. and Corning Incorporated exemplify scale-driven positioning through fiber-fed infrastructure deployment. TE Connectivity Ltd. occupies a specialist position in precision RF interconnect systems. Ericsson represents radio access network expertise ported into public safety spectrum blocks. These anchors collectively illustrate how technical lineage shapes competitive differentiation in multi-code compliance environments.
| Leading Market Players |
|---|
| CommScope Inc. |
| Corning Incorporated |
| TE Connectivity Ltd. |
| Ericsson |
| Nokia Corporation |
| Cisco Systems Inc. |
| SOLiD Technologies LLC |
| Advanced RF Technologies Inc. |
| Zinwave Limited |
| Others |
Supply & Pricing Matrix
FirstNet interoperability mandates in United States high-rise commercial towers are forcing building owners toward certified integrators capable of bundled NFPA 1221 and IFC 510 compliance, compressing vendor selection and elevating pricing power for qualified suppliers while squeezing margins on non-compliant hardware.
Pricing Analysis
Warranty and service bundling now separates premium-tier integrators from commodity hardware vendors. Project-based pricing dominates, with differentiation driven by BICSI certification level and multi-year SLA coverage. Cost compression in passive DAS tiers is intensifying because FirstNet multi-band requirements render legacy architectures non-compliant. Facility management teams in United States healthcare systems show highest price sensitivity, while airport authorities demonstrate lowest sensitivity due to mission-critical reliability thresholds.
Supply Chain Analysis
Dual-sourcing requirements for fiber-optic components and precision RF connectors mandate multi-supplier qualification across United States, German, and Japanese manufacturing clusters. Specialized low-loss coaxial cable draws from concentrated Asian production bases, creating single-source vulnerability for project timelines. Distribution runs through certified integrator networks capable of bundled code compliance rather than direct OEM channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a cost-of-compliance story where FCC Part 90 mandates and bundled NFPA 1221-IFC 510 enforcement create a barrier-to-entry moat protecting certified integrators from unqualified competitors.
For Market Incumbents: Hedge against passive DAS obsolescence by accelerating hybrid architecture R&D and securing backward integration into fiber-optic component supply. Cloud-based RF analytics platforms from emerging software entrants threaten recurring revenue streams; defend through exclusive facilities management partnerships in United States healthcare systems. For New Entrants and Emerging Players: METI smart building incentives in Japan open a window for converged public safety-commercial cellular DAS in Tokyo and Osaka mixed-use developments. Target digital DAS remote monitoring as the most penetrable segment, with AI-powered RF optimization as the go-to-market angle for stadium and airport authorities. For Investors and Strategic Acquirers: The window for entry favors certified integrators with bundled NFPA 1221 and IFC 510 compliance capabilities. Long-term viability rests on consolidation plays in fragmented regional markets. Watch BNetzA enforcement tightening in Germany as the inflection indicator for European passive-to-hybrid conversion velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Certified Integrator Acquisition | Bundled NFPA 1221 and IFC 510 compliance capabilities compress vendor selection to qualified players. |
| AI-Powered RF Optimization Platform Launch | Automation of real-time power balancing eliminates manual drive-test cycles for stadium operators. |
| Backward Integration into Fiber-Optic Components | Captive supply of low-loss cable insulates project timelines from Asian manufacturing volatility. |
| Converged DAS Architecture Development | METI incentives in Japan reward combined public safety and commercial cellular infrastructure. |
| Multi-Year Service Agreement Expansion | Standalone SLAs with United States healthcare systems separate operational budgets from capital accounting. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with DAS system integrators, BICSI-certified technicians, facilities management directors, and FCC regulatory affairs specialists combined with NFPA code documentation, FCC Part 90 enforcement records, and BNetzA spectrum licensing databases. Bottom-up project pipeline assessment and top-down infrastructure spend estimates were triangulated to validate market sizing.
Granularity-level modeling addressed system type, deployment environment, and end-user archetype across the projection horizon. Active, passive, hybrid, and digital DAS architectures were modeled separately with carrier aggregation capability and upgrade pathway assumptions. CAGRs were derived from installed base replacement cycles and new build penetration rates, incorporating FirstNet band expansion timelines and sub-6 GHz spectrum reallocation pathways as industry-specific forecast inputs.
The model assumes a particular technology adoption path; alternative pathways for digital DAS and AI-powered RF optimization would alter the outlook if cloud-based platforms displace traditional hardware faster than projected. Deviation in FCC enforcement intensity or BNetzA regulatory timelines would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Public Safety
Europe Public Safety Market
Public Safety
Public Safety Drones Market
Public Safety
Public Safety in-Building Wireless Distributed Antenna System (DAS) Market
Public Safety
AI for Public Security and Safety Market
Public Safety
Crime Risk Report Market
Public Safety
Outdoor Public Safety Market
Public Safety
Global IoT for Public Safety Market
Public Safety
Latin America Public Safety Market
Public Safety
Global Public Safety Analytics Market
Public Safety
Middle East Crime and Combat Market
Public Safety
Europe Public Infrastructure Safety Market
Public Safety
US Mass Notification Systems Market
Public Safety
North America Road Safety Market
Public Safety
Safe City Market
Public Safety
Voice Evacuation Systems Market
Public Safety
Global Public Safety Solution Market