
 Cheetah Friction Reduction Technologies Market | 2026-2036
Cheetah Friction Reduction Technologies Market Size, Share, and Industry Trends Forecast 2026-2036
Cheetah Friction Reduction Technologies Market Insights
Industrial automation firms is collapsing as the fastest-growing buyer archetype for cheetah friction reduction systems, overtaking traditional energy producers in procurement volume. BASF SE leverages its polymer chemistry portfolio to supply advanced surface coating formulations for precision instruments. Afton Chemical Corporation anchors North American supply chains with additive packages tailored to heavy machinery hydrodynamic systems. Lubrizol Corporation differentiates through captive R&D on elastohydrodynamic lubricants for wind turbine gearboxes.
Cheetah friction reduction technologies encompass engineered systems and material treatments that minimize mechanical contact losses through hydrodynamic film formation, magnetic levitation suspension, or nanostructured surface modification with coefficients below 0.05 under rated load conditions. These technologies serve critical industrial functions including energy conservation, component longevity extension, and operational precision maintenance in rotating and reciprocating machinery. Surface coating technologies occupy the broadest installed base due to retrofit compatibility and lower capital barriers, while magnetic levitation represents the fastest-expanding margin pool driven by aerospace and precision instrument demand. Hydrodynamic systems retain mature dominance in marine propulsion and heavy machinery where fluid film stability under variable load remains non-negotiable.
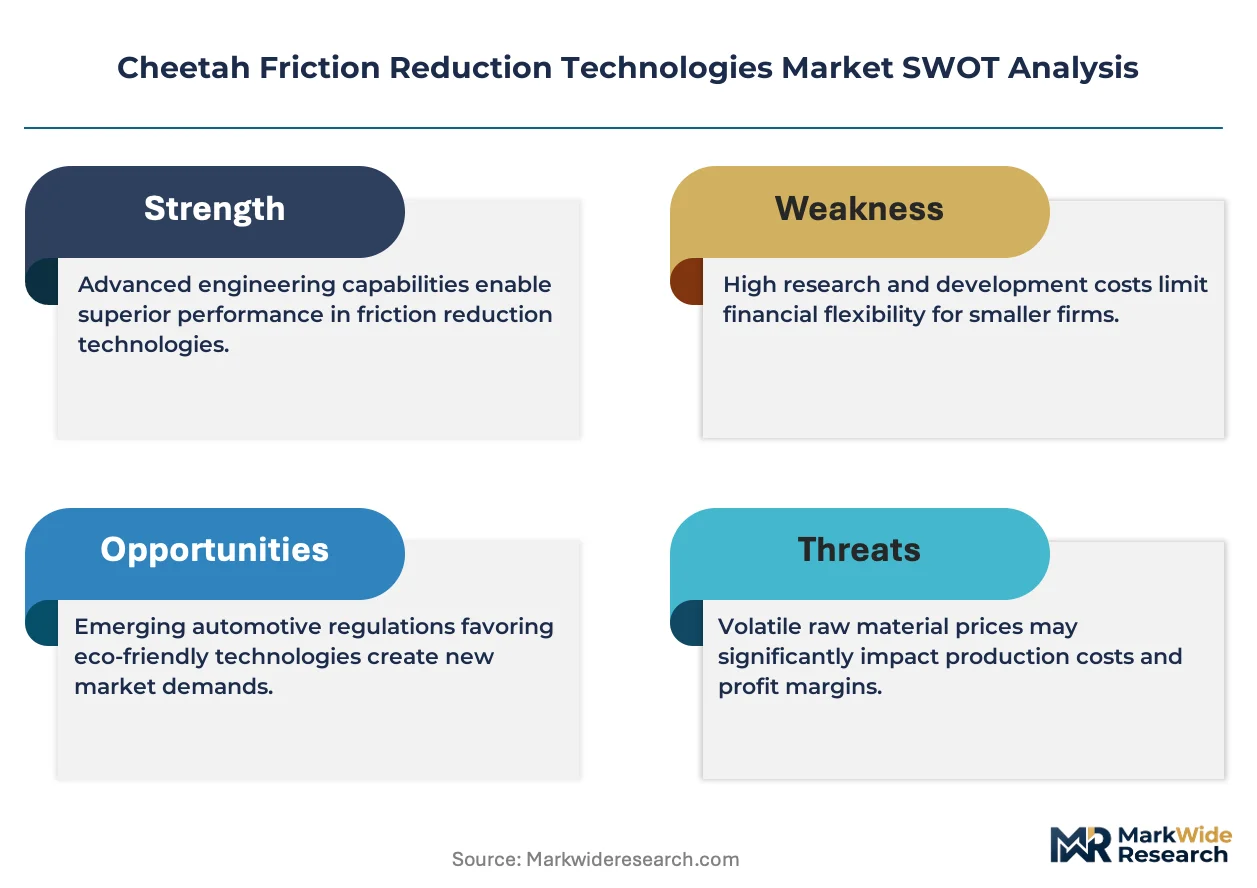
EPA regulations in the United States restrict volatile organic compound emissions from lubricant formulations, compelling reformulation of thermal and electrostatic friction reduction chemistries. REACH and the EU Green Deal in Europe mandate substance registration and carbon footprint disclosure across coating supply chains, raising compliance costs for non-European suppliers. The F-Gas Regulation further constrains certain thermal management fluids used in friction reduction systems. Stakeholders must monitor regulatory divergence between jurisdictions to determine whether centralized or regionalized product certification strategies minimize market access friction.
Market Dynamics
REACH compliance deadlines and EPA volatile organic compound restrictions are compressing formulation timelines for coating suppliers while aerospace constructors accelerate magnetic levitation procurement for turbine applications. This dual pressure from regulatory tightening and specification escalation is restructuring competitive position.
Growth Catalysts
- REACH substance registration mandates:European coating suppliers face mandatory carbon footprint disclosure and substance registration under ECHA frameworks, accelerating reformulation toward compliant nanostructured surface treatments.
- Aerospace turbine applications:Magnetic levitation systems for gearbox and turbine assemblies are displacing conventional bearing assemblies in precision manufacturing clusters across Germany and France.
- Wind turbine gearbox demand:Elastohydrodynamic lubricant specifications for offshore wind installations are tightening performance requirements for hydrodynamic film stability under variable load conditions.
Market Restraints
- Perfluorinated compound substitution threat:F-Gas Regulation constraints on thermal management fluids are forcing abandonment of certain electrostatic friction reduction chemistries with no mature replacement at equivalent performance.
- Rare earth magnet supply concentration:Magnetic levitation system manufacturers depend on concentrated neodymium processing capacity concentrated in China, exposing aerospace constructors to price volatility and export restriction risk.
- Capital intensity of retrofit compatibility:Surface coating application equipment for existing machinery fleets requires specialized application infrastructure that small and mid-sized precision manufacturers cannot internally finance.
Strategic Opportunities
- India precision manufacturing expansion:PLI scheme incentives for automotive component production are creating specification demand for friction reduction systems in emerging domestic supply chains.
- Marine propulsion electrification:Hydrodynamic system integration with battery-electric and hybrid propulsion architectures opens retrofit and newbuild specification channels for fluid film stability technologies.
- ISO 14001 certification convergence:Environmental management system certification is becoming a gatekeeping requirement for supplier qualification in German automotive R&D procurement, favoring coating suppliers with documented life-cycle assessment capabilities.
Industry Challenges
- Tribology specialist talent scarcity:Universities in Germany and the United States are producing insufficient graduates with combined surface chemistry and mechanical engineering training to staff R&D functions at coating formulators.
- Multi-jurisdiction certification timeline compression:Simultaneous EPA pre-manufacture notification, REACH registration, and state-level volatile organic compound approval processes extend product launch cycles by 18-24 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cheetah Friction Reduction Technologies Market |
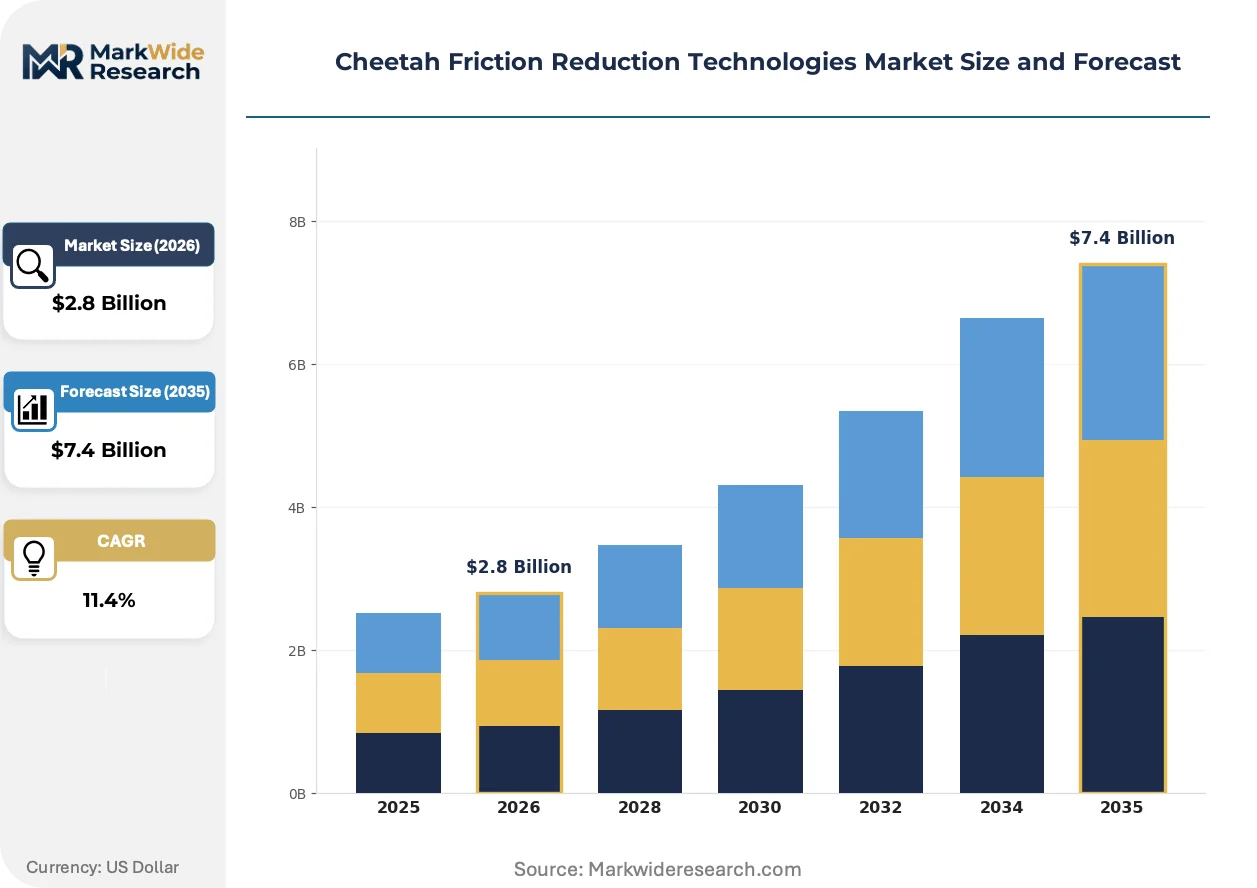
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $7.4 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Hydrodynamic, Magnetic Levitation, Surface Coating, Elastohydrodynamic, Thermal, Electrostatic Application: Power Transmission Systems, Wind Turbine Gearboxes, Aerospace Components, Precision Instruments, Marine Propulsion, Heavy Machinery End User Industry: Manufacturing Plants, Aerospace Constructors, Energy Producers, Marine Operators, Industrial Automation Firms Deployment: Onboard Systems, Stationary Machinery, Portable Equipment, Automated Production Lines, Experimental Setups |
| Companies Covered | BASF SE, Afton Chemical Corporation, Lubrizol Corporation, Croda International PLC, Chevron Corporation, Royal Dutch Shell, ADEKA CORPORATION, BRB International BV, LANXESS, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cheetah Friction Reduction Technologies Market Trends and Innovations
Active friction reduction research is pivoting from incremental lubricant additive improvement toward structural reconfiguration of contact mechanics through levitation and surface engineering. This shift is compressing traditional hydrodynamic dominance in high-value precision applications.
Graphene-infused nanocoatings are decomposing the historical trade-off between wear resistance and coefficient of friction in precision instrument bearings. Medical device manufacturers in Switzerland and semiconductor fabrication equipment constructors in Japan are specifying these formulations for cleanroom-compatible rotary stages. The technology is decomposing incumbent diamond-like carbon coating margins by delivering sub-0.03 friction coefficients without vacuum deposition infrastructure.
EPA volatile organic compound emission limits under the Clean Air Act are compelling reformulation of thermal friction reduction chemistries across industrial lubricant categories. Formulators must eliminate specific solvent carriers while maintaining film formation kinetics, driving R&D expenditure toward waterborne and reactive diluent alternatives. Heavy machinery hydrodynamic system suppliers in the United States are responding by qualifying European-developed base fluid portfolios that preempt anticipated state-level restrictions.
Specification authority is migrating from maintenance procurement functions to engineering design teams with embedded tribology expertise. Automotive transmission and aerospace gearbox constructors are unbundling lubricant selection from historical supplier relationships, instead issuing performance-based specifications that qualified coating and additive suppliers must bid against directly. This pattern is most visible in German precision manufacturing clusters where OEMs consolidate supplier panels around certified formulation partners.
Cheetah Friction Reduction Technologies Market Segmentation
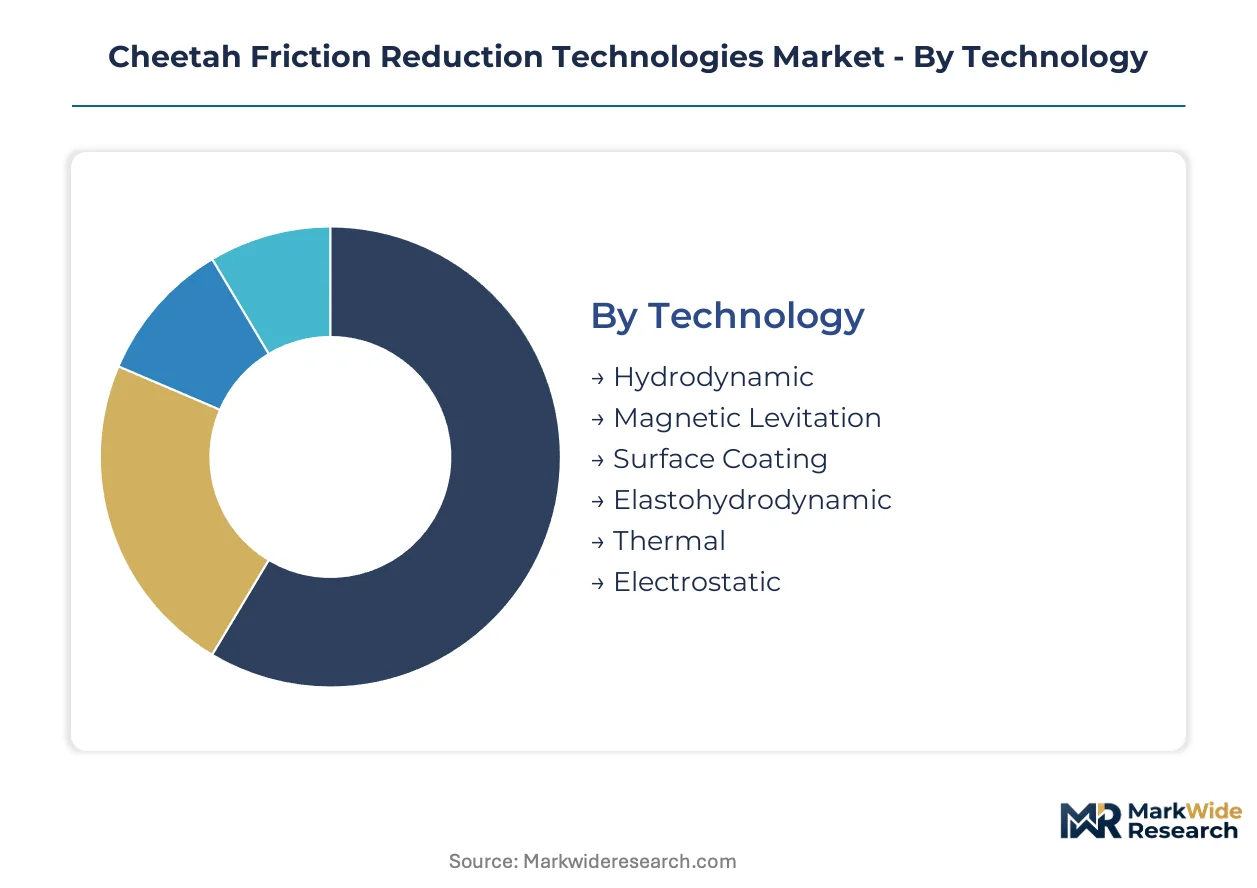
Cheetah friction reduction technologies fragment across four dimensions that determine procurement patterns and margin structures. Technology type governs capital intensity and retrofit feasibility. Application and end-user concentration in Germany, France, and Japan drives specification divergence. Deployment mode shapes service revenue attachment and lifecycle economics.
Technology:
Domestic demand concentrates in Germany and France for precision manufacturing applications, while export-led growth channels through Japanese semiconductor equipment and US aerospace supply chains.
- Surface Coating:Nanostructured treatments including diamond-like carbon and graphene-infused formulations achieve sub-0.05 friction coefficients without vacuum infrastructure. German automotive R&D centers in Stuttgart and Munich specify these for transmission components requiring retrofit compatibility.
- Magnetic Levitation:Neodymium-based suspension systems eliminate mechanical contact entirely. Aerospace constructors in Toulouse and Hamburg accelerate procurement for turbine and gearbox assemblies where precision maintenance is non-negotiable.
- Hydrodynamic:Fluid film systems dominate marine propulsion and heavy machinery where load variability demands established stability.
- Elastohydrodynamic:Wind turbine gearbox specifications in the North Sea and Baltic offshore zones tighten performance requirements for lubricant formulators.
- Thermal:Phase-change and thermoelectric systems face EPA volatile organic compound reformulation pressure.
- Electrostatic:F-Gas Regulation constraints force abandonment of certain chemistries with no mature replacement.
Surface Coating holds the largest share; momentum sits with Magnetic Levitation.
Application:
Cost tier segmentation separates premium precision applications from volume-driven heavy machinery installations.
- Aerospace Components:Turbine and gearbox assemblies demand magnetic levitation for operational precision maintenance. French and German aerospace clusters issue performance-based specifications that unbundle lubricant selection from historical supplier relationships.
- Wind Turbine Gearboxes:Offshore installations in the North Sea require elastohydrodynamic lubricants with hydrodynamic film stability under variable load. Maintenance procurement functions here retain specification authority.
- Power Transmission Systems:Automotive transmission constructors consolidate supplier panels around certified coating partners.
- Precision Instruments:Swiss medical device manufacturers and Japanese semiconductor fabricators specify graphene-infused nanocoatings for cleanroom-compatible rotary stages.
- Marine Propulsion:Battery-electric and hybrid architectures open retrofit channels for fluid film stability technologies.
- Heavy Machinery:Hydrodynamic dominance persists where capital barriers block coating infrastructure investment.
Aerospace Components commands premium pricing; Wind Turbine Gearboxes is expanding most quickly.
End User Industry:
Customer type bifurcation separates specification authority between engineering design teams and maintenance procurement functions.
- Industrial Automation Firms:These buyers are collapsing procurement volume fastest, overtaking traditional energy producers. German precision manufacturing clusters embed tribology expertise directly into design teams.
- Aerospace Constructors:Engineering-led specification unbundles lubricant selection from historical relationships. Toulouse and Hamburg facilities issue direct performance-based tenders to qualified coating suppliers.
- Manufacturing Plants:Maintenance procurement retains authority for retrofit surface coating applications.
- Energy Producers:Wind farm operators in the North Sea drive elastohydrodynamic lubricant demand.
- Marine Operators:Newbuild and retrofit electrification creates specification channels for hydrodynamic integration.
Aerospace Constructors anchors specification authority; Industrial Automation Firms is gaining share fastest.
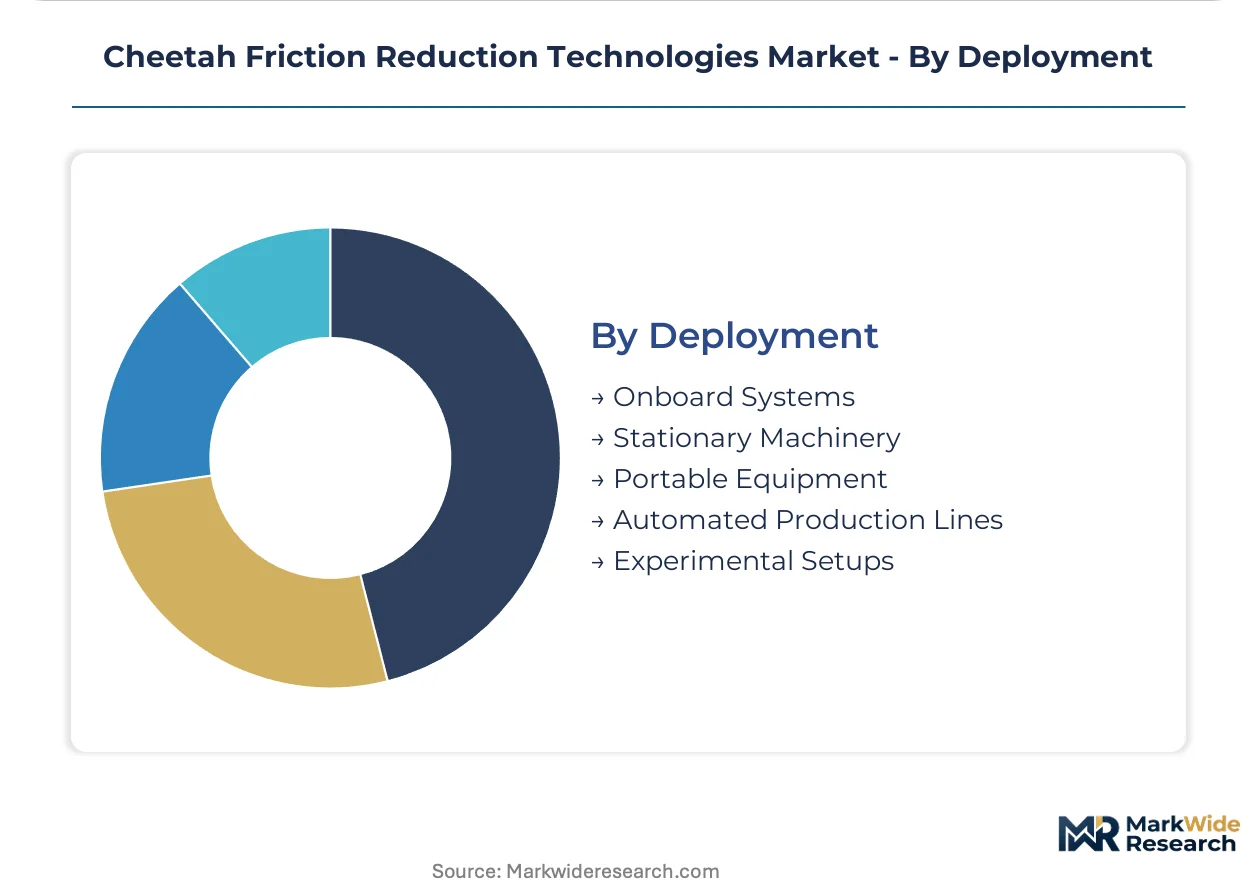
Deployment:
Volume concentration favors stationary machinery where coating infrastructure amortizes across extended production runs.
- Stationary Machinery:Precision manufacturing lines in Germany and Switzerland deploy surface coating infrastructure for high-volume component processing. Capital intensity here blocks mid-sized manufacturer entry.
- Automated Production Lines:Continuous processing environments favor hydrodynamic and elastohydrodynamic systems with integrated fluid management.
- Onboard Systems:Aerospace and marine applications demand magnetic levitation and thermal management with weight constraints.
- Portable Equipment:Field maintenance applications favor pre-applied coating formulations and cartridge-based lubricant systems.
- Experimental Setups:R&D facilities in German automotive centers test graphene-infused nanocoatings before production qualification.
Stationary Machinery dominates installed base; Automated Production Lines shows steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German precision manufacturing clusters export surface coating specifications to aerospace constructors in Toulouse and Hamburg, while Japanese semiconductor fabricators drive graphene-infused nanocoating demand across Asian supply chains.
Germany
Automotive R&D centers in Stuttgart and Munich specify retrofit-compatible surface coatings for transmission components. REACH substance registration under ECHA frameworks mandates carbon footprint disclosure across coating supply chains. Precision manufacturing clusters in Baden-Württemberg and Bavaria consolidate supplier panels around certified formulation partners with embedded tribology expertise.
United States
Heavy machinery hydrodynamic system suppliers face EPA volatile organic compound emission limits under the Clean Air Act. State-level restrictions in California and Texas preemptively drive qualification of European-developed base fluid portfolios. Aerospace constructors in Seattle and Wichita accelerate magnetic levitation procurement for turbine assemblies.
Japan
Semiconductor fabrication equipment constructors specify graphene-infused nanocoatings for cleanroom-compatible rotary stages. METI industrial standards guide performance-based lubricant specifications in precision instrument manufacturing. Manufacturing concentration in the Chubu region around Nagoya drives demand for sub-0.03 friction coefficient formulations.
France
Aerospace constructors in Toulouse issue direct performance-based tenders for magnetic levitation systems in gearbox assemblies. EU Green Deal carbon footprint disclosure requirements raise compliance costs for non-European coating suppliers. The F-Gas Regulation constrains thermal management fluids used in certain friction reduction chemistries.
India
PLI scheme incentives for automotive component production create specification demand for friction reduction systems in emerging domestic supply chains. Central government production-linked incentive frameworks accelerate precision manufacturing capacity buildout. Industrial corridors in Maharashtra and Gujarat attract coating suppliers seeking qualified formulation partnerships.
Cheetah Friction Reduction Technologies Market Competitive Landscape
Player mix skews toward diversified chemical conglomerates with polymer chemistry portfolios, creating a tiered structure where formulation capabilities separate premium-positioned suppliers from commodity additive packagers. Strategic archetypes include surface coating specialists with nanostructured treatment expertise, magnetic levitation system integrators dependent on rare earth supply chains, and hydrodynamic fluid formulators serving marine and heavy machinery segments. Competitive moves concentrate on strategic partnerships with aerospace constructors and geographic expansion into Indian precision manufacturing corridors.
Among European-based chemical conglomerates, BASF SE and LANXESS occupy positions within the diversified formulation tier, leveraging polymer chemistry portfolios to supply advanced surface treatments. Afton Chemical Corporation represents the North American additive packaging archetype, anchoring regional supply chains with hydrodynamic system expertise. These three exemplify how regulatory compliance capabilities and certified formulation partnerships determine supplier qualification in German automotive R&D procurement.
| Leading Market Players |
|---|
| BASF SE |
| Afton Chemical Corporation |
| Lubrizol Corporation |
| Croda International PLC |
| Chevron Corporation |
| Royal Dutch Shell |
| ADEKA CORPORATION |
| BRB International BV |
| LANXESS |
| Others |
Pricing and Supply Chain Analysis
Long-term offtake agreements between aerospace constructors and magnetic levitation system suppliers lock in neodymium magnet supply access while freezing price visibility across multi-year procurement cycles. This contract structure shields German and French precision manufacturing clusters from rare earth price volatility but transfers inventory risk downstream to coating formulators facing REACH carbon footprint disclosure mandates.
Pricing Analysis
Next-generation graphene-infused nanocoatings command premium positioning against incumbent diamond-like carbon treatments, while legacy hydrodynamic fluid systems compete on volume scale. Three-tier pricing structure separates aerospace-grade magnetic levitation assemblies from industrial automation surface coatings and commodity marine lubricant formulations. Cost compression in thermal friction reduction chemistries intensifies because EPA volatile organic compound reformulation eliminates high-margin solvent carriers. Industrial automation firms exhibit highest price sensitivity as procurement volume concentrates, while aerospace constructors prioritize performance certification over unit economics.
Supply Chain Analysis
Extended lead times for neodymium magnet processing stretch magnetic levitation system delivery schedules to 18-24 months, forcing inventory pre-positioning. Supply concentrates in China for rare earth magnet processing, Germany for precision coating application equipment, and Japan for graphene nanomaterial synthesis. Formulators depend on fluoropolymer feedstocks, synthetic base oils, and nanostructured carbon additives. Single-source vulnerability in Chinese neodymium refining exposes aerospace supply chains to export restriction risk. Distribution runs through certified formulation partnerships directly to OEM engineering teams, bypassing traditional distributor channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specification authority migration from maintenance procurement to engineering design teams concentrates buyer power among a shrinking panel of certified formulation partners. This consolidation favors incumbents with embedded tribology expertise and documented life-cycle assessment capabilities.
For Market Incumbents: Consolidate supplier panel positions by deepening captive R&D on elastohydrodynamic lubricants for wind turbine applications and securing ISO 14001 certification ahead of German automotive R&D procurement gates. Magnetic levitation system integrators threaten traditional coating margins through performance-based specification displacement. Backward integration into graphene nanomaterial synthesis reduces feedstock cost exposure. For New Entrants and Emerging Players: Differentiate on REACH-compliant nanocoating formulations targeting mid-sized precision manufacturers excluded by capital barriers from surface coating infrastructure investment. India's PLI scheme corridors in Maharashtra and Gujarat offer the most penetrable geography for qualified formulation partnerships. A direct technical sales model embedding tribology specialists with automotive component producers accelerates specification adoption. For Investors and Strategic Acquirers: Capital is best deployed toward surface coating specialists with documented carbon footprint disclosure capabilities and existing German automotive R&D procurement relationships. Long-term viability hinges on regulatory compliance infrastructure rather than formulation chemistry alone. Watch for F-Gas Regulation expansion signals as inflection indicators for thermal friction reduction chemistry abandonment rates.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Graphene Synthesis | Captive nanomaterial supply secures sub-0.03 friction coefficient formulation margins against diamond-like carbon competitors. |
| REACH Registration Acceleration | ECHA substance registration ahead of compliance deadlines locks in European coating supply chain access before competitor qualification. |
| PLI Scheme Partnership in India | Maharashtra and Gujarat industrial corridor presence captures automotive component specification demand from emerging domestic supply chains. |
| Magnetic Levitation System Certification | Aerospace constructor qualification in Toulouse and Hamburg opens turbine and gearbox assembly procurement channels. |
| ISO 14001 Life-Cycle Assessment Documentation | Environmental management certification satisfies German automotive R&D procurement gatekeeping requirements for supplier panel consolidation. |
Research Methodology
A standing panel of tribology R&D directors, aerospace procurement engineers, coating formulator technical leads, and wind farm maintenance managers provided ongoing calibration across primary interview cycles. Secondary validation drew from ECHA REACH registration databases, EPA Clean Air Act enforcement records, customs trade data for fluoropolymer feedstocks, and SEC filings from diversified chemical conglomerates. Bottom-up segment sizing triangulated against top-down macroeconomic indicators across the analysis window.
Consistency checks against external benchmarks validated volume and value outputs against IEA offshore wind deployment trajectories, German automotive production indices, and aerospace OEM capital expenditure disclosures. The analytical framework modeled technology type, application end-use, deployment mode, and regional regulatory cluster across the projection horizon. CAGRs derived from segment-level growth rate convergence weighted by installed base replacement cycles and specification migration patterns from hydrodynamic to magnetic levitation systems.
The analysis sits within stated boundaries; outcomes outside sustained rare earth magnet supply access or accelerated EPA state-level volatile organic compound adoption would require recalibration. Forecasts reflect assumptions regarding REACH compliance timeline adherence and aerospace magnetic levitation procurement acceleration. Rare earth export restrictions, F-Gas Regulation expansion, or tribology talent scarcity shocks could revise trajectory assumptions. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
Automotive Thermal Systems Market
Automotive Parts
France Automotive Pneumatic Actuators Market
Automotive Parts
Global Automotive Muffler Tip Market
Automotive Parts
Global Automotive Hydraulic Brake Market
Automotive Parts
Malaysia Passenger Vehicles Lubricants Market
Automotive Parts
Global Automotive Flywheel Market
Automotive Parts
Europe Motorcycle Parts and Accessories Market
Automotive Parts
Electric Vehicle Brake Pad Market
Automotive Parts
Full Synthetic Motor Oil Market
Automotive Parts
Automotive Rear Spoiler Market
Automotive Parts
Russia Automotive Actuators Market
Automotive Parts
Automotive Canister Market
Automotive Parts
South Korea Passenger Vehicles Lubricants Market
Automotive Parts
Automotive Engine Oil Coolers Market
Automotive Parts
Electromagnetic Clutches Market
Automotive Parts
Two-Wheeler Lubricants Market