
 US Automotive Parts Magnesium Die Casting Market | 2026-2036
US Automotive Parts Magnesium Die Casting Market Size, Share, and Industry Trends Forecast 2026-2036
US Automotive Parts Magnesium Die Casting Market Analytics
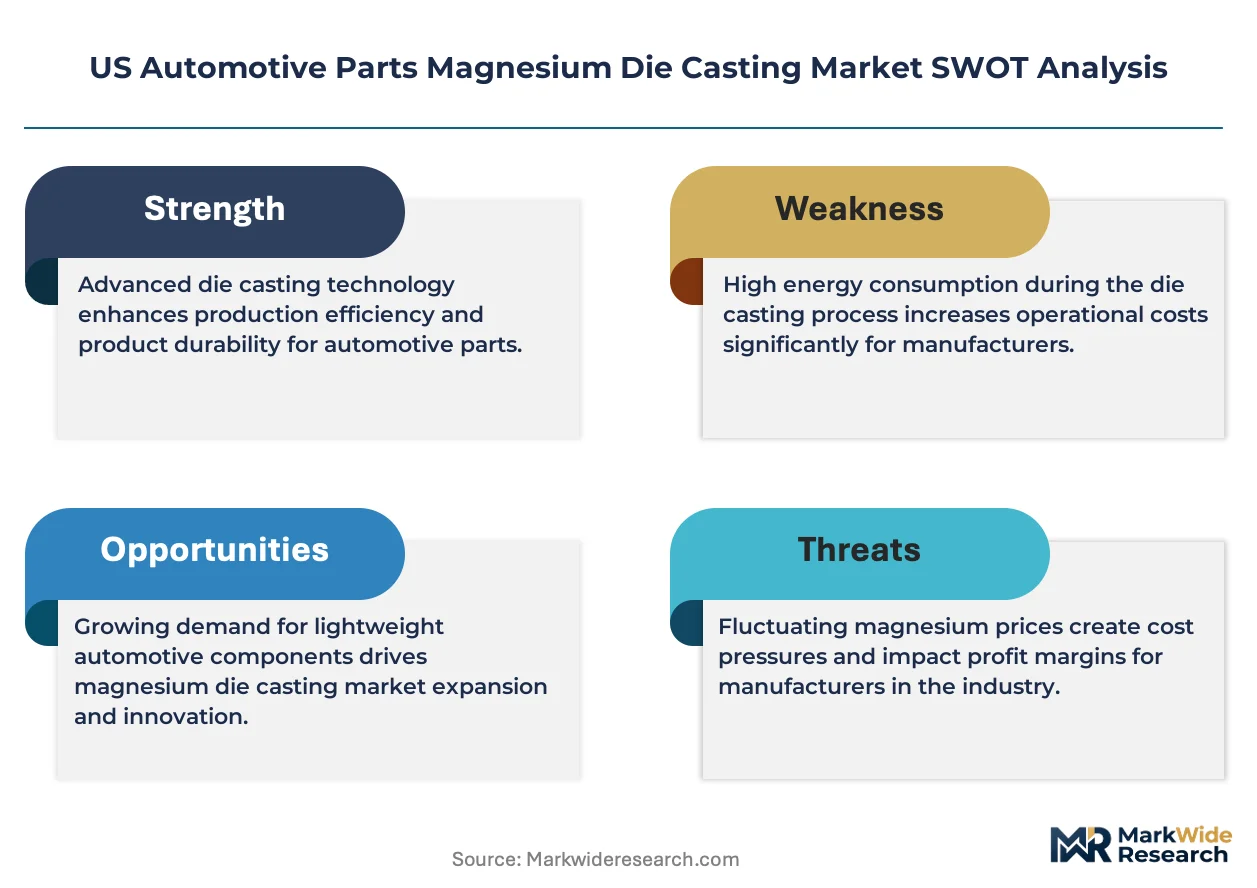
Domestic magnesium alloy supply is hardening around the Great Lakes manufacturing belt. Meridian Lightweight Technologies leverages captive hot-chamber capacity to dominate structural component programs for Detroit-based OEMs. Gibbs Die Casting Group anchors its position through backward integration into magnesium ingot sourcing. Shiloh Industries differentiates via high-pressure thin-wall casting expertise for transmission housings.
Automotive parts magnesium die casting employs AZ91D and AM60B alloys in hot-chamber and cold-chamber processes to produce net-shape components with density one-quarter that of steel, primarily serving vehicle weight reduction mandates. Engine components command the deepest margin pools due to thermal-load specifications and qualification barriers. Structural components within the lightweight structures application represent the fastest-expanding demand segment as OEMs pursue platform-level mass reduction. Wheels remain a mature category with stable aftermarket replenishment cycles.
NHTSA Corporate Average Fuel Economy standards and EPA tailpipe emissions frameworks directly incentivize gram-per-mile reductions through magnesium substitution. OSHA casting facility safety regulations and ASTM B94 alloy specifications shape shop-floor compliance and material certification pathways. Stakeholders must monitor alloy price volatility against aluminum substitution economics and evolving EV platform architectures that redefine structural load paths.
Market Dynamics
OEM platform consolidation around electric vehicle architectures is compressing traditional transmission housing demand while amplifying structural magnesium applications for battery enclosures and crash management systems.
Growth Catalysts
- NHTSA CAFE Standards:Gram-per-mile fuel economy mandates force automakers toward magnesium substitution in powertrain and chassis components. The regulatory pressure intensifies through model year 2032.
- EV Structural Load Path Redesign:Battery pack integration demands new lightweight crash structures. Magnesium die castings replace stamped steel assemblies in front and rear subframes.
- AZ91D Alloy Process Refinement:Hot-chamber die casting advances reduce porosity rates below three percent. Improved yield rates expand design freedom for thin-wall transmission cases.
Market Restraints
- Magnesium Ingot Price Volatility:Primary magnesium pricing swings against aluminum LME benchmarks create substitution uncertainty. Die casters face margin compression during alloy spikes.
- Great Lakes Supply Concentration:Over seventy percent of domestic hot-chamber capacity clusters within Michigan and Ohio. Single-region weather disruptions threaten national component supply.
- OSHA Pyrophoric Material Handling:Molten magnesium combustion risk mandates costly facility investments. Small foundries struggle with ventilation and fire suppression compliance.
Strategic Opportunities
- Texas EV Manufacturing Corridor:Tesla, Rivian, and emerging OEMs anchor new assembly plants outside traditional Midwest supply networks. Greenfield die casting investments can capture platform-level sourcing decisions.
- Thixomolding Process Convergence:Semi-solid casting technology merges with conventional high-pressure methods. Hybrid production lines serve both structural and cosmetic automotive grades.
- IRA Clean Vehicle Tax Credits:Domestic content requirements incentivize reshoring of magnesium component supply. Casters qualifying under assembly and battery mineral thresholds gain preferential OEM access.
Industry Challenges
- Hot-Chamber Technician Scarcity:Specialized die maintenance and process engineering expertise concentrates among retiring Midwest workforces. Training pipelines lag replacement demand.
- ASTM B94 Certification Timelines:New alloy qualification for safety-critical components requires eighteen to twenty-four month validation cycles. Program delays risk design freeze misses.
- Legacy ERP Integration Friction:Foundry scheduling systems struggle with OEM demand signal transparency. Real-time production adjustments remain manual across supplier tiers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | US Automotive Parts Magnesium Die Casting Market |
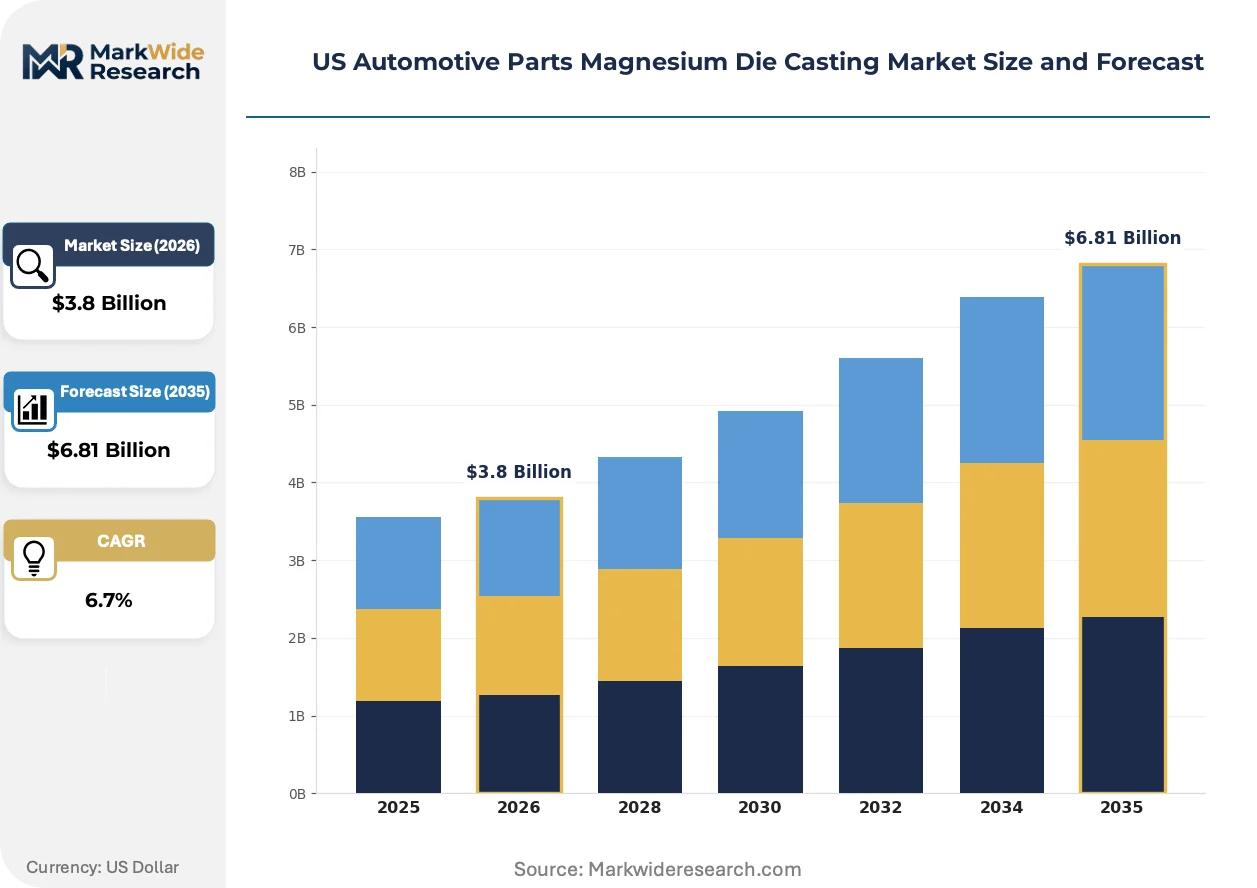
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $6.81 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Engine Components, Transmission Housings, Chassis Parts, Wheels Application: Lightweight Structures, Structural Components, Performance Parts, Safety Systems Delivery Mode: Direct Shipping, Retail Distribution, E-commerce, Bulk Supply End User: OEMs, Aftermarket Suppliers, Tier-1 Suppliers, Vehicle Assemblers |
| Companies Covered | Meridian Lightweight Technologies, George Fischer AG, Shiloh Industries, Pace Industries, Gibbs Die Casting Group, Dynacast, Kinetic Die Casting Company, Chicago White Metal Casting Inc., Continental Casting LLC, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
US Automotive Parts Magnesium Die Casting Market Evolving Landscape
Process digitization and alloy formulation advances are compressing development cycles while expanding magnesium's addressable component set beyond traditional transmission and engine applications.
Thixomolding equipment is decentralizing from centralized captive operations toward tiered supplier networks. Tier-1 seating and interior specialists adopt in-house semi-solid capacity for thin-wall structural brackets. The technology is decentralizing quality control and reducing logistics costs for just-in-sequence delivery to assembly plants.
NHTSA's updated side-impact and pedestrian protection protocols tighten crashworthiness thresholds for 2026-2030 model years. Magnesium's specific strength advantages gain priority in front-end module redesigns. Structural die casters in Michigan and Ohio accelerate AM60B alloy development for energy-absorption-optimized geometries.
Fleet procurement departments now mandate lifecycle carbon accounting in supplier scorecards. Magnesium's production emissions disadvantage versus aluminum forces Great Lakes casters to secure renewable electricity contracts and primary metal from low-carbon smelters. The sourcing behavior shift is most visible in California and Washington state fleet mandates driving OEM tier-one requirements.
US Automotive Parts Magnesium Die Casting Market Segmentation
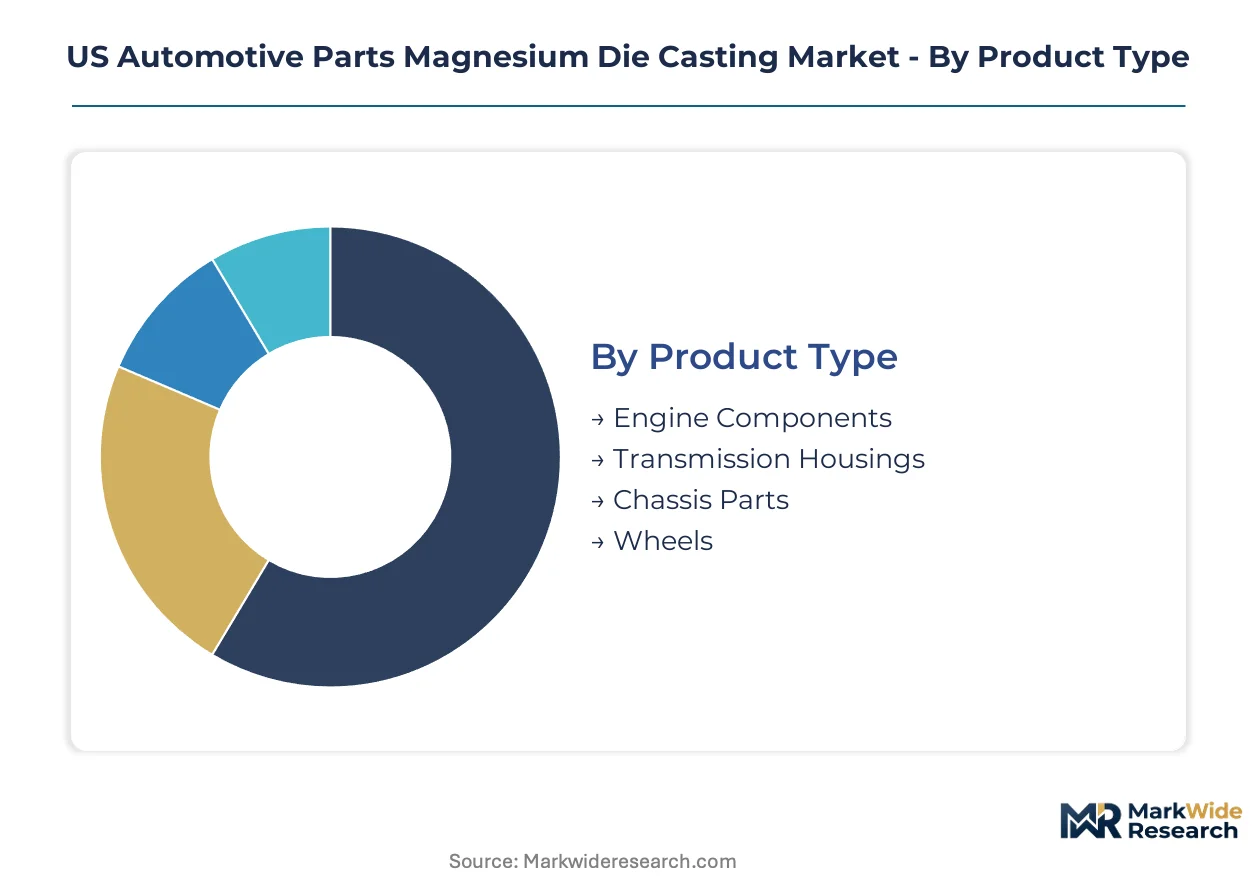
Magnesium die casting segmentation reflects divergent qualification barriers, margin structures, and OEM sourcing protocols across the US automotive supply base. Component geometry, thermal loading requirements, and crashworthiness specifications determine alloy selection and process routing for each segment.
Product Type:
Hot-chamber and cold-chamber process capabilities align with thermal load specifications and wall thickness requirements across powertrain and chassis applications.
- Engine Components:Cylinder head covers, oil pans, and intake manifolds demand AZ91D alloy for creep resistance at elevated temperatures. NHTSA fuel economy mandates concentrate demand in Detroit Three powertrain programs where thermal management specifications are most stringent.
- Transmission Housings:Bell housings and transmission cases utilize AM60B for ductility and vibration damping. OEM platform consolidation around EV architectures is compressing traditional automatic transmission demand while expanding e-axle housing applications.
- Chassis Parts:Steering column brackets and pedal assemblies serve mass reduction targets in ICE and electric platforms alike.
- Wheels:Cast magnesium wheels address performance vehicle and aftermarket segments with stable replenishment cycles.
Mature deployment sits with Wheels. Newer deployment is concentrated in Chassis Parts.
Application:
Functional requirements for crash energy management and structural load bearing create distinct specification tiers across vehicle systems.
- Lightweight Structures:Battery enclosures, seat frames, and closure panels target platform-level mass reduction. Tesla and Rivian Texas assembly plants are driving fastest share gains for structural magnesium in EV skateboard architectures.
- Structural Components:Front and rear subframes, crash management systems, and cross-car beams absorb impact loads. NHTSA side-impact protocol updates for 2026-2030 model years are accelerating AM60B alloy development for energy-absorption-optimized geometries.
- Performance Parts:Suspension links and control arms serve niche motorsport and high-performance street applications.
- Safety Systems:Steering wheel armatures and seatbelt anchor brackets must satisfy FMVSS occupant protection standards.
Volume concentration sits with Structural Components. Specification intensity is climbing fastest in Lightweight Structures.
Delivery Mode:
Supply chain configuration varies with OEM integration depth, inventory velocity requirements, and geographic proximity to assembly plants.
- Direct Shipping:Just-in-sequence delivery from Michigan and Ohio foundries to Detroit Three assembly plants dominates high-volume transmission and engine programs. Great Lakes weather disruptions threaten this concentrated supply network.
- Bulk Supply:Containerized magnesium ingot and machined casting shipments serve tier-1 processor networks with intermediate finishing capabilities.
- Retail Distribution:Aftermarket wheels and performance accessories move through specialty automotive channels.
- E-commerce:Replacement components and small-batch custom castings reach independent repair facilities and enthusiast markets.
Volume scale sits with Direct Shipping. Channel diversification is advancing fastest in E-commerce.
End User:
Procurement authority and technical specification control determine contract structures and qualification timelines across the automotive value chain.
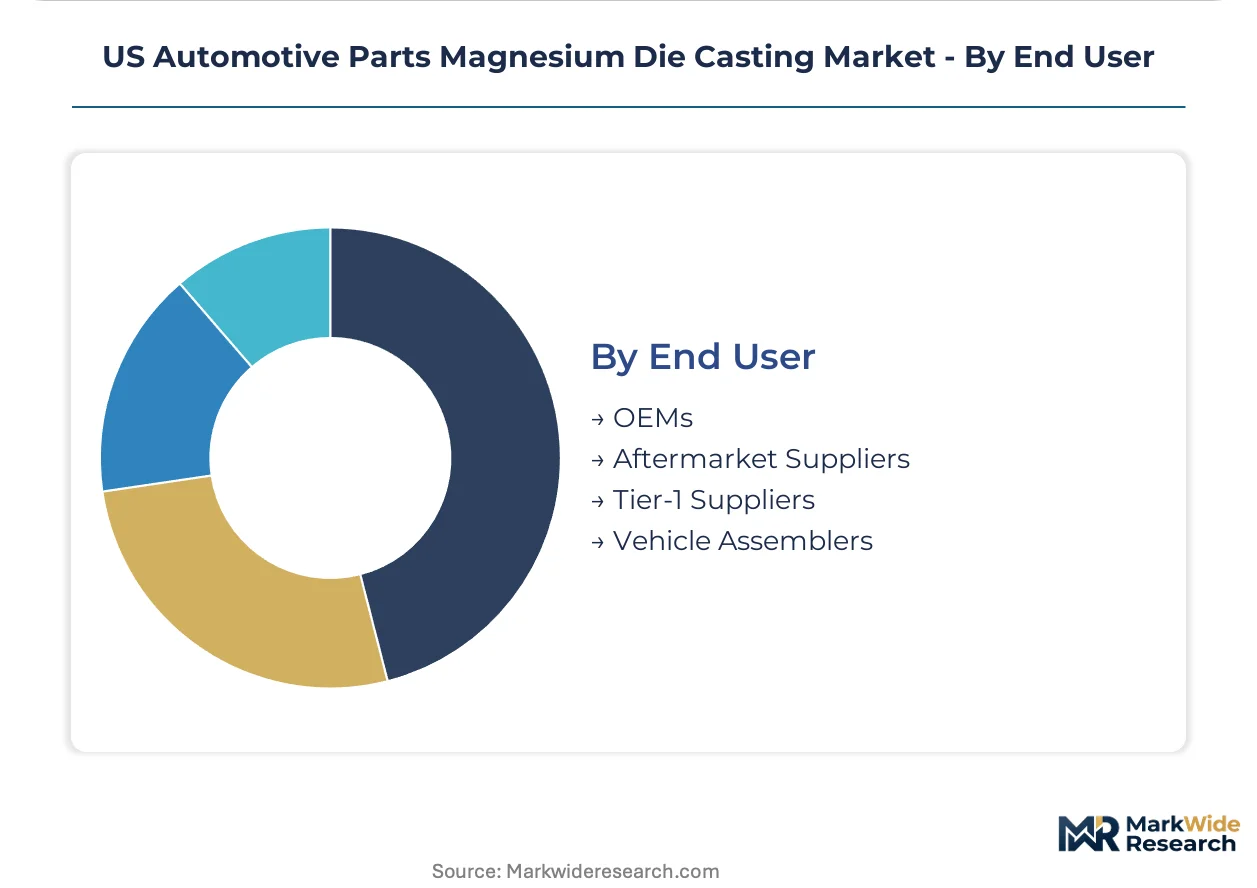
- OEMs:Ford, GM, and Stellantis maintain direct sourcing relationships for safety-critical structural components. IRA Clean Vehicle Tax Credits incentivize domestic content verification through tier-one supply chain audits.
- Tier-1 Suppliers:Seating specialists and interior module integrators adopt in-house thixomolding capacity for thin-wall structural brackets, decentralizing quality control from captive foundry operations.
- Vehicle Assemblers:Tesla, Rivian, and Lucid Motors in Texas and California establish greenfield sourcing relationships outside traditional Midwest supplier networks.
- Aftermarket Suppliers:Wheel distributors and performance parts retailers serve replacement demand with lower qualification barriers than OEM programs.
Contract value sits with OEMs. Procurement relationship formation is expanding fastest among Vehicle Assemblers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Primary magnesium smelting capacity concentrates in Utah and Washington state, anchoring raw material access for Great Lakes die casters. NHTSA fuel economy mandates and EPA tailpipe standards drive demand concentration in traditional automotive manufacturing belts.
Michigan
Detroit Three powertrain programs dominate transmission housing demand for AZ91D and AM60B castings. OSHA pyrophoric material handling regulations govern foundry operations across the state's dense hot-chamber capacity cluster. Meridian Lightweight Technologies and Gibbs Die Casting Group anchor southeastern Michigan's supplier concentration around Sterling Heights and Battle Creek.
Ohio
Transmission case and engine component programs for GM and Stellantis sustain demand in the Toledo-Cleveland corridor. NHTSA CAFE standards through model year 2032 intensify gram-per-mile reduction targets for Ohio-based tier-1 suppliers. Shiloh Industries maintains high-pressure thin-wall casting operations in the state's northwestern manufacturing belt.
Texas
Tesla Gigafactory Texas and Rivian's emerging presence in the Central Texas EV corridor reshape structural magnesium demand for battery enclosures. IRA Clean Vehicle Tax Credits incentivize domestic content verification for Texas-assembled electric vehicles. Greenfield die casting investments target platform-level sourcing decisions outside traditional Midwest supply networks.
Indiana
Subframe and chassis component programs for Toyota and Honda manufacturing operations sustain AM60B demand in the Indianapolis-Lafayette region. Indiana's logistics infrastructure supports just-in-sequence delivery to Detroit Three and Japanese transplant assembly plants. Casting specialists cluster along Interstate 65 to access both Midwest OEM networks and southeastern automotive expansion.
California
State fleet procurement mandates for lifecycle carbon accounting drive low-carbon magnesium sourcing requirements for West Coast vehicle assemblers. CARB tailpipe regulations complement federal EPA standards in accelerating lightweight material substitution. Lucid Motors and emerging EV specialists in the Bay Area establish qualification relationships outside Great Lakes supplier networks.
US Automotive Parts Magnesium Die Casting Market Competitive Landscape
Global majors compete with regional champions across captive hot-chamber capacity and OEM direct-sourcing relationships. The vendor base concentrates among tier-1 automotive suppliers with backward integration into magnesium ingot sourcing and alloy formulation expertise. Three strategic archetypes dominate: captive foundry operations owned by seating and interior specialists, independent high-volume transmission housing specialists, and hybrid thixomolding-capable structural component suppliers. Capacity expansion and strategic partnerships represent the dominant competitive moves as EV platform consolidation reshapes addressable demand.
Among North American-based specialists, Meridian Lightweight Technologies, Gibbs Die Casting Group, and Shiloh Industries occupy positions reflecting distinct process and integration strategies. Meridian exemplifies captive hot-chamber dominance for Detroit-based OEM structural programs. Gibbs Die Casting Group represents backward integration archetypes with upstream magnesium supply control. Shiloh Industries anchors the high-pressure thin-wall specialization tier for transmission housing applications. Swiss-based George Fischer AG and Pace Industries sit within the global multi-process die casting tier serving cross-regional automotive platforms.
| Leading Market Players |
|---|
| Meridian Lightweight Technologies |
| George Fischer AG |
| Shiloh Industries |
| Pace Industries |
| Gibbs Die Casting Group |
| Dynacast |
| Kinetic Die Casting Company |
| Chicago White Metal Casting Inc. |
| Continental Casting LLC |
| Others |
Value Network & Pricing Analysis
Hot-chamber certification tiers split the supplier base between NHTSA-qualified structural casters and undifferentiated commodity operators, with that bifurcation hardening contract terms for Detroit Three programs while pushing price-sensitive buyers toward spot-market Arizona and Utah ingot sourcing. OEM direct-sourcing agreements bundle eighteen-month validation cycles and thermal-load warranties into long-term offtakes, whereas tier-2 processors absorb alloy volatility through shorter-term contracts with limited after-sales protection.
Pricing Analysis
Warranty and service bundling separates captive foundry operations from independent die casters, with Meridian and Gibbs packaging validation support and scrap-recovery guarantees into multi-year OEM agreements while smaller operators quote unbundled unit pricing. Three-tier pricing structure across premium, standard, and economy levels tracks ASTM B94 certification status and hot-chamber technician density, with NHTSA structural qualification commanding sustained premiums. Cost compression in standard-tier transmission housings is intensifying because EV platform consolidation shrinks addressable automatic transmission demand. Fleet procurement departments show highest price sensitivity as lifecycle carbon accounting forces magnesium's production emissions disadvantage against aluminum into total-cost-of-ownership calculations.
Supply Chain Analysis
Freight costs from Utah and Washington state primary smelters to Michigan and Ohio foundries add material burden to AZ91D and AM60B alloy pricing, compressing margins for non-vertically integrated casters during diesel price spikes. Domestic supply draws from US Magnesium in Utah and Alcoa's Wenatchee operations, with secondary recovery from scrap processors in Indiana and Ohio supplementing virgin ingot. Single-region concentration risk sits with Great Lakes hot-chamber capacity clustering, where Ohio River flooding or polar vortex disruptions threaten national transmission housing supply. Distribution runs through just-in-sequence direct shipping to Detroit Three assembly plants, with bulk ingot supply serving tier-1 processors and e-commerce channels capturing aftermarket wheel replenishment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform-level EV consolidation is forcing structural separation between qualified structural component suppliers and undifferentiated transmission housing casters, with NHTSA fuel economy mandates accelerating that consolidation through model year 2032 qualification deadlines.
For Market Incumbents: Deepen captive hot-chamber capacity utilization through AM60B alloy development for battery enclosure programs, securing IRA Clean Vehicle Tax Credit verification before Texas EV assemblers lock in greenfield supplier relationships. Backward integration into Utah primary magnesium sourcing insulates margin positions against LME aluminum substitution economics and ingot price volatility spikes. For New Entrants and Emerging Players: Thixomolding equipment convergence offers entry into thin-wall structural brackets for tier-1 seating specialists decentralizing from captive Midwest foundries. Texas EV manufacturing corridor presents the most penetrable geography, with Tesla and Rivian platform-level sourcing decisions still open to qualification relationships outside traditional supplier networks. Target aftermarket wheel distributors through e-commerce channel partnerships with lower ASTM B94 barriers than OEM safety-critical programs. For Investors and Strategic Acquirers: Re-rating potential sits with hybrid thixomolding-capable structural suppliers given NHTSA side-impact protocol updates accelerating AM60B energy-absorption geometry demand. Long-term viability over the next decade hinges on IRA domestic content threshold compliance and renewable electricity contracting for carbon-accounting fleet procurement. Monitor OSHA pyrophoric handling compliance cost trajectories as inflection indicator for small foundry distress acquisition opportunities.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Primary Magnesium | Captive Utah smelter access insulates Gibbs Die Casting Group against LME volatility and supply disruption. |
| Thixomolding Capacity Installation | Hybrid production lines enable Shiloh Industries to serve both structural and cosmetic automotive grades. |
| Texas Greenfield Foundry Investment | Proximity to Tesla Gigafactory Texas captures platform-level battery enclosure sourcing decisions. |
| AM60B Alloy Qualification Acceleration | NHTSA side-impact protocol compliance opens 2026-2030 model year crash management system contracts. |
| Renewable Electricity Contracting | Low-carbon smelter power sourcing satisfies California and Washington state fleet procurement mandates. |
Research Methodology
Multi-period observation of AZ91D alloy price spreads, hot-chamber capacity utilization rates, and NHTSA CAFE compliance timelines anchored the trend analysis, supplemented by interviews with tier-1 supplier procurement directors, OEM platform engineers, OSHA compliance officers, and aftermarket wheel distributors. Secondary validation drew from EPA tailpipe emission filings, NHTSA fuel economy rulemaking dockets, ASTM B94 certification registries, and IHS Markit vehicle production databases. Bottom-up casting volume estimates triangulated against top-down OEM lightweighting spend allocations.
Input-output matrices modeled magnesium content per vehicle across ICE transmission housings, EV battery enclosures, and structural subframes, with segmentation dimensions spanning propulsion architecture, component thermal load specification, and regional production cluster. CAGRs were derived from regression analysis of historical alloy substitution elasticities and OEM platform rollout schedules, incorporating IRA Clean Vehicle Tax Credit phase-in assumptions and EV skateboard architecture penetration curves.
Several conditions sit outside the modeled scope, including unforeseen OSHA regulatory tightening on pyrophoric material handling, catastrophic disruption to Utah primary smelting capacity, and breakthrough aluminum-lithium alloy formulations displacing magnesium in structural applications. Forecasts reflect documented assumptions about NHTSA rulemaking continuity and IRA credit stability. Stakeholders should weight assumptions against their own operating context and scenario-test for alloy price volatility extremes.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
Automotive Coolant Market
Automotive Parts
Europe Ball Bearings Market
Automotive Parts
Global Automotive Hydraulics System Market
Automotive Parts
Automotive Timing Chain Market
Automotive Parts
Passenger Car Motor Oil Market
Automotive Parts
Automotive Performance Parts Market
Automotive Parts
Europe Automotive Parts Zinc Die Casting Market
Automotive Parts
Engine Oil Pan Market
Automotive Parts
France Automotive Hydraulic Actuators Market
Automotive Parts
Global Automotive Gear Shift System Market
Automotive Parts
France Automotive Actuators Market
Automotive Parts
Automotive Cylinder Head Gasket Market
Automotive Parts
Middle East Passenger Vehicles Lubricants Market
Automotive Parts
Automatic Gearbox Valves Market
Automotive Parts
Asia-Pacific Electric Power Steering Market
Automotive Parts
Auxiliary Oil Cooler Market