
 Australia Automotive Parts Magnesium Die Casting Market | 2026-2036
Australia Automotive Parts Magnesium Die Casting Market Size, Share, and Industry Trends Forecast 2026-2036
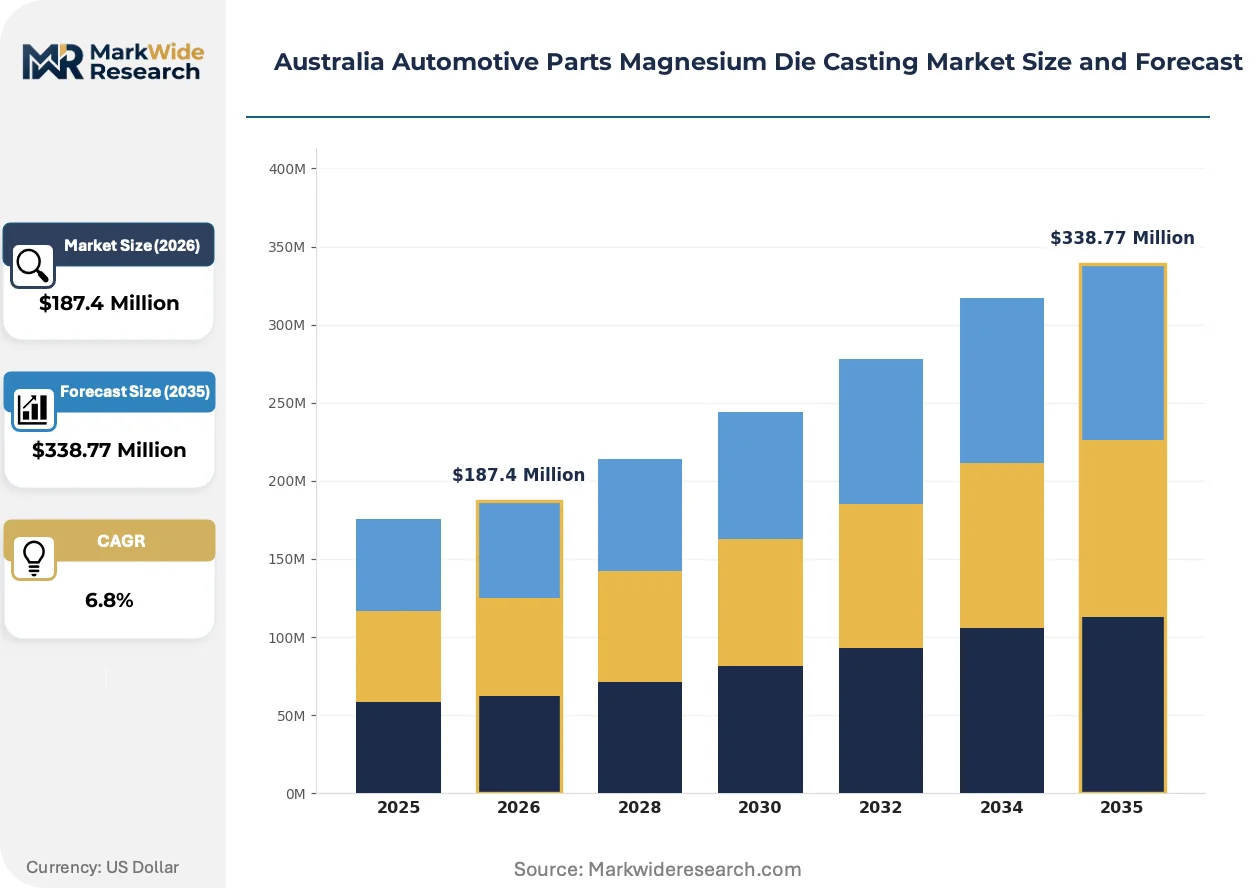
Australia Automotive Parts Magnesium Die Casting Market Outlook
OEM buyer concentration is pivoting as domestic vehicle assemblers consolidate supplier panels while EV startups fragment procurement across specialized tier-1s. A.F. Diecasters leverages its Melbourne-based high-pressure casting lines to anchor supply contracts with Holden Special Vehicles legacy programs. MAGNIUM AUSTRALIA sustains competitive positioning through captive magnesium billet sourcing and in-house alloy development. Diecast Australia Pty. Ltd. specializes in thin-wall transmission cases that occupy a defensible niche against imported Asian competitors.
Automotive parts magnesium die casting involves injecting molten AZ91D or AM60B magnesium alloy into hardened steel dies at clamping pressures exceeding 2,500 tonnes to produce near-net-shape components with wall thickness below 1.5 millimetres. The process yields powertrain and structural parts that reduce vehicle kerb weight by up to 75 per cent versus comparable steel stampings. Engine Components command the largest value share among product types due to cylinder head covers and oil pan complexity. Electric Cars represent the fastest-expanding application segment as battery enclosure frames and motor housings drive incremental magnesium tonnage. OEMs capture the deepest margin pools across end users by specifying proprietary alloy blends and demanding zero-defect quality protocols.
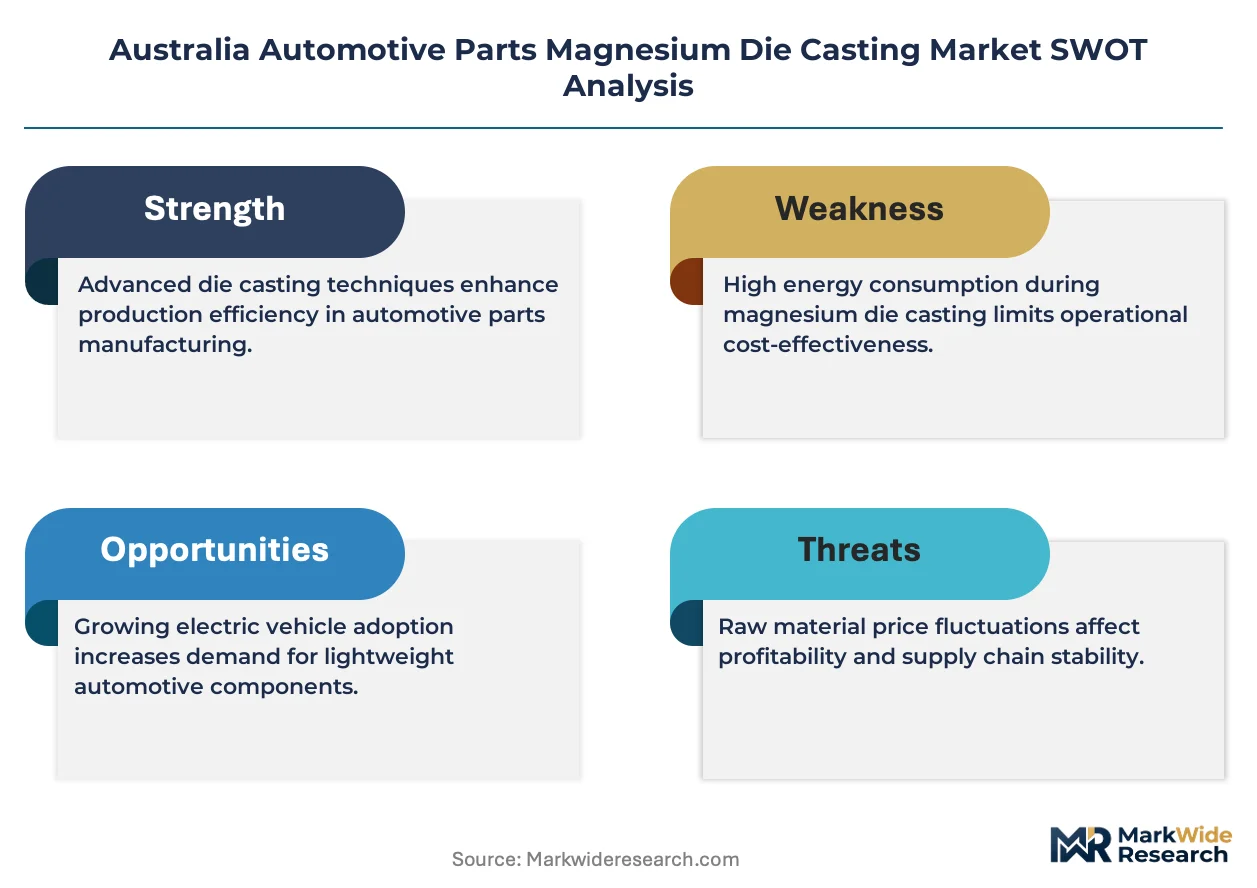
TGA-administered workplace safety standards intersect with state-level EPA emissions controls in Victoria and South Australia to mandate closed-loop fluxing and sulphur hexafluoride phase-out in magnesium melting operations. ADR design rules enforced by the Department of Infrastructure and Transport dictate crashworthiness minimums that directly influence magnesium wall thickness specifications and heat treatment requirements. Stakeholders must monitor evolving federal vehicle efficiency standards and state-based manufacturing incentives to time capacity investments before supplier qualification windows close.
Market Dynamics
High-pressure die casting with real-time porosity monitoring is concentrating production capability among Victorian foundries capable of meeting ADR crashworthiness specifications for sub-1.5mm magnesium wall thickness.
Growth Catalysts
- ADR Emissions Standards:Tightening federal vehicle efficiency mandates compel OEMs to specify magnesium powertrain housings that cut kerb weight by up to 75 per cent versus steel alternatives.
- Victoria Manufacturing Corridor:Foundry clustering around Melbourne and Geelong creates supplier density that accelerates qualification timelines for new magnesium alloy formulations.
- Fluxing Technology:Closed-loop sulphur hexafluoride-free melting systems mandated by EPA Victoria enable compliant capacity expansion without process interruption.
Market Restraints
- AZ91D Alloy Volatility:Primary magnesium ingot prices fluctuate with Chinese export quotas, compressing foundry margins on fixed-price OEM contracts.
- Tooling Lead Times:Hardened steel die fabrication for 2,500-tonne clamping pressures extends 18-24 months, freezing capacity responsiveness to demand spikes.
- Aluminium Substitution:High-pressure aluminium die casting competes for transmission cases where 15-20 per cent weight penalty is acceptable to buyers.
Strategic Opportunities
- Battery Enclosure Frames:Electric vehicle motor housings and battery trays represent uncontracted magnesium tonnage as local EV startups bypass incumbent aluminium supply chains.
- Geelong Supplier Zone:Underutilised industrial land near the former Holden manufacturing footprint offers brownfield foundry sites with existing logistics infrastructure.
- TGA Workplace Standards:Anticipated harmonisation of state-level fluxing regulations with federal occupational safety frameworks rewards early compliance investments.
Industry Challenges
- Die Maintenance Expertise:Shortage of technicians trained in thermal fatigue management for high-cycling magnesium dies limits uptime at automated casting lines.
- Zero-Defect Protocols:OEM proprietary alloy specifications demand real-time X-ray verification that strains capital budgets for tier-2 foundries.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Australia Automotive Parts Magnesium Die Casting Market |
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $338.77 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Engine Components, Transmission Parts, Chassis Parts, Brake Components End User: OEMs, Aftermarket Providers, Tier-1 Suppliers, Vehicle Assemblers Manufacturing Stage: Die Casting, Finishing, Assembly, Quality Control Application: Lightweight Vehicles, Electric Cars, Performance Vehicles, Commercial Vehicles |
| Companies Covered | A.F. Diecasters, Diecast Australia Pty. Ltd., HARROP ENGINEERING, Bühler AG, MAGNIUM AUSTRALIA, Cascade Die Casting Group Inc, Dongguan Minghe Die Casting Company, Kemlows Diecasting Products Ltd, Harrop Engineering Pty Ltd., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Australia Automotive Parts Magnesium Die Casting Market Strategic Shifts
Real-time process control systems and alloy formulation advances are compressing development cycles for thin-wall magnesium components destined for electrified powertrains.
High-pressure die casting with integrated porosity detection is expanding into battery enclosure production for electric vehicles. Tier-1 suppliers in Victoria are retrofitting 2,500-tonne presses with in-line CT scanning to eliminate post-cast inspection bottlenecks. This capability compression allows domestic foundries to qualify for EV motor housing contracts previously awarded to Asian competitors.
EPA Victoria's sulphur hexafluoride phase-out mandate is forcing foundries to adopt closed-loop fluxing systems by 2027. The regulation eliminates the most common atmospheric protection gas in magnesium melting, requiring capital conversion of crucible operations. Heat treatment facilities in South Australia are responding fastest, leveraging existing environmental compliance infrastructure to capture overflow from Victorian suppliers.
Consolidating domestic vehicle assemblers are fragmenting procurement across specialised tier-1s rather than legacy full-service suppliers. EV startups in New South Wales and Queensland are bypassing established Holden-era supply chains to source directly from magnesium specialists with in-house alloy development. This channel disintermediation is most visible in transmission case contracts, where thin-wall capability now outweighs historical relationship value in supplier selection.
Australia Automotive Parts Magnesium Die Casting Market Segmentation
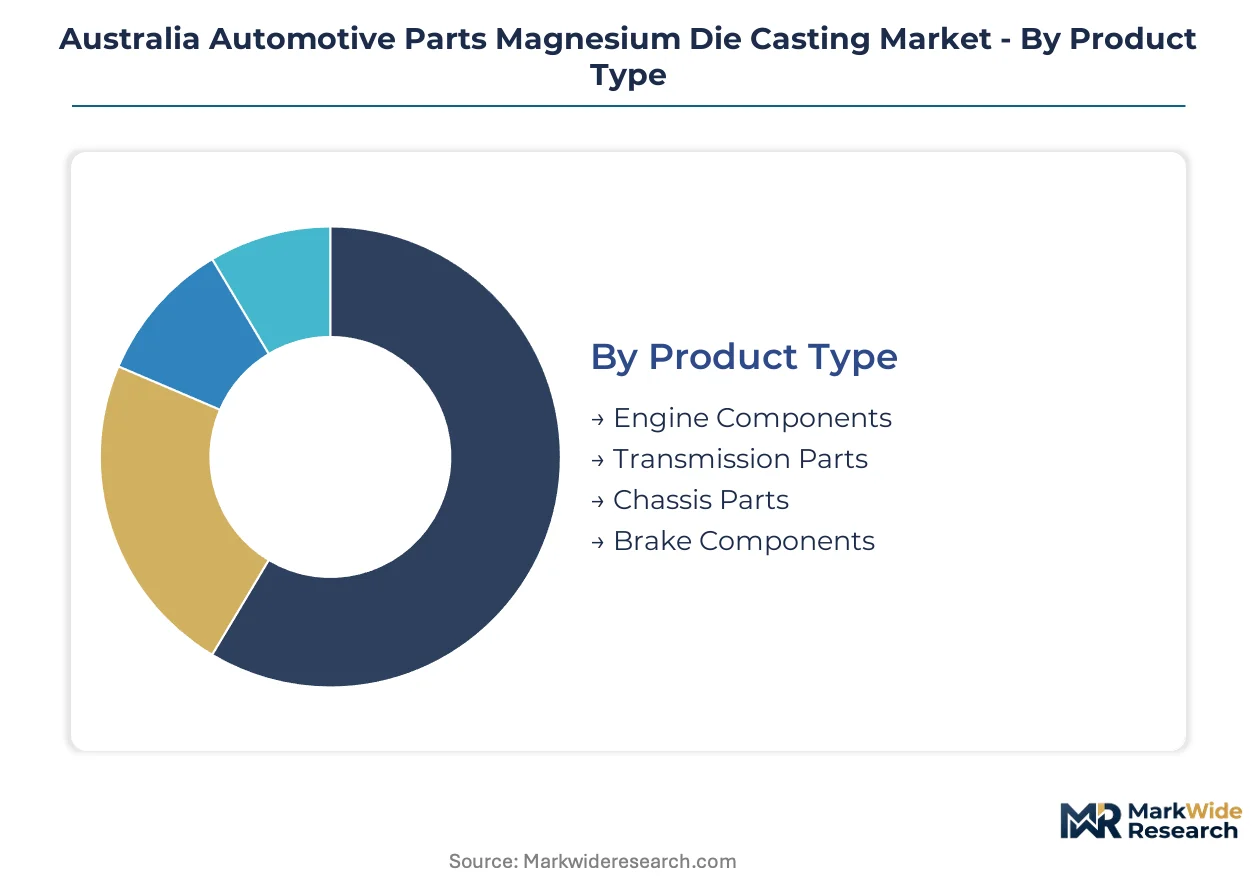
Segmentation in Australian magnesium die casting reveals how technical specifications, procurement hierarchies, and regulatory compliance create distinct margin pools across the value chain. Each dimension exposes where Victorian foundries concentrate capability versus where Asian imports retain cost advantage.
Product Type:
Volume concentration sits with legacy powertrain castings, while premium capture shifts toward electrification-optimized thin-wall designs.
- Engine Components:Cylinder head covers and oil pans require AZ91D alloy with heat-resistant surface treatments to meet ADR thermal cycling standards. Victorian foundries around Geelong anchor supply contracts with Holden-era engine programs facing emissions-driven redesign cycles.
- Transmission Parts:Thin-wall transmission cases below 1.5 millimetres demand AM60B alloy formulations with enhanced ductility for crashworthiness compliance. Diecast Australia Pty. Ltd. defends this niche against Thai and Malaysian competitors through captive tooling expertise.
- Chassis Parts:Structural crossmembers and steering housings absorb road-load stresses requiring T6 heat treatment protocols.
- Brake Components:Pedal assemblies and master cylinder housings prioritize corrosion resistance through proprietary coating systems.
Today's leader: Engine Components. Tomorrow's challenger: Transmission Parts.
End User:
Procurement authority fragments as domestic assemblers consolidate panels while EV startups bypass traditional tier structures.
- OEMs:Vehicle manufacturers specify proprietary alloy blends with zero-defect X-ray protocols that strain tier-2 capital budgets. Ford Australia and Toyota Australia retain direct sourcing relationships with MAGNIUM AUSTRALIA for powertrain housing programs.
- Tier-1 Suppliers:Full-service integrators like A.F. Diecasters manage multi-component assemblies across Melbourne's manufacturing corridor. Their captive high-pressure casting lines compress qualification timelines for new EV motor housing contracts.
- Vehicle Assemblers:Contract manufacturers without in-house design authority rely on foundry technical partnership for ADR compliance documentation.
- Aftermarket Providers:Replacement part distributors source remanufactured or imported castings where OEM tooling exclusivity has expired.
Procurement gravity centers on OEMs. Disintermediation pressure builds fastest among Tier-1 Suppliers.
Manufacturing Stage:
Capability differentiation concentrates at process intersections where real-time monitoring meets regulatory traceability.
- Die Casting:2,500-tonne clamping pressures with integrated CT scanning eliminate post-cast inspection bottlenecks for battery enclosure frames. Victorian foundries retrofitting these systems capture EV contracts previously lost to Chinese competitors.
- Quality Control:Real-time porosity detection and automated X-ray verification satisfy TGA workplace standards while enabling zero-defect shipment protocols demanded by proprietary alloy specifications.
- Finishing:CNC machining and surface preparation remove flash and achieve dimensional tolerances for assembly integration.
- Assembly:Multi-component integration of castings with fasteners, seals, and sensors creates value-add capture points.
Process leadership resides in Die Casting. Compliance differentiation emerges strongest in Quality Control.
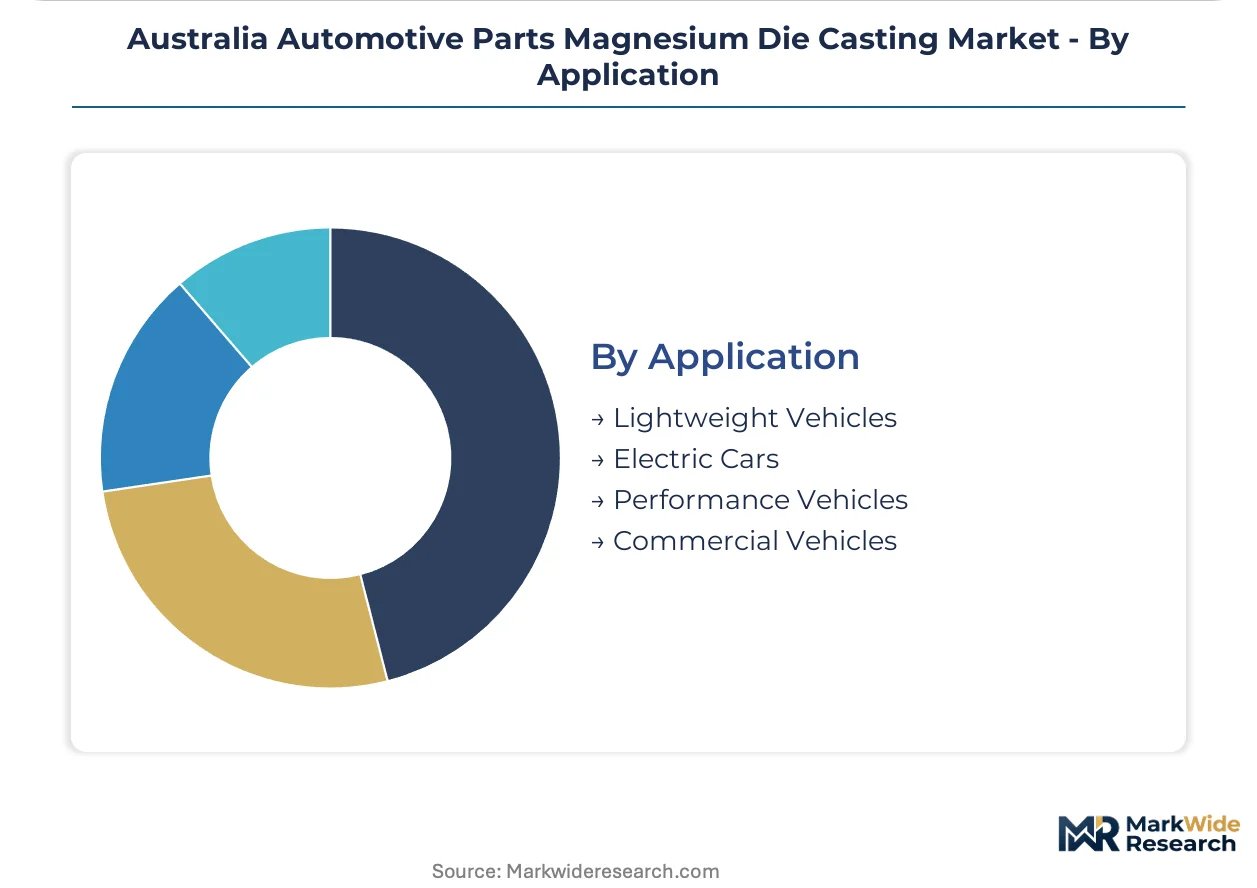
Application:
Weight reduction mandates intersect with electrification architecture to reposition magnesium's competitive set against aluminium and composite alternatives.
- Electric Cars:Battery enclosure frames and motor housings drive uncontracted magnesium tonnage as local EV startups bypass incumbent aluminium supply chains. High-pressure die casting with sub-1.5 millimetre wall capability qualifies suppliers for programs where crashworthiness and thermal management converge.
- Performance Vehicles:Lightweight powertrain housings for Holden Special Vehicles legacy programs and aftermarket tuners prioritize kerb weight reduction up to 75 per cent versus steel alternatives.
- Lightweight Vehicles:Mass-market passenger cars with federal efficiency targets specify magnesium for non-structural components where cost tolerance permits alloy premium.
- Commercial Vehicles:Truck and bus applications face aluminium substitution pressure where 15-20 per cent weight penalty is acceptable against magnesium's cost volatility.
Application expansion runs fastest through Electric Cars. Defensive positioning concentrates in Performance Vehicles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's automotive magnesium die casting sector operates at substantially larger scale than Australia's, yet both markets confront similar tooling lead time constraints and sulphur hexafluoride phase-out deadlines that reshape foundry investment cycles.
Victoria
Melbourne and Geelong anchor Australia's densest concentration of high-pressure die casting capacity, with local foundries retrofitting 2,500-tonne presses for EV battery enclosure production. EPA Victoria's sulphur hexafluoride phase-out mandate by 2027 accelerates closed-loop fluxing adoption among Geelong-based suppliers. The former Holden manufacturing corridor now hosts brownfield foundry sites where underutilised industrial land attracts EV startup procurement.
South Australia
Adelaide's heat treatment facilities capture overflow demand from Victorian magnesium suppliers facing environmental compliance bottlenecks. The state's existing environmental compliance infrastructure enables faster certification for sulphur hexafluoride-free melting operations. TGA workplace safety standards intersect with state-level controls to position South Australian foundries as compliant capacity alternatives.
New South Wales
Sydney-based EV startups fragment procurement across specialised tier-1 magnesium suppliers rather than legacy full-service chains. The state's startup ecosystem drives uncontracted magnesium tonnage for battery enclosure frames and motor housings. Western Sydney industrial zones attract die casting specialists seeking proximity to emerging EV assembly operations.
Queensland
Brisbane's automotive component distributors source remanufactured castings where OEM tooling exclusivity has expired, creating aftermarket revenue streams. The state's mining equipment manufacturers represent adjacent demand for structural magnesium castings. Queensland's distance from Victorian supplier density limits direct foundry investment but enables import substitution opportunities.
Western Australia
Perth's resource sector machinery builders generate intermittent demand for corrosion-resistant magnesium brake components and pedal assemblies. The state's isolation from eastern manufacturing corridors necessitates longer logistics chains for precision die cast parts. Local machine shops specialise in CNC finishing of imported magnesium blanks rather than primary casting operations.
Australia Automotive Parts Magnesium Die Casting Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across Australia's magnesium die casting sector, creating a tiered supplier structure where captive alloy development capabilities separate premium-tier competitors from commodity fabricators. Market concentration remains moderate, with Victorian foundries commanding geographic proximity advantages for ADR qualification timelines. Three archetypes dominate: integrated alloy developers with captive billet sourcing, high-pressure casting specialists with automated porosity monitoring, and legacy tier-1 assemblers managing multi-component supply contracts. Competitive moves centre on capacity retrofitting for EV-specific battery enclosures and strategic positioning for sulphur hexafluoride compliance ahead of 2027 regulatory deadlines.
Among Australian-based operators, A.F. Diecasters exemplifies the high-pressure casting specialist archetype through its Melbourne manufacturing presence, while MAGNIUM AUSTRALIA occupies a position consistent with integrated alloy developers possessing captive magnesium billet capabilities. Diecast Australia Pty. Ltd. represents the thin-wall transmission case niche that defends against lower-cost Asian imports. These three entities collectively illustrate how geographic clustering around Victoria's automotive corridor combines with process specialisation to determine competitive positioning in a market where OEM qualification windows are narrowing.
| Leading Market Players |
|---|
| A.F. Diecasters |
| Diecast Australia Pty. Ltd. |
| HARROP ENGINEERING |
| Bühler AG |
| MAGNIUM AUSTRALIA |
| Cascade Die Casting Group Inc |
| Dongguan Minghe Die Casting Company |
| Kemlows Diecasting Products Ltd |
| Harrop Engineering Pty Ltd. |
| Others |
Value Chain & Pricing Dynamics
EPA Victoria's sulphur hexafluoride phase-out mandate gates both qualified supply and premium-tier pricing access, as foundries lacking closed-loop fluxing systems face exclusion from OEM qualification windows while compliant operators capture margin premiums on zero-defect battery enclosure contracts.
Pricing Analysis
Capacity additions in South Australia are reshaping price floors for compliant magnesium billet, compressing spreads between Victorian foundries and Adelaide-based heat treatment facilities. Contract pricing stratifies across premium, standard, and economy tiers based on ADR crashworthiness certification and real-time porosity monitoring capability. Pricing pressure stems from AZ91D alloy volatility tied to Chinese export quotas, squeezing margins on fixed-price OEM agreements. Tier-2 foundries exhibit highest price sensitivity due to capital constraints for X-ray verification systems, while integrated alloy developers with captive billet sourcing maintain pricing power.
Supply Chain Analysis
Single-source vulnerability sits with primary magnesium ingot from China, where export quota fluctuations cascade through Australian foundry cost structures. Raw material flows draw from Chinese smelters, domestic billet casters, and specialty alloy formulators in Japan. Supply chain risk centers on tariff exposure from trade policy shifts affecting magnesium metal imports. Distribution runs through Melbourne-Geelong logistics corridors to OEM assembly plants, with secondary channels serving aftermarket remanufacturers in Queensland.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder, with EPA Victoria's 2027 sulphur hexafluoride deadline accelerating consolidation among foundries capable of environmental compliance investment.
For Market Incumbents: Anchor market position through captive magnesium billet sourcing and accelerated retrofit of 2,500-tonne presses with integrated CT scanning. Threats from high-pressure aluminium die casting substitution in transmission cases demand defensive alloy formulation R&D. Priority levers include backward integration into alloy development and pre-emptive qualification for EV motor housing programs before startup procurement windows close. For New Entrants and Emerging Players: Direct-to-EV-startup sales channels offer lowest barrier to entry, bypassing entrenched Holden-era supply relationships. White-space targets concentrate in battery enclosure frames for New South Wales-based electric vehicle assemblers and thin-wall motor housings for Queensland mining equipment applications. Go-to-market positioning should emphasize sub-1.5 millimetre wall capability with real-time porosity guarantees. For Investors and Strategic Acquirers: Roll-up economics work for mid-cap foundry specialists because sulphur hexafluoride compliance investments create stranded asset risk for sub-scale operators. Long-term viability across a decade horizon favors platforms with captive alloy development and brownfield Geelong sites. Acquisition targets should display heat treatment infrastructure and EPA Victoria certification progress. The signal to watch is EV startup procurement fragmentation accelerating beyond legacy tier-1 channels.| Strategic Initiative | Industry Significance |
|---|---|
| Closed-Loop Fluxing System Deployment | EPA Victoria compliance enables qualification for OEM zero-defect contracts. |
| High-Pressure Press Retrofit with CT Scanning | In-line porosity detection eliminates inspection bottlenecks for EV battery enclosures. |
| Captive Magnesium Billet Sourcing | Backward integration insulates margins from Chinese export quota volatility. |
| Geelong Brownfield Site Acquisition | Underutilised Holden-era industrial land offers logistics-advantaged capacity expansion. |
| EV Startup Direct Supply Agreements | Channel disintermediation bypasses entrenched tier-1 procurement hierarchies. |
Study Parameters
Coverage spans Victoria, South Australia, New South Wales, and Queensland, with primary inputs from each state informing demand calibration. Foundry operations directors, OEM platform engineers, Tier 1 supplier procurement leads, and EPA Victoria compliance officers contributed structured interviews. Secondary validation drew from Australian Bureau of Statistics manufacturing data, Department of Infrastructure and Transport ADR documentation, EPA Victoria emissions filings, and IHS Markit vehicle production databases. Bottom-up capacity assessments and top-down demand projections underwent triangulation against alloy consumption trends.
Rate-of-change decomposition separated volume drivers from value capture mechanisms across the projection horizon. Segmentation dimensions modeled include product type, end user tier, manufacturing stage, and application with propulsion architecture differentiation. CAGRs were derived from fitted growth curves applied to baseline capacity and demand estimates. Industry-specific forecast inputs incorporated sulphur hexafluoride phase-out timelines and EV startup procurement pipeline visibility.
The model assumes a particular technology adoption path; alternative pathways for solid-state battery thermal management would alter the outlook for magnesium enclosure demand. Forecasts reflect assumptions regarding ADR efficiency standard stringency and Chinese magnesium export policy continuity. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
South Africa Automotive Hydraulic Actuators Market
Automotive Parts
Two Wheeler Chain Sprocket Kit Market
Automotive Parts
Automotive Piston Pin Market
Automotive Parts
Global Automotive Cup Holder Market
Automotive Parts
Automotive Oil and Air Filters Market
Automotive Parts
Ball Bearing Market
Automotive Parts
Tire Vulcanizer Market
Automotive Parts
India Automotive Lubricants Market
Automotive Parts
Leaf Spring Shackle Side Bar Market
Automotive Parts
Automotive Fluids Market
Automotive Parts
Automotive Oil Pressure Switch Market
Automotive Parts
India Automotive Parts Aluminum Die Casting Market
Automotive Parts
Electric Vehicle Fasteners Market
Automotive Parts
Latin America Automotive Parts Magnesium Die Casting Market
Automotive Parts
Automotive Brake Linings Market
Automotive Parts
Constant Velocity Joint Market