
 Automotive Oil Pans Market | 2026-2036
Automotive Oil Pans Market Size, Share, and Industry Trends Forecast 2026-2036
Automotive Oil Pans Market Analytics
Structural-grade aluminum specification is bifurcating the Automotive Oil Pans Market into performance-differentiated supply tiers. MAHLE leverages its foundry-to-assembly vertical integration to control alloy sourcing costs across European passenger vehicle programs. Magna International sustains North American market presence through just-in-sequence delivery contracts with Detroit-based OEMs. Aisin Seiki anchors Asian supply networks with precision die-casting expertise for hybrid powertrain oil pan architectures.
An automotive oil pan is a stamped, cast, or molded reservoir mounted beneath the internal combustion engine block, typically fabricated from stamped steel, die-cast aluminum A380 alloy, or glass-reinforced polyamide composite, designed to store engine lubricant and house the oil pump pickup tube. Its primary function is to maintain adequate oil volume for circulation while withstanding thermal cycling, road debris impact, and corrosive fluid exposure over vehicle life. Aluminum oil pans command the dominant value share due to OEM lightweighting mandates, while composite oil pans represent the fastest-growing product type as thermal stability polymers displace metal in electric vehicle range-extender applications. OEM end users capture the deepest margin pools through multi-year platform contracts, whereas aftermarket providers compete on catalog breadth and regional warehouse density.
EPA Corporate Average Fuel Economy standards, EU REACH material compliance frameworks, and China's GB standards for automotive component recyclability collectively elevate aluminum and composite material substitution above legacy steel designs. NHTSA crashworthiness protocols further shape pan geometry and mounting interface specifications for North American light truck platforms. Stakeholders must monitor evolving powertrain electrification timelines to calibrate capital allocation between internal combustion oil pan capacity and thermal management reservoir development for hybrid architectures.
Market Dynamics
EPA fuel-economy mandates and EU CO₂ fleet targets are compressing oil pan material selection cycles, forcing simultaneous aluminum lightweighting investment and composite R&D allocation across multi-platform powertrain architectures.
Growth Catalysts
- EPA Corporate Average Fuel Economy standards:Tightening mandates in the United States accelerate aluminum substitution for stamped steel in full-size truck and SUV oil pan applications.
- Hybrid powertrain proliferation:Range-extender architectures require thermally stable composite reservoirs that reduce NVH while accommodating dual-circuit lubrication systems.
- China:Domestic OEM platform expansion drives die-casting capacity additions for structural-grade A380 alloy components serving volume passenger vehicle segments.
Market Restraints
- Primary aluminum price volatility:LME spot fluctuations compress foundry margins and complicate multi-year OEM contract pricing structures.
- Tooling capex intensity:High-pressure die-cast mold costs for complex pan geometries exceed amortization horizons for low-volume specialty vehicle programs.
- EU REACH compliance:Surface treatment chemical restrictions limit corrosion protection options for aluminum pans in salt-heavy European markets.
Strategic Opportunities
- India:Underpenetrated aluminum adoption in compact passenger vehicles creates white space for localized die-casting investments serving Maruti Suzuki and Hyundai Motor India platforms.
- Battery electric vehicle thermal management:Convergence of oil pan form factors with inverter cooling reservoirs opens adjacent component supply contracts.
- Direct-to-OEM digital procurement platforms:Tier-2 foundries bypass traditional distributor networks through Volkswagen Group's industrial marketplace and similar OEM portals.
Industry Challenges
- Die-cast simulation expertise shortage:MAGMAsoft and ProCAST proficiency gaps constrain foundry workforce scaling for thin-wall aluminum pan production.
- Platform validation timelines:Extended NHTSA crashworthiness certification cycles delay SOP dates and tie up engineering resources across concurrent programs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Automotive Oil Pans Market |
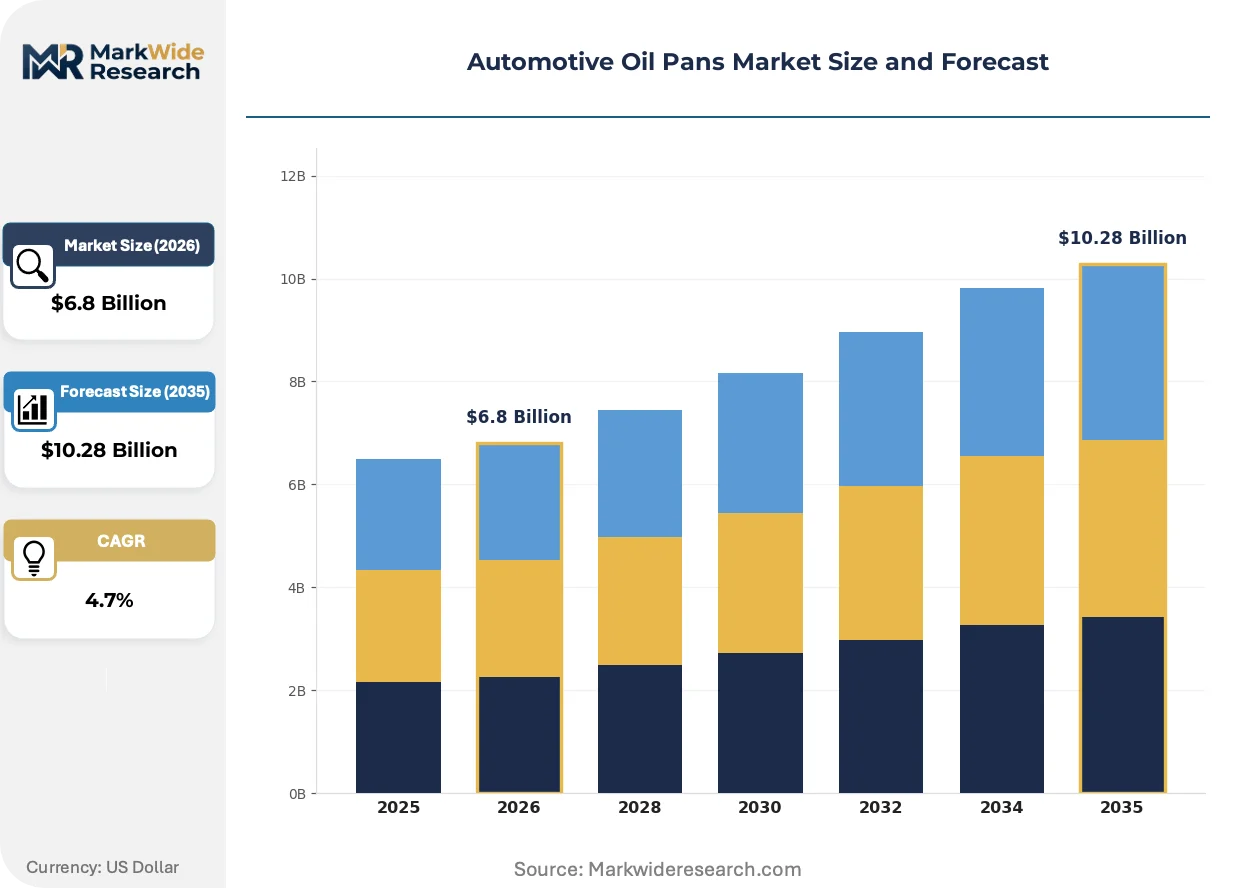
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $10.28 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Steel Oil Pans, Aluminum Oil Pans, Composite Oil Pans, Billet Oil Pans End User: OEMs, Aftermarket Providers, Vehicle Assemblers, Repair Shops Installation Type: Drop-in, Bolt-on, Weld-on, Integrated Distribution Channel: Direct Sales, Online Retail, Specialty Stores, Wholesalers |
| Companies Covered | MAHLE, Magna International, Aisin Seiki, Dana Incorporated, Tenneco, Martinrea International, Federal-Mogul, MANN+, Liland Global, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Automotive Oil Pans Market Evolving Landscape
Material science advances and powertrain electrification timelines are bifurcating oil pan development roadmaps, separating legacy internal combustion optimization from hybrid-thermal convergence architectures.
Glass-reinforced polyamide composite formulations are fragmenting established metal-centric supply relationships. These materials reduce mass by 40-50% versus aluminum equivalents while damping gear mesh noise in range-extender applications. BMW and Volvo Car Group procurement teams are qualifying composite pans for plug-in hybrid transverse engine layouts, compressing traditional foundry supplier incumbency in premium segments.
EU F-Gas Regulation phase-down schedules are accelerating hydrofluoroolefin adoption in aluminum heat treatment processes. Foundries serving Stellantis and Renault Group must retool thermal processing lines to maintain carbon footprint compliance under Scope 3 reporting requirements. German KBA type-approval documentation now requires material lifecycle data for oil pan submissions.
Fleet procurement centralization is consolidating specification authority at OEM headquarters. Regional purchasing organizations previously managing pan sourcing for individual assembly plants now cede negotiation control to global commodity councils. This concentration is most visible in Volkswagen Group's consolidated aluminum casting tenders, which bundle transmission pans, oil pans, and structural brackets into single-source multi-year agreements.
Automotive Oil Pans Market Segmentation
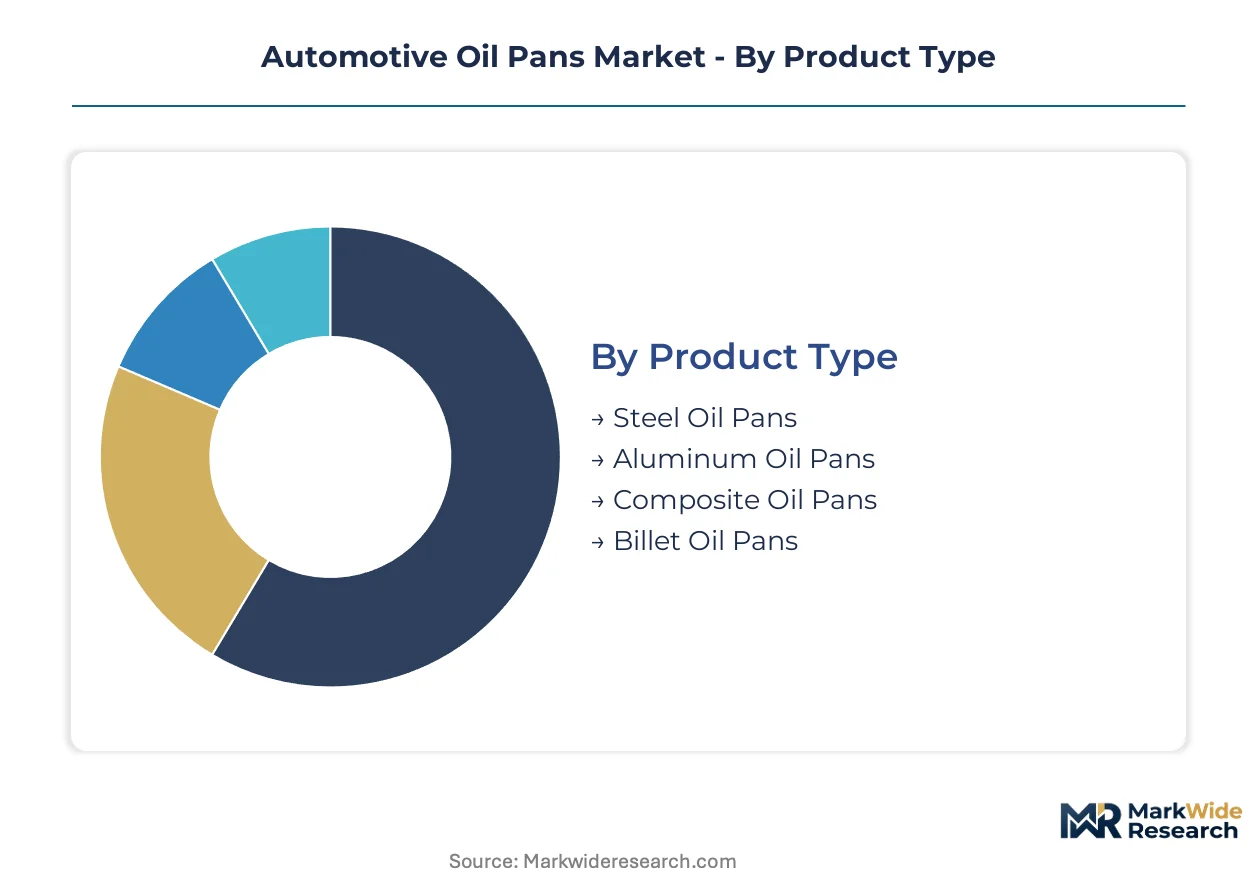
Material substitution pressures and powertrain electrification timelines fragment the Automotive Oil Pans Market into divergent technology roadmaps. Segment boundaries harden as EPA fuel-economy mandates compress steel-to-aluminum conversion cycles while composite formulations capture hybrid architectures.
Product Type:
Aluminum and composite formulations face divergent substitution threats—aluminum displaces legacy steel at volume scale while composites challenge aluminum's thermal performance in electrified powertrains.
- Steel Oil Pans:Stamped cold-rolled mild steel construction dominates full-size truck platforms where impact resistance outweighs mass reduction targets. Demand concentrates in Detroit Three heavy-duty pickup programs where NHTSA crashworthiness protocols favor ductile metal deformation over brittle fracture modes.
- Aluminum Oil Pans:Die-cast A380 alloy reservoirs command the dominant value position through OEM lightweighting mandates. Passenger vehicle OEMs in Germany and the United States specify structural-grade aluminum for transverse engine layouts where 30-40% mass reduction justifies foundry tooling investment.
- Composite Oil Pans:Glass-reinforced polyamide formulations reduce NVH in range-extender hybrids. BMW and Volvo Car Group procurement teams qualify these for plug-in hybrid transverse layouts.
- Billet Oil Pans:CNC-machined aluminum blocks serve motorsport and limited-production specialty vehicles requiring custom sump geometries.
Aluminum oil pans retain volume leadership; composite oil pans hold the steepest expansion curve.
End User:
Margin concentration separates captive OEM supply from fragmented aftermarket channels, with platform contract duration determining supplier profitability tiers.
- OEMs:Original equipment manufacturers capture the deepest margin pools through multi-year platform contracts bundling transmission pans, oil pans, and structural brackets. Volkswagen Group's consolidated aluminum casting tenders exemplify procurement centralization.
- Aftermarket Providers:Catalog breadth and regional warehouse density determine competitive position. These suppliers compete on SKU coverage for legacy vehicle parc maintenance.
- Vehicle Assemblers:Contract manufacturers serving emerging OEMs source through direct-to-OEM digital procurement platforms.
- Repair Shops:Independent service networks drive demand for drop-in replacement pans with standardized mounting interfaces.
OEMs dominate value capture; aftermarket providers sustain the broadest geographic footprint.
Installation Type:
Assembly line integration requirements stratify installation complexity, with welded and integrated formats locking in supplier relationships through vehicle platform life.
- Drop-in:Pre-assembled reservoir units enable rapid service bay replacement. Repair shops favor these for minimizing labor time.
- Bolt-on:Flanged mounting interfaces dominate OEM production lines where robotic fastening ensures torque specification compliance.
- Weld-on:Structural integration with engine cradles occurs in heavy-duty truck platforms where pan-to-frame load transfer is critical.
- Integrated:Oil pan castings incorporating windage trays, baffles, and pump housings reduce part count in hybrid powertrain architectures.
Bolt-on formats retain production volume dominance; integrated designs climb fastest on electrified platform penetration.
Distribution Channel:
Channel economics separate high-touch specialty supply from automated digital procurement, with direct sales capturing platform contract value.
- Direct Sales:Tier-1 suppliers engage OEM commodity councils through consolidated multi-year agreements. Volkswagen Group's industrial marketplace enables foundry bypass of traditional distributor networks.
- Online Retail:E-commerce platforms serve DIY enthusiasts and independent repair shops with catalog-driven search and comparison tools.
- Specialty Stores:Performance-focused retailers stock billet and motorsport-grade pans for enthusiast modification markets.
- Wholesalers:Regional distributors maintain inventory depth for aftermarket providers serving dispersed repair networks.
Direct sales anchor OEM contract value; online retail expands fastest on digital procurement platform adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in China and India exhibit acute price sensitivity to aluminum LME fluctuations, while German and US OEMs absorb material premiums to secure structural-grade alloy supply for lightweighting programs.
China
Domestic passenger vehicle platform expansion drives die-casting capacity additions for A380 alloy oil pans. GB standards for automotive component recyclability mandate material traceability systems across supplier networks. Shanghai and Yangtze River Delta clusters concentrate foundry investments serving SAIC Motor and Geely Auto volume programs.
Germany
Volkswagen Group and BMW procurement centralization bundles oil pan contracts into multi-year aluminum casting tenders. EU REACH surface treatment restrictions limit corrosion protection chemistries for salt-road exposure. Bavaria and Baden-Württemberg house MAHLE's foundry-to-assembly operations controlling alloy sourcing costs.
United States
Detroit Three heavy-duty truck programs sustain stamped steel demand where NHTSA crashworthiness protocols favor ductile deformation. EPA Corporate Average Fuel Economy tightening accelerates aluminum substitution in full-size SUV architectures. Michigan and Ohio assembly corridors anchor just-in-sequence delivery contracts with tier-1 suppliers.
India
Compact passenger vehicle segments remain underpenetrated for aluminum adoption, creating white space for localized die-casting investments. BIS certification requirements shape material specifications for domestic OEM platforms. Maharashtra and Tamil Nadu industrial corridors attract capital serving Maruti Suzuki and Hyundai Motor India production networks.
Japan
Hybrid powertrain proliferation demands thermally stable composite reservoirs for range-extender applications. METI carbon neutrality roadmaps pressure foundries to retool thermal processing lines. Aichi Prefecture's Nagoya-Toyota industrial zone concentrates precision die-casting expertise for dual-circuit lubrication systems.
Automotive Oil Pans Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, with foundry-to-assembly integrators commanding alloy sourcing advantages while modular specialists capture hybrid powertrain niches. The market structure consolidates around three tiers: captive OEM supply divisions, tier-1 diversified systems suppliers, and regional foundry specialists serving aftermarket channels. Strategic moves center on backward integration into primary aluminum sourcing and geographic co-location with high-volume assembly plants.
Among diversified tier-1 systems suppliers, MAHLE and Magna International occupy positions spanning foundry operations through module assembly. Aisin Seiki anchors Asian supply networks with precision casting capabilities. These three exemplify the vertical integration archetype that controls material cost exposure across multi-year OEM platform contracts.
| Leading Market Players |
|---|
| MAHLE |
| Magna International |
| Aisin Seiki |
| Dana Incorporated |
| Tenneco |
| Martinrea International |
| Federal-Mogul |
| MANN+ |
| Liland Global |
| Others |
Value Network & Pricing Analysis
Die-casting capacity utilization above 85% in Yangtze River Delta clusters compresses foundry margins and elevates price floors for structural-grade A380 alloy components. This scale concentration enables tier-1 suppliers to extract volume discounts while marginal players absorb LME volatility through spot-market exposure.
Pricing Analysis
EPA Corporate Average Fuel Economy standards dictate the pricing tier structure across aluminum oil pan supply. Three-tier pricing separates structural-grade alloy specifications from standard die-cast and economy steel alternatives. Price differentiation rests on certification grade for NHTSA crashworthiness and OEM platform volume scale. Pricing pressure stems from primary aluminum spot volatility compressing foundry margins. Aftermarket providers exhibit acute price sensitivity versus captive OEM supply divisions absorbing premiums for just-in-sequence delivery.
Supply Chain Analysis
Container availability constraints on Asia-Europe trade lanes elevate inbound logistics costs for alloy ingot shipments. Geographic supply concentrates in China, Germany, and the United States. Raw material dependencies draw from LME-traded primary aluminum, A380 alloy specifications, and glass-reinforced polyamide resin feedstocks. Supply chain risk centers on single-source vulnerability for precision die-cast tooling. Distribution runs through direct-to-OEM digital procurement platforms consolidating tier-2 foundry access.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Automotive oil pan supply exhibits defensive moat characteristics through regulatory entrenchment in EPA fuel-economy certification pathways. Switching costs for OEM platform validation create multi-year supplier lock-in.
For Market Incumbents: Compound backward integration into primary aluminum sourcing to offset LME volatility exposure. Secure captive alloy supply through long-term offtake agreements with smelters serving Yangtze River Delta clusters. Expand die-casting capacity in Maharashtra and Tamil Nadu industrial corridors before Maruti Suzuki platform consolidation closes entry windows. Reinforce regulatory compliance capabilities as EU REACH surface treatment restrictions intensify. For New Entrants and Emerging Players: Aftermarket digital procurement under-service creates white space for specialized catalog platforms targeting independent repair shops. Target India's compact passenger vehicle segments where aluminum penetration remains below 15% of oil pan volume. Pursue direct qualification with Hyundai Motor India and Tata Motors through BIS-certified A380 alloy supply. Anchor initial revenue through drop-in replacement pan SKUs before expanding into bolt-on production formats. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors precision die-casting specialists with hybrid powertrain composite reservoir capabilities. Long-term viability hinges on dual-material competency spanning aluminum lightweighting and thermally stable polymer formulations. Acquisition targets should demonstrate MAGMAsoft simulation proficiency and active Volkswagen Group or Stellantis platform contracts. Monitor EPA fuel-economy standard tightening velocity as inflection indicator for aluminum substitution acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Primary Aluminum | Captive A380 alloy supply insulates MAHLE and Magna from LME spot volatility. |
| Hybrid Powertrain Composite Reservoir Development | Glass-reinforced polyamide expertise opens BMW and Volvo range-extender platform contracts. |
| Localized Die-Casting Capacity Expansion | Maharashtra foundry investments capture Maruti Suzuki aluminum adoption acceleration. |
| Direct-to-OEM Digital Procurement Platform Access | Tier-2 foundries bypass distributor networks through Volkswagen Group's industrial marketplace. |
| EU REACH Surface Treatment Compliance Investment | Retooled corrosion protection lines maintain Stellantis and Renault Group supply position. |
Research Methodology
Desk research of customs trade databases, vehicle production registries, and SEC filings preceded structured interviews with OEM platform engineers, tier-1 supplier procurement directors, aftermarket distribution heads, and foundry operations managers. Primary fieldwork across China, Germany, and the United States validated secondary estimates of die-casting capacity and aluminum substitution rates. Bottom-up build from platform-level content per vehicle and top-down triangulation against vehicle production forecasts reconciled volume estimates.
Variance decomposition across material substitution scenarios, powertrain electrification timelines, and regional regulatory stringency shaped the analytical framework. Segmentation modeling covered vehicle class, propulsion architecture, material grade tier, and OEM supply tier across the projection horizon. CAGRs derived from S-curve penetration analysis for aluminum versus steel and composite displacement trajectories. Industry-specific inputs incorporated EPA fuel-economy standard compliance costs and EU REACH surface treatment restriction impacts.
Underlying assumptions cover EPA mandate enforcement continuity, LME aluminum price band stability, and hybrid powertrain volume penetration, with deviation risk concentrated in battery electric vehicle acceleration compressing internal combustion oil pan demand. Practitioners should keep alternative scenarios live as powertrain electrification timelines and regulatory stringency evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
Asia-Pacific Electric Power Steering Market
Automotive Parts
Two Wheeler Chain Sprocket Kit Market
Automotive Parts
Heavy Duty Clutches Market
Automotive Parts
United Kingdom Passenger Vehicles Lubricants Market
Automotive Parts
Latin America Automotive Parts Magnesium Die Casting Market
Automotive Parts
South Korea Automotive Airfilters Market
Automotive Parts
South Africa Automotive Parts Aluminium Die Casting Market
Automotive Parts
Automotive Trim Part Market
Automotive Parts
Industrial Bearings Market
Automotive Parts
Automotive Coolant Market
Automotive Parts
Automotive Belts and Hoses Market
Automotive Parts
Automotive Magnesium Alloy Market
Automotive Parts
Apron Bus Market
Automotive Parts
Automotive Grease Market
Automotive Parts
Automotive Cooling Fan Market
Automotive Parts
Wheel Arch Liner Market