
 Nigeria Automotive Engine Oils Market | 2026-2036
Nigeria Automotive Engine Oils Market Size, Share, and Industry Trends Forecast 2026-2036
Nigeria Automotive Engine Oils Market Foresight
API SP and ACEA C3 specification upgrades is unwinding across Nigeria's engine oils landscape. TotalEnergies Nigeria leverages its blending facility in Apapa to supply high-performance synthetics to fleet operators. Shell Nigeria anchors its position through extensive service station networks spanning the Lagos-Ibadan expressway corridor. Mobil Nigeria differentiates via technical partnerships with commercial vehicle dealerships in northern trade zones.
Automotive engine oils are lubricating formulations composed of base stocks and additive packages designed to reduce friction, dissipate heat, and neutralize combustion byproducts in internal combustion engines; SAE viscosity grades define flow characteristics across temperature ranges, with multi-grade formulations like 10W-40 maintaining pumpability in tropical climates. Mineral oils still occupy the volume base among price-sensitive motorcycle and aging passenger vehicle owners, while synthetic oils lead margin pools as commercial fleets prioritize extended drain intervals. Semi-synthetic blends are capturing growth in the mid-market as independent workshops in Onitsha and Aba seek balanced performance economics. Service stations dominate distribution for branded products, though auto part shops in Ladipo Market control the aftermarket re-lubrication segment.
Standards Organisation of Nigeria enforces lubricant labeling and performance claims through mandatory product registration, while the Department of Petroleum Resources monitors fuel quality standards that indirectly affect oil degradation rates. The National Automotive Design and Development Council promotes local blending capacity through policy incentives tied to automotive sector localization goals. Stakeholders must track enforcement intensity around counterfeit product seizures and the pace of OEM service standard adoption by independent garage chains.
Market Dynamics
API SP and ACEA C3 specification upgrades are compressing mineral oil shelf space as commercial fleets in Lagos and Kano prioritize extended drain intervals over upfront cost savings.
Growth Catalysts
- SON lubricant quality benchmarks:Mandatory product registration and labeling enforcement is elevating formulation standards across domestic blending facilities. Fleet operators now specify certified synthetics in procurement tenders.
- Interstate haulage corridor expansion:Heavy-duty commercial vehicles operating Lagos-Kano-Abuja routes accumulate engine stress loads that accelerate oil degradation. Synthetic formulations with thermal stability additives address this operational intensity.
- Independent workshop upgrading:Mechanics in Onitsha and Aba are investing in oil analysis equipment to justify premium synthetic recommendations to motorcycle and passenger vehicle owners.
Market Restraints
- Base oil import dependency:Nigeria lacks Group II/III base stock refining capacity, exposing blenders to naphtha and vacuum gas oil price volatility denominated in foreign exchange.
- Counterfeit packaging sophistication:Re-lubrication channels in Ladipo Market distribute mislabeled products that undermine branded synthetic penetration among price-sensitive vehicle owners.
- Extended drain interval compression:Synthetic oil longevity reduces per-vehicle consumption frequency, constraining volume growth even as value per liter rises.
Strategic Opportunities
- Northern trade zone dealership partnerships:Commercial vehicle distributors in Kano and Kaduna seek technical collaboration on OEM-specified service protocols. First-mover alignment captures fleet maintenance contracts.
- Semi-synthetic mid-market positioning:Independent workshops serving aging passenger vehicles represent an underserved segment between mineral economy and full synthetic premium tiers.
- NADDC automotive localization incentives:Policy support for domestic blending capacity expansion offers capital subsidy access for facility upgrades meeting international formulation standards.
Industry Challenges
- Lubricant chemist talent scarcity:Domestic universities produce limited graduates with additive package formulation expertise, forcing reliance on expatriate technical staff at blending facilities.
- Service station network capital intensity:Branded distribution expansion along emerging haulage corridors requires storage tank and dispensing infrastructure investment ahead of demand maturation.
- API certification timeline friction:Overseas testing laboratory queues delay new product introductions by six to nine months, constraining rapid response to specification evolution.
Report Scope
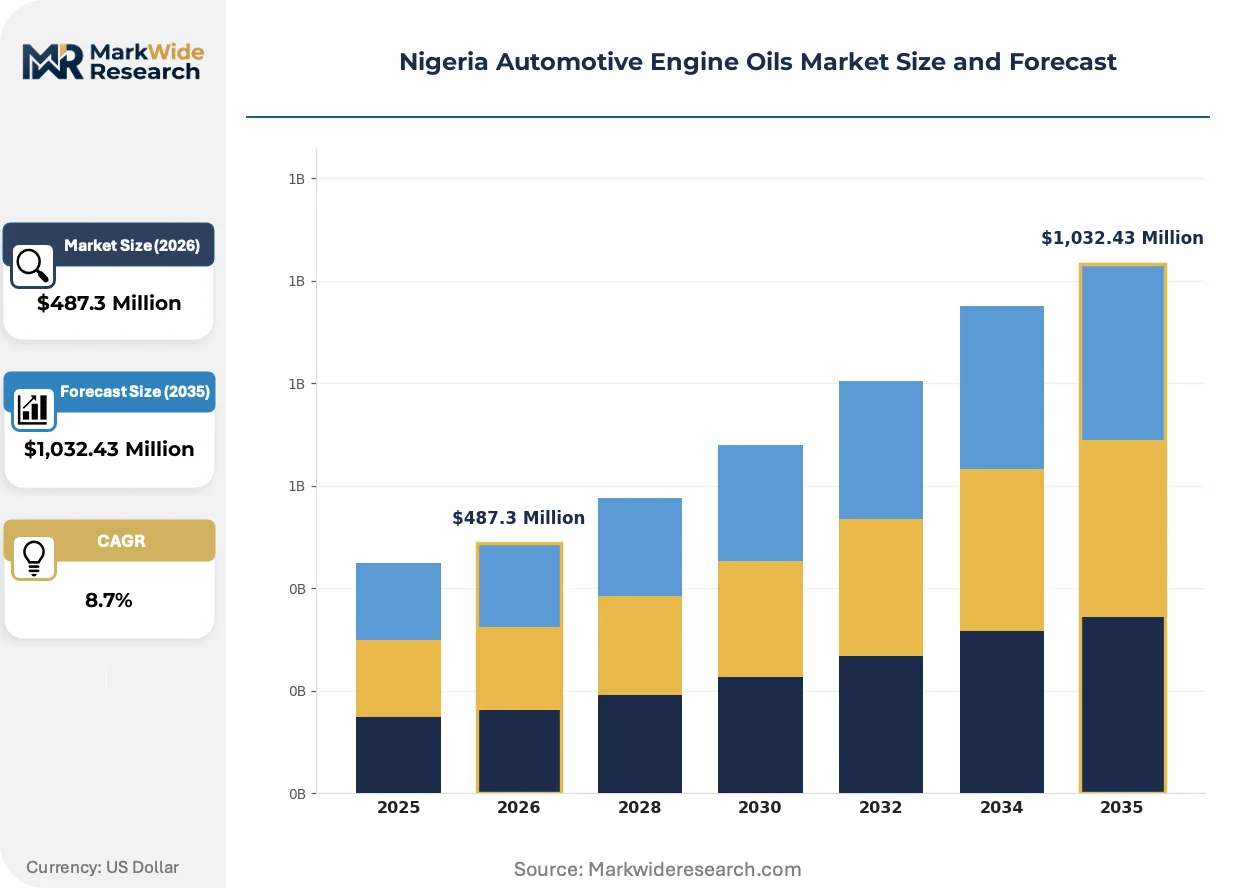
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Nigeria Automotive Engine Oils Market |
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $1,032.43 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Synthetic Oils, Mineral Oils, Semi-Synthetic Oils, Additive Packages End User: Passenger Vehicles, Commercial Vehicles, Heavy-Duty Trucks, Motorcycles Distribution Channel: Online Retail, Auto Part Shops, Supermarkets, Service Stations Viscosity Grade: SAE 20W-50, SAE 10W-40, SAE 5W-30, SAE 15W-40 |
| Companies Covered | Oando Plc, Ardova Plc, TotalEnergies Nigeria, Conoil Nigeria, 11Plc, Shell Nigeria, Mobil Nigeria, MRS Oil Nigeria Plc, BP Plc (Castrol), Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Nigeria Automotive Engine Oils Market Shifts & Advancements
Synthetic formulation chemistry is advancing faster than distribution infrastructure can adapt, creating mismatches between product capability and channel education.
Group III+ hydrocracked base stocks with advanced friction modifier packages are supplanting conventional mineral formulations in fleet procurement specifications. Transport operators running Mercedes-Benz Actros and MAN TGX tractors across the Lagos-Ibadan corridor specify these synthetics to meet manufacturer warranty terms. The shift is compressing margin pools for mineral-dominant suppliers while rewarding blenders with technical service capabilities.
SON's lubricant labeling enforcement protocol is tightening product registration verification at port entry points. Importers now face laboratory testing requirements before market release, extending clearance timelines. Blending facilities with in-house quality certification are capturing share from traders dependent on third-party testing.
Fleet maintenance managers are consolidating supplier relationships around single-source technical partnerships rather than spot purchasing across multiple brands. Large haulage operators in Kano now negotiate annual volume contracts with embedded oil analysis and drain interval optimization services. This concentration is visible most acutely among cement and petroleum product tanker fleets operating fixed routes with predictable duty cycles.
Nigeria Automotive Engine Oils Market Segmentation
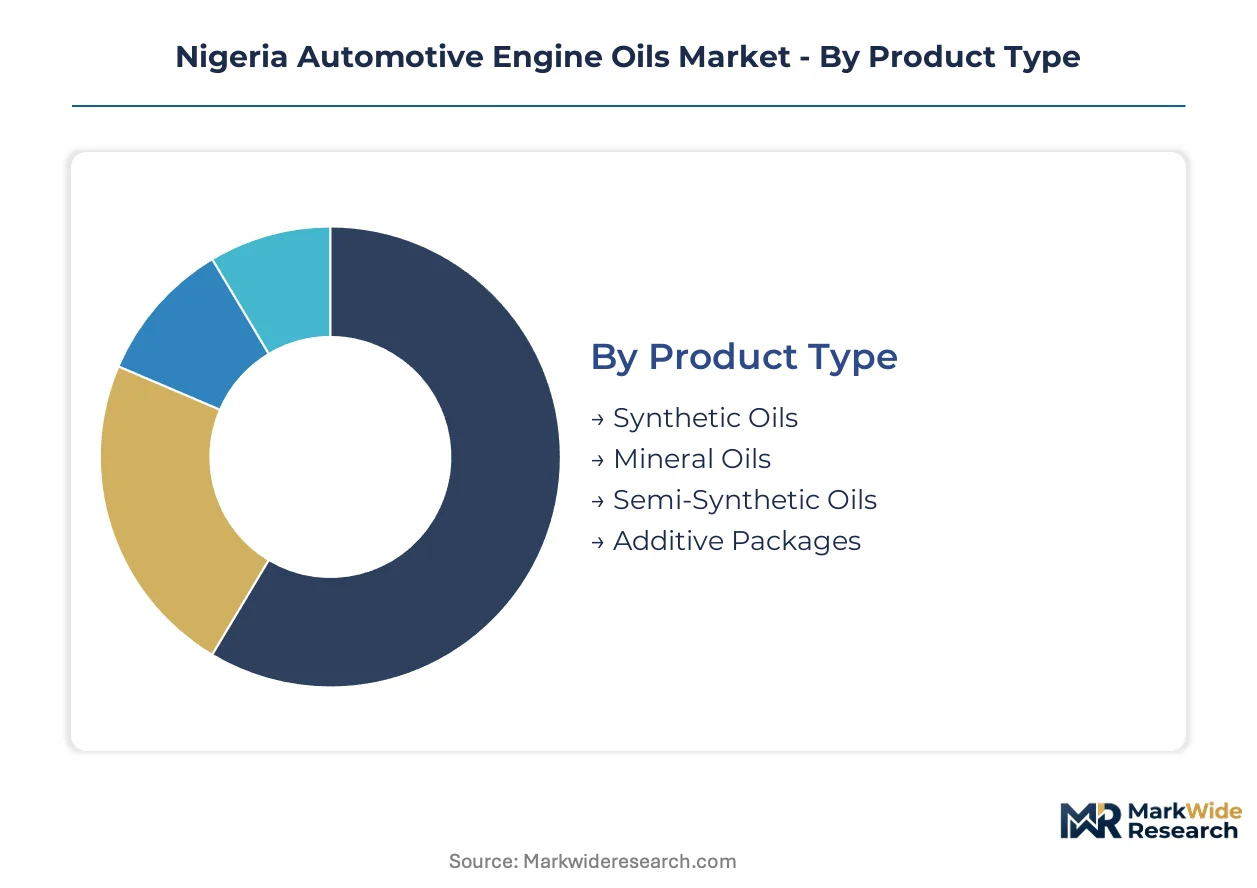
Segmentation in Nigeria's automotive engine oils market reveals distinct procurement patterns across vehicle types and channel structures. Fleet operators in Lagos and Kano prioritize synthetic formulations with extended drain intervals, while independent workshops in Onitsha and Aba balance performance economics for aging vehicle populations.
Product Type:
Domestic blending facilities in Apapa and Port Harcourt supply the mineral and semi-synthetic volume base, while synthetic formulations depend heavily on imported Group III base stocks and additive packages from European and Asian suppliers.
- Synthetic Oils:Formulated from Group III+ hydrocracked base stocks with advanced friction modifier packages, these lubricants deliver thermal stability under the sustained engine loads of Mercedes-Benz Actros tractors hauling cement across the Lagos-Ibadan corridor. Fleet procurement managers specify synthetics to satisfy OEM warranty terms and optimize drain intervals.
- Mineral Oils:Refined from solvent-extracted base stocks without hydrocracking, mineral formulations retain dominance among price-sensitive motorcycle operators and owners of aging passenger vehicles in northern trade zones. SON quality enforcement is gradually compressing shelf space for uncertified mineral products.
- Semi-Synthetic Oils:Blends combining mineral base stocks with synthetic additives occupy the mid-market tier where independent workshops seek balanced performance economics.
- Additive Packages:Concentrated chemical formulations imported by domestic blenders to customize viscosity and performance characteristics for tropical operating conditions.
Mineral oils command the established base. The steepest expansion runs through synthetic oils.
End User:
Cost tier differentiation separates premium fleet contracts from transactional retail purchases, with commercial operators accepting per-liter premiums for technical service bundling.
- Passenger Vehicles:Owners of Toyota Corolla and Honda Accord models dominate this segment, with demand concentrating in Lagos and Abuja urban corridors where service station networks provide branded synthetic options alongside mineral economy choices.
- Commercial Vehicles:Interstate haulage operators running fixed routes accumulate engine stress loads that accelerate oil degradation. These fleets negotiate annual volume contracts with embedded oil analysis services, consolidating supplier relationships around single-source technical partnerships rather than spot purchasing.
- Heavy-Duty Trucks:MAN TGX and Scania tractor units operating the Lagos-Kano-Abuja corridor specify ACEA E6/E9 heavy-duty formulations with extended drain capability.
- Motorcycles:Commercial okada operators and private owners in Kano and Kaduna represent a price-sensitive volume base for mineral formulations, though workshop upgrading in Aba is shifting some demand toward semi-synthetic protection.
Passenger vehicles anchor volume consumption. Commercial vehicles generate the fastest margin expansion.
Distribution Channel:
Channel concentration reflects infrastructure maturity, with branded networks controlling highway corridors and independent traders dominating aftermarket re-lubrication.
- Service Stations:Shell and TotalEnergies outlets along the Lagos-Ibadan expressway corridor anchor branded synthetic distribution, offering OEM-specified formulations with warranty documentation for fleet operators.
- Auto Part Shops:Ladipo Market traders in Lagos control the aftermarket re-lubrication segment, though counterfeit packaging sophistication undermines certified product penetration among price-sensitive buyers.
- Online Retail:E-commerce platforms are capturing urban professional demand for convenience purchasing, particularly in Lagos and Abuja where delivery logistics support scheduled maintenance planning.
- Supermarkets:Hypermarket chains in Lagos metropolitan areas stock consumer-packaged lubricants for DIY maintenance among middle-class vehicle owners.
Service stations dominate branded premium distribution. Auto part shops retain the highest transaction frequency.
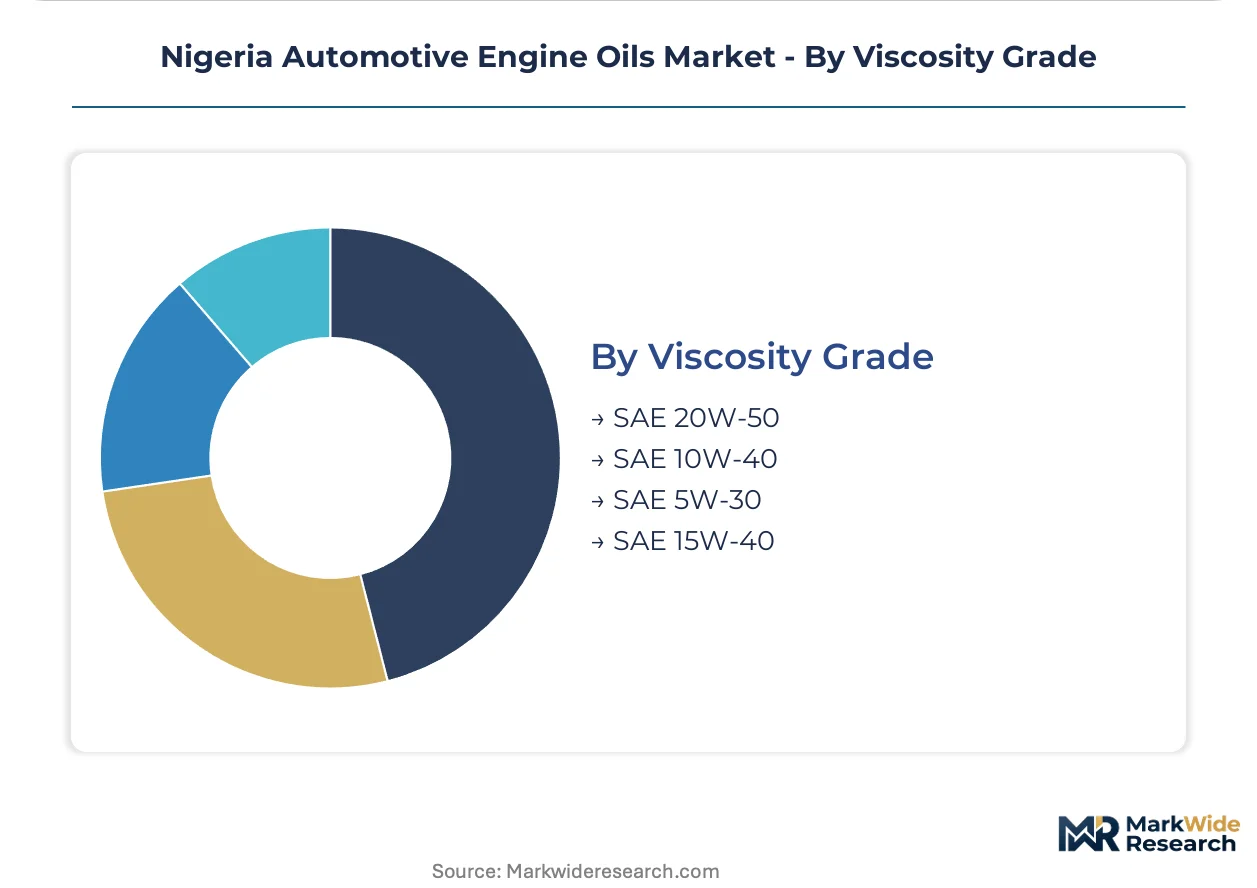
Viscosity Grade:
Application requirements and ambient temperature ranges dictate grade selection, with tropical climates favoring higher-temperature formulations.
- SAE 20W-50:Multi-grade mineral and semi-synthetic formulations maintain film strength under the sustained high temperatures of stop-start traffic in Lagos and engine stress from poorly maintained cooling systems in aging commercial fleets.
- SAE 10W-40:The workhorse specification for passenger vehicles and light commercial applications across Nigeria's tropical climate, balancing cold-start pumpability with high-temperature protection.
- SAE 5W-30:Lower viscosity synthetics specified by modern OEMs for fuel economy optimization, gaining traction among urban professional vehicle owners in Abuja.
- SAE 15W-40:Heavy-duty diesel specification dominating commercial vehicle and truck applications, particularly for engines operating without consistent coolant maintenance.
SAE 20W-50 holds the volume base. SAE 5W-30 is climbing the fastest on synthetic substitution.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Price elasticity varies sharply across Nigerian sub-markets. Fleet operators in Lagos and Kano accept synthetic premiums for extended drain intervals. Motorcycle operators in northern trade zones remain anchored to mineral economy tiers despite gradual workshop upgrading.
Lagos State
Interstate haulage fleets operating the Lagos-Ibadan corridor accumulate engine stress loads that accelerate oil degradation. Standards Organisation of Nigeria enforcement concentrates at Apapa port entry points, extending clearance timelines for imported additive packages. Blending facilities in the Apapa industrial zone capture share from traders dependent on third-party testing through in-house quality certification.
Kano State
Commercial vehicle distributors in this northern trade zone negotiate annual volume contracts with embedded oil analysis services. The National Automotive Design and Development Council policy incentives for domestic blending capacity expansion offer capital subsidy access for facility upgrades. Fleet maintenance managers at cement and petroleum product tanker operations consolidate supplier relationships around single-source technical partnerships.
Onitsha-Aba Corridor
Independent workshops in these southeastern manufacturing centers balance performance economics for aging passenger vehicle populations. SON lubricant labeling enforcement is gradually compressing shelf space for uncertified mineral products. Mechanics investing in oil analysis equipment justify premium synthetic recommendations to motorcycle and passenger vehicle owners.
Abuja Federal Capital Territory
Urban professional vehicle owners in the capital generate demand for lower viscosity synthetics specified by modern OEMs for fuel economy optimization. The Department of Petroleum Resources monitors fuel quality standards that indirectly affect oil degradation rates. Service station networks along major arterial roads provide branded synthetic options alongside mineral economy choices.
Port Harcourt
Domestic blending facilities in this Niger Delta hub supply the mineral and semi-synthetic volume base for regional distribution. Base oil import dependency exposes operations to naphtha and vacuum gas oil price volatility denominated in foreign exchange. Industrial clusters around the port handle imported Group III base stocks and additive packages from European and Asian suppliers.
Nigeria Automotive Engine Oils Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes across Nigeria's engine oils landscape. International majors with blending facility ownership and technical service capabilities command premium fleet contracts. Domestic marketers with extensive downstream distribution networks capture volume across price-sensitive segments. Three archetypes dominate: integrated international operators with local blending assets, national petroleum marketing companies with retail infrastructure, and independent traders controlling aftermarket re-lubrication channels. Competitive moves concentrate on strategic partnerships with commercial vehicle dealerships and capacity expansion at domestic blending facilities.
Within the integrated international tier, TotalEnergies Nigeria and Shell Nigeria anchor positions through differentiated infrastructure strategies. TotalEnergies leverages its Apapa blending facility to supply high-performance synthetics directly to fleet operators. Shell anchors through extensive service station networks spanning the Lagos-Ibadan expressway corridor. Among domestic petroleum marketers, Oando Plc and Ardova Plc occupy positions defined by downstream reach and portfolio breadth across lubricant tiers.
| Leading Market Players |
|---|
| Oando Plc |
| Ardova Plc |
| TotalEnergies Nigeria |
| Conoil Nigeria |
| 11Plc |
| Shell Nigeria |
| Mobil Nigeria |
| MRS Oil Nigeria Plc |
| BP Plc (Castrol) |
| Others |
Supply & Pricing Matrix
Group III+ base stock substitution for solvent-extracted mineral oils simultaneously concentrates supply geography around European and Asian hydrocracking facilities and compresses pricing economics for domestic Nigerian blenders exposed to foreign exchange volatility. This input shift forces procurement managers to balance extended drain interval premiums against import-dependent cost structures.
Pricing Analysis
After-sales service bundling drives lifetime value for fleet operators negotiating annual volume contracts with embedded oil analysis and drain interval optimization. Three-tier pricing structure across premium synthetic, semi-synthetic standard, and mineral economy levels separates procurement specifications by vehicle duty cycle and warranty compliance needs. Pricing pressure stems from counterfeit packaging sophistication in Ladipo Market re-lubrication channels. Motorcycle operators in northern trade zones exhibit highest price sensitivity, while cement and petroleum tanker fleets accept synthetic premiums.
Supply Chain Analysis
Belgium, Singapore, and South Korea anchor Group II/III base stock production for Nigerian blenders lacking domestic hydrocracking capacity. Domestic blending facilities in Apapa and Port Harcourt draw from imported additive packages and vacuum gas oil feedstocks denominated in foreign exchange. Single-source vulnerability concentrates around European additive suppliers facing laboratory testing queue delays. Distribution runs through branded service station networks along interstate haulage corridors and independent auto part shops controlling aftermarket re-lubrication.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents must navigate electric vehicle penetration threats that compress long-term internal combustion engine lubricant demand, positioning synthetic formulation expertise as a bridge asset during powertrain transition.
For Market Incumbents: Shield fleet maintenance contracts through technical partnership deepening with commercial vehicle dealerships in Kano and Kaduna. Accelerate in-house quality certification investment to capture share from traders dependent on third-party SON testing. Blending facility vertical integration into additive package formulation reduces expatriate chemist dependency and compresses new product introduction timelines.
For New Entrants and Emerging Players: Differentiate on semi-synthetic mid-market positioning targeting independent workshops in Onitsha and Aba serving aging passenger vehicle populations. Capture underserved mechanics investing in oil analysis equipment to justify premium recommendations. Pursue NADDC capital subsidy access for domestic blending facility upgrades meeting international formulation standards.
For Investors and Strategic Acquirers: The market sits at a specification upgrade phase that favors blenders with technical service capabilities and in-house quality certification. Long-term viability hinges on synthetic formulation chemistry leadership and fleet contract concentration rather than mineral volume exposure. Acquisition targets should demonstrate embedded oil analysis service revenue and single-source technical partnerships with haulage operators. Monitor SON enforcement intensity around counterfeit product seizures as inflection indicator for branded synthetic penetration.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Additive Package Formulation | Reduces API certification timeline friction and expatriate chemist dependency at Apapa blending facilities. |
| Fleet Technical Partnership Expansion | Cements annual volume contracts with embedded oil analysis services for cement and petroleum tanker operators. |
| NADDC Localization Incentive Capture | Unlocks capital subsidy access for domestic blending capacity upgrades meeting ACEA C3 specification standards. |
| Counterfeit Detection Channel Investment | Protects branded synthetic penetration in Ladipo Market re-lubrication segments through verification technology deployment. |
| Semi-Synthetic Mid-Market Line Extension | Targets independent workshop upgrading in Onitsha and Aba with balanced performance economics for aging vehicle fleets. |
Research Methodology
Cross-validation between fleet procurement manager interviews and SON registration database analysis anchors the qualitative findings on specification upgrade adoption patterns. Primary fieldwork incorporated blending facility technical directors, commercial vehicle dealership service managers, independent workshop mechanics in Onitsha and Aba, and Ladipo Market auto part traders. Secondary validation drew from SON lubricant labeling enforcement protocols, NADDC automotive sector localization policy documents, Department of Petroleum Resources fuel quality monitoring reports, and interstate haulage corridor traffic density assessments. Bottom-up volume triangulation across vehicle parc estimates and top-down value reconciliation against blending facility capacity utilization ensured analytical coherence.
Sensitivity analysis across base oil import price scenarios and foreign exchange volatility bands stress-tested projection robustness. The analytical framework segmented volume and value across product type, end user category, distribution channel structure, and viscosity grade specifications throughout the forecast period. CAGRs derived from vehicle fleet expansion rates, drain interval extension trends, and synthetic substitution elasticity coefficients modeled demand evolution. Industry-specific inputs incorporated SON enforcement intensity indices and NADDC incentive disbursement timelines.
Material uncertainties — counterfeit packaging sophistication evolution, electric vehicle penetration acceleration, and base oil refinery capacity expansion in source markets — sit outside the modeled envelope. Forecasts reflect assumptions around specification compliance enforcement continuity and fleet operator procurement consolidation trajectories. Recalibration cycles align with material shifts in SON seizure reporting frequency and NADDC policy incentive program modifications.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
Car Phone Holder Market
Automotive Parts
Electric Coolant Pump Market
Automotive Parts
Air Brake Market
Automotive Parts
Canada Automotive Actuators Market
Automotive Parts
Uae Commercial Vehicles Lubricants Market
Automotive Parts
South Africa Commercial Vehicles Lubricants Market
Automotive Parts
Automobile Muffler Market
Automotive Parts
Bearing Steel Balls for New Energy Vehicles Market
Automotive Parts
Automotive Propeller Shaft Couplings Market
Automotive Parts
Electric Parking Brake Market
Automotive Parts
Passenger Car Motor Oil Market
Automotive Parts
China Automotive Parts Aluminum Die Casting Market
Automotive Parts
Global Automotive Cooler Market
Automotive Parts
Automotive Piston Pin Market
Automotive Parts
Fluid Couplings Market
Automotive Parts
Racing Vehicles Market