
 Africa and Middle East Automotive Actuators Market | 2026-2036
Africa and Middle East Automotive Actuators Market Size, Share, and Industry Trends Forecast 2026-2036
Africa and Middle East Automotive Actuators Market Outlook
The divergence between premium smart actuators and commodity traditional units is realigning procurement patterns across the Africa and Middle East Automotive Actuators Market. Robert Bosch GmbH leverages its electromechanical actuator portfolio to dominate powertrain applications in South African vehicle assembly plants. Continental AG anchors its regional position through brake system actuator supply to Egyptian and Moroccan OEM networks. Denso Corporation specializes in thermal actuator technology for HVAC comfort systems targeting Gulf state passenger vehicle fleets.
Automotive actuators are electromechanical, hydraulic, pneumatic, or thermal devices that convert electrical signals into precise mechanical motion to control engine, braking, steering, and climate functions in vehicles, typically operating within voltage ranges of 12V to 48V and temperature tolerances exceeding 150°C for under-hood deployment. Electromechanical actuators lead product type demand due to their compatibility with hybrid powertrain architectures spreading across North African manufacturing zones. Smart actuators and IoT-enabled variants represent the fastest-expanding technology category as telematics integration becomes standard in fleet vehicles across Saudi Arabia and the UAE. OEMs capture the dominant end-user channel, though aftermarket providers are gaining traction in Nigeria and Kenya where aging vehicle parc sustains replacement demand.
Saudi Standards, Metrology and Quality Organization (SASO) fuel economy regulations and UAE's Emirates Authority for Standardization and Metrology (ESMA) vehicle safety mandates are elevating actuator precision requirements for market access across Gulf Cooperation Council jurisdictions. South Africa's National Regulator for Compulsory Specifications (NRCS) enforces local automotive component standards that shape supplier qualification protocols for electromechanical and thermal actuator categories. Stakeholders must monitor evolving carbon-neutral vehicle targets in Egypt and Morocco, where government industrial strategies will determine whether domestic actuator production capacity expands or remains import-dependent.
Market Dynamics
Commercial fleet electrification across Saudi Arabia and the UAE is compressing actuator replacement cycles while elevating precision specifications for brake and engine management systems in heavy-duty logistics vehicles.
Growth Catalysts
- SASO Fuel Economy Standards:Saudi Arabia's tightened corporate average fuel economy mandates force OEMs to source higher-precision thermal and electromechanical actuators for powertrain optimization.
- Logistics Fleet Modernization:Dubai and Jebel Ali commercial vehicle operators are retrofitting aging fleets with smart actuator systems to meet Emirates Authority for Standardization and Metrology safety protocols.
- Local Content Requirements:Morocco's automotive industrial strategy incentivizes domestic actuator assembly, drawing component suppliers into Tangier and Casablanca manufacturing zones.
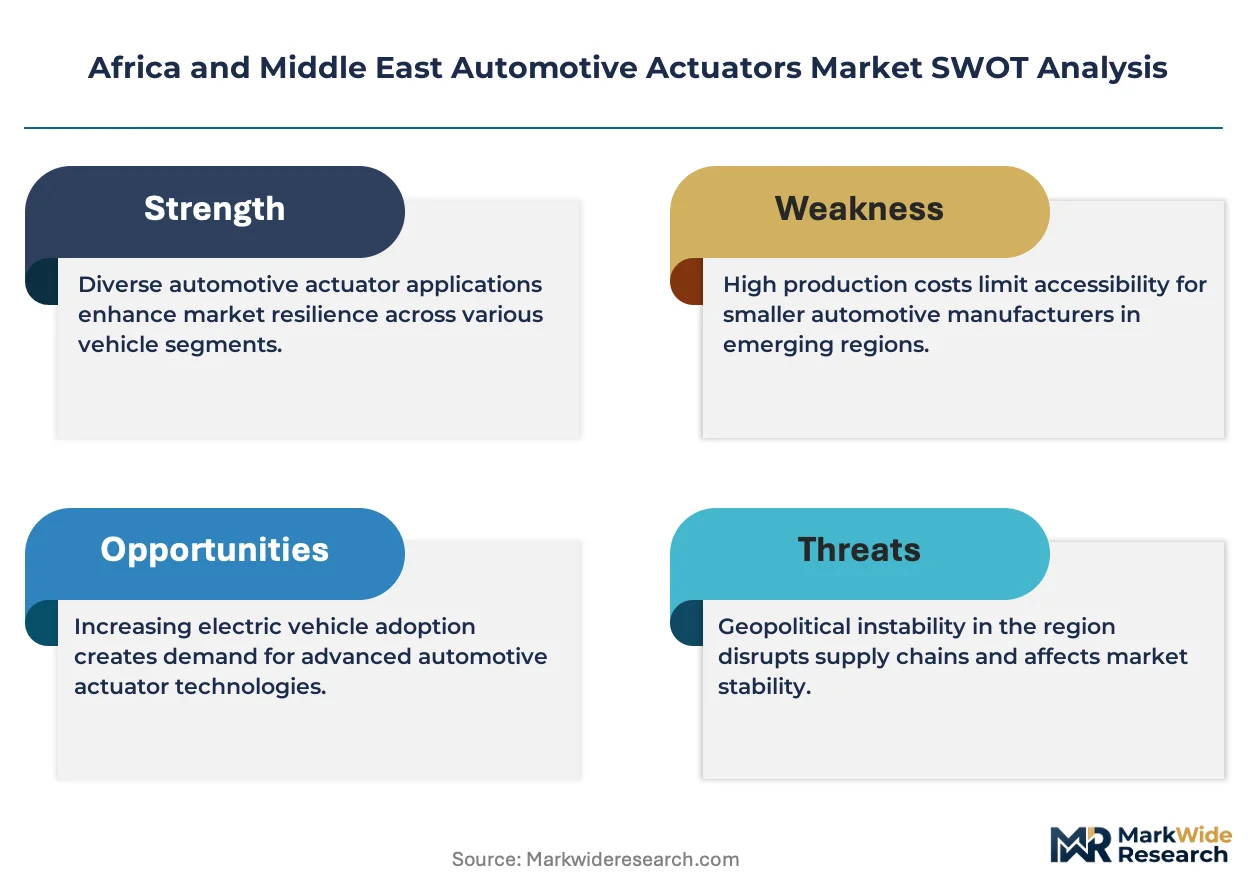
Market Restraints
- Rare Earth Magnet Volatility:Neodymium and dysprosium price swings destabilize electromechanical actuator cost structures for North African suppliers dependent on Chinese material flows.
- Single-Source Hydraulic Component Risk:Brake actuator hydraulic subsystems concentrate among European tier-one suppliers, exposing Egyptian and Moroccan OEM networks to allocation constraints.
- Thermal Tolerance Ceiling:Conventional thermal actuators face hard temperature limits around 180°C, restricting deployment in next-generation turbocharged engine compartments.
Strategic Opportunities
- Kenya Aftermarket Penetration:Nairobi and Mombasa aging vehicle parc sustains replacement demand for legacy pneumatic actuators as formal service networks expand.
- IoT-Telematics Convergence:Connected actuator systems integrating CAN bus protocols with fleet management platforms unlock predictive maintenance revenue streams for UAE logistics operators.
- Egypt Carbon-Neutral Vehicle Targets:Government industrial strategies under the National Climate Change Strategy position domestic actuator production for electric commercial vehicle qualification.
Industry Challenges
- Embedded Software Talent Scarcity:Smart actuator firmware development requires control systems engineers in short supply across South African and Gulf state manufacturing hubs.
- Dual Certification Burden:Suppliers must simultaneously satisfy South Africa's NRCS local content rules and Gulf Cooperation Council SASO/ESMA technical regulations, extending product qualification timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Africa and Middle East Automotive Actuators Market |
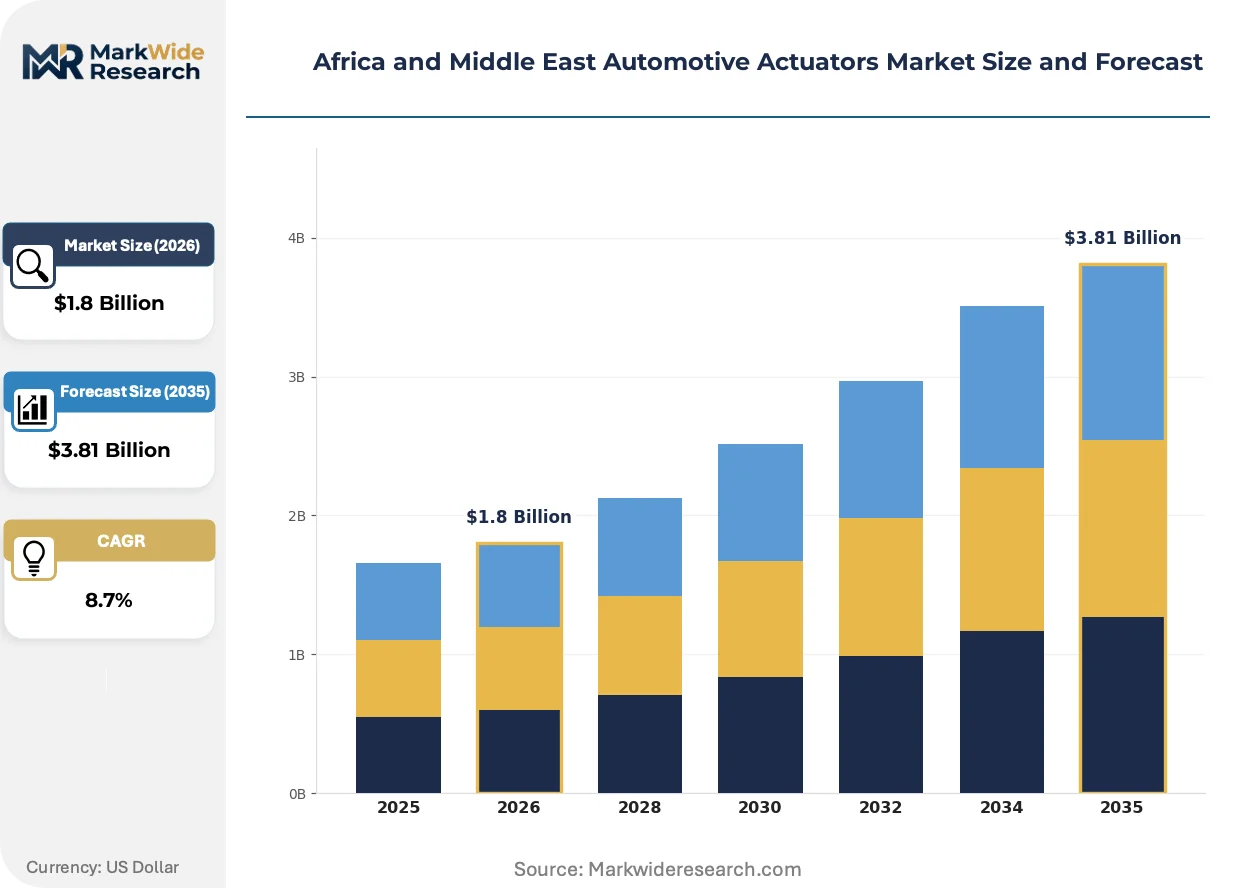
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.81 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electromechanical Actuators, Hydraulic Actuators, Pneumatic Actuators, Thermal Actuators End User: OEMs, Aftermarket Providers, Vehicle Manufacturers, Tier-1 Suppliers Technology: Smart Actuators, Autonomous Systems, IoT-Enabled Actuators, Traditional Actuators Application: Powertrain Control, Brake System, Steering System, Comfort System |
| Companies Covered | Robert Bosch GmbH, Continental AG, HELLA GmbH & Co. KGaA, Denso Corporation, Mitsubishi Electric Corporation, Johnson Electric Holdings Limited, Nidec Corporation, ZF Friedrichshafen AG, Mahle GmbH, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Africa and Middle East Automotive Actuators Market Strategic Shifts
Intelligence migration into mechanical systems is redefining actuator value propositions across African and Middle Eastern automotive supply chains, with software-defined motion control displacing purely electromechanical specifications.
Brushless DC motor integration with integrated position sensing is automating clutch and transmission actuator functions in Egyptian and Moroccan passenger vehicle assembly plants. Tier-one suppliers are embedding Hall-effect sensors and microcontrollers directly into motor housings, eliminating discrete control modules. This consolidation is automating calibration workflows and compressing supplier tier structures in North African manufacturing corridors.
SASO and ESMA coordinated safety mandates are elevating functional safety requirements to ASIL-D levels for brake-by-wire actuator systems. The regulations mandate redundant position feedback and fault-tolerant architectures for market access across Gulf Cooperation Council jurisdictions. Heavy-duty commercial vehicle platforms serving Saudi Arabia's mining and logistics sectors face the steepest compliance ramps, forcing suppliers to requalify existing electromechanical product lines.
Fleet operators in the UAE are unbundling actuator maintenance from comprehensive vehicle service contracts, creating standalone component-level procurement channels. Dubai-based logistics companies now source brake and engine management actuators through direct supplier relationships rather than OEM captive parts networks. This disintermediation is most pronounced in Jebel Ali's free trade zone, where independent service providers aggregate demand across multiple fleet operators for volume pricing leverage.
Africa and Middle East Automotive Actuators Market Segmentation
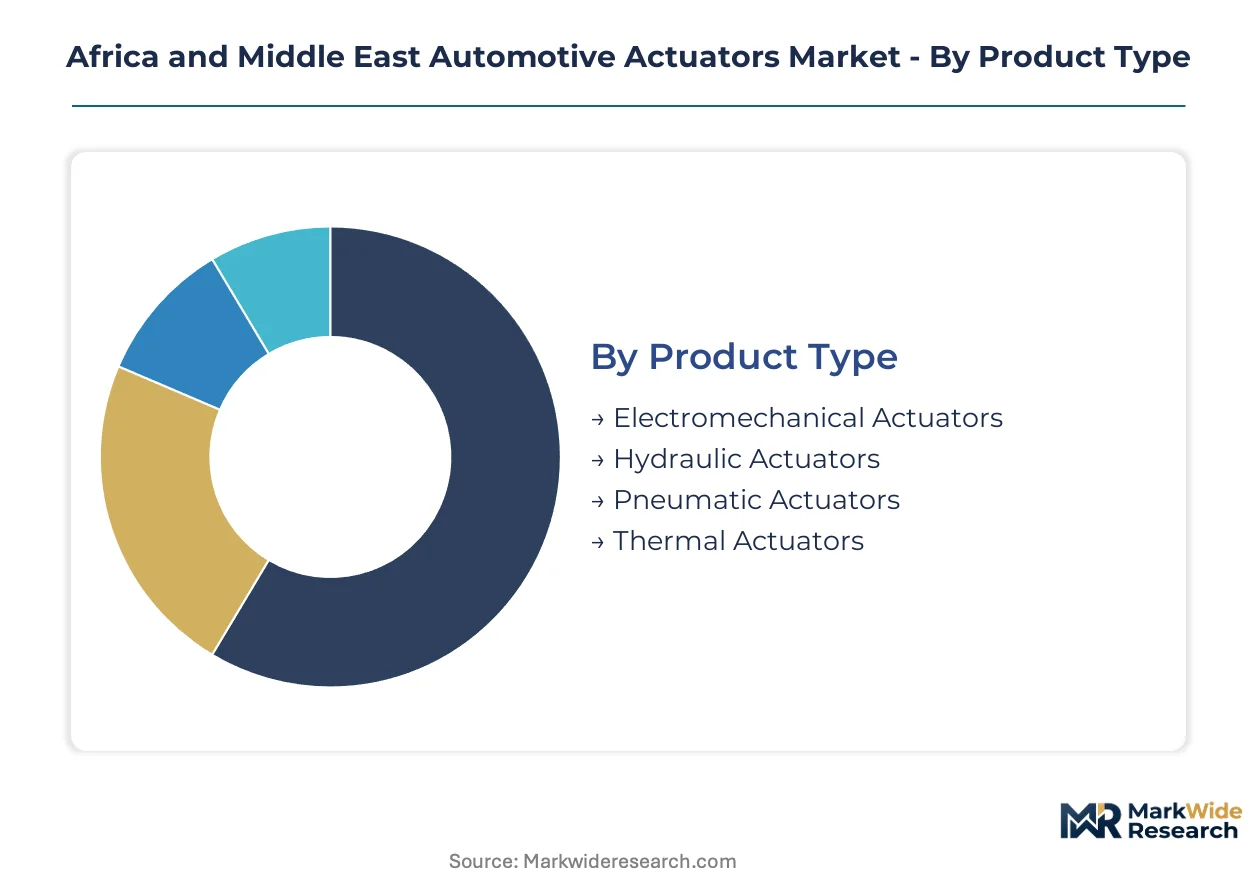
Segmentation across the Africa and Middle East Automotive Actuators Market reveals distinct certification pathways and procurement patterns. Each dimension carries specific regulatory burdens from SASO, ESMA, and NRCS that shape supplier qualification requirements and customer targeting strategies.
Product Type:
SASO fuel economy mandates and NRCS local content rules apply differentially across electromechanical versus thermal actuator categories, with electromechanical variants facing stricter electromagnetic compatibility testing in Gulf Cooperation Council jurisdictions.
- Electromechanical Actuators:Convert electrical signals into precise linear or rotary motion using brushless DC motors with integrated Hall-effect position sensing. Demand concentrates in Egyptian and Moroccan passenger vehicle assembly plants where clutch and transmission automation is accelerating. SASO electromagnetic compatibility certification represents the primary market access hurdle for this category.
- Hydraulic Actuators:Deploy pressurized fluid systems for high-force brake and steering applications in heavy-duty commercial vehicles. Procurement clusters around Dubai and Jebel Ali logistics fleet operators modernizing under ESMA safety protocols. European tier-one supplier concentration creates allocation risk exposure for North African OEM networks.
- Pneumatic Actuators:Compressed air systems dominate legacy vehicle replacement demand in Kenya's Nairobi and Mombasa aftermarket channels. NRCS standards apply selectively based on import origin classification.
- Thermal Actuators:Temperature-responsive expansion elements control HVAC and engine cooling functions. Gulf state passenger vehicle fleets drive specification requirements, though 180°C temperature ceilings restrict turbocharged engine deployment.
Leading the category by volume: Electromechanical Actuators. Growing fastest: Smart actuator variants within electromechanical architectures.
End User:
Customer type determines procurement channel structure and margin capture, with OEM captive relationships yielding volume stability while aftermarket channels offer pricing leverage through demand aggregation.
- OEMs:Original equipment manufacturers in South African vehicle assembly plants specify actuator performance standards that cascade through tiered supply chains. Long-term supply agreements with Robert Bosch GmbH and Continental AG dominate powertrain and brake system procurement.
- Aftermarket Providers:Independent service networks in Nigeria and Kenya aggregate replacement demand across aging vehicle parc. Nairobi-based distributors increasingly bypass OEM captive parts networks for direct supplier relationships.
- Vehicle Manufacturers:Egyptian and Moroccan passenger vehicle assemblers qualify actuator suppliers against NRCS local content thresholds. Domestic assembly partnerships with European tier-one suppliers satisfy regulatory requirements.
- Tier-1 Suppliers:Integrated system providers bundle actuator subsystems with control electronics for brake-by-wire and steer-by-wire platforms. ESMA functional safety mandates to ASIL-D levels drive qualification costs upward.
Highest volume concentration: OEMs. Steepest expansion trajectory: Aftermarket Providers in East African corridors.
Technology:
Technology tier correlates directly with embedded software complexity and firmware development talent scarcity across South African and Gulf state manufacturing hubs.
- Smart Actuators:Microcontroller-integrated units with CAN bus connectivity enable predictive maintenance and remote diagnostics. UAE logistics operators in Dubai and Jebel Ali lead fleet-wide deployment. Firmware development capability gaps constrain regional supplier participation.
- Autonomous Systems:Redundant position feedback architectures satisfy ASIL-D functional safety requirements for brake-by-wire applications. Saudi Arabia's mining and logistics sectors drive heavy-duty commercial vehicle qualification ramps.
- IoT-Enabled Actuators:Cellular and satellite-connected variants integrate with fleet management platforms. Telematics convergence unlocks subscription revenue streams for component suppliers serving UAE commercial operators.
- Traditional Actuators:Discrete electromechanical units without embedded intelligence dominate price-sensitive replacement markets. Kenyan and Nigerian aftermarket channels sustain demand as formal service networks expand.
Volume leadership: Traditional Actuators. Technology transition momentum: Smart Actuators climbing fastest toward mainstream adoption.
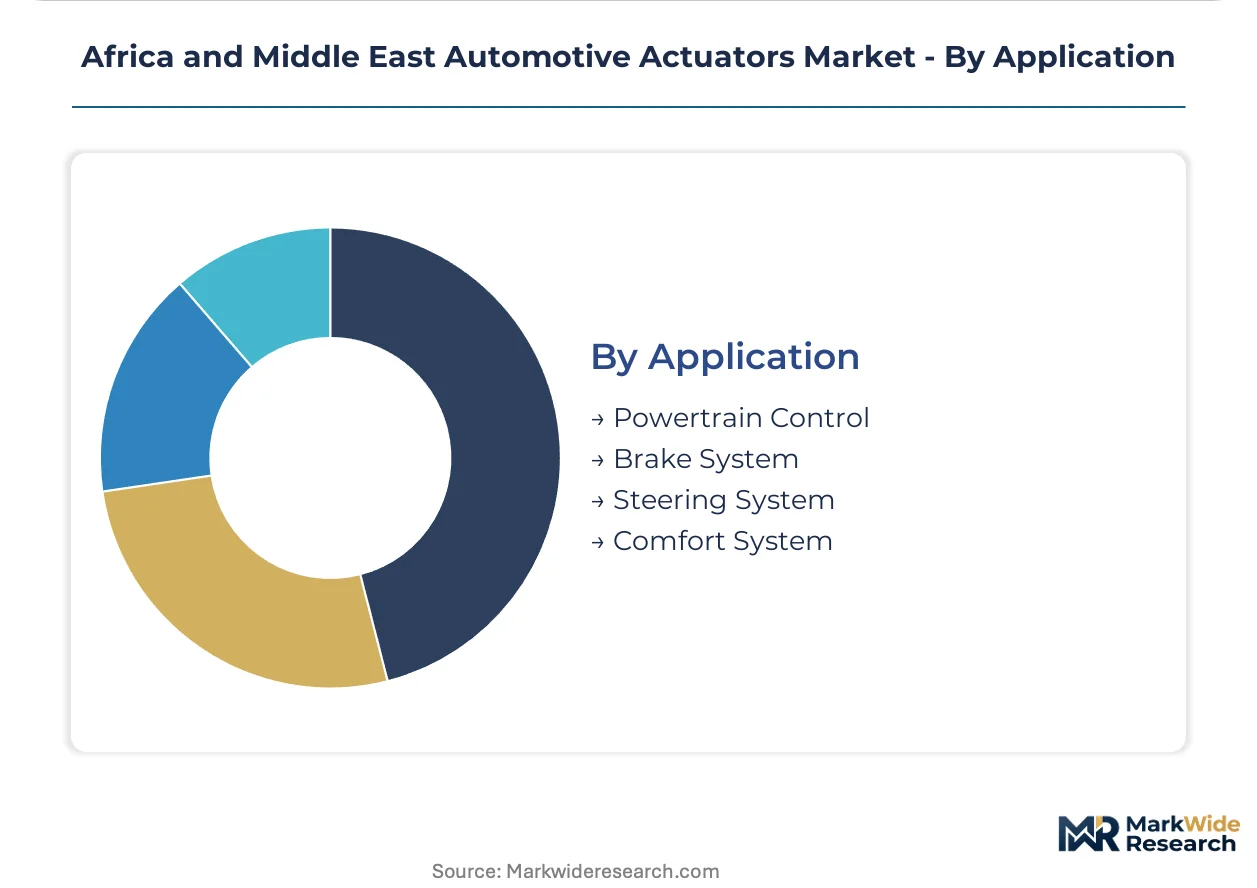
Application:
Application area dictates thermal tolerance requirements and precision specifications, with under-hood deployment demanding 150°C+ temperature ratings and brake systems requiring ASIL-D functional safety certification.
- Powertrain Control:Engine management actuators optimize fuel injection, variable valve timing, and turbocharger wastegate positioning. SASO corporate average fuel economy mandates force precision upgrades across Saudi Arabian fleet operators. Thermal tolerance requirements exceed 180°C for turbocharged applications.
- Brake System:Electromechanical brake-by-wire actuators replace hydraulic circuits in next-generation commercial vehicles. ESMA and SASO coordinated safety mandates mandate redundant architectures for Gulf Cooperation Council market access. Heavy-duty logistics platforms face steepest compliance ramps.
- Steering System:Electric power steering actuators reduce fuel consumption versus hydraulic alternatives. Moroccan and Egyptian passenger vehicle assemblers specify brushless DC motor integration with integrated position sensing.
- Comfort System:HVAC thermal actuators and seat adjustment electromechanical units target Gulf state passenger vehicle fleets. Denso Corporation specialization in this category leverages regional climate conditions.
Category volume leader: Powertrain Control. Application segment gaining share fastest: Brake System as electrification accelerates replacement cycles.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Dubai and Jebel Ali anchor commercial vehicle actuator demand across the Gulf Cooperation Council corridor, with logistics fleet modernization compressing replacement cycles for precision brake and engine management systems.
Saudi Arabia
SASO fuel economy mandates force OEMs to source higher-precision thermal and electromechanical actuators for powertrain optimization. The National Industrial Development Center incentivizes domestic manufacturing partnerships for actuator assembly. Riyadh's automotive industrial zone attracts tier-one suppliers establishing regional technical centers to satisfy local content thresholds.
United Arab Emirates
ESMA vehicle safety protocols drive smart actuator adoption across Dubai-based logistics operators managing heavy-duty commercial fleets. The Emirates Authority for Standardization and Metrology mandates ASIL-D functional safety certification for brake-by-wire systems. Jebel Ali's free trade zone enables direct procurement relationships between fleet operators and component suppliers, bypassing traditional OEM captive parts networks.
South Africa
NRCS local content rules shape supplier qualification protocols for electromechanical and thermal actuator categories serving vehicle assembly plants. The National Regulator for Compulsory Specifications enforces electromagnetic compatibility testing standards. Gauteng's automotive manufacturing corridor concentrates powertrain actuator demand as clutch and transmission automation accelerates in passenger vehicle production.
Egypt
Carbon-neutral vehicle targets under the National Climate Change Strategy position domestic actuator production for electric commercial vehicle qualification. Government industrial strategies determine whether manufacturing capacity expands or remains import-dependent. The Suez Canal Economic Zone attracts European tier-one suppliers establishing assembly operations to satisfy regional demand while managing customs efficiency.
Morocco
Automotive industrial strategy incentives draw component suppliers into Tangier and Casablanca manufacturing zones for domestic actuator assembly. Local content requirements redirect procurement toward qualified domestic producers. The Tanger Med port complex facilitates export-oriented production serving European OEM networks while satisfying regional North African demand.
Africa and Middle East Automotive Actuators Market Competitive Environment
Capital-heavy electromechanical actuator producers compete with asset-light smart actuator designers for positioning across African and Middle Eastern supply chains. The vendor base separates into three tiers: integrated system providers bundling control electronics, specialized component fabricators serving aftermarket channels, and technology licensors enabling regional assembly partnerships. Consolidation pressures concentrate among brake system suppliers where European tier-one concentration creates allocation constraints. Competitive moves center on firmware development capability acquisition and dual-certification qualification investments satisfying both NRCS local content rules and Gulf Cooperation Council technical regulations.
Among German-based integrated system providers, Robert Bosch GmbH and Continental AG anchor the electromechanical and brake actuator segments respectively, while Denso Corporation represents Japanese specialization in thermal management applications. These three entities exemplify the strategic archetype of full-system suppliers leveraging long-term OEM supply agreements to dominate powertrain and climate control procurement channels across South African assembly plants and Gulf state passenger vehicle fleets.
| Leading Market Players |
|---|
| Robert Bosch GmbH |
| Continental AG |
| HELLA GmbH & Co. KGaA |
| Denso Corporation |
| Mitsubishi Electric Corporation |
| Johnson Electric Holdings Limited |
| Nidec Corporation |
| ZF Friedrichshafen AG |
| Mahle GmbH |
| Others |
Value Chain & Pricing Dynamics
SASO fuel economy mandates and ESMA safety protocols gate qualified supply access and premium-tier pricing power across the Africa and Middle East Automotive Actuators Market. Suppliers holding dual NRCS and Gulf Cooperation Council certifications command 15-20% price premiums over single-certified competitors, while uncertified producers remain trapped in commodity aftermarket tiers.
Pricing Analysis
Value-based pricing anchored to fleet uptime outcomes dominates smart actuator procurement from UAE logistics operators. Three-tier pricing structure across premium, standard, and economy levels separates ASIL-D certified brake-by-wire systems from basic electromechanical units and legacy pneumatic replacements. Cost compression in thermal actuator categories is intensifying because 180°C temperature ceilings limit turbocharged engine deployment. Aftermarket providers in Kenya and Nigeria exhibit highest price sensitivity, while Saudi mining fleet operators prioritize performance over unit cost.
Supply Chain Analysis
Dual certification requirements for NRCS local content rules and Gulf Cooperation Council technical regulations gate supplier participation and elongate qualification timelines. Manufacturing concentrates in Germany, Japan, and China for brushless DC motor cores, Hall-effect sensors, and neodymium magnet assemblies. Rare earth magnet price volatility feeds from Chinese export quota fluctuations. Single-source vulnerability concentrates in European tier-one hydraulic brake subsystem suppliers. Distribution runs through Jebel Ali free trade zone hubs aggregating demand across multiple fleet operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Smart actuator firmware development capacity scarcity props pricing premiums across the Africa and Middle East Automotive Actuators Market. Qualified embedded control systems engineers remain concentrated in South African and Gulf state technical centers, constraining regional supplier expansion.
For Market Incumbents: Extend firmware development capabilities through targeted acquisition of South African control systems engineering teams. Deepen backward integration into brushless DC motor manufacturing to offset rare earth magnet cost volatility. Lock in long-term supply agreements with Dubai and Jebel Ali fleet operators before independent service providers consolidate demand aggregation power.
For New Entrants and Emerging Players: IoT-enabled predictive maintenance algorithms offer a technology-first wedge into UAE commercial vehicle fleet management platforms. Target Kenya's Nairobi and Mombasa aftermarket corridors where aging vehicle parc sustains replacement demand and formal service network expansion creates channel access. Pursue direct procurement relationships with independent logistics operators bypassing OEM captive parts networks.
For Investors and Strategic Acquirers: Egyptian government announcements of domestic electric commercial vehicle production subsidies are the leading indicator that actuator assembly capacity expansion will accelerate in the Suez Canal Economic Zone. Five-to-ten year viability hinges on qualification timeline compression for dual-certified suppliers. Acquisition target archetype: mid-tier electromechanical actuator fabricators with established NRCS relationships and latent Gulf Cooperation Council certification pathways.
| Strategic Initiative | Industry Significance |
|---|---|
| Dual Certification Investment | Simultaneous NRCS and SASO/ESMA qualification unlocks premium pricing across South African and Gulf state demand corridors. |
| Firmware Development Acquisition | Control systems engineering talent scarcity in Gauteng and Dubai technical centers constrains smart actuator regional production scaling. |
| Jebel Ali Distribution Hub Establishment | Free trade zone positioning enables direct fleet operator procurement relationships bypassing traditional OEM captive channels. |
| Rare Earth Magnet Supply Agreement | Long-term offtake contracts with Chinese producers stabilize electromechanical actuator cost structures against quota volatility. |
| Egyptian Assembly Partnership | Suez Canal Economic Zone manufacturing access positions suppliers for National Climate Change Strategy electric vehicle procurement. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis. Primary interviews with Tier 1 supplier procurement managers, OEM platform engineers, aftermarket distributors, and fleet operations directors in Dubai, Jebel Ali, and Johannesburg combined with SASO technical documentation, NRCS compulsory specifications, and ESMA vehicle safety mandates. Bottom-up actuator shipment data triangulated against top-down vehicle production forecasts from regional automotive manufacturing databases.
Granularity-level modeling operated at product type, end user, technology tier, and application segment dimensions across the projection horizon. Vehicle class, propulsion architecture, and content per vehicle variations shaped unit demand estimates. CAGRs derived from regression analysis of historical certification timelines and fleet replacement cycle compression rates. Electromagnetic compatibility testing passage rates and functional safety ASIL-D qualification costs informed technology transition assumptions.
Several conditions sit outside the modeled scope, including unannounced revisions to SASO fuel economy mandates, abrupt rare earth export restrictions, and geopolitical disruptions affecting Suez Canal logistics corridors. Forecasts reflect assumptions about certification timeline stability and fleet electrification program continuity. A model refresh is warranted upon material change in Egyptian domestic manufacturing incentive announcements or UAE logistics operator consolidation patterns.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Components
Global Automotive Composite Market
Automotive Components
Global Automotive Components Forging Market
Automotive Components
Automotive Filters Market
Automotive Components
Automotive Fender Market
Automotive Components
Global Automotive Thermal Management Market
Automotive Components
Automotive Instrument Cluster Market
Automotive Components
Automotive Brake Pads Market
Automotive Components
Metal Forming for Automotive Market
Automotive Components
Italy Automotive Sunroof Market
Automotive Components
Automotive Metal Timing Chain Market
Automotive Components
Asia Pacific Automotive Actuators Market
Automotive Components
MEMS Automobile Sensors Market
Automotive Components
Automotive Tie Rod Market
Automotive Components
China Automotive Composites Market
Automotive Components
Beryllium Copper for Automobile Market
Automotive Components
Mexico Automotive Pneumatic Actuators Market