
 France Automotive Parts Magnesium Die Casting Market | 2026-2036
France Automotive Parts Magnesium Die Casting Market Size, Share, and Industry Trends Forecast 2026-2036
France Automotive Parts Magnesium Die Casting Market Foresight
High-pressure die casting automation is reshaping how magnesium structural parts achieve dimensional precision at production scale. Meridian Lightweight Technologies leverages European foundry networks to sustain capacity for OEM programs. Brabant Alucast anchors its position through specialization in thin-wall transmission housings. George Fischer Ltd competes via integrated tooling and machining capabilities that reduce secondary operations.
France Automotive Parts Magnesium Die Casting refers to the net-shape forming of AZ91D and AM60B magnesium alloys into automotive components using steel dies and controlled thermal cycling, yielding parts with density one-quarter that of steel and superior vibration damping. The primary commercial purpose is mass reduction in vehicle platforms where every kilogram saved directly improves fleet emissions compliance. High pressure die casting dominates current tonnage due to its cycle speed and surface finish quality, while squeeze die casting captures margin pools in structural nodes requiring zero porosity. Engine components and chassis components represent the deepest existing demand, though crash management systems show the fastest application expansion as safety structures lighten.
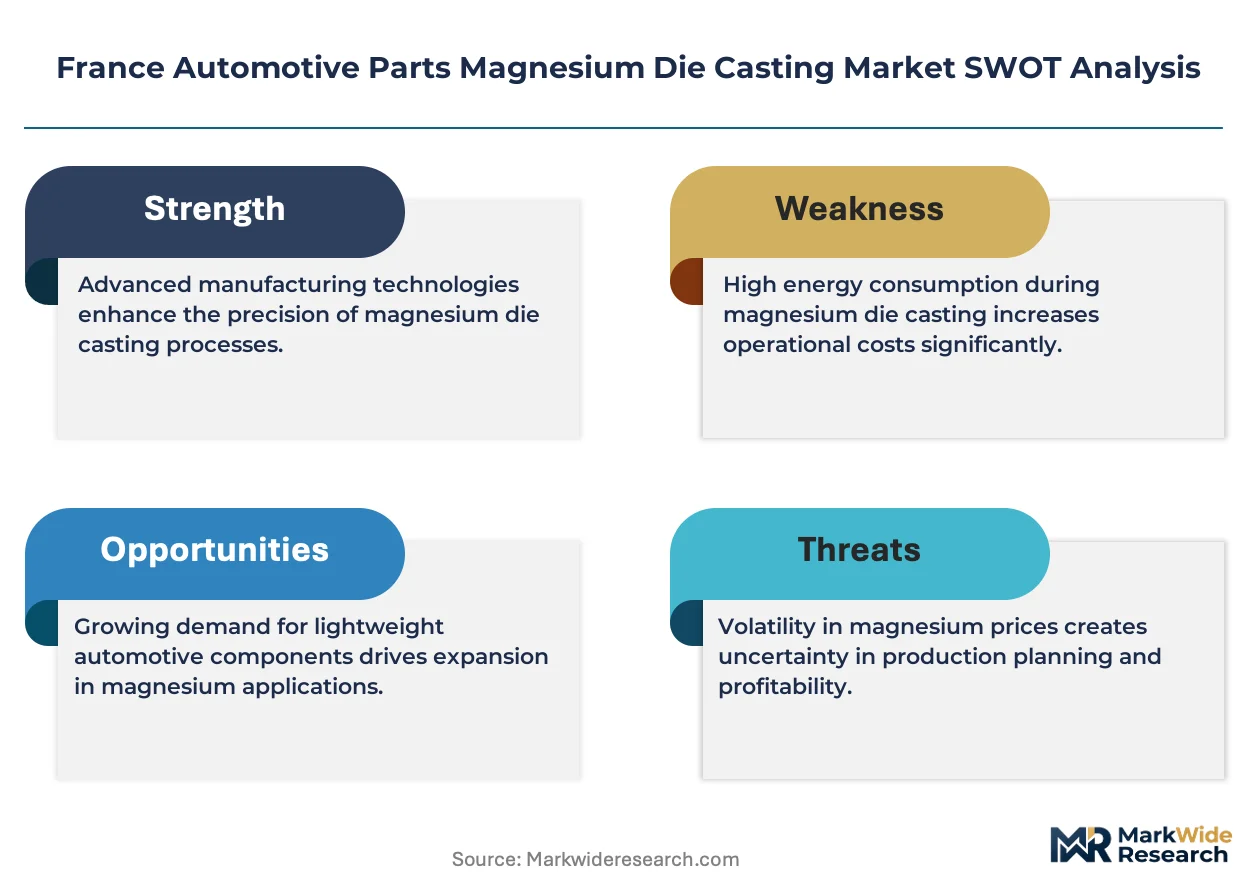
France's environmental regulator applies EU CO2 fleet standards through national enforcement mechanisms that penalize overweight vehicle platforms. REACH and the EU Green Deal constrain raw material sourcing and mandate recycled content thresholds that reshape supplier qualification. ANSM workplace exposure limits affect foundry automation investment decisions. Stakeholders must monitor how battery electric platform architectures redistribute magnesium demand away from traditional powertrain locations toward battery housings and motor mounts.
Market Dynamics
France's automotive magnesium die casting sector pivots on the tension between EU CO2 fleet enforcement and the technical complexity of substituting steel with magnesium in safety-critical structures. Foundries must simultaneously satisfy ANSM workplace exposure mandates while scaling capacity for battery electric vehicle architectures that relocate material demand away from traditional powertrain locations.
Growth Catalysts
- EU Green Deal recycled content mandates:OEM procurement specifications now require minimum post-consumer magnesium ratios, qualifying domestic foundries with established scrap recovery loops for long-term supply contracts.
- Battery housing integration:Electric platform architectures from Stellantis and Renault specify magnesium for motor mounts and battery enclosures, opening tonnage pools previously served by aluminum extrusions.
- Rhône-Alpes cluster density:Proximity to Lyon-based Tier-1 stamping and machining operations compresses logistics costs and enables just-in-sequence delivery to Saint-Étienne assembly plants.
Market Restraints
- Primary magnesium supply concentration:Over 85% of global smelting capacity sits in China, exposing French foundries to export quota volatility and ocean freight rate swings.
- REACH authorization complexity:ECHA substance evaluation timelines for magnesium alloy additives extend qualification periods for new formulations, freezing product development cycles.
- Aluminum 6xxx-series substitution:Crash-relevant structural nodes increasingly specify high-strength aluminum when magnesium wall thickness requirements exceed castability limits.
Strategic Opportunities
- Battery tray deep-drawing replacement:Squeeze die casting of AZ91D offers net-shape forming for complex cooling channel geometries that stamped aluminum cannot achieve.
- Nord-Pas-de-Calais reshoring corridor:Dunkirk port infrastructure and existing steel foundry conversion candidates support magnesium capacity expansion for UK and Benelux OEM programs.
- CSRD supply chain disclosure rules:Mandatory Scope 3 emissions reporting pushes OEMs toward EU-sourced magnesium with verified low-carbon smelting credentials.
Industry Challenges
- High-pressure die casting technician scarcity:ANSM-mandated molten metal handling certifications require 18-month apprenticeship periods that outpace retirement-driven workforce attrition in Auvergne-Rhône-Alpes.
- Multi-material joining validation:Dissimilar metal corrosion between magnesium and steel/aluminum interfaces demands proprietary coating development that extends OEM approval timelines by 24-36 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | France Automotive Parts Magnesium Die Casting Market |
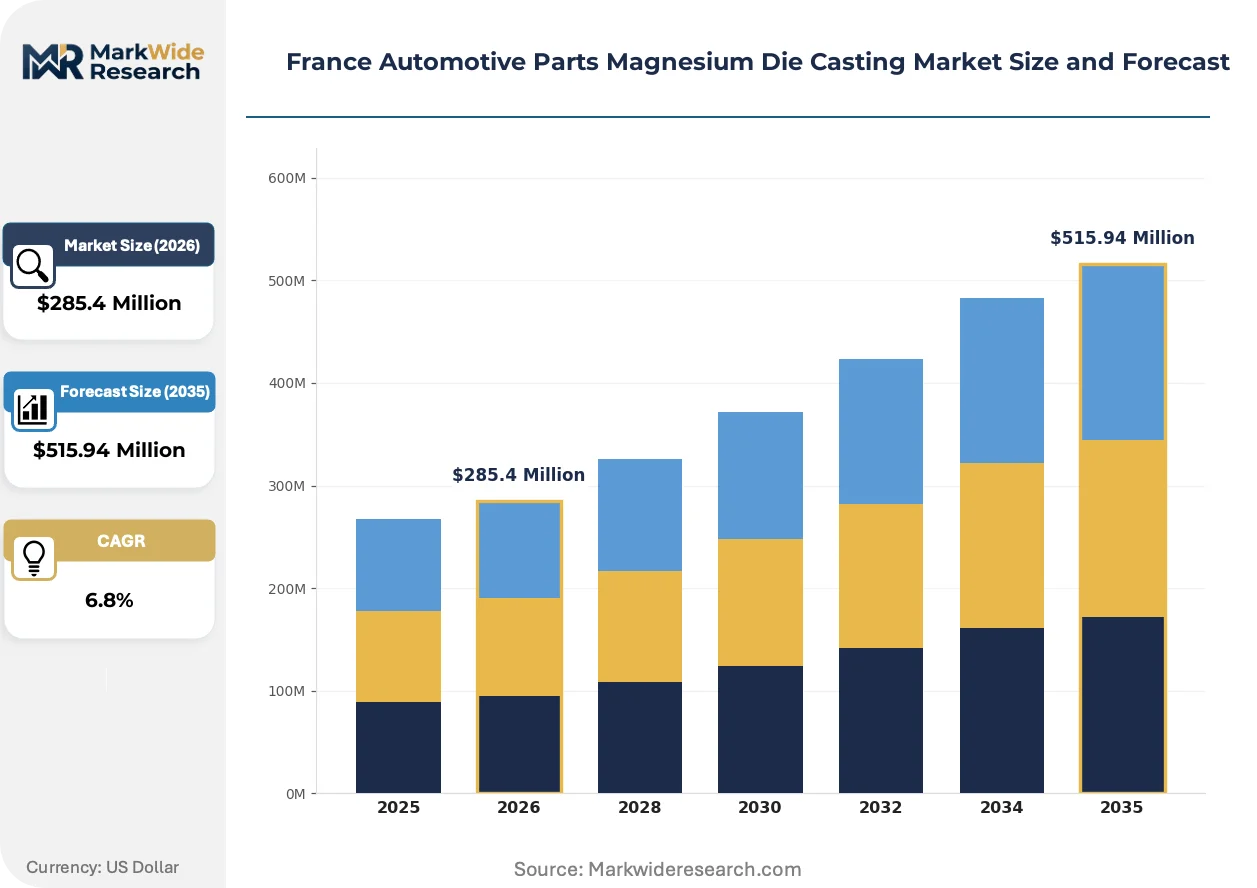
| Market Size in 2026 | $285.4 Million |
| Market Size in 2035 | $515.94 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Engine Components, Transmission Parts, Chassis Components, Interior Fixtures, Exterior Fittings Technology: High Pressure Die Casting, Low Pressure Die Casting, Gravity Die Casting, Squeeze Die Casting Application: Lightweight Structural Parts, Heat Dissipation Components, Vibration Damping Elements, Crash Management Systems End User: OEM Manufacturers, Tier-1 Suppliers, Aftermarket Providers, Vehicle Assemblers |
| Companies Covered | Pace Industries, Brabant Alucast, Meridian Lightweight Technologies, Continental Casting LLC, Chicago White Metal Casting Inc, Gibbs Die Casting Group, Shiloh Industries Inc, MK Group Of Companies, George Fischer Ltd, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
France Automotive Parts Magnesium Die Casting Market Shifts & Advancements
Process instrumentation and alloy formulation advances are compressing development cycles while regulatory disclosure requirements reshape supplier qualification. Foundries that integrate real-time thermal monitoring with predictive maintenance protocols capture margin pools lost to dimensional drift and unplanned downtime.
Real-time cavity temperature monitoring is digitizing quality assurance in high-pressure die casting operations. Tier-1 suppliers serving Renault and Stellantis deploy distributed sensor arrays that feed machine learning models predicting porosity formation before ejection. This capability compresses first-article inspection timelines and reduces scrap rates that previously eroded thin-wall transmission housing economics.
REACH Annex XIV authorization expansion is tightening raw material traceability requirements for magnesium alloy additives. ECHA evaluations of cerium and lanthanum-containing grain refiners now demand full supply chain substance mapping from smelter to finished component. French foundries with established laboratory partnerships for ICP-MS testing capture qualification advantages over competitors relying on external certification.
Consolidated Tier-1 procurement is compressing supplier panels and extending contract durations. Stellantis and Renault now mandate single-source magnesium die casting responsibility for entire vehicle platform families, displacing multi-foundry sourcing strategies. This concentration rewards Auvergne-Rhône-Alpes operations with proven volume scalability and integrated machining capabilities.
France Automotive Parts Magnesium Die Casting Market Segmentation
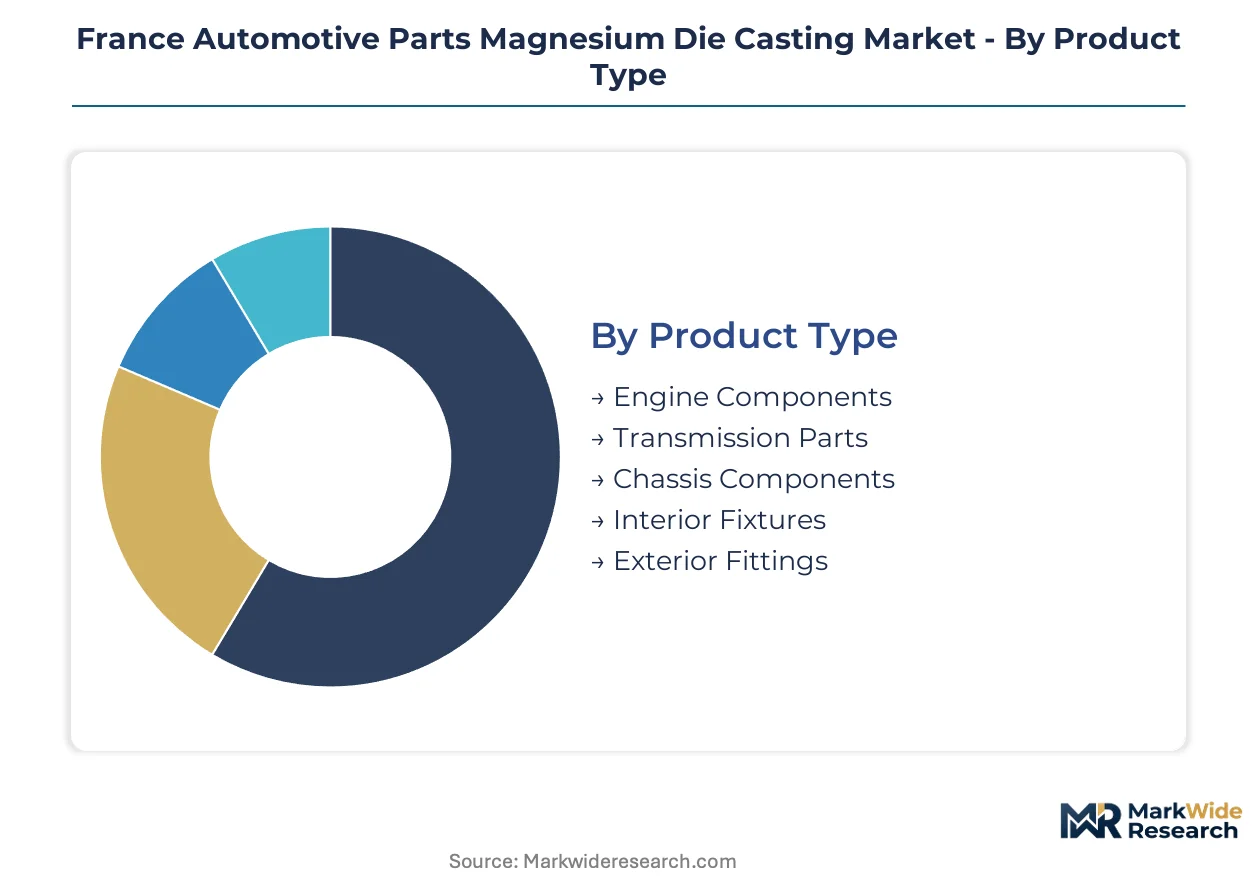
Segmentation reveals how magnesium die casting demand concentrates across technical specifications and supply chain tiers in France. Each dimension exposes different margin structures, qualification barriers, and growth trajectories that shape supplier strategy.
Product Type:
After-sales service intensity varies sharply across component categories, with powertrain parts demanding specialized remanufacturing capabilities that aftermarket networks struggle to replicate.
- Engine Components:AZ91D alloy valve covers and oil pans achieve wall thicknesses below 2mm through high-pressure die casting. Demand clusters around Renault's Douai powertrain plant and Stellantis's Trémery facility, where ANSM-mandated molten metal handling certifications constrain supplier qualification. CO2 fleet enforcement drives magnesium substitution for aluminum in these applications.
- Transmission Parts:AM60B housings for dual-clutch and electric drive units require superior elongation properties for bolted joint integrity. Auvergne-Rhône-Alpes foundries serving Saint-Étienne assembly plants capture volume through just-in-sequence delivery integration.
- Chassis Components:Crossmembers and subframe nodes exploit magnesium's vibration damping for NVH performance.
- Interior Fixtures:Steering wheel armatures and seat frames prioritize surface finish quality over structural load.
- Exterior Fittings:Door handles and mirror housings compete with painted plastic on cost and cosmetic durability.
Engine Components holds the largest share; momentum sits with Chassis Components as electric platforms redistribute structural loads.
Technology:
Process selection determines capital intensity, cycle economics, and the defect rates that OEMs now monitor through real-time data feeds.
- High Pressure Die Casting:Locking forces exceeding 4,000 tonnes inject molten magnesium at 70-100 m/s into hardened steel dies, achieving 30-second cycle times for thin-wall transmission housings. Rhône-Alpes operations serving Lyon-based Tier-1 machining centers dominate this segment through automated trim press integration.
- Squeeze Die Casting:Controlled solidification under mechanical pressure eliminates porosity in battery tray and motor mount applications requiring X-ray qualification. Renault's electric platform specifications now mandate this process for safety-critical nodes.
- Low Pressure Die Casting:Gravity-fed filling with applied gas pressure suits wheels and aesthetic components where surface integrity matters.
- Gravity Die Casting:Manual ladle pouring persists for prototype volumes and legacy aerospace crossover parts.
High Pressure Die Casting commands the greatest installed capacity; squeeze die casting is gaining share fastest as battery housing specifications tighten.
Application:
Functional requirements dictate alloy selection, with structural applications demanding AM60B ductility and thermal applications tolerating AZ91D brittleness.
- Lightweight Structural Parts:AM60B subframe nodes and motor mounts achieve 30-40% mass reduction versus aluminum equivalents. Stellantis's electric platform programs specify these for battery pack support structures where crash pulse management is critical.
- Crash Management Systems:Controlled crush behavior in magnesium front rails and bumper beams enables pedestrian protection compliance. Development concentrates around Renault's Technocentre in Guyancourt with validation at Lardy test facilities.
- Heat Dissipation Components:AZ91D's thermal conductivity serves LED headlight housings and power electronics enclosures.
- Vibration Damping Elements:Magnesium's internal friction coefficient benefits steering column brackets and HVAC mounting.
Lightweight Structural Parts represents the deepest revenue pool; Crash Management Systems shows the steepest expansion trajectory as safety structures lighten.
End User:
Procurement authority and technical specification control diverge across the supply chain, with OEMs increasingly consolidating magnesium sourcing under single-source platform responsibility.
- OEM Manufacturers:Renault and Stellantis direct magnesium specifications for powertrain and battery housing applications, leveraging CSRD supply chain disclosure rules to favor EU-sourced material with verified low-carbon smelting credentials. Platform-level sourcing agreements now span 7-10 year horizons.
- Tier-1 Suppliers:Faurecia and Valeo integrate magnesium die casting into module assemblies for Saint-Étienne and Sochaux vehicle plants, capturing value through machining and coating integration.
- Vehicle Assemblers:Contract manufacturers lack specification authority but drive volume consolidation through platform sharing.
- Aftermarket Providers:Limited to cosmetic trim and non-structural replacement parts due to liability and joining complexity barriers.
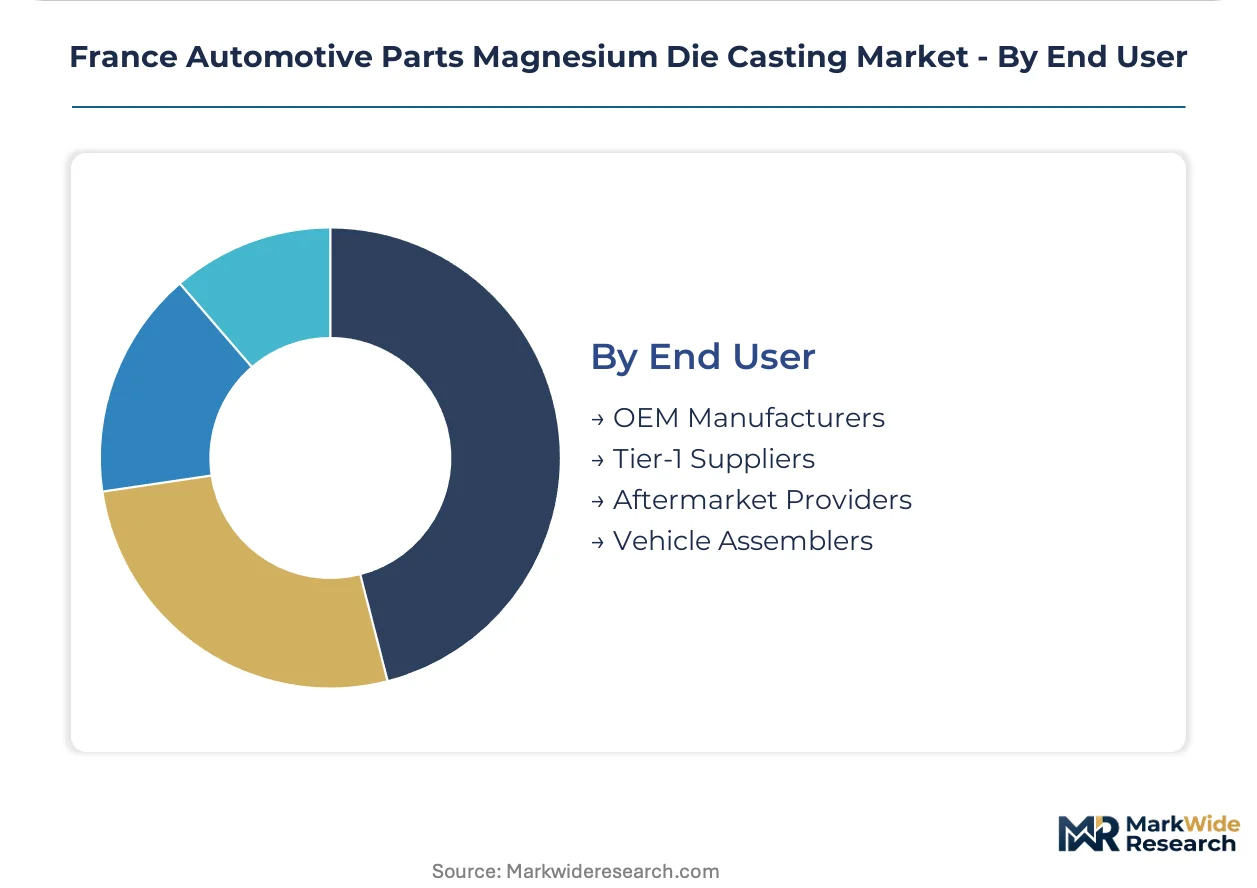
OEM Manufacturers concentrate specification control; Tier-1 Suppliers are capturing the fastest volume growth through module integration mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyer archetypes in France's automotive magnesium die casting sector cluster around OEM platform engineering teams and Tier-1 module integrators seeking proximity to Saint-Étienne assembly operations. Procurement authority concentrates with manufacturers pursuing CSRD-compliant supply chain disclosure.
Auvergne-Rhône-Alpes
Powertrain housing demand from Renault's Douai and Stellantis's Trémery plants drives magnesium adoption for valve covers and oil pans. ANSM workplace exposure mandates require 18-month apprenticeship certifications for molten metal handling. Lyon-based Tier-1 machining centers enable just-in-sequence delivery compression to Saint-Étienne vehicle plants.
Île-de-France
Crash management system development for electric platforms concentrates around Renault's Technocentre in Guyancourt. ECHA REACH evaluations of cerium-containing grain refiners demand full supply chain substance mapping from smelter to finished component. Lardy validation facilities anchor pedestrian protection compliance testing for magnesium front rail designs.
Hauts-de-France
Battery housing integration opportunities attract investment toward Dunkirk port infrastructure and steel foundry conversion candidates. EU Green Deal recycled content mandates qualify operations with established scrap recovery loops for long-term OEM contracts. The Nord-Pas-de-Calais corridor supports capacity expansion serving UK and Benelux automotive programs.
Provence-Alpes-Côte d'Azur
Heat dissipation component demand from LED headlight and power electronics applications leverages AZ91D thermal conductivity properties. Regional aerospace crossover expertise supports prototype gravity die casting for legacy specialty volumes. Marseille-Fos port access facilitates raw material inbound logistics from Mediterranean smelting sources.
France Automotive Parts Magnesium Die Casting Market Competitive Landscape
Channel-controlling players compete with product-specialist players across a moderately consolidated vendor base where platform-level sourcing agreements now span 7-10 year horizons. Tier-1 module integrators capture value through machining and coating integration while foundries with automated trim press operations dominate thin-wall transmission housing economics. Three archetypes define positioning: European foundry network operators, thin-wall transmission housing specialists, and integrated tooling-machining providers. Competitive moves center on single-source platform responsibility consolidation and real-time cavity temperature monitoring deployment.
Within the European foundry network tier, Meridian Lightweight Technologies occupies a position exemplifying capacity scalability for OEM programs. Brabant Alucast anchors the thin-wall specialization vector through its nomenclature-derived casting focus. George Fischer Ltd represents the integrated tooling-machining archetype, with its corporate suffix indicating limited liability structure and its name suggesting upstream process control capabilities.
| Leading Market Players |
|---|
| Pace Industries |
| Brabant Alucast |
| Meridian Lightweight Technologies |
| Continental Casting LLC |
| Chicago White Metal Casting Inc |
| Gibbs Die Casting Group |
| Shiloh Industries Inc |
| MK Group Of Companies |
| George Fischer Ltd |
| Others |
Supply & Pricing Matrix
Dunkirk port freight corridors anchor inbound magnesium logistics from Mediterranean and Chinese smelters, with ocean rate volatility transmitting directly to AZ91D alloy contract pricing and compressing margin pools for Auvergne-Rhône-Alpes foundries serving Saint-Étienne assembly plants.
Pricing Analysis
Long-term offtake contracts with London Metal Exchange-linked indexation dominate procurement between French foundries and OEM platform engineering teams. Price differentiation hinges on squeeze die casting certification tier and integrated machining depth. Cost compression in standard high-pressure die castings is intensifying because aluminum 6xxx-series substitution threatens volume pools. Tier-1 module integrators exhibit lowest price sensitivity due to pass-through mechanisms, while aftermarket providers face acute margin pressure from Chinese import competition.
Supply Chain Analysis
Supply-chain finance facilities with 90-day extended terms have become standard between Rhône-Alpes foundries and Lyon-based machining centers, compressing working capital for operations without captive scrap recovery. Primary magnesium smelting concentrates in China, Russia, and Israel, with French foundries drawing from Chinese export quotas and Israeli Dead Sea Works output. The supply chain rests on ocean freight exposure through Mediterranean and Atlantic routes. Distribution runs through just-in-sequence pipelines to Saint-Étienne and Sochaux vehicle plants.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
France's automotive magnesium die casting sector sits in a cyclical recovery phase driven by battery electric platform launches from Stellantis and Renault redistributing material demand toward battery housings and motor mounts.
For Market Incumbents: Build technical moats around real-time cavity temperature monitoring and predictive maintenance protocols that machine learning models deploy for porosity prevention. Defensive consolidation should prioritize backward integration into scrap recovery loops qualifying for EU Green Deal recycled content mandates. Threats from aluminum substitution in crash-relevant nodes demand AM60B alloy formulation R&D investment to extend castability limits.
For New Entrants and Emerging Players: Battery tray deep-drawing replacement opportunities in Hauts-de-France represent the most penetrable entry point, with Dunkirk port infrastructure and steel foundry conversion candidates supporting capacity expansion. Squeeze die casting specialization for Renault's electric platform safety-critical nodes offers qualification pathways absent from saturated high-pressure die casting segments. Go-to-market execution should anchor on CSRD-compliant supply chain disclosure partnerships with OEMs seeking EU-sourced magnesium credentials.
For Investors and Strategic Acquirers: Automated trim press operations with proven volume scalability in Auvergne-Rhône-Alpes constitute the acquisition target archetype with durable positioning under single-source platform responsibility consolidation. Long-term viability across the next decade hinges on battery electric architecture penetration rates and magnesium's share of battery housing material specifications. The signal to watch is ECHA REACH authorization timelines for cerium-containing grain refiners, which would freeze product development cycles and reshape competitive qualification.
| Strategic Initiative | Industry Significance |
|---|---|
| Squeeze Die Casting Capacity Expansion | Captures Renault battery tray specifications requiring zero-porosity X-ray qualification. |
| Scrap Recovery Loop Integration | Qualifies foundries for EU Green Deal recycled content procurement mandates. |
| Real-Time Cavity Monitoring Deployment | Compresses first-article inspection timelines for Lyon Tier-1 machining centers. |
| Nord-Pas-de-Calais Manufacturing Footprint | Positions capacity to serve UK and Benelux OEM programs through Dunkirk logistics. |
| CSRD Supply Chain Disclosure Partnership | Aligns with Stellantis and Renault Scope 3 emissions reporting requirements. |
Research Methodology
The analysis maps high-pressure die casting, squeeze die casting, and gravity die casting sub-sectors, each validated through primary interviews with OEM platform engineers, Tier-1 procurement leads, foundry operations managers, and ANSM compliance officers, combined with secondary validation from ECHA REACH substance databases, EU customs trade flows, vehicle production registries, and SEC filings of listed automotive suppliers, employing bottom-up volume triangulation against top-down OEM platform material specifications.
Forecast assumptions held battery electric vehicle penetration and EU CO2 fleet enforcement trajectories fixed while varying magnesium-aluminum substitution elasticities and primary smelting capacity expansion scenarios across the projection horizon. Segmentation dimensions modeled include product type, casting technology, application function, and end-user procurement authority, with CAGRs derived from slope-log regression against historical tonnage flows and OEM platform launch schedules, incorporating content-per-vehicle assumptions for transmission housings and battery enclosures.
Macroeconomic conditions sit as an overlay; deviation in ocean freight rates, Chinese export quota policy, or euro-dollar exchange dynamics would shift the trajectory. Forecasts reflect documented assumptions regarding alloy formulation qualification timelines and ECHA authorization pathways. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Automotive Parts
Iran Automotive Engine Oils Market
Automotive Parts
Automotive Hoses Market
Automotive Parts
Autonomous Forklift Market
Automotive Parts
Racing Vehicles Market
Automotive Parts
Camshaft Bearings Market
Automotive Parts
Bearing Steel Balls for New Energy Vehicles Market
Automotive Parts
Automotive Engine Cooling Fan Market
Automotive Parts
Electric Power Steering Market
Automotive Parts
Automotive Fuel Accumulator Market
Automotive Parts
Two Speed Gearbox Market
Automotive Parts
China Automotive Parts Magnesium Die Casting Market
Automotive Parts
Global Automotive Plain Carbon ERW Tubes Market
Automotive Parts
Power Steering Oil Market
Automotive Parts
Automotive Oil and Valve Stem Seals Market
Automotive Parts
Ball Bearing Market
Automotive Parts
Australia Automotive Airfilters Market