
 Robo-Advisory Software Market | 2026-2036
Robo-Advisory Software Market Size, Share, and Industry Trends Forecast 2026-2036
Robo-Advisory Software Market Analytics
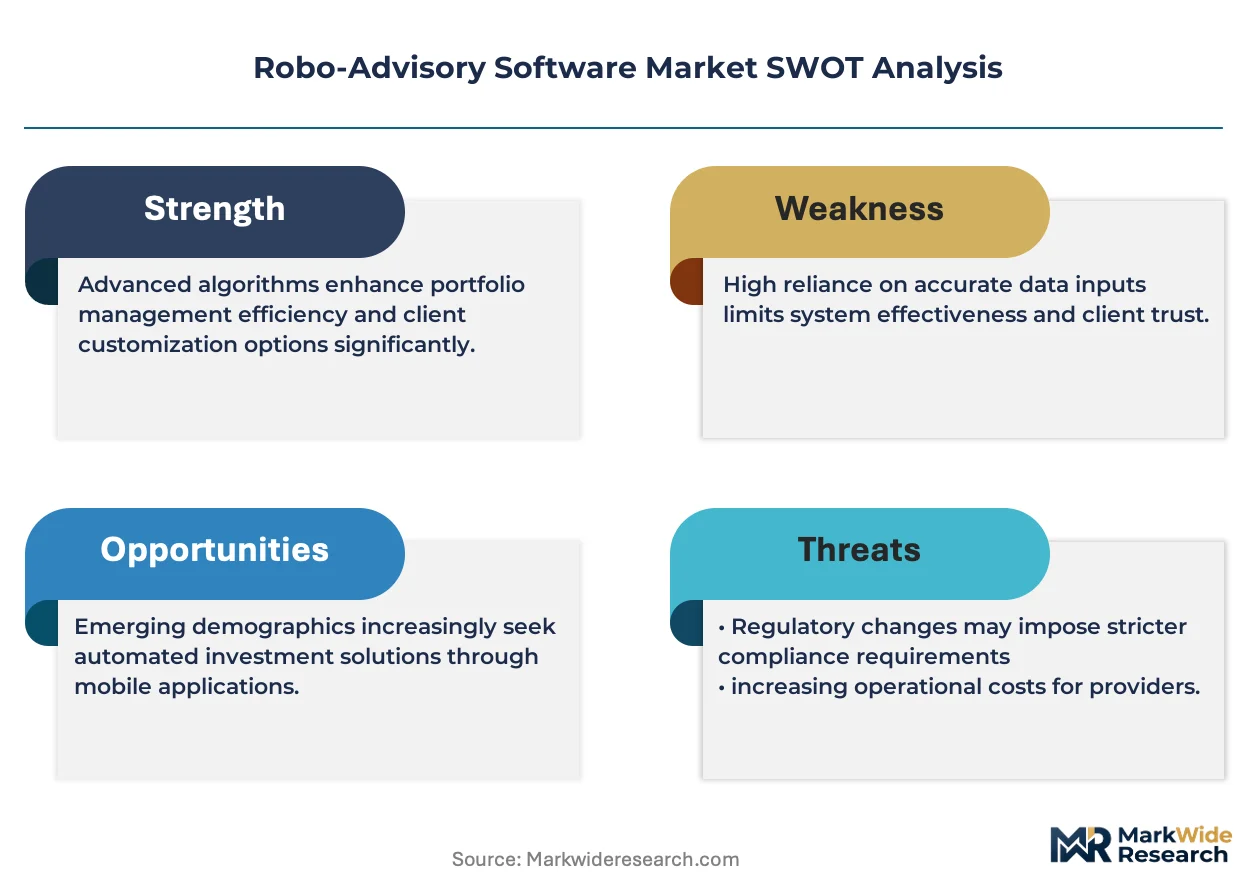
CFP Board certification and Series 65 licensing requirements are redrawing competitive boundaries in automated wealth management. The Vanguard Group leverages its mutual fund infrastructure to anchor hybrid robo-human advisory models at scale. Charles Schwab Corporation sustains price disruption through zero-commission positioning integrated with Intelligent Portfolios. Betterment specializes in tax-loss harvesting sophistication and goal-based financial planning interfaces for mass-affluent households.
Robo-advisory software deploys algorithmic portfolio construction engines that rebalance across exchange-traded funds based on Modern Portfolio Theory risk parameters and client-declared time horizons. Its commercial purpose centers on delivering institutional-grade asset allocation to retail investors at fractional cost structures relative to traditional human advisors. Cloud-based deployment dominates operational architecture due to elastic compute requirements for real-time Monte Carlo simulation and automated rebalancing triggers. Subscription-based pricing captures recurring revenue predictability, while performance fee structures concentrate among platforms serving high-net-worth segments through white-label arrangements with wealth management firms.
The SEC enforces fiduciary standards through Regulation Best Interest, compelling robo-advisors to document algorithmic suitability logic and conflict-of-interest disclosures. The EU's MiFID II mandates granular cost transparency and periodic suitability assessments, forcing European platforms to rebuild client onboarding architectures. The UK's FCA operational resilience requirements and Singapore's MAS technology risk management guidelines add compliance layers for multi-jurisdictional providers. Stakeholders must monitor evolving algorithmic accountability frameworks as regulators scrutinize black-box investment recommendation engines for disparate impact across demographic cohorts.
Market Dynamics
Algorithmic fiduciary accountability is decomposing traditional fee structures as regulators mandate explainable AI logic for investment recommendations across multiple jurisdictions.
Growth Catalysts
- SEC Regulation Best Interest:The SEC's fiduciary standard compels broker-dealers to document algorithmic suitability logic, accelerating compliance-integrated platform adoption among registered investment advisors in the United States.
- ETF infrastructure maturation:Low-cost exchange-traded fund ecosystems enable fractional institutional-grade asset allocation, democratizing portfolio construction for mass-affluent households previously excluded from wealth management services.
- Cloud-native architecture:Elastic compute environments support real-time Monte Carlo simulation and automated rebalancing triggers, reducing operational overhead for emerging fintech challengers competing against established custodians.
Market Restraints
- Algorithmic opacity risk:Black-box recommendation engines face heightened scrutiny for disparate impact across demographic cohorts, creating liability exposure under emerging algorithmic accountability frameworks in the European Union.
- Concentrated cloud dependency:Dominant hyperscaler infrastructure creates single-point-of-failure vulnerabilities for real-time portfolio management systems serving time-sensitive rebalancing functions.
- Human advisor substitution ceiling:Complex estate planning and behavioral coaching requirements limit pure-robo penetration among ultra-high-net-worth segments requiring bespoke trust structuring and intergenerational wealth transfer guidance.
Strategic Opportunities
- Hybrid advisory white-labeling:Regional banks and credit unions seek turnkey algorithmic infrastructure to compete against national broker-dealers without proprietary technology development costs.
- Tax-loss harvesting sophistication:Direct indexing capabilities enable security-level loss realization unavailable through mutual fund wrappers, attracting taxable brokerage assets from sophisticated retail investors.
- EU MiFID II cost transparency mandates:Granular fee disclosure requirements create competitive opening for platforms with native embedded finance architecture and automated ex-ante cost projection engines.
Industry Challenges
- CFP-credentialed talent scarcity:Hybrid models require licensed professionals capable of interpreting algorithmic outputs for complex client situations, constraining scalable human-capital deployment.
- Multi-jurisdictional compliance engineering:Simultaneous adherence to SEC, FCA, MAS, and EU regulatory architectures demands modular rule-engine infrastructure with jurisdiction-specific logic branching.
- Legacy core system integration:Established wealth management firms operate on decades-old custodial platforms resistant to API-native connectivity, extending implementation timelines for algorithmic overlay deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Robo-Advisory Software Market |
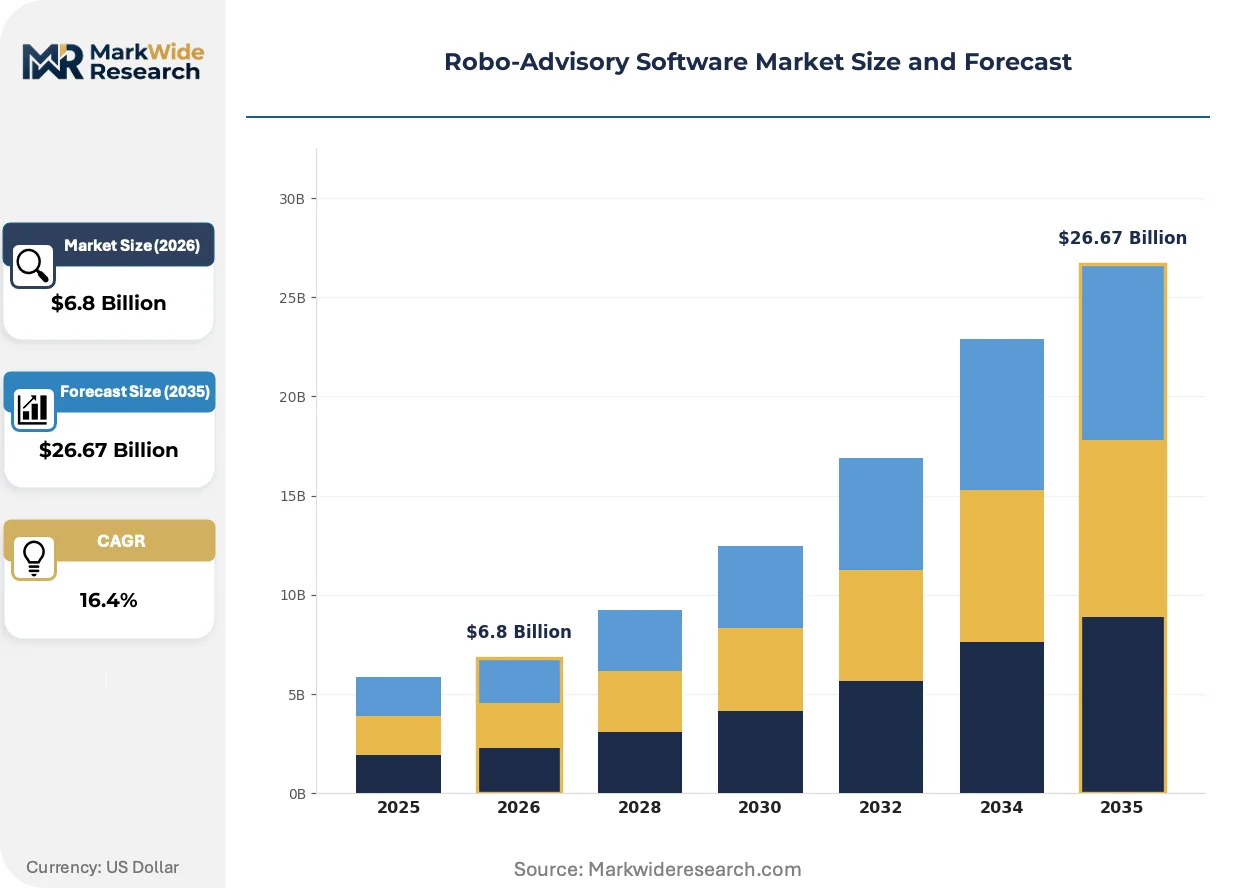
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $26.67 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Automated Investment Advice, Portfolio Management, Tax Optimization, Financial Planning Deployment: Cloud-Based, On-Premises, Hybrid, SaaS End User: Individual Investors, Financial Institutions, Wealth Management Firms, Startups Pricing Model: Subscription-Based, Transaction Fee, Performance Fee, Freemium |
| Companies Covered | The Vanguard Group, Inc., Charles Schwab Corporation, Betterment, Wealthfront Corporation, SigFig Wealth Management, SoFi Technologies, Inc., Scalable Capital GmbH, Fidelity Investments, AdvisorEngine, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Robo-Advisory Software Market Evolving Landscape
Explainable AI architectures are reshaping competitive positioning as regulators demand interpretable investment logic, while behavioral data integration enables predictive financial wellness interventions.
Natural language processing is decomposing static risk-tolerance questionnaires into dynamic conversational interfaces. Millennial and Gen Z investor cohorts engage preference-elicitation tools through chatbot modalities rather than traditional form-based onboarding. This technology compression reduces abandonment rates during account opening while generating richer behavioral data for algorithmic personalization.
The EU AI Act's risk-based classification system imposes conformity assessment requirements on automated decision-making systems affecting financial outcomes. Robo-advisory platforms serving European clients must implement human oversight mechanisms and algorithmic impact documentation. High-net-worth white-label arrangements face particular scrutiny given the systemic importance of wealth concentration among affected client segments.
Subscription-based pricing models are displacing percentage-of-assets fee structures among digitally native investors seeking cost predictability. Direct-to-consumer platforms unbundle advice from custody and execution, forcing traditional broker-dealers to unbundle historically integrated service stacks. This consumption-pattern shift concentrates among mass-affluent households in the United States with portable retirement assets and low switching costs.
Robo-Advisory Software Market Segmentation
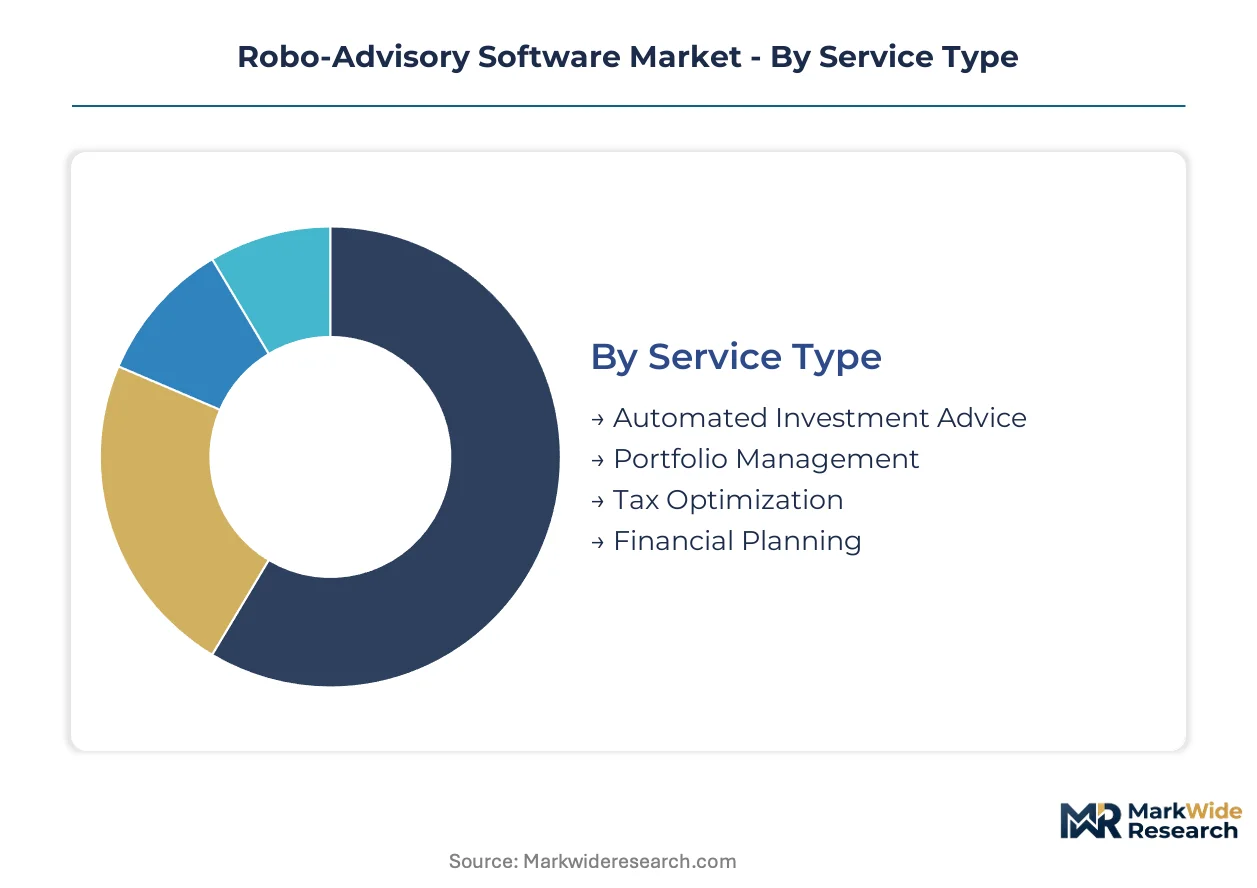
Segmentation in robo-advisory software reveals how algorithmic infrastructure aligns with distinct client risk profiles, regulatory requirements, and operational scale. Each dimension shapes platform architecture decisions and revenue model viability across investor cohorts.
Service Type:
Channel mix varies sharply by service complexity—automated advice flows through direct-to-consumer mobile apps, while tax optimization and financial planning concentrate in hybrid advisory channels serving mass-affluent households.
- Automated Investment Advice:Algorithmic portfolio construction engines deploy Modern Portfolio Theory risk parameters across ETF wrappers. Demand concentrates among millennial investors in the United States seeking fractional-cost alternatives to human advisors, with SEC Regulation Best Interest accelerating fiduciary-compliant platform adoption.
- Portfolio Management:Real-time rebalancing systems execute tax-efficient asset allocation across taxable and tax-advantaged accounts. Wealth management firms in the United States white-label these capabilities to compete with fintech challengers, driven by elastic cloud compute requirements for Monte Carlo simulation.
- Tax Optimization:Direct indexing enables security-level loss harvesting unavailable through mutual fund structures. Mass-affluent households with taxable brokerage assets drive adoption.
- Financial Planning:Goal-based interfaces integrate retirement, education, and estate objectives into unified projections. Hybrid advisory models favor this segment for behavioral coaching augmentation.
Automated Investment Advice dominates installed base. Tax Optimization is where expansion concentrates.
Deployment:
Cost tier stratification separates hyperscaler-dependent cloud architectures from compliance-heavy on-premises installations serving EU MiFID II mandates.
- Cloud-Based:Elastic compute environments support real-time portfolio rebalancing and Monte Carlo simulation without capital expenditure. Fintech challengers in the United States leverage AWS, Azure, and Google Cloud to compete against established custodians.
- SaaS:Multi-tenant architectures enable rapid deployment for regional banks and credit unions seeking turnkey algorithmic infrastructure. Subscription pricing aligns with recurring revenue predictability goals.
- Hybrid:Sensitive client data resides on-premises while compute-intensive analytics execute in cloud environments. European wealth managers favor this model for GDPR compliance.
- On-Premises:Legacy custodial platforms at established broker-dealers resist API-native connectivity, extending implementation timelines for algorithmic overlay deployment.
Cloud-Based captures the majority of new platform launches. Hybrid deployments are climbing the fastest among multi-jurisdictional providers.
End User:
Customer type determines feature depth—individual investors trigger standardized onboarding flows, while wealth management firms demand customizable risk models and white-label branding.
- Individual Investors:Direct-to-consumer platforms unbundle advice from custody and execution, serving digitally native cohorts with portable retirement assets. Natural language processing enables chatbot-based risk tolerance elicitation.
- Wealth Management Firms:White-label arrangements require modular rule-engine infrastructure with jurisdiction-specific logic branching for SEC, FCA, and MAS compliance. High-net-worth segments demand bespoke trust structuring capabilities.
- Financial Institutions:Regional banks and credit unions seek algorithmic infrastructure without proprietary technology development costs.
- Startups:Venture-backed challengers prioritize speed-to-market over regulatory breadth, concentrating in single-jurisdiction launches.
Individual Investors represent the largest addressable population. Wealth Management Firms generate the highest revenue per deployment.
Pricing Model:
Margin structure separates predictable subscription streams from volatile performance fees concentrated in high-net-worth white-label arrangements.
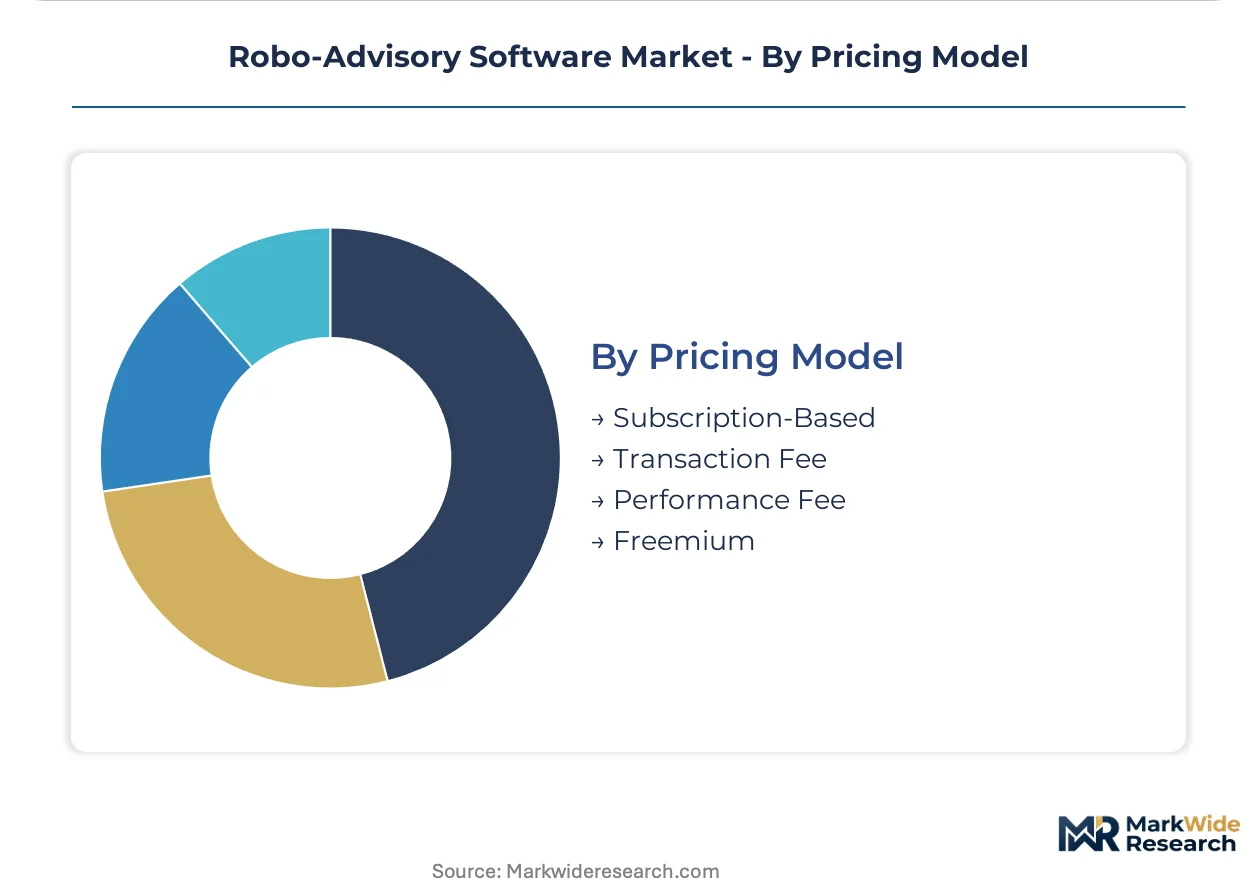
- Subscription-Based:Monthly or annual fees displace percentage-of-assets structures among cost-sensitive investors seeking predictability. Mass-affluent households in the United States with low switching costs favor this model.
- Performance Fee:Revenue ties to algorithmic alpha generation or tax-loss harvesting outcomes. High-net-worth segments through white-label arrangements concentrate here.
- Transaction Fee:Per-trade charges align with active trading overlays on core passive allocations. Zero-commission positioning at Charles Schwab compresses this tier.
- Freemium:Basic portfolio tracking and goal-setting features convert to paid tiers for tax optimization and financial planning. Customer acquisition costs challenge unit economics.
Subscription-Based pricing anchors the revenue mix. Performance Fee structures are gaining share fastest among platforms serving taxable high-net-worth assets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
SEC Regulation Best Interest and the EU's MiFID II suitability requirements are accelerating compliance-integrated platform adoption across major financial centers. Cloud-native architectures dominate new deployments as regulators mandate explainable algorithmic logic for investment recommendations.
United States
Millennial and Gen Z investor cohorts drive demand for fractional-cost wealth management alternatives. The SEC enforces fiduciary documentation requirements through Regulation Best Interest, compelling registered investment advisors to rebuild client onboarding architectures. New York and San Francisco anchor fintech challenger concentration, with established broker-dealers deploying hybrid robo-human models at scale.
United Kingdom
Mass-affluent households seek goal-based financial planning interfaces with behavioral coaching augmentation. The FCA's operational resilience requirements impose system downtime limits on real-time portfolio management functions. London's wealth management cluster favors hybrid deployments with sensitive client data residing on-premises for GDPR compliance.
Germany
Regional banks and credit unions pursue turnkey algorithmic infrastructure without proprietary technology development costs. BaFin implements granular cost transparency mandates aligned with EU MiFID II frameworks. Frankfurt's financial services ecosystem concentrates white-label arrangement demand for modular rule-engine infrastructure.
Singapore
High-net-worth segments require bespoke trust structuring capabilities beyond pure-robo penetration limits. The MAS technology risk management guidelines add compliance layers for multi-jurisdictional providers serving Asian wealth concentration. The city-state's private banking hub drives performance fee structures among platforms with direct indexing sophistication.
Canada
Taxable brokerage assets from sophisticated retail investors concentrate demand for security-level loss harvesting unavailable through mutual fund wrappers. The country's national securities regulator enforces suitability assessment documentation comparable to SEC standards. Toronto's fintech corridor hosts emerging challengers prioritizing subscription-based pricing predictability over percentage-of-assets models.
Robo-Advisory Software Market Competitive Landscape
Player mix skews toward established custodians with mutual fund infrastructure and venture-backed fintech challengers with cloud-native architectures. The competitive field fragments across hybrid advisory providers, direct-to-consumer platforms, and white-label infrastructure vendors. Three archetypes dominate: scale-driven incumbents leveraging zero-commission positioning, specialists in tax-loss harvesting sophistication, and modular SaaS providers serving regional financial institutions. M&A activity concentrates on algorithmic capability acquisition, while strategic partnerships link custody infrastructure to frontend user experience layers.
Within the scale-driven tier, The Vanguard Group and Charles Schwab Corporation exemplify incumbent positioning through integrated fund infrastructure and price disruption capabilities. Betterment occupies a specialist position representing tax-optimization sophistication and goal-based interface design. These three entities anchor contrasting competitive vectors: mutual fund ecosystem leverage, zero-commission custody integration, and direct-to-consumer subscription predictability.
| Leading Market Players |
|---|
| The Vanguard Group, Inc. |
| Charles Schwab Corporation |
| Betterment |
| Wealthfront Corporation |
| SigFig Wealth Management |
| SoFi Technologies, Inc. |
| Scalable Capital GmbH |
| Fidelity Investments |
| AdvisorEngine |
| Others |
Value Network & Pricing Analysis
Ninety-day implementation timelines for hybrid deployment architectures compress vendor selection cycles and amplify pricing power for cloud-native providers with modular compliance engines. This lead-time pressure concentrates procurement decisions among established hyperscaler partners, while subscription-based pricing models absorb upfront infrastructure costs that would otherwise exclude regional banks from algorithmic advisory capabilities.
Pricing Analysis
Service tier sophistication creates the primary spread between mass-market direct-to-consumer platforms and white-label enterprise arrangements. Subscription-based pricing dominates direct-to-consumer deployments, while performance fee structures concentrate among high-net-worth white-label segments serving taxable brokerage assets. Cost compression in the mass-affluent tier intensifies as zero-commission positioning at established custodians eliminates transaction-based revenue streams. Individual investors exhibit highest price sensitivity, seeking predictable monthly fees; wealth management firms demonstrate lowest sensitivity, prioritizing regulatory compliance and customization depth over per-seat costs.
Supply Chain Analysis
Container availability constraints on trans-Pacific trade lanes elevate inbound logistics costs for specialized compute hardware deployed in on-premises hybrid installations. Software development concentrates in the United States, Germany, and Singapore, with cloud infrastructure sourcing from hyperscaler data centers across multiple jurisdictions. Critical dependencies include elastic compute capacity, API-native custodial connectivity, and jurisdiction-specific compliance rule engines. Single-source vulnerability runs through dominant hyperscaler ecosystems for real-time portfolio rebalancing functions. Distribution runs through direct SaaS provisioning for fintech challengers and licensed enterprise agreements for established wealth management firms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Regulatory mandates for explainable AI logic across SEC, EU, and MAS jurisdictions are accelerating platform consolidation around compliance-integrated architectures. This technological inflection favors vendors with modular rule-engine infrastructure capable of jurisdiction-specific logic branching.
For Market Incumbents: Shield core custody relationships by accelerating hybrid advisory deployment before fintech challengers capture mass-affluent rollover assets. Prioritize API-native connectivity investments to reduce legacy core system integration friction that extends implementation timelines. Vertical integration into proprietary ETF infrastructure, following The Vanguard Group's mutual fund ecosystem model, anchors pricing power against zero-commission disruptors. For New Entrants and Emerging Players: Differentiate on tax-loss harvesting sophistication and direct indexing capabilities unavailable through incumbent mutual fund wrappers. Target regional banks and credit unions in Germany and Canada seeking turnkey algorithmic infrastructure without proprietary development costs. A white-label SaaS go-to-market with rapid deployment timelines exploits incumbent implementation bottlenecks. For Investors and Strategic Acquirers: Carve-out targets emerge from established wealth management firms with stranded technology assets and captive client bases lacking algorithmic overlay capabilities. Long-term viability centers on platforms with multi-jurisdictional compliance architecture and hybrid human-robo service delivery. Monitor SEC enforcement patterns around algorithmic suitability documentation as an inflection indicator for compliance-integrated platform valuations.| Strategic Initiative | Industry Significance |
|---|---|
| Hybrid Advisory Platform Launch | Captures mass-affluent households seeking behavioral coaching augmentation alongside algorithmic portfolio construction. |
| Direct Indexing Capability Expansion | Enables security-level tax-loss harvesting for taxable brokerage assets at Charles Schwab and Betterment scale. |
| Multi-Jurisdictional Compliance Modularization | Addresses simultaneous SEC, FCA, MAS, and EU regulatory adherence through rule-engine infrastructure. |
| White-Label SaaS Partnership | Supplies regional banks and credit unions with algorithmic infrastructure without proprietary technology development. |
| Explainable AI Architecture Investment | Satisfies EU AI Act conformity assessment requirements for automated financial decision-making systems. |
Research Methodology
Operator-level perspectives from robo-advisory platform CTOs, wealth management firm CIOs, SEC compliance officers, and regional bank digital strategy heads anchored the qualitative base. Primary interviews triangulated with secondary validation from SEC Regulation Best Interest filings, EU MiFID II cost transparency disclosures, MAS technology risk management guidelines, and FCA operational resilience consultations. Hyperscaler capex disclosures and fintech venture funding databases supplied infrastructure scaling indicators. Bottom-up deployment counts across service tiers reconciled with top-down addressable wealth management fee pool estimates.
Sensitivity analysis tested forecast robustness across regulatory implementation timelines and cloud infrastructure cost trajectories over the projection horizon. Segmentation dimensions modeled include service type complexity, deployment architecture, end-user scale, and pricing model structure. CAGRs derived from installed base expansion rates and average revenue per account trajectories. Industry-specific inputs incorporated SEC enforcement intensity indices and EU AI Act implementation phase transitions.
Forecasts assume regulatory continuity in SEC, EU MiFID II, and MAS regimes; material policy shifts would require re-modeling. Algorithmic accountability framework expansions or fiduciary standard elevations represent specific revision triggers. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
FinTech
Latin America Fintech Market
FinTech
Cloud AI in Fintech Market
FinTech
Financial Cloud Market
FinTech
Hand Account Software Market
FinTech
Financial Technology Fintech Market
FinTech
Fintech Cloud Market
FinTech
Japan AI in Fintech Market
FinTech
Asia-Pacific Neo Banking Market
FinTech
Transaction Monitoring Software Market
FinTech
Netherlands AI in Fintech Market
FinTech
Australia Fintech Market
FinTech
Micro-Investing Platform Market
FinTech
Financial Consolidation Software Market
FinTech
North America AI in Fintech Market
FinTech
Financial Audit Software Market
FinTech
Intelligent Cash Deposit Machine Market