
 Australia Fintech Market | 2026-2036
Australia Fintech Market Size, Share, and Industry Trends Forecast 2026-2036
Australia Fintech Market Intelligence
Digital banking channels are rewriting how Australian consumers access credit and treasury services. Afterpay leverages its merchant network to sustain buy-now-pay-later dominance across retail verticals. Airwallex anchors cross-border payment infrastructure for SMEs operating in Asia-Pacific trade corridors. Zip competes aggressively on installment lending through direct-to-consumer app distribution.
Australia fintech encompasses technology-enabled financial services delivered via software platforms, mobile applications, and API-connected infrastructure that automate payments, lending, wealth management, and compliance functions. These systems rely on real-time data processing, encrypted transaction protocols, and cloud-native architecture to reduce cost-to-serve ratios versus legacy banking rails. Payment Solutions and Lending Platforms command the largest revenue pools as merchant acquirers and alternative lenders displace traditional branch-based distribution. Investment Tools and Insurance Technology segments are expanding fastest as robo-advisory platforms and embedded insurance APIs penetrate superannuation and general insurance markets.
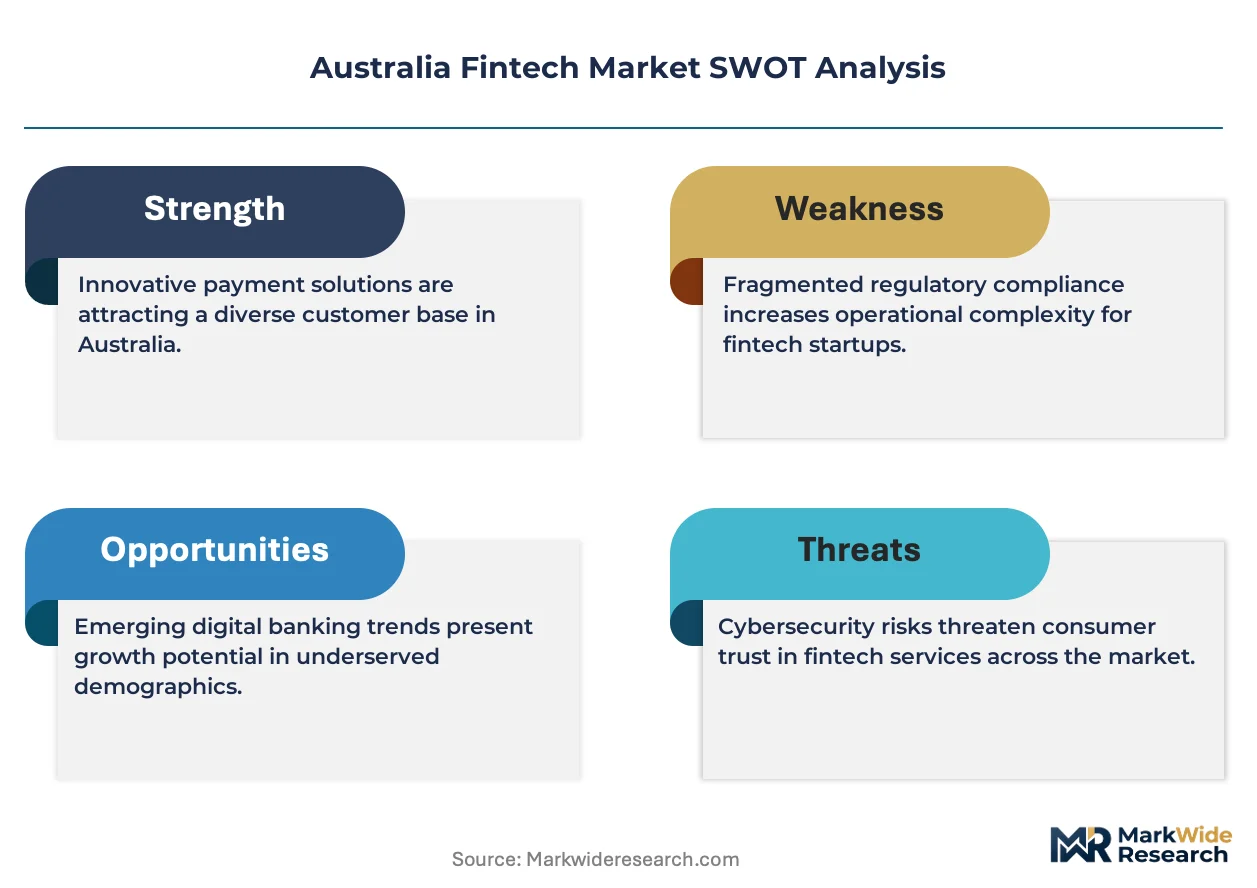
ASIC, APRA, and the ACCC collectively govern market conduct, prudential standards, and competition policy across Australian fintech operations, with the Consumer Data Right mandating standardized open banking data sharing that lowers barriers for new entrants. RBA oversight of real-time payment settlements through the New Payments Platform further shapes infrastructure access and interoperability requirements. Stakeholders must monitor evolving licensing thresholds and data sovereignty rules as regulatory technology investments become mandatory for scalable compliance.
Market Dynamics
The Consumer Data Right regime is forcing incumbent banks to surrender transactional data custody, eroding the deposit-gathering moats that sustained branch-based customer acquisition for generations.
Growth Catalysts
- Open Banking Mandates:The Consumer Data Right compels major banks to share customer data through standardized APIs, lowering customer acquisition costs for neobanks and payment platforms seeking to displace legacy deposit relationships.
- SME Payment Modernization:Australian small businesses operating in Asia-Pacific trade corridors demand real-time cross-border settlement infrastructure, concentrating platform development investment in Sydney and Melbourne fintech corridors.
- Real-Time Rail Expansion:The New Payments Platform enables instant account-to-account transfers, accelerating merchant acquirer displacement of card network dominance in retail and hospitality verticals.
Market Restraints
- Prudential Capital Requirements:APRA's restricted ADI licensing framework imposes minimum capital thresholds that constrain neobank balance sheet scaling relative to established deposit-taking institutions.
- Data Sovereignty Compliance:Cloud infrastructure providers must maintain Australian-resident data centers to satisfy ASIC and APRA operational risk standards, elevating platform hosting costs versus global alternatives.
- Legacy Core Banking Entrenchment:Major banks' multi-decade investments in on-premise core systems create switching friction that slows enterprise fintech adoption in treasury and institutional banking segments.
Strategic Opportunities
- Superannuation Robo-Advisory:The A$3.5 trillion compulsory superannuation pool remains underpenetrated by automated investment platforms, creating white space for API-connected advice engines targeting default fund consolidation.
- Embedded Insurance APIs:General insurers lag in real-time policy issuance infrastructure, opening distribution partnerships for fintech platforms seeking to embed coverage into lending and payment workflows.
- Regulatory Technology Convergence:ASIC's escalating surveillance technology mandates are hybridizing compliance automation with core banking infrastructure, creating bundled vendor opportunities across reporting and audit functions.
Industry Challenges
- Cloud-Native Engineering Scarcity:Fintech platforms compete with global technology employers for distributed systems engineers capable of building fault-tolerant payment infrastructure at scale.
- Multi-Regulator Licensing Complexity:Firms operating across payments, lending, and wealth management must navigate overlapping ASIC, APRA, and ACCC compliance timelines that extend product launch cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Australia Fintech Market |
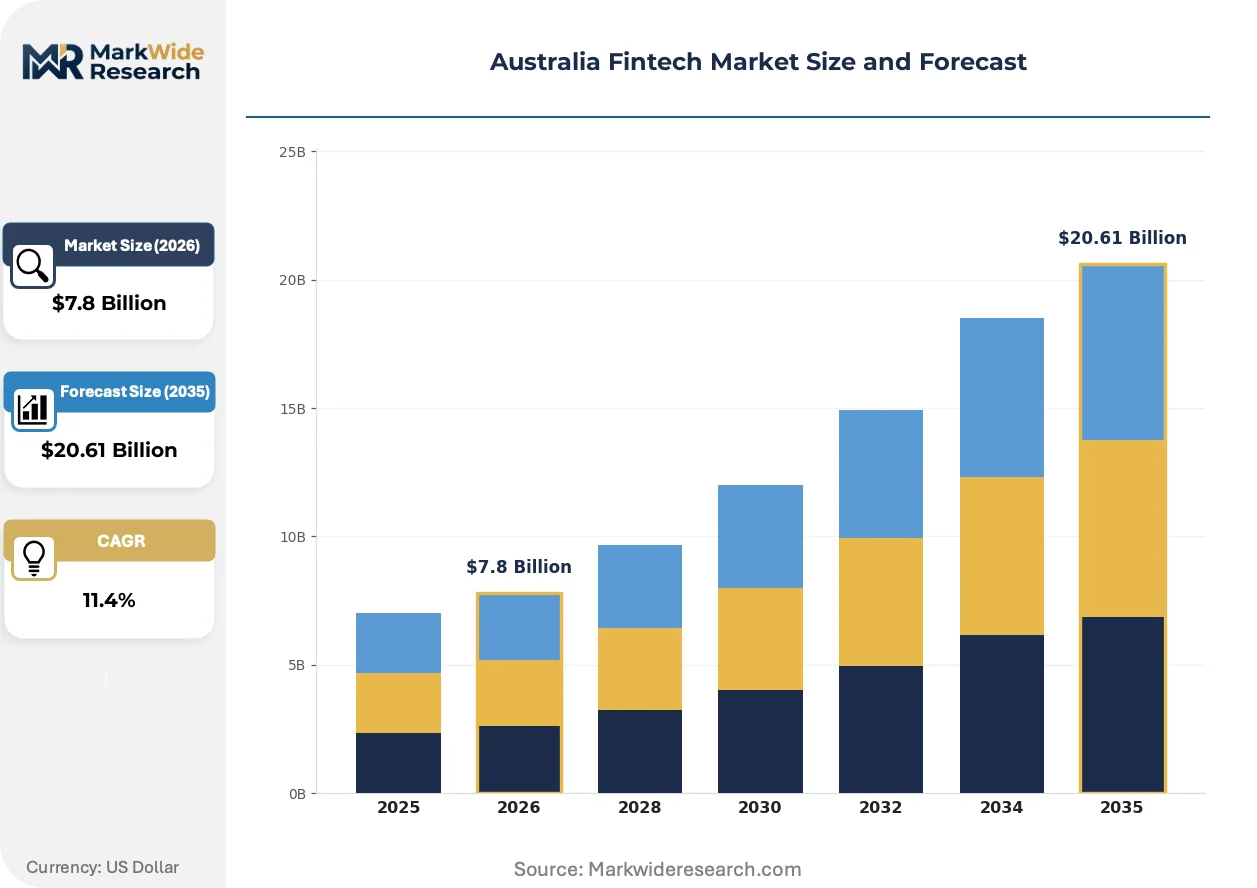
| Market Size in 2026 | $7.8 Billion |
| Market Size in 2035 | $20.61 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Payment Solutions, Lending Platforms, Investment Tools, Insurance Technology Customer Type: Consumers, Small Businesses, Enterprises, Financial Institutions Technology: Blockchain, Artificial Intelligence, Machine Learning, API Integrations Service Type: Wealth Management, Crowdfunding, Peer-to-Peer Lending, Regulatory Compliance |
| Companies Covered | Zip, Airwallex, Wisr, Stockspot, Up Bank, Afterpay, Tyro Payments, Plenti, Judo Bank, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Australia Fintech Market Strategic Shifts & Innovations
Platform architecture decisions are compressing time-to-market for new financial products while regulatory technology investments are becoming mandatory preconditions for scalable operations across multiple licensing regimes.
Artificial intelligence is hybridizing credit decisioning engines with real-time alternative data ingestion, enabling lenders to assess SME cash flow health through accounting software integrations rather than historical financial statements. Non-bank lenders targeting trade finance and invoice factoring verticals are deploying these models fastest, compressing approval timelines from weeks to hours and eroding the collateral-based risk frameworks that sustained major bank dominance in working capital products.
ASIC's design and distribution obligations now require product issuers to document target market determinations before launch, embedding consumer protection compliance into product development workflows rather than treating it as post-launch legal review. Fintech platforms offering complex investment or credit products must restructure their governance frameworks to satisfy these upstream obligations, with robo-advisory and buy-now-pay-later segments experiencing the steepest compliance recalibration.
Merchant acquirers are unbundling payment acceptance from working capital advances, enabling retail and hospitality businesses to access revenue-based financing through the same transaction data streams that previously supported only settlement services. This convergence of payments and lending is most visible in Sydney's restaurant and retail corridors, where point-of-sale platforms now originate credit decisions within minutes of onboarding rather than referring applicants to separate banking relationships.
Australia Fintech Market Segmentation
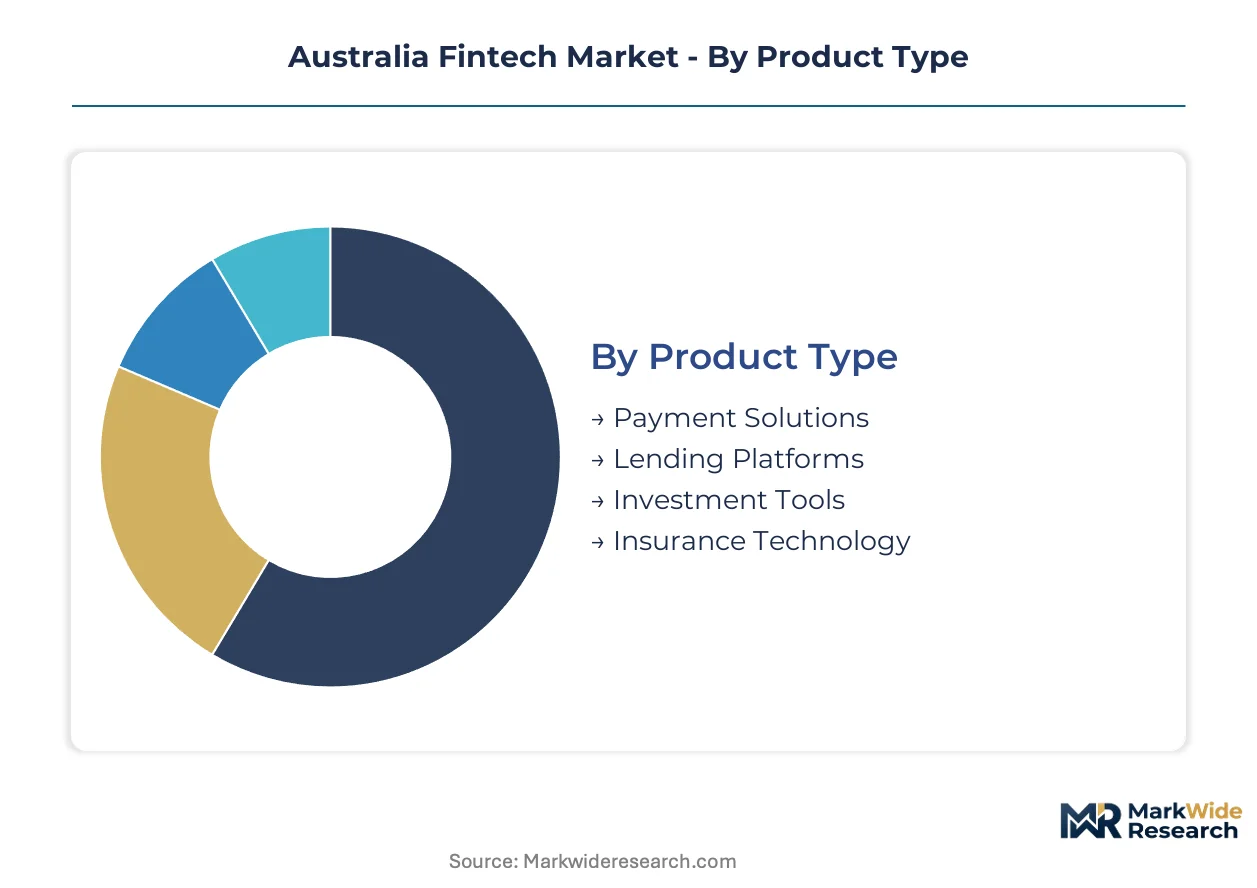
Segmentation in Australian fintech reveals how regulatory architecture and infrastructure maturity create divergent investment cycles across product categories. Understanding these velocity differences helps vendors allocate engineering resources and compliance budgets against predictable revenue timelines.
Product Type:
Payment Solutions turn over fastest with merchant contract cycles measured in months, while Insurance Technology platforms require multi-year product development and prudential approval timelines.
- Payment Solutions:Real-time transaction processing infrastructure built atop the New Payments Platform enables instant account-to-account settlement. Sydney and Melbourne merchant acquirers concentrate demand as retail and hospitality operators abandon card network rails for lower-cost settlement alternatives. The segment expands most quickly as open banking APIs reduce integration friction for new entrants.
- Lending Platforms:Alternative credit decisioning engines ingest accounting software data and bank transaction feeds through Consumer Data Right mandates. Small business borrowers in trade finance and invoice factoring verticals drive concentration as approval timelines compress from weeks to hours.
- Investment Tools:Robo-advisory platforms automate portfolio construction and rebalancing for superannuation and retail brokerage accounts.
- Insurance Technology:Embedded policy issuance APIs and claims automation infrastructure target general insurers lagging in real-time distribution capabilities.
Payment Solutions dominates installed base. Lending Platforms is where expansion concentrates.
Customer Type:
Cost tier structures diverge sharply: Financial Institutions command enterprise pricing and customization premiums, while Consumers access freemium models subsidized by merchant interchange or data monetization.
- Small Businesses:Cross-border payment infrastructure and working capital products serve Asia-Pacific trade corridor operators concentrated in Sydney and Melbourne. Real-time settlement demands and multi-currency treasury needs drive platform selection criteria above price sensitivity.
- Financial Institutions:Legacy core banking modernization and regulatory technology procurement absorb the largest implementation budgets. APRA compliance mandates and ASIC surveillance requirements shape vendor selection around audit trails and operational risk controls.
- Consumers:Mobile-native banking apps and buy-now-pay-later services compete for deposit relationships and installment lending volumes.
- Enterprises:Treasury management platforms and institutional payment infrastructure serve corporate finance functions.
Financial Institutions anchor revenue per contract. Small Businesses is where customer acquisition velocity climbs the fastest.
Technology:
Application intensity varies by infrastructure layer: API Integrations penetrate fastest at the customer interface, while Blockchain implementations remain experimental in trade finance pilots.
- API Integrations:Standardized open banking interfaces mandated by Consumer Data Right protocols enable third-party data access with customer consent. Neobanks and payment platforms leverage these rails to displace legacy deposit relationships without branch infrastructure.
- Artificial Intelligence:Credit decisioning engines and fraud detection systems process real-time transaction streams and alternative data feeds. Non-bank lenders deploy these models to assess SME cash flow health through accounting software integrations.
- Machine Learning:Predictive analytics for customer lifetime value and churn modeling refine acquisition spend allocation.
- Blockchain:Distributed ledger infrastructure targets trade finance documentation and cross-border settlement efficiency.
API Integrations command the broadest deployment footprint. Artificial Intelligence is where R&D investment concentrates.
Service Type:
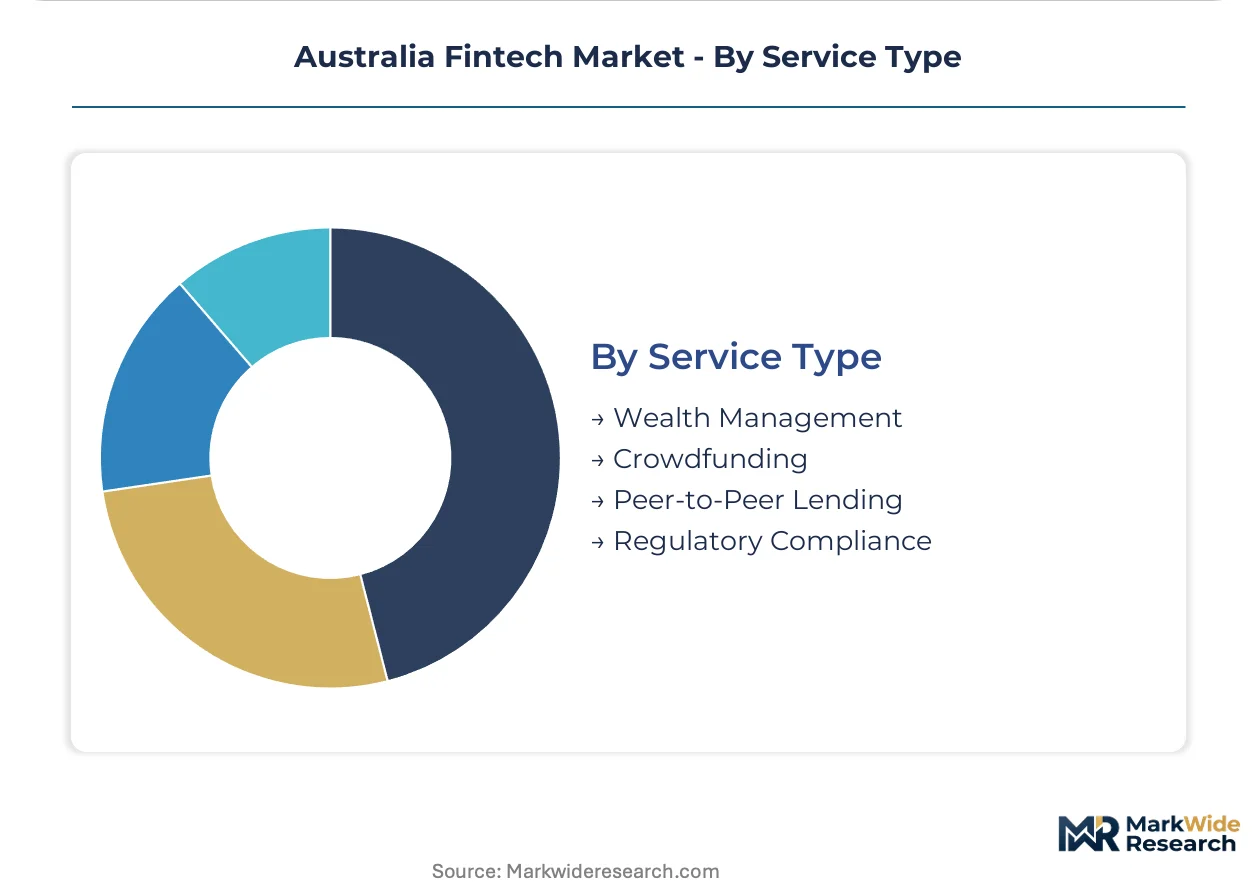
Volume concentration follows regulatory complexity: Regulatory Compliance absorbs mandatory technology spend, while Crowdfunding remains niche with limited scale economics.
- Regulatory Compliance:ASIC design and distribution obligations and APRA prudential reporting mandates require automated audit trails and surveillance infrastructure. Fintech platforms bundle compliance automation with core banking functions to satisfy multi-regulator licensing timelines.
- Wealth Management:Superannuation robo-advisory targets the compulsory retirement savings pool through API-connected advice engines. Default fund consolidation and member engagement metrics drive platform differentiation.
- Peer-to-Peer Lending:Marketplace credit platforms match retail investors with consumer and SME borrowers outside traditional bank intermediation.
- Crowdfunding:Equity and debt issuance platforms serve early-stage capital formation for unlisted companies.
Regulatory Compliance dominates mandatory spend allocation. Wealth Management is where automated platform penetration gains share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
New South Wales commands premium pricing power over Victoria in fintech infrastructure deployment, reflecting Sydney's concentration of Asia-Pacific trade finance demand against Melbourne's consumer lending density.
New South Wales
Cross-border payment infrastructure and SME working capital platforms drive demand concentration in Sydney's fintech corridor. ASIC's design and distribution obligations shape compliance architecture for platforms serving institutional clients. The Sydney CBD and North Sydney technology precincts host merchant acquirers and treasury management vendors targeting Asia-Pacific trade settlement.
Victoria
Consumer-facing neobanks and buy-now-pay-later platforms anchor demand in Melbourne's metropolitan market. The Consumer Data Right mandates enable third-party data access that lowers customer acquisition costs for deposit-taking challengers. Melbourne's inner-city fintech cluster concentrates robo-advisory development targeting superannuation fund consolidation.
Queensland
Tourism and hospitality payment modernization drives merchant acquirer investment in Brisbane and Gold Coast corridors. APRA's restricted ADI licensing framework constrains neobank balance sheet scaling relative to established deposit-taking institutions. South East Queensland's startup ecosystem hosts early-stage lending platforms focused on invoice factoring for construction and logistics verticals.
Western Australia
Mining sector treasury management and commodity trade finance sustain specialized platform demand in Perth. Data sovereignty compliance requirements elevate cloud hosting costs for infrastructure providers serving resource sector clients. Perth's central business district concentrates institutional payment platforms facilitating multi-currency settlement for extractive industry exporters.
South Australia
Agricultural supply chain finance and regional SME lending platforms address underbanked segments outside metropolitan cores. The RBA's New Payments Platform enables instant account-to-account transfers that accelerate merchant displacement of card network dominance. Adelaide's technology precinct hosts compliance automation vendors serving multi-regulator licensing requirements.
Australia Fintech Market Key Industry Players
Specialist payment infrastructure providers and diversified consumer lending platforms split the market between B2B treasury automation and retail credit origination. Market structure tilts toward fragmentation as regulatory technology mandates lower barriers for niche compliance vendors. Three archetypes dominate: merchant acquirers with embedded working capital products, neobanks leveraging open banking APIs, and alternative lenders deploying AI-driven credit decisioning. Competitive moves concentrate on strategic partnerships with accounting software providers and geographic expansion into Asia-Pacific trade corridors.
Within the consumer lending archetype, Zip and Afterpay exemplify buy-now-pay-later specialists competing through direct-to-consumer app distribution. Airwallex anchors the cross-border payment infrastructure tier, representing merchant acquirers that unbundle settlement services from revenue-based financing. These three companies sit within distinct strategic positions: installment lending dominance, Asia-Pacific treasury automation, and retail payment network density respectively.
| Leading Market Players |
|---|
| Zip |
| Airwallex |
| Wisr |
| Stockspot |
| Up Bank |
| Afterpay |
| Tyro Payments |
| Plenti |
| Judo Bank |
| Others |
Cost & Logistics Intelligence
Undercapacity in cloud-native engineering pipelines across Sydney and Melbourne fintech corridors is elevating talent acquisition costs while compressing vendor margins. This utilization squeeze forces platform providers to pass through infrastructure expenses while competing for scarce distributed systems engineers capable of building fault-tolerant payment rails.
Pricing Analysis
Customization-premium spreads separate enterprise-grade regulatory compliance bundles from standardized SaaS tiers. Three-tier pricing structure across premium, standard, and economy levels dominates, with APRA-mandated audit trails and ASIC surveillance infrastructure commanding enterprise premiums. Price differentiation rests on certification depth and geographic data residency requirements. Pricing pressure stems from open banking API commoditization of core payment functions. Small businesses exhibit highest price sensitivity, while financial institutions absorb premium tiers for operational risk controls.
Supply Chain Analysis
Export-control regimes limiting semiconductor and encryption technology flows into Australian data centers elevate hardware procurement timelines for ASIC-compliant infrastructure. Cloud infrastructure draws from United States hyperscalers, Singapore regional nodes, and domestic Australian-resident facilities. Critical dependencies include specialized encryption processors, high-availability networking equipment, and sovereign cloud compute instances. Single-source vulnerability concentrates in offshore API gateway providers. Distribution runs through direct enterprise sales for institutional clients and self-serve onboarding for SME segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbent banks must defend against neobank deposit substitution accelerated by Consumer Data Right mandates that erode traditional customer acquisition moats.
For Market Incumbents: Entrench core banking relationships through embedded working capital products that merge payment settlement with revenue-based financing. Deepen upstream control over accounting software integration partnerships to intercept SME cash flow data before alternative lenders capture decisioning authority. Counter Afterpay and Zip installment lending encroachment by unbundling merchant acquirer services from proprietary credit origination. For New Entrants and Emerging Players: Establish a beachhead in superannuation robo-advisory where default fund consolidation creates white space for API-connected advice engines. Target Queensland and South Australia regional corridors where agricultural supply chain finance remains underpenetrated by automated lending platforms. Lead with Consumer Data Right-enabled cash flow underwriting to bypass collateral requirements that sustain major bank dominance in working capital products. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among merchant acquirers with embedded lending capabilities that monetize transaction data streams beyond settlement fees. Long-term viability favors platforms with multi-regulator licensing coverage spanning ASIC, APRA, and ACCC compliance domains. Watch for consolidation signals when open banking API providers achieve critical mass in accounting software integration partnerships.| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Technology Bundling | ASIC design and distribution obligations force compliance automation into core banking procurement decisions. |
| Accounting Software Integration | API partnerships with Xero and MYOB intercept SME cash flow data for alternative credit decisioning. |
| Asia-Pacific Corridor Expansion | Sydney-based platforms leverage real-time settlement infrastructure to capture cross-border trade finance demand. |
| Superannuation API Penetration | Robo-advisory engines target the compulsory retirement savings pool through default fund consolidation strategies. |
| Revenue-Based Financing Unbundling | Merchant acquirers originate working capital advances through transaction data previously supporting only settlement. |
Research Approach
Desk research of ASIC regulatory filings, APRA prudential statistics, and New Payments Platform transaction disclosures preceded structured interviews with neobank product executives, alternative lender credit officers, superannuation fund technology leads, and merchant acquirer partnership directors. Primary fieldwork captured platform architecture decisions and compliance investment trajectories. Secondary validation drew from RBA payment system reports, ACCC competition assessments, and cloud infrastructure provider capacity disclosures. Bottom-up segment sizing triangulated against top-down market aggregation.
Assumptions held fixed across the modeling period include Consumer Data Right API standardization timelines, APRA restricted ADI licensing thresholds, and New Payments Platform interoperability protocols. Variables stress-tested encompass open banking adoption velocity, neobank deposit migration rates, and regulatory technology mandate escalation. Segmentation dimensions modeled span product type, customer archetype, technology layer, and service category. CAGRs derived from segment-level growth rate reconciliation against aggregate market trajectory.
Stress conditions across cloud infrastructure cost inflation, engineering talent scarcity, and multi-regulator licensing timeline extensions were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding regulatory implementation schedules and technology adoption curves. Material shifts in APRA capital requirement thresholds or ASIC surveillance technology mandates would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
FinTech
China Fintech Market
FinTech
Artificial Intelligence (AI) in Fintech Market
FinTech
Intelligent Cash Deposit Machine Market
FinTech
Spend Management Platform Market
FinTech
Smart Advisors Market
FinTech
Financial Management Software Market
FinTech
Asia-Pacific Fintech Cloud Market
FinTech
AI in Fintech Market
FinTech
North America AI in Fintech Market
FinTech
Europe Embedded Finance Market
FinTech
United Kingdom AI in Fintech Market
FinTech
Russia AI in Fintech Market
FinTech
Financial Audit Software Market
FinTech
IoT for Finance Market
FinTech
Embedded Finance Market
FinTech
Smart Financial Solutions Market