
 Fintech Cloud Market | 2026-2036
Fintech Cloud Market Size, Share, and Industry Trends Forecast 2026-2036
Fintech Cloud Market Analysis
Buyer concentration among banking institutions is expanding as regional banks consolidate technology procurement around fewer cloud providers. Amazon Web Services leverages its financial services competency program to anchor infrastructure contracts with tier-one lenders. Microsoft Azure competes through dedicated cloud regions with in-country data residency for regulated workloads. Google Cloud Platform differentiates via BigQuery analytics integration with core banking modernization programs.
Fintech cloud denotes the delivery of financial services infrastructure, software, and data processing through distributed computing architectures with API-native orchestration, encryption-at-rest protocols, and sub-100-millisecond latency thresholds for real-time payment clearing. Its primary commercial purpose is to decouple capital expenditure from technology scaling while enabling elastic capacity during settlement window peaks. Payment Processing dominates service type revenue as real-time rails proliferate across jurisdictions, while Fraud Detection within the solution dimension captures widening margin pools as synthetic identity schemes multiply. Hybrid Cloud deployments lead among investment firms balancing legacy mainframe coexistence with cloud-native innovation, though Public Cloud is accelerating fastest among neobanks unencumbered by technical debt.
US bank supervisors including the OCC and Federal Reserve enforce third-party risk management guidance that mandates independent audits of cloud service providers handling critical banking functions. EBA guidelines across Europe impose concentration risk limits on outsourcing to single cloud vendors, directly shaping multi-provider procurement strategies. Stakeholders must monitor how divergent sovereignty requirements between US CLOUD Act frameworks and EU data localization rules reshape cross-border architecture decisions.
Market Dynamics
Banking institutions face intensifying pressure to migrate core payment infrastructure from on-premise mainframes to cloud-native architectures while satisfying divergent data sovereignty mandates across operating jurisdictions.
Growth Catalysts
- Real-time payment rails:Central banks in Singapore, Thailand, and India are mandating instant settlement infrastructure that demands elastic cloud capacity for transaction spikes during peak windows.
- EU DORA framework:The Digital Operational Resilience Act imposes strict third-party risk management requirements that accelerate regulated financial institutions toward compliant cloud service procurement.
- Synthetic identity fraud proliferation:Advanced machine learning models deployed via cloud APIs enable real-time transaction scoring that legacy rule-based systems cannot match.
Market Restraints
- Concentrated hyperscaler supply:Three US-based cloud providers control the majority of certified financial services infrastructure, creating systemic dependency risk that European regulators actively discourage.
- Cross-border data friction:The US CLOUD Act's extraterritorial data access provisions conflict with EU GDPR localization requirements, forcing architectural complexity for multinational banks.
- Legacy mainframe coexistence:Decades-old core banking systems written in COBOL resist API-native integration, extending migration timelines and inflating hybrid operational costs.
Strategic Opportunities
- Indonesia's unbanked population:Mobile-first neobanks deploying entirely on public cloud infrastructure bypass legacy technical debt while capturing underpenetrated retail banking demand across the archipelago.
- Embedded finance convergence:The integration of banking-as-a-service APIs with e-commerce and logistics platforms creates new distribution channels for cloud-native payment orchestration.
- MAS sandbox licensing:Singapore's regulatory sandbox accelerates time-to-market for novel cloud banking models, attracting regional headquarters decisions from ASEAN expansion strategies.
Industry Challenges
- Cloud FinOps talent scarcity:Financial institutions compete for engineers capable of optimizing multi-cloud spend across reserved instance strategies and spot market arbitrage.
- Hybrid integration complexity:Maintaining sub-100-millisecond latency for real-time clearing while bridging containerized microservices with monolithic legacy databases strains operational teams.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Fintech Cloud Market |
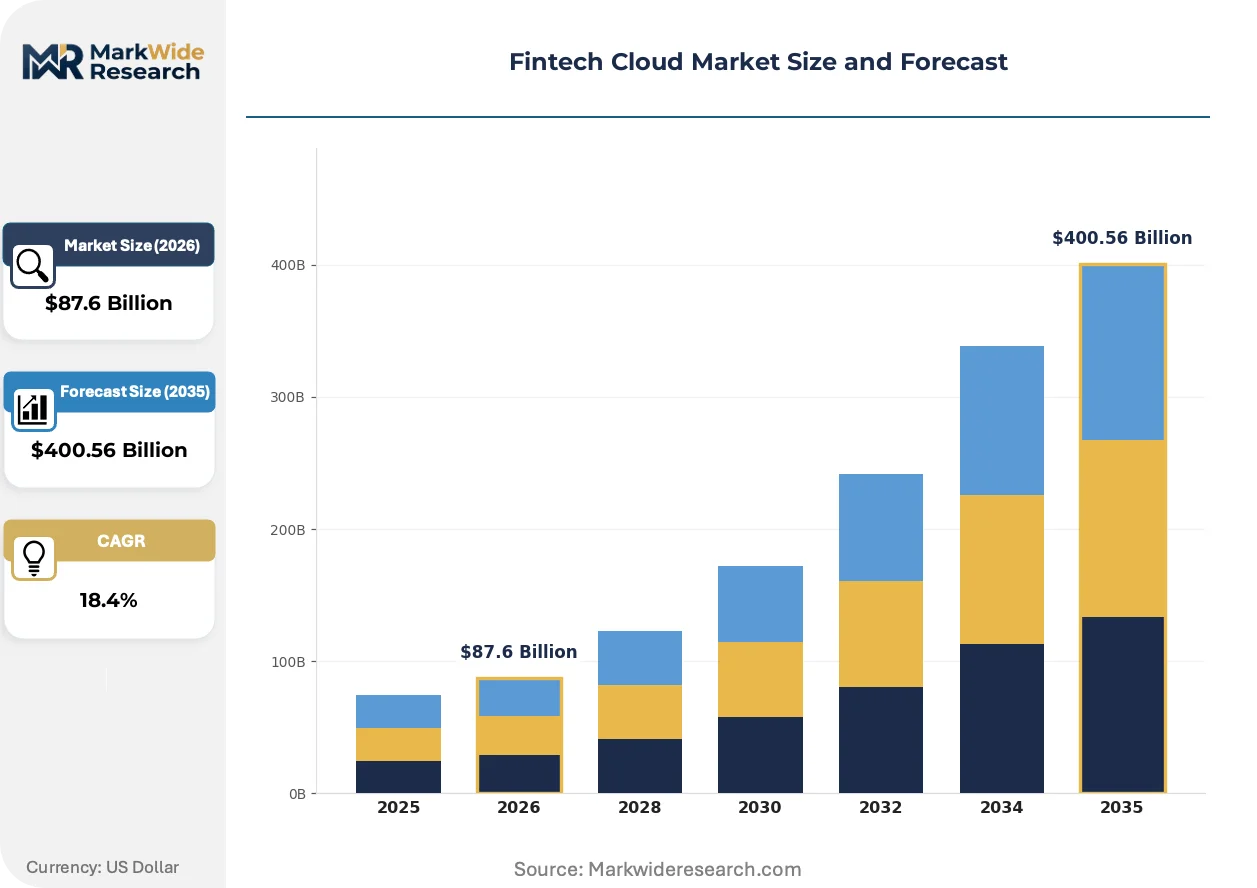
| Market Size in 2026 | $87.6 Billion |
| Market Size in 2035 | $400.56 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Payment Processing, Wealth Management, Loan Origination, Digital Banking Deployment: Public Cloud, Private Cloud, Hybrid Cloud, Community Cloud End User: Banking Institutions, Investment Firms, Insurance Companies, Credit Unions Solution: Analytics Solutions, Fraud Detection, Risk Management, Compliance Tools |
| Companies Covered | Stripe, SDK.finance, Amazon Web Services, Salesforce, Workday, Microsoft Azure, Snowflake, Fiserv, Google Cloud Platform, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Fintech Cloud Market Emerging Trajectories
Generative AI is penetrating fraud detection and customer service workflows, while regulatory technology automates compliance reporting. Sovereign cloud deployments are proliferating as data localization hardens into non-negotiable procurement criteria.
Event-driven serverless architectures are automating payment reconciliation and exception handling. Tier-two banks in Vietnam and the Philippines are adopting these patterns fastest, leapfrogging traditional virtualization layers. This compression of infrastructure abstraction layers is automating operational tasks previously requiring dedicated platform engineering teams.
The EU AI Act's risk-based classification system imposes conformity assessments on credit scoring algorithms deployed via cloud APIs. Banks must maintain audit trails for automated lending decisions. High-risk AI system providers are responding by embedding explainability modules directly into cloud-hosted inference pipelines.
Neobanks are unbundling core banking procurement from single-vendor suites, selecting best-of-breed cloud components for ledger, KYC, and payment orchestration. This composable architecture preference is most visible in Brazil and Nigeria, where regulatory sandboxes permit rapid vendor switching. Traditional core banking software incumbents face displacement from API-native challengers.
Fintech Cloud Market Segmentation
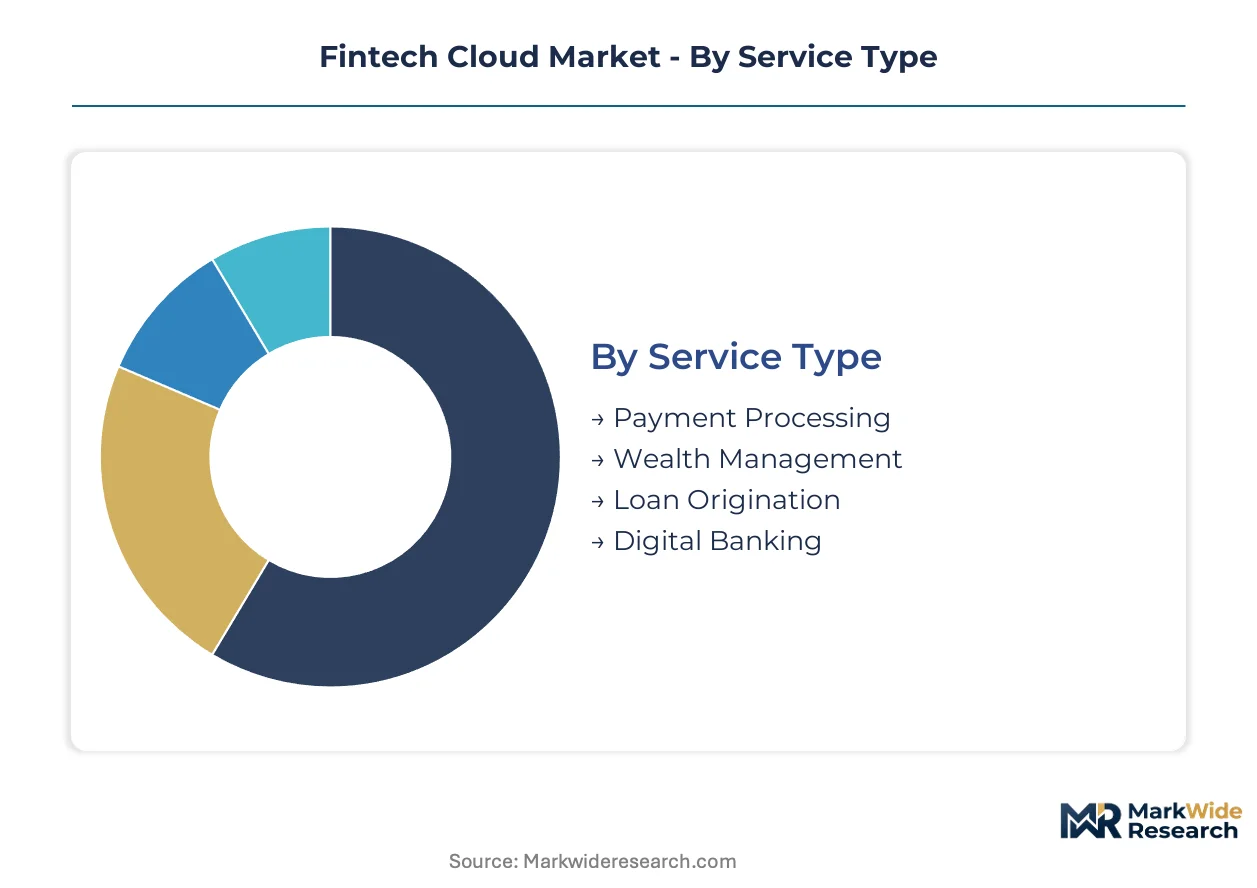
Segmentation in fintech cloud reveals how infrastructure procurement splits across regulatory tolerance, technical debt burdens, and risk-appetite profiles. Each dimension captures distinct commercial logic governing vendor selection and architecture investment cycles.
Service Type:
Replacement cycles vary dramatically across service categories, with legacy payment switches facing the most urgent cloud-native overhauls.
- Payment Processing:Real-time clearing infrastructure demands elastic compute clusters capable of absorbing settlement-window spikes without fixed-capacity provisioning. Singapore's FAST network and India's UPI rails concentrate procurement among central bank-mandated instant payment schemes.
- Wealth Management:Portfolio rebalancing engines and robo-advisory platforms leverage cloud GPU clusters for Monte Carlo simulations. Demand clusters among Singaporean private banks serving ultra-high-net-worth clients across Southeast Asia.
- Loan Origination:Digital credit workflows embed alternative data scoring via API-native decision engines.
- Digital Banking:Full-stack cloud cores enable neobanks to launch without mainframe dependencies.
Volume placements concentrate in Payment Processing; the faster expansion belongs to Wealth Management.
Deployment:
Cost-tier stratification separates regulated institutions requiring dedicated infrastructure from agile challengers optimizing unit economics.
- Public Cloud:Shared-tenant infrastructure delivers lowest per-transaction economics for unregulated or lightly-supervised fintechs. Neobanks in Indonesia and Vietnam deploy here exclusively, bypassing capital expenditure entirely.
- Private Cloud:Single-tenant environments satisfy data residency mandates from EU GDPR and Singapore's MAS Technology Risk Management Guidelines. Tier-one lenders in France and Germany maintain these for core ledger systems.
- Hybrid Cloud:Workload portability between on-premise and public environments dominates among investment firms reconciling legacy mainframe coexistence with innovation velocity.
- Community Cloud:Shared infrastructure among consortium members addresses concentration risk concerns raised by European Banking Authority outsourcing guidelines.
Hybrid Cloud captures the dominant procurement volume; Public Cloud climbs the fastest among ASEAN neobanks.
End User:
Customer-type maturity determines whether cloud migration proceeds as rip-and-replace transformation or incremental coexistence.
- Banking Institutions:Universal banks face the most complex migration calculus, balancing decades of COBOL accumulation against regulatory deadlines. Singapore's DBS and OCBC anchor regional cloud-native transformation programs.
- Investment Firms:Hedge funds and asset managers prioritize low-latency co-location for algorithmic trading, with cloud reserved for middle-office analytics.
- Insurance Companies:Actuarial modeling and claims processing drive demand for burst-compute capacity during catastrophe events.
- Credit Unions:Cooperative structures with limited IT budgets favor managed cloud services over in-house platform engineering.
Banking Institutions command the largest infrastructure commitments; Credit Unions are expanding cloud spending most rapidly from a smaller base.
Solution:
Margin-structure differentiation separates commodity infrastructure from value-add software layers capturing widening profit pools.
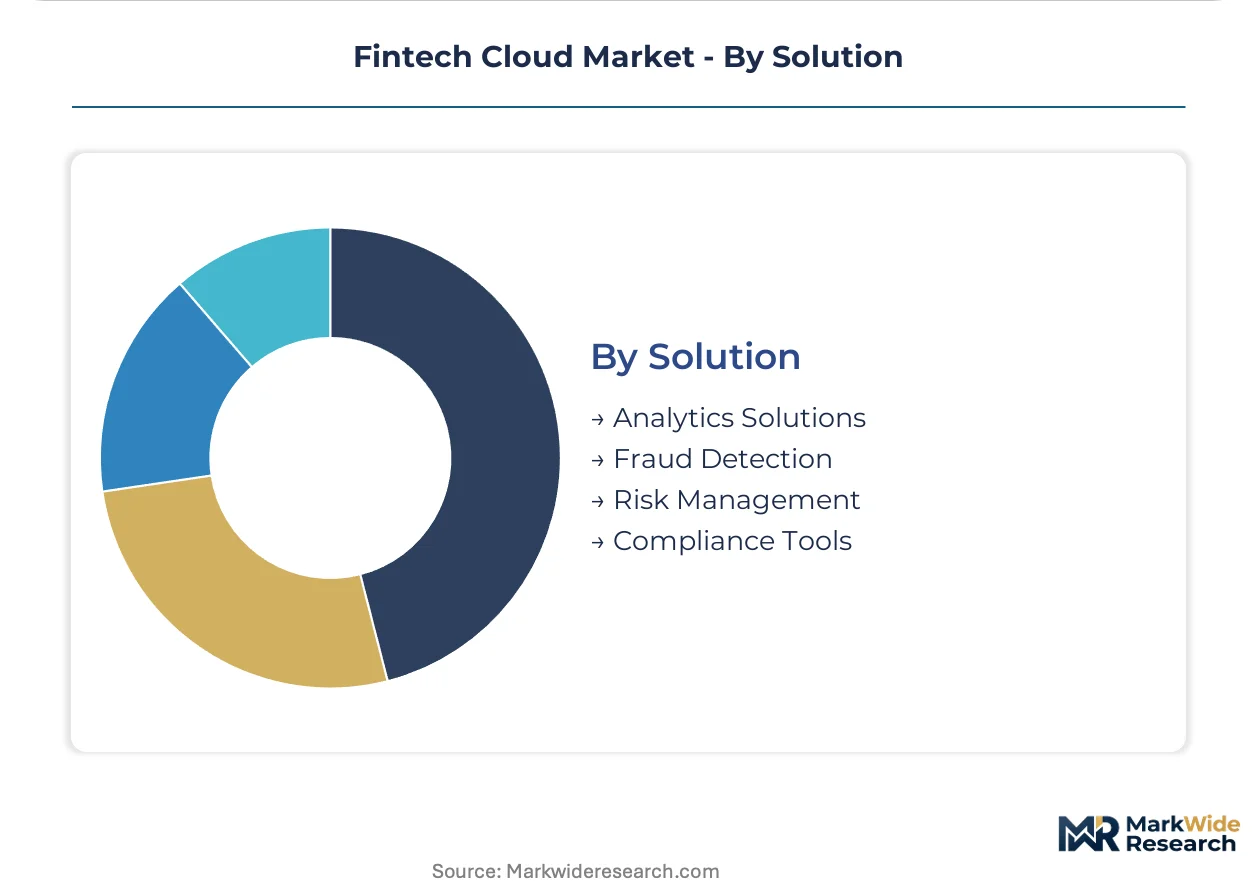
- Fraud Detection:Machine learning pipelines scoring transactions in sub-100-millisecond windows demand specialized cloud GPU instances and feature-store architectures. Synthetic identity proliferation across Southeast Asian e-commerce channels accelerates procurement.
- Risk Management:Counterparty exposure calculations and stress-testing engines leverage serverless elasticity for regulatory reporting deadlines. European banks facing ECB climate risk disclosure requirements drive adoption.
- Analytics Solutions:Data warehouse modernization programs consolidate fragmented banking data lakes into queryable cloud repositories.
- Compliance Tools:Automated regulatory reporting and audit-trail generation reduce manual compliance headcount.
Fraud Detection solutions claim the steepest expansion trajectory; Analytics Solutions represent the most established procurement category.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Singapore's monetary authority sandbox licenses anchor Asia-Pacific cloud banking deployment, while EU regulatory frameworks reshape European procurement patterns and US bank supervisors enforce third-party risk mandates.
United States
OCC and Federal Reserve guidance mandates independent audits of cloud providers handling critical banking functions. The CLOUD Act's extraterritorial data access provisions create architectural friction for multinational institutions. New York and San Francisco financial centers concentrate neobank cloud-native infrastructure deployment.
Singapore
MAS Technology Risk Management Guidelines establish data residency requirements for core ledger systems. Regulatory sandbox licenses accelerate time-to-market for novel cloud banking models. The city-state anchors regional headquarters decisions for ASEAN expansion strategies.
Germany
EBA outsourcing guidelines impose concentration risk limits on single-vendor cloud procurement. The Digital Operational Resilience Act mandates strict third-party risk management for regulated institutions. Frankfurt's banking cluster maintains private cloud deployments for universal bank core systems.
Indonesia
Mobile-first neobanks deploy entirely on public cloud infrastructure to capture underpenetrated retail banking demand. The archipelago's unbanked population drives elastic capacity requirements for digital payment orchestration. Jakarta anchors fintech cloud procurement for domestic remittance corridors.
United Kingdom
FCA operational resilience rules mandate maximum tolerable downtime thresholds for cloud-hosted payment systems. Brexit divergence from EU data adequacy decisions complicates cross-border architecture planning. London's fintech cluster drives demand for real-time clearing infrastructure with sub-100-millisecond latency.
Fintech Cloud Market Vendor Landscape
Established hyperscalers occupy the standard tier; emerging entrants pursue specialized financial services compliance and sovereign cloud differentiation. Three US-based providers control certified infrastructure supply, creating systemic dependency concerns that European regulators actively counter. Strategic archetypes include full-stack cloud platforms, API-native banking specialists, and data analytics infrastructure providers. Competitive moves concentrate on multi-region expansion and embedded finance partnership ecosystems.
Within the infrastructure tier, Amazon Web Services, Microsoft Azure, and Google Cloud Platform represent dominant architectural choices for regulated workloads. Stripe and SDK.finance occupy positions among API-native payment orchestration specialists. Snowflake exemplifies the analytics infrastructure archetype supporting cloud data warehouse modernization programs.
| Leading Market Players |
|---|
| Stripe |
| SDK.finance |
| Amazon Web Services |
| Salesforce |
| Workday |
| Microsoft Azure |
| Snowflake |
| Fiserv |
| Google Cloud Platform |
| Others |
Supply Flow & Price Mechanics
Vertical integration into sovereign cloud infrastructure anchors supply positions for tier-one lenders while compressing margins for multi-tenant public cloud providers. AWS, Azure, and Google Cloud Platform extract pricing power through dedicated financial services regions that satisfy MAS and EBA data residency mandates.
Pricing Analysis
Warranty and service bundling separates premium-tier managed cloud contracts from unbundled infrastructure-as-a-service consumption. Subscription-based SaaS tiers dominate procurement for fraud detection and analytics solutions, while per-transaction pricing governs payment processing volumes. Price differentiation hinges on certification grade—PCI-DSS Level 1 compliance commands substantial premiums over standard-tier offerings—and geographic data residency guarantees. Cost compression in public cloud tiers is intensifying because ASEAN neobanks prioritize unit economics over enterprise-grade SLAs. Credit unions exhibit the highest price sensitivity, while Singaporean universal banks accept premium pricing for sovereign cloud assurances.
Supply Chain Analysis
Regional distribution centers for hyperscaler cloud infrastructure concentrate in Singapore, Ireland, and Virginia, with hub-and-spoke patterns extending to Frankfurt and Mumbai for latency-sensitive workloads. Compute hardware supply draws from Taiwan semiconductor foundries, South Korean memory fabricators, and US chip designers. Supply chain risk centers on single-source vulnerability for specialized GPU instances powering fraud detection inference pipelines. Distribution runs through direct enterprise sales channels for banking institutions, supplemented by systems integrator partnerships for mid-market credit unions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
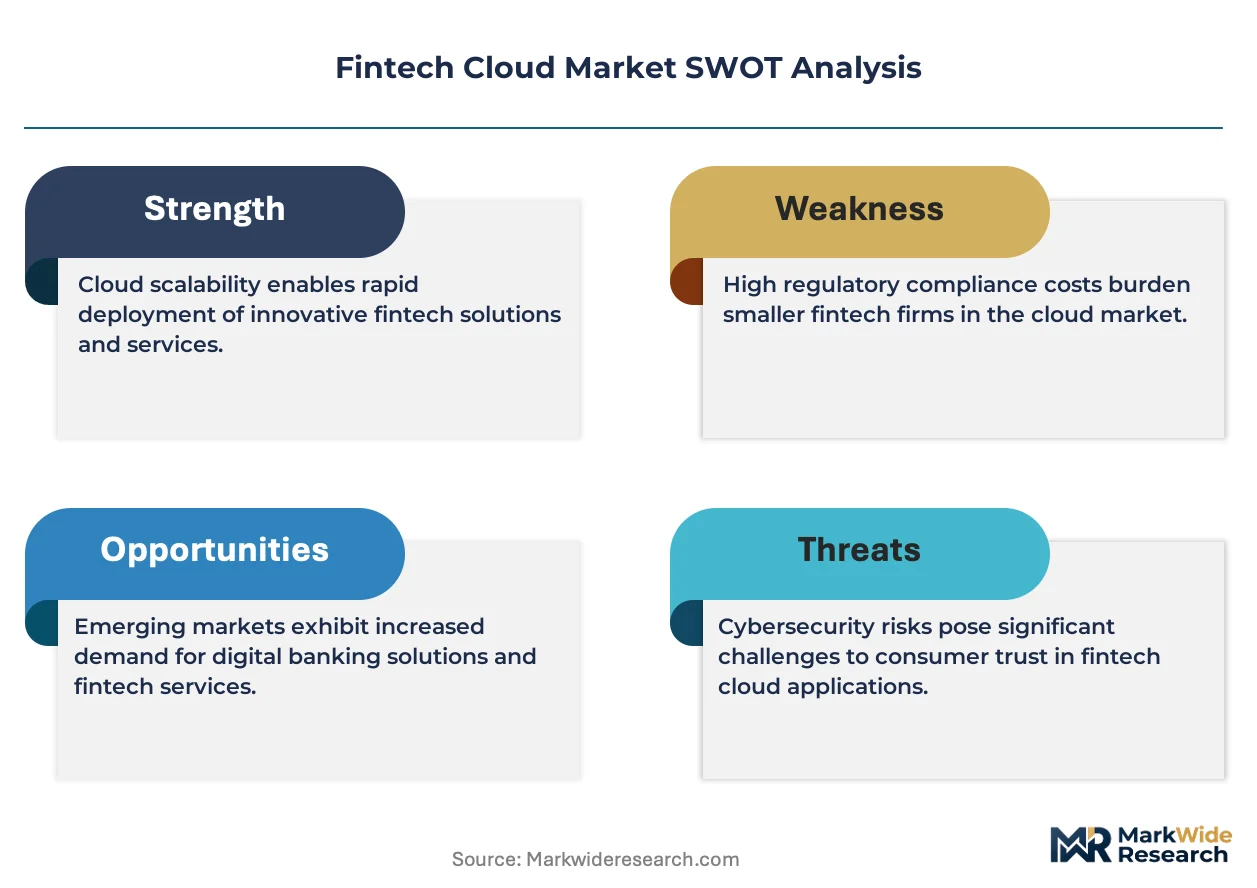
Hyperscaler concentration is forcing weaker regional cloud providers toward acquisition or exit as regulatory compliance costs escalate beyond standalone viability.
For Market Incumbents: Acquire specialized RegTech compliance modules to accelerate EU AI Act and DORA framework certification timelines. AWS and Azure should deepen sovereign cloud footprints in Frankfurt and Singapore to preempt regulatory fragmentation. Threat from API-native banking specialists like Stripe demands embedded finance partnership ecosystems that lock in distribution channels. For New Entrants and Emerging Players: Neobank channel partnerships in Indonesia and Vietnam offer the most penetrable entry vector for public cloud infrastructure plays. Target credit union managed service white-space where hyperscaler direct sales coverage remains thin. Go-to-market execution should emphasize FinOps cost optimization tooling that addresses the talent scarcity constraining incumbent procurement decisions. For Investors and Strategic Acquirers: Exit pathways concentrate in hyperscaler acquisition of sovereign cloud specialists with established MAS or EBA compliance track records. Long-term viability favors targets with durable data residency moats rather than commodity compute arbitrage. Watch for ECB climate risk disclosure enforcement as inflection indicator accelerating burst-compute demand for stress-testing engines.| Strategic Initiative | Industry Significance |
|---|---|
| Sovereign Cloud Region Expansion | MAS Technology Risk Management Guidelines mandate in-country data residency for Singaporean core ledger systems. |
| API-Native Banking Platform Integration | Stripe and SDK.finance embed payment orchestration into e-commerce and logistics distribution channels. |
| Regulatory Technology Acquisition | EU AI Act conformity assessments for automated lending decisions require explainable ML pipeline investments. |
| FinOps Talent Development Program | Reserved instance optimization and spot market arbitrage capabilities address cloud spend management scarcity. |
| Hybrid Cloud Architecture Partnership | Legacy mainframe coexistence with containerized microservices bridges decades of COBOL technical debt. |
Methodological Framework
Document review covered hyperscaler capex disclosures, central bank sandbox license registries, and EU regulatory framework publications, complemented by interviews with cloud infrastructure procurement officers at ASEAN universal banks, compliance leads at European tier-one lenders, and platform engineers at Indonesian neobanks. Secondary validation drew from MAS Technology Risk Management Guidelines, EBA outsourcing concentration risk circulars, and OCC third-party risk management bulletins. Bottom-up transaction volume modeling and top-down infrastructure spend estimates were triangulated against disclosed cloud region deployment timelines.
Cross-referencing historical payment rail migration patterns against panel input from Singaporean and German banking executives informed elasticity assumptions across the projection horizon. Segmentation dimensions modeled encompass deployment architecture, service type, end-user institution category, and solution layer. CAGRs were derived from capacity expansion announcements and regulatory deadline clustering. Forecast inputs incorporated real-time payment rail proliferation timelines and synthetic identity fraud incident trajectories.
Caveats apply where divergent US CLOUD Act and EU GDPR enforcement interpretations could materially shift the outlook for multinational bank architecture decisions. Forecasts reflect assumptions around central bank instant payment mandate adherence and hyperscaler certification maintenance. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
FinTech
China AI in Fintech Market
FinTech
Robo-Advisory Services Market
FinTech
Smart Financial Solutions Market
FinTech
Stock Trading App Market
FinTech
Global Cloud Financial Close Solutions Software Market
FinTech
Global Fin Tech Blockchain Market
FinTech
Fintech-As-A-Service Market
FinTech
Global Fundraising Software Market
FinTech
MENA Fintech Market
FinTech
Smart Advisors Market
FinTech
Vietnam Fintech Market
FinTech
India AI in Fintech Market
FinTech
Digital Banking Platform Market
FinTech
Asia-Pacific Fintech Market
FinTech
Financial Technology Fintech Market
FinTech
Robo Advisory Market