
 Financial Cloud Market | 2026-2036
Financial Cloud Market Size, Share, and Industry Trends Forecast 2026-2036
Financial Cloud Market Insights
The EU AI Act is broadening compliance obligations for automated credit scoring and fraud detection systems deployed on cloud platforms. Microsoft leverages its Azure confidential computing capabilities to address these emerging data sovereignty requirements. Amazon Web Services anchors its financial services practice through dedicated infrastructure zones that isolate regulated workloads from general cloud tenants. Google Cloud differentiates through sovereign cloud partnerships with European telecommunications providers, competing for institutional mandates that demand jurisdictional data control.
Financial cloud denotes the delivery of banking, insurance, and capital markets infrastructure through virtualized, multi-tenant computing environments with encryption at rest and in transit, API-native architecture, and sub-millisecond latency thresholds for high-frequency trading applications. Its primary commercial purpose is to replace on-premise mainframe systems with elastic compute resources that scale with transaction volume and regulatory reporting frequency. Hybrid cloud deployment leads current adoption patterns as institutions retain sensitive customer data in private environments while bursting analytical workloads to public infrastructure. Payment processing solutions command the largest solution share, though regulatory compliance tools are expanding fastest as institutions automate MiFID II and Dodd-Frank reporting obligations.
The Federal Reserve's SR 11-7 guidance on model risk management, the SEC's cybersecurity disclosure rules, and the EU's Digital Operational Resilience Act collectively shape product certification requirements and vendor selection criteria for financial cloud procurement. Health Canada and the UK's Financial Conduct Authority are extending comparable operational resilience frameworks, tightening cross-border data governance standards. Stakeholders must monitor how divergent national cloud certification regimes fragment procurement options and inflate compliance architecture costs.
Market Dynamics
Core banking modernization is accelerating as retail institutions dismantle decades-old mainframe architectures in favor of API-native cloud infrastructure, driven by the EU AI Act's algorithmic transparency mandates and competitive pressure from fintech challengers.
Growth Catalysts
- Regulatory Sandboxing:The OCC and CFPB cloud-first policies in the United States enable faster institutional adoption of virtualized infrastructure for automated credit decisions.
- High-Frequency Trading Latency Thresholds:Sub-millisecond execution requirements in capital markets pull elastic compute resources into cloud environments.
- MiFID II Automation:European investment firms automate transaction reporting through cloud-native compliance tools, expanding demand for regulatory technology infrastructure.
Market Restraints
- Data Sovereignty Fragmentation:Divergent national cloud certification regimes in Germany, France, and the United Kingdom inflate compliance architecture costs for cross-border deployments.
- Hybrid Integration Complexity:Technical limitations in synchronizing private on-premise environments with public burst capacity create operational friction during peak transaction windows.
- Mainframe Exit Costs:Proprietary legacy systems in North American money-center banks require multi-year capital commitments that delay full cloud migration timelines.
Strategic Opportunities
- Sovereign Cloud Partnerships:Telecommunications providers in Spain and Italy offer jurisdictional data control for institutions seeking EU Digital Operational Resilience Act compliance.
- Embedded Insurance Distribution:API-native architecture enables real-time policy issuance through e-commerce platforms and mobility applications.
- Quantum-Resistant Cryptography:Convergence of post-quantum encryption standards with confidential computing creates differentiation for trading infrastructure providers.
Industry Challenges
- Model Risk Management Talent:Shortage of professionals certified under Federal Reserve SR 11-7 guidance delays validation of automated decision systems.
- Cross-Border Data Governance:Reconciliation between SEC cybersecurity disclosure rules and EU GDPR requirements complicates unified cloud procurement strategies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Financial Cloud Market |
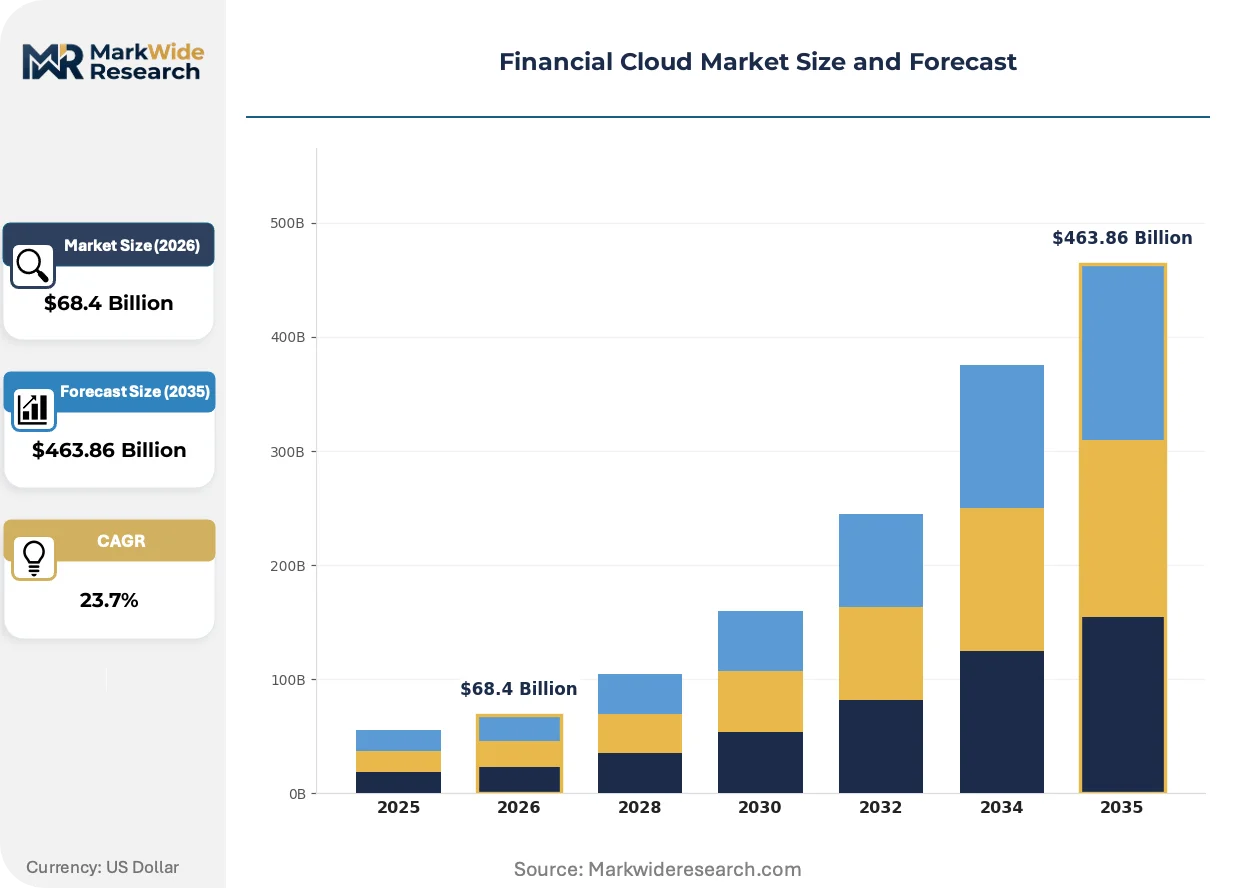
| Market Size in 2026 | $68.4 Billion |
| Market Size in 2035 | $463.86 Billion |
| CAGR (2026 – 2036) | 23.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Public Cloud, Private Cloud, Hybrid Cloud, Community Cloud Solution: Payment Processing, Risk Management, Fraud Detection, Regulatory Compliance, Wealth Management End User: Investment Firms, Credit Unions, Insurers, Payment Gateways Pricing Model: Subscription, Pay-as-you-go, Enterprise License, Freemium, Usage-based |
| Companies Covered | Amazon Web Services, Microsoft, Google Cloud, Oracle, IBM, SAP, Salesforce, Cisco Systems, Acumatica, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Financial Cloud Market Trends and Innovations
Confidential computing architectures are reshaping how financial institutions handle sensitive workloads, enabling processing of encrypted data without decryption exposure. This shift is compressing traditional security-perimeter models and creating new vendor differentiation axes.
Confidential computing is expanding into payment processing and fraud detection workflows. Tier-one banks in the United States and United Kingdom are piloting hardware-based trusted execution environments for real-time transaction scoring. This technology is expanding into markets previously blocked by data residency requirements, compressing the advantage of purely on-premise security claims.
The EU AI Act's risk classification framework for automated decision systems entered force across member states in 2024. Financial institutions must now maintain technical documentation and human oversight protocols for high-risk credit scoring algorithms. Asset managers and retail banks in France and Germany are restructuring cloud procurement contracts to embed algorithmic audit trails and explainability requirements.
Buyers are consolidating vendor relationships around integrated platform stacks rather than best-of-breed point solutions. Regional banks in the United States are replacing fragmented software contracts with unified cloud-native cores spanning deposits, lending, and treasury operations. This concentration is most visible among institutions with assets between ten and fifty billion dollars seeking to match fintech operational agility without multiplying integration overhead.
Financial Cloud Market Segmentation
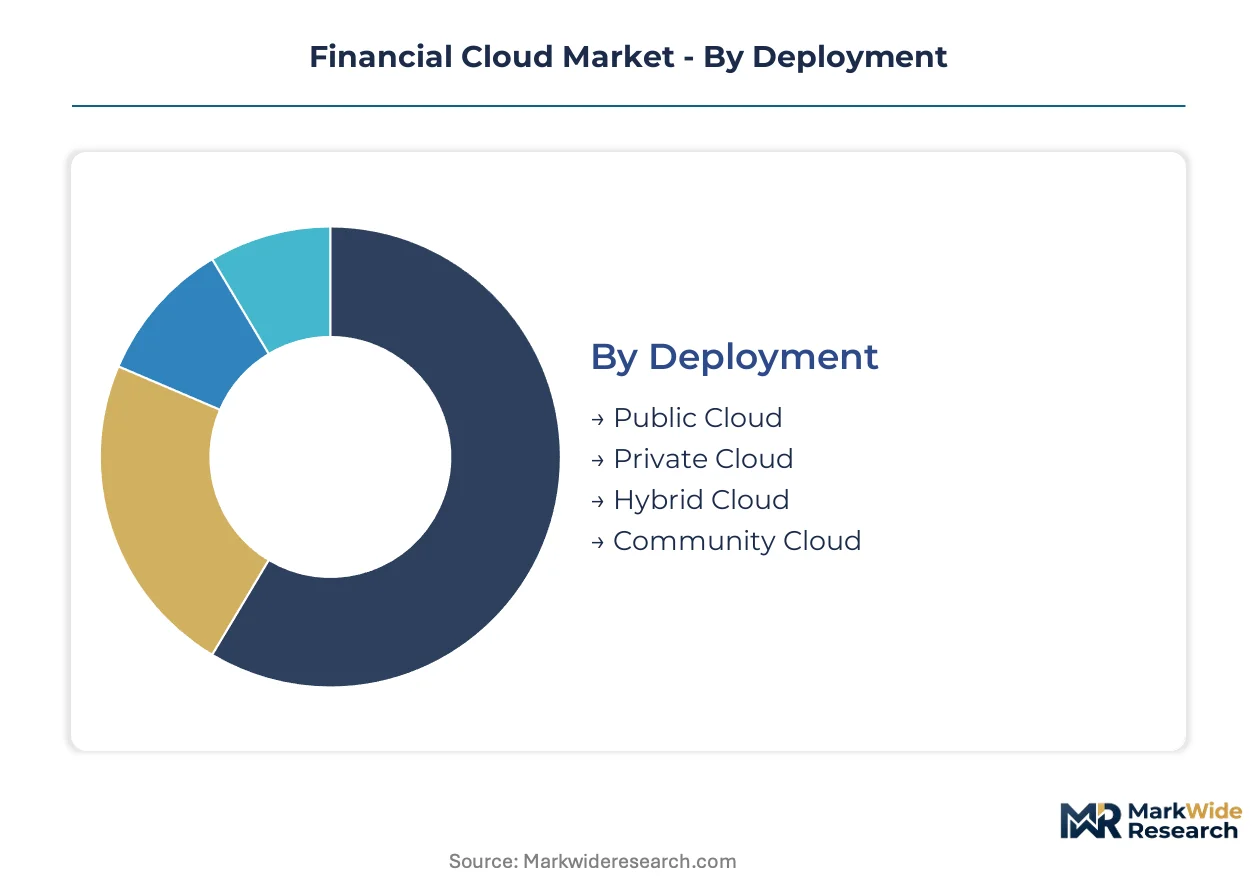
Financial cloud procurement patterns diverge sharply across deployment architectures and solution types, with regulatory pressure and latency requirements fragmenting vendor selection criteria. Institutions weigh data sovereignty obligations against elastic compute economics when structuring cloud contracts.
Deployment:
Technical architecture determines jurisdictional control, encryption boundaries, and burst capacity economics for regulated workloads.
- Public Cloud:Multi-tenant infrastructure delivers elastic compute with sub-millisecond latency for high-frequency trading applications. Demand concentrates among hedge funds and proprietary trading desks in the United States where OCC cloud-first policies minimize procurement friction.
- Hybrid Cloud:Split architectures retain sensitive customer data in private environments while bursting analytical workloads to public infrastructure. European retail banks under EU Digital Operational Resilience Act mandates favor this model for core banking modernization.
- Private Cloud:Dedicated single-tenant environments isolate regulated workloads with hardware-level encryption boundaries. Swiss private banks and German Landesbanken deploy these for custody operations requiring absolute data residency guarantees.
- Community Cloud:Shared infrastructure among consortium members reduces compliance duplication for common regulatory frameworks. French and Italian banking cooperatives utilize these for pooled MiFID II reporting infrastructure.
Mature deployment sits with Private Cloud. Newer deployment is concentrated in Hybrid Cloud.
Solution:
Functional modules align with operational workflows spanning transaction execution, risk surveillance, and regulatory automation.
- Payment Processing:Real-time transaction routing with API-native architecture replaces legacy ACH and SWIFT gateways. Payment gateways in the United States and United Kingdom drive demand as real-time payment schemes proliferate.
- Regulatory Compliance:Automated reporting tools for MiFID II, Dodd-Frank, and SR 11-7 model risk documentation. Investment firms in Germany and France are expanding fastest here as EU AI Act audit trail mandates take effect.
- Fraud Detection:Machine learning pipelines scoring transactions against behavioral baselines with confidential computing isolation. Credit unions in North America prioritize these deployments for check fraud and authorized push payment protection.
- Risk Management:Portfolio analytics and counterparty exposure calculation with quantum-resistant cryptography preparation. Insurers in London and Zurich utilize these for Solvency II stochastic modeling.
- Wealth Management:Unified advisory platforms integrating custody, tax optimization, and client reporting. Independent registered investment advisors in the United States adopt these to match wirehouse technology stacks.
Payment Processing commands established revenue share. Regulatory Compliance is climbing the fastest as institutions automate reporting obligations.
End User:
Institutional type shapes procurement scale, security certification requirements, and integration complexity with legacy cores.
- Investment Firms:Asset managers and hedge funds requiring low-latency execution infrastructure with algorithmic audit trails. MiFID II best execution obligations drive cloud migration for transaction cost analysis.
- Insurers:Life and property-casualty carriers modernizing policy administration and claims processing. Embedded distribution partnerships with e-commerce platforms accelerate API-native core adoption.
- Credit Unions:Member-owned cooperatives with constrained IT budgets seeking operational parity with regional banks. Core banking-as-a-service contracts consolidate vendor relationships.
- Payment Gateways:Merchant acquirers and fintech processors handling transaction volume spikes with elastic scaling. Real-time payment scheme participation mandates infrastructure refresh cycles.
Investment Firms anchor mature procurement volumes. Credit Unions represent the steepest expansion trajectory as cloud-native cores democratize fintech capabilities.
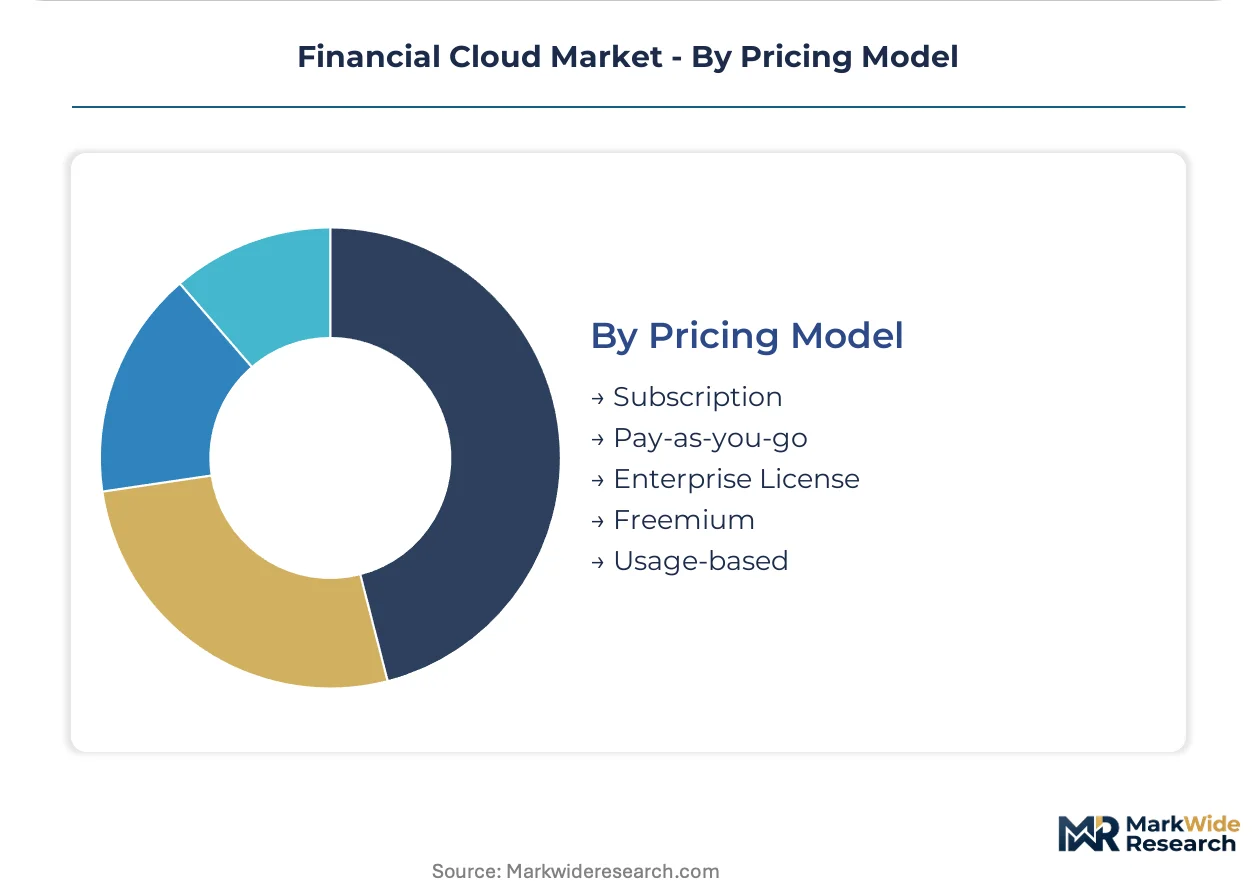
Pricing Model:
Commercial terms reflect workload predictability, regulatory capital treatment, and integration depth with institutional procurement systems.
- Subscription:Fixed monthly fees for predictable workload baselines with committed capacity reservations. Regional banks favor these for budgeting certainty.
- Pay-as-you-go:Metered consumption billing aligned with transaction volume fluctuations. Trading desks utilize these for seasonal volatility exposure.
- Enterprise License:Multi-year agreements with customization rights and dedicated support tiers. Tier-one money-center banks negotiate these for core system replacement.
- Usage-based:Granular billing tied to API calls, compute minutes, or storage volumes. Fintech challengers prefer these for unit economics alignment.
- Freemium:Limited-tier entry points converting to paid tiers at scale thresholds. Neobanks and robo-advisors leverage these for initial market entry.
Enterprise License dominates established institutional procurement. Usage-based models are gaining share fastest among fintech-native entrants.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
New York City anchors financial cloud procurement intensity, hosting headquarters for tier-one banks and proprietary trading desks that demand sub-millisecond latency infrastructure. Regulatory sandboxes at the OCC and CFPB accelerate cloud-first adoption among regional institutions.
United States
Demand concentrates among hedge funds and retail banks modernizing core systems. The SEC's cybersecurity disclosure rules and SR 11-7 model risk guidance shape vendor selection criteria. Manhattan and Chicago trading clusters pull elastic compute resources for high-frequency execution infrastructure.
Germany
Landesbanken and private banks prioritize hardware-level encryption for custody operations. The EU Digital Operational Resilience Act and GDPR requirements tighten cross-border data governance standards. Frankfurt's financial district hosts sovereign cloud partnerships addressing jurisdictional control mandates.
United Kingdom
Investment firms automate MiFID II transaction reporting through cloud-native compliance tools. The Financial Conduct Authority's operational resilience framework extends certification requirements. London's asset management corridor drives demand for algorithmic audit trail infrastructure.
France
Banking cooperatives deploy community cloud models for pooled regulatory reporting. The EU AI Act's risk classification framework mandates technical documentation for credit scoring algorithms. Paris-based institutions restructure procurement contracts to embed explainability requirements.
Switzerland
Private banks maintain absolute data residency guarantees through dedicated single-tenant environments. Swiss banking secrecy laws intersect with international transparency standards. Zurich and Geneva custody operations lead private cloud deployment for wealth management infrastructure.
Financial Cloud Market Competitive Landscape
Premium-margin players sit above commodity-margin players across confidential computing capabilities and sovereign cloud certifications. The vendor base organizes into three tiers: hyperscale cloud providers with dedicated financial services infrastructure zones, enterprise software incumbents with core banking modernization suites, and specialized regulatory technology vendors with automated compliance tooling. Dominant competitive moves include strategic partnerships with telecommunications providers for jurisdictional data control and portfolio diversification into quantum-resistant cryptography preparation.
Within the hyperscale tier, Amazon Web Services, Microsoft, and Google Cloud occupy positions defined by confidential computing differentiation and sovereign cloud partnerships. Amazon Web Services exemplifies the dedicated infrastructure zone archetype through regulated workload isolation. Microsoft represents the confidential computing vector with hardware-based trusted execution environments. Google Cloud sits within the sovereign partnership model through European telecommunications collaborations. These three anchors demonstrate how vendor selection criteria fragment across data sovereignty obligations and latency thresholds.
| Leading Market Players |
|---|
| Amazon Web Services |
| Microsoft |
| Google Cloud |
| Oracle |
| IBM |
| SAP |
| Salesforce |
| Cisco Systems |
| Acumatica |
| Others |
Pricing and Supply Chain Analysis
Hyperscale-to-specialist bifurcation in confidential computing capabilities creates divergent margin structures across the financial cloud stack, compressing commodity infrastructure pricing while amplifying premiums for sovereign-certified deployments and algorithmic audit-ready architectures.
Pricing Analysis
Outcome-linked pricing for sub-millisecond latency guarantees anchors tier-one procurement contracts, with hedge funds and proprietary trading desks paying elastic compute premiums tied to execution throughput rather than raw capacity. Price differentiation rests on confidential computing certification tiers and EU Digital Operational Resilience Act compliance bundling. Cost compression in standard public cloud tiers is intensifying because hyperscale providers are absorbing margin pressure to capture core banking modernization contracts. Regional banks with assets between ten and fifty billion dollars exhibit highest price sensitivity, while Swiss private banks and German Landesbanken demonstrate lowest sensitivity due to absolute data residency requirements.
Supply Chain Analysis
EU data localization mandates are reshaping hardware sourcing for trusted execution environments, forcing hyperscale providers to establish dedicated foundry relationships within member states. Semiconductor fabrication for confidential computing enclaves concentrates in Taiwan, South Korea, and the United States, with advanced packaging for financial-grade security modules drawing from specialized German and Israeli facilities. Supply chain risk centers on single-source vulnerability for hardware security module production. Distribution runs through direct enterprise sales teams with embedded compliance architects, supplemented by telecommunications provider partnerships for sovereign cloud last-mile delivery.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Vertical integration into confidential computing hardware and algorithmic audit infrastructure is accelerating as incumbents seek to capture premiums escaping to semiconductor and regulatory technology specialists.
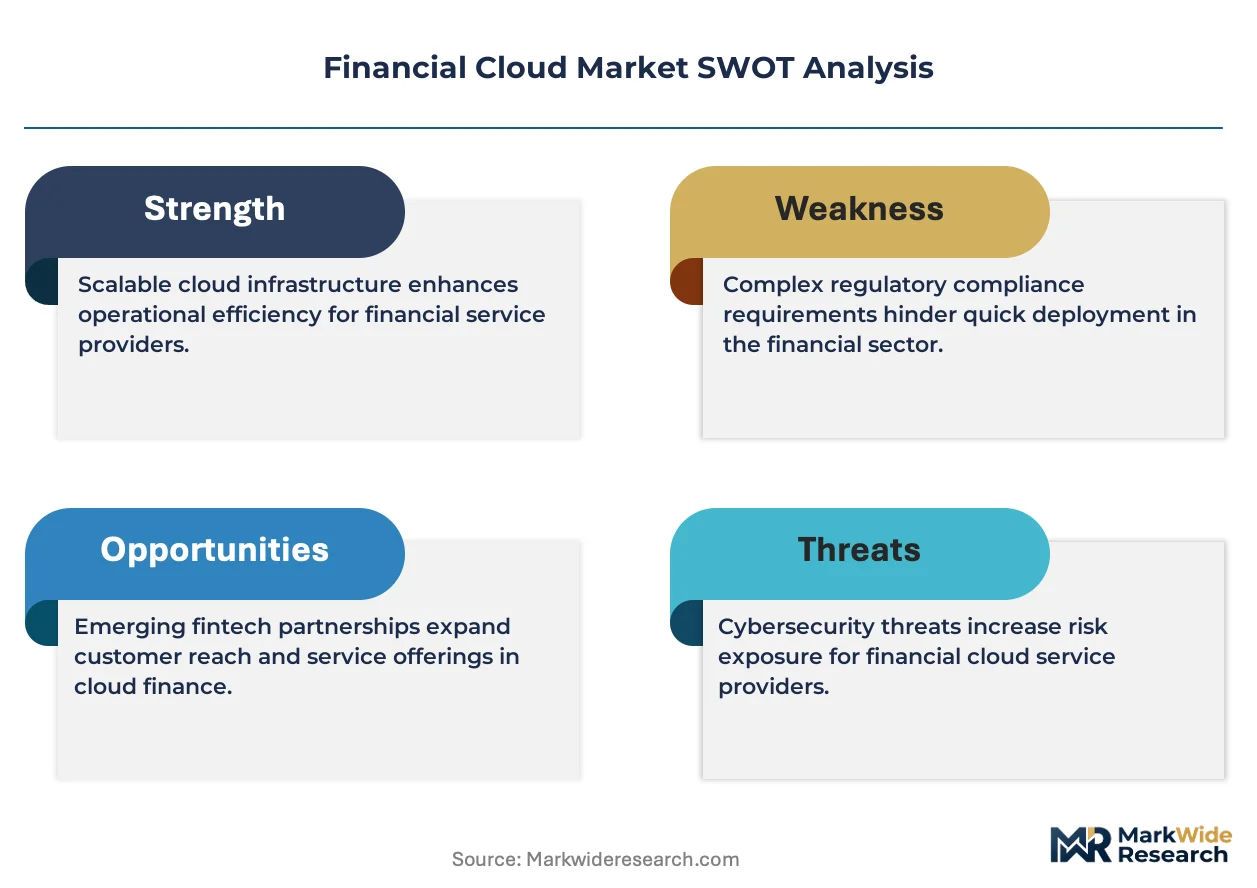
For Market Incumbents: Acquire confidential computing hardware security module fabrication capacity or exclusive foundry allocations to secure supply chain control over trusted execution environment deployment. Consolidate fragmented regulatory technology vendors to embed EU AI Act algorithmic audit capabilities directly into core banking platforms, defending against fintech challengers offering native compliance automation. For New Entrants and Emerging Players: Credit unions and community banks in North America represent the most penetrable buyer archetype, with constrained IT budgets and accelerating core banking-as-a-service demand creating white-space for API-native platform entrants. Sovereign cloud partnerships with European telecommunications providers offer jurisdictional data control differentiation for MiFID II automation tools targeting mid-tier investment firms in Germany and France. For Investors and Strategic Acquirers: Re-rating potential sits with regulatory technology specialists possessing automated SR 11-7 model risk documentation and EU AI Act explainability tooling, given accelerating procurement mandates from tier-one institutions. Long-term viability favors vendors with quantum-resistant cryptography preparation converging with confidential computing architectures. Watch confidential computing pilot expansions from tier-one United States and United Kingdom banks as inflection indicators for enterprise-scale deployment velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Sovereign Cloud Partnership | Telecommunications collaborations in Spain and Italy satisfy EU Digital Operational Resilience Act jurisdictional control mandates for retail banks. |
| Confidential Computing Scale-Up | Hardware-based trusted execution environment expansion compresses on-premise security claims and unlocks data-residency-blocked markets. |
| Regulatory Technology Acquisition | Automated MiFID II and SR 11-7 compliance tooling consolidation captures fastest-expanding solution segment in procurement budgets. |
| Quantum-Resistant Cryptography Investment | Post-quantum encryption standards preparation creates differentiation for trading infrastructure providers serving London and Zurich insurers. |
| Core Banking Modernization Platform | API-native unified stacks spanning deposits, lending, and treasury operations match fintech agility for regional United States banks. |
Research Methodology
SEC filings, hyperscaler infrastructure capex disclosures, and EU regulatory implementation guidance formed the secondary backbone, supplemented by customs data on hardware security module trade flows. Primary interviews with cloud procurement officers at tier-one banks, regulatory technology vendor executives, and telecommunications partnership leads validated demand assumptions across deployment architectures. Chief technology officers at regional banks and compliance architects at investment firms provided operational perspective on EU AI Act implementation timelines. Bottom-up and top-down triangulation reconciled vendor revenue disclosures with institutional procurement survey data.
Bottom-up modeling aggregated individual country-level adoption curves for public, hybrid, private, and community cloud deployments, while top-down analysis calibrated aggregate market expansion against macroeconomic indicators for financial services IT spending. Segmentation dimensions included deployment architecture, solution type spanning payment processing through regulatory compliance, end-user institutional category, and pricing model structure. CAGRs were derived from curve-fitting observed adoption velocities against regulatory mandate enforcement schedules. Forecast inputs incorporated Federal Reserve SR 11-7 guidance compliance deadlines and EU Digital Operational Resilience Act implementation phases.
Revisions become necessary when divergent national cloud certification regimes fragment procurement options more severely than modeled, or when confidential computing hardware supply constraints delay sovereign cloud deployment timelines. Forecasts reflect assumptions regarding regulatory enforcement consistency and hyperscale provider capacity expansion trajectories. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
FinTech
United Kingdom Fintech Market
FinTech
Singapore AI in Fintech Market
FinTech
Artificial Intelligence (AI) in Fintech Market
FinTech
MENA Fintech Market
FinTech
Australia Fintech Market
FinTech
IoT for Finance Market
FinTech
Europe AI in Fintech Market
FinTech
Smart Finance Technologies Market
FinTech
AI Finance Market
FinTech
Global Cloud Financial Close Solutions Software Market
FinTech
Micro-Investing Platform Market
FinTech
Smart Finance Connectivity Market
FinTech
Stock Trading App Market
FinTech
US AI in Fintech Market
FinTech
Account Checking Software Market
FinTech
Cloud AI in Fintech Market