
 Hand Account Software Market | 2026-2036
Hand Account Software Market Size, Share, and Industry Trends Forecast 2026-2036
Hand Account Software Market Insights
Skilled accounting labor scarcity is bifurcating the Hand Account Software Market into premium automation suites and stripped-down entry tools. SAP SE leverages its enterprise ERP backbone to anchor complex multi-entity consolidation demand. Sage Group plc competes through localized tax compliance engines across European jurisdictions. Zoho Corporation differentiates via aggressive freemium tiering that captures solo practitioners and micro-firms.
Hand Account Software denotes digital platforms that automate ledger maintenance, transaction categorization, financial statement generation, and statutory tax filing through rule-based engines and API-connected bank feeds. Cloud-based deployment leads functional-area segmentation because real-time collaboration and automatic backup eliminate on-premise server burdens for distributed teams. The payroll functional area records the fastest structural expansion as gig-economy workforce classification rules multiply compliance complexity. API integration capability now sits at the core of margin pools, since embedded banking and e-invoicing connectivity commands subscription premiums.
The EU AI Act and GDPR constrain algorithmic expense-categorization features and cross-border data residency choices for vendors serving European freelancers and SMEs. India's RBI and CDSCO-equivalent financial data standards, alongside the US IRS e-filing mandates, fragment certification requirements and force modular product architectures. Stakeholders must monitor whether emerging real-time tax reporting regimes in major economies will obsolete batch-processing legacy stacks or create parallel compliance product lines.
Market Dynamics
Real-time tax reporting mandates across major economies are forcing vendors to abandon batch-processing architectures in favor of streaming ledger systems, compressing product development cycles and fragmenting compliance certification requirements.
Growth Catalysts
- EU AI Act algorithmic transparency rules:Automated expense categorization engines must now maintain audit trails, creating demand for upgraded compliance modules among European SMEs.
- India's RBI financial data localization:Domestic cloud infrastructure requirements accelerate indigenous platform development and reduce foreign vendor dominance in South Asian markets.
- Gig-economy workforce classification complexity:Multi-jurisdictional contractor payroll rules expand addressable market for specialized compliance automation tools.
Market Restraints
- Cloud infrastructure concentration:Hyperscaler dependency in three dominant providers creates systemic resilience risk for distributed ledger backup systems.
- API standard fragmentation:Incompatible banking feed protocols across regional financial institutions inflate integration engineering costs.
- Legacy ERP substitution threat:Embedded accounting modules within enterprise resource planning suites capture mid-market customers seeking unified workflows.
Strategic Opportunities
- German Mittelstand digitization gap:Family-owned manufacturing SMEs remain underpenetrated by cloud-native solutions due to historical on-premise SAP loyalty.
- Open banking and embedded finance convergence:Real-time payment reconciliation fused with automated bookkeeping creates new product category for fintech-software hybrids.
- US IRS continuous transaction reporting pilots:Proposed real-time income verification mandates would obsolete quarterly filing workflows and demand streaming architecture upgrades.
Industry Challenges
- Qualified API integration engineers:Scarcity of developers proficient in both financial data standards and modern cloud-native stacks extends implementation timelines.
- Multi-jurisdictional certification synchronization:Parallel GDPR, EU AI Act, and national tax authority approvals delay feature releases by 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Hand Account Software Market |
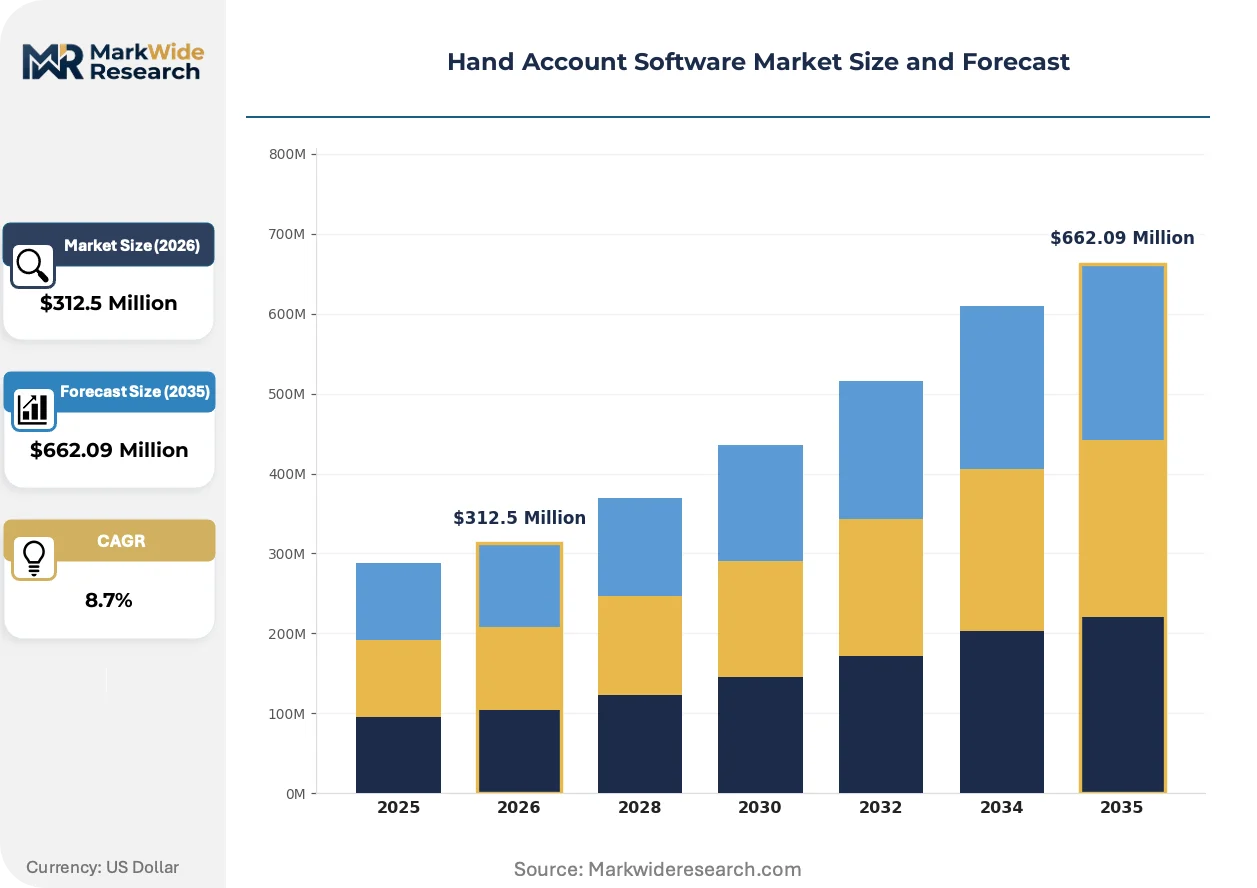
| Market Size in 2026 | $312.5 Million |
| Market Size in 2035 | $662.09 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment Model: Cloud-based, On-premise, Hybrid, SaaS Customer Type: Small Businesses, Medium Enterprises, Large Corporations, Freelancers Functional Area: Accounting, Budgeting, Tax Management, Payroll Integration Capability: API Integration, Third-party Software, Data Import, Real-time Sync |
| Companies Covered | SAP SE, Oracle Corporation, Intuit, Sage Group plc, Zoho Corporation, Xero, FreshBooks, Workday, Inc, Infor, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Hand Account Software Market Trends and Innovations
Streaming data architectures are supplanting batch-processing foundations across the competitive landscape, while regulatory pressure on algorithmic decision-making and embedded finance integration reshape product roadmaps.
Embedded machine-learning expense categorization is supplanting rule-based transaction coding in mid-market suites. Freelancer platforms and digital-native micro-firms adopt these engines fastest, compressing manual reconciliation labor to near-zero for standard transactions.
GDPR Article 22 automated decision-making constraints are reshaping algorithmic feature design across European deployments. Vendors must now implement human-in-the-loop overrides for AI-driven tax recommendations, increasing interface complexity but reducing regulatory liability exposure for German and French customer bases.
Subscription unbundling is fragmenting traditional suite pricing. Solo practitioners now purchase payroll-only or invoicing-only modules through app marketplaces, displacing the all-in-one package model that dominated SME procurement for two decades. This pattern concentrates in India's freelancer economy and US side-hustle demographics.
Hand Account Software Market Segmentation
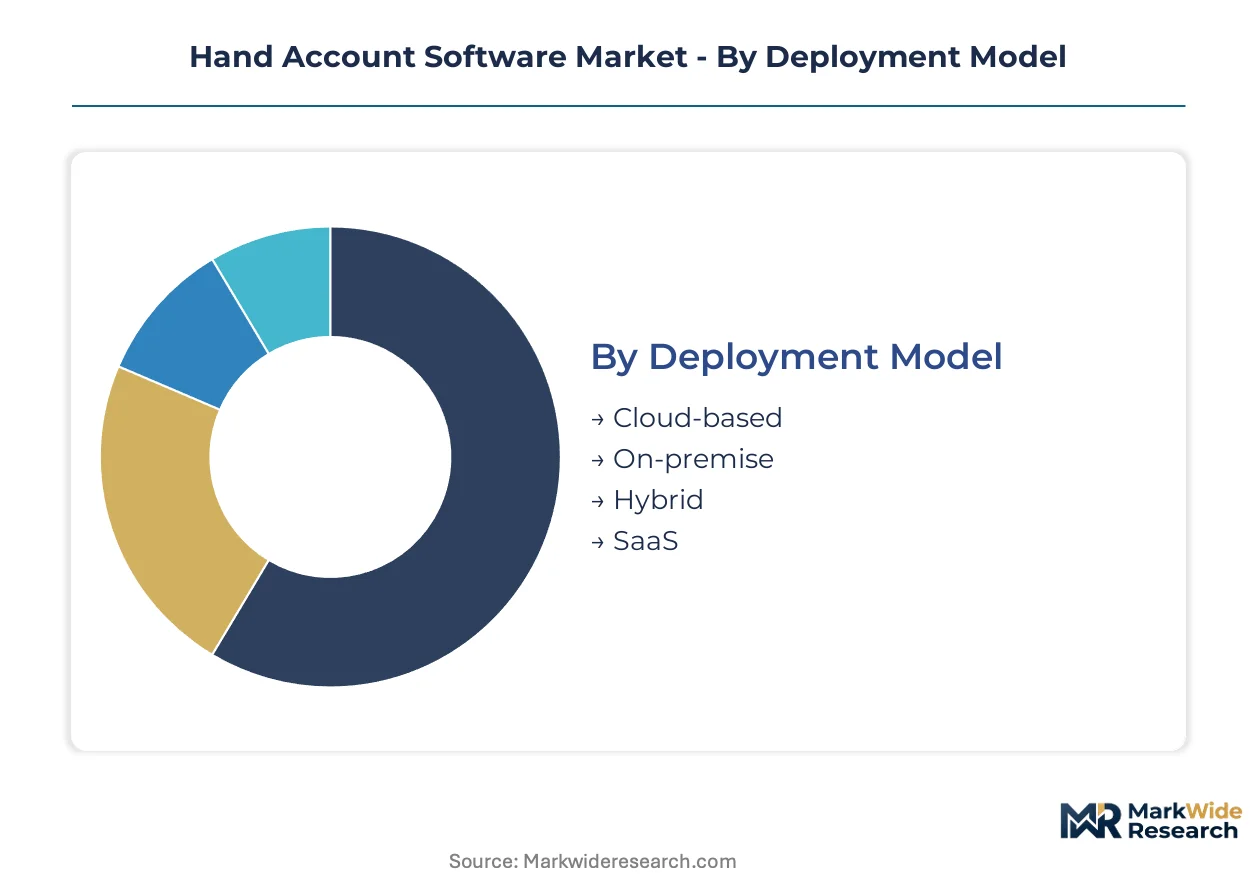
Segmentation in the Hand Account Software Market reveals how regulatory fragmentation and customer scale dictate divergent product architectures. Vendors must engineer separate compliance layers for each deployment environment while calibrating feature depth to workforce size and functional complexity.
Deployment Model:
GDPR data residency mandates and the EU AI Act's algorithmic transparency requirements split vendor roadmaps across deployment architectures, with European freelancers demanding localized cloud instances that US contractors rarely require.
- Cloud-based:Multi-tenant architectures with automatic backup and real-time collaboration dominate distributed team adoption. German Mittelstand manufacturers and Indian digital-native startups drive demand as legacy server maintenance costs become unsustainable.
- On-premise:Single-tenant installations with direct hardware control persist in sectors with stringent data sovereignty requirements. French public sector entities and defense contractors in the United States maintain this preference despite higher total cost of ownership.
- Hybrid:Split workloads with sensitive payroll data on local servers and routine bookkeeping in public cloud. Mid-market professional services firms in the United Kingdom adopt this configuration to satisfy client confidentiality agreements.
- SaaS:Browser-delivered applications with zero local infrastructure burden. Solo practitioners and micro-firms across India and the United States gravitate toward this lowest-friction entry point.
Established volume favors Cloud-based; emerging adoption favors SaaS.
Customer Type:
Workforce classification complexity scales inversely with organizational size, creating tiered compliance automation requirements that fragment pricing and feature packaging strategies.
- Small Businesses:Entities with under 50 employees requiring streamlined ledger maintenance and basic tax filing automation. Owners in the United States and Germany seek solutions that minimize external accountant dependency.
- Medium Enterprises:Organizations with 50-500 employees needing multi-entity consolidation and departmental budgeting workflows. Indian manufacturing SMEs and US professional services firms represent concentrated demand for this tier.
- Large Corporations:Complex multi-jurisdictional operations demanding ERP-grade consolidation and statutory reporting across dozens of tax regimes. SAP SE and Oracle Corporation capture this segment through embedded accounting modules.
- Freelancers:Solo operators with gig-economy income streams requiring simplified invoicing and quarterly estimated tax calculations. This demographic expands fastest in India's platform economy and US side-hustle markets.
Revenue concentration sits with Medium Enterprises; steepest expansion trajectory belongs to Freelancers.
Functional Area:
Real-time tax reporting mandates are elevating Payroll from back-office utility to strategic compliance priority, while Budgeting gains prominence amid interest rate volatility.
- Accounting:Core ledger automation with transaction categorization and financial statement generation. This foundational capability anchors procurement decisions for Small Businesses across Germany and the United States.
- Budgeting:Forecasting tools with scenario modeling and variance analysis. Medium Enterprises in India and the United Kingdom deploy these modules to navigate working capital constraints.
- Tax Management:Statutory filing preparation with jurisdiction-specific rule engines. Vendors serving European customers must integrate GDPR Article 22 human-in-the-loop overrides for AI-driven recommendations.
- Payroll:Workforce compensation processing with contractor classification and multi-state compliance. Gig-economy expansion in the United States and platform worker regulations in India propel this segment's structural growth.
Feature completeness concentrates in Accounting; regulatory pressure elevates Payroll fastest.
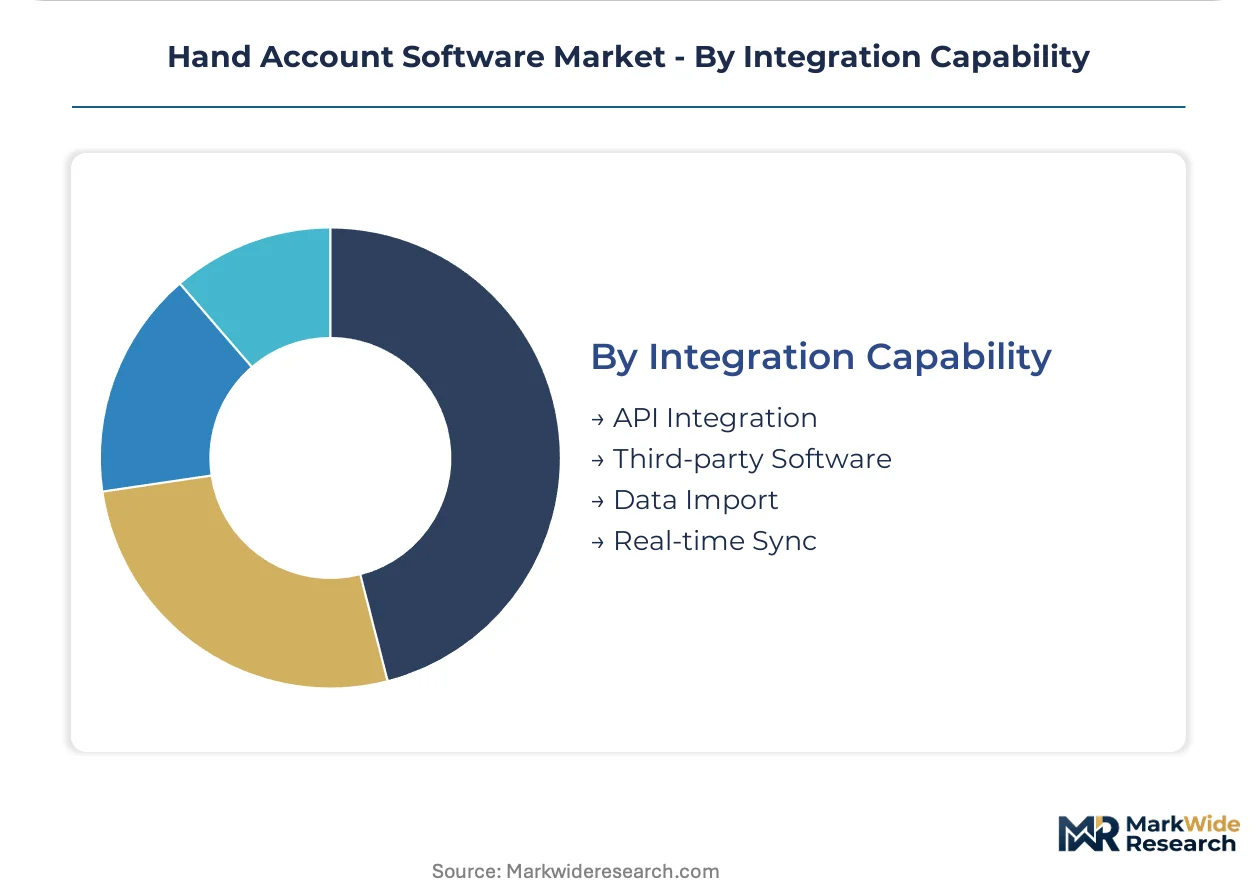
Integration Capability:
API standard fragmentation across regional banking systems inflates engineering costs and creates vendor lock-in through proprietary connector ecosystems.
- API Integration:Programmatic data exchange with external systems through documented endpoints. Embedded finance convergence in Germany and open banking mandates in the United Kingdom make this capability table stakes.
- Third-party Software:Pre-built connectors to CRM, inventory, and e-commerce platforms. Small Businesses in the United States prioritize this plug-and-play approach over custom development.
- Data Import:Batch file ingestion from legacy systems and spreadsheet formats. On-premise migration projects in French manufacturing retain demand for this transitional capability.
- Real-time Sync:Continuous bidirectional data flow eliminating reconciliation lag. Fintech-software hybrids targeting Indian freelancers and US digital-native firms differentiate through this architecture.
Implementation friction favors Third-party Software; competitive differentiation shifts toward Real-time Sync.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across geographies. Freelancers in India and the United States adopt stripped-down SaaS modules for gig-economy tax compliance, while German manufacturers demand multi-entity consolidation tools that interface with legacy ERP infrastructure.
United States
Digital-native micro-firms and side-hustle operators drive SaaS adoption for quarterly estimated tax automation. IRS continuous transaction reporting pilots are forcing streaming architecture upgrades among incumbent vendors. Silicon Valley fintech-software hybrids and Austin-based payroll specialists are capturing freelancer segment growth through real-time sync capabilities.
Germany
Family-owned Mittelstand manufacturers sustain demand for complex consolidation tools despite historical on-premise SAP loyalty. GDPR Article 22 constraints and EU AI Act algorithmic transparency rules reshape feature design for automated tax recommendations. Munich and Stuttgart industrial clusters are witnessing gradual cloud migration as server maintenance costs escalate.
India
Platform economy freelancers and digital-native startups represent the fastest-expanding customer tier. RBI financial data localization mandates and CDSCO-equivalent standards accelerate indigenous platform development. Bangalore and Hyderabad tech corridors are spawning domestic SaaS vendors that compete through aggressive freemium tiering.
United Kingdom
Mid-market professional services firms adopt hybrid deployments to satisfy client confidentiality agreements. Open banking mandates elevate API integration capability to table stakes. London's financial services cluster and Manchester's professional services corridor are driving demand for real-time payment reconciliation tools.
France
Public sector entities and defense contractors maintain on-premise preferences despite higher total cost of ownership. CNIL oversight of automated decision-making systems adds compliance layers to AI-driven expense categorization. Paris Île-de-France and Toulouse aerospace clusters sustain single-tenant installation demand for sensitive payroll data.
Hand Account Software Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, creating a bifurcated structure where enterprise ERP anchors compete against cloud-native challengers. The upper tier commands multi-jurisdictional compliance certification and streaming architecture capabilities. Three strategic archetypes dominate: legacy ERP extenders, freemium SaaS disruptors, and vertical payroll specialists. Competitive moves concentrate on API ecosystem expansion and modular unbundling of traditional suite pricing.
Within the legacy ERP extender tier, SAP SE and Oracle Corporation occupy positions anchored to enterprise consolidation demand. Sage Group plc exemplifies the localized compliance engine archetype across European jurisdictions. Zoho Corporation sits within the aggressive freemium tier that captures solo practitioners and micro-firms through stripped-down entry tools.
| Leading Market Players |
|---|
| SAP SE |
| Oracle Corporation |
| Intuit |
| Sage Group plc |
| Zoho Corporation |
| Xero |
| FreshBooks |
| Workday, Inc |
| Infor, Inc. |
| Others |
Pricing and Supply Chain Analysis
Cloud infrastructure scale economies in hyperscaler data centers compress unit economics for SaaS delivery, concentrating vendor margin pools among platforms achieving multi-tenant density above critical thresholds while fragmenting price floors for sub-scale competitors.
Pricing Analysis
Contract structures in Hand Account Software gravitate toward annual subscription tiers with modular unbundling displacing legacy suite licensing. Three-tier pricing separates enterprise-grade multi-entity consolidation from mid-market departmental tools and freelancer entry modules. Price differentiation rests on API integration depth and jurisdiction-specific compliance certification rather than core ledger functionality. Cost compression in the freelancer tier intensifies because Zoho Corporation and domestic Indian vendors compete through aggressive freemium conversion. Small Businesses exhibit highest price sensitivity; Large Corporations prioritize integration reliability over subscription cost.
Supply Chain Analysis
API standard fragmentation across regional banking systems creates engineering chokepoints that inflate integration timelines for vendors serving multi-jurisdictional customers. Cloud infrastructure supply concentrates in United States, Ireland, and Singapore data center clusters where GDPR data residency and RBI localization mandates force geographic distribution of compute workloads. Raw material dependencies include banking feed protocols, identity verification APIs, and tax authority filing endpoints. Single-source vulnerability runs through dominant hyperscaler relationships where three providers control distributed ledger backup resilience. Distribution runs through direct digital sales for SaaS tiers and channel partners for enterprise deployments requiring implementation support.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Shortage of developers proficient in both financial data standards and cloud-native architectures constrains feature velocity, creating asymmetric advantage for vendors with established certification pipelines and modular product architectures.
For Market Incumbents: Secure multi-jurisdictional compliance certification synchronization to compress 8-14 month approval delays that fragment product roadmaps. Deepen vertical integration into embedded banking partnerships to capture fintech-software hybrid margins before challenger platforms consolidate API ecosystems. SAP SE and Oracle Corporation must defend against cloud-native payroll specialists eroding mid-market share through real-time sync capabilities.
For New Entrants and Emerging Players: Lead with unbundled payroll-only modules targeting India's platform economy freelancers where RBI localization mandates disadvantage foreign incumbents. White-space concentration sits in German Mittelstand manufacturers migrating from on-premise SAP loyalty toward cloud-native consolidation tools. Go-to-market execution should emphasize human-in-the-loop tax recommendation interfaces that satisfy GDPR Article 22 constraints without engineering overhead.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among vertical payroll specialists with gig-economy compliance automation depth. Long-term viability across the analysis window favors platforms with streaming architecture foundations capable of absorbing real-time tax reporting mandates. Acquisition target archetype: domestic Indian SaaS vendors with RBI-certified infrastructure and established freelancer user bases. Signal to watch: IRS continuous transaction reporting pilot expansion that would obsolete quarterly filing workflows and trigger incumbent vendor replacement cycles.
| Strategic Initiative | Industry Significance |
|---|---|
| API Ecosystem Expansion | Embedded banking partnerships in Germany and open banking mandates in the United Kingdom command subscription premiums. |
| Compliance Module Investment | EU AI Act audit trail requirements and GDPR Article 22 overrides reshape European feature roadmaps. |
| Streaming Architecture Migration | Real-time tax reporting pilots in the United States and India obsolete batch-processing legacy stacks. |
| Geographic Localization | RBI data residency mandates accelerate indigenous platform development and reduce foreign vendor dominance. |
| Vertical Payroll Specialization | Gig-economy workforce classification complexity expands addressable market for contractor compliance tools. |
Research Methodology
Cross-validation between primary interviews with software engineering directors and secondary validation through SEC filings and hyperscaler capex disclosures anchors the qualitative findings. Stakeholder roles engaged include CTOs at mid-market professional services firms, IT procurement officers at German manufacturing SMEs, platform engineers at Indian fintech-software hybrids, and integration specialists at payroll service bureaus. Secondary sources encompass EU regulatory filings documenting GDPR Article 22 implementation patterns, RBI circulars on financial data localization, and IRS technical guidance on continuous transaction reporting pilots. Bottom-up deployment model adoption curves triangulate against top-down addressable market sizing across freelancer, small business, and enterprise tiers.
Sensitivity analysis around regulatory implementation timelines and cloud infrastructure cost trajectories informs scenario-weighted outputs across the projection horizon. Segmentation dimensions modeled include deployment architecture, organization size tier, functional area priority, integration complexity level, and regional regulatory cluster. CAGRs derive from fitted adoption curves calibrated to historical SaaS penetration patterns in adjacent financial automation categories. Industry-specific forecast inputs include API standard fragmentation indices and multi-jurisdictional certification lag estimates.
Underlying assumptions cover steady-state regulatory enforcement, stable hyperscaler pricing, and gradual Mittelstand cloud migration, with deviation risk concentrated in accelerated real-time tax reporting mandates and geopolitical data localization escalations. Practitioners should keep alternative scenarios live as EU AI Act algorithmic transparency rules and IRS pilot program expansions evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
FinTech
North America Fintech Market
FinTech
Netherlands AI in Fintech Market
FinTech
Latin America Fintech Market
FinTech
Fintech Technologies Market
FinTech
United Kingdom Fintech Market
FinTech
IT Financial Management Tools Market
FinTech
Decentralized Finance Technology Market
FinTech
Vietnam Fintech Market
FinTech
Financial Consolidation Software Market
FinTech
Financial Audit Software Market
FinTech
Financial App Market
FinTech
Global Fundraising Software Market
FinTech
Business Analytics in Fintech Market
FinTech
Global Fin Tech Blockchain Market
FinTech
Asia-Pacific AI in Fintech Market
FinTech
Financial Analytics Market