
 Financial Technology Fintech Market | 2026-2036
Financial Technology Fintech Market Size, Share, and Industry Trends Forecast 2026-2036
Financial Technology Fintech Market Insights
The EU AI Act is restructuring risk classification requirements for automated lending and fraud-detection systems across European fintech deployments. Stripe Inc. leverages its infrastructure stack to anchor embedded finance distribution for software platforms. Adyen N.V. competes through unified commerce capabilities spanning online, in-store, and mobile channels. PayPal Holdings Inc. dominates consumer digital wallets with established two-sided network density across North America and Europe.
Financial technology encompasses software, platforms, and infrastructure that automate, digitize, or disintermediate traditional financial services through API-driven architecture, real-time data processing, and distributed ledger verification. Its primary purpose is reducing transaction friction, expanding credit access, and lowering compliance costs for regulated and unregulated financial intermediaries. Payment Processing leads service-type revenue generation due to recurring transaction-volume economics and merchant-acquiring scale. Artificial Intelligence within the technology dimension sustains margin expansion through predictive risk scoring and conversational customer interfaces. Cloud Computing deployment models anchor fastest-growing infrastructure adoption as neobanks and regional lenders exit on-premises data center obligations.
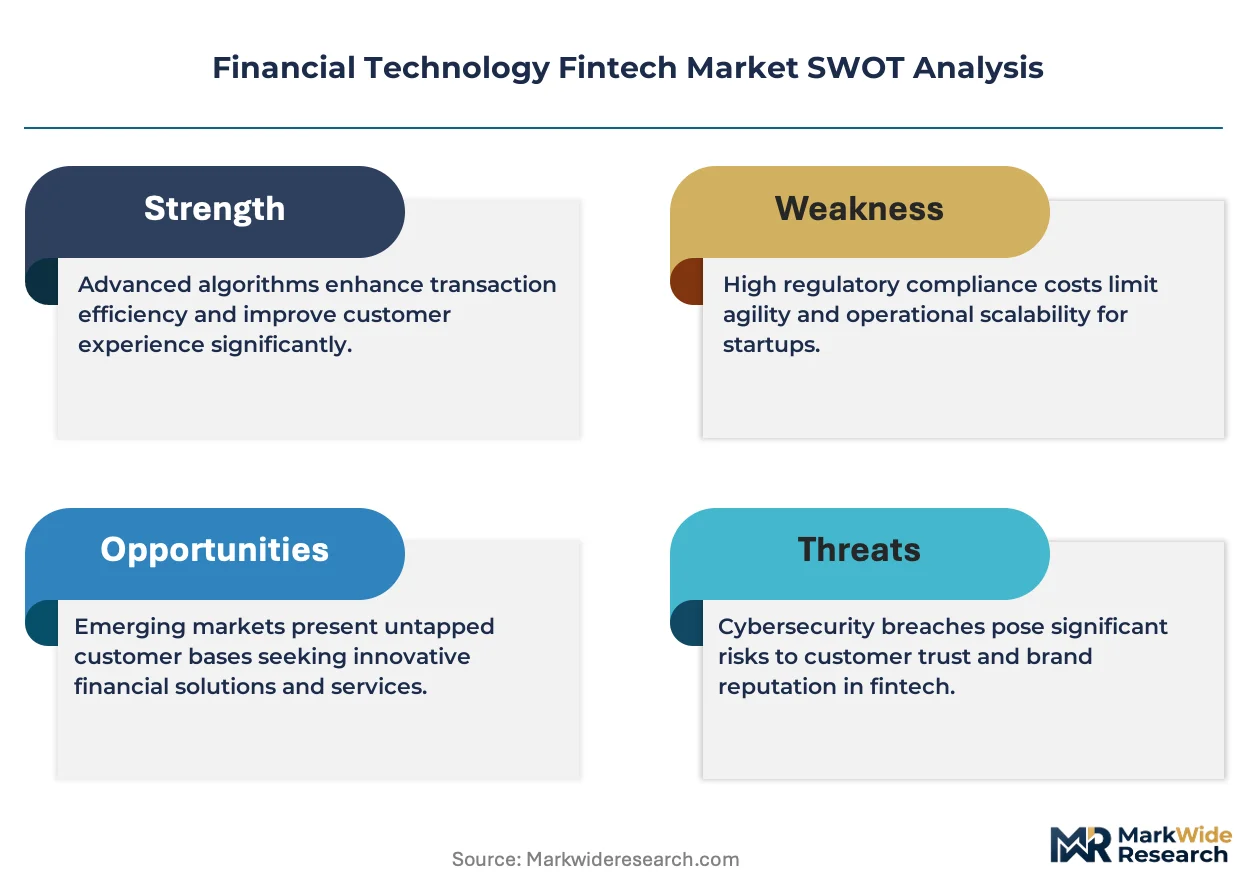
The US Consumer Financial Protection Bureau shapes fintech product standards through enforcement of fair lending and deposit insurance rules, while the EU Digital Operational Resilience Act imposes systemic incident-reporting requirements on critical payment and cloud service providers. India's RBI mandates data localization for payment system operators, constraining cross-border cloud architecture choices for foreign entrants. Stakeholders must monitor divergence between permissive sandbox regimes and prescriptive licensing frameworks as jurisdictions compete for fintech capital without surrendering financial stability mandates.
Market Dynamics
Embedded finance adoption is compressing distribution layers as software platforms integrate payment acceptance directly into merchant workflows, bypassing traditional banking intermediaries and reshaping how financial services reach end-users.
Growth Catalysts
- EU AI Act compliance frameworks:Algorithmic credit scoring systems across European fintech deployments face mandatory risk classification, creating specialized demand for explainable AI infrastructure and audit-ready decision engines.
- India's UPI rail expansion:Real-time payment volume through India's digital public infrastructure enables merchant onboarding at fractional cost compared to card network economics, accelerating financial inclusion in underbanked segments.
- Cloud-native core banking migration:Neobanks and regional lenders exit on-premises data center obligations, shifting capital expenditure to operational models that scale with transaction volume.
Market Restraints
- Data localization mandates:India's RBI requires payment system operators to store transaction data within national borders, constraining cross-border cloud architecture choices and increasing compliance overhead for foreign entrants.
- Algorithmic bias liability exposure:Automated lending decisions face heightened scrutiny under fair lending enforcement, requiring costly model validation and documentation systems that compress margins on thin-spread credit products.
- Core banking vendor concentration:Legacy core system providers in North America and Europe control critical infrastructure for established institutions, creating switching friction that slows modernization timelines.
Strategic Opportunities
- Brazil's PIX instant payment network:Underpenetrated merchant segments in Latin America's largest economy present white space for embedded finance platforms to replicate India's UPI success through API-first distribution.
- Convergence of AI and blockchain verification:Smart contract-based identity verification combined with predictive risk scoring enables automated KYC workflows that reduce onboarding friction for cross-border remittance corridors.
- EU Digital Operational Resilience Act incident reporting:Mandatory systemic reporting requirements for critical payment providers create demand for specialized compliance software and third-party risk management tools.
Industry Challenges
- Explainable AI talent scarcity:Model interpretability requirements under EU AI Act and US fair lending rules outpace supply of engineers capable of building auditable algorithmic systems, inflating compensation costs for specialized roles.
- Legacy core integration complexity:Mainframe-based banking infrastructure at incumbent institutions requires expensive middleware layers to connect with modern API architectures, extending implementation timelines and inflating project risk.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Financial Technology Fintech Market |
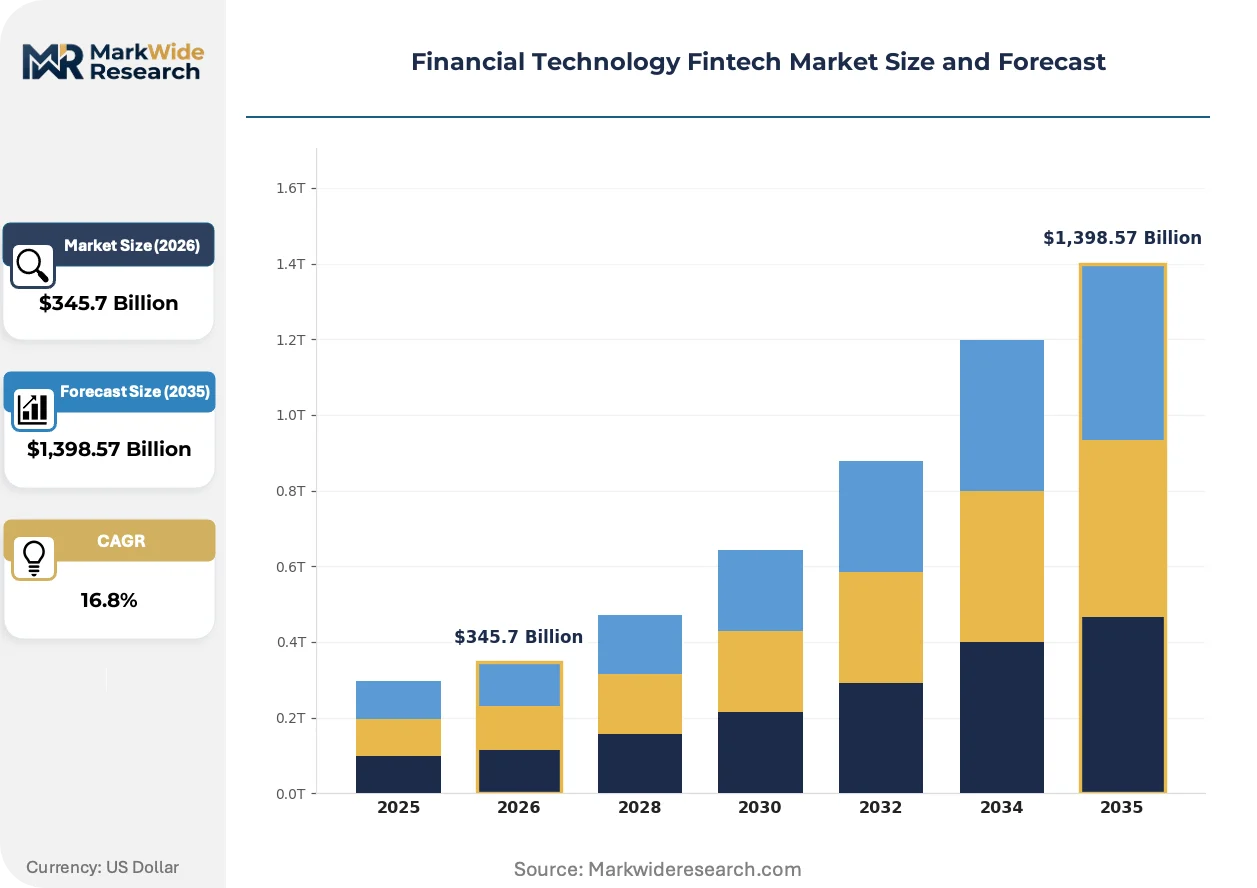
| Market Size in 2026 | $345.7 Billion |
| Market Size in 2035 | $1,398.57 Billion |
| CAGR (2026 – 2036) | 16.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Payment Processing, Digital Lending, Wealth Management, Insurtech, Regtech, Personal Finance Technology: Blockchain, Artificial Intelligence, Cloud Computing, Big Data Analytics, Biometrics, Robotic Process Automation Client Type: Banks, Credit Unions, Microfinance Institutions, Fintech Startups, Investment Firms, Payment Processors Deployment Model: Cloud-Based, On-Premises, Hybrid Solutions, API Integration, SaaS Platforms, Mobile Applications |
| Companies Covered | PayPal Holdings Inc., Ant Group Co. Ltd., Stripe Inc., Block Inc., Adyen N.V., Coinbase Global Inc., Robinhood Markets Inc., Revolut Ltd., Nubank, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Financial Technology Fintech Market Trends and Innovations
Distributed ledger infrastructure is rearchitecting trust mechanisms in financial transactions, displacing centralized intermediaries with programmable settlement layers that compress clearing cycles and reduce counterparty exposure.
Blockchain-based settlement rails are decentralizing correspondent banking relationships by enabling programmable escrow and atomic settlement between counterparties without intermediary reconciliation. Cross-border payment platforms in Southeast Asia and the Middle East are deploying these protocols to bypass SWIFT messaging delays. The structural consequence is compressing settlement windows from T+2 to real-time, eliminating prefunding requirements and freeing trapped liquidity.
The EU AI Act's risk-based classification system is mandating human oversight for high-risk automated credit decisions, forcing fintech lenders to redesign algorithmic workflows with intervention checkpoints. Deployment of explainable model architectures now precedes product launch in European markets. Credit-scoring platforms are responding by integrating local-language model documentation and audit trail systems that satisfy national regulator interpretation variance.
Merchant procurement of financial services is fragmenting across vertical software platforms rather than concentrating through banking relationships. SaaS providers in retail, hospitality, and logistics are embedding payment acceptance, lending, and insurance into operational workflows. This pattern is most visible in India and Southeast Asia, where platform density enables single-vendor consolidation of previously separate financial service procurement decisions.
Financial Technology Fintech Market Segmentation
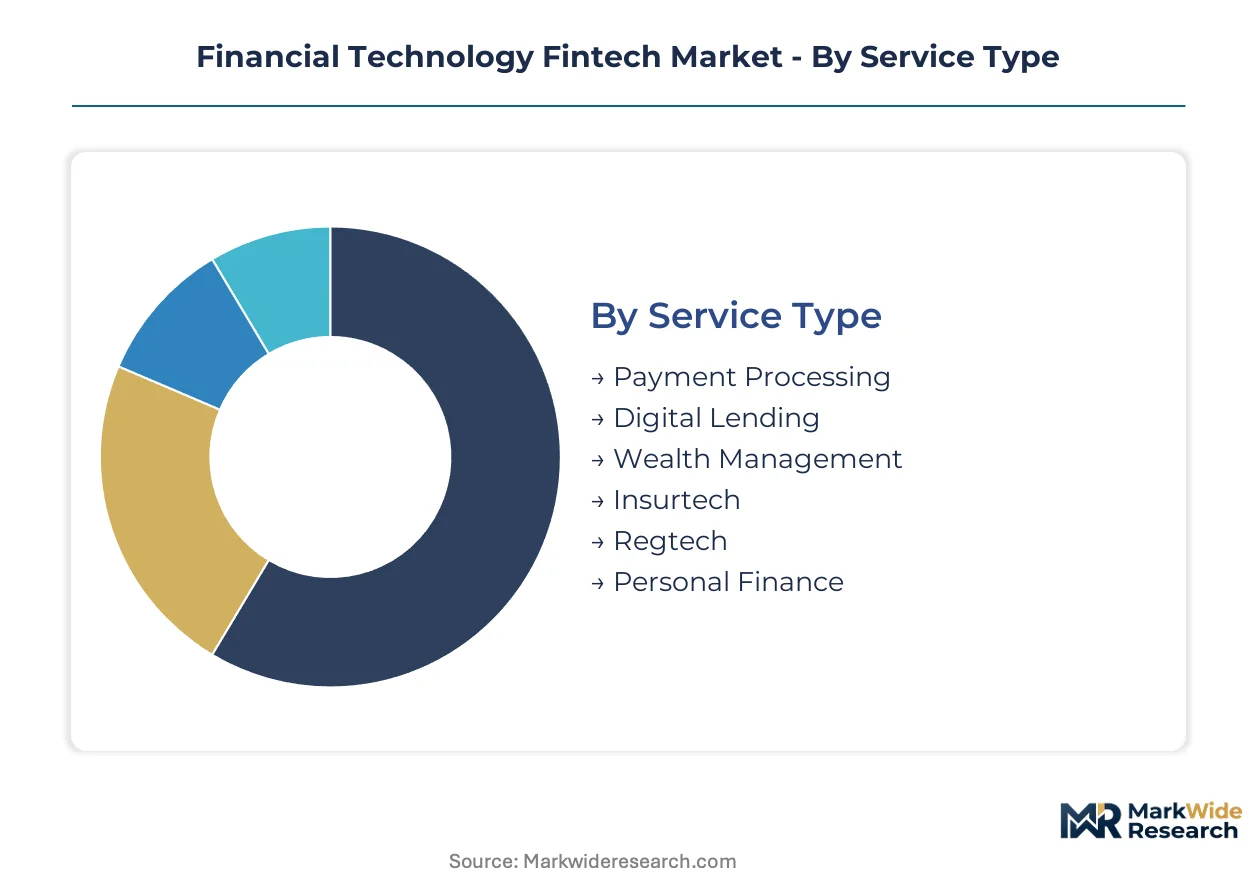
Segmentation in fintech reveals how regulatory burden, infrastructure maturity, and customer sophistication fragment procurement patterns across service lines. Distinct compliance obligations attach to each technology tier and client category, shaping vendor selection criteria and contract structures.
Service Type:
Payment Processing carries the heaviest certification load across jurisdictions, requiring PCI DSS compliance, EU Digital Operational Resilience Act registration, and RBI data localization adherence for cross-border operators. Digital Lending faces layered scrutiny under US fair lending enforcement and EU AI Act algorithmic decision rules. Wealth Management navigates SEC fiduciary standards and MiFID II suitability requirements. Insurtech must satisfy state-level insurance commissioner approvals in the US and Solvency II equivalence in Europe. Regtech vendors pursue ISO 27001 and SOC 2 Type II attestations. Personal Finance applications confront GDPR consent architecture and CCPA disclosure mandates.
- Payment Processing:Transaction-rail infrastructure enabling merchant acquiring, card network integration, and real-time settlement across domestic and cross-border corridors. Demand concentrates among retail merchants in India leveraging UPI rails for fractional-cost onboarding, constrained by RBI data localization mandates that force domestic server deployment.
- Digital Lending:Algorithmic credit origination platforms spanning consumer, SME, and point-of-sale financing. European neobanks and regional lenders drive procurement, compelled by EU AI Act risk classification to deploy explainable model architectures with mandatory human oversight checkpoints.
- Wealth Management:Robo-advisory and portfolio management tools for retail and mass-affluent segments. US registered investment advisors and European private banks anchor demand, navigating SEC and national regulator custody rule variations.
- Insurtech:Digital distribution, underwriting automation, and claims management for property, life, and health lines. Southeast Asian insurers and Middle Eastern takaful operators expand fastest, adapting products to local regulatory sandbox frameworks.
- Regtech:Compliance automation for AML, KYC, transaction monitoring, and regulatory reporting. Tier 1 banks in the US and EU dominate procurement, responding to FinCEN and ECB enforcement intensity.
- Personal Finance:Budgeting, credit monitoring, and savings tools for consumer self-service. Indian and Brazilian fintech startups capture underbanked segments through mobile-first distribution.
Payment Processing sits at the top of the volume ranking, with Digital Lending climbing the fastest.
Technology:
Cost tier stratification separates enterprise-grade infrastructure from mid-market accessible tools, with Blockchain and AI commanding premium implementation spend while RPA and Biometrics penetrate lower contract values.
- Blockchain:Distributed ledger infrastructure for settlement, identity, and smart contract execution. Southeast Asian cross-border payment platforms and Middle Eastern trade finance consortia deploy these protocols to bypass SWIFT delays, compressing settlement from T+2 to real-time.
- Artificial Intelligence:Predictive risk scoring, conversational interfaces, and algorithmic decision engines. European fintech lenders face mandatory EU AI Act compliance costs that inflate model validation and documentation overhead.
- Cloud Computing:Elastic infrastructure for core banking, payment processing, and data analytics workloads. Neobanks in Brazil and Nigeria exit on-premises obligations fastest, shifting capex to operational models scaling with transaction volume.
- Big Data Analytics:Customer intelligence, fraud detection, and portfolio optimization engines. US card issuers and Indian payment system operators concentrate demand, leveraging real-time data processing for behavioral scoring.
- Biometrics:Fingerprint, facial recognition, and voice authentication for identity verification and transaction authorization. African mobile money providers and Southeast Asian super-apps integrate these layers for financial inclusion scaling.
- Robotic Process Automation:Back-office automation for reconciliation, compliance reporting, and customer service workflows. Mid-tier banks in Europe and North America deploy RPA to compress operational cost bases without core system replacement.
Cloud Computing leads contract volume, with Blockchain gaining share fastest among infrastructure investments.
Client Type:
Application maturity varies sharply: incumbent banks demand retrofit compatibility while fintech startups prioritize API-native architecture and rapid deployment velocity.
- Banks:Tier 1 and regional depository institutions modernizing legacy infrastructure. US money center banks and European universal banks drive largest contract values, constrained by mainframe integration complexity that extends implementation timelines.
- Credit Unions:Member-owned cooperative financial institutions in North America. US state-chartered credit unions procure cloud-native core systems to compete with neobanks on digital experience without matching IT staffing levels.
- Microfinance Institutions:Small-balance lenders serving underbanked populations. Indian NBFC-MFIs and Kenyan SACCOs expand mobile disbursement capabilities, leveraging digital public infrastructure for last-mile credit delivery.
- Fintech Startups:Venture-backed neobanks, payment platforms, and lending marketplaces. Brazilian and Indonesian startups anchor fastest procurement velocity, exploiting regulatory sandbox access to compress time-to-market.
- Investment Firms:Asset managers, hedge funds, and private equity sponsors. US RIAs and European UCITS managers demand portfolio analytics and alternative data integration for alpha generation.
- Payment Processors:Merchant acquirers, card networks, and money transmitters. Indian payment system operators and Middle Eastern remittance corridors modernize settlement infrastructure under central bank modernization mandates.
Banks dominate absolute procurement value, with Fintech Startups expanding most quickly in number of new vendor relationships.
Deployment Model:
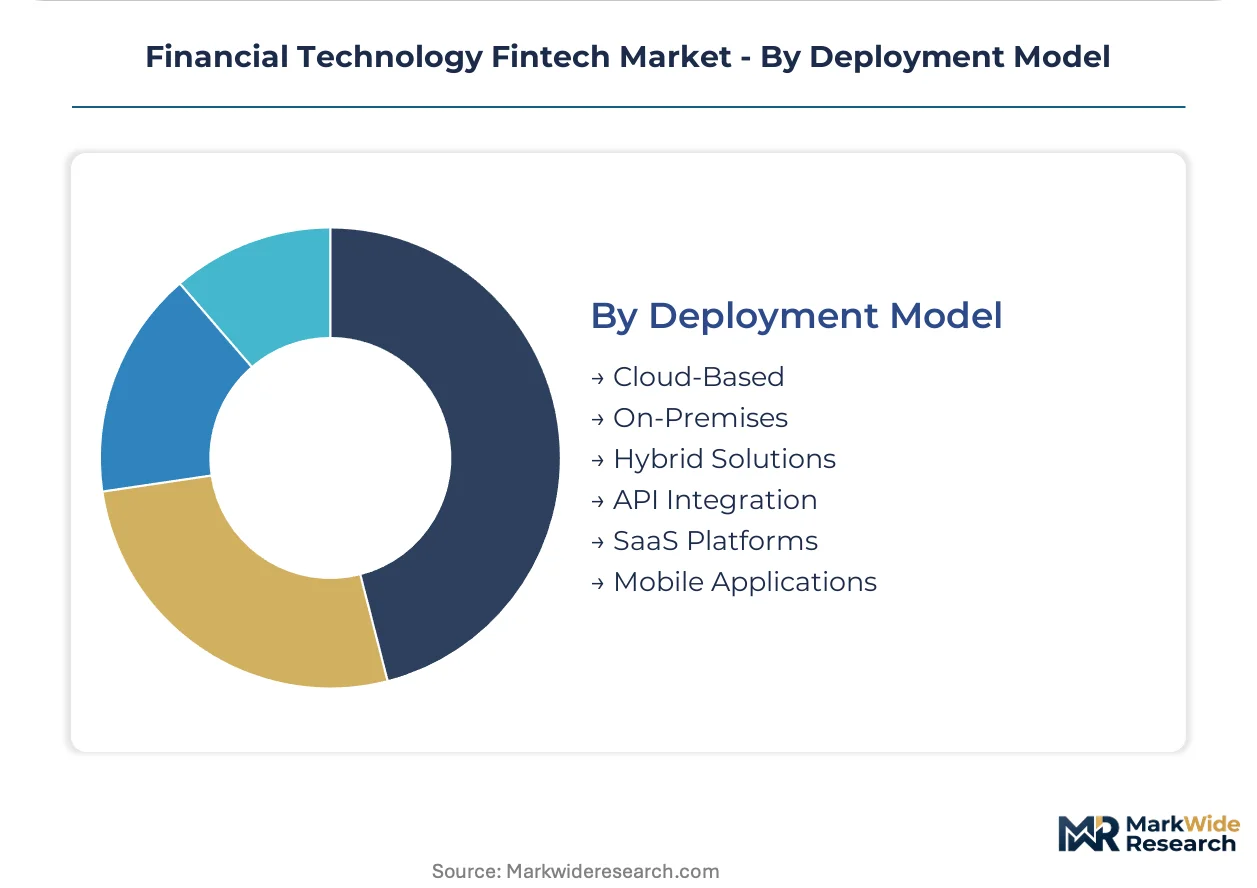
Geography dictates architecture choice: data localization mandates in India and China force on-premises or sovereign cloud deployment, while permissive jurisdictions enable pure SaaS delivery.
- Cloud-Based:Fully managed infrastructure with elastic scaling and pay-per-use economics. Neobanks in Singapore and the UK default to this model, exiting data center obligations entirely.
- On-Premises:Self-managed infrastructure within client-controlled facilities. Chinese banks and Indian payment system operators deploy on-premises stacks to satisfy NMPA and RBI data sovereignty requirements.
- Hybrid Solutions:Mixed architecture with sensitive workloads on-premises and scalable functions in cloud. European banks favor this pattern under Digital Operational Resilience Act systemic risk classifications.
- API Integration:Embedded connectivity layers for third-party service orchestration. Retail software platforms in India and Southeast Asia procure API-first payment acceptance to consolidate merchant financial services procurement.
- SaaS Platforms:Multi-tenant software delivery with standardized configuration and rapid deployment. US community banks and European cooperative institutions adopt SaaS core banking to compress vendor management overhead.
- Mobile Applications:Native and progressive web apps for consumer and merchant endpoints. Brazilian and Nigerian fintech startups prioritize mobile-first distribution to capture underbanked smartphone penetration.
Cloud-Based deployment leads in new contract volume, with API Integration expanding most rapidly among embedded finance platforms.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Engineering talent clusters in Bangalore, Singapore, and London anchor fintech infrastructure development across three continents. Regulatory divergence between permissive sandbox regimes and prescriptive licensing frameworks forces capital allocation trade-offs. Venture deployment concentrates where central bank digital currency pilots and real-time payment rails reduce customer acquisition costs.
United States
Venture capital deployment in digital lending and wealth management platforms drives procurement of cloud-native core systems. The Consumer Financial Protection Bureau enforces fair lending rules on algorithmic credit decisions, requiring model documentation systems. New York and San Francisco clusters host neobanks modernizing legacy payment infrastructure through API-first architectures.
India
UPI transaction volume expansion and merchant onboarding at fractional cost accelerate embedded finance penetration. The Reserve Bank of India mandates data localization for payment system operators, constraining cross-border cloud deployment. Mumbai and Bangalore clusters concentrate fintech startups leveraging digital public infrastructure for last-mile credit delivery.
United Kingdom
Open Banking API adoption and neobank density sustain demand for compliance automation tools. The Financial Conduct Authority enforces operational resilience standards on critical payment providers. London anchors European fintech capital formation, with regional lenders procuring SaaS core banking to compress vendor management overhead.
Brazil
PIX instant payment network penetration creates white space for embedded finance platforms in underpenetrated merchant segments. The central bank's regulatory sandbox accelerates neobank licensing velocity. São Paulo clusters host fintech startups replicating India's UPI success through API-first distribution models.
Germany
Industrial SME demand for integrated payment and working capital solutions drives B2B fintech procurement. BaFin enforces MiFID II suitability requirements on robo-advisory platforms. Berlin and Frankfurt clusters concentrate insurtech vendors adapting products to national regulatory interpretation variance.
Financial Technology Fintech Market Competitive Landscape
Capital-heavy infrastructure providers compete with asset-light software platforms for merchant and institutional relationships. The vendor base stratifies across three tiers: global payment networks with two-sided density, regional neobanks with regulatory sandbox access, and vertical software platforms embedding financial services. Strategic moves concentrate on API partnership ecosystems and cloud-native core banking migrations that shift client capital expenditure to operational models.
Among US-based platform operators, PayPal Holdings Inc. and Stripe Inc. exemplify divergent archetypes within payment infrastructure. PayPal occupies a position anchored in consumer digital wallet density across North America and Europe. Stripe sits within the embedded finance tier, supplying infrastructure stacks to software platforms seeking integrated payment acceptance. Ant Group Co. Ltd. represents the scale-driven Asian archetype, leveraging super-app architecture to consolidate financial service procurement decisions. These three anchors illustrate how geographic origin and platform strategy stratify competitive positioning without requiring identical capability investments.
| Leading Market Players |
|---|
| PayPal Holdings Inc. |
| Ant Group Co. Ltd. |
| Stripe Inc. |
| Block Inc. |
| Adyen N.V. |
| Coinbase Global Inc. |
| Robinhood Markets Inc. |
| Revolut Ltd. |
| Nubank |
| Others |
Pricing and Supply Chain Analysis
Venture-backed fintech infrastructure specialists concentrate ownership of cloud-native core banking platforms, compressing pricing discipline through recurring SaaS economics while sovereign wealth participation in Indian and Brazilian payment rails shapes procurement cost structures for foreign entrants.
Pricing Analysis
The bundled-vs-unbundled service split separates enterprise-grade payment processing from modular API components. Three-tier pricing structure across premium, standard, and economy levels aligns with PCI DSS certification tiers and RBI data localization compliance scope. Cost compression in economy-tier SaaS offerings intensifies because neobank density in Brazil and Nigeria forces vendor consolidation. Indian microfinance institutions exhibit highest price sensitivity due to fractional transaction margins, while Tier 1 North American banks absorb premium pricing for mainframe integration compatibility.
Supply Chain Analysis
Engineering talent scarcity in Bangalore and Singapore manufacturing geographies constrains deployment velocity for algorithmic credit platforms. Infrastructure supply concentrates in Ireland and Netherlands for EU data residency compliance, with component sourcing from Taiwan for specialized AI accelerators and from Estonia for blockchain verification nodes. Single-source vulnerability attaches to legacy core banking vendors in North America, where mainframe expertise concentrates among aging specialist workforces. Distribution runs through hyperscaler marketplaces and direct API documentation portals for developer-centric procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play: EU AI Act compliance costs inflate European fintech operational overhead while India's permissive sandbox regime and fractional UPI onboarding costs enable capital-efficient scale.
For Market Incumbents: Cement API partnership density with vertical software platforms before embedded finance consolidation accelerates. Defensive cloud-native core banking migrations must precede neobank regulatory sandbox expansion in Brazil and Southeast Asia. Priority lever rests on explainable AI talent acquisition to preempt EU AI Act audit requirements.
For New Entrants and Emerging Players: The premium-to-economy pricing gap in SME lending infrastructure exposes white space for modular, compliance-light deployment. Target underpenetrated merchant segments in Latin America replicating India's UPI embedded finance penetration. Go-to-market angle centers on PIX-native API distribution bypassing card network economics.
For Investors and Strategic Acquirers: Valuations sit cheapest among regional neobanks with regulatory sandbox access but subscale infrastructure ownership. Long-term viability favors asset-light platforms with embedded distribution rather than capital-heavy balance sheet lenders. Signal to watch: central bank digital currency pilot announcements compressing customer acquisition costs in target corridors.
| Strategic Initiative | Industry Significance |
|---|---|
| Cloud-Native Core Migration | Shifts neobank capex to opex models scaling with UPI transaction volume in India. |
| Explainable AI Platform Investment | Satisfies EU AI Act audit trails for algorithmic credit decisions across European deployments. |
| PIX API Distribution Partnership | Replicates India's embedded finance success through Brazil's instant payment rail penetration. |
| Data Localization Compliance Buildout | Meets RBI mandates constraining cross-border cloud architecture for payment operators. |
| Regulatory Sandbox Market Entry | Accelerates licensing velocity for fintech startups in Brazil and Indonesia before incumbent response. |
Research Methodology
Coverage spans North America, Europe, India, and Latin America, with primary inputs from each combining structured interviews with neobank CTOs, payment platform engineering leads, regulatory affairs specialists at RBI and BaFin, and venture capital fintech partners. Secondary validation draws from SEC 10-K infrastructure disclosures, ECB systemic risk reports, UPI transaction volume publications, and EU AI Act implementation guidance. Bottom-up vendor sizing and top-down macroeconomic triangulation anchor value estimates.
Rate-of-change decomposition separates transaction volume growth from pricing compression and regulatory cost inflation across the analysis window. Segmentation dimensions modeled include service type, technology tier, client archetype, and deployment model, with regional regulatory cluster as the fintech-specific overlay. CAGRs derive from historical trajectory analysis adjusted for policy inflection points. Industry-specific inputs incorporate central bank digital currency pilot timelines and real-time payment rail penetration curves.
Caveats apply where RBI data localization enforcement intensity or EU AI Act penalty calibration could materially shift the outlook. Forecasts reflect assumptions on regulatory divergence persistence and sandbox regime stability. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
FinTech
IoT for Finance Market
FinTech
France BNPL Market
FinTech
Wealthtech Solutions Market
FinTech
Middle East AI in Fintech Market
FinTech
Robo-Advisory Software Market
FinTech
Financial Audit Software Market
FinTech
Lendtech Market
FinTech
Fintech Lending Market
FinTech
Smart Advisors Market
FinTech
Spend Management Platform Market
FinTech
Germany AI in Fintech Market
FinTech
Fintech Cloud Market
FinTech
China AI in Fintech Market
FinTech
Decentralized Finance Technology Market
FinTech
Indonesia Financial Technology Services Market
FinTech
North America Fintech Cloud Market