
 Financial Services Software Market | 2026-2036
Financial Services Software Market Size, Share, and Industry Trends Forecast 2026-2036
Financial Services Software Market Analysis
The EU Green Deal is decoupling sustainability reporting from voluntary disclosure across European banking, forcing institutions to embed carbon accounting into core financial software. Stripe leverages its API-first infrastructure to capture this workflow shift among neobanks. Fiserv anchors its position through captive data-center assets that sustain compliance latency requirements for real-time payment clearing. Temenos specializes in modular core banking architecture that competes with monolithic legacy stacks.
Financial services software comprises modular applications that process transactions, manage risk exposure, automate regulatory reporting, and interface with clearing networks through standardized protocols such as ISO 20022. Banking software and risk management solutions command the deepest margin pools as institutions replace decades-old COBOL cores. Cloud-based deployment is expanding fastest among payment processors seeking elastic capacity for transaction spikes, while on-premises systems retain dominance at tier-one commercial banks with bespoke security mandates.
Basel Committee standards, the EU AI Act, and SEC climate disclosure rules collectively reshape product roadmaps by mandating algorithmic audit trails and emissions-linked risk weighting. The EU AI Act specifically prohibits opaque credit-scoring models, forcing vendors to build explainability layers into fraud detection modules. Stakeholders must monitor how divergent regulatory timetables between Washington and Brussels fragment compliance architecture requirements.
Market Dynamics
Cloud-native core banking platforms are displacing COBOL-based legacy systems as Basel III capital requirements tighten and real-time payment clearing demands elastic infrastructure. This architectural migration concentrates procurement among payment processors and investment firms seeking modular, API-first deployment models.
Growth Catalysts
- EU AI Act compliance mandates:Prohibitions on opaque credit-scoring models force financial institutions to retrofit explainability layers into fraud detection modules, expanding software replacement cycles.
- ISO 20022 protocol standardization:Payment processors across multiple jurisdictions are modernizing message formats to enable richer data exchange in cross-border clearing.
- Neobank API infrastructure expansion:Digital-native banks require embedded carbon accounting workflows to satisfy EU Green Deal sustainability reporting requirements.
Market Restraints
- COBOL talent scarcity:Decades-old codebase maintenance depends on an aging specialist workforce with limited pipeline replenishment.
- Captive data-center capex:Tier-one commercial banks with bespoke security mandates face stranded asset risk as cloud migration accelerates elsewhere.
- Divergent regulatory timetables:Misaligned compliance deadlines between Washington and Brussels fragment product architecture roadmaps.
Strategic Opportunities
- Modular core banking penetration:Monolithic legacy stack displacement creates white space for componentized architecture vendors.
- SEC climate disclosure alignment:Emissions-linked risk weighting requirements drive demand for integrated carbon accounting modules.
- Real-time payment clearing infrastructure:Elastic capacity provisioning for transaction spikes opens new service tiers among payment processors.
Industry Challenges
- Algorithmic audit trail implementation:Regulatory mandates for explainable AI require re-engineering of black-box fraud detection systems.
- Hybrid deployment complexity:Institutions maintaining on-premises security mandates while adopting cloud elasticity face integration friction.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Financial Services Software Market |
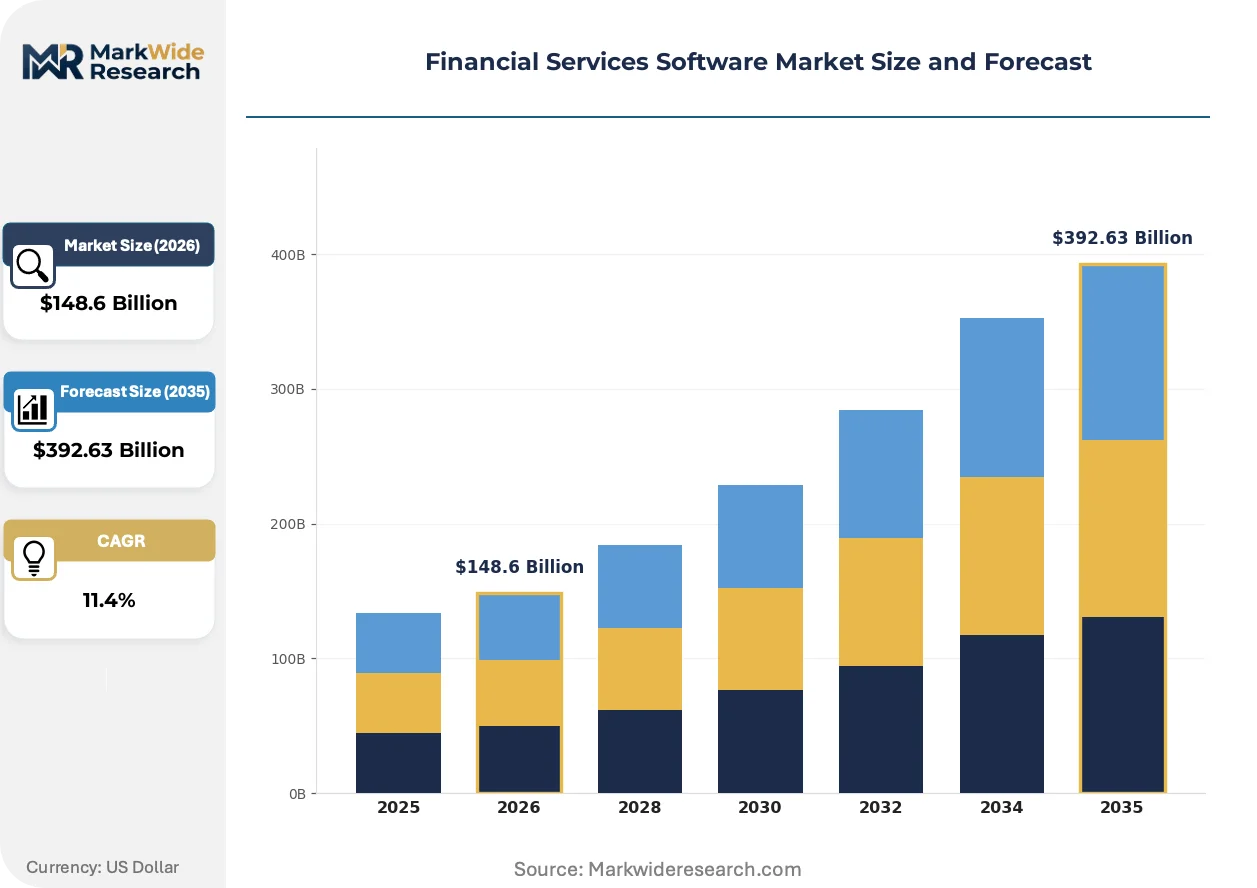
| Market Size in 2026 | $148.6 Billion |
| Market Size in 2035 | $392.63 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Accounting Software, Risk Management Solutions, Banking Software, Wealth Management Tools End User: Investment Firms, Commercial Banks, Insurance Companies, Payment Processors Deployment: On-Premises, Cloud-Based, Hybrid, SaaS Feature: Fraud Detection, Compliance Management, Portfolio Analytics, Automated Reporting |
| Companies Covered | Stripe, Mastercard, Finastra, PayPal, Visa, Fiserv, Adyen, Thought Machine, Temenos, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Financial Services Software Market Emerging Trajectories
Financial services software architecture is pivoting from monolithic legacy stacks toward modular, API-first platforms. This transformation reshapes competitive positioning around deployment flexibility and regulatory adaptability.
Embedded finance infrastructure is converging with carbon accounting workflows as EU Green Deal mandates force sustainability data into core financial systems. Neobanks and payment processors are adopting these integrated stacks fastest. This convergence is compressing procurement cycles for standalone ESG reporting tools.
The EU AI Act's prohibition on opaque credit-scoring models is forcing vendors to rebuild fraud detection modules with built-in explainability layers. Banks must demonstrate algorithmic decision trails to regulators. European institutions are responding by accelerating core banking replacement timelines.
Subscription-based platform licensing is displacing perpetual license models among mid-tier banks seeking predictable opex structures. Cloud-native vendors capture this shift with usage-based pricing. United States regional banks exhibit the fastest adoption of this procurement pattern.
Financial Services Software Market Segmentation
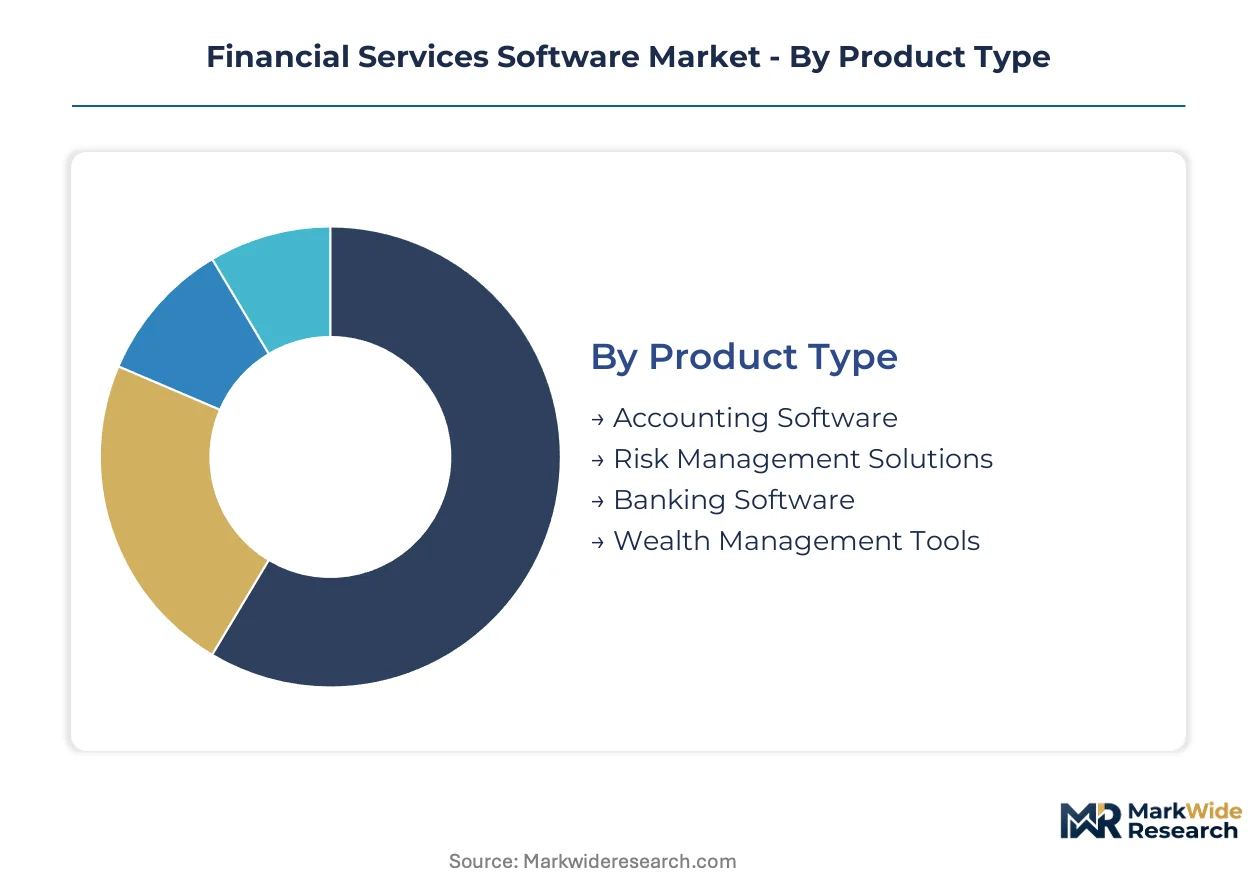
Financial services software procurement patterns diverge sharply across product architecture, end-user sophistication, and deployment topology. Vendors must align engineering roadmaps with distinct capital cycles and compliance burdens that characterize each segment cluster.
Product Type:
Capital intensity varies dramatically across product categories, with core banking infrastructure demanding the heaviest upfront investment in data center assets and regulatory certification.
- Banking Software:Core transaction processing engines and ledger management systems form the operational backbone of financial institutions. Commercial banks across the United States are replacing COBOL-based legacy stacks with modular architectures that accommodate real-time payment clearing requirements under tightening Basel III frameworks.
- Risk Management Solutions:Algorithmic engines quantify credit, market, and operational exposure through stochastic modeling and stress-testing protocols. Investment firms in major financial centers are retrofitting these modules with explainability layers to satisfy EU AI Act prohibitions on opaque credit-scoring models.
- Accounting Software:General ledger automation and financial consolidation tools streamline back-office operations. Mid-tier institutions favor subscription-based licensing for predictable operational expenditure structures.
- Wealth Management Tools:Portfolio construction and client advisory platforms serve high-net-worth segments. Neobanks are embedding these capabilities through API-first distribution models.
Banking software absorbs the bulk of installed capacity; risk management solutions are expanding most quickly.
End User:
Customer type determines procurement velocity, with regulated deposit-taking institutions moving slowest due to embedded infrastructure and security mandates.
- Commercial Banks:Full-service deposit and lending institutions with the most stringent regulatory oversight. Tier-one institutions in the United States maintain captive data-center assets to sustain compliance latency requirements for real-time payment clearing.
- Payment Processors:Transaction routing specialists requiring elastic capacity for volume spikes. These entities are adopting cloud-native deployment fastest to handle cross-border clearing modernization under ISO 20022 protocols.
- Investment Firms:Asset managers and broker-dealers seeking algorithmic audit trails. SEC climate disclosure rules are forcing emissions-linked risk weighting into portfolio analytics workflows.
- Insurance Companies:Risk-bearing institutions with actuarial modeling requirements. Solvency II and parallel capital frameworks drive demand for integrated compliance management modules.
Commercial banks command the deepest legacy replacement cycles; payment processors are climbing the fastest in new procurement volume.
Deployment:
Delivery topology shapes vendor margin structures and customer switching costs across the contract lifecycle.
- Cloud-Based:Fully managed infrastructure with elastic provisioning and usage-based pricing. Payment processors favor this model for transaction spike accommodation without stranded asset risk.
- SaaS:Application-layer subscriptions with vendor-managed updates and security patching. United States regional banks exhibit the fastest adoption of this procurement pattern for core banking functions.
- On-Premises:Customer-controlled hardware with bespoke security configurations. Tier-one commercial banks retain this topology for sensitive clearing operations despite higher capital expenditure burdens.
- Hybrid:Mixed topology balancing sensitive on-premises workloads with cloud elasticity for non-critical functions. Institutions face integration friction maintaining dual compliance postures.
On-premises systems retain dominance at large institutions; cloud-based deployment is gaining share fastest among mid-market entrants.
Feature:
Functional module demand correlates directly with regulatory enforcement timelines and supervisory priorities.
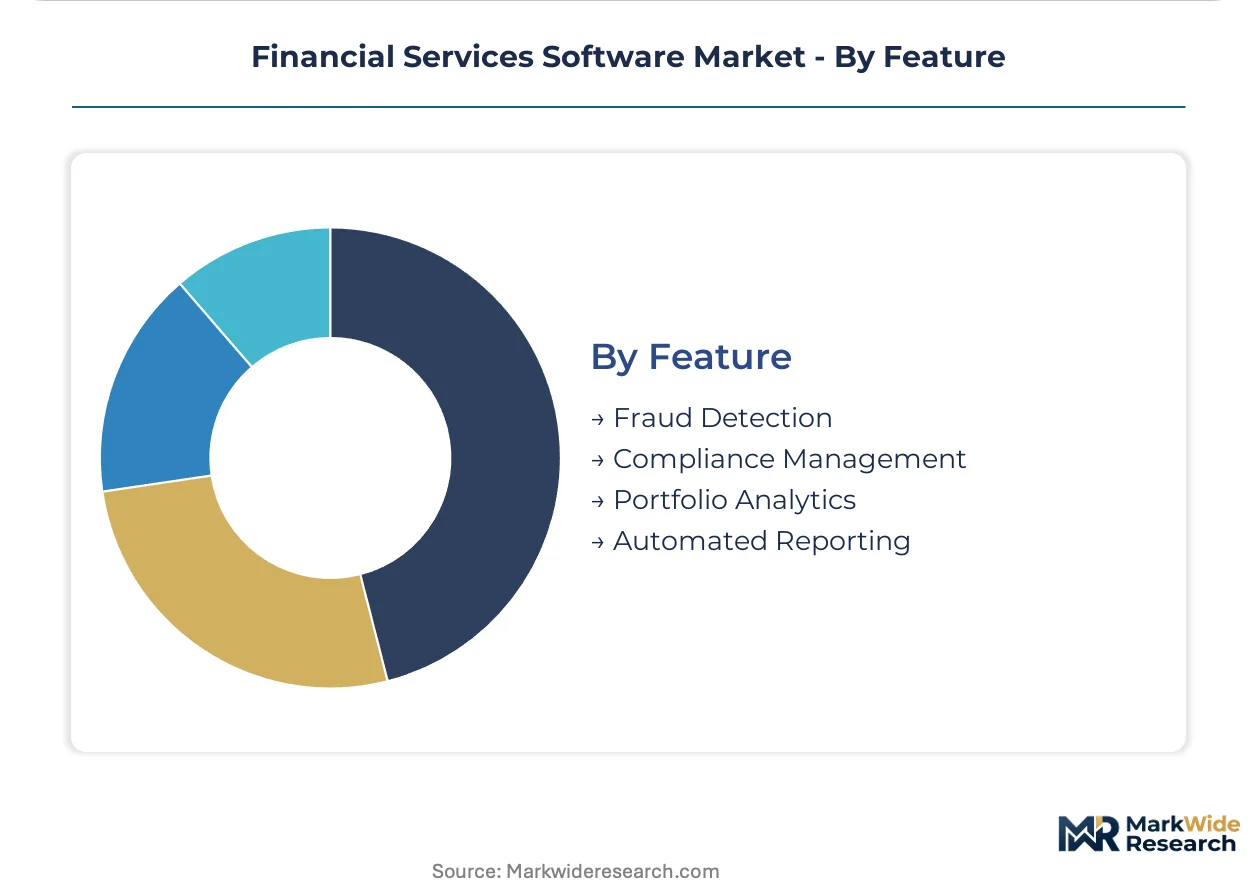
- Compliance Management:Automated regulatory reporting and audit trail generation. EU Green Deal mandates are forcing carbon accounting integration into core financial workflows across European banking.
- Fraud Detection:Real-time transaction monitoring with machine-learned anomaly detection. Vendors are rebuilding these modules with built-in explainability layers to demonstrate algorithmic decision trails to regulators.
- Portfolio Analytics:Investment performance attribution and risk decomposition tools. SEC climate disclosure alignment is driving demand for emissions-linked risk weighting capabilities.
- Automated Reporting:Standardized disclosure generation for regulatory and investor audiences. ISO 20022 protocol standardization is modernizing message formats for richer data exchange in cross-border clearing.
Compliance management commands the steepest expansion trajectory; fraud detection carries the heaviest re-engineering burden from explainability mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
New York City's financial district concentrates procurement decisions for core banking modernization across North American institutions. Commercial banks headquartered in Manhattan are replacing COBOL infrastructure with cloud-native platforms. This metropolitan concentration shapes vendor go-to-market strategies for the entire continent.
United States
Payment processors in Chicago and San Francisco are adopting elastic cloud infrastructure for ISO 20022 compliance. SEC climate disclosure rules force emissions-linked risk weighting into portfolio analytics. The Southeast regional banking corridor from Charlotte to Atlanta is accelerating SaaS procurement for predictable operational expenditure.
Germany
Frankfurt's banking cluster is retrofitting fraud detection modules with explainability layers under EU AI Act prohibitions. BaFin supervision mandates algorithmic audit trails for credit-scoring systems. Bavarian fintech hubs in Munich are embedding carbon accounting into core financial workflows for CSRD alignment.
United Kingdom
London's clearing banks are modernizing message formats for cross-border payment modernization. The Prudential Regulation Authority enforces Basel III capital requirements that tighten core banking replacement timelines. Edinburgh's wealth management centers are adopting API-first distribution models for high-net-worth advisory platforms.
Japan
Tokyo's megabanks maintain hybrid deployment topologies balancing on-premises security with cloud elasticity. METI guidelines promote real-time payment infrastructure investment. Osaka's regional banking associations are piloting modular core architectures to reduce stranded asset risk from captive data centers.
Singapore
Marina Bay financial institutions are deploying compliance management modules for ASEAN cross-border clearing integration. The Monetary Authority of Singapore mandates API-first infrastructure standards for digital banking licenses. Raffles Place payment processors are provisioning elastic capacity for transaction spikes without capital-intensive hardware.
Financial Services Software Market Vendor Landscape
Premium-margin players sit above commodity-margin players across deployment flexibility and regulatory adaptability. The vendor base stratifies into three tiers: legacy incumbents with captive data-center assets, cloud-native specialists with API-first architectures, and modular core banking disruptors. Consolidation pressure intensifies as tier-one banks demand end-to-end compliance integration. Dominant competitive moves include strategic partnerships for carbon accounting workflow embedding and technology licensing for explainable AI layers.
Within the cloud-native specialist tier, Stripe and Adyen exemplify API-first infrastructure positioning for neobank and payment processor segments. Temenos occupies a position representing modular core banking architecture that competes with monolithic legacy stacks. Fiserv anchors the incumbent tier through captive data-center assets sustaining compliance latency requirements for real-time clearing.
| Leading Market Players |
|---|
| Stripe |
| Mastercard |
| Finastra |
| PayPal |
| Visa |
| Fiserv |
| Adyen |
| Thought Machine |
| Temenos |
| Others |
Supply Flow & Price Mechanics
Captive data-center ownership among tier-one commercial banks anchors both supply security postures and pricing power in core banking infrastructure procurement. This vertical integration pattern forces cloud-native vendors to compete on elastic capacity economics rather than asset-heavy balance sheets.
Pricing Analysis
Outcome-based pricing tied to transaction throughput uptime anchors vendor revenue models in payment processing segments. Three-tier pricing structure across premium, standard, and economy levels stratifies by compliance certification grade and customization depth. Pricing pressure stems from subscription SaaS displacement of perpetual licenses among mid-tier institutions. Payment processors exhibit highest price sensitivity due to volume-scaled procurement; tier-one banks show lowest sensitivity given captive infrastructure switching costs.
Supply Chain Analysis
COBOL specialist workforce availability in the United States, Germany, and Japan constrains legacy system maintenance capacity. Engineering talent draws from aging domestic labor pools with limited pipeline replenishment. Supply chain risk centers on single-source vulnerability for critical compliance certification expertise. Distribution runs through direct enterprise sales teams and systems integrator partnerships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
COBOL talent scarcity props pricing for maintenance contracts across legacy infrastructure segments. This supply-constrained dynamic sustains vendor margins despite cloud-native competitive pressure.
For Market Incumbents: Extend modular architecture roadmaps to capture displacement demand from monolithic core banking stacks. Acquire explainable AI engineering capabilities to preempt EU AI Act compliance mandates. Defensive consolidation around carbon accounting workflow integration counters neobank API-first threats. For New Entrants and Emerging Players: Launch via embedded finance distribution models targeting regional banks in the United States Southeast corridor. White-space concentration sits in SaaS-tiered compliance management for mid-tier institutions. API-first carbon accounting integration represents the most penetrable feature wedge. For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisition by incumbent platform vendors seeking modular core banking capabilities. Long-term viability favors vendors with demonstrated Basel III certification traction. Watch EU AI Act enforcement timelines as inflection signal for explainability layer demand spikes.| Strategic Initiative | Industry Significance |
|---|---|
| Modular Core Banking Platform Launch | Enables real-time payment clearing compliance under tightening Basel III frameworks. |
| Explainable AI Layer Integration | Satisfies EU AI Act prohibitions on opaque credit-scoring model deployments. |
| Carbon Accounting Workflow Embedding | Aligns with EU Green Deal mandatory sustainability reporting requirements. |
| API-First Infrastructure Partnership | Captures neobank procurement velocity through embedded finance distribution. |
| ISO 20022 Protocol Modernization | Enables richer data exchange for cross-border payment clearing modernization. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs alongside primary interviews with bank CTOs, payment platform engineers, regulatory compliance officers, and systems integration specialists. SEC disclosure databases, BaFin supervision reports, ECB statistical releases, and ISO standardization committee records provided validation layers. Bottom-up transaction volume modeling and top-down macroeconomic triangulation converged on segment-level estimates.
Granularity-level modeling deployed deployment topology, institution size tier, vertical segment, and regional regulatory cluster as core dimensions across the analysis window. CAGRs derived from fitted growth curves applied to baseline transaction volume data. Forecast inputs incorporated Basel III implementation timelines, EU AI Act enforcement phases, and ISO 20022 migration schedules without year-specific anchoring.
Regulatory timetable divergence, COBOL workforce attrition rates, and cloud migration acceleration are the dominant revision risks to modeled outputs. Forecasts reflect documented assumptions about compliance cost pass-through and substitution elasticity. A small set of named triggers warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Financial Services
Middle East Financial Consulting Software Market
Financial Services
Global Management Consulting Services Market
Financial Services
Online Lottery Market
Financial Services
Currency Exchange Software Market
Financial Services
Financial Advisory Services Market
Financial Services
Back-Office Outsourcing in Financial Services Market
Financial Services
White Glove Services Market
Financial Services
Europe E-Invoicing Market
Financial Services
Global Alternative Data Market
Financial Services
Treasury Management Market
Financial Services
Virtual Account Management Software Market
Financial Services
Online Investment Platform Market
Financial Services
Currency Exchange Bureau Software Market
Financial Services
E-Brokerage Market
Financial Services
Global Treasury Management System (TMS) Market
Financial Services
Global Business Management Consulting Service Market