
 North America AI in Fintech Market | 2026-2036
North America AI in Fintech Market Size, Share, and Industry Trends Forecast 2026-2036
North America AI in Fintech Market Analytics
Revenue-based software licensing is tilting competitive dynamics toward capital-efficient entrants. JPMorgan Chase leverages its proprietary data infrastructure to dominate enterprise-grade fraud detection. Microsoft Corporation anchors cloud-based AI delivery for mid-tier payment processors. Goldman Sachs differentiates through in-house quantitative research platforms that compete directly with vendor solutions.
North America AI in Fintech encompasses machine learning models, natural language processing engines, robotic process automation tools, and computer vision systems deployed to automate financial decision-making, detect anomalous transactions, and personalize customer interactions at scale. Algorithmic trading applications currently command the largest deployment budgets, while fraud detection systems exhibit the fastest implementation velocity among regional banks. Natural language processing for customer service automation sits at a more mature adoption curve, with margin pools shifting toward integration and maintenance services as initial deployments age.
The SEC, FINRA, and OCC collectively shape market access through disclosure requirements for AI-driven advisory tools and model risk management standards. Canadian regulators under OSFI impose parallel expectations on AI governance for federally chartered institutions. Stakeholders must monitor evolving supervisory guidance on algorithmic accountability to align product roadmaps with enforcement priorities.
Market Dynamics
Algorithmic trading desks at Canadian investment firms are expanding their AI procurement budgets, while the SEC's enforcement actions on AI-driven investment advice tighten compliance requirements across the continent. This regulatory pressure is concentrating demand in New York's fintech corridor and Toronto's financial district.
Growth Catalysts
- SEC disclosure mandates:The SEC's enforcement actions on AI-driven advisory tools force institutions to upgrade governance infrastructure, creating sustained procurement cycles for compliance-enabling platforms.
- Algorithmic trading expansion:Canadian investment firms are scaling machine learning deployment for execution optimization, driving hardware and model-serving demand.
- Fraud detection velocity:Regional banks prioritize anomalous transaction detection, accelerating implementation timelines for supervised learning pipelines.
Market Restraints
- Model risk management costs:FINRA and OCC standards require extensive documentation and validation, inflating deployment timelines for mid-tier institutions.
- Cloud concentration risk:Microsoft Corporation anchors cloud-based AI delivery, creating dependency on a limited supplier base for mid-tier payment processors.
- Explainability limitations:Deep learning architectures face supervisory scrutiny for opaque decision pathways, restricting deployment in credit adjudication.
Strategic Opportunities
- OSFI governance alignment:Canadian federally chartered institutions face parallel AI accountability expectations, opening vendor opportunities for cross-border compliance platforms.
- Integration services white space:Natural language processing deployments for customer service automation are aging, shifting margin pools toward maintenance and upgrade contracts.
- Quantitative research convergence:Goldman Sachs-style in-house platforms compete with vendor solutions, creating partnership openings for specialized model providers.
Industry Challenges
- Quantitative talent scarcity:Investment banks and fintech vendors compete for machine learning engineers with financial domain expertise, compressing hiring cycles.
- Legacy core integration:Mainframe-dependent regional banks face friction connecting modern AI inference engines to decades-old transaction processing systems.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America AI in Fintech Market |
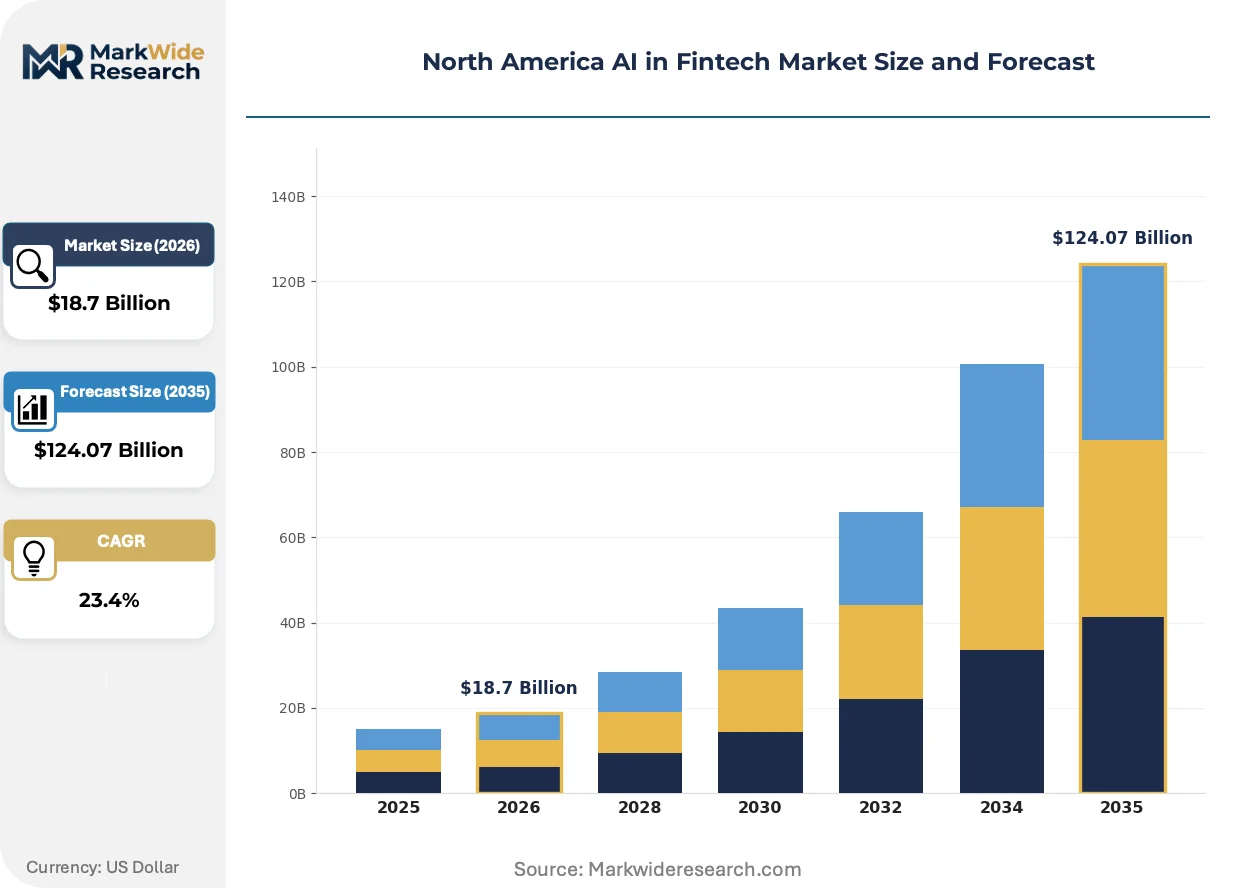
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $124.07 Billion |
| CAGR (2026 – 2036) | 23.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Technology: Machine Learning, Natural Language Processing, Robotic Process Automation, Computer Vision Application: Fraud Detection, Risk Management, Customer Service, Algorithmic Trading End User: Banks, Insurance Companies, Investment Firms, Payment Processors Service Type: Consulting, Implementation, Maintenance, Support |
| Companies Covered | JPMorgan Chase, Goldman Sachs, Bank of America, Wells Fargo, Morgan Stanley, Amazon Web Services, Microsoft Corporation, International Business Machines Corporation, Intel Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America AI in Fintech Market Evolving Landscape
Revenue-based software licensing is tilting competitive dynamics toward capital-efficient entrants, while proprietary data infrastructure separates dominant players from challengers. Three developments are actively restructuring how AI capabilities reach financial institutions.
Generative adversarial networks for synthetic data generation are enabling model training without exposing sensitive customer records. Mid-tier payment processors are adopting these tools aggressively to close the data gap with JPMorgan Chase-scale repositories. This capability is digitizing compliance workflows by automating documentation and audit trail generation.
FINRA's guidance on algorithmic accountability is tightening disclosure requirements for model logic and training data provenance. The industrial consequence is a procurement preference for platforms with built-in explainability dashboards and automated governance documentation. Broker-dealers in New York's fintech corridor are responding by retrofitting existing deployments or selecting vendors with native compliance architectures.
Enterprise buyers are unbundling after-sales service from initial software licenses, treating model retraining and drift monitoring as separate procurement categories. This pattern is displacing traditional perpetual-license vendors who bundled maintenance. The shift is most visible among Toronto's financial district institutions negotiating multi-year AI service contracts with outcome-linked fee structures.
North America AI in Fintech Market Segmentation
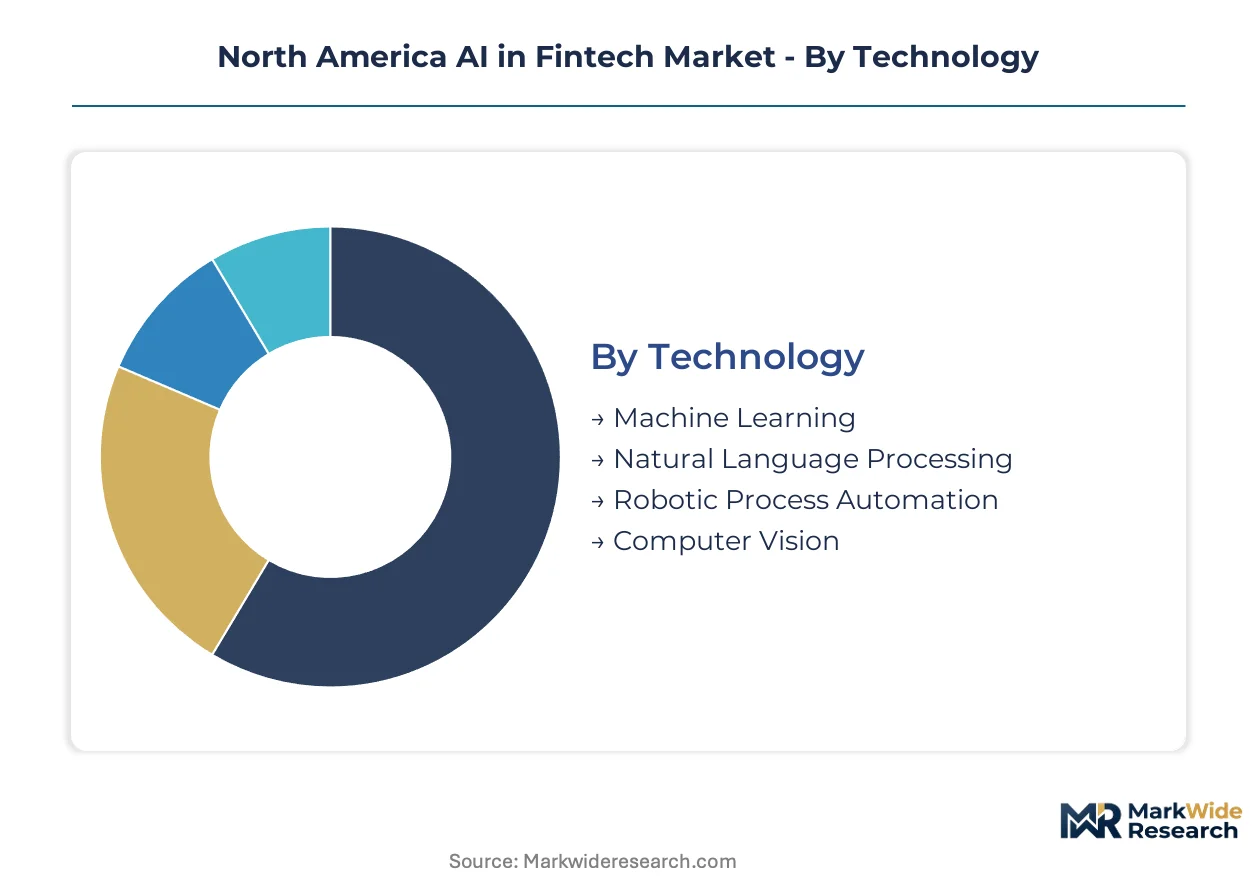
North American financial institutions unbundle AI procurement into discrete technology, application, and service layers. This modular purchasing pattern lets buyers mix vendor solutions with in-house development across fraud detection, trading, and customer engagement workflows.
Technology:
After-sales service intensity varies sharply across these four technology clusters, with machine learning platforms demanding continuous model retraining contracts.
- Machine Learning:Supervised and unsupervised learning architectures power predictive analytics for credit scoring and transaction monitoring. Demand concentrates among New York-based investment banks seeking execution optimization, driven by FINRA's model risk documentation requirements.
- Natural Language Processing:Text and speech analytics automate customer service interactions and regulatory filing extraction. Toronto's financial district institutions are retrofitting aging deployments with explainability dashboards to satisfy OSFI governance expectations.
- Robotic Process Automation:Software bots handle repetitive back-office tasks in reconciliation and compliance reporting. Mid-tier payment processors in Chicago and Montreal deploy these tools to reduce manual processing costs.
- Computer Vision:Image recognition systems verify identity documents and detect check fraud. Regional banks in Texas and Florida prioritize this technology for branch-based customer onboarding.
Machine Learning holds the largest share; momentum sits with Natural Language Processing as compliance documentation automation expands.
Application:
Cost tier stratification separates enterprise-grade algorithmic trading from mass-market fraud detection implementations.
- Fraud Detection:Real-time transaction monitoring identifies anomalous patterns using behavioral biometrics and network analysis. Regional banks across the US Southeast accelerate deployment timelines due to supervisory pressure on cyber resilience.
- Algorithmic Trading:Execution algorithms optimize order routing and market timing across equity and fixed-income markets. Canadian investment firms in Calgary and Vancouver expand procurement budgets for hardware-accelerated inference.
- Risk Management:Credit and market risk models stress-test portfolio exposures under regulatory scenarios. Insurance companies in Hartford and Boston prioritize these tools for Solvency II and NAIC alignment.
- Customer Service:Conversational AI and sentiment analysis personalize digital banking interactions. Credit unions in the Pacific Northwest adopt these solutions to compete with national bank digital channels.
Fraud Detection commands the largest deployment base; Algorithmic Trading shows the steepest expansion trajectory as Canadian firms scale ML budgets.
End User:
Customer type determines procurement sophistication, with investment firms leading on quantitative model development and banks dominating integration spending.
- Banks:Retail and commercial banks deploy AI across lending, payments, and branch operations. JPMorgan Chase-scale institutions leverage proprietary data infrastructure; regional players depend on cloud-based vendor platforms.
- Investment Firms:Asset managers and broker-dealers apply machine learning to alpha generation and execution cost reduction. New York's fintech corridor concentrates quantitative talent and model-serving infrastructure investment.
- Insurance Companies:Underwriters and claims processors use predictive models for pricing automation and fraud identification. Hartford and Bermuda-based carriers lead North American adoption.
- Payment Processors:Card networks and merchant acquirers prioritize real-time authorization decisioning. Mid-tier processors face cloud concentration risk with limited supplier alternatives.
Banks represent the largest addressable base; Investment Firms gain share fastest as algorithmic trading budgets expand.
Service Type:
Margin pools are shifting from implementation toward maintenance and model governance as initial deployments mature.
- Consulting:Strategy and architecture advisory helps institutions navigate vendor selection and regulatory alignment. Toronto institutions increasingly demand cross-border compliance expertise covering OSFI and SEC requirements.
- Implementation:System integration and deployment services connect AI engines to legacy core banking platforms. Regional banks face friction integrating modern inference tools with decades-old mainframe systems.
- Maintenance:Ongoing model monitoring, drift detection, and retraining contracts generate recurring revenue. Enterprise buyers unbundle these services from initial licenses, creating outcome-linked fee structures.
- Support:Technical assistance and troubleshooting for production AI systems. Natural language processing deployments for customer service automation drive expanding support contract volumes.
Implementation holds the largest current share; Maintenance captures expanding margin pools as model governance requirements tighten.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
SEC disclosure mandates and OSFI governance expectations are redirecting procurement toward compliance-enabling platforms across North American financial centers. Canadian investment firms are scaling algorithmic trading infrastructure while US regulators tighten model risk documentation requirements.
United States
New York's fintech corridor concentrates quantitative talent and model-serving infrastructure investment. The SEC's enforcement actions on AI-driven advisory tools force broker-dealers to upgrade governance frameworks. JPMorgan Chase leverages proprietary data infrastructure to dominate enterprise-grade fraud detection deployments.
Canada
Algorithmic trading desks in Calgary and Vancouver are expanding machine learning procurement budgets for execution optimization. OSFI imposes parallel AI governance expectations on federally chartered institutions. Toronto's financial district institutions negotiate multi-year AI service contracts with outcome-linked fee structures.
Mexico
Payment processors in Mexico City prioritize real-time authorization decisioning systems. The country's national banking regulator applies international standards on model risk management to foreign bank subsidiaries. Guadalajara's technology corridor attracts fintech vendors serving cross-border payment automation.
North America AI in Fintech Market Competitive Landscape
On the supply side, the industry is bifurcated between proprietary in-house platforms and cloud-based vendor solutions. Large financial institutions develop captive AI capabilities while mid-tier players depend on external providers. Two strategic archetypes dominate: data-rich incumbents with proprietary infrastructure and capital-efficient vendors with revenue-based licensing models. Competitive moves center on M&A for quantitative talent acquisition and strategic partnerships for legacy core integration.
Within the data-rich incumbent tier, JPMorgan Chase and Goldman Sachs exemplify institutions competing directly with vendor solutions through in-house quantitative research platforms. Microsoft Corporation anchors cloud-based AI delivery for mid-tier payment processors, representing the vendor archetype that capitalizes on unbundled procurement patterns. These three players occupy distinct competitive positions—proprietary infrastructure dominance, quantitative research convergence, and cloud-based scale delivery—without overlapping strategic territory.
| Leading Market Players |
|---|
| JPMorgan Chase |
| Goldman Sachs |
| Bank of America |
| Wells Fargo |
| Morgan Stanley |
| Amazon Web Services |
| Microsoft Corporation |
| International Business Machines Corporation |
| Intel Corporation |
| Others |
Value Network & Pricing Analysis
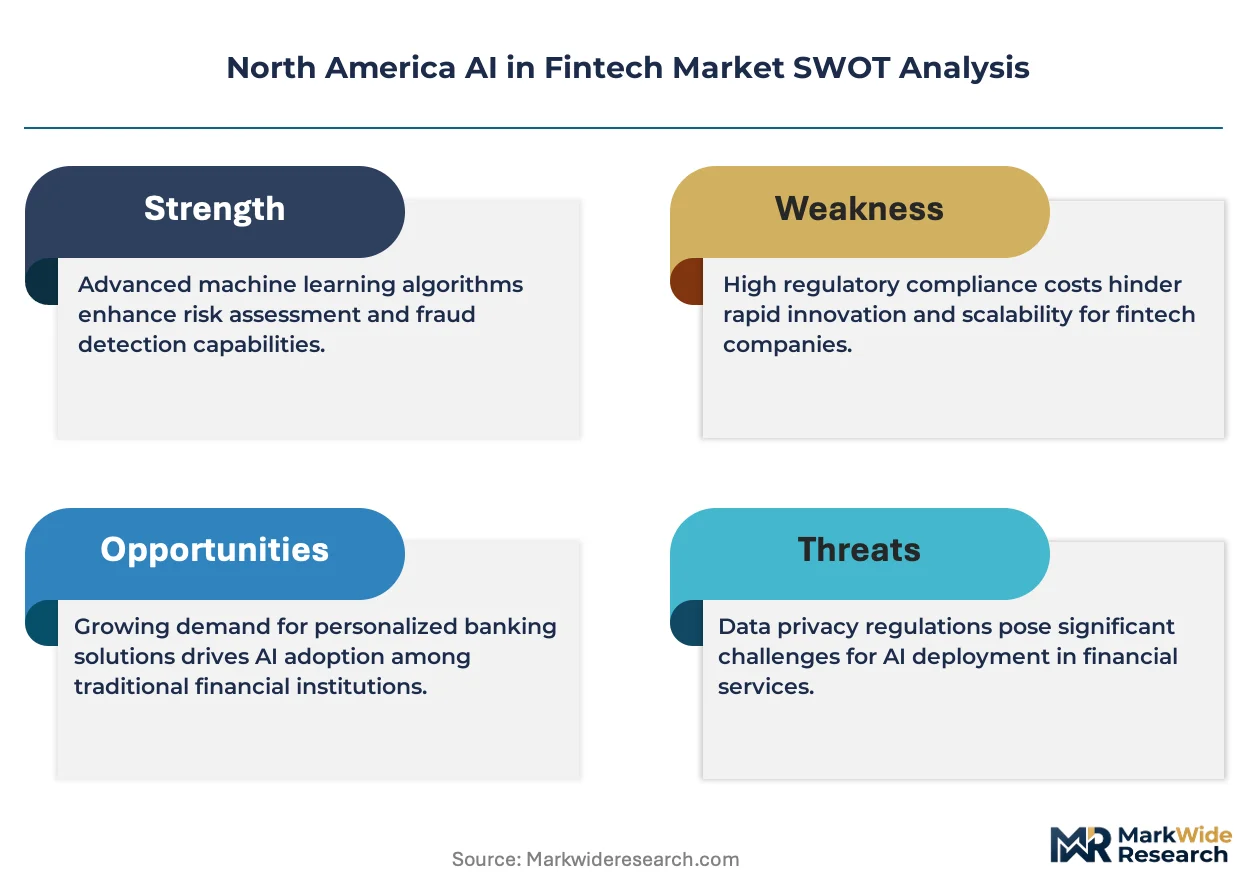
Single-source dependency on NVIDIA GPU clusters for model training infrastructure determines both pricing tier spreads and supply chain shape in North American AI fintech deployment. Cloud concentration risk with Microsoft Azure and Amazon Web Services creates procurement chokepoints that inflate enterprise-grade service contracts while compressing margins for mid-tier payment processors forced into standardized SaaS tiers.
Pricing Analysis
Certification level for model explainability and audit trail documentation creates the primary spread between premium and standard deployment tiers. Revenue-based software licensing dominates, with FINRA-compliant governance platforms commanding substantial premiums over basic fraud detection APIs. Price differentiation stems from vertical integration depth and after-sales service bundling, with JPMorgan Chase-scale proprietary infrastructure insulating against cost compression while regional banks face pricing pressure from cloud vendor concentration. Investment firms show least price sensitivity due to alpha-generation ROI justification; credit unions exhibit highest sensitivity, prioritizing per-transaction pricing over fixed licensing.
Supply Chain Analysis
TSMC foundry capacity in Taiwan and Intel manufacturing in Arizona and Oregon anchors GPU and specialized AI accelerator supply for fintech model training workloads. The hardware layer draws from South Korean HBM memory suppliers and Japanese precision component manufacturers, while software dependencies center on open-source ML frameworks and proprietary cloud APIs. Single-source vulnerability concentrates in NVIDIA data center GPU allocation, with tariff exposure on Chinese-manufactured networking equipment amplifying total cost of ownership. Distribution runs through hyperscaler marketplaces and direct enterprise sales teams, with Canadian institutions increasingly demanding cross-border data residency compliance as a procurement threshold.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Quantitative talent scarcity with financial domain expertise constrains scaling velocity across algorithmic trading and risk model development pipelines, forcing strategic choices around build-versus-buy for machine learning capabilities.
For Market Incumbents: Pre-empt cloud vendor lock-in by diversifying across at least two hyperscaler relationships while building captive model-serving infrastructure for latency-sensitive trading applications. Invest in OSFI-SEC cross-border compliance certification to capture Toronto-New York corridor procurement cycles before specialized vendors establish regulatory arbitrage positions. For New Entrants and Emerging Players: Mexico City payment processor automation represents the most penetrable geographic white space, with real-time authorization decisioning systems underserved by incumbent AI vendors. Target mid-tier processors with hybrid deployment models combining edge inference for latency and cloud fallback for compliance documentation, using outcome-linked fee structures to bypass capital-intensive upfront licensing competition. For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors specialized model providers with proven FINRA explainability architectures over generalist AI platforms. Long-term viability hinges on regulatory technology moats rather than raw algorithmic performance, with acquisition priority on firms holding active SEC no-action letters or OSFI supervisory guidance alignment. Watch for inflection in model drift monitoring contract volumes as initial NLP deployments age and governance requirements tighten.| Strategic Initiative | Industry Significance |
|---|---|
| Proprietary Data Infrastructure Investment | JPMorgan Chase-scale repositories create sustainable fraud detection advantages against cloud-dependent competitors. |
| Cross-Border Compliance Platform Development | Dual SEC-OSFI alignment opens Toronto-New York corridor procurement with unified governance documentation. |
| Synthetic Data Generation Capability | GAN-based training tools close data gaps for mid-tier processors without customer record exposure risks. |
| Model Explainability Dashboard Integration | Native compliance architectures satisfy FINRA algorithmic accountability guidance without retrofit friction. |
| Outcome-Linked Service Contract Structuring | Unbundled maintenance procurement captures expanding margin pools as initial deployments mature. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with quantitative research heads at investment firms, AI procurement officers at regional banks, cloud platform engineers, and regulatory technology vendors. Secondary validation drew from SEC enforcement action filings, OSFI supervisory guidance documents, FINRA model risk management bulletins, and hyperscaler AI service revenue disclosures. Bottom-up deployment sizing across algorithmic trading, fraud detection, and customer service automation segments was triangulated against top-down cloud infrastructure capex allocation patterns.
Calibration across the projection horizon employed scenario-weighted CAGRs derived from regulatory enforcement intensity, cloud concentration risk premiums, and talent scarcity indices. Segmentation dimensions modeled include technology cluster, application workflow, end-user institution type, and service layer unbundling pattern. Forecast inputs incorporated hardware accelerator supply constraints, model retraining frequency benchmarks, and compliance documentation automation penetration curves.
The forecast holds incumbent behavior within observed patterns; aggressive moves by capital-efficient entrants with revenue-based licensing or hyperscaler vertical integration into financial services would shift outcomes substantially. Quarterly review of SEC enforcement action frequency, OSFI guidance publication cadence, and GPU cluster allocation pricing is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
FinTech
Smart Financial Solutions Market
FinTech
Financial Fraud Detection Software Market
FinTech
North America Fintech Cloud Market
FinTech
India AI in Fintech Market
FinTech
Embedded Finance Market
FinTech
Global Fundraising Software Market
FinTech
Financial Cloud Market
FinTech
Asia-Pacific Financial Analytics Market
FinTech
Singapore AI in Fintech Market
FinTech
Financial Services Cloud Market
FinTech
Europe Financial Analytics Market
FinTech
Fintech Cloud Market
FinTech
Canada AI in Fintech Market
FinTech
Stock Trading App Market
FinTech
Financial Technology Fintech Market
FinTech
Saudi Arabia Fintech Market