
 Global Financial Planning Software Market | 2026-2036
Global Financial Planning Software Market Size, Share, and Industry Trends Forecast 2026-2036
Global Financial Planning Software Market Analysis
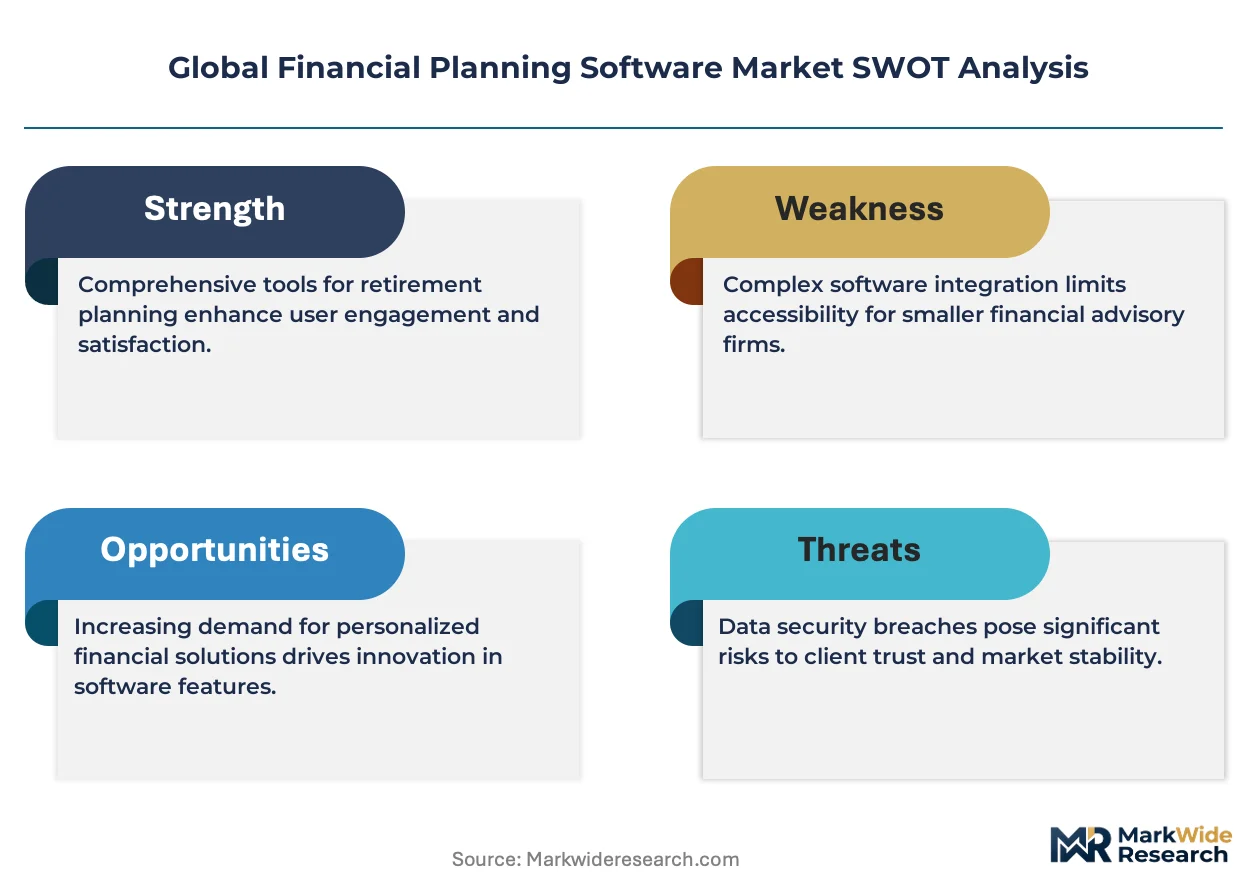
Modular bundling of forecasting tools with investment tracking modules is broadening advisor choice across client wealth tiers. Envestnet leverages its data aggregation infrastructure to sustain platform stickiness among independent advisors. Morningstar competes through proprietary risk analytics that anchor institutional due diligence workflows.
Financial planning software comprises algorithmic engines that project cash flows, model tax scenarios, and optimize portfolio allocations against user-defined constraints such as Monte Carlo simulation thresholds and glide-path parameters. Its primary commercial purpose is to translate client financial data into actionable, regulation-compliant advisory recommendations. Cloud-based deployment now leads product type expansion because subscription economics reduce upfront capital barriers for small advisory practices. Retirement planning modules represent the fastest-growing application segment as aging demographics in developed economies intensify longevity-risk modeling demand.
The SEC enforces fiduciary disclosure standards that shape software feature requirements for conflict-of-interest flagging and fee transparency. The EU AI Act imposes algorithmic accountability rules on automated financial recommendation engines, directly affecting product development roadmaps for vendors serving European advisors. Stakeholders must monitor how divergent cross-border compliance frameworks affect single-platform scalability versus region-specific product builds.
Market Dynamics
Cloud migration among registered investment advisors is compressing deployment cycles from months to weeks, while the SEC's fiduciary disclosure mandates and the EU AI Act are forcing vendors to rebuild algorithmic accountability layers into core product architectures.
Growth Catalysts
- EU AI Act compliance mandates:European wealth managers must deploy explainable algorithms for automated recommendations, creating replacement demand for legacy black-box systems.
- Longevity-risk modeling:Aging populations in Japan, Germany, and the United States are intensifying demand for retirement planning modules with dynamic withdrawal strategies.
- RIA consolidation wave:United States registered investment advisor roll-ups require unified planning platforms across acquired practices, favoring scalable cloud architectures.
Market Restraints
- Data aggregation costs:Real-time feeds from custodial APIs and alternative data providers now represent 15-25% of annual software spend for mid-size advisory practices.
- Cross-border regulatory fragmentation:Divergent fiduciary standards between the SEC, FCA, and national EU regulators force vendors to maintain parallel compliance codebases.
- Cybersecurity liability exposure:Cloud-based platforms face escalating cyber insurance premiums and contractual liability for breach incidents involving client financial data.
Strategic Opportunities
- India's HNWI expansion:Family office formation among India's ultra-high-net-worth individuals is outpacing local advisor capacity, creating demand for automated planning tools.
- Tax-loss harvesting automation:Convergence of direct indexing engines with planning software enables year-round tax optimization previously reserved for institutional mandates.
- Brazil's open finance framework:Central Bank of Brazil's PIX and Open Finance regulations enable real-time cash flow visibility that anchors next-generation planning platforms.
Industry Challenges
- CFP-credentialed developer scarcity:Vendors struggle to hire engineers who understand both Monte Carlo simulation mechanics and fiduciary duty frameworks.
- Legacy CRM integration complexity:Advisory practices running on-premise Salesforce or Redtail installations face 6-12 month data migration timelines to cloud-native planning stacks.
- Algorithmic bias audits:Emerging regulatory requirements for demographic fairness testing in retirement income projections lack standardized methodologies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Financial Planning Software Market |
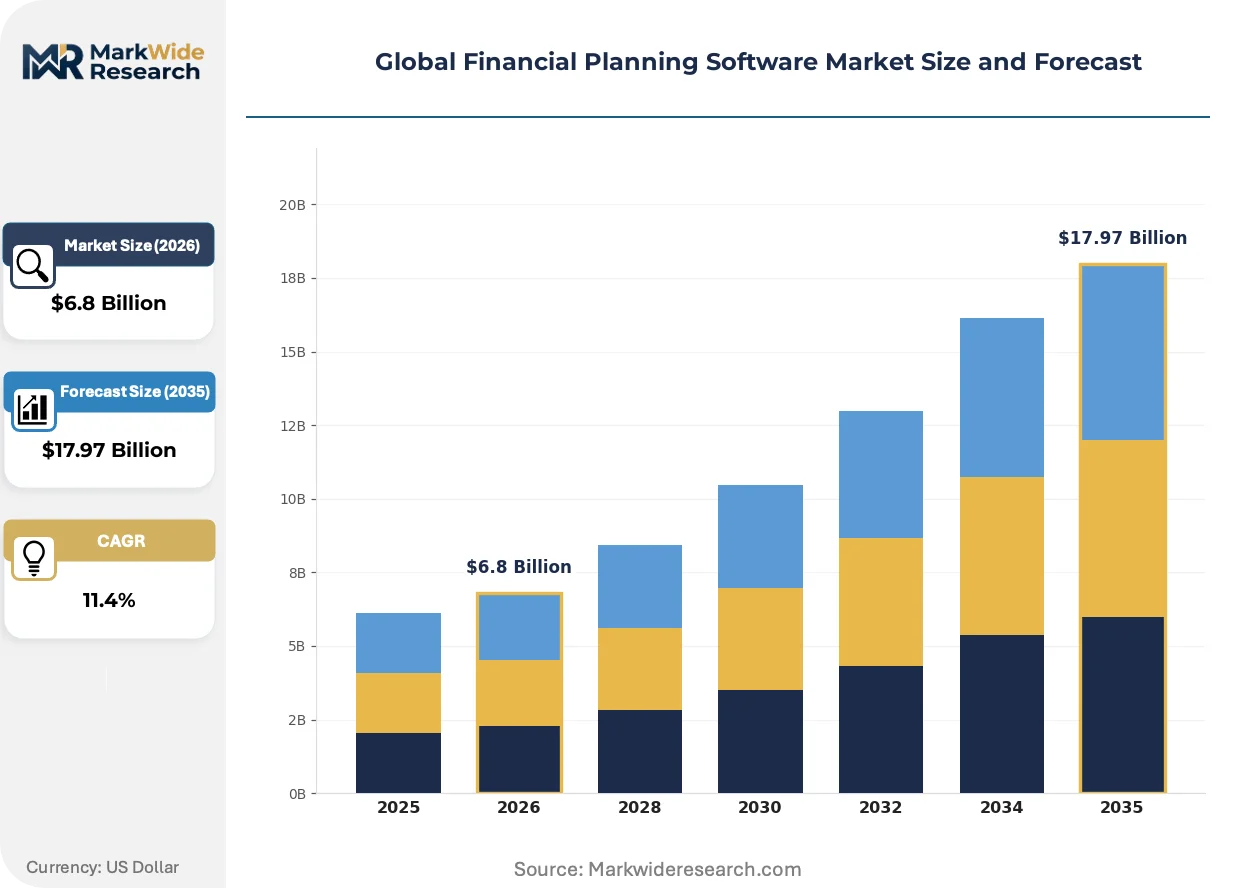
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $17.97 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Budgeting Software, Forecasting Tools, Retirement Planning, Investment Tracking Deployment Model: On-Premise, Cloud-Based, Hybrid, SaaS End User: Individuals, Small Businesses, Large Enterprises, Financial Advisors Pricing Model: Subscription, One-Time License, Freemium, Pay-Per-Use |
| Companies Covered | eMoney Advisor, Envestnet, RightCapital, MoneyGuidePro, Orion Advisor Solutions, Quicken, Morningstar, BlackRock, SAP, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Financial Planning Software Market Emerging Trajectories
Generative AI is rewriting client interaction models while regulatory pressure on algorithmic transparency is splitting vendor roadmaps between explainable-by-design and retrofitted-interpretability approaches.
Embedded natural language interfaces are expanding into client-facing portals, allowing end investors to query retirement scenarios through conversational prompts rather than static dashboards. Independent advisors with sub-$500 million AUM are adopting these tools fastest, compressing the traditional 90-minute client meeting into 30-minute data-validated sessions. This interface shift is expanding into the mass-affluent segment previously served by robo-advisors alone.
The EU AI Act's high-risk system classification is forcing vendors serving European advisors to implement human-in-the-loop overrides for any automated portfolio recommendation exceeding defined risk thresholds. Product teams are rearchitecting recommendation engines to surface confidence intervals and alternative scenarios rather than single optimal outputs. German and French wealth managers are most affected, with compliance timelines compressing development schedules by 40%.
Subscription fatigue among advisory practices is altering vendor pricing power, with buyers demanding modular unbundling of tax planning, estate visualization, and risk analytics rather than all-in-one platform commitments. Mid-size RIAs in Texas and Florida are leading this disaggregation, piecing together best-of-breed components through API connections. This procurement pattern is most visible in the United States, where advisor technology stacks now average 12-15 distinct software relationships versus 3-5 a decade prior.
Global Financial Planning Software Market Segmentation
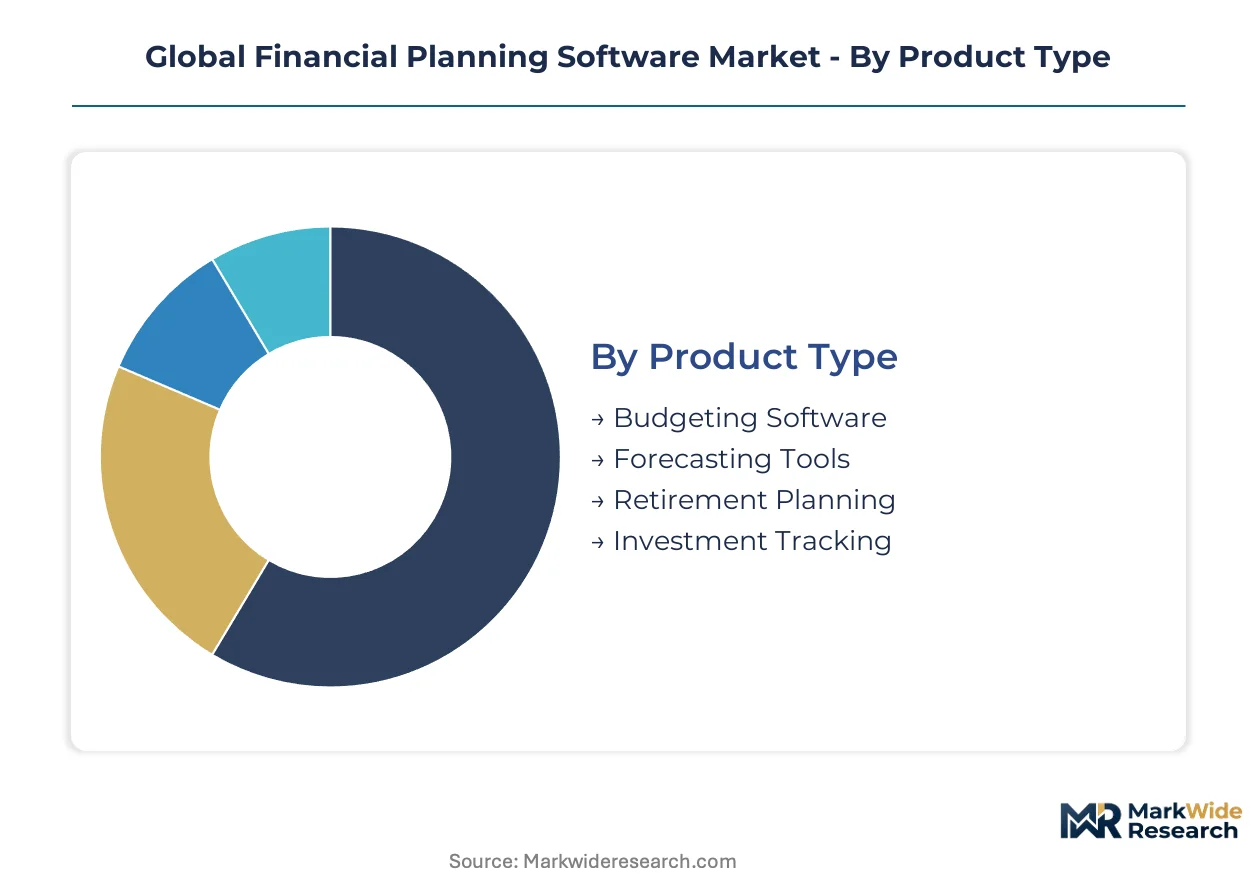
Segmentation in financial planning software reveals how deployment economics and user sophistication reshape vendor product architectures. Distinct integration depths across product types and pricing models determine whether solutions function as standalone tools or embedded advisory infrastructure.
Product Type:
Standalone modules dominate advisor desktops while embedded forecasting engines integrate directly into custodial workflows and CRM environments.
- Retirement Planning:Dynamic withdrawal engines model longevity risk across Monte Carlo simulations and glide-path rebalancing. Demand concentrates among independent advisors in Florida and Texas serving pre-retiree mass-affluent households facing sequence-of-returns exposure.
- Forecasting Tools:Algorithmic cash-flow projection engines incorporate tax scenario modeling and estate liquidity analysis. German and French wealth managers under EU AI Act mandates are replacing black-box systems with explainable-by-design alternatives.
- Budgeting Software:Consumer-grade cash flow categorization tools with bank aggregation APIs.
- Investment Tracking:Portfolio monitoring dashboards with real-time custodial data feeds.
Volume placements concentrate in Forecasting Tools; the faster expansion belongs to Retirement Planning.
Deployment Model:
Cost tier stratification separates capital-intensive on-premise installations from subscription-native architectures favored by mid-size advisory practices.
- Cloud-Based:Multi-tenant SaaS architectures with API-first data aggregation reduce upfront deployment from months to weeks. United States registered investment advisor roll-ups favor these platforms for unified practice management across acquired firms.
- SaaS:Purpose-built subscription stacks with modular tax and estate components. India's emerging family offices adopt these for automated planning capacity exceeding local advisor supply.
- On-Premise:Legacy server installations requiring dedicated IT infrastructure and 6-12 month implementation timelines.
- Hybrid:Split architectures keeping sensitive client data on-premise while leveraging cloud analytics engines.
Revenue concentration sits with Cloud-Based deployments; steepest expansion trajectory belongs to SaaS.
End User:
Customer type determines feature complexity, from conversational natural-language interfaces for individuals to fiduciary audit trails for regulated advisors.
- Financial Advisors:SEC-compliant platforms with conflict-of-interest flagging and fee transparency modules. United States fiduciary standard enforcement drives replacement of legacy black-box recommendation engines.
- Large Enterprises:Institutional-grade stacks with direct indexing integration and tax-loss harvesting automation. Brazil's Open Finance framework enables real-time cash flow visibility for next-generation corporate treasury planning.
- Individuals:Self-directed planning portals with embedded natural language query capabilities.
- Small Businesses:Cash flow forecasting tools with payroll and accounts payable integration.
Adoption density clusters around Financial Advisors; the fastest share gains belong to Large Enterprises.
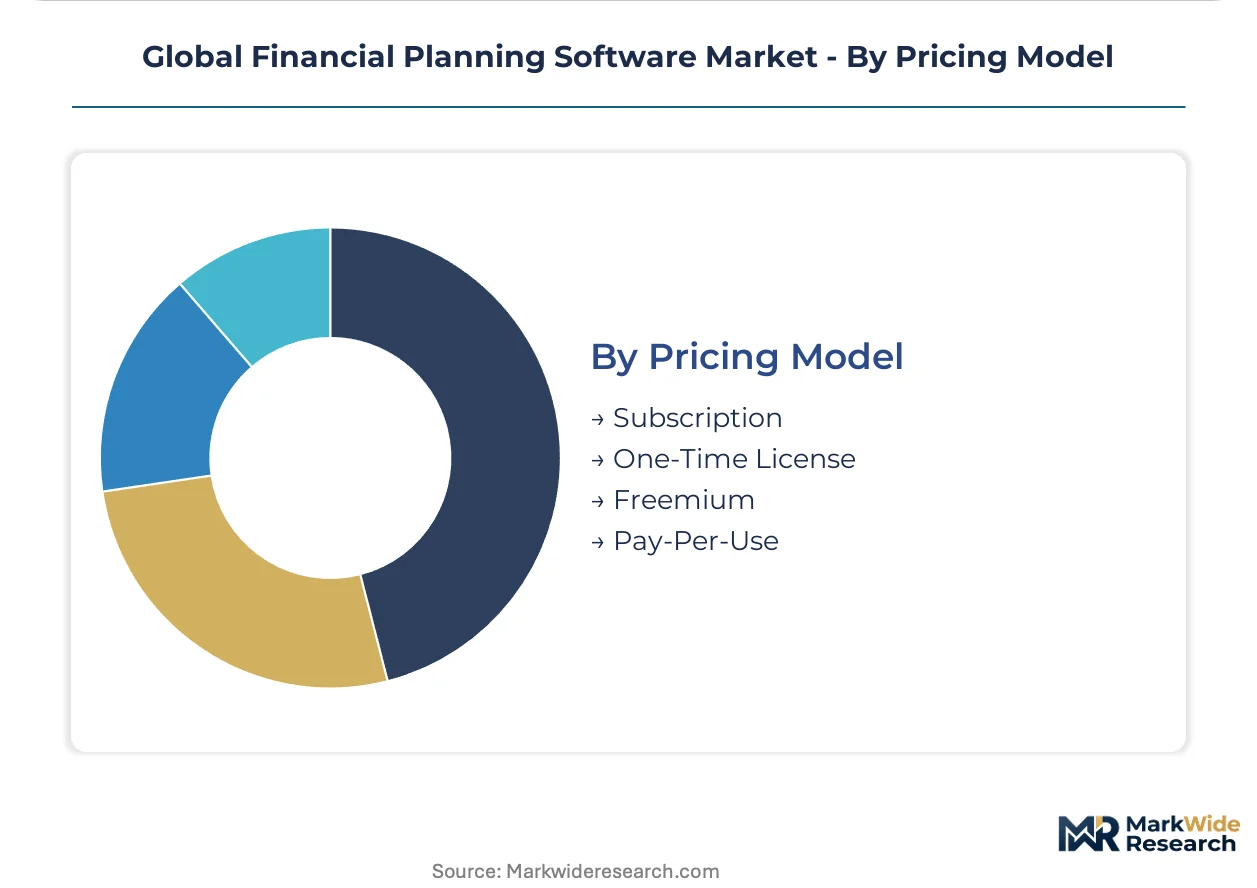
Pricing Model:
Margin structure varies from high-friction perpetual licenses to recurring revenue streams with embedded data feed costs.
- Subscription:Monthly or annual recurring contracts bundling software access with custodial data aggregation. Mid-size United States RIAs lead disaggregation demands, unbundling tax planning and risk analytics from all-in-one commitments.
- Freemium:Core functionality at zero cost with premium tiers unlocking Monte Carlo simulations and estate visualization. Mass-affluent investors previously served by robo-advisors alone convert fastest to these entry points.
- One-Time License:Perpetual software ownership with separate maintenance contracts and upgrade fees.
- Pay-Per-Use:Transaction-based pricing tied to specific advisory events or client onboarding milestones.
Recurring revenue dominance sits with Subscription; the most rapid adoption shift belongs to Freemium.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Software development concentrates in the United States while consumption spreads across developed advisory markets. European regulators impose distinct compliance architectures that fragment vendor product roadmaps. Asian wealth expansion outpaces local platform capacity, creating import dependency for sophisticated planning engines.
United States
Registered investment advisor consolidation drives demand for scalable cloud platforms that unify acquired practices under single data architectures. The SEC enforces fiduciary disclosure standards requiring conflict-of-interest flagging and fee transparency modules within advisory software. Texas and Florida host the densest advisor clusters, where independent practices serving pre-retiree mass-affluent households accelerate Monte Carlo simulation adoption.
Germany
German wealth managers face compressed development schedules as the EU AI Act mandates human-in-the-loop overrides for automated portfolio recommendations exceeding risk thresholds. The BaFin coordinates national implementation of algorithmic accountability rules affecting retirement income projection engines. Frankfurt's private banking concentration anchors demand for explainable-by-design forecasting tools that surface confidence intervals rather than single optimal outputs.
United Kingdom
UK advisory practices exhibit pronounced subscription fatigue, demanding modular unbundling of tax planning and estate visualization from all-in-one platform commitments. The FCA's evolving conduct rules shape software requirements for suitability documentation and client understanding verification. London's wealth management corridor leads disaggregation procurement patterns, with mid-size firms averaging 12-15 distinct software relationships versus consolidated stacks.
India
Family office formation among ultra-high-net-worth individuals outpaces local advisor capacity, creating demand for automated planning tools that replicate institutional-grade capabilities. The RBI and SEBI frameworks govern cross-border data flows affecting cloud deployment architectures for foreign vendors. Mumbai and Delhi-NCR concentrate emerging family office activity, where SaaS adoption bridges the gap between wealth complexity and available advisory labor supply.
Brazil
Open Finance regulations enable real-time cash flow visibility through PIX integration, anchoring next-generation planning platform development for corporate treasury and individual applications. The Central Bank of Brazil's regulatory sandbox accelerates permissioned testing of algorithmic advisory tools with embedded compliance guardrails. São Paulo's financial services cluster drives platform innovation as local and international vendors compete to leverage instantaneous payment data for dynamic forecasting engines.
Global Financial Planning Software Market Vendor Landscape
The competitive structure tilts toward data-aggregation specialists with captive advisor networks. Consolidation pressure concentrates among mid-size vendors lacking custodial API depth or proprietary risk analytics. Three archetypes dominate: infrastructure-heavy aggregators sustaining platform stickiness through data network effects, risk-analytics specialists anchoring institutional due diligence workflows, and modular specialists winning disaggregated procurement from subscription-fatigued practices. M&A activity targets data aggregation capabilities, while product development prioritizes API-first architectures that reduce client onboarding friction.
Among data-aggregation-centric players, Envestnet represents the infrastructure-heavy archetype with its advisor-facing platform ecosystem. Morningstar occupies the risk-analytics specialist position, anchoring institutional due diligence workflows through proprietary methodologies. eMoney Advisor exemplifies the planning-software pure-play, sitting within the modular specialist tier that benefits from unbundling demand among mid-size independent advisors.
| Leading Market Players |
|---|
| eMoney Advisor |
| Envestnet |
| RightCapital |
| MoneyGuidePro |
| Orion Advisor Solutions |
| Quicken |
| Morningstar |
| BlackRock |
| SAP |
| Others |
Supply Flow & Price Mechanics
Cloud-native SaaS architectures simultaneously compress vendor cost structures and concentrate data aggregation leverage among platforms with custodial API depth. Subscription economics shift pricing power toward buyers while embedding real-time feed costs that now dominate mid-size advisory practice technology budgets.
Pricing Analysis
Cost compression in mid-tier SaaS offerings accelerates as subscription fatigue drives modular unbundling demands. Three-tier pricing structure across premium, standard, and economy levels separates institutional-grade risk analytics from mass-affluent entry points and basic cash-flow tools. Price differentiation traces to integration complexity and fiduciary audit trail depth. Small advisory practices in Texas and Florida exhibit highest price sensitivity, while institutional wealth managers absorb premium tiers for explainable algorithmic accountability.
Supply Chain Analysis
Real-time data feed infrastructure rests on custodial API partnerships concentrated in the United States, United Kingdom, and Brazil. Core inputs encompass alternative data streams, Monte Carlo simulation engines, and natural language processing modules for client-facing interfaces. Single-source vulnerability concentrates in dominant data aggregators with captive advisor networks. Distribution runs through direct vendor sales to registered investment advisors and indirect channels via wealth management platforms.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Financial planning software is consolidating around data-aggregation specialists as subscription fatigue and regulatory compliance costs force weaker vendors toward exit. The EU AI Act and SEC fiduciary mandates accelerate this Darwinian pressure.
For Market Incumbents: Anchor platform stickiness through vertical integration into proprietary risk analytics and captive custodial data feeds. Defend against modular specialists by unbundling selectively while maintaining API-first architectures that reduce client onboarding friction for acquired practices. Prioritize explainable-by-design algorithmic accountability investments to preempt regulatory displacement.
For New Entrants and Emerging Players: Embedded natural language interfaces for mass-affluent self-directed investors represent the most penetrable white-space target. India's family office formation outpacing local advisor capacity offers geographic entry with lower incumbent saturation. Pursue freemium conversion models that compress traditional advisory meeting durations through conversational client portals.
For Investors and Strategic Acquirers: Exit pathways concentrate in strategic acquisitions by infrastructure-heavy aggregators seeking data network effects. Five-to-ten-year viability favors vendors with deep custodial API relationships and modular architectures serving subscription-fatigued mid-size practices. Watch algorithmic bias audit standardization as the inflection trigger for compliance-tech acquisition premiums.
| Strategic Initiative | Industry Significance |
|---|---|
| API-First Architecture Development | Reduces RIA onboarding friction from months to weeks across acquired practices. |
| Explainable Algorithmic Accountability Investment | BaFin and SEC mandates force human-in-the-loop overrides for high-risk recommendations. |
| Modular Unbundling Strategy | Captures subscription-fatigued Texas and Florida advisors piecing together best-of-breed stacks. |
| Data Aggregation Capability Acquisition | Deepens platform stickiness through captive custodial feed relationships. |
| Geographic Expansion into India | Family office formation outpaces local advisor capacity in Mumbai and Delhi-NCR. |
Methodological Framework
Independent corroboration across primary interviews with wealth management CTOs, independent RIA principals, custodial platform engineers, and regulatory compliance officers underwrites the qualitative findings. Secondary validation draws from SEC disclosure filings, EU AI Act implementation guidance, BaFin regulatory circulars, and cloud software vendor financial statements. Bottom-up practice-level demand estimates triangulate against top-down market sizing from subscription revenue disclosures.
Rate-of-change decomposition separates volume expansion from pricing dynamics across deployment models, end-user sophistication tiers, and regional regulatory clusters. Segmentation modeling incorporates cloud versus on-premise architecture, advisor practice size, integration complexity depth, and fiduciary jurisdiction patterns. CAGRs derive from fitted adoption curves adjusted for RIA consolidation velocity and compliance mandate implementation timelines. Monte Carlo simulation adoption rates and data aggregation cost trajectories anchor forecast sensitivity.
The model holds under stable regulatory implementation schedules; deviation in EU AI Act enforcement intensity or SEC fiduciary rule expansion would shift replacement demand timelines. A small set of triggers—algorithmic bias audit standardization, cross-border data flow restrictions, and cyber insurance premium spikes—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Personal Finance and Financial Planning
Debt Settlement Market
Personal Finance and Financial Planning
Account Planning Tool Market
Personal Finance and Financial Planning
Renters Insurance Market
Personal Finance and Financial Planning
Personal Finance Software Market
Personal Finance and Financial Planning
Global Personal Finance Tools and Market
Personal Finance and Financial Planning
Global Financial Wellness Software Market
Personal Finance and Financial Planning
China Financial Planning Software Market
Personal Finance and Financial Planning
Household Finances Market
Personal Finance and Financial Planning
Global Personal Loans Market
Personal Finance and Financial Planning
Credit Scores, Credit Reports and Credit Check Services Market
Personal Finance and Financial Planning
Financial Calculators Market