
 Global Financial Wellness Software Market | 2026-2036
Global Financial Wellness Software Market Size, Share, and Industry Trends Forecast 2026-2036
Global Financial Wellness Software Market Analysis
Artificial intelligence is expanding its role in personalizing financial guidance within employer wellness platforms. Prudential Financial leverages its insurance heritage to anchor retirement-income planning modules inside integrated dashboards. Mercer LLC competes through actuarial rigor, embedding predictive analytics that forecast employee financial stress before it triggers turnover. LearnLux differentiates by specializing in millennial and Gen Z debt-to-savings transitions, a demographic sweet spot for talent-retention budgets.
Financial wellness software comprises digital platforms that aggregate budgeting algorithms, debt-optimization engines, investment-tracking APIs, and behavioral nudge architectures to improve individual or household financial stability. Cloud-based deployment dominates solution delivery, since multi-tenant SaaS architectures slash per-seat costs and accelerate feature rollouts for distributed workforces. Corporate user types command the deepest feature penetration, with automated alerts and analytics modules commanding premium pricing against basic budgeting tools sold to individuals.
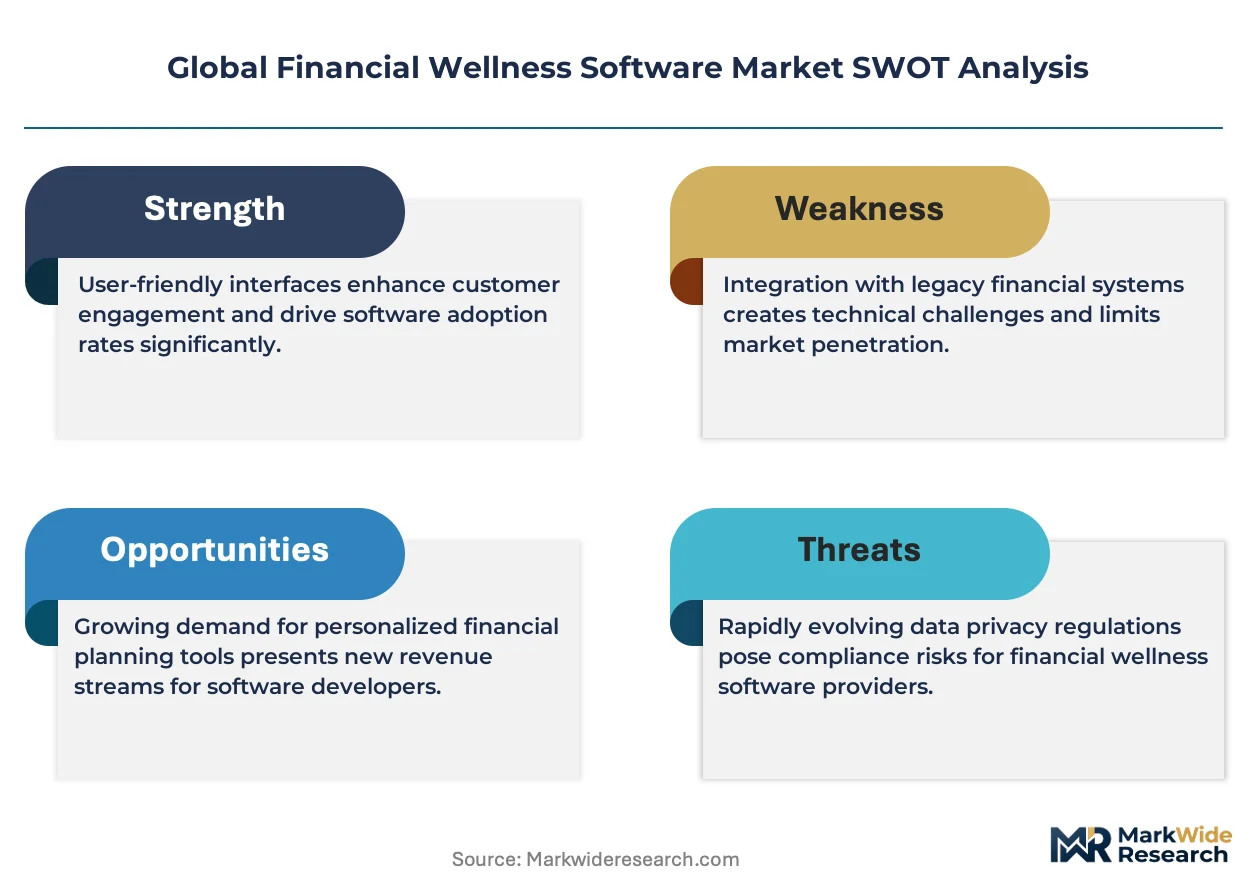
The U.S. Department of Labor's fiduciary guidance under ERISA shapes how retirement-adjacent features are marketed and priced, while the SEC's investment-adviser regulations constrain robo-advisory components embedded within wellness suites. The EU AI Act imposes transparency obligations on algorithmic financial recommendations served to employees in France, Germany, and the Netherlands. Stakeholders must monitor whether regulators in India and Brazil extend local fiduciary standards to foreign-hosted platforms before committing localization budgets.
Market Dynamics
The shift from on-premise HR systems to cloud-native SaaS architectures is compressing implementation cycles and expanding addressable employer segments beyond Fortune 500 boundaries.
Growth Catalysts
- ERISA fiduciary guidance:The U.S. Department of Labor's clarifications on retirement-adjacent advice create compliance-driven procurement mandates for integrated financial wellness modules.
- Student debt optimization engines:Public sector employers and hospital systems deploy targeted repayment tools to differentiate compensation packages in tight labor markets.
- API-first architectures:Open banking interfaces and payroll system connectors slash integration costs for mid-market HR technology stacks.
Market Restraints
- Data localization mandates:India's RBI and Brazil's central bank impose domestic hosting requirements that fragment cloud infrastructure economics for foreign platforms.
- Actuarial talent scarcity:The specialized skill set bridging behavioral economics and predictive modeling commands compensation premiums that inflate platform development costs.
- SEC investment-adviser regulations:Compliance overhead for robo-advisory components embedded within wellness suites constrains feature bundling strategies.
Strategic Opportunities
- Gig economy penetration:Non-traditional employer relationships in India and Southeast Asia create whitespace for direct-to-worker subscription models bypassing enterprise procurement.
- EU AI Act transparency obligations:Algorithmic explainability requirements in France, Germany, and the Netherlands favor vendors with auditable recommendation engines.
- Healthcare cost volatility:High-deductible health plan proliferation in the United States drives demand for integrated health savings account optimization tools.
Industry Challenges
- Legacy payroll system fragmentation:Decades-old on-premise HRIS platforms in manufacturing and logistics sectors resist API-based data exchange, forcing costly custom middleware development.
- Cross-border data governance:Conflicting requirements between GDPR's right-to-explanation and U.S. state-level privacy statutes complicate multi-tenant platform architectures.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Financial Wellness Software Market |
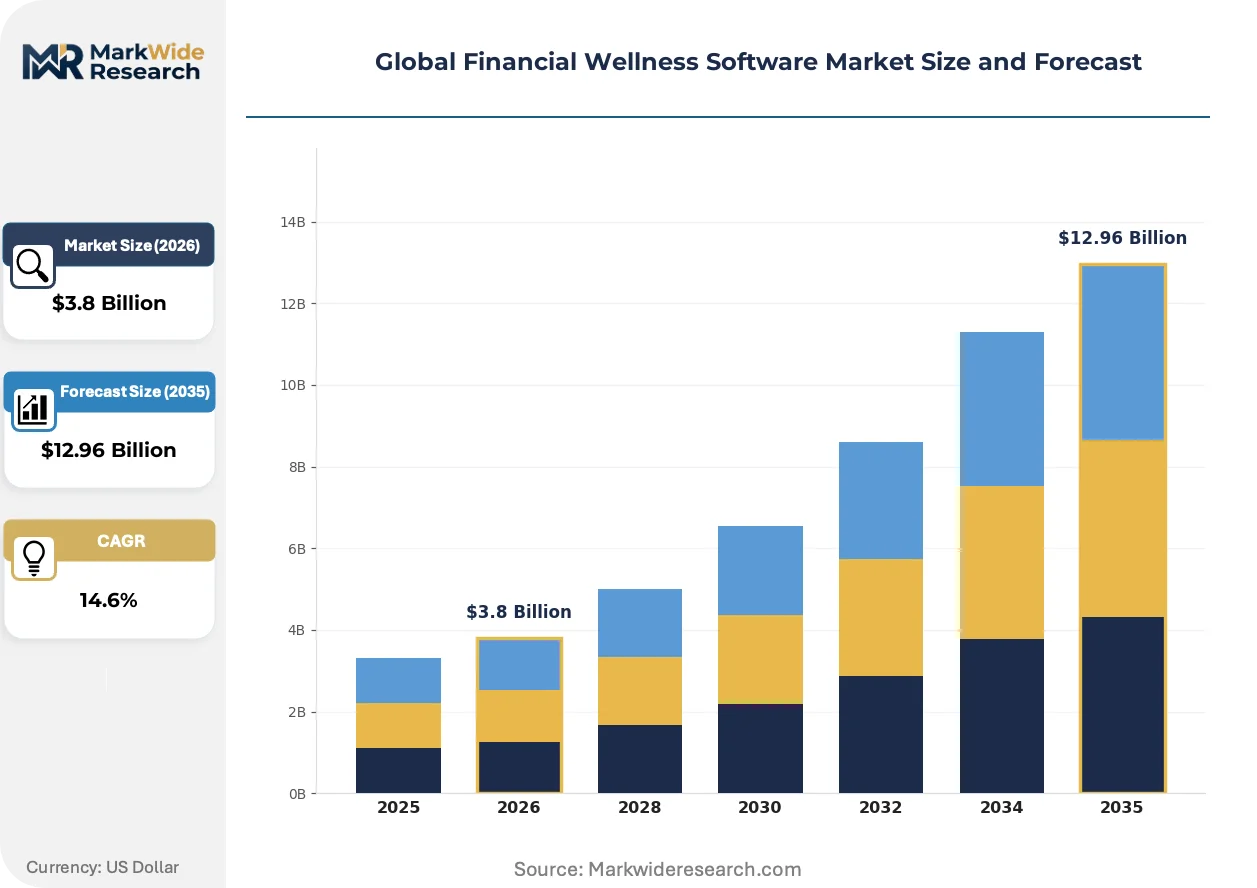
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $12.96 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Solution Type: Budgeting Tools, Debt Management, Financial Planning, Investment Tracking Deployment Model: Cloud-based, On-premises, Hybrid, Mobile Applications User Type: Individuals, Small Businesses, Corporates, Non-profits Feature Set: Automated Alerts, Goal Setting, Reports, Analytics |
| Companies Covered | Prudential Financial, Financial Finesse, Mercer LLC, LearnLux, SmartDollar, Fidelity Investments, BrightDime, Enrich, PayActiv, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Financial Wellness Software Market Emerging Trajectories
Generative AI architectures are absorbing conversational interfaces that previously required human financial coaching, compressing service delivery costs while raising regulatory scrutiny on advice quality.
Natural language processing engines are absorbing the burden of personalized debt counseling conversations that historically required certified financial planners. Large employers in the United States and United Kingdom are piloting these tools for hourly workforces previously excluded from human advisory services. The technology is absorbing marginal counseling capacity and enabling 24/7 engagement at per-interaction costs below traditional call center economics.
The EU AI Act's risk-tier classification system imposes documentation and human oversight requirements on algorithmic financial recommendations served to employees. Vendors must maintain technical files and conformity assessments for high-risk AI systems deployed in France, Germany, and the Netherlands. This regulatory architecture is compressing deployment timelines and favoring established platforms with compliance infrastructure over leaner entrants.
Enterprise buyers are unbundling financial wellness from bundled HR benefit suites and procuring point solutions with measurable engagement metrics. Procurement committees now demand proof of employee financial stress reduction rather than enrollment counts alone. This behavioral shift is most visible in the United States, where talent retention budgets face heightened CFO scrutiny and vendors must demonstrate ROI through reduced turnover correlation studies.
Global Financial Wellness Software Market Segmentation
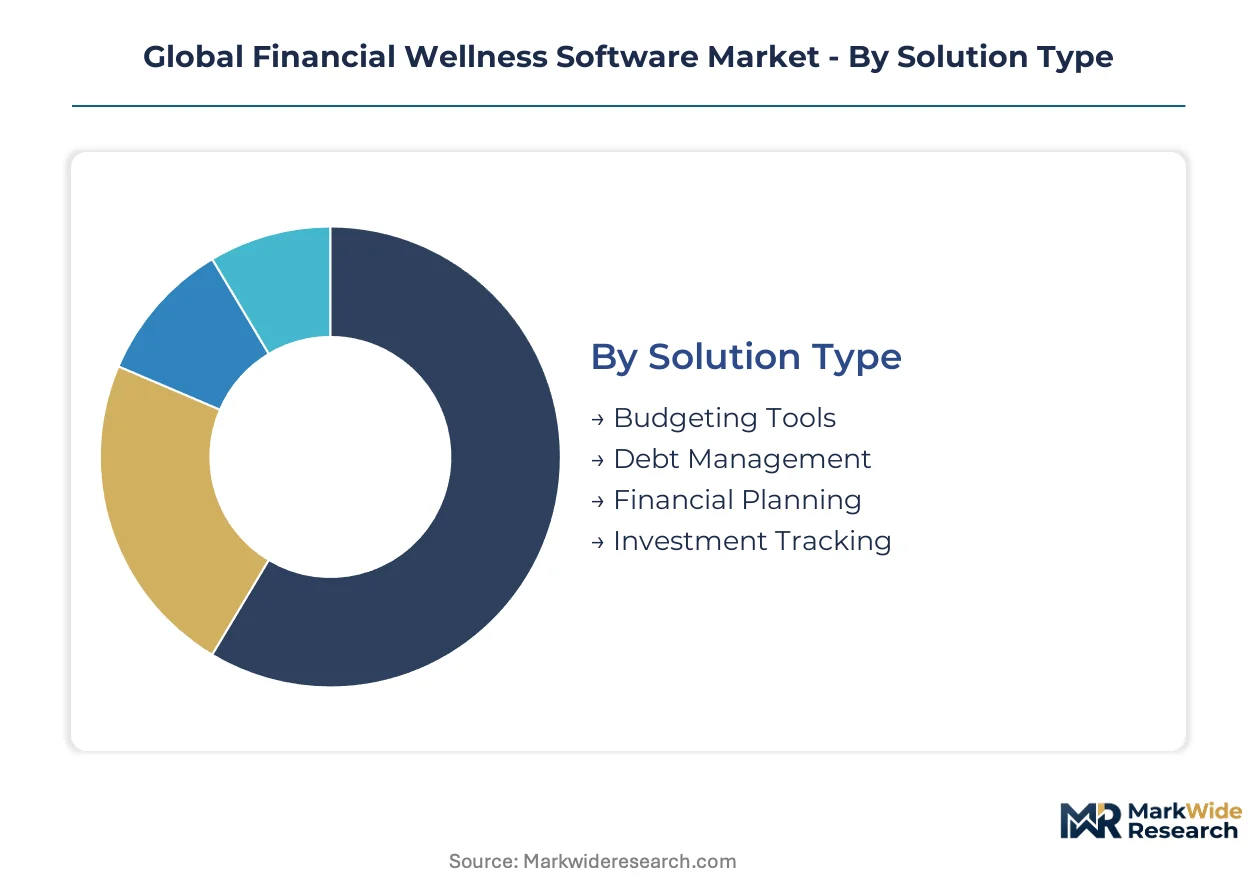
Segmentation in financial wellness software reveals how procurement patterns split between standardized consumer tools and deeply customized enterprise deployments. Buyers prioritize integration depth over feature breadth when committing budgets above mid-market thresholds.
Solution Type:
Customization intensity varies sharply across this category, with modular APIs enabling bespoke configurations at the high end and pre-built dashboards serving price-sensitive tiers.
- Financial Planning:Comprehensive retirement-income modeling and scenario-testing engines anchor employer-sponsored wellness suites. United States enterprise demand concentrates here as CFOs demand quantifiable turnover reduction tied to employee financial stress alleviation.
- Debt Management:Student loan optimization and credit card consolidation algorithms target millennial and Gen Z workforce segments. Hospital systems and public sector employers in the United States deploy these tools to differentiate compensation packages in tight labor markets.
- Budgeting Tools:Entry-level cash flow visualization for individual subscribers and micro-businesses.
- Investment Tracking:Portfolio aggregation APIs subject to SEC investment-adviser compliance overhead.
Leading the category by volume: Financial Planning. Growing fastest: Debt Management.
Deployment Model:
Cost tier stratification separates multi-tenant SaaS architectures from capital-intensive on-premise installations requiring dedicated infrastructure teams.
- Cloud-based:Multi-tenant SaaS architectures slash per-seat costs and accelerate feature rollouts for distributed workforces. Mid-market employers across Germany, France, and the Netherlands favor this model for EU AI Act compliance documentation maintained by vendors.
- Mobile Applications:Native iOS and Android interfaces with biometric authentication and push-notification nudge architectures. Gig economy penetration in India and Southeast Asia relies on direct-to-worker subscription models bypassing enterprise procurement entirely.
- Hybrid:Sensitive payroll data remains on-premise while analytics processing shifts to cloud instances.
- On-premises:Legacy manufacturing and logistics sectors in the United States resist API-based data exchange, forcing costly custom middleware development.
Expanding most quickly: Cloud-based. Retaining share in regulated verticals: On-premises.
User Type:
Customer type determines feature penetration depth, with corporates commanding automated alerts and analytics modules at premium pricing against basic tools sold to individuals.
- Corporates:Large enterprises demand integrated dashboards with predictive analytics forecasting employee financial stress before turnover triggers. Procurement committees now require proof of financial stress reduction through reduced turnover correlation studies rather than enrollment counts alone.
- Small Businesses:Mid-market buyers benefit from compressed implementation cycles as cloud-native SaaS architectures expand addressable segments beyond Fortune 500 boundaries.
- Individuals:Direct-to-consumer subscriptions with limited API connectivity and standardized nudge architectures.
- Non-profits:Grant-funded deployments serving financially vulnerable populations with simplified user interfaces.
Deepest feature penetration: Corporates. Fastest subscription growth: Small Businesses.
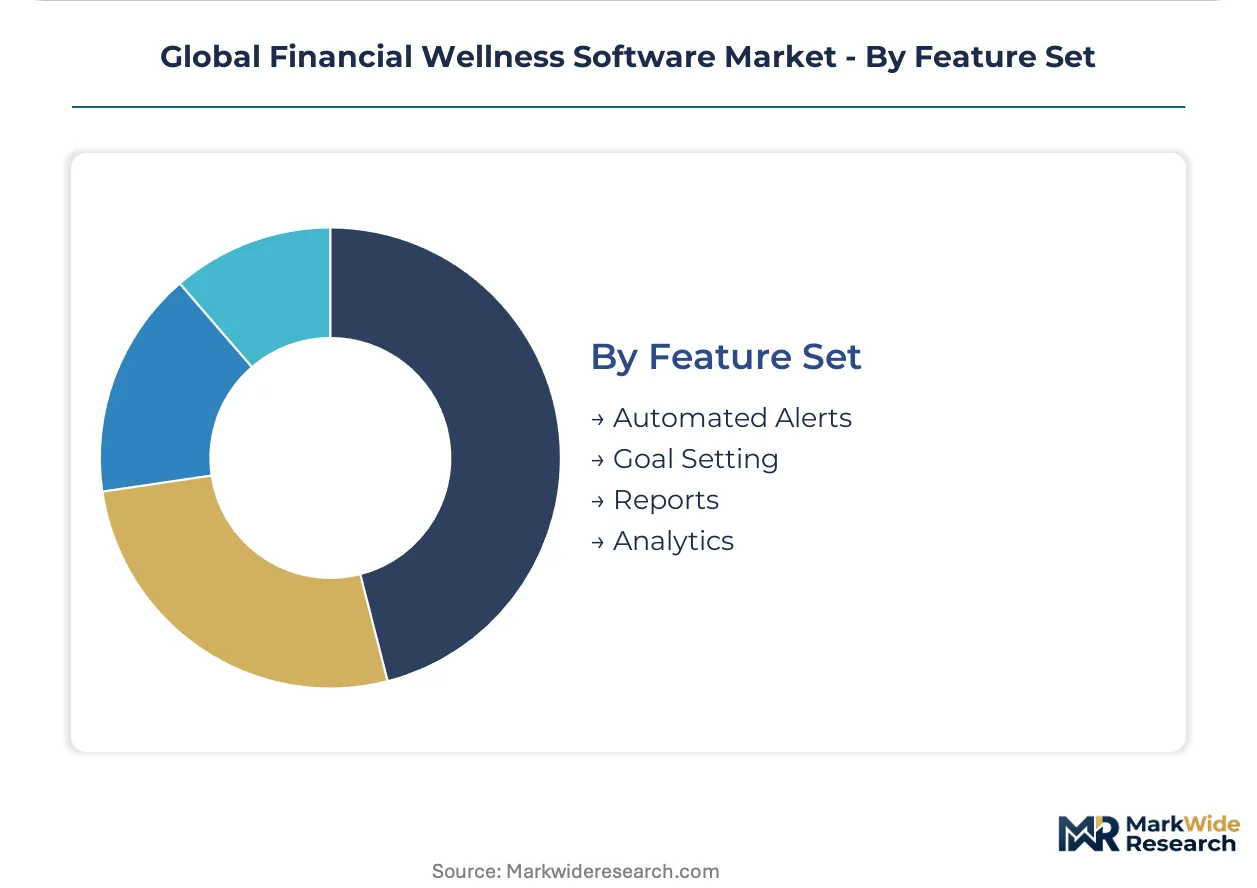
Feature Set:
Maturity gradients separate legacy reporting functions from algorithmic innovations facing heightened regulatory scrutiny under emerging AI governance frameworks.
- Analytics:Predictive modeling engines bridging behavioral economics and actuarial rigor command development cost premiums due to specialized talent scarcity. Mercer LLC embeds these capabilities to forecast employee financial stress before it triggers turnover.
- Automated Alerts:Real-time notifications for bill payments, savings milestones, and budget deviations integrated with payroll system connectors. API-first architectures slash integration costs for mid-market HR technology stacks.
- Goal Setting:Behavioral nudge architectures guiding debt-to-savings transitions.
- Reports:Standardized compliance documentation for ERISA fiduciary requirements and EU AI Act technical files.
Highest margin attachment: Analytics. Broadest deployment: Automated Alerts.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Employer procurement concentrates in the United States, where healthcare cost volatility and student debt burdens drive demand for integrated wellness platforms. Germany and France follow as regulatory clarity around algorithmic transparency accelerates vendor selection. India and Brazil present expansion whitespace despite data localization friction.
United States
Large enterprises dominate procurement, with hospital systems and public sector employers deploying student debt optimization engines to differentiate compensation packages. The Department of Labor's ERISA fiduciary guidance shapes how retirement-adjacent features are marketed and priced. The Boston-Washington corridor anchors vendor development activity, with New York Metro hosting the densest concentration of actuarial talent bridging behavioral economics and predictive modeling.
Germany
Mid-market employers favor cloud-native SaaS architectures as the EU AI Act's transparency obligations compress deployment timelines for established vendors. The Federal Financial Supervisory Authority and CNIL-equivalent state regulators impose algorithmic explainability requirements on financial recommendations served to employees. The Frankfurt-Rhine-Main cluster concentrates compliance infrastructure investments, while Munich anchors predictive analytics development for stress-forecasting modules.
France
Enterprise buyers unbundle financial wellness from bundled HR suites and demand measurable engagement metrics rather than enrollment counts alone. The EU AI Act's risk-tier classification system mandates technical files and conformity assessments for high-risk algorithmic systems. Paris anchors vendor localization efforts, with Lyon emerging as a secondary hub for behavioral nudge architecture development serving francophone European markets.
India
Gig economy penetration creates whitespace for direct-to-worker subscription models bypassing traditional enterprise procurement entirely. The Reserve Bank of India's data localization mandates fragment cloud infrastructure economics for foreign-hosted platforms. Bangalore and Hyderabad concentrate domestic vendor development, while Mumbai anchors partnerships between fintech platforms and payroll system providers serving the unorganized workforce segment.
Brazil
Non-traditional employer relationships in logistics and manufacturing sectors resist API-based data exchange, forcing costly custom middleware development for platform entrants. The central bank's domestic hosting requirements complicate multi-tenant architectures for foreign vendors. São Paulo anchors regional vendor headquarters, with Rio de Janeiro concentrating pilot deployments for healthcare cost volatility tools targeting high-deductible plan proliferation.
Global Financial Wellness Software Market Vendor Landscape
Portfolio diversification dominates the current landscape as established players absorb conversational AI capabilities and specialized vendors deepen demographic targeting. The market exhibits tiered concentration, with insurance heritage firms and actuarial consultancies commanding premium positioning against leaner SaaS entrants. Three archetypes define competitive positioning: integrated benefit suite anchors, predictive analytics specialists, and generational cohort specialists. M&A activity and API-first partnership networks constitute the primary competitive vectors, compressing feature development cycles while expanding distribution reach.
Within the insurance-heritage tier, Prudential Financial and Fidelity Investments exemplify platform breadth through retirement-income planning modules embedded inside integrated dashboards. Mercer LLC occupies a distinct position bridging actuarial rigor with predictive analytics for employee financial stress forecasting. LearnLux represents the generational-specialist archetype, targeting millennial and Gen Z debt-to-savings transitions that align with talent-retention budgets at mid-market employers. These three anchors illustrate how competitive differentiation fragments across heritage depth, analytical sophistication, and demographic precision.
| Leading Market Players |
|---|
| Prudential Financial |
| Financial Finesse |
| Mercer LLC |
| LearnLux |
| SmartDollar |
| Fidelity Investments |
| BrightDime |
| Enrich |
| PayActiv |
| Others |
Supply Flow & Price Mechanics
Actuarial talent scarcity in the Boston-Washington corridor inflates development cost premiums that propagate through SaaS pricing tiers, widening spreads between premium predictive analytics modules and standardized budgeting tools.
Pricing Analysis
Volume concentrates in mid-market cloud subscriptions while margins accrue to enterprise predictive analytics suites. Three-tier pricing structure across premium, standard, and economy levels separates actuarial-grade stress forecasting from basic nudge architectures. Price differentiation hinges on integration depth and EU AI Act compliance documentation. Cost compression in standard tiers intensifies because API-first architectures democratize entry-level feature parity, while CFO procurement committees in United States hospital systems show lowest price sensitivity for turnover-correlation proof points.
Supply Chain Analysis
Direct-to-employer channels handle Fortune 500 demand while API marketplaces and HRIS integrators distribute to mid-market buyers. Development talent concentrates in the United States, Germany, and India, with cloud infrastructure sourcing from domestic hosting providers in Brazil and India to satisfy RBI and central bank data localization mandates. The supply chain draws from specialized behavioral economists, actuarial modelers, and open banking interface providers. Single-source vulnerability sits with legacy payroll system connectors in United States manufacturing and logistics sectors resisting API-based data exchange.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Actuarial talent scarcity props SaaS pricing premiums, creating supply-constrained conditions that favor vendors with captive modeling capabilities.
For Market Incumbents: Lock in actuarial talent pipelines through university partnerships in the Boston-Washington corridor and Frankfurt-Rhine-Main cluster. Acquire specialized debt-optimization engines targeting millennial workforce segments before leaner SaaS entrants achieve feature parity. Vertical integration into predictive modeling capabilities defends margin position against API-first challengers commoditizing basic analytics modules. For New Entrants and Emerging Players: HRIS channel partners in mid-market manufacturing and logistics sectors offer the most penetrable entry vector given legacy system fragmentation blocking incumbent integration. Target direct-to-worker subscription models in India's gig economy, bypassing enterprise procurement entirely. White-label API architectures for regional payroll providers in Southeast Asia create fast-follow distribution without captive sales infrastructure. For Investors and Strategic Acquirers: Re-rating potential sits with generational-cohort specialists given talent-retention budget expansion at mid-market employers. Firms bridging millennial debt-to-savings transitions command premium multiples against generalized wellness platforms. Watch for EU AI Act technical file completion as inflection signal separating compliant scale-ups from documentation-deficient entrants.| Strategic Initiative | Industry Significance |
|---|---|
| API-First Architecture Development | Open banking interfaces slash integration costs for mid-market HR technology stacks in Germany and France. |
| Predictive Analytics Acquisition | Actuarial-grade stress forecasting commands premium pricing against standardized budgeting tool commoditization. |
| EU AI Act Compliance Investment | Technical file infrastructure separates established vendors from leaner entrants in France, Germany, and Netherlands. |
| Direct-to-Worker Channel Launch | Gig economy penetration in India bypasses enterprise procurement friction and data localization mandates. |
| Legacy Payroll System Integration | Custom middleware development unlocks manufacturing and logistics sectors resisting API-based data exchange. |
Methodological Framework
Independent corroboration across HR technology procurement officers, actuarial consultants, benefits directors at hospital systems, and fintech platform engineers underwrites the qualitative findings. Primary interviews with CTOs at mid-market employers, integration specialists at HRIS vendors, and regulatory affairs leads navigating SEC investment-adviser constraints combined with secondary validation from SEC filings, EU AI Act implementation guidance, Department of Labor ERISA advisory opinions, and open banking API documentation. Bottom-up subscription volume estimates and top-down enterprise IT spend allocations triangulate market sizing.
Comparable historical periods anchored the forecast window to pre-pandemic baseline adoption curves and post-2020 remote-workforce acceleration patterns. The analytical framework models deployment model, organization size, vertical industry, and regional regulatory cluster across the projection horizon. CAGRs derive from segment-level growth rate reconciliation against aggregate employer wellness spend trends. Forecast inputs include API integration cost trajectories and EU AI Act compliance timeline assumptions.
Several conditions sit outside the modeled scope, including potential SEC rulemaking expansion to wellness-embedded robo-advisory components and unforeseen RBI data localization enforcement intensity. Forecasts reflect assumptions about sustained employer sponsorship of financial wellness benefits and stable cloud infrastructure economics. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Personal Finance and Financial Planning
Financial Calculators Market
Personal Finance and Financial Planning
Global Personal Finance Tools and Market
Personal Finance and Financial Planning
Credit Scores, Credit Reports and Credit Check Services Market
Personal Finance and Financial Planning
Global Personal Loans Market
Personal Finance and Financial Planning
China Financial Planning Software Market
Personal Finance and Financial Planning
Renters Insurance Market
Personal Finance and Financial Planning
Global Financial Planning Software Market
Personal Finance and Financial Planning
Account Planning Tool Market
Personal Finance and Financial Planning
Personal Finance Software Market
Personal Finance and Financial Planning
Debt Settlement Market
Personal Finance and Financial Planning
Household Finances Market