
 Intelligent Cash Deposit Machine Market | 2026-2036
Intelligent Cash Deposit Machine Market Size, Share, and Industry Trends Forecast 2026-2036
Intelligent Cash Deposit Machine Market Foresight
Bank branch networks across emerging economies are reconfiguring their physical footprints to prioritize automated cash-handling endpoints over traditional teller windows. GRG Banking Equipment leverages its manufacturing scale to dominate procurement cycles for large-scale bank deployments across Asia. Diebold Nixdorf sustains technology leadership through intensive R&D in multi-currency recognition engines. NCR Corporation anchors North American demand with extensive service infrastructure and software integration capabilities.
An intelligent cash deposit machine is a self-service terminal engineered to authenticate, count, sort, and store banknotes without human teller intervention, typically processing 300-600 notes per minute through spectral imaging and magnetic ink detection. Its primary commercial purpose is to reduce labor costs, accelerate cash recycling, and minimize vault transit risks for financial institutions. Banking terminals command the largest installed base due to regulatory requirements for deposit automation, while self-service kiosks represent the fastest-expanding category as convenience stores and fuel stations adopt cash-to-digital conversion. Machine learning within the technology dimension is displacing rules-based counterfeit detection, creating margin pools for vendors with proprietary algorithm training datasets.
FCC certification governs wireless communication modules in US-deployed units, while CE marking and GDPR compliance shape European product design for customer data capture. India's BIS standards and RBI circulars on cash management infrastructure mandate specific uptime and audit-trail specifications that filter market access. Stakeholders must monitor how central bank digital currency pilots reshape cash velocity and, consequently, the business case for deposit automation capital expenditure.
Market Dynamics
Bank branch automation mandates from central banks across emerging Asia are compressing deployment timelines for intelligent cash deposit machines, forcing manufacturers to accelerate software certification cycles while hardware commoditization squeezes margin pools on base units.
Growth Catalysts
- RBI Cash Management Circulars:India's central bank mandates enhanced audit trails and uptime specifications for deposit infrastructure, compelling tier-2 and tier-3 banks to accelerate procurement of compliant terminals.
- Spectral Imaging Modules:Multi-wavelength authentication engines reduce false-positive rejection rates for polymer banknotes, improving throughput velocity in high-traffic urban banking corridors.
- Indonesia's Branch Rationalization:State-owned banks are consolidating physical footprints while expanding self-service networks in Jakarta, Surabaya, and Medan to maintain deposit access without teller overhead.
Market Restraints
- Optical Sensor Supply Concentration:High-resolution CMOS arrays for spectral authentication concentrate among Japanese and German component suppliers, exposing assemblers to allocation risk during semiconductor demand spikes.
- GDPR Data Retention Friction:European deployment of customer-facing deposit terminals requires complex anonymization architectures for transaction imagery, extending product development cycles and compliance costs.
- Central Bank Digital Currency Substitution:Pilot programs for retail CBDCs in Thailand, China, and India threaten long-term cash velocity assumptions underlying deposit automation ROI calculations.
Strategic Opportunities
- Vietnam's Underpenetrated Provincial Banking:Joint-stock banks in secondary cities lack deposit automation coverage, creating first-mover positioning for vendors willing to localize software interfaces and service networks.
- Convenience Store Cash-to-Digital Kiosks:Non-bank retail channels in Indonesia and Philippines seek compact deposit terminals enabling e-wallet top-ups, bill payments, and remittance funding.
- PLI Scheme Component Incentives:India's production-linked incentive framework for electronics manufacturing attracts domestic assembly of cash-handling modules, reducing landed cost for regional deployments.
Industry Challenges
- Embedded Firmware Talent Scarcity:Shortage of engineers with expertise in real-time operating systems for financial terminals delays customization timelines for bank-specific integration requirements.
- Multi-Currency Certification Backlogs:Central bank testing protocols for new polymer substrate authentication extend approval timelines, freezing product launches during validation windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Intelligent Cash Deposit Machine Market |
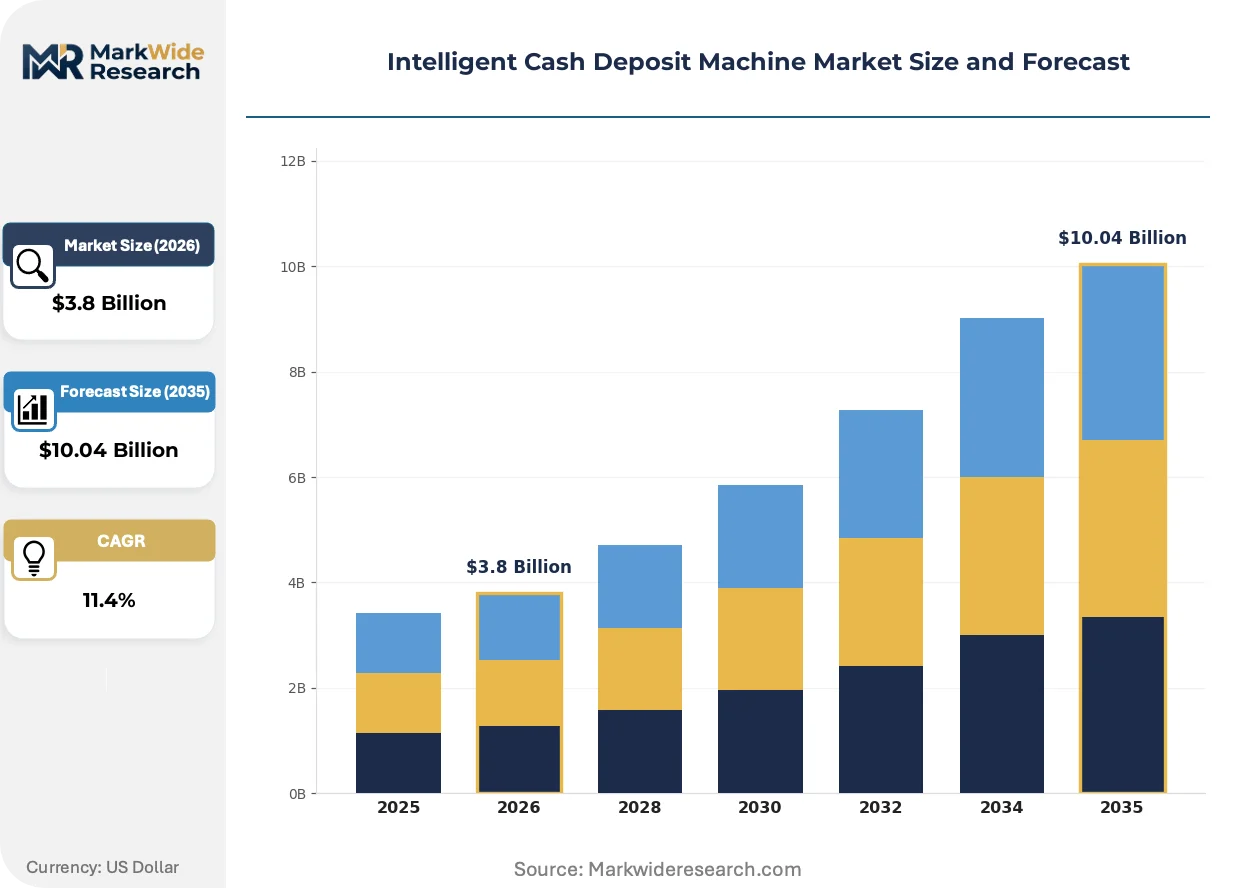
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.04 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Self-Service Kiosks, Retail Solutions, Banking Terminals, ATM Integration End User: Banks, Credit Unions, Retailers, Financial Institutions Technology: Biometric Authentication, Image Recognition, Machine Learning, Cloud Computing Installation: On-Premise, Remote Locations, Urban Installations, High Traffic Areas |
| Companies Covered | GRG Banking Equipment Co., Ltd., Triton Systems of Delaware, Diebold Nixdorf, Nautilus Hyosung Inc., OKI Electric Industry Co., Ltd., NCR Corporation, Fujitsu Limited, HESS Cash Systems GmbH & Co. KG, Hitachi Omron Terminal Solutions, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Intelligent Cash Deposit Machine Market Shifts & Advancements
Machine learning architectures are displacing rules-based counterfeit detection across deposit terminals, compressing authentication latency while opening margin pools for vendors with proprietary training datasets and regulatory-grade algorithm certifications.
Spectral imaging is hybridizing with magnetic ink character recognition in next-generation deposit modules, enabling simultaneous denomination verification and serial number capture for traceability compliance. Tier-1 banks in India and Indonesia are piloting these fused authentication stacks in high-volume branches, seeking to reduce manual reconciliation labor while satisfying RBI and Bank Indonesia audit requirements. The convergence is compressing hardware refresh cycles from seven-year baselines toward five-year replacement timelines.
CE marking requirements under the EU AI Act are extending conformity assessment timelines for customer-facing terminals with biometric authentication or behavioral analytics capabilities. European manufacturers must document algorithmic transparency and bias testing for deposit machines capturing facial imagery or transaction patterns, adding six to nine months to product launches. Vendors are responding by segregating AI-enabled features into modular software licenses rather than embedded hardware to isolate regulatory exposure.
After-sales service unbundling is fragmenting procurement relationships between hardware OEMs and bank technology departments. Large Southeast Asian banks are separating terminal purchases from maintenance contracts, awarding multi-vendor service agreements to specialized third-party field engineering networks. This disintermediation is most visible in Thailand, where Kasikornbank and Siam Commercial Bank have consolidated service procurement across competing hardware brands to standardize uptime SLA enforcement.
Intelligent Cash Deposit Machine Market Segmentation
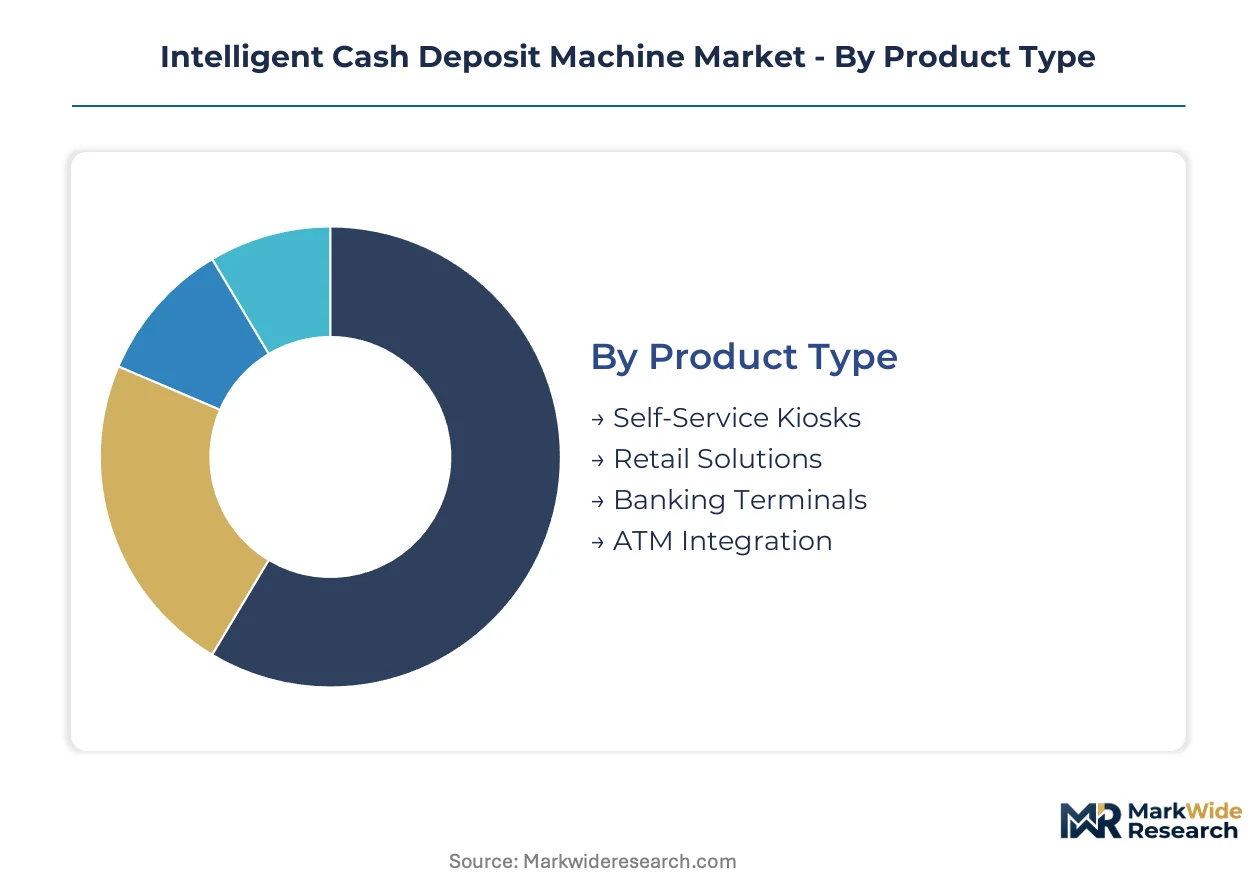
Intelligent cash deposit machines serve divergent operational requirements across banking infrastructure, retail networks, and remote service points. Understanding how product configurations, authentication technologies, and deployment contexts fragment the addressable market clarifies procurement priorities and margin architecture for equipment vendors.
Product Type:
Deployment contexts span high-security vault-adjacent terminals to compact retail-facing kiosks requiring minimal footprint and power draw.
- Banking Terminals:Full-featured units engineered for branch vault integration process 300-600 notes per minute through spectral imaging and magnetic ink detection. State-owned banks in Indonesia consolidate physical footprints while expanding these terminals across Jakarta, Surabaya, and Medan to maintain deposit access without teller overhead.
- Self-Service Kiosks:Compact, standalone units enable cash-to-digital conversion in non-bank retail channels. Convenience stores and fuel stations across the Philippines and Indonesia deploy these for e-wallet top-ups, bill payments, and remittance funding, compressing hardware refresh cycles toward five-year replacement timelines.
- Retail Solutions:Mid-capacity units optimized for commercial cash-intensive operations including supermarkets and hospitality chains. RBI cash management circulars mandate enhanced audit trails that accelerate procurement among tier-2 and tier-3 Indian banks seeking compliant endpoints.
- ATM Integration:Deposit modules retrofitting existing automated teller machine infrastructure. European deployment requires complex anonymization architectures for transaction imagery under GDPR data retention protocols, extending product development cycles.
The dominant share belongs to Banking Terminals, while Self-Service Kiosks is closing the gap fastest.
End User:
Customer procurement sophistication varies sharply between regulated deposit-taking institutions and retail operators seeking payment ecosystem integration.
- Banks:Tier-1 institutions in India and Indonesia pilot fused authentication stacks combining spectral imaging with magnetic ink character recognition. RBI and Bank Indonesia audit requirements drive simultaneous denomination verification and serial number capture for traceability compliance.
- Financial Institutions:Non-bank payment system operators and fintech platforms require API-integrated deposit terminals. Vietnam's joint-stock banks in secondary cities lack automation coverage, creating first-mover positioning for vendors willing to localize software interfaces.
- Credit Unions:Member-owned cooperative banks prioritize cost-efficient deposit automation with standardized service agreements. Thailand's Kasikornbank and Siam Commercial Bank consolidate service procurement across competing hardware brands to standardize uptime SLA enforcement.
- Retailers:Convenience store chains and fuel station operators seek compact terminals enabling cash recycling without vault infrastructure. India's production-linked incentive framework for electronics manufacturing attracts domestic assembly of cash-handling modules, reducing landed cost for regional deployments.
Procurement volume concentrates with Banks, though Retailers are gaining share fastest as non-bank channels expand deposit access.
Technology:
Authentication architectures differentiate between established rules-based detection and emerging algorithmic approaches requiring regulatory-grade certification.
- Machine Learning:Proprietary algorithm training datasets enable compressed authentication latency and reduced false-positive rejection rates for polymer banknotes. Vendors with regulatory-grade certifications capture margin pools as central bank testing protocols for new substrate authentication extend approval timelines.
- Image Recognition:Multi-wavelength spectral imaging modules authenticate banknotes through ultraviolet, infrared, and visible light analysis. High-resolution CMOS arrays for this function concentrate among Japanese and German component suppliers, exposing assemblers to allocation risk during semiconductor demand spikes.
- Biometric Authentication:Fingerprint, palm-vein, and facial recognition modules for customer identity verification. CE marking requirements under the EU AI Act extend conformity assessment timelines, with manufacturers documenting algorithmic transparency and bias testing for terminals capturing facial imagery.
- Cloud Computing:Remote transaction processing and software update distribution reduce on-site maintenance requirements. GDPR compliance shapes European product design for customer data capture, with vendors segregating AI-enabled features into modular software licenses to isolate regulatory exposure.
Adoption momentum favors Machine Learning, while Cloud Computing is climbing fastest as after-sales service unbundling fragments procurement relationships.
Installation:
Physical deployment constraints determine environmental hardening requirements, connectivity specifications, and service network density.
- On-Premise:Branch-integrated installations with dedicated network connectivity and climate-controlled environments. India's BIS standards and RBI circulars mandate specific uptime and audit-trail specifications that filter market access for domestic and imported equipment.
- Urban Installations:High-density metropolitan deployment in Jakarta, Surabaya, Medan, and Indian tier-1 cities. Spectral imaging modules improve throughput velocity in these high-traffic banking corridors where deposit automation reduces labor costs and vault transit risks.
- High Traffic Areas:Transportation hubs, shopping districts, and central business districts with continuous operation requirements. FCC certification governs wireless communication modules in US-deployed units, while CE marking shapes European product design.
- Remote Locations:Provincial and rural installations with intermittent connectivity and limited service technician access. Vietnam's underpenetrated provincial banking infrastructure in secondary cities creates positioning opportunities for vendors establishing localized service networks.
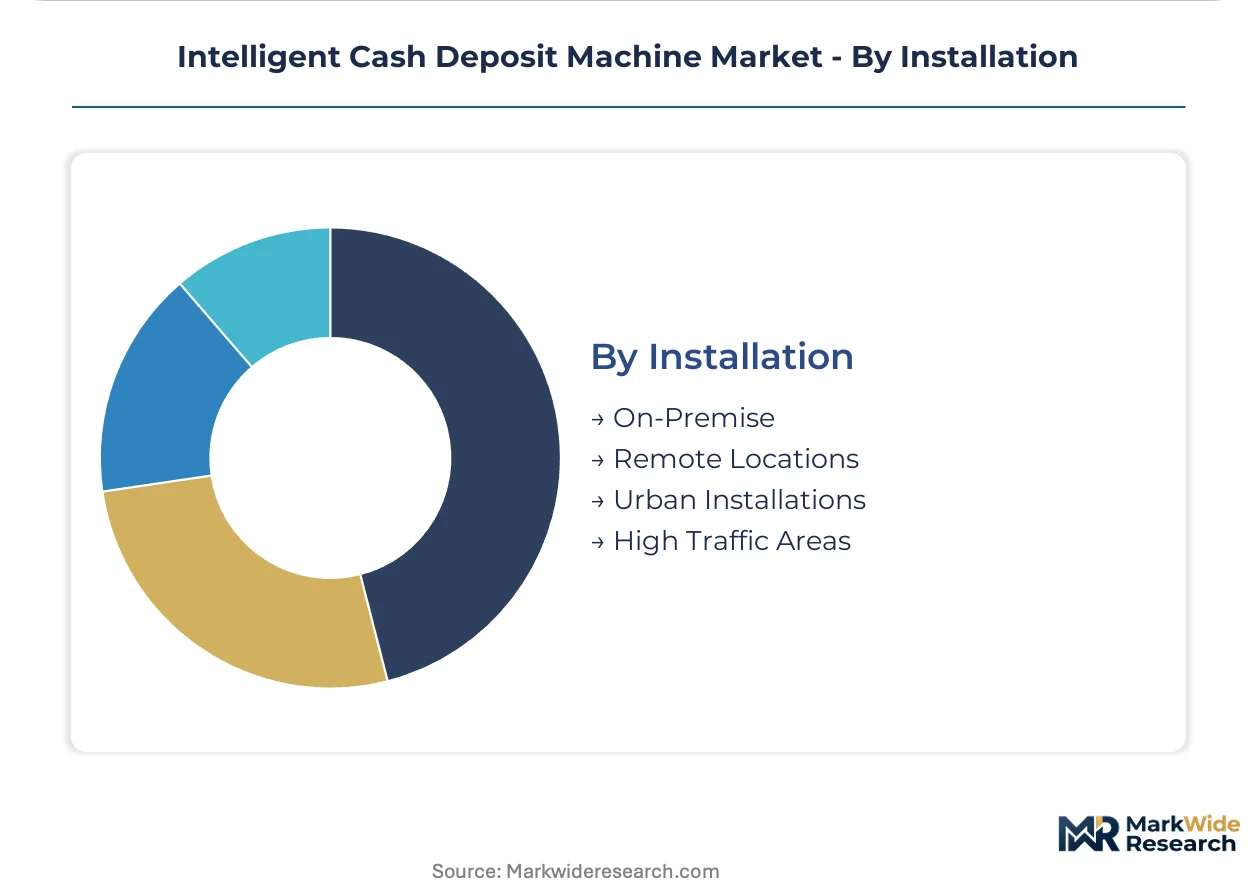
Deployment volume centers on On-Premise installations, though Remote Locations are expanding most quickly as provincial banks automate deposit infrastructure.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Java-Bali electricity interconnection underwrites Indonesia's position as the densest deployment corridor for deposit automation infrastructure in Southeast Asia.
Indonesia
State-owned banks are consolidating 2,400 branch locations while expanding self-service networks across Jakarta, Surabaya, and Medan. Bank Indonesia regulations mandate enhanced audit trails for cash management infrastructure. The Jakarta-Surabaya banking corridor concentrates procurement volume for spectral imaging-enabled terminals.
India
Tier-2 and tier-3 banks are accelerating procurement of compliant terminals following RBI cash management circulars. The PLI scheme for electronics manufacturing attracts domestic assembly of cash-handling modules. Maharashtra and Gujarat house the primary manufacturing clusters for regional deployment.
Vietnam
Joint-stock banks in secondary cities lack deposit automation coverage, creating positioning opportunities for vendors establishing localized service networks. The State Bank of Vietnam issues circulars on payment infrastructure modernization. Ho Chi Minh City and Hanoi anchor demand for API-integrated deposit terminals.
Thailand
Retail CBDC pilot programs threaten long-term cash velocity assumptions underlying deposit automation ROI calculations. Bank of Thailand guidelines shape procurement specifications for self-service networks. Bangkok's financial district concentrates pilot deployments of fused authentication stacks.
Philippines
Convenience store chains and fuel station operators seek compact terminals enabling e-wallet top-ups and remittance funding. Bangko Sentral ng Pilipinas regulations govern electronic payment and financial institution infrastructure. Metro Manila's retail corridor drives demand for cash-to-digital kiosks.
Intelligent Cash Deposit Machine Market Competitive Landscape
On the supply side, the industry is consolidating around three distinct capability tiers. Established banking equipment manufacturers with integrated software stacks occupy the premium segment. Mid-scale regional fabricators compete on localization and service density. Component specialists concentrate in optical sensor and authentication module supply. Competitive moves center on geographic licensing partnerships and backward integration into critical sensor arrays.
Within the premium-tier vector, GRG Banking Equipment Co., Ltd. and Diebold Nixdorf exemplify the integrated hardware-software archetype, while NCR Corporation anchors North American service infrastructure capabilities. These three represent contrasting geographic footprints and customer relationship models across the addressable market.
| Leading Market Players |
|---|
| GRG Banking Equipment Co., Ltd. |
| Triton Systems of Delaware |
| Diebold Nixdorf |
| Nautilus Hyosung Inc. |
| OKI Electric Industry Co., Ltd. |
| NCR Corporation |
| Fujitsu Limited |
| HESS Cash Systems GmbH & Co. KG |
| Hitachi Omron Terminal Solutions |
| Others |
Supply & Pricing Matrix
The Shanghai-Singapore maritime corridor carries spectral imaging modules and CMOS arrays from Japanese and German suppliers to assembly plants in China and Southeast Asia, with freight cost volatility compressing margins on economy-tier terminals while premium-tier vendors absorb logistics premiums through captive service networks.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates procurement, with differentiation driven by certification grade (RBI/Bank Indonesia compliance tiers) and after-sales bundling. Cost compression in the economy tier is intensifying because hardware commoditization squeezes base-unit margins, while tier-1 banks in India and Indonesia exhibit lowest price sensitivity due to regulatory mandate urgency. Provincial joint-stock banks in Vietnam and credit unions in Thailand represent the most price-sensitive buyer archetypes, prioritizing unbundled hardware procurement over integrated service contracts.
Supply Chain Analysis
Foxconn and Jabil Electronics hold contract-manufacturing capacity for cash-handling module assembly across China, Vietnam, and India. High-resolution CMOS arrays for spectral authentication draw from Japanese and German component specialists, creating single-source vulnerability during semiconductor demand spikes. Distribution runs through bank technology procurement departments and specialized third-party field engineering networks, with after-sales service unbundling fragmenting traditional OEM-channel relationships in Thailand and Indonesia.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market represents an early-cycle expansion story, with central bank automation mandates across emerging Asia creating sustained procurement tailwinds that outpace hardware replacement baselines.
For Market Incumbents: Entrench position through backward integration into optical sensor supply and accelerated RBI software certification cycles. GRG Banking Equipment and Diebold Nixdorf must defend against embedded firmware talent scarcity by captive hiring in Indian and Vietnamese engineering clusters, while isolating regulatory exposure from EU AI Act compliance through modular software licensing rather than embedded hardware features.
For New Entrants and Emerging Players: Pursue white-space positioning in Vietnam's underpenetrated provincial banking infrastructure and Indonesia's convenience store cash-to-digital kiosk channel. Joint-stock banks in secondary Vietnamese cities lack deposit automation coverage, creating first-mover advantage for vendors localizing software interfaces and establishing dedicated service networks. API-integrated terminals for non-bank retail channels offer the most penetrable entry vector.
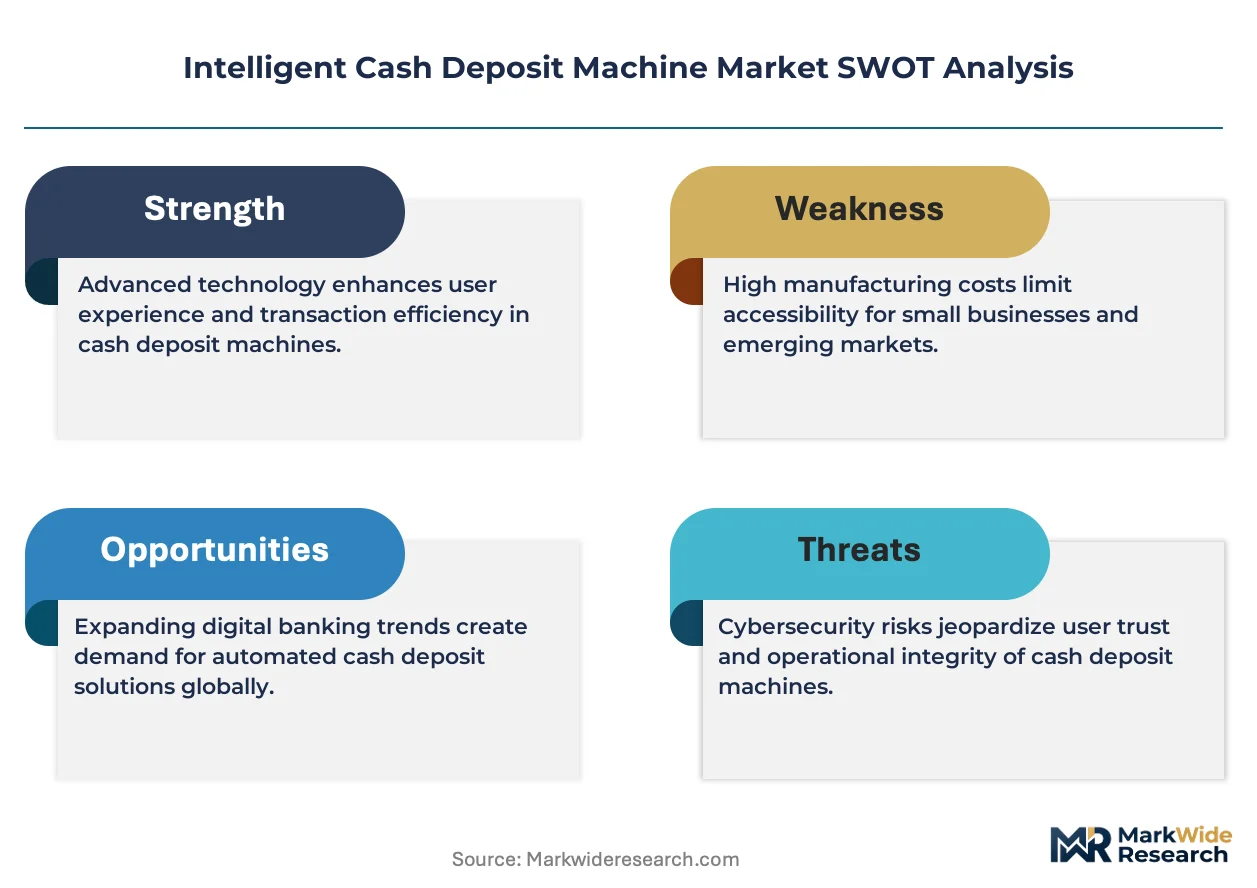
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified industrial conglomerates with dormant cash-handling equipment divisions or regional fabricators lacking algorithmic authentication capabilities. Long-term viability rests on machine learning displacement of rules-based counterfeit detection and regulatory-grade algorithm certifications. Monitor central bank digital currency pilot programs in Thailand, China, and India as the primary inflection signal threatening cash velocity assumptions.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Optical Sensors | Captive supply of CMOS arrays insulates Japanese and German allocation risk for premium-tier vendors. |
| RBI Certification Fast-Track Investment | Accelerated software validation cycles capture tier-2 and tier-3 Indian bank procurement mandates. |
| Provincial Service Network Buildout | Localized field engineering density secures first-mover positioning in Vietnam's secondary cities. |
| Modular AI Feature Licensing | Software-based regulatory isolation reduces EU AI Act conformity assessment exposure for European deployments. |
| Convenience Store Channel Partnership | Non-bank retail kiosk deployment captures Indonesia and Philippines e-wallet top-up transaction volume. |
Research Methodology
A standing panel of bank technology procurement officers, branch operations directors, central bank payment infrastructure specialists, and field service engineering managers provided ongoing calibration throughout the study period. Primary interviews with these stakeholders combined with secondary validation from RBI circulars, Bank Indonesia regulations, BIS standards documentation, and customs trade data for cash-handling equipment imports. Bottom-up unit deployment estimates across Indonesia, India, Vietnam, Thailand, and the Philippines triangulated against top-down market value reconstruction.
Scenario-bracketing framed the analytical approach across the projection horizon, with segmentation dimensions spanning product type (banking terminals, self-service kiosks, retail solutions, ATM integration), authentication technology (machine learning, spectral imaging, biometric modules), and installation context (on-premise, urban, high-traffic, remote). CAGRs derived from logistic diffusion modeling of central bank mandate penetration curves and hardware replacement cycle compression, with inputs from polymer banknote authentication protocol evolution and embedded firmware talent supply constraints.
Macroeconomic conditions sit as an overlay; deviation in emerging market currency stability, semiconductor availability, or central bank digital currency adoption velocity would shift the trajectory. Forecasts reflect documented assumptions on regulatory mandate enforcement timelines and hardware commoditization rates. Quarterly review of RBI procurement circulars, Bank Indonesia infrastructure spend disclosures, and CBDC pilot program announcements is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
FinTech
Fintech Crisis Management Market
FinTech
Canada AI in Fintech Market
FinTech
Global Saas Spend Management Software Market
FinTech
Account Checking Software Market
FinTech
Africa AI in Fintech Market
FinTech
Spend Management Platform Market
FinTech
IT Financial Management Tools Market
FinTech
Financial App Market
FinTech
North America Fintech Market
FinTech
Decentralized Finance Technology Market
FinTech
Cloud AI in Fintech Market
FinTech
Smart Lending Platform Market
FinTech
United Kingdom AI in Fintech Market
FinTech
Asia-Pacific Neo Banking Market
FinTech
Global Cloud Financial Close Solutions Software Market
FinTech
Global Fin Tech Blockchain Market