
 Portfolio Management Software Market | 2026-2036
Portfolio Management Software Market Size, Share, and Industry Trends Forecast 2026-2036
Portfolio Management Software Market Analysis
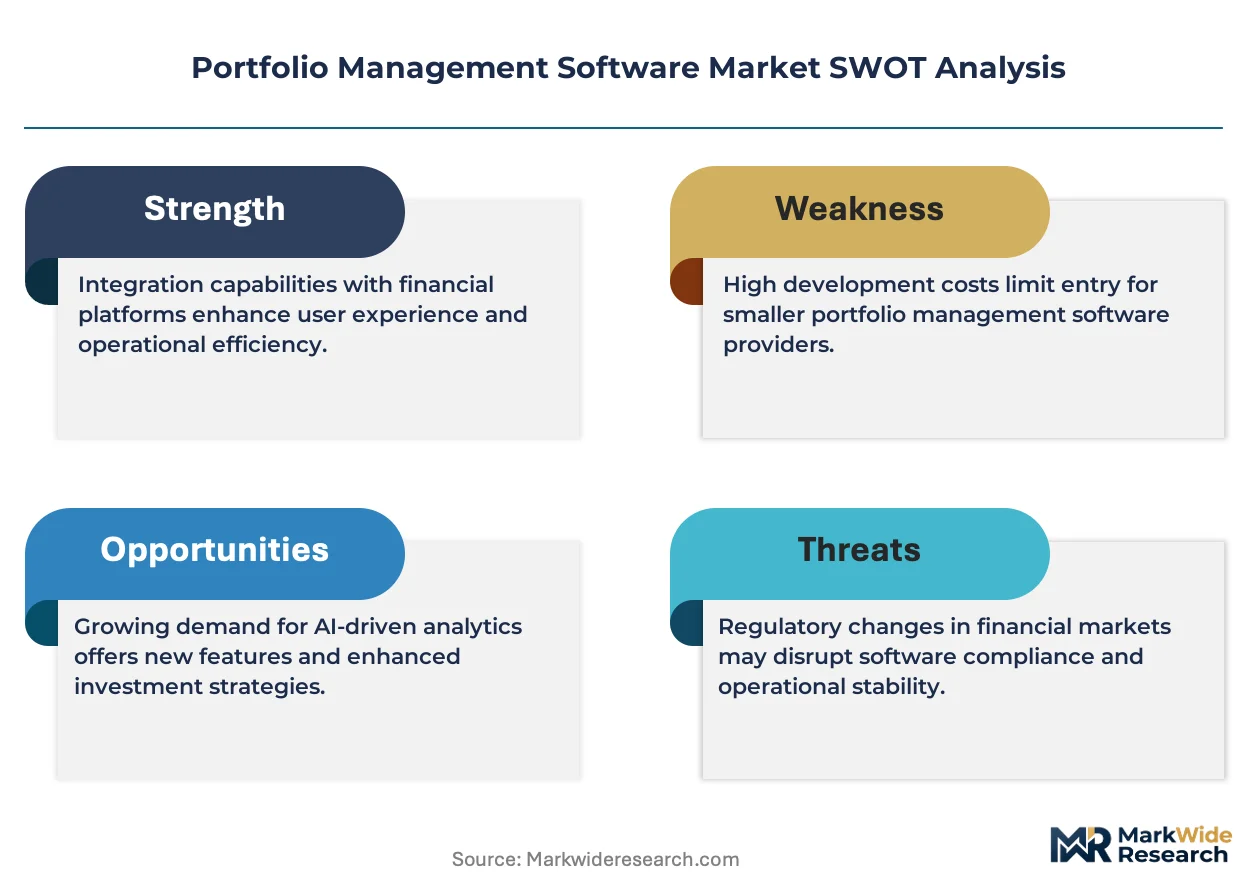
Modular platform bundling is broadening buyer choice across the portfolio management software landscape. Oracle leverages its database heritage to anchor enterprise-grade deployments for large asset managers. Microsoft competes through Azure-integrated workflows that extend across Office ecosystems. SAP differentiates via embedded analytics that connect portfolio data with enterprise resource planning streams.
Portfolio management software encompasses systems that aggregate, analyze, and execute investment positions across asset classes, typically processing real-time market feeds, risk calculations, and compliance checks through algorithmic engines. Cloud-based deployment now leads adoption as hedge funds and asset managers prioritize elastic compute for Monte Carlo simulations and stress-testing. Investment Analytics represents the most mature segment with established margin pools, while Risk Management Tools capture the fastest growth trajectory driven by Basel III and Solvency II alignment needs. Trading Platforms remain concentrated among top-tier sell-side institutions where latency requirements sustain premium pricing.
SEC oversight shapes product architecture through Form PF and ADV filing automation requirements, while GDPR in Europe mandates consent-tracking layers that increase engineering overhead for cross-border platforms. The EU AI Act introduces additional scrutiny for algorithmic trading components, pressuring vendors to document decision-audit trails. Stakeholders must weigh regulatory compliance costs against the operational leverage that integrated risk-reporting workflows deliver.
Market Dynamics
Cloud-native architecture is compressing deployment cycles for portfolio management platforms, forcing legacy vendors to re-engineer core engines while hedge funds demand elastic compute for real-time risk analytics.
Growth Catalysts
- Basel III and Solvency II alignment:European insurers and banks must upgrade risk engines to meet capital adequacy reporting timelines, driving replacement demand for compliance-automated platforms.
- Alternative data integration:Asset managers in New York and Boston now require NLP pipelines for satellite imagery and social sentiment feeds, expanding platform data-layer capabilities.
- Form PF automation:SEC filing mandates for private funds are pushing hedge funds toward end-to-end reporting suites that eliminate manual reconciliation workflows.
Market Restraints
- Engineering talent scarcity:Quantitative developers with C++ and Python expertise command premium compensation, inflating vendor R&D cost structures.
- Cloud concentration risk:Over-reliance on AWS, Azure, and Google Cloud for Monte Carlo simulations creates single-point-of-failure exposure during regional outages.
- GDPR consent architecture:Cross-border data residency requirements add 15-20% engineering overhead for platforms serving EU and US clients simultaneously.
Strategic Opportunities
- WealthTech democratization:Registered investment advisors with under $100 million AUM remain underserved by enterprise platforms, creating white space for modular, per-seat pricing models.
- ESG data convergence:Integration of carbon accounting engines with portfolio analytics represents an unclaimed capability gap as EU CSRD disclosure mandates expand.
- Embedded finance channels:Neobanks and fintech platforms seek white-labeled portfolio modules, opening distribution beyond traditional asset manager sales cycles.
Industry Challenges
- Legacy system entanglement:Mainframe-dependent custodian banks face multi-year migration timelines to API-first architectures, slowing vendor platform upgrades.
- Model risk governance:EU AI Act documentation requirements for algorithmic trading components demand audit-trail engineering that most platforms lack.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Portfolio Management Software Market |
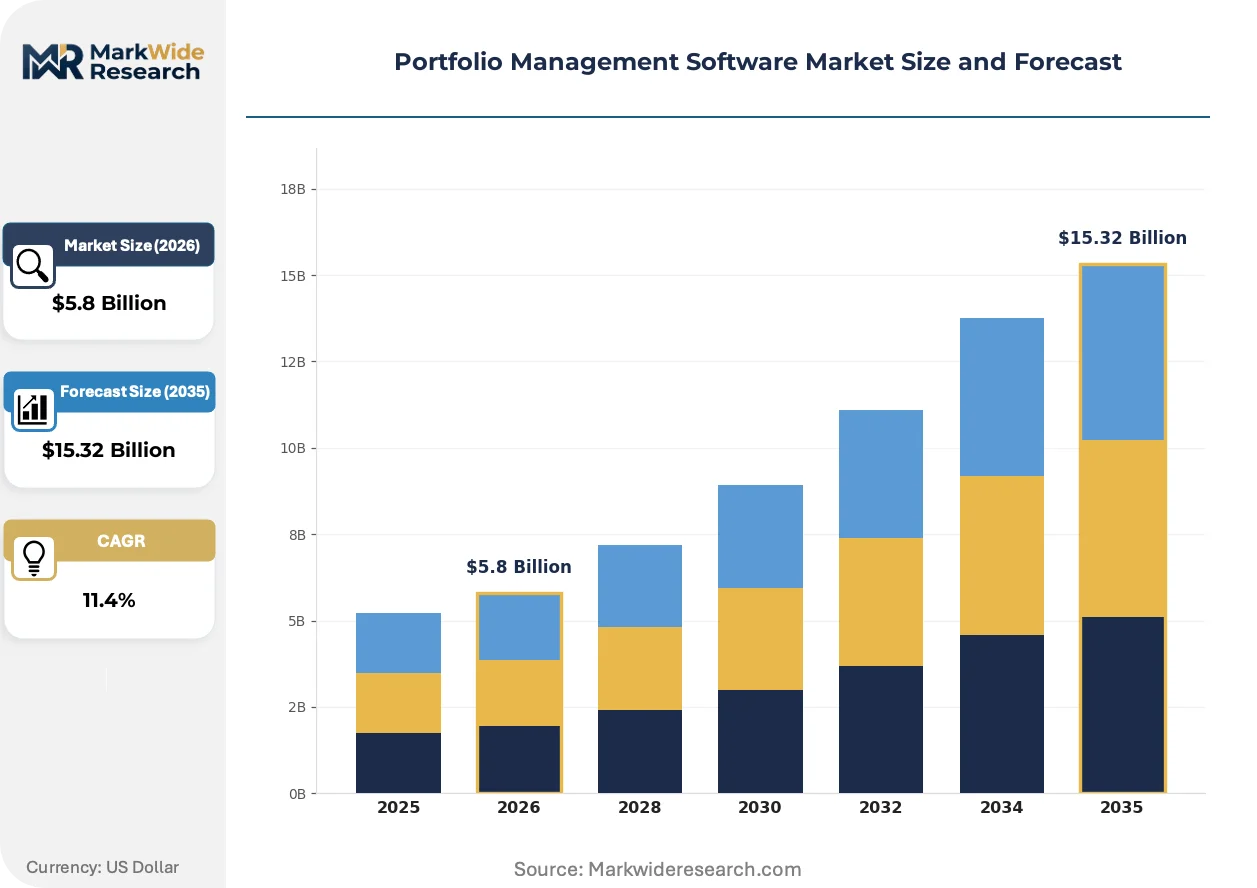
| Market Size in 2026 | $5.8 Billion |
| Market Size in 2035 | $15.32 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Investment Analytics, Risk Management Tools, Reporting Solutions, Trading Platforms End User: Asset Managers, Financial Advisors, Hedge Funds, Retail Investors Deployment: On-premise, Cloud-based, Hybrid, SaaS Investment Strategy: Active Management, Passive Management, Risk Parity, Factor Investing |
| Companies Covered | Oracle, ServiceNow, Atlassian, Smartsheet, Microsoft, Planview, Asana, SAP, Wrike, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Portfolio Management Software Market Emerging Trajectories
Generative AI and real-time data fabrics are compressing the latency between signal detection and position execution, while regulatory automation becomes a primary vendor selection criterion.
Large language models are rewriting how portfolio managers query unstructured data. Multi-asset desks at quantitative hedge funds now deploy natural language interfaces to interrogate earnings transcripts and central bank communications. This capability is compressing research-cycle timelines from days to hours.
The EU AI Act is mandating algorithmic accountability layers for automated trading systems. Vendors must now embed decision-audit trails and human-in-the-loop checkpoints. European asset managers are prioritizing platforms with pre-built compliance documentation modules.
Subscription pricing is displacing perpetual licenses across middle-market asset managers. Firms with $500 million to $5 billion AUM now favor usage-based contracts that scale with position volume. This shift is most visible among Boston-based registered investment advisors renegotiating vendor agreements.
Portfolio Management Software Market Segmentation
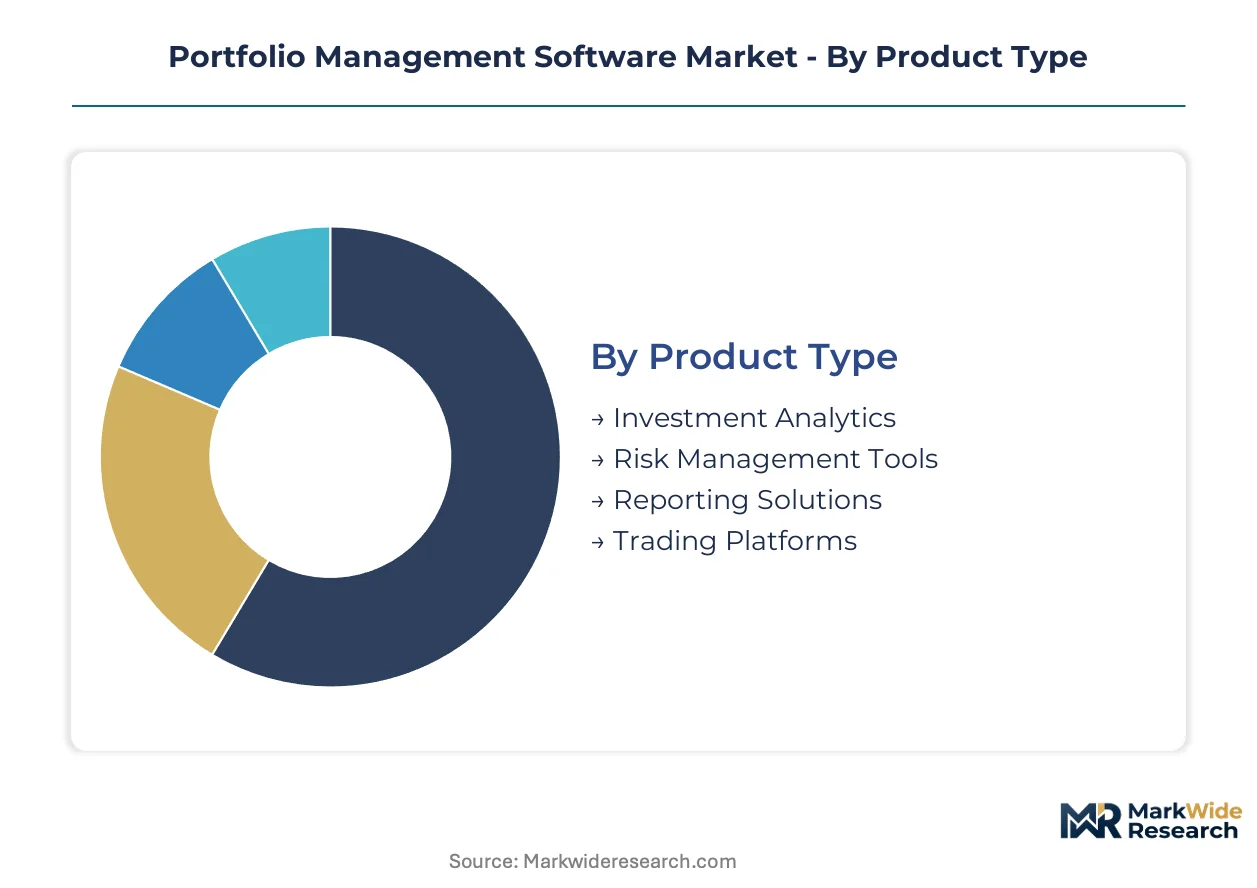
Portfolio management software segments diverge sharply in their compliance architectures. Investment Analytics platforms face lighter documentation burdens than algorithmic Trading Platforms, which must satisfy SEC Form PF automation and EU AI Act audit-trail mandates. Deployment mode further stratifies certification requirements, with cloud-native SaaS offerings navigating GDPR consent-engineering overhead that on-premise installations largely avoid.
Product Type:
SEC Form PF, EU AI Act, and Basel III reporting obligations map unevenly across product categories, with algorithmic trading components bearing the heaviest documentation burdens.
- Investment Analytics:These platforms aggregate multi-asset position data and run Monte Carlo simulations for portfolio optimization. Asset managers in New York and Boston dominate procurement, drawn by embedded risk visualization modules that satisfy institutional due diligence requirements. Mature margin pools characterize this segment, though vendors face pressure to integrate alternative data NLP pipelines.
- Risk Management Tools:Stress-testing engines calculate Value-at-Risk and counterparty exposure across derivative books. European insurers and banks drive replacement demand as Solvency II and Basel III deadlines tighten, with vendors embedding automated capital adequacy reporting to compress compliance timelines. This category is expanding most quickly as regulatory alignment needs intensify.
- Reporting Solutions:Automated SEC ADV and Form PF filing suites eliminate manual reconciliation for private funds. GDPR consent-tracking layers add engineering overhead for cross-border deployments.
- Trading Platforms:Low-latency execution systems serving sell-side institutions require sub-millisecond infrastructure. EU AI Act documentation mandates for algorithmic decision-audit trails are reshaping vendor development priorities.
Investment Analytics sits at the top of the volume ranking, with Risk Management Tools climbing the fastest.
End User:
Customer scale determines pricing architecture and implementation complexity, with enterprise asset managers demanding bespoke integrations that retail-facing platforms cannot economically support.
- Asset Managers:Institutional platforms process real-time feeds across equities, fixed income, and derivatives. New York and Boston firms prioritize cloud elasticity for overnight risk recalculations, while GDPR compliance adds 15-20% engineering overhead for EU mandates.
- Hedge Funds:Quantitative strategies require C++ and Python-native engines for signal generation and execution. Engineering talent scarcity inflates vendor R&D costs as these clients demand custom alternative data integrations.
- Financial Advisors:Registered investment advisors with under $100 million AUM remain underserved, creating white space for modular per-seat pricing.
- Retail Investors:Neobank-embedded portfolio modules are opening distribution beyond traditional sales cycles, though latency tolerance limits functionality.
Asset Managers command the largest installed base, with Hedge Funds gaining share fastest on alternative data demands.
Deployment:
Infrastructure choice shapes regulatory exposure and total cost of ownership, with hybrid architectures emerging as a risk-mitigation response to cloud concentration vulnerabilities.
- Cloud-based:Elastic compute supports Monte Carlo simulations without capital-intensive hardware. AWS, Azure, and Google Cloud concentration creates single-point-of-failure exposure during regional outages.
- SaaS:Subscription pricing displaces perpetual licenses among middle-market firms with $500 million to $5 billion AUM. Boston-based advisors are renegotiating vendor agreements toward usage-based contracts.
- On-premise:Air-gapped installations satisfy data residency requirements for sovereign wealth funds and defense-adjacent portfolios.
- Hybrid:Split architectures keep sensitive client data on-premise while leveraging cloud burst capacity for stress-testing.
Cloud-based deployments hold the volume lead, with SaaS showing the steepest expansion trajectory among renegotiating mid-market firms.
Investment Strategy:
Strategy complexity dictates data throughput requirements and the sophistication of algorithmic components subject to regulatory scrutiny.
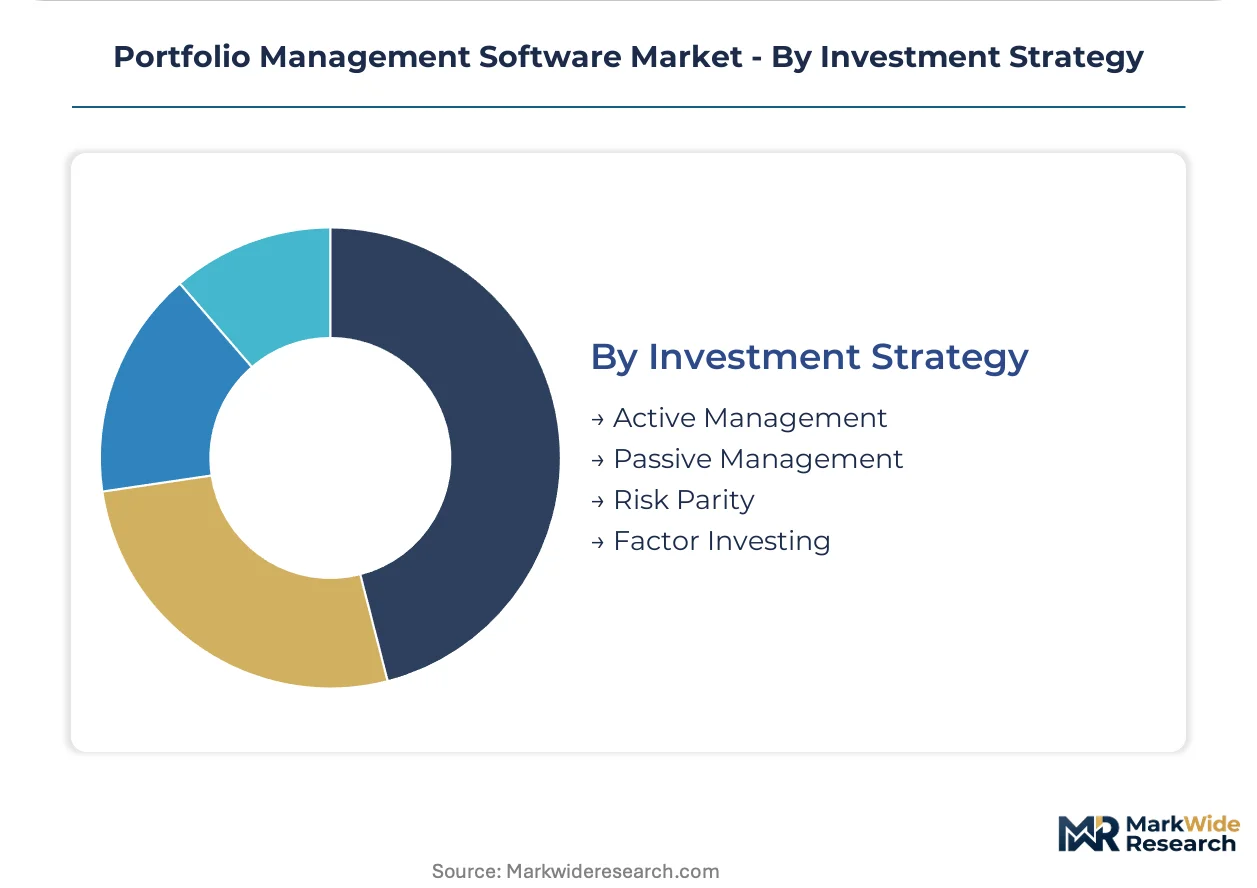
- Active Management:Discretionary and systematic strategies demand real-time analytics and rapid rebalancing capabilities. Managers require NLP pipelines for earnings transcript analysis, compressing research cycles from days to hours.
- Factor Investing:Smart beta and risk premia strategies need granular factor attribution engines. Quantitative desks prioritize platforms with pre-built factor libraries and custom factor construction tools.
- Passive Management:Index tracking minimizes trading intensity but requires precise cash equitization and corporate action processing.
- Risk Parity:Volatility-targeting approaches need dynamic leverage calibration across asset classes, stressing risk engine sophistication.
Active Management dominates platform revenue, with Factor Investing advancing fastest as quantitative allocation expands.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Portfolio management software originated in the United States during the 1980s, when Wall Street firms pioneered digital trading and risk calculation systems. The industry's historical roots in New York and Boston continue to shape geographic demand patterns today.
United States
Asset managers in New York and Boston drive procurement volume for cloud-native platforms with elastic compute capabilities. SEC Form PF and ADV filing automation requirements shape vendor product roadmaps. Manhattan-based hedge funds demand sub-millisecond latency infrastructure for quantitative strategies.
United Kingdom
London's asset management cluster prioritizes GDPR-compliant consent-tracking layers for cross-border data flows. The FCA's regulatory sandbox encourages fintech innovation in portfolio analytics. The City of London houses Europe's densest concentration of alternative data integration specialists.
Germany
Frankfurt-based insurers and banks upgrade risk engines to meet Solvency II and Basel III capital adequacy deadlines. BaFin's strict oversight accelerates replacement demand for compliance-automated platforms. Bavarian software vendors embed carbon accounting engines to address EU CSRD disclosure mandates.
Switzerland
Geneva and Zurich private banks seek air-gapped on-premise installations for sovereign wealth fund mandates. FINMA's cross-border asset management rules elevate data residency requirements. Swiss vendors differentiate through precision in multi-currency portfolio consolidation.
Singapore
Family offices and wealth managers in Singapore's financial district adopt modular per-seat pricing models. MAS licensing frameworks for digital asset service providers expand platform compliance scopes. The city-state's fintech hub status attracts vendors targeting Southeast Asian expansion.
Portfolio Management Software Market Vendor Landscape
The competitive structure tilts toward diversified technology conglomerates with database and cloud infrastructure heritage. Oracle, Microsoft, and SAP anchor enterprise-grade deployments through integrated analytics and workflow ecosystems. Three strategic archetypes dominate: database-native platforms leveraging existing data infrastructure, cloud-first vendors offering elastic subscription models, and ERP-embedded specialists connecting portfolio data with enterprise resource planning streams. M&A activity concentrates on alternative data pipeline acquisitions, while vendors prioritize API-first re-architecture to displace legacy mainframe installations.
Within the database-native tier, Oracle exemplifies enterprise anchoring through its heritage in financial data infrastructure. Microsoft occupies a position spanning cloud compute and productivity workflow integration. SAP represents the ERP-embedded archetype, connecting portfolio analytics with broader enterprise planning systems. These three conglomerates sit within a competitive set where vertical specialization in risk engines or trading latency separates mid-tier challengers from scale leaders.
| Leading Market Players |
|---|
| Oracle |
| ServiceNow |
| Atlassian |
| Smartsheet |
| Microsoft |
| Planview |
| Asana |
| SAP |
| Wrike |
| Others |
Supply Flow & Price Mechanics
Cloud-native re-architecture of core risk engines is simultaneously compressing vendor R&D cost structures and concentrating procurement leverage among hyperscale cloud providers. This dual transformation reshapes how portfolio management platforms are priced and delivered across buy-side and sell-side institutions.
Pricing Analysis
Subscription-based SaaS tiers with usage-scaled contracts now dominate middle-market asset manager procurement. Price differentiation rests on data throughput volume and embedded compliance automation depth. Cost compression in the sub-$5 billion AUM segment is intensifying because Boston-based advisors are consolidating vendor relationships. Registered investment advisors with under $100 million AUM exhibit the highest price sensitivity, while Manhattan hedge funds prioritize latency performance over per-seat economics.
Supply Chain Analysis
Single-source vulnerability sits with AWS, Azure, and Google Cloud for elastic compute capacity serving Monte Carlo simulations. Engineering talent concentrates in the United States, United Kingdom, and India for quantitative development. Raw material dependencies include proprietary risk model libraries, alternative data feed licenses, and regulatory compliance documentation modules. Tariff exposure on cross-border data flows threatens margin stability for EU-US dual-deployment platforms. Distribution runs through direct enterprise sales teams and strategic systems integrators serving asset manager technology procurement functions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The portfolio management software market functions as a regulatory compounder where EU AI Act audit-trail mandates and SEC Form PF automation requirements generate sustained replacement demand across compliance-automated platforms.
For Market Incumbents: Lock in enterprise asset manager relationships through API-first re-architecture that displaces legacy mainframe installations. Deepen embedded finance channel partnerships with neobanks seeking white-labeled portfolio modules. Prioritize carbon accounting engine development to address EU CSRD disclosure mandates before specialized ESG vendors capture this capability gap. For New Entrants and Emerging Players: Begin with modular per-seat pricing models targeting registered investment advisors with under $100 million AUM, the most underserved buyer archetype in the current landscape. Pursue Singapore family offices as the most penetrable geographic entry point given MAS licensing frameworks and regional expansion potential. Lead with natural language interfaces for earnings transcript analysis to differentiate against established analytics platforms. For Investors and Strategic Acquirers: Valuations sit cheapest among vertical specialists in alternative data pipeline integration and NLP-driven research automation. Long-term viability over the next decade hinges on regulatory automation depth rather than raw computational performance. Watch for EU AI Act enforcement actions as the critical inflection signal for compliance-documentation platform demand.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Connects portfolio analytics with SAP and Oracle ERP streams for unified enterprise planning. |
| Acquisition of Specialist Firm | Captures alternative data pipeline capabilities for satellite imagery and social sentiment feeds. |
| Strategic Partnership | Secures AWS or Azure committed use discounts to lower cloud concentration cost exposure. |
| Product Launch | Introduces pre-built EU AI Act compliance documentation modules for European asset managers. |
| Geographic Expansion | Establishes Singapore presence to serve Southeast Asian family offices and wealth managers. |
Methodological Framework
Direct dialogue with CTOs at asset management firms, quantitative hedge fund technology officers, compliance documentation specialists, and cloud procurement leads grounded the primary research foundation. Secondary validation drew from SEC Form PF filing disclosures, BaFin regulatory guidance documents, EU AI Act implementation texts, and hyperscaler infrastructure investment reports. Bottom-up segment sizing triangulated against top-down market aggregation to ensure consistency across deployment models and end-user categories.
Market size and growth trajectory outputs were derived through multi-dimensional segmentation modeling across product type, deployment architecture, organization scale, investment strategy complexity, and regional regulatory cluster. CAGRs were calculated from fitted growth curves incorporating technology adoption S-cycles and regulatory deadline impacts. Industry-specific inputs included cloud infrastructure pricing trends, quantitative developer compensation inflation, and compliance engineering overhead estimates for cross-border data residency requirements.
Caveats apply where EU AI Act enforcement intensity, SEC reporting mandate revisions, or hyperscale cloud regional outages could materially shift the outlook. Forecasts reflect assumptions about regulatory timeline adherence and technology migration pace that may prove optimistic or conservative. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Portfolio Management and Asset Allocation
Balanced Funds Market
Portfolio Management and Asset Allocation
Portfolio Analytics Market
Portfolio Management and Asset Allocation
Corporate Performance Management Market
Portfolio Management and Asset Allocation
UK Mutual Funds Market
Portfolio Management and Asset Allocation
United States Project Portfolio Management Market
Portfolio Management and Asset Allocation
Germany Mutual Funds Market
Portfolio Management and Asset Allocation
US Mutual Funds Market
Portfolio Management and Asset Allocation
Global Project Portfolio Management (PPM) Market
Portfolio Management and Asset Allocation
Energy Portfolio Management Market