
 Wealth Management Software Market | 2026-2036
Wealth Management Software Market Size, Share, and Industry Trends Forecast 2026-2036
Wealth Management Software Market Intelligence
Subscription-based project finance for cloud infrastructure is reconfiguring how wealth management software vendors scale without heavy capital expenditure. SS&C Technologies leverages its custody and fund-administration backbone to anchor enterprise deployments across multi-billion-dollar advisory practices. Envestnet sustains dominance in unified data aggregation, competing through open-architecture APIs that connect thousands of third-party applications. BlackRock differentiates via its Aladdin risk engine, which extends portfolio analytics from institutional clients down to registered investment advisors seeking institutional-grade tooling.
Wealth management software comprises integrated digital platforms that automate portfolio construction, rebalancing, tax-loss harvesting, and client reporting through algorithmic engines processing real-time market data feeds and custodial file formats. These systems serve as the operational core for financial advisors, replacing spreadsheet-based workflows with centralized dashboards that sync positions, transactions, and performance across multiple account structures. Cloud-based deployment leads adoption momentum as advisory firms abandon server maintenance, while SaaS pricing captures recurring revenue streams that outpace one-time license models. Financial Planning and Investment Advisory solutions command premium positioning due to embedded fiduciary compliance logic, whereas Portfolio Management functions approach maturity with compressed differentiation among incumbent vendors.
SEC oversight under the Investment Advisers Act shapes product roadmaps by mandating audit trails, best-execution documentation, and Form ADV disclosure automation within advisor-facing platforms. The EU's GDPR and the forthcoming EU AI Act impose cross-border data residency and algorithmic transparency requirements that constrain how US-centric vendors architect multi-tenant environments for European clients. Stakeholders must weigh whether to build compliance-native infrastructure or retrofit existing stacks as regulatory fragmentation between Washington and Brussels intensifies.
Market Dynamics
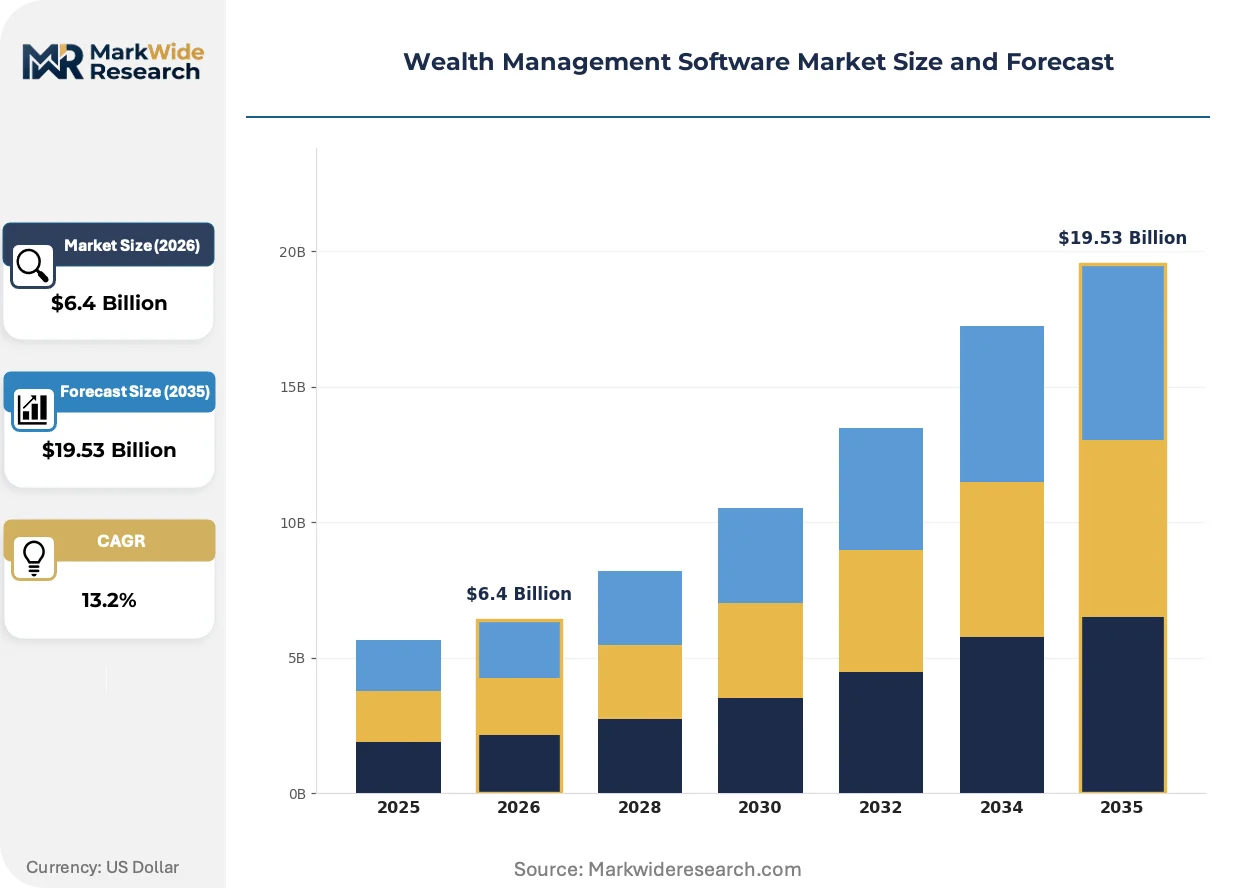
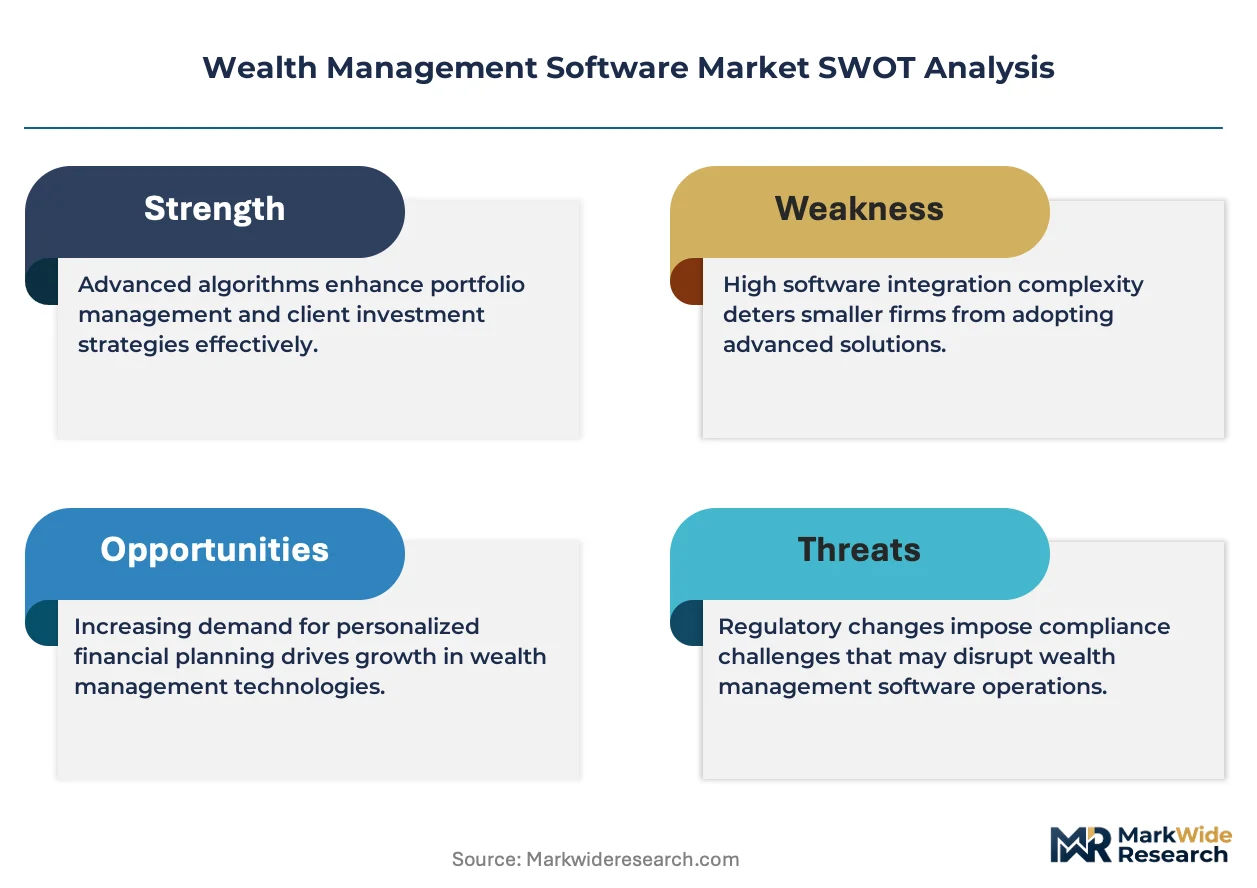
Asset-light SaaS licensing is compressing capital barriers for independent registered investment advisors, while SEC fiduciary enforcement and GDPR data residency mandates are forcing vendors to rebuild compliance-native architectures rather than retrofit legacy stacks.
Growth Catalysts
- SEC Investment Advisers Act enforcement:Audit trail mandates and Form ADV automation requirements compel advisory firms to abandon spreadsheet workflows for centralized platforms.
- Cloud-native rebalancing engines:Real-time tax-loss harvesting and algorithmic portfolio construction replace manual quarterly reviews, cutting operational drag for multi-custodial practices.
- United States advisor migration:Registered investment advisors are consolidating onto unified dashboards, eliminating server maintenance overhead and accelerating platform consolidation.
Market Restraints
- Cross-border data fragmentation:GDPR residency requirements and forthcoming EU AI Act algorithmic transparency rules constrain US-centric vendors from serving European clients through single-tenant architectures.
- Custodial file format heterogeneity:Proprietary data schemas from legacy custodians impose integration costs that compress margins for mid-tier software providers.
- Specialized compliance engineering talent scarcity:Shortages of developers versed in both securities regulation and distributed systems limit vendor roadmap velocity.
Strategic Opportunities
- EU AI Act preparation services:Algorithmic explainability tooling and model documentation automation create premium service layers for vendors serving cross-border advisory firms.
- Direct indexing infrastructure:Separately managed account platforms that automate custom equity baskets at scale open retail-adjacent segments beyond traditional high-net-worth channels.
- Embedded insurance-annuity workflows:Converging wealth and protection product data models onto unified advisor dashboards captures recurring revenue from holistic planning mandates.
Industry Challenges
- Legacy system API fragmentation:Decades-old custodial mainframes lack real-time data feeds, forcing middleware layers that degrade user experience and inflate implementation timelines.
- Fiduciary liability engineering:Best-execution documentation and recommendation audit trails require product teams to embed legal logic deep in algorithmic engines, slowing release cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Wealth Management Software Market |
| Market Size in 2026 | $6.4 Billion |
| Market Size in 2035 | $19.53 Billion |
| CAGR (2026 – 2036) | 13.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: On-Premises, Cloud-Based, Hybrid, SaaS End User: Individual Investors, Financial Advisors, Institutions, Banks Solution: Portfolio Management, Risk Management, Financial Planning, Investment Advisory Pricing Model: Subscription, One-Time License, Freemium, Tiered Pricing |
| Companies Covered | SS&C Technologies, Envestnet, Fidelity Investments, BlackRock, Charles Schwab, Orion Advisor Tech, Morningstar, Fiserv, Broadridge Financial Solutions, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Wealth Management Software Market Strategic Shifts & Innovations
Generative interfaces and embedded compliance automation are compressing the gap between institutional-grade risk tooling and advisor-facing platforms, reshaping how software vendors capture recurring revenue.
Artificial intelligence is hybridizing portfolio analytics by merging natural language generation with quantitative risk engines. Mid-sized registered investment advisors are adopting these tools fastest, seeking institutional-grade reporting without dedicated quant teams. This convergence is hybridizing vendor competitive positioning, compressing differentiation between premium and standard platform tiers.
GDPR and the EU AI Act are mandating algorithmic transparency and data residency controls that fragment multi-tenant cloud architectures. Vendors must now maintain separate infrastructure stacks for European clients or absorb compliance retrofit costs. Cross-border advisory firms with US and EU operations face the steepest architectural decisions, with some segmenting client bases by jurisdiction to limit exposure.
Advisory firms are unbundling implementation and ongoing platform support, treating software as a commodity while paying premiums for specialized data migration and change management. Independent broker-dealers and hybrid RIAs are driving this shift, separating vendor selection from deployment partner contracts. This pattern is most pronounced in the United States, where advisor headcount growth outpaces internal technology staffing.
Wealth Management Software Market Segmentation
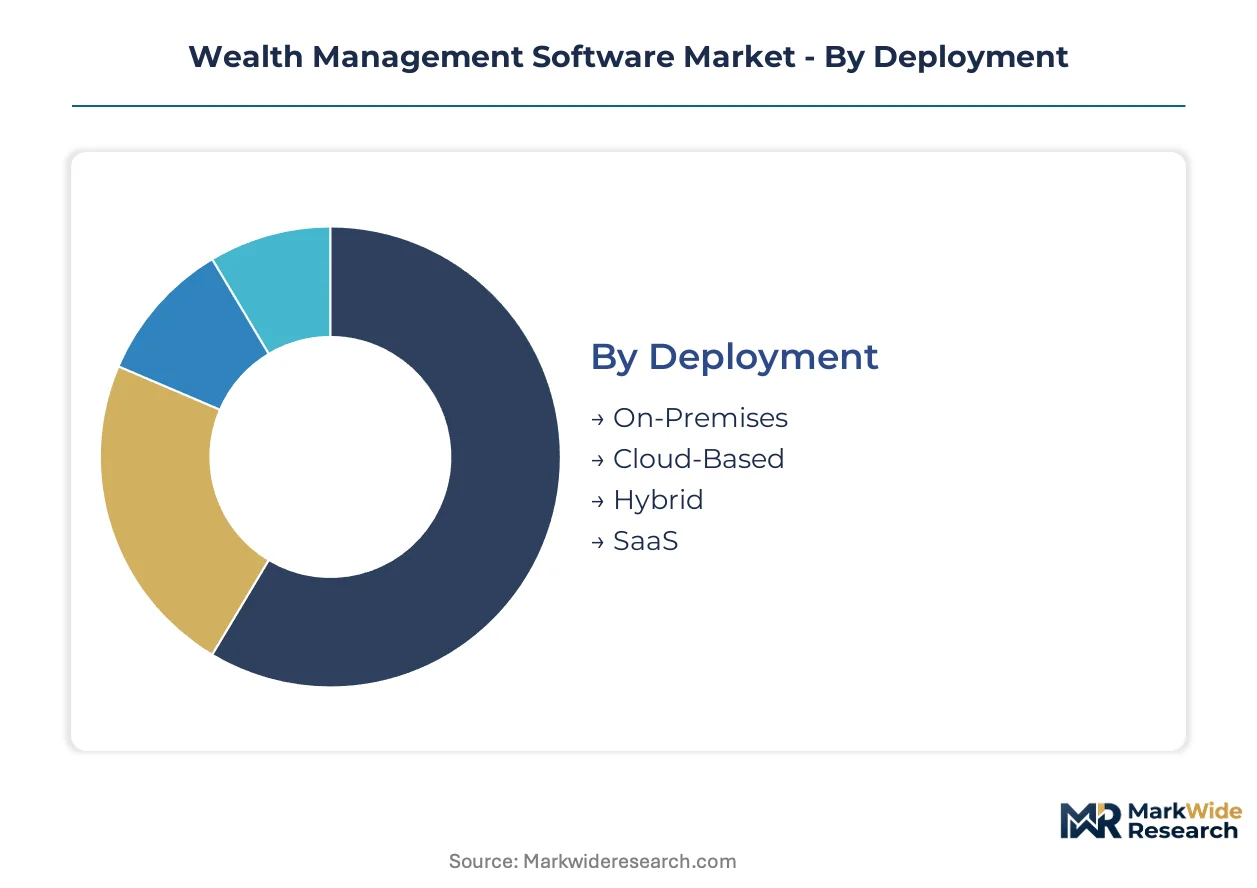
Deployment architecture determines refresh cycles across wealth management software, with cloud-native platforms turning over every 18-24 months while legacy on-premises installations persist for 7-10 years. End-user sophistication and regulatory exposure further stratify replacement velocity, creating tiered upgrade patterns that vendors must map against recurring revenue models.
Deployment:
Cloud-based deployments compress replacement cycles to 18-24 months as vendors push continuous feature releases, while on-premises installations stagnate for 7-10 years until hardware obsolescence or compliance mandates force migration.
- Cloud-Based:Multi-tenant architectures with automatic security patching and API-first integration frameworks. Demand concentrates among registered investment advisors in the United States seeking to eliminate server maintenance overhead while satisfying SEC audit trail mandates through centralized data repositories.
- SaaS:Subscription licensing with usage-based scaling and embedded compliance automation. Advisory firms in California and New York are adopting these platforms fastest, drawn by recurring-fee predictability and rapid deployment timelines that bypass traditional IT procurement cycles.
- On-Premises:Legacy server installations with custom configuration control and air-gapped security for ultra-high-net-worth family offices.
- Hybrid:Split architectures retaining sensitive client data locally while leveraging cloud analytics engines.
On-Premises dominates installed base. Cloud-Based is where expansion concentrates.
End User:
Institutional clients drive the longest sales cycles at 12-18 months due to procurement committees and security reviews, while individual investors convert through self-service onboarding in under 48 hours.
- Financial Advisors:Registered investment advisors and hybrid RIA-broker-dealer practitioners managing $50M-$500M in assets under management. These practitioners across Texas and Florida are consolidating onto unified dashboards that sync multi-custodial positions, replacing fragmented spreadsheet workflows with algorithmic rebalancing engines.
- Institutions:Pension funds, endowments, and asset managers with dedicated compliance teams and custom integration requirements. Demand clusters in Massachusetts and Illinois where multi-billion-dollar advisory practices require institutional-grade risk analytics and bespoke reporting waterfalls.
- Banks:Regional and community banks with wealth management divisions seeking white-labeled platforms.
- Individual Investors:Self-directed retail users accessing robo-advisory tools through mobile-first interfaces.
Financial Advisors represent the fastest-growing trajectory. Institutions anchor average contract value.
Solution:
Portfolio management functions approach technical maturity with compressed vendor differentiation, while financial planning modules command premium positioning through embedded fiduciary logic and tax-optimization engines.
- Financial Planning:Goal-based projection engines integrating cash flow modeling, estate planning workflows, and insurance-annuity convergence. Advisory practices in Pennsylvania and Ohio are adopting these tools to capture holistic planning mandates and justify ongoing retainer fees through documented value delivery.
- Investment Advisory:Algorithmic recommendation engines with best-execution documentation and Form ADV disclosure automation. Firms in Washington and Colorado are deploying these platforms to preempt SEC enforcement actions while scaling personalized advice across expanding client books.
- Portfolio Management:Real-time rebalancing, tax-loss harvesting, and performance attribution across multi-custodial account structures.
- Risk Management:Stress testing, scenario analysis, and regulatory capital calculation engines for institutional compliance.
Portfolio Management dominates installed base. Financial Planning is where expansion concentrates.
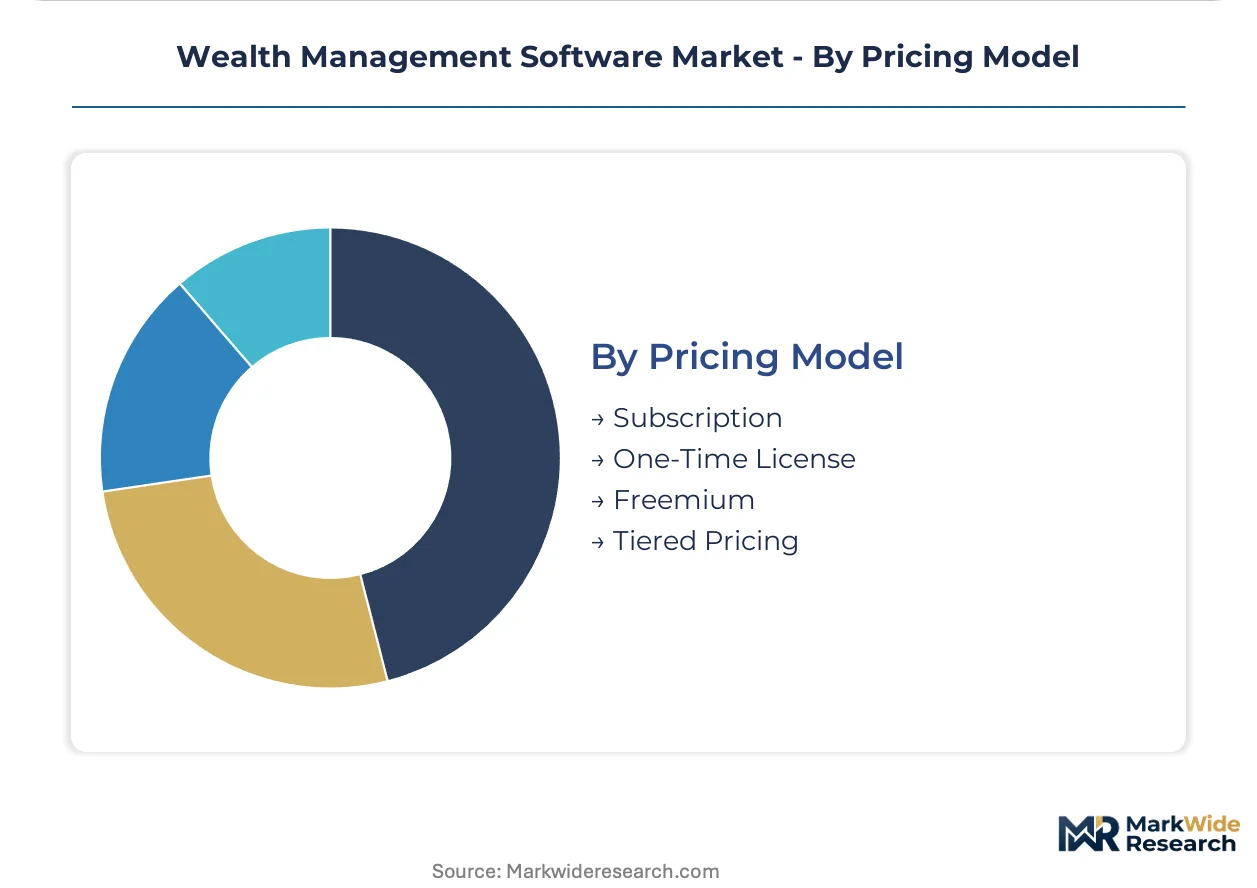
Pricing Model:
Subscription structures align vendor incentives with client success metrics, while one-time licenses create misaligned support incentives and deferred upgrade revenue.
- Subscription:Monthly or annual recurring fees tied to assets under management or advisor seat counts. Independent RIAs across Arizona and North Carolina are migrating to these models to convert capital expenditure into predictable operating expenses while accessing continuous platform improvements.
- Tiered Pricing:Feature-gated packages separating basic portfolio accounting from advanced analytics and white-label customization. Broker-dealers in Georgia and Michigan are negotiating these structures to match software capabilities against advisor productivity tiers.
- One-Time License:Perpetual usage rights with annual maintenance contracts for legacy system support.
- Freemium:Limited-feature entry tiers converting to paid subscriptions through usage thresholds or advanced functionality unlocks.
One-Time License dominates installed base. Subscription is where expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States runs a substantial trade surplus in wealth management software services, exporting SaaS platforms to advisory firms across Canada, the United Kingdom, and Australia while importing minimal competing solutions. This export dominance reflects concentrated vendor development in financial technology corridors and established regulatory frameworks that validate platform credibility abroad.
United States
Registered investment advisors in Texas and Florida are consolidating onto cloud-native dashboards, eliminating legacy server maintenance. SEC enforcement under the Investment Advisers Act mandates audit trails and Form ADV automation that drive platform replacement cycles. Boston anchors institutional-grade deployments where multi-billion-dollar practices demand bespoke risk analytics and unified data aggregation.
United Kingdom
Wealth managers in London and Edinburgh are adopting API-first architectures to connect fragmented legacy systems. GDPR data residency requirements and forthcoming FCA Consumer Duty rules compel vendors to maintain UK-specific infrastructure stacks. The City of London cluster concentrates demand for white-labeled platforms serving high-net-worth family offices with cross-border compliance needs.
Germany
Private banks in Bavaria and Baden-Württemberg are migrating from on-premises portfolio accounting to SaaS models. BaFin supervision and EU AI Act algorithmic transparency mandates force architectural decisions about model documentation and explainability tooling. Frankfurt's wealth management hub drives demand for embedded compliance automation that satisfies both German and cross-border regulatory requirements.
Canada
Independent advisory practices in Ontario and British Columbia are adopting subscription-based platforms to convert capital expenditure into predictable operating costs. CIRO oversight and provincial securities commission disclosure rules elevate requirements for centralized client reporting. Toronto's financial district concentrates vendor sales activity targeting mid-sized firms with hybrid RIA-broker-dealer structures.
Australia
Self-managed superannuation fund advisors in New South Wales and Victoria are deploying direct indexing infrastructure for custom equity basket automation. ASIC regulatory guidance on best-interest duties and fee disclosure shapes product roadmaps for recommendation engines. Sydney's wealth technology cluster supports regional expansion by US and UK vendors seeking Asia-Pacific market entry.
Wealth Management Software Market Key Industry Players
On the supply side, the industry is consolidating around custody-anchored incumbents, open-architecture aggregators, and risk-engine specialists. Three strategic archetypes dominate: custodial backbone providers leveraging fund administration scale, data aggregation platforms connecting third-party application ecosystems, and institutional risk engine vendors extending tooling downstream to advisory practices. Competitive moves concentrate on API ecosystem expansion and embedded compliance automation rather than price-based rivalry.
Within the custody-anchored tier, SS&C Technologies exemplifies scale-driven positioning through its fund administration backbone, while Envestnet occupies the data aggregation archetype with open-architecture connectivity. BlackRock represents the risk-engine specialist vector, extending institutional-grade analytics to registered investment advisors. These three entities anchor competitive dynamics by defining the technical standards and integration frameworks that mid-tier vendors must accommodate.
| Leading Market Players |
|---|
| SS&C Technologies |
| Envestnet |
| Fidelity Investments |
| BlackRock |
| Charles Schwab |
| Orion Advisor Tech |
| Morningstar |
| Fiserv |
| Broadridge Financial Solutions |
| Others |
Cost & Logistics Intelligence
The Trans-Atlantic fiber corridor carries real-time market data feeds from New York and London into cloud-native wealth management platforms, with bandwidth costs compressing margins for mid-tier SaaS vendors while amplifying pricing power for custody-anchored incumbents who absorb these logistics expenses through scale. This infrastructure asymmetry forces independent software providers to tier pricing aggressively around data latency guarantees, separating premium sub-10-millisecond feeds from standard tiers that tolerate cross-border routing delays.
Pricing Analysis
Enterprise advisory practices anchor subscription pricing across the wealth management software landscape, with three-tier structures separating custody-integrated enterprise suites from modular advisor workstations and entry-level planning tools. Price differentiation hinges on embedded compliance automation depth and API connection density to third-party custodians, with SEC audit trail mandates driving premium tier premiums. Cost compression in the mid-market intensifies as independent RIAs migrate from perpetual licenses to SaaS models, eroding upfront revenue recognition. Individual self-directed investors exhibit highest price sensitivity, converting through freemium tiers at sub-$50 monthly thresholds before upgrading to tax-optimization modules.
Supply Chain Analysis
Upstream software development talent concentrates in the United States, India, and Ireland, with engineering centers in Bangalore and Dublin feeding cloud infrastructure codebases that power multi-tenant advisor platforms. Raw material dependencies include proprietary custodial data schemas from legacy mainframe systems, real-time market data feeds from exchanges, and compliance logic engines certified for SEC and GDPR jurisdictions. Single-source vulnerability runs through dominant custody data aggregators whose file format specifications dictate integration architecture for downstream vendors. Distribution runs through direct enterprise sales teams targeting billion-dollar advisory practices, supplemented by channel partnerships with broker-dealer networks and independent RIA consolidators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Wealth management software is approaching a platform-economics inflection where custody-anchored incumbents, open-architecture aggregators, and risk-engine specialists are consolidating around API interoperability standards that determine which vendors capture advisor workflow lock-in.
For Market Incumbents: Harden custody data integration moats by embedding proprietary file format handlers directly into advisor-facing dashboards, neutralizing middleware-dependent challengers. Acquire specialized compliance engineering teams in Massachusetts and Texas to accelerate EU AI Act documentation tooling before cross-border competitors retrofit equivalent capabilities. Prioritize direct indexing infrastructure investments that capture separately managed account workflows before asset-light entrants commoditize custom equity basket automation. For New Entrants and Emerging Players: Canadian mid-sized hybrid RIA-broker-dealers present the most penetrable geographic white space, with CIRO oversight elevating compliance requirements that incumbent vendors serve inadequately through US-centric platforms. Target embedded insurance-annuity workflow convergence as the fastest-adjacent segment, capturing recurring revenue from holistic planning mandates that established portfolio management vendors address through bolt-on partnerships rather than native data models. Lead with change-management services that unbundle implementation from software licensing, mirroring the advisory firm procurement shift documented across Ontario and British Columbia. For Investors and Strategic Acquirers: Algorithmic explainability tooling vendors serving cross-border EU-US advisory firms represent the highest-conviction acquisition archetype, with regulatory fragmentation creating durable demand for compliance-native infrastructure. Long-term viability centers on vendors who architect multi-tenant stacks for jurisdictional data residency from inception rather than retrofitting legacy single-tenant deployments. Watch for SEC enforcement patterns around best-execution documentation as the signal indicating which compliance automation layers will command sustained premium pricing versus commodity feature parity.| Strategic Initiative | Industry Significance |
|---|---|
| API Ecosystem Expansion | Open-architecture connectivity to thousands of third-party applications locks advisor workflows onto unified data aggregation platforms. |
| Embedded Compliance Automation | Native SEC audit trail and Form ADV disclosure logic accelerates platform replacement cycles among enforcement-exposed advisory practices. |
| Direct Indexing Infrastructure | Separately managed account automation opens retail-adjacent segments beyond traditional high-net-worth advisory channels. |
| EU AI Act Preparation Services | Algorithmic explainability tooling creates premium service layers for cross-border firms facing Brussels algorithmic transparency mandates. |
| Strategic Partnership | Custody backbone alliances with fund administration specialists anchor enterprise deployments across multi-billion-dollar advisory practices. |
Research Approach
A standing panel of chief technology officers at registered investment advisors, compliance officers at hybrid RIA-broker-dealers, custodial data integration specialists, and platform procurement leads at independent advisory consolidators provided ongoing calibration across primary interview cycles. Secondary validation drew from SEC Investment Advisers Act enforcement records, Form ADV filing databases, EU AI Act draft documentation, hyperscaler cloud infrastructure capex disclosures, and custodial file format specification repositories. Bottom-up deployment counts by advisor headcount and assets under management were triangulated against top-down vendor revenue segmentation across the analysis window.
Scenario bracketing anchored projections across cloud-native migration velocity, regulatory enforcement intensity, and cross-border data residency fragmentation. Segmentation dimensions modeled include deployment architecture, end-user sophistication tier, solution functional module, and regional regulatory cluster. CAGRs were derived from advisor headcount growth trajectories, platform replacement cycle compression, and SaaS pricing penetration curves. Industry-specific forecast inputs incorporated SEC examination priority shifts and EU AI Act implementation timelines affecting algorithmic transparency requirements.
The forecast holds incumbent behavior within observed patterns; aggressive vertical integration into custody infrastructure by software specialists or rapid consolidation among mid-tier aggregators would shift outcomes materially from projected trajectories. Cross-checking against advisor technology spending surveys and custodial platform migration announcements is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Wealth Management and Private Banking
Digital Wealth Management Market
Wealth Management and Private Banking
High Net Worth (HNW) Offshore Investment Market
Wealth Management and Private Banking
Europe Wealth Management Market
Wealth Management and Private Banking
Family Office Services Market
Wealth Management and Private Banking
Asia Pacific Private Banking Market
Wealth Management and Private Banking
Global Wealth Management Platform Market
Wealth Management and Private Banking
Family Offices Market
Wealth Management and Private Banking
Private Banking Market
Wealth Management and Private Banking
India Private Banking Market
Wealth Management and Private Banking
Family Office Software for Financial Management Market
Wealth Management and Private Banking
United States Private Banking Market
Wealth Management and Private Banking
Japan Private Banking Market
Wealth Management and Private Banking
UK Pension Fund Market
Wealth Management and Private Banking
Latin America Wealth Management Market
Wealth Management and Private Banking
Wealth Management Market
Wealth Management and Private Banking
Smart Wealth Management Market