
 Financial Consolidation Software Market | 2026-2036
Financial Consolidation Software Market Size, Share, and Industry Trends Forecast 2026-2036
Financial Consolidation Software Market Foresight
Buyer concentration among Fortune 500 multinationals is hardening as these organizations consolidate vendor relationships around fewer strategic platforms. Oracle sustains deep entrenchment in enterprise resource planning ecosystems that feed directly into consolidation workflows. OneStream differentiates through unified performance management architecture that collapses planning and close processes into one environment. SAP anchors market presence with decades of installed base across European headquarters of global conglomerates.
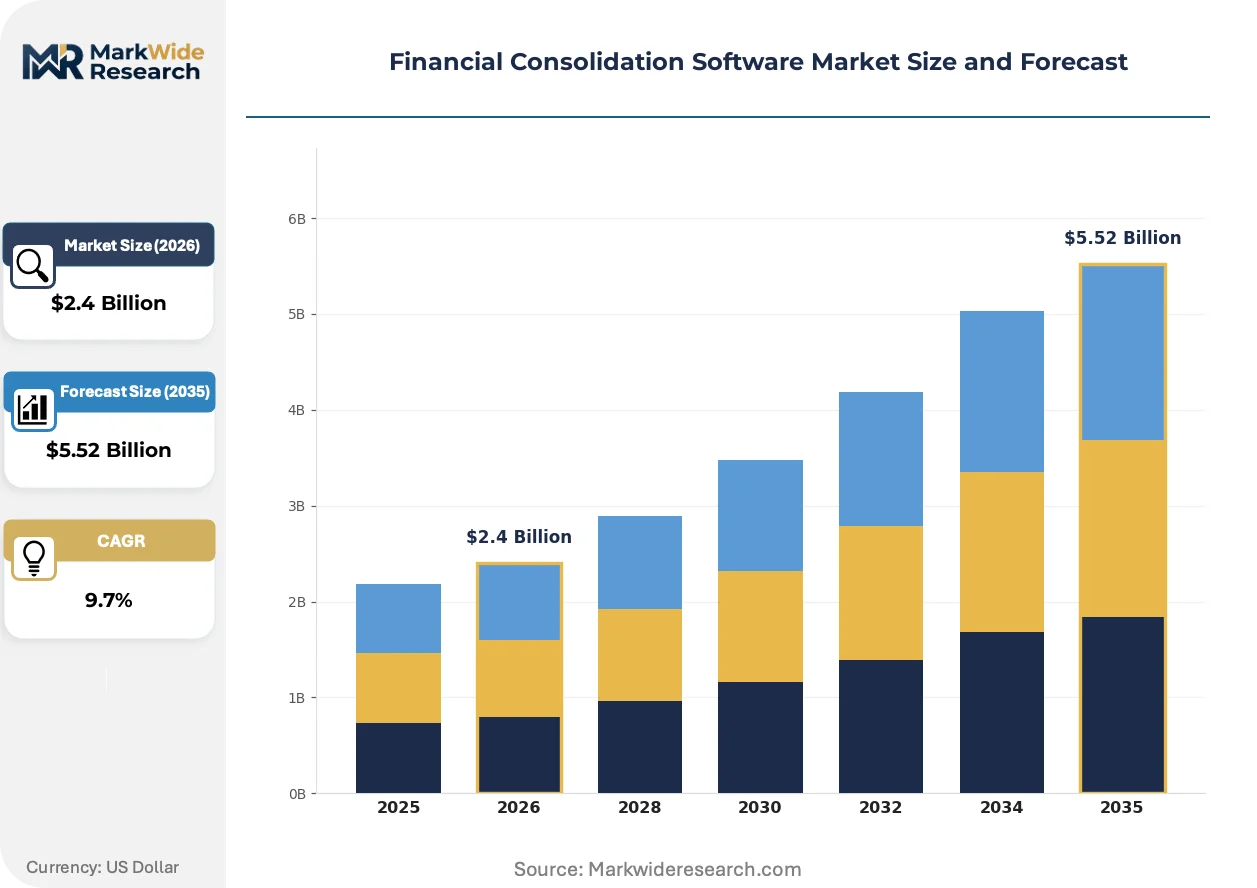
Financial consolidation software automates the aggregation, elimination, and currency translation of subsidiary financial data into parent-company statements, typically handling intercompany reconciliations, minority interest calculations, and GAAP-to-IFRS adjustments within a single controlled workflow. Cloud-based deployment now leads new procurement decisions as finance teams prioritize remote accessibility and reduced infrastructure overhead over on-premise control. The SME end-user segment represents the fastest expansion pool, though large enterprises still occupy the dominant share of annual contract value due to multi-entity complexity and regulatory filing volume.
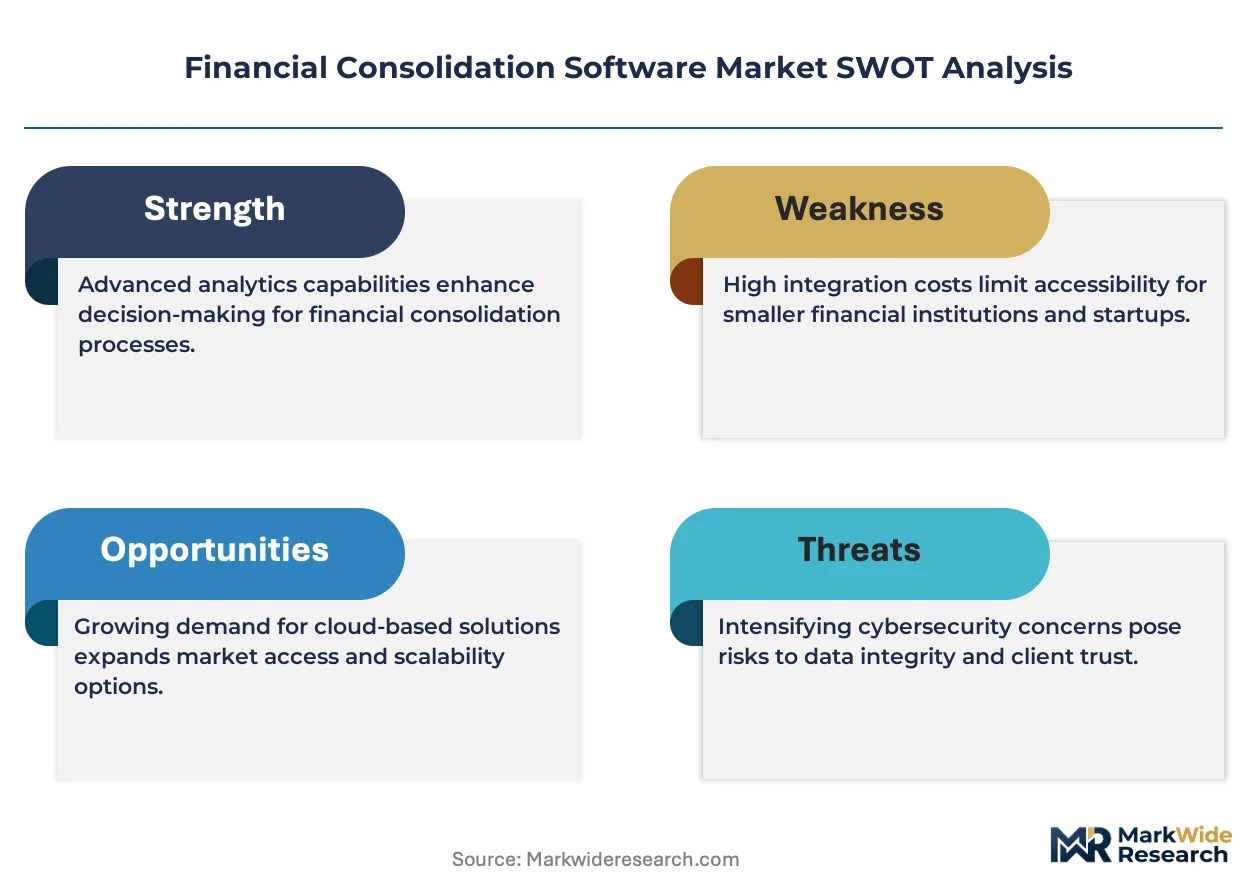
The US SEC enforces strict electronic filing standards through its EDGAR system, while the EU CSRD mandates granular sustainability disclosures that ripple into consolidated reporting templates. ISO 27001 certification has become a baseline procurement filter for financial data platforms handling audited statements across borders. Stakeholders must monitor how AI-generated narrative disclosures reshape auditor liability frameworks and procurement criteria for consolidation tools.
Market Dynamics
Cloud migration is compressing deployment cycles for financial consolidation platforms as finance teams abandon multi-year on-premise implementations for configurable SaaS architectures. This shift is collapsing the traditional vendor lock-in patterns that previously protected incumbent ERP ecosystems.
Growth Catalysts
- CSRD-aligned sustainability reporting:The EU's Corporate Sustainability Reporting Directive mandates granular ESG disclosures that ripple into consolidated financial templates. Mittelstand firms in Germany are accelerating platform upgrades to capture Scope 3 emissions data within group reporting workflows.
- Intercompany reconciliation automation:AI-powered matching engines are eliminating manual elimination entries for complex subsidiary structures. Multinational corporations with 50-plus entities are deploying these tools to compress month-end close timelines.
- US SEC electronic filing enforcement:The EDGAR system's XBRL validation requirements are forcing audit-ready consolidation tools into mandatory procurement cycles. Public filers are prioritizing platforms with embedded validation engines to reduce restatement risk.
Market Restraints
- Implementation cost concentration:Data migration from legacy hyperion installations consumes 40-60% of total project spend. Mid-market buyers are deferring upgrades due to professional services sticker shock.
- Cloud concentration risk:AWS and Azure host the majority of SaaS consolidation platforms. Finance executives cite vendor lock-in concerns around egress fees and regional data residency requirements.
- Functional substitution by ERP modules:SAP S/4HANA and Oracle Fusion are embedding consolidation capabilities into core licensing. Standalone platform vendors face displacement pressure from bundled pricing.
Strategic Opportunities
- Underpenetrated SME segment:Private equity-backed mid-market rollups in the US and UK are creating multi-entity complexity without enterprise-scale IT budgets. Vendors are packaging pre-configured consolidation templates for 10-50 entity structures.
- AI-generated narrative disclosure:Large language models are automating MD&A drafting from consolidated data. Early adopters in the UK are piloting tools that draft regulatory footnotes from structured trial balances.
- Embedded ESG data pipelines:Convergence between carbon accounting APIs and consolidation platforms is enabling real-time sustainability reporting. Vendors are partnering with emissions data providers to pre-map Scope 1-3 calculations to group reporting lines.
Industry Challenges
- Technical accounting talent scarcity:Complex equity method calculations and currency translation mechanics require specialized expertise. Implementation partners report 6-12 month backlogs for certified consolidation specialists.
- Legacy system integration friction:SAP ECC and Oracle EBS instances with decades of custom configurations resist standardized data extraction. Finance teams are rebuilding chart of account mappings for each subsidiary.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Financial Consolidation Software Market |
| Market Size in 2026 | $2.4 Billion |
| Market Size in 2035 | $5.52 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
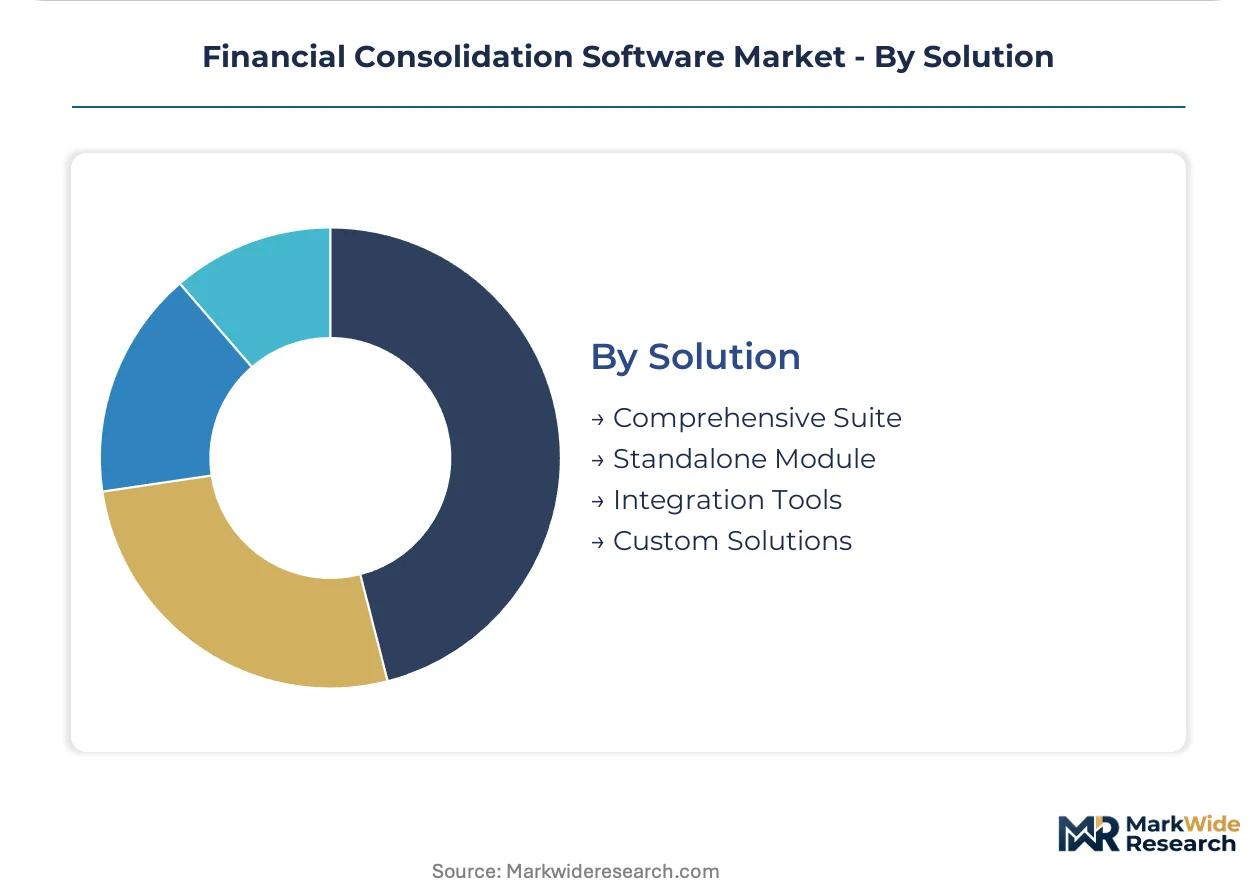
| Segmentation | Deployment: On-Premise, Cloud-Based, Hybrid, SaaS End User: Large Enterprises, SMEs, Financial Institutions, Government Feature: Automated Reporting, Multi-Currency Support, Data Integration, Audit Trails Solution: Comprehensive Suite, Standalone Module, Integration Tools, Custom Solutions |
| Companies Covered | SAP, Oracle, OneStream, Wolters Kluwer, BlackLine, Workday, Anaplan, Joiin, Fathom, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Financial Consolidation Software Market Shifts & Advancements
Artificial intelligence is penetrating financial consolidation workflows through three distinct vectors: automated reconciliation engines, narrative generation tools, and predictive close analytics. These capabilities are compressing the traditional boundaries between record-to-report and planning processes.
Embedded AI matching engines are modularizing intercompany reconciliation workflows by replacing rule-based elimination logic with probabilistic matching algorithms. Fortune 500 shared service centers are deploying these tools to process millions of monthly intercompany transactions without manual intervention. The technology is modularizing the close calendar by collapsing reconciliation from weeks to days.
The EU CSRD is forcing sustainability data architecture into consolidation platforms through mandatory double materiality assessments. Reporting entities must now capture environmental impact data across subsidiary operations and translate these into consolidated disclosures. European headquarters of global conglomerates are most affected, with many mandating ISO 27001-certified platforms that can handle audited ESG statements across borders.
Subscription-based pricing models are displacing perpetual license structures as finance teams prioritize operational expenditure treatment over capital investment. Mid-market buyers are negotiating consumption-based contracts that scale with entity count rather than user seats. This shift is most visible in the UK and US, where private equity portfolio companies are standardizing on SaaS consolidation stacks during platform buildouts.
Financial Consolidation Software Market Segmentation
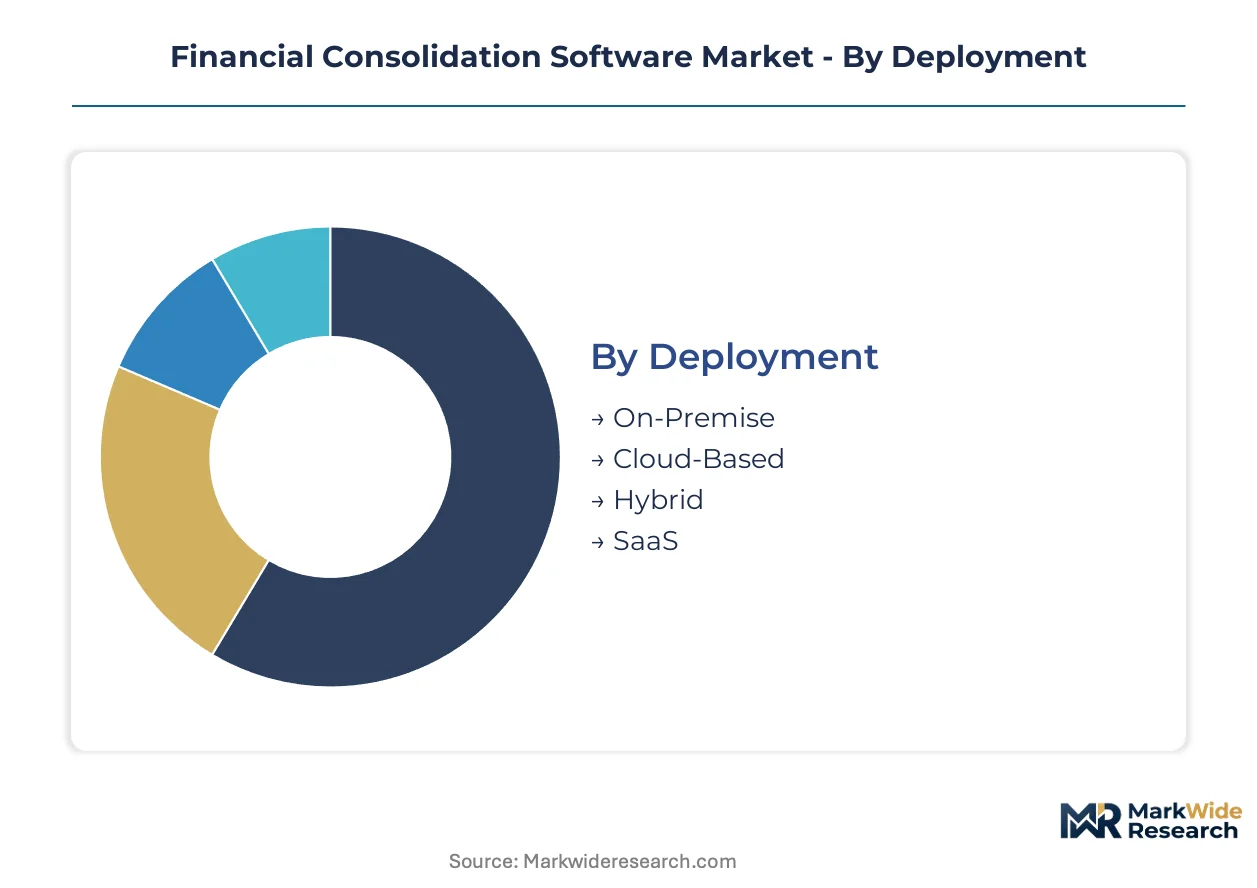
Segmentation in financial consolidation software reflects how procurement priorities diverge across IT infrastructure maturity, regulatory exposure, and entity complexity. Vendors architect their roadmaps around these fault lines because deployment preferences and feature requirements rarely overlap cleanly between a German Mittelstand manufacturer and a US-based private equity platform.
Deployment:
Supply concentration among hyperscale cloud providers is redrawing how consolidation platforms reach end-users, with infrastructure decisions now preceding software selection in most procurement cycles.
- Cloud-Based:Native multi-tenant architectures eliminate infrastructure provisioning delays and enable automatic regulatory template updates. German Mittelstand firms are migrating here fastest to satisfy CSRD-aligned group reporting obligations without capital expenditure approval cycles.
- SaaS:Subscription models align consolidation costs with operational expenditure treatment, appealing to private equity portfolio companies standardizing multi-entity stacks during rollups. AWS and Azure host the majority of these deployments, creating egress fee concerns among finance executives.
- On-Premise:Remains entrenched in highly regulated sectors requiring air-gapped financial data environments.
- Hybrid:Bridges legacy ERP instances in subsidiary locations with cloud-based parent company consolidation engines.
Cloud-Based absorbs the bulk of installed capacity; SaaS is expanding most quickly.
End User:
Customer type determines pricing architecture and implementation complexity more than any other dimension, with entity count and filing volume driving contract value divergence.
- Large Enterprises:Multi-entity structures exceeding 50 subsidiaries demand automated intercompany reconciliation and embedded XBRL validation for SEC EDGAR filing. These buyers consolidate vendor relationships around fewer strategic platforms to reduce integration tax.
- SMEs:Private equity-backed mid-market rollups in the US and UK create multi-entity complexity without enterprise IT budgets. Pre-configured templates for 10-50 entity structures are capturing this segment.
- Financial Institutions:Require granular audit trails and regulatory capital reporting integration.
- Government:Procurement prioritizes FedRAMP or equivalent certification over feature depth.
Large Enterprises command the dominant share of annual contract value; SMEs represent the steepest expansion trajectory.
Feature:
Functional modules are modularizing as vendors unbundle consolidation engines to compete with embedded ERP capabilities from SAP and Oracle.
- Automated Reporting:AI-powered narrative generation from structured trial balances is collapsing the boundary between close and disclosure processes. UK filers are piloting MD&A drafting tools that ingest consolidated outputs directly.
- Multi-Currency Support:Real-time translation engines handling GAAP-to-IFRS adjustments are essential for European headquarters of global conglomerates managing subsidiary operations across monetary zones.
- Data Integration:Pre-built connectors to SAP ECC and Oracle EBS instances reduce chart of account remapping burdens.
- Audit Trails:Immutable transaction logs satisfy ISO 27001 certification requirements for cross-border audited statements.
Automated Reporting captures the greatest R&D investment intensity; Multi-Currency Support is climbing fastest as European regulatory harmonization accelerates.
Solution:
Packaging strategy reflects competitive pressure from ERP vendors bundling consolidation into core licensing, forcing standalone providers to articulate differentiation through architecture choices.
- Comprehensive Suite:Unified performance management platforms that collapse planning, consolidation, and reporting into one environment. These command premium pricing but reduce integration friction for Fortune 500 shared service centers.
- Standalone Module:Point solutions for intercompany reconciliation or currency translation, appealing to buyers with existing ERP investments seeking to augment rather than replace.
- Integration Tools:API-first middleware connecting legacy hyperion installations to modern cloud architectures.
- Custom Solutions:Professional services-heavy engagements for conglomerates with decades of subsidiary-specific configurations.
Comprehensive Suite holds the majority of enterprise deployments; Standalone Module is gaining share fastest as modular procurement patterns spread from mid-market buyers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand concentrates most visibly in Germany, where Mittelstand firms modernize legacy accounting stacks. The US SEC's electronic filing mandates accelerate procurement of audit-ready tools. Cloud migration patterns diverge sharply across national regulatory environments.
United States
Fortune 500 shared service centers drive enterprise-scale consolidation deployments. The SEC's EDGAR system enforces XBRL validation requirements that filter vendor selection toward embedded compliance engines. New York and Chicago financial districts host the densest concentration of multi-entity headquarters upgrading month-end close infrastructure.
Germany
Mittelstand manufacturers with complex subsidiary structures represent the steepest adoption curve. The EU CSRD mandates granular ESG disclosures that ripple into group reporting templates, forcing platform upgrades. Industrial clusters in Bavaria and Baden-Württemberg accelerate cloud migration to capture Scope 3 emissions data within consolidated workflows.
United Kingdom
Private equity portfolio companies standardize on SaaS consolidation stacks during mid-market rollups. The Financial Conduct Authority's disclosure requirements align with international sustainability standards. London's fintech corridor pilots AI-generated narrative disclosure tools that draft MD&A from structured trial balances.
Japan
Headquarters of global conglomerates manage subsidiary operations across monetary zones requiring real-time translation engines. METI's digital transformation incentives support ERP modernization that feeds consolidation workflows. Tokyo and Osaka house the dominant share of regional procurement decision-making for Asia-Pacific entity structures.
India
IT services exporters and multinational captive centers build consolidation capability for global parent companies. SEBI's listed company disclosure norms tighten audit trail requirements for cross-border financial reporting. Bangalore and Hyderabad emerge as implementation hubs where technical accounting talent scarcity creates six-month specialist backlogs.
Financial Consolidation Software Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue modular point solutions and AI-augmented close automation. The vendor base stratifies between comprehensive suite providers and standalone specialists unbundling specific consolidation functions. Strategic archetypes include ERP-anchored incumbents with deep workflow integration, cloud-native disruptors collapsing planning and close processes, and reconciliation-focused modules attacking intercompany complexity. Competitive moves concentrate on M&A to absorb AI matching engine capabilities and strategic partnerships embedding ESG data pipelines.
Within the ERP-anchored tier, SAP and Oracle exemplify installed-base leverage that protects consolidation workflows feeding from core licensing. OneStream occupies a position among cloud-native architects unifying performance management environments. These three names anchor the competitive structure without exhausting its variation, as Wolters Kluwer and BlackLine represent adjacent specialists in compliance automation and financial close management respectively.
| Leading Market Players |
|---|
| SAP |
| Oracle |
| OneStream |
| Wolters Kluwer |
| BlackLine |
| Workday |
| Anaplan |
| Joiin |
| Fathom |
| Others |
Supply & Pricing Matrix
Cloud-native multi-tenant architectures are collapsing traditional deployment economics while concentrating infrastructure leverage among AWS and Azure. This shift simultaneously compresses vendor margins and redistributes pricing power toward hyperscale hosting providers that control egress fees and regional data residency compliance.
Pricing Analysis
Volume contracts for Fortune 500 shared service centers command substantial per-seat discounts against list rates, while mid-market buyers face steeper unit economics without enterprise leverage. Subscription-based SaaS tiers dominate procurement decisions, with price differentiation driven by entity-count scaling and ISO 27001 certification bundling. Cost compression in the mid-market segment is intensifying because ERP-anchored vendors embed consolidation capabilities into core licensing at marginal cost. Private equity portfolio companies exhibit the highest price sensitivity, prioritizing consumption-based contracts that align with operational expenditure treatment.
Supply Chain Analysis
Hyperscale cloud infrastructure supply rests on concentrated data center capacity in the United States, Ireland, and Germany, with specialized compliance hosting clusters in Singapore and Switzerland for financial services workloads. Software development draws from Indian implementation hubs, Eastern European engineering talent pools, and US-based product management centers. Single-source vulnerability concentrates around AWS and Azure egress fee structures that lock customers into proprietary hosting ecosystems. Distribution runs through direct enterprise sales teams for large accounts and channel partners for mid-market penetration.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a cost-of-compliance story where the EU CSRD mandates create barrier-to-entry moats for platforms with pre-certified ESG data architectures. Regulatory filing automation becomes the defendable competitive position.
For Market Incumbents: Deepen embedded AI matching engine capabilities to compress intercompany reconciliation timelines below what ERP-anchored competitors can replicate. Fortify ISO 27001 certification moats against cloud-native entrants lacking cross-border audit trail maturity. Prioritize capacity addition in German Mittelstand industrial clusters where CSRD-aligned platform upgrades accelerate fastest. For New Entrants and Emerging Players: The price-point gap between premium comprehensive suites and economy-tier ERP modules creates white-space opportunity for modular intercompany reconciliation point solutions. Target private equity-backed mid-market rollups in the United States and United Kingdom with pre-configured templates for 10-50 entity structures. Pursue partnership-led go-to-market angles with emissions data API providers to embed Scope 3 calculations into group reporting workflows. For Investors and Strategic Acquirers: Re-rating potential sits with cloud-native consolidation specialists given AI-generated narrative disclosure capabilities that collapse close-to-disclosure timelines. Long-term viability across the projection horizon favors platforms with unified performance management architecture over standalone modules facing ERP bundling pressure. Watch AI-powered MD&A drafting adoption rates among UK filers as inflection indicator for narrative automation demand.| Strategic Initiative | Industry Significance |
|---|---|
| Acquisition of AI Matching Engine Specialist | Automated intercompany reconciliation compresses month-end close timelines for 50-plus entity structures. |
| Strategic Partnership with Emissions Data API Provider | Pre-mapped Scope 3 calculations enable real-time CSRD-aligned sustainability reporting for German Mittelstand firms. |
| Geographic Expansion into UK Fintech Corridor | London's pilot programs for AI-generated MD&A drafting create first-mover advantage in narrative automation. |
| Platform Integration with SAP S/4HANA | Pre-built connectors reduce chart of account remapping burdens for European headquarters of global conglomerates. |
| ISO 27001 Certification Investment | Baseline procurement filter for cross-border audited statements handling SEC EDGAR and EU CSRD filings. |
Research Methodology
SEC EDGAR filings, EU regulatory disclosure databases, and hyperscaler infrastructure capex reports formed the secondary backbone for market sizing and competitive positioning. Primary interviews with CFOs at Fortune 500 shared service centers, technical accounting implementation partners, and private equity platform operations heads validated demand drivers and procurement criteria. Bottom-up and top-down triangulation cross-checked entity-count scaling assumptions against cloud deployment penetration rates across the analysis window.
Bottom-up modeling aggregated individual vendor contract values by deployment model and end-user segment, while top-down validation tracked aggregate software spend flowing into financial close automation categories. Segmentation dimensions included cloud deployment architecture, organization size tier, feature module bundling, and regional regulatory exposure. CAGRs derived from fitted growth curves incorporating CSRD implementation timelines and SEC electronic filing enforcement phases. Forecast inputs captured AI adoption rates in reconciliation workflows and private equity rollup velocity in mid-market segments.
Underlying measurement precision varies by segment; cloud-based deployments carry tighter precision than hybrid legacy bridges due to clearer vendor reporting. Forecasts reflect assumptions around regulatory implementation schedules and ERP bundling intensity that could revise materially. A small set of triggers warrants ongoing watch: AI-generated disclosure liability frameworks, hyperscaler egress fee restructuring, and ERP vendor consolidation module pricing aggression.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
FinTech
Spend Management Platform Market
FinTech
Smart Lending Platform Market
FinTech
Advanced Authentication in Financial Services Market
FinTech
Intelligent Cash Deposit Machine Market
FinTech
China AI in Fintech Market
FinTech
AI-Powered Wealth Management Solution Market
FinTech
Smart Financial Solutions Market
FinTech
Smart Finance Connectivity Market
FinTech
Account Checking Software Market
FinTech
Europe Fintech Cloud Market
FinTech
MENA Fintech Market
FinTech
IT Financial Management Tools Market
FinTech
AI in Fintech Market
FinTech
Robo-Advisory Services Market
FinTech
Digital Banking Platform Market
FinTech
Singapore Fintech Market